
 South Africa Nuclear Imaging Market | 2026-2036
South Africa Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Nuclear Imaging Market Analytics
A wide capital-intensity divergence between installed-base incumbents and emerging service providers is reorganizing competitive dynamics in South Africa. GE Healthcare leverages its long-standing imaging infrastructure footprint across public hospital networks. Siemens Healthineers anchors its position through cyclotron-linked radiopharmaceutical supply chains that reduce import dependency. NTP Radioisotopes SOC Ltd competes as the domestic producer of molybdenum-99 and technetium-99m, sustaining strategic sovereignty in isotope availability.
Nuclear imaging encompasses diagnostic techniques that employ radiopharmaceutical tracers to visualize physiological function, with gamma cameras detecting gamma-ray emissions at 140 keV for technetium-based agents and PET systems capturing 511 keV annihilation photons from fluorine-18 compounds. Hybrid imaging systems lead capital expenditure flows as South African tertiary centers prioritize PET-CT and PET-MRI configurations that merge metabolic and anatomical data for oncology staging. Gamma cameras retain volume dominance in cardiac perfusion studies across provincial hospitals where reimbursement constraints limit PET adoption. Radioisotope production represents a structurally protected margin pool given NTP Radioisotopes' monopoly on SAFARI-1 reactor output and the capital barriers to domestic cyclotron deployment.
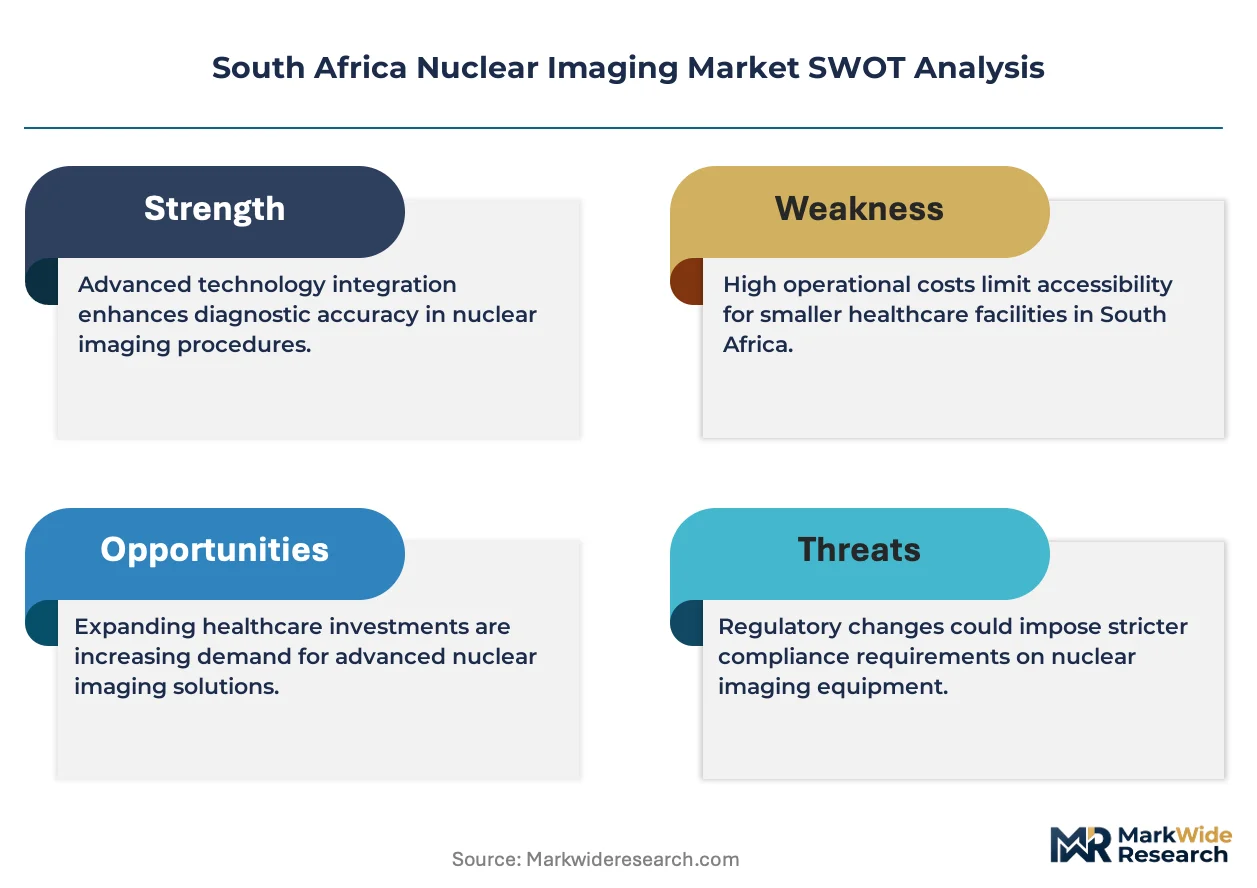
South Africa's Medicines Control Council governs radiopharmaceutical registration and Good Manufacturing Practice compliance, while the National Nuclear Regulator licenses radiation facility operations and enforces occupational exposure limits under the Hazardous Substances Act. These dual frameworks elevate compliance costs for new market entrants and reinforce incumbent advantages in traceability and quality assurance. Stakeholders must monitor the Department of Health's nuclear medicine infrastructure rollout plans and the South African Health Products Regulatory Authority's emerging role in consolidated device-pharmaceutical oversight.
Market Dynamics
The South Africa nuclear imaging market restructures around NTP Radioisotopes' monopoly on SAFARI-1 reactor output and the capital barriers that prevent alternative domestic isotope production, concentrating supply-side power in a single state-owned entity while demand fragments across provincial hospital networks.
Growth Catalysts
- Oncology Staging Protocols:PET-CT utilization expands across Gauteng's academic hospitals for treatment monitoring and staging precision.
- Medicines Control Council Registration:Compliance thresholds filter smaller distributors, reinforcing quality assurance among established radiopharmaceutical suppliers.
- Western Cape Training Pipeline:Nuclear medicine specialist programs at Stellenbosch University and University of Cape Town feed tertiary center staffing needs.
Market Restraints
- Import-Dependent Cyclotron Infrastructure:Domestic fluorine-18 production remains minimal, binding PET tracer supply to foreign cyclotron networks.
- SAFARI-1 Reactor Concentration:Molybdenum-99 availability hinges on single-source domestic production with aging reactor infrastructure.
- Provincial Reimbursement Caps:Public sector PET scan authorization limits constrain adoption outside private tertiary centers.
Strategic Opportunities
- KwaZulu-Natal Expansion:Inkosi Albert Luthuli Central Hospital and Nelson R. Mandela School of Medicine anchor underserved demand in the province.
- Theranostics Convergence:Lutetium-177 PSMA therapy paired with gallium-68 imaging creates integrated diagnostic-treatment revenue streams.
- National Health Insurance Alignment:Department of Health infrastructure rollout plans may elevate nuclear medicine into standardized benefit packages.
Industry Challenges
- Radiopharmacist Shortage:Compounding expertise for technetium-99m kit preparation falls below staffing requirements at regional hospitals.
- Dual Regulatory Burden:Medicines Control Council pharmaceutical compliance layered with National Nuclear Regulator radiation licensing extends facility commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Nuclear Imaging Market |
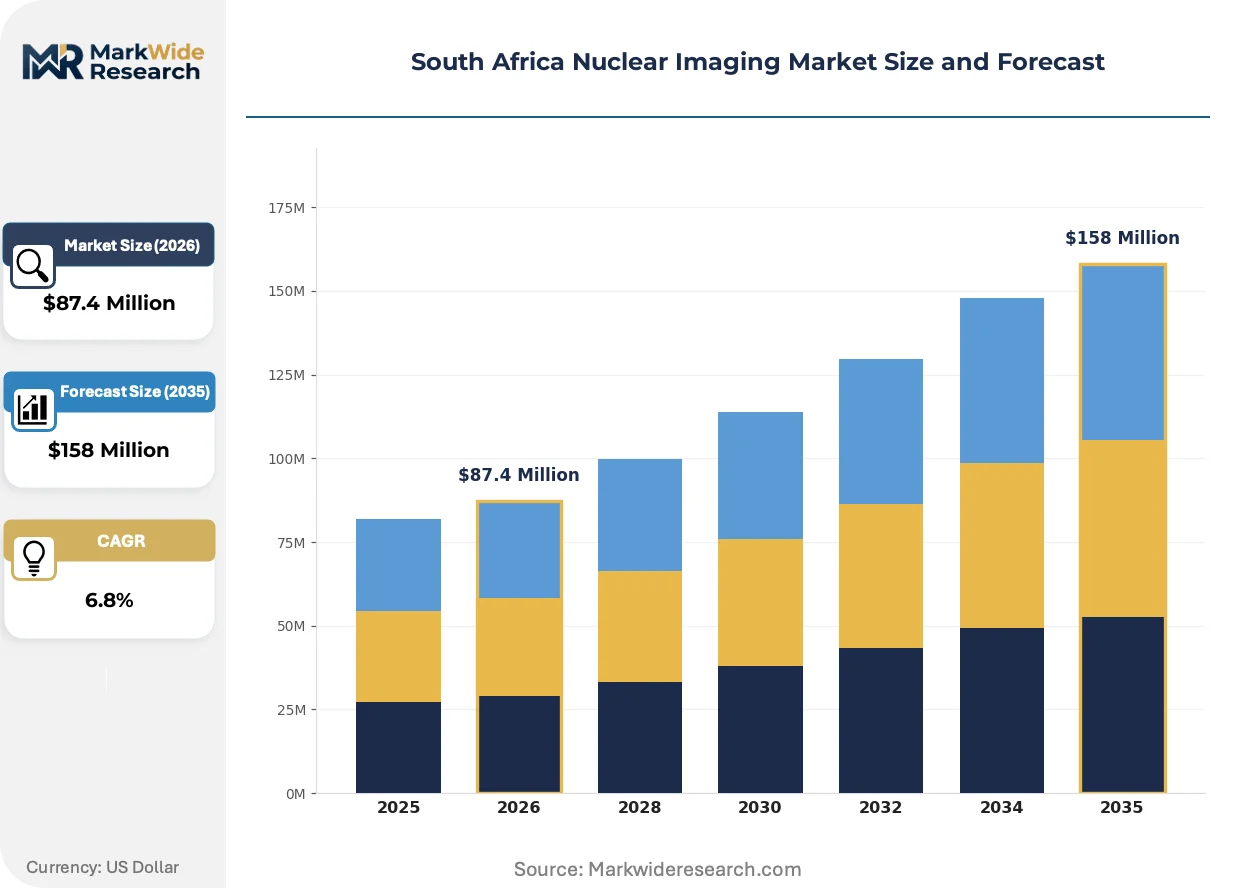
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Photon Emission Computed Tomography, Positron Emission Tomography, Hybrid Imaging Systems, Others End User: Hospitals, Diagnostic Centers, Research Institutes, Outpatient Facilities Application: Oncology, Cardiology, Neurology, Endocrinology Technology: Gamma Cameras, PET Scanners, Imaging Software, Radioisotope Production |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, NTP Radioisotopes SOC Ltd, Bracco Group, Curium, Klydon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Nuclear Imaging Market Evolving Landscape
Hybrid imaging architectures are compressing the market's technology stack while regulatory consolidation and procurement centralization reshape how capital equipment reaches end-users.
Digital PET detectors with silicon photomultiplier arrays are supplanting conventional photomultiplier tube configurations in new system installations. Tertiary oncology centers in Johannesburg and Cape Town prioritize these platforms for improved signal-to-noise ratios in low-dose protocols. The shift compresses maintenance revenue pools as solid-state electronics reduce replacement part turnover.
South African Health Products Regulatory Authority consolidation merges device and pharmaceutical oversight functions previously split between agencies. Radiopharmaceutical manufacturers face unified inspection protocols and traceability requirements spanning production to patient administration. Facilities in Gauteng and Western Cape provinces absorb compliance adaptation costs earlier than regional hospitals.
Provincial treasury procurement is aggregating imaging equipment purchases through centralized tender frameworks. Single-contractor service agreements covering multiple hospital sites displace site-specific maintenance arrangements. Eastern Cape and Limpopo health departments exhibit the most pronounced aggregation behavior as budget constraints intensify.
South Africa Nuclear Imaging Market Segmentation
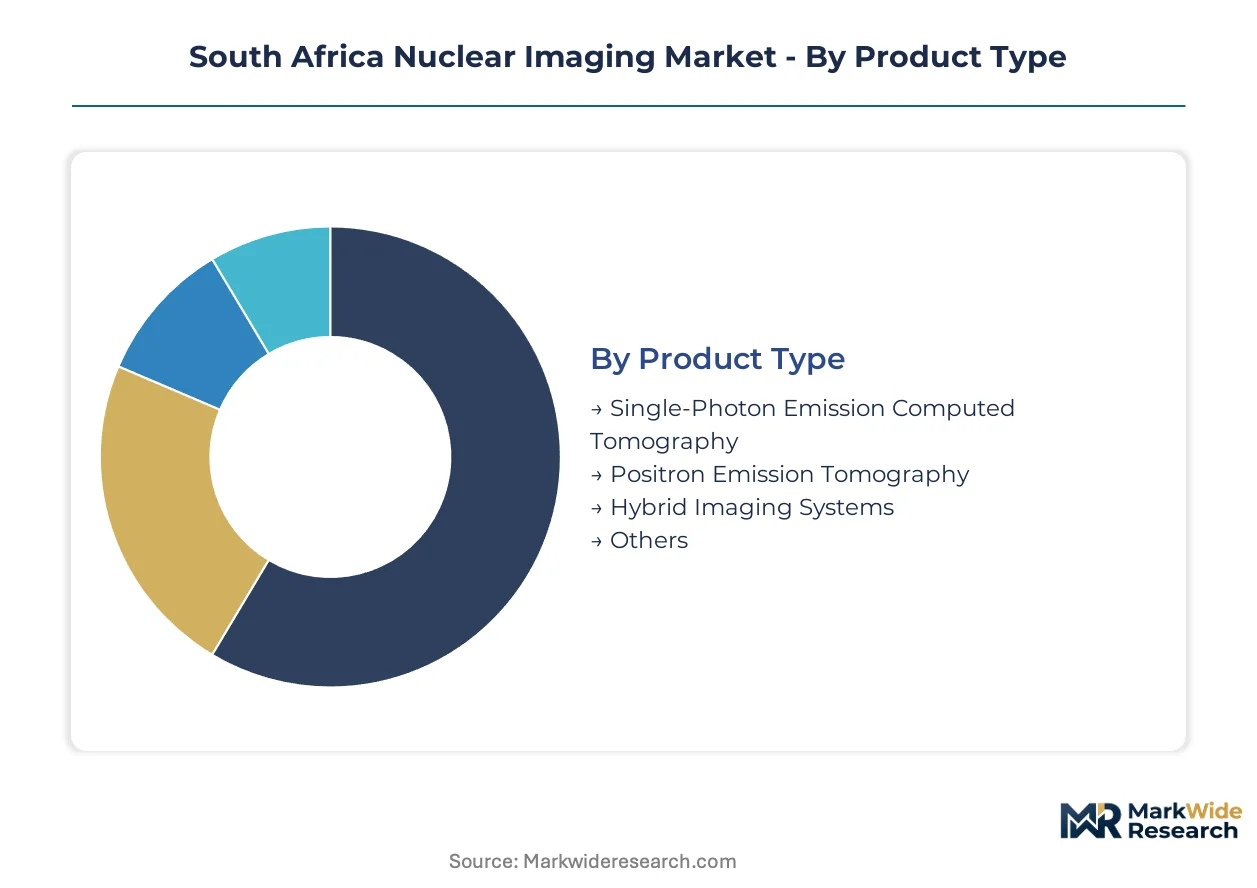
Nuclear imaging segmentation in South Africa tracks capital deployment across hybrid architectures, reimbursement-dependent end-users, and isotope-constrained applications. Margin distribution follows installed equipment bases in Gauteng and Western Cape while emerging provinces reshape volume trajectories.
Product Type:
Margin pools concentrate in systems that merge metabolic and anatomical data capture, with service contracts and radiopharmaceutical coupling extending revenue duration.
- Hybrid Imaging Systems:PET-CT and PET-MRI configurations dominate tertiary center capital budgets in Johannesburg and Cape Town. Academic hospitals prioritize these platforms for oncology staging protocols that demand fused functional-structural datasets. NTP Radioisotopes' domestic isotope supply creates captive radiopharmaceutical bundling opportunities.
- Positron Emission Tomography:Dedicated PET scanners serve high-throughput oncology centers where fluorine-18 tracer availability permits scheduled patient volumes. Import-dependent cyclotron infrastructure constrains provincial hospital adoption outside private networks.
- Single-Photon Emission Computed Tomography:Technetium-99m compatibility sustains SPECT relevance across cardiac perfusion imaging at regional hospitals.
- Others:Planar scintigraphy systems retain niche utility in thyroid and bone imaging at under-resourced facilities.
Hybrid Imaging Systems hold installed capacity. Positron Emission Tomography is rotating up the share rankings.
End User:
Reimbursement authorization tiers split demand between fully equipped tertiary centers and constrained provincial networks.
- Hospitals:Public sector academic hospitals in Gauteng and Western Cape anchor equipment utilization through National Health Insurance pilot programs. PET-CT staging protocols for lung and lymphoma cases drive scan volumes at Charlotte Maxeke Johannesburg Academic Hospital and Groote Schuur Hospital.
- Diagnostic Centers:Private imaging chains concentrate in urban corridors where medical aid coverage permits out-of-hospital nuclear medicine services. Life Healthcare and Netcare facilities compete on appointment availability and radiologist reporting speed.
- Research Institutes:Stellenbosch University and University of Cape Town nuclear medicine departments operate hybrid systems for clinical trial imaging cores.
- Outpatient Facilities:Limited radiopharmaceutical handling licenses restrict nuclear imaging to hospital-adjacent day clinics in major metros.
Hospitals command procedure volume leadership. Diagnostic Centers are climbing the fastest as medical aid networks expand authorized provider panels.
Application:
Clinical utility and reimbursement alignment determine which specialties absorb capital equipment depreciation.
- Oncology:PET-CT utilization for treatment response assessment and staging precision consumes the majority of fluorine-18 and gallium-68 tracer production. Gauteng's academic hospitals prioritize lung, colorectal, and lymphoma imaging protocols.
- Cardiology:Myocardial perfusion imaging with technetium-99m sestamibi sustains SPECT camera utilization across provincial hospital networks where PET viability studies remain authorization-capped.
- Neurology:Dementia differential diagnosis and epilepsy focus applications remain concentrated at University of Cape Town and University of the Witwatersrand academic centers.
- Endocrinology:Thyroid scintigraphy and parathyroid adenoma localization represent stable but lower-volume procedure categories.
Oncology anchors revenue concentration. Cardiology defends volume base through technetium-99m supply reliability.
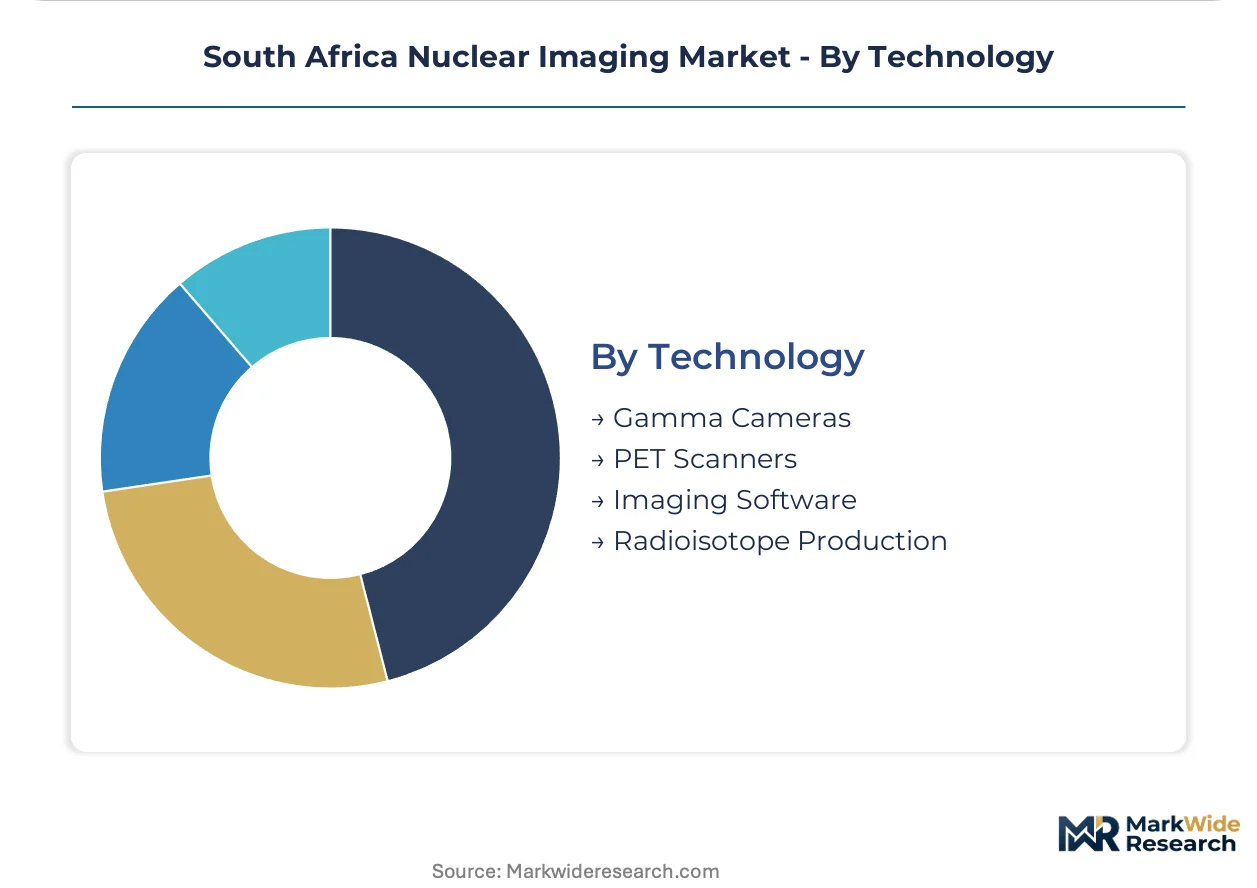
Technology:
Capital intensity and regulatory licensing requirements stratify competitive positioning across detection hardware and isotope production.
- PET Scanners:Digital silicon photomultiplier detector arrays are supplanting conventional photomultiplier tube configurations in new installations. Tertiary oncology centers prioritize signal-to-noise improvements for low-dose protocols.
- Radioisotope Production:NTP Radioisotopes' SAFARI-1 reactor monopoly on molybdenum-99 and technetium-99m generation creates structurally protected margins. Cyclotron-based fluorine-18 production remains minimal domestically.
- Gamma Cameras:Anger camera technology persists in cardiac and skeletal imaging where SPECT-CT hybridization is capital-constrained.
- Imaging Software:PACS integration and AI-assisted lesion detection tools are standardizing across new system procurements.
Radioisotope Production captures supply-side margin concentration. PET Scanners are gaining share fastest through digital detector upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Gauteng and Western Cape provinces exceeds KwaZulu-Natal by margins reflecting specialist concentration and private medical aid density. Provincial reimbursement caps fragment demand across South Africa's nine provinces while infrastructure investment favors metropolitan academic hospital networks.
Gauteng
Charlotte Maxeke Johannesburg Academic Hospital and Steve Biko Academic Hospital drive PET-CT utilization for oncology staging protocols. The Department of Health's National Health Insurance pilot programs channel equipment procurement through centralized tender frameworks. Pretoria's nuclear medicine training programs at University of Pretoria feed specialist supply into tertiary centers across the province.
Western Cape
Groote Schuur Hospital and Tygerberg Hospital anchor hybrid imaging demand through university-affiliated research programs. Stellenbosch University and University of Cape Town nuclear medicine departments operate under South African Health Products Regulatory Authority consolidated oversight. Cape Town's private diagnostic chains compete on radiologist reporting speed for medical aid-authorized procedures.
KwaZulu-Natal
Inkosi Albert Luthuli Central Hospital serves as the province's sole comprehensive nuclear medicine facility with limited PET-CT availability. Nelson R. Mandela School of Medicine trains specialists who migrate to Gauteng and Western Cape for employment. Durban's private hospital networks rely on fluorine-18 tracer imports from Johannesburg cyclotron facilities.
Eastern Cape
Provincial treasury procurement aggregation concentrates equipment purchases through single-contractor service agreements covering multiple hospital sites. Walter Sisulu University trains nuclear medicine physicians who face limited local employment opportunities. Port Elizabeth's Livingstone Hospital operates gamma cameras for cardiac perfusion studies with constrained SPECT-CT upgrade pathways.
Free State
Universitas Academic Hospital maintains the province's only dedicated nuclear medicine department with technetium-99m dependency on NTP Radioisotopes' SAFARI-1 reactor output. University of the Free State's specialist training program feeds staff into neighboring provinces. Bloemfontein's private diagnostic sector remains underdeveloped relative to metropolitan provinces.
South Africa Nuclear Imaging Market Competitive Landscape
Concentration sits with multinational imaging equipment manufacturers and the state-owned isotope producer. The market structures around three tiers: capital equipment suppliers with long-standing public hospital infrastructure footprints, radiopharmaceutical distributors navigating Medicines Control Council registration requirements, and the domestic monopoly on molybdenum-99 generation. Competitive moves center on cyclotron-linked supply chain partnerships and centralized provincial procurement aggregation.
Among imaging system suppliers, GE Healthcare, Siemens Healthineers, and Koninklijke Philips NV represent the established multinational tier with installed bases across South African tertiary centers. These companies exemplify capital-intensive positioning where service contracts and equipment upgrade cycles extend revenue duration. NTP Radioisotopes SOC Ltd occupies a structurally protected position as the domestic producer of technetium-99m from SAFARI-1 reactor output, creating supply-side concentration that no competitor can replicate without comparable nuclear research infrastructure.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| NTP Radioisotopes SOC Ltd |
| Bracco Group |
| Curium |
| Klydon |
| Others |
Value Network & Pricing Analysis
Digital PET detector arrays replacing conventional photomultiplier tube configurations are redrawing procurement geography toward Johannesburg and Cape Town tertiary centers while compressing maintenance revenue pools through reduced replacement part turnover. This substitution dynamic simultaneously elevates capital equipment pricing premiums for solid-state configurations and diminishes recurring service contract values across South Africa's installed base.
Pricing Analysis
The customization-premium spread separates standard gamma camera configurations from hybrid PET-CT and PET-MRI systems configured to academic hospital oncology protocols. Pricing stratifies across premium, standard, and economy tiers based on detector technology sophistication and radiopharmaceutical bundling depth. Cost compression in the SPECT segment intensifies because provincial reimbursement caps limit authorization for advanced hybrid systems. Public sector hospitals exhibit highest price sensitivity due to National Health Insurance pilot budget constraints, while private diagnostic chains absorb premium pricing for faster reporting capabilities.
Supply Chain Analysis
Strategic stockpile preferences dominate radiopharmaceutical inventory management given technetium-99m's six-hour half-life and fluorine-18's 110-minute decay window. Domestic supply draws from NTP Radioisotopes' SAFARI-1 reactor output in Pretoria, with cyclotron-based fluorine-18 production remaining minimal and import-dependent. Raw material dependencies center on enriched uranium targets, molybdenum-98 irradiation services, and gallium-68 generator elution chemistry. Single-source vulnerability concentrates in SAFARI-1 reactor infrastructure aging. Distribution runs through Medicines Control Council-licensed radiopharmaceutical depots serving Gauteng, Western Cape, and KwaZulu-Natal hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from National Health Insurance infrastructure rollout plans creating standardized procurement niches outside established academic hospital corridors. Provincial treasury aggregation behavior in Eastern Cape and Limpopo opens entry pathways for service-focused competitors.
For Market Incumbents: Fortify cyclotron-linked radiopharmaceutical supply chains through exclusive distributor arrangements that bind PET tracer availability to equipment service contracts. Deepen backward integration into gallium-68 and lutetium-177 production capabilities ahead of theranostics convergence. Digital detector upgrade cycles at Charlotte Maxeke Johannesburg Academic Hospital and Groote Schuur Hospital threaten maintenance revenue retention. For New Entrants and Emerging Players: Lead with theranostics integration packages combining gallium-68 PSMA imaging with lutetium-177 therapy coordination at Inkosi Albert Luthuli Central Hospital and Nelson R. Mandela School of Medicine. KwaZulu-Natal's specialist migration patterns create staffing partnership opportunities with Gauteng training programs. Position through mobile PET-CT deployment models serving Eastern Cape and Free State provincial networks where fixed installation capital is constrained. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors radiopharmaceutical distribution specialists with Medicines Control Council registration depth and cyclotron access partnerships. Long-term viability hinges on National Health Insurance benefit package inclusion elevating nuclear medicine into standardized care. Acquisition targets should demonstrate SAFARI-1 reactor supply agreements or foreign cyclotron offtake contracts. Watch for Department of Health infrastructure rollout tender announcements as volume inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Partnership Formation | Secures fluorine-18 tracer supply autonomy reducing import dependency for Gauteng private networks. |
| Theranostics Service Integration | Creates bundled diagnostic-treatment revenue streams pairing gallium-68 imaging with lutetium-177 therapy. |
| Provincial Tender Aggregation | Captures multi-site equipment procurement contracts through Eastern Cape and Limpopo health department centralization. |
| Digital Detector Upgrade Program | Replaces photomultiplier tube configurations with silicon photomultiplier arrays at Johannesburg tertiary centers. |
| Radiopharmacist Training Pipeline | Addresses compounding expertise shortages through Stellenbosch University and University of Cape Town program expansion. |
Research Methodology
Cross-validation between hospital procurement database analysis and South African Health Products Regulatory Authority filing records anchors the qualitative findings on equipment installation patterns. Primary interviews with nuclear medicine department heads, radiopharmacist supervisors, biomedical engineers, and provincial health department procurement officers combined with secondary validation from Medicines Control Council registration databases, National Nuclear Regulator licensing records, and Department of Health infrastructure planning documents. Bottom-up equipment unit economics triangulate against top-down provincial health expenditure allocations.
Sensitivity analysis around SAFARI-1 reactor output assumptions and National Health Insurance rollout pacing shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include hybrid architecture type, end-user reimbursement tier, isotope application category, and provincial regulatory cluster. CAGRs derive from installed base replacement cycles and radiopharmaceutical procedure volume trajectories. Industry-specific forecast inputs incorporate cyclotron deployment timelines and specialist training program graduation rates.
Underlying assumptions cover reactor maintenance scheduling continuity and medical aid authorization expansion rates, with deviation risk concentrated in SAFARI-1 infrastructure lifespan and National Health Insurance benefit package finalization. Forecasts reflect these documented conditions without claiming predictive certainty. Revision becomes warranted when provincial reimbursement authorization thresholds cross expansion or contraction inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
AI Fetal Ultrasound View Detection Software Market
Medical Imaging
Global Elastography Imaging Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
Medical Imaging Agent-Producing System Market
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
Radio-Fluoroscopy Systems Market
Medical Imaging
North America Computed Tomography (CT) Market
Medical Imaging
C-Arms Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
Global Contrast Enhanced Digital Mammography (CEDM) Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Gallium-68 Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
Interventional X - Ray Systems Market