
 Specimen Radiography Systems Market | 2026-2036
Specimen Radiography Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Specimen Radiography Systems Market Analytics
The gap between premium digital specimen radiography and commodity analog units is shifting from a feature distinction to a workflow-integration divide. Hologic leverages its mammography installed base to bundle specimen verification into broader breast surgery suites. Kubtec specializes in compact cabinet systems that anchor outpatient surgery centers with limited capital budgets.
Specimen radiography systems capture high-resolution X-ray images of excised tissue during surgical procedures to verify margin clearance and specimen integrity, typically operating at 20-50 kVp with dedicated low-power tubes and high-frequency generators for soft-tissue contrast. Digital X-Ray Systems dominate current procurement cycles as hospitals phase out film-based workflows, while Flat Panel Detectors capture the fastest replacement demand due to their direct conversion efficiency and dose reduction. Research Institutions represent an emerging segment where optical imaging extensions are gaining traction for translational pathology studies.
FDA 510(k) requirements and EU MDR conformity assessments shape product development timelines and commercial access across North America and Europe, with Japan's PMDA adding distinct electromagnetic compatibility testing for imported units. Stakeholders must weigh regulatory registration costs against the margin premiums available in integrated digital platforms versus standalone analog alternatives. Procurement committees increasingly demand DICOM connectivity and PACS interoperability as baseline specifications rather than optional upgrades.
Market Dynamics
The transition from analog film to digital flat-panel detector systems is compressing replacement cycles and forcing vendors to re-architect service revenue models around software integration rather than hardware margins alone.
Growth Catalysts
- EU MDR conformity assessments:The 2021 Medical Device Regulation mandates enhanced clinical evidence for diagnostic imaging equipment, accelerating hospital upgrades to certified digital platforms that streamline documentation workflows.
- Outpatient surgery centers:Ambulatory breast surgery volumes in the United States are expanding specimen radiography deployment beyond traditional hospital radiology departments into point-of-care settings.
- Optical imaging extensions:Research institutions are integrating multispectral imaging modules with conventional X-ray cabinets to enable translational pathology studies on excised tissue margins.
Market Restraints
- Flat-panel detector supply concentration:Manufacturing of amorphous selenium direct-conversion layers concentrates among a limited set of East Asian substrate suppliers, creating vulnerability to input bottlenecks.
- FDA 510(k) pathway tightening:Enhanced quality benchmarks for digital breast tomosynthesis extensions are extending clearance timelines and elevating regulatory registration costs for new market entrants.
- Computed radiography substitution:Retrofit phosphor plate systems offer intermediate digital capability at lower capital outlay, delaying full detector replacements in budget-constrained facilities.
Strategic Opportunities
- Japan's PMDA electromagnetic compatibility requirements:Domestic testing infrastructure for imported units remains underdeveloped, creating first-mover advantage for vendors establishing local certification partnerships.
- Pathology workflow digitization:Germany's university hospital networks are piloting AI-assisted margin assessment algorithms that require high-resolution specimen radiography inputs as training data.
- Three-dimensional specimen imaging:Convergence of cone-beam CT reconstruction with conventional specimen cabinets enables volumetric margin analysis without tissue sectioning.
Industry Challenges
- DICOM integration complexity:Legacy PACS architectures in mid-tier hospitals require custom middleware development to accommodate specimen radiography metadata schemas.
- Clinical engineering specialization:Maintenance of high-frequency generators and microfocus tubes demands technicians with hybrid imaging-electronics expertise that outpaces current training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specimen Radiography Systems Market |
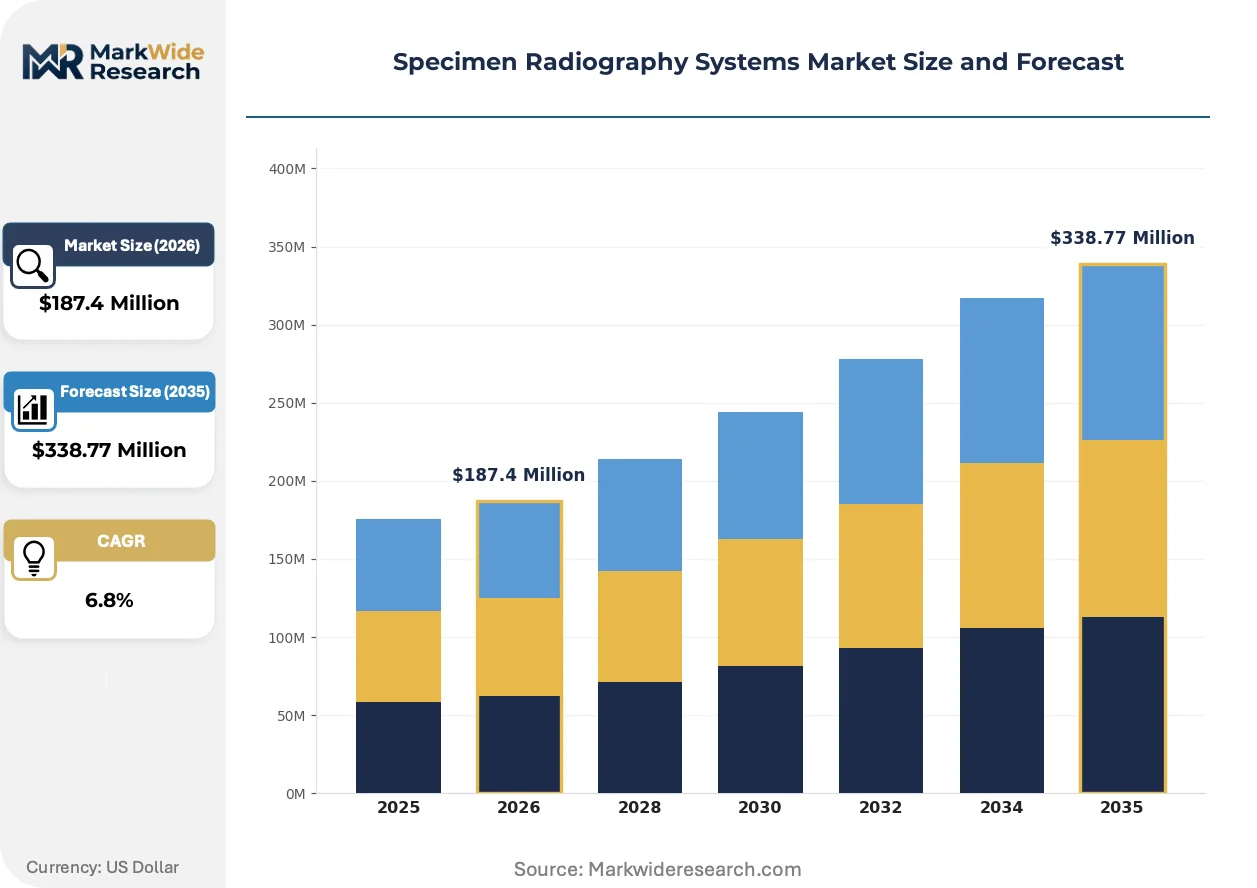
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital X-Ray Systems, Computed Radiography, Optical Imaging Systems, Analog X-Ray Systems Application: Oncology, Orthopedics, Dental Imaging, Research Labs End User: Hospitals, Diagnostic Centers, Research Institutions, Private Practices Technology: Flat Panel Detectors, Image Processing Software, Radiographic Film, Mobile Imaging Systems |
| Companies Covered | Hologic, Kubtec, Faxitron, Simeks, GE Healthcare, Siemens Healthineers, Canon Medical Systems Corporation, Philips Healthcare, Hitachi Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specimen Radiography Systems Market Evolving Landscape
Software-defined imaging workflows are displacing hardware-centric procurement criteria as hospitals prioritize seamless EMR integration over incremental detector resolution gains.
Specimen radiography hardware is modularizing around swappable detector cartridges and upgradeable generator firmware. Tertiary hospital breast surgery suites in the United States are adopting platform architectures that accommodate future optical or tomographic extensions without cabinet replacement. This modularity is compressing capital depreciation schedules and shifting vendor competition toward software subscription attach rates.
Japan's PMDA has implemented distinct electromagnetic compatibility testing protocols for imported diagnostic imaging equipment that exceed IEC baseline requirements. European manufacturers seeking access must establish local conformity assessment partnerships or face 6-12 month additional approval timelines. The regulation most directly impacts compact cabinet systems targeting outpatient surgery centers, where Japanese distributors now demand pre-certified inventory positions.
Hospital procurement committees are elevating DICOM connectivity and PACS interoperability to baseline specifications rather than optional upgrades. Standalone analog vendors without HL7 FHIR integration capabilities are losing access to integrated delivery network tenders in Germany and the United States. This behavioral shift is most visible in breast cancer screening network expansions, where centralized pathology workflow digitization mandates end-to-end digital specimen handling protocols.
Specimen Radiography Systems Market Segmentation
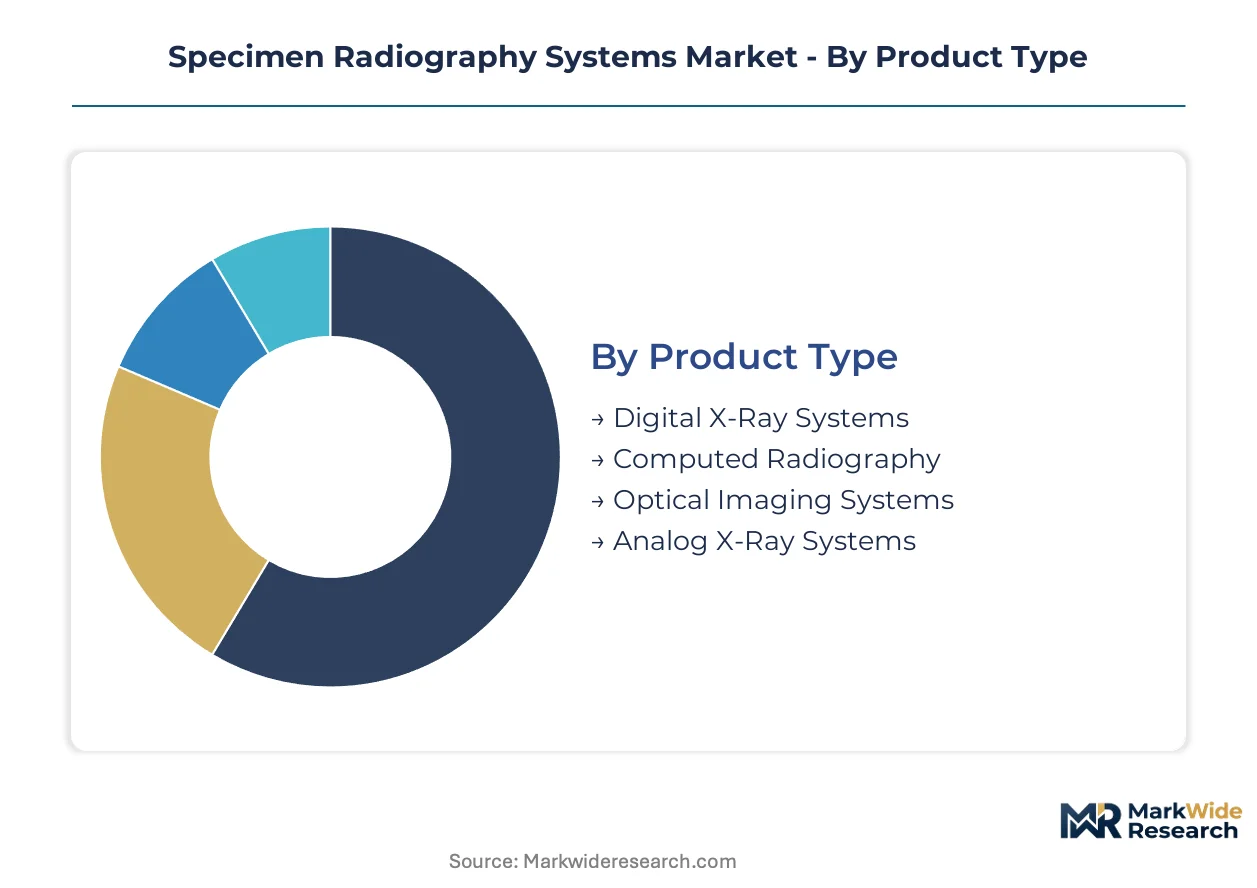
Specimen radiography procurement splits sharply between facilities pursuing full digital integration and those optimizing capital efficiency through phased transitions. Regulatory certification burdens vary dramatically across product tiers, with FDA 510(k) pathways for digital extensions imposing documentation requirements that analog alternatives bypass entirely.
Product Type:
FDA 510(k) clearance timelines stretch longest for digital breast tomosynthesis extensions, while analog systems face minimal premarket scrutiny; EU MDR conformity assessments meanwhile accelerate hospital migration toward certified digital platforms with streamlined documentation workflows.
- Digital X-Ray Systems:These platforms deploy amorphous selenium direct-conversion flat panels operating at 20-50 kVp with dedicated microfocus tubes for soft-tissue contrast. Demand concentrates in United States tertiary hospital breast surgery suites where intraoperative margin verification reduces re-excision rates; FDA quality benchmark tightening for tomosynthesis extensions extends vendor clearance timelines and elevates registration costs.
- Computed Radiography:Retrofit phosphor plate systems deliver intermediate digital capability through reusable imaging plates and laser digitization. Budget-constrained facilities in Germany's mid-tier hospital networks deploy these as bridge solutions; lower capital outlay delays full flat-panel detector replacements while satisfying minimum EU MDR documentation requirements.
- Optical Imaging Systems:Multispectral modules integrated with conventional X-ray cabinets enable translational pathology studies on excised tissue margins.
- Analog X-Ray Systems:Film-based workflows persist in outpatient surgery centers with limited capital budgets and minimal PACS integration requirements.
Leading the category by volume: Digital X-Ray Systems. Growing fastest: Optical Imaging Systems.
Application:
Cost tier stratification separates premium intraoperative verification suites from budget-conscious screening support functions, with reimbursement differentials driving capital allocation across clinical departments.
- Oncology:Breast surgery applications dominate procurement cycles as hospitals phase out film-based workflows for margin assessment. United States ambulatory surgery centers expanding specimen radiography deployment beyond traditional radiology departments into point-of-care settings; bundled payment models for lumpectomy procedures create accountability for re-excision rates.
- Orthopedics:Intraoperative verification of bone fragment alignment and hardware placement drives compact cabinet demand. Japanese outpatient surgery centers prioritize electromagnetic compatibility-certified units; PMDA testing protocols exceed IEC baseline requirements and favor vendors with established local conformity partnerships.
- Dental Imaging:Extraction verification and implant planning support functions in private practice settings.
- Research Labs:Translational pathology studies requiring multimodal imaging inputs for algorithm training datasets.
Category leadership by installed base: Oncology. Steepest expansion trajectory: Research Labs.
End User:
Customer type determines connectivity specifications, with integrated delivery networks mandating DICOM interoperability that standalone private practices frequently omit.
- Hospitals:Tertiary breast surgery suites in the United States adopt modular platform architectures accommodating future optical or tomographic extensions without cabinet replacement. Germany's university hospital networks pilot AI-assisted margin assessment algorithms requiring high-resolution specimen radiography training data; HL7 FHIR integration capabilities filter vendor access to centralized tenders.
- Diagnostic Centers:High-volume breast cancer screening networks in Japan demand pre-certified inventory positions from distributors. PMDA electromagnetic compatibility testing for imported units creates first-mover advantage for vendors establishing local certification partnerships; six-to-twelve month additional approval timelines disadvantage unprepared entrants.
- Research Institutions:Multispectral imaging modules gain traction for translational pathology studies with flexible procurement outside clinical reimbursement constraints.
- Private Practices:Limited capital budgets favor compact cabinet systems with minimal middleware requirements.
Highest absolute procurement value: Hospitals. Gaining share fastest: Research Institutions.
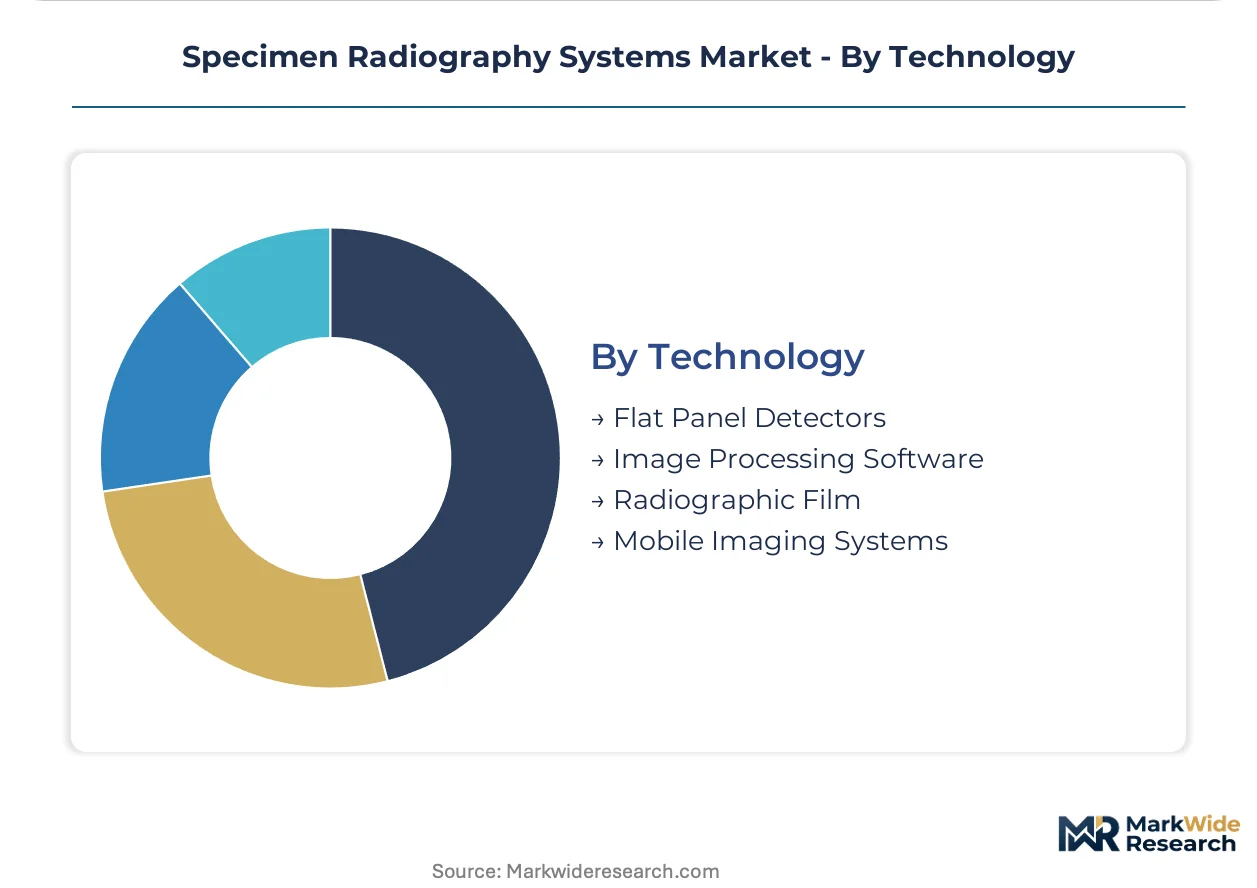
Technology:
Supply concentration in East Asian substrate manufacturing for direct-conversion layers creates input bottlenecks that reshape technology sourcing strategies.
- Flat Panel Detectors:Amorphous selenium direct-conversion layers manufactured by concentrated East Asian substrate suppliers create vulnerability to input bottlenecks. Replacement demand accelerates fastest among digital migration hospitals seeking dose reduction and immediate image availability; manufacturing concentration elevates procurement risk assessments in European and North American procurement committees.
- Image Processing Software:AI-assisted margin assessment algorithms under pilot in Germany require high-resolution specimen radiography inputs as training data. Software-defined imaging workflows displace hardware-centric procurement criteria as hospitals prioritize seamless EMR integration; subscription attach rates shift vendor competition from hardware margins toward recurring revenue models.
- Radiographic Film:Legacy workflows persist where PACS interoperability remains non-mandatory.
- Mobile Imaging Systems:Point-of-care deployment in ambulatory surgery centers demands compact form factors with battery-independent operation.
Dominant technology by replacement volume: Flat Panel Detectors. Climbing the fastest: Image Processing Software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors specimen radiography procurement intensity through its concentration of tertiary breast surgery centers and academic medical complexes. Hospital networks across this cluster prioritize intraoperative margin verification systems to reduce re-excision rates in lumpectomy procedures. The metropolitan corridor's procurement committees mandate DICOM connectivity as baseline specification.
United States
Ambulatory surgery centers in Texas and Florida are expanding specimen radiography deployment beyond traditional radiology departments into point-of-care settings. FDA 510(k) clearance pathways for digital breast tomosynthesis extensions are tightening quality benchmarks and extending vendor timelines. The Cleveland Clinic and Mayo Clinic networks anchor demand for modular platform architectures accommodating future optical extensions.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia pilot AI-assisted margin assessment algorithms requiring high-resolution specimen radiography training data. EU MDR conformity assessments mandate enhanced clinical evidence for diagnostic imaging equipment, accelerating migration toward certified digital platforms. The Rhine-Ruhr metropolitan region concentrates procurement for pathology workflow digitization initiatives.
Japan
High-volume breast cancer screening networks in the Kanto region demand pre-certified inventory positions from distributors. PMDA electromagnetic compatibility testing protocols for imported diagnostic imaging equipment exceed IEC baseline requirements and create six-to-twelve month additional approval timelines. Tokyo's university hospital clusters favor vendors with established local conformity assessment partnerships.
United Kingdom
NHS England's screening program expansions drive procurement for integrated digital specimen handling protocols across London and Southeast hospital trusts. MHRA post-Brexit regulatory frameworks maintain alignment with EU MDR documentation standards while adding distinct UKCA marking requirements. The Cambridge-Oxford-London life sciences triangle anchors research institution demand for multispectral imaging modules.
India
Private hospital chains in Maharashtra and Karnataka are deploying compact cabinet systems for outpatient oncology surgery centers with limited capital budgets. CDSCO medical device registration requirements are tightening quality documentation for imported imaging equipment. Mumbai's tertiary care complexes concentrate demand for intermediate digital capability through computed radiography bridge solutions.
Specimen Radiography Systems Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the workflow-integration dimension rather than raw hardware specifications. The vendor base organizes into three tiers: integrated imaging conglomerates with mammography installed bases, compact cabinet specialists targeting outpatient settings, and research-focused platform architects. Consolidation pressure favors vendors with software subscription attach rates over pure hardware margins. Dominant competitive moves include strategic partnerships for PACS interoperability certification and geographic expansion through local conformity assessment partnerships.
Within the integrated imaging tier, Hologic and GE Healthcare exemplify archetypes leveraging existing mammography relationships to bundle specimen verification into broader breast surgery suites. Kubtec occupies a specialist position among compact cabinet fabricators targeting capital-constrained outpatient surgery centers. Siemens Healthineers represents the research-platform vector through its positioning within university hospital networks piloting AI-assisted margin assessment algorithms.
| Leading Market Players |
|---|
| Hologic |
| Kubtec |
| Faxitron |
| Simeks |
| GE Healthcare |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Philips Healthcare |
| Hitachi Medical Systems |
| Others |
Value Network & Pricing Analysis
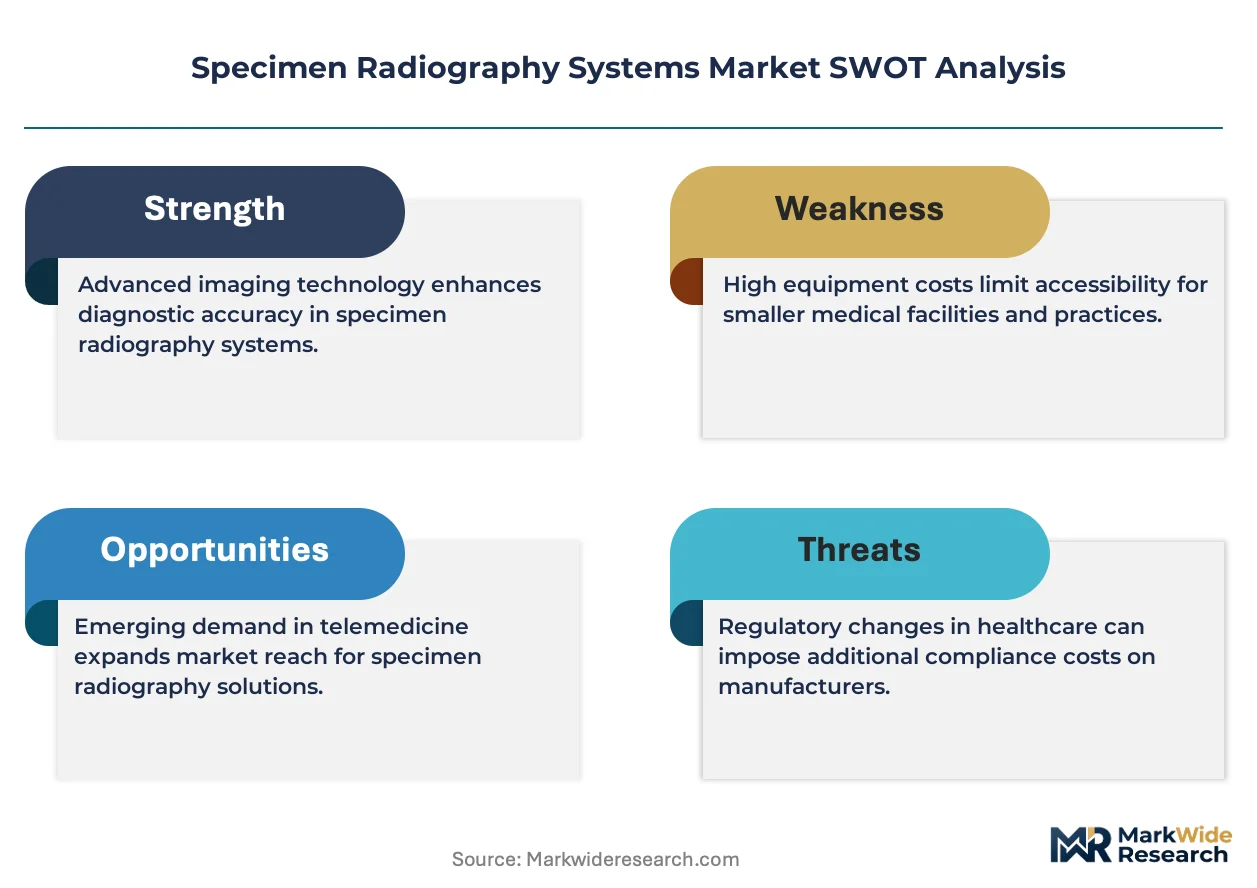
Workflow-integration capability separates premium digital platforms from commodity analog alternatives, with this bifurcation manifesting in subscription-based software attach rates for integrated suites versus transactional hardware margins for standalone cabinets. FDA 510(k) clearance costs and EU MDR documentation burdens concentrate pricing power among vendors with established regulatory infrastructures, while East Asian substrate bottlenecks for amorphous selenium direct-conversion layers constrain supply elasticity for flat-panel detector upgrades.
Pricing Analysis
Outcome-based pricing anchored to re-excision rate reduction dominates tertiary hospital procurement in the United States, with bundled payment models for lumpectomy procedures creating accountability metrics that vendors monetize through performance guarantees. Three-tier pricing structure across premium, standard, and economy levels stratifies by DICOM integration depth and PACS interoperability certification, with Germany's university hospital networks least sensitive to capital outlay and India's outpatient surgery centers most responsive to computed radiography bridge solutions. Cost compression in analog tiers is intensifying because computed radiography retrofit systems delay full digital migration without triggering reimbursement penalties.
Supply Chain Analysis
Regulatory qualification gating through FDA 510(k) pathways and Japan's PMDA electromagnetic compatibility protocols concentrates manufacturing partnerships among vendors with pre-certified component streams. Amorphous selenium direct-conversion layers draw from concentrated East Korean and Japanese substrate suppliers, while high-frequency generator assemblies and microfocus tubes rest on German and United States precision electronics capabilities. Single-source vulnerability in East Asian flat-panel detector substrates elevates procurement risk assessments among European and North American hospital committees. Distribution runs through authorized medical device distributors with regional conformity assessment partnerships, particularly for Japanese market access where local certification infrastructure remains underdeveloped.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-side concentration in amorphous selenium substrate manufacturing props pricing for flat-panel detector systems, with capacity expansion timelines lagging replacement demand from digital migration cycles.
For Market Incumbents: Anchor service revenue models around software subscription attach rates rather than hardware margins alone, defending against computed radiography substitution by accelerating HL7 FHIR integration certification. Capacity addition in Japanese electromagnetic compatibility testing infrastructure represents a critical lever for preempting six-to-twelve month approval delays that disadvantage unprepared competitors. For New Entrants and Emerging Players: Begin with optical imaging extensions for research institutions, where flexible procurement outside clinical reimbursement constraints enables technology validation without FDA 510(k) clearance timelines. Japan's outpatient surgery centers present the most penetrable geography given PMDA certification partnership gaps among established vendors; a go-to-market angle through local distributor pre-certification programs accelerates market access. For Investors and Strategic Acquirers: Re-rating potential sits with compact cabinet specialists possessing established PMDA conformity partnerships given Japan's screening network expansion and electromagnetic compatibility bottlenecks. Long-term viability across the analysis window favors vendors with software-defined imaging workflows and recurring revenue models over pure hardware fabricators; acquisition targets should demonstrate DICOM connectivity as baseline specification rather than optional upgrade. The signal to watch is AI-assisted margin assessment algorithm pilots in German university hospital networks, which require high-resolution specimen radiography training data and will consolidate procurement around integrated digital platforms.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Certification Partnership | Local electromagnetic compatibility testing infrastructure in Japan compresses approval timelines for imported cabinet systems. |
| HL7 FHIR Integration Development | Seamless EMR connectivity filters vendor access to integrated delivery network tenders in Germany and the United States. |
| AI Algorithm Training Data Partnership | High-resolution specimen radiography inputs from German university hospital networks enable next-generation margin assessment software. |
| Modular Platform Architecture | Swappable detector cartridges and upgradeable firmware accommodate optical extensions without cabinet replacement in tertiary suites. |
| Computed Radiography Bridge Positioning | Intermediate digital capability at lower capital outlay captures budget-constrained facilities delaying full flat-panel migration. |
Research Methodology
FDA 510(k) clearance databases, EU MDR conformity assessment registries, and hospital procurement contract disclosures formed the secondary backbone, supplemented by customs records for amorphous selenium substrate trade flows. Primary interviews with biomedical engineering directors, hospital purchasing committee chairs, GPO contracts managers, and pathology workflow digitization leads combined with secondary validation through bottom-up installation base triangulation and top-down market sizing across product tiers. Triangulation across primary and secondary sources anchored volume and value estimates for digital X-ray systems, computed radiography, and optical imaging extensions.
Historical trendline analysis of replacement cycles from analog to digital platforms informed penetration curve modeling across the projection horizon. Segmentation dimensions included product type, application specialty, end-user facility tier, and technology architecture, with regulatory certification tier and DICOM integration depth as industry-specific forecast inputs. CAGRs were derived from weighted average of equipment replacement velocity and software subscription attach rate trajectories, incorporating PMDA approval timeline variations for Japanese market access.
Underlying measurement precision varies by segment; digital X-ray systems and flat-panel detector replacement demand carry tighter precision than emerging optical imaging extensions where translational pathology adoption remains nascent. Forecasts reflect assumptions around EU MDR documentation workflow acceleration and FDA quality benchmark tightening for tomosynthesis extensions. A model refresh is warranted upon material change in East Asian substrate supplier capacity or PMDA electromagnetic compatibility protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Veterinary Diagnostic Imaging Market
Medical Imaging
Digital Mammography Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
China Computed Tomography Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
Next Generation Ultrasound Systems Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market
Medical Imaging
MRI Ferromagnetic Detection Systems Market
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
Germany Digital Pathology Market
Medical Imaging
Mexico Digital X-Ray Devices Market
Medical Imaging
Spain Diagnostic Imaging Equipment Market