
 Global Medical Image Management Market | 2026-2036
Global Medical Image Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Image Management Market Intelligence
North American health IT infrastructure spending is consolidating around enterprise imaging platforms that unify radiology and cardiology workflows. GE HealthCare leverages its installed base of diagnostic modalities to anchor hybrid cloud deployments across integrated delivery networks. Siemens Healthineers AG competes through AI-native orchestration layers that extend beyond traditional PACS boundaries. FUJIFILM Holdings Corporation specializes in enterprise viewer architectures that occupy the interoperability layer between hospitals and telemedicine providers.
Medical image management encompasses the software systems, storage architectures, and interoperability protocols that govern acquisition, indexing, retrieval, and distribution of diagnostic imaging data across healthcare enterprises, typically operating on DICOM standards with HL7 FHIR integration for clinical workflow orchestration. PACS remains the revenue backbone for most vendors, though VNA deployments are accelerating as health systems seek vendor-neutral long-term archives that outlast individual modality lifecycles. Cloud-based deployment models represent the fastest-growing configuration, particularly among diagnostic centers and telemedicine providers that lack capital-intensive on-premise infrastructure.
FDA 21 CFR Part 820 quality-system requirements shape software validation protocols for US market access, while EU MDR and GDPR impose concurrent demands on clinical traceability and cross-border patient-data governance. FDA's emerging software-as-medical-device guidance and the EU AI Act's risk-classification framework for diagnostic algorithms will force vendors to rebuild compliance documentation around machine-learning components. Stakeholders must decide now whether to absorb these compliance costs through in-house regulatory teams or outsource to specialized health IT consultancies.
Market Dynamics
Cloud-native architectures are forcing a fundamental reconfiguration of medical image storage economics, compressing deployment timelines from months to weeks while shifting capital expenditure models toward operational spending structures.
Growth Catalysts
- EU MDR data-integrity mandates:Hospital networks across Germany and France must replace legacy PACS with vendor-neutral archives that ensure clinical traceability across modality lifecycles.
- Diagnostic imaging volume expansion:Oncology screening programs in Japan and South Korea are generating petabyte-scale data flows that exceed on-premise storage capacity.
- HL7 FHIR interoperability protocols:Standardized APIs are dissolving data silos between radiology departments and enterprise electronic health records.
Market Restraints
- Cross-border data governance friction:GDPR's extraterritoriality clauses complicate cloud hosting architectures that span multiple European jurisdictions.
- Specialized radiology informatics talent scarcity:Health systems in secondary cities face recruitment gaps for DICOM integration specialists and clinical workflow engineers.
- Hybrid cloud connectivity infrastructure:Rural hospital networks lack fiber bandwidth for real-time image streaming to centralized cloud archives.
Strategic Opportunities
- Telemedicine provider segment:Remote diagnostic platforms in Brazil and Mexico require turnkey image management without capital-intensive server deployments.
- FDA software-as-medical-device pathway:AI-enabled diagnostic algorithms now require structured quality-system documentation that creates compliance service revenue streams.
- Edge computing convergence:On-premise inference chips paired with cloud archives enable real-time image preprocessing at the modality.
Industry Challenges
- DICOM-to-FHIR mapping complexity:Health IT teams struggle to reconcile decades of proprietary metadata schemas with modern interoperability standards.
- AI model validation timelines:FDA 21 CFR Part 820 protocols for machine-learning components extend software release cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Image Management Market |
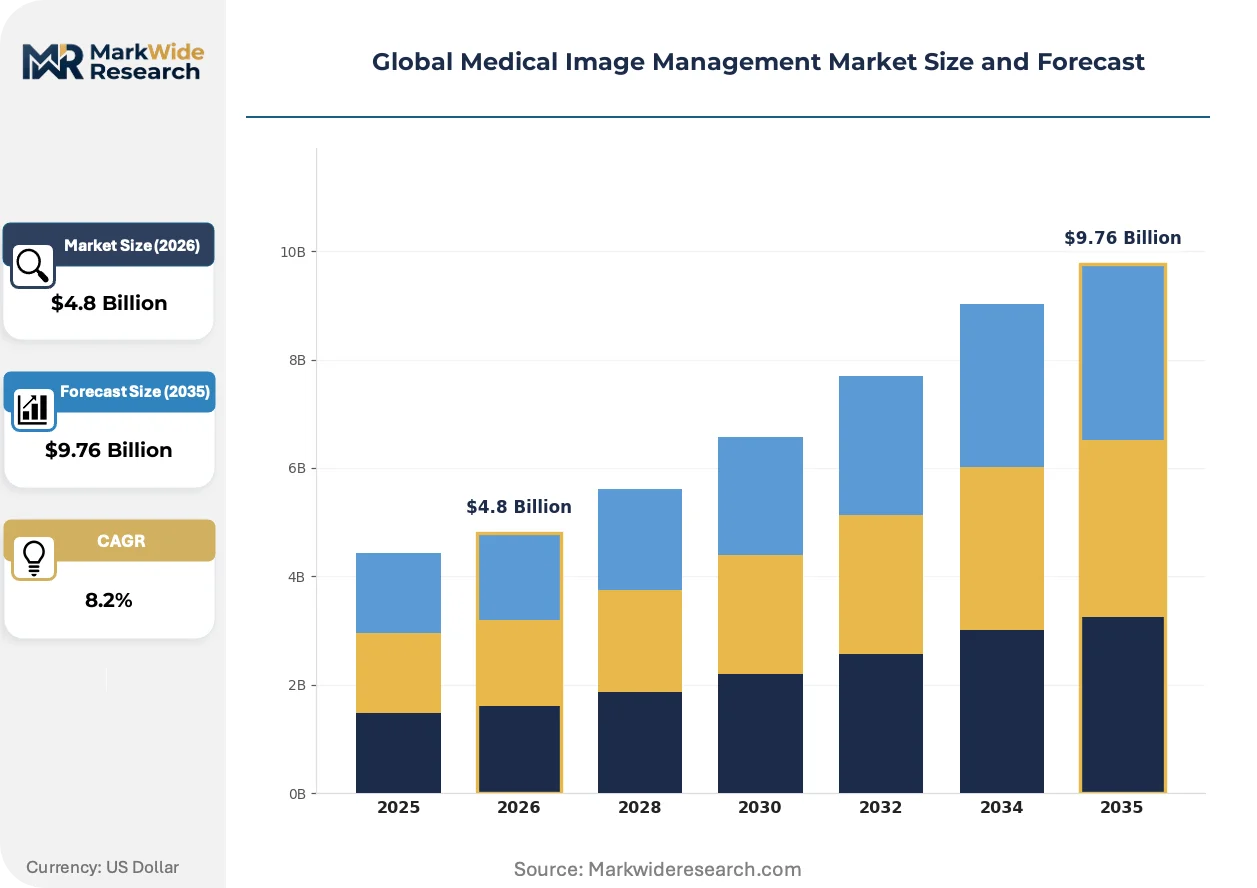
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PACS, VNA, Imaging Analytics, Enterprise Viewer, Cloud Archive, Reporting Software Application: Radiology, Cardiology, Oncology, Orthopedics, Neurology, Dental End User: Hospitals, Specialty Clinics, Diagnostic Centers, Telemedicine Providers, Research Institutes, Imaging Centers Deployment: On-Premise, Cloud-Based, Hybrid, Virtualized Environments, Federated Systems, Edge Computing |
| Companies Covered | GE HealthCare, Siemens Healthineers AG, Koninklijke Philips N.V., McKesson Corporation, FUJIFILM Holdings Corporation, Agfa-Gevaert Group, Carestream Health, Sectra AB, Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Image Management Market Strategic Shifts & Innovations
Artificial intelligence is embedding itself into every layer of image management infrastructure, from acquisition protocols through diagnostic decision support, fundamentally altering how radiology departments architect their technology stacks.
Serverless computing architectures are converging with diagnostic imaging workloads to eliminate idle infrastructure costs. Regional diagnostic chains in the United States are adopting consumption-based storage pricing that scales with examination volume. This convergence is compressing total cost of ownership by 40-60% compared to traditional capital-intensive deployments.
The EU AI Act's risk-classification framework for diagnostic algorithms is forcing vendors to restructure compliance documentation. High-risk AI applications now require conformity assessments that mirror medical device certification rigor. European health systems are delaying procurement decisions until vendor roadmaps demonstrate regulatory pathway clarity.
Radiology groups are consolidating vendor relationships around enterprise imaging platforms that unify cardiology and radiology workflows. Integrated delivery networks in the United States are replacing best-of-breed point solutions with single-vendor contracts that bundle storage, viewing, and AI orchestration. This consolidation is visible most acutely among mid-sized hospital systems seeking procurement simplification.
Global Medical Image Management Market Segmentation
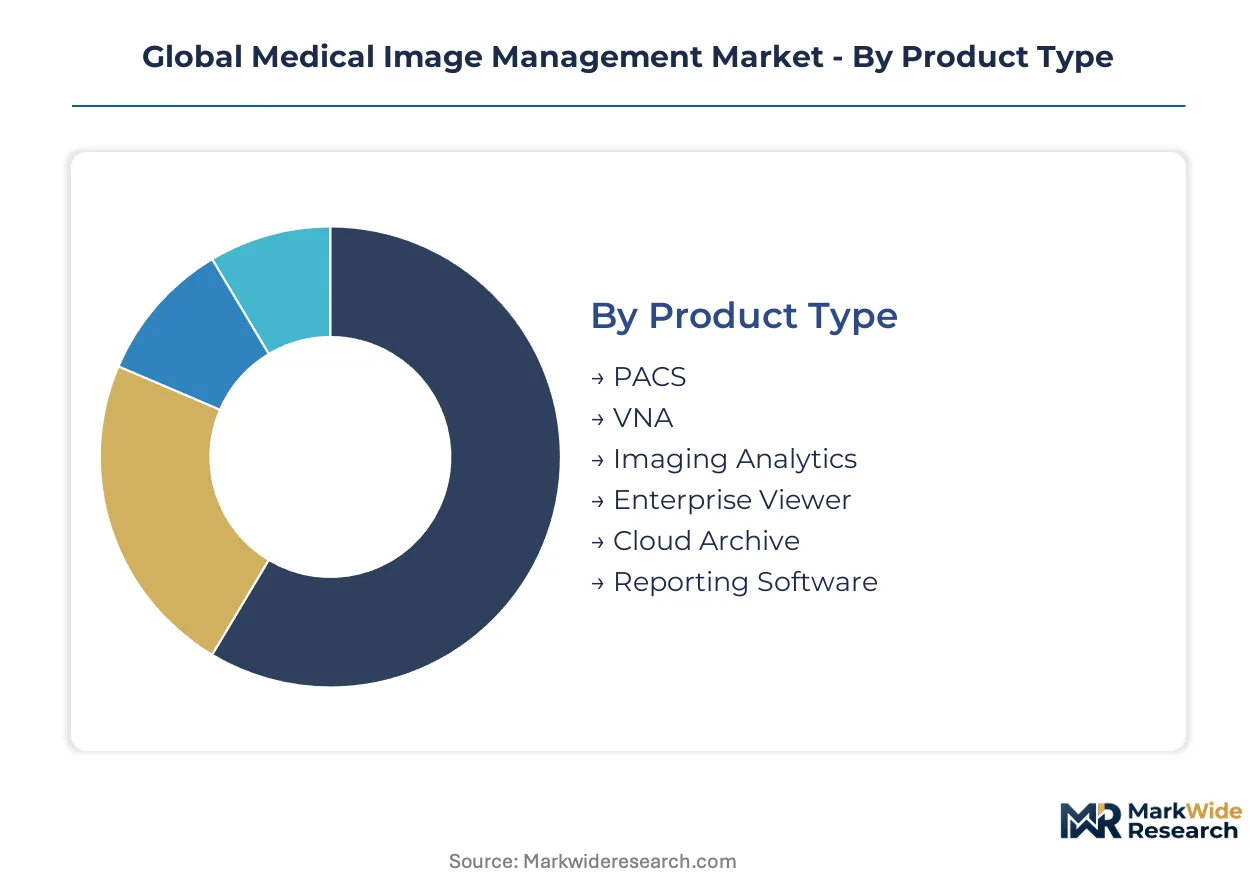
Medical image management segmentation reveals how procurement decisions bifurcate between capital-intensive hospital infrastructure and agile cloud-first deployments. Technology buyers weigh archival longevity against real-time accessibility when selecting across product categories.
Product Type:
PACS-to-VNA migration trajectories define the technology specification axis for enterprise procurement committees.
- PACS:Traditional picture archiving and communication systems anchor radiology department workflows through DICOM-compliant storage and retrieval protocols. German hospital networks under EU MDR mandates retain PACS for acute diagnostic workflows while layering VNA for long-term clinical traceability.
- VNA:Vendor-neutral archives decouple imaging data from proprietary PACS platforms, enabling cross-modality accessibility across equipment lifecycles. French health systems prioritize VNA deployments to satisfy GDPR-compliant patient-data portability requirements spanning multiple diagnostic vendors.
- Imaging Analytics:AI-powered diagnostic decision support layers extract quantitative biomarkers from imaging datasets.
- Enterprise Viewer:Zero-footprint web-based visualization tools enable remote diagnostic interpretation without client-side software installation.
- Cloud Archive:Consumption-priced object storage tiers replace capital-intensive on-premise storage arrays for secondary imaging data.
- Reporting Software:Structured reporting templates standardize radiology communication with referring physicians through HL7 FHIR integration.
PACS leads on scale; VNA leads on momentum.
Application:
Clinical volume and reimbursement intensity shape application-level demand concentration.
- Radiology:General diagnostic imaging generates the highest examination throughput across CT, MRI, and X-ray modalities. Japanese oncology screening programs drive petabyte-scale storage demands that exceed on-premise capacity.
- Cardiology:Echocardiography and cardiac catheterization imaging require specialized viewing tools with cine loop playback and quantitative ventricular analysis. United States integrated delivery networks consolidate cardiology-radiology workflows onto single enterprise platforms.
- Oncology:Longitudinal tumor tracking across serial imaging studies demands robust temporal comparison tools.
- Orthopedics:Preoperative templating and postoperative implant assessment drive 3D reconstruction software adoption.
- Neurology:Functional MRI and diffusion tensor imaging require specialized neuroimaging analysis pipelines.
- Dental:Cone-beam CT and panoramic radiography serve ambulatory dental practice workflows.
Radiology commands volume concentration; cardiology captures premium pricing per study.
End User:
Capital availability and technical staffing depth segment procurement behavior across buyer types.
- Hospitals:Acute care institutions deploy comprehensive enterprise imaging platforms unifying multiple clinical departments. South Korean hospital networks under national cancer screening mandates scale storage infrastructure to match examination volume growth.
- Diagnostic Centers:Independent imaging facilities prioritize turnkey cloud deployments minimizing IT overhead. Brazilian diagnostic chains adopt consumption-based pricing to align costs with fluctuating patient volumes.
- Specialty Clinics:Focused practices require modality-specific workflows without enterprise-scale complexity.
- Telemedicine Providers:Remote diagnostic platforms demand zero-footprint viewers and low-latency image streaming.
- Research Institutes:Academic medical centers balance clinical operations with imaging biobank curation for longitudinal studies.
- Imaging Centers:High-throughput outpatient facilities optimize throughput through automated workflow orchestration.
Hospitals anchor revenue concentration; telemedicine providers expand most quickly.
Deployment:
Connectivity infrastructure maturity and data sovereignty requirements determine architecture selection.
- Cloud-Based:Fully managed SaaS deployments eliminate capital expenditure and compress implementation timelines from months to weeks. United States rural health systems lacking fiber bandwidth for real-time streaming adopt cloud archives with local caching appliances.
- Hybrid:Split architectures retain recent studies on-premise for immediate access while aging data migrates to cloud tiers. German hospital networks satisfy EU GDPR data-residency requirements through hybrid configurations with European-hosted cloud regions.
- On-Premise:Traditional data center deployments persist where regulatory constraints or bandwidth limitations preclude external hosting.
- Virtualized Environments:Software-defined infrastructure abstracts storage hardware from application layers.
- Federated Systems:Distributed architectures enable cross-institutional image sharing without centralized data aggregation.
- Edge Computing:On-premise inference processors enable real-time AI preprocessing at the modality before cloud archival.
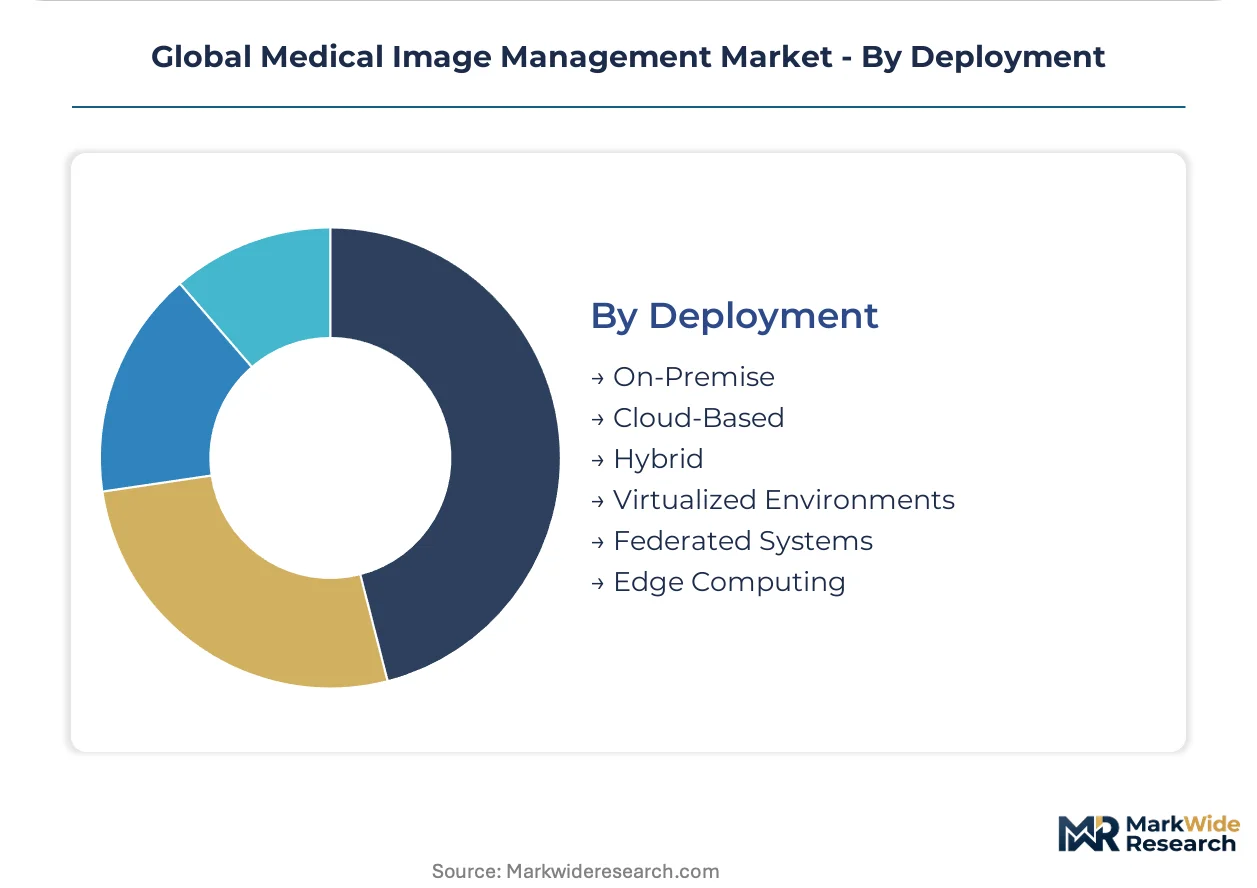
Hybrid architectures dominate current procurement; cloud-native configurations show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital networks outpace French systems in PACS-to-VNA migration velocity, while South Korean oncology screening programs generate storage demands that rival entire European regions.
United States
Integrated delivery networks in Texas and California consolidate cardiology-radiology workflows onto single enterprise platforms. FDA 21 CFR Part 820 quality-system requirements shape software validation protocols for market access. The Mayo Clinic cluster in Rochester anchors hybrid cloud deployments across Midwestern health systems.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia expand vendor-neutral archives under EU MDR data-integrity mandates. GDPR cross-border data governance clauses complicate cloud hosting architectures spanning multiple European jurisdictions. The Berlin-Brandenburg medical technology corridor hosts concentrated PACS migration consulting capacity.
Japan
National cancer screening programs in Kanto and Kansai regions generate petabyte-scale imaging data flows exceeding on-premise storage capacity. PMDA software-as-medical-device guidance shapes AI-enabled diagnostic algorithm documentation requirements. The Nagoya medical device cluster specializes in enterprise viewer integration for telemedicine providers.
South Korea
Hospital networks under national cancer screening mandates scale storage infrastructure to match examination volume growth in Seoul Capital Area. MFDS regulates clinical traceability requirements for diagnostic imaging systems. The Busan-Ulsan diagnostic hub drives cloud-native deployment adoption among regional imaging centers.
Brazil
Diagnostic chains in São Paulo and Rio de Janeiro adopt consumption-based pricing to align costs with fluctuating patient volumes. ANVISA medical device regulations govern software validation for imported image management platforms. The São Paulo metropolitan cluster concentrates telemedicine provider demand for turnkey cloud deployments.
Global Medical Image Management Market Key Industry Players
United States producers anchor the premium enterprise tier; European specialists hold regulatory compliance differentiation. The vendor base concentrates around three strategic archetypes: diversified health technology conglomerates, pure-play imaging software developers, and radiology-focused workflow specialists. M&A activity targets AI orchestration capabilities, while strategic partnerships address hybrid cloud connectivity gaps.
Among diversified health technology conglomerates, GE HealthCare and Siemens Healthineers AG exemplify the modality-anchored platform approach. FUJIFILM Holdings Corporation occupies a distinct position bridging enterprise viewer architectures with interoperability layers for telemedicine integration. These three represent divergent strategic postures: equipment-led ecosystem control, AI-native orchestration extension, and software-centric interoperability specialization.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| McKesson Corporation |
| FUJIFILM Holdings Corporation |
| Agfa-Gevaert Group |
| Carestream Health |
| Sectra AB |
| Canon Medical Systems Corporation |
| Others |
Cost & Logistics Intelligence
EU MDR data-integrity mandates are forcing German hospital networks to accelerate PACS-to-VNA migrations, compelling vendors to absorb compliance documentation costs and compress implementation timelines while maintaining subscription pricing tiers that reflect regulatory service bundling.
Pricing Analysis
Distributor margins in enterprise imaging typically range from 15% to 25% for channel partners serving mid-sized hospital systems, while direct-to-IDN contracts eliminate intermediary markups entirely. Three-tier pricing structure across premium, standard, and economy levels stratifies by deployment complexity, with hybrid cloud configurations commanding premium positioning against pure SaaS alternatives. Cost compression in the standard tier is intensifying because Brazilian diagnostic chains and Mexican telemedicine providers are consolidating procurement around consumption-based storage pricing. Diagnostic centers exhibit highest price sensitivity due to capital constraints, whereas integrated delivery networks in the United States prioritize total cost of ownership over per-unit pricing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States integrated delivery networks and South Korean hospital systems, while regional VARs serve secondary cities lacking specialized radiology informatics talent. Manufacturing concentration spans the United States for FDA-validated software stacks, Germany for EU MDR-compliant archival systems, and Japan for enterprise viewer architectures. Component dependencies include DICOM parsing engines, HL7 FHIR integration modules, and GPU-accelerated inference chips. Single-source vulnerability in cloud infrastructure regions creates exposure when European GDPR data-residency requirements conflict with centralized hosting economics. Distribution runs through modality OEMs, GPO contracts, and direct SaaS provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native deployment economics create geographic arbitrage between United States health systems with fiber bandwidth for real-time streaming and Brazilian diagnostic chains seeking turnkey implementations without capital-intensive infrastructure.
For Market Incumbents: Anticipate margin pressure from AI-native orchestration layers by deepening in-house production of machine-learning components and securing FDA software-as-medical-device pre-certification pathways before EU AI Act conformity assessments reshape competitive positioning. Anchor hybrid cloud deployments through modality-installed base control, particularly across Midwestern United States health systems consolidating cardiology-radiology workflows. For New Entrants and Emerging Players: Rural hospital networks in secondary United States cities present the most penetrable buyer archetype, given fiber bandwidth limitations that preclude real-time cloud streaming and scarcity of DICOM integration specialists for on-premise maintenance. Target telemedicine providers in São Paulo and Mexico City with zero-footprint enterprise viewers bundled with consumption-priced cloud archives. Lead with regulatory compliance as a service, outsourcing EU MDR documentation and FDA 21 CFR Part 820 validation for AI-enabled diagnostic algorithms. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play imaging software developers possessing AI orchestration capabilities and established HL7 FHIR interoperability layers, positioned for acquisition by diversified health technology conglomerates seeking to extend beyond traditional PACS boundaries. Long-term viability hinges on regulatory pathway clarity across FDA software-as-medical-device guidance and EU AI Act risk-classification frameworks. Watch procurement consolidation signals among mid-sized United States hospital systems replacing best-of-breed point solutions with single-vendor enterprise imaging contracts.| Strategic Initiative | Industry Significance |
|---|---|
| AI Orchestration Layer Development | Extends vendor positioning beyond traditional PACS boundaries into diagnostic decision support workflows. |
| EU MDR Compliance Documentation Service | Captures recurring revenue from hospital networks migrating vendor-neutral archives under clinical traceability mandates. |
| Hybrid Cloud Connectivity Partnership | Addresses rural bandwidth limitations through local caching appliances paired with centralized cloud archives. |
| FHIR-Native Enterprise Viewer Launch | Enables zero-footprint remote diagnostic interpretation without client-side software installation overhead. |
| Edge Computing Inference Integration | Delivers real-time AI preprocessing at the modality before cloud archival, reducing latency for acute workflows. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital CIOs, radiology department heads, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EUDAMED device registrations, hospital procurement databases, and CMS Medicare imaging utilization data. Bottom-up modeling of PACS, VNA, and cloud archive deployments triangulated against top-down health IT infrastructure spending estimates from integrated delivery networks.
Segment-weighting applied differential growth assumptions across deployment models, with cloud-native configurations receiving higher trajectory coefficients than on-premise alternatives, and product types stratified by migration momentum from PACS toward VNA and imaging analytics. End-user segments incorporated capital availability scoring for hospitals versus diagnostic centers. CAGRs derived from fitted exponential curves applied to examination volume growth, storage cost decline rates, and regulatory compliance spending patterns. Forecast inputs included oncology screening program expansion in Japan and South Korea, EU AI Act implementation timelines, and fiber bandwidth deployment curves in rural United States markets.
Underlying measurement precision varies by segment; cloud-based deployment forecasts carry tighter precision than edge computing configurations given earlier commercial maturity. Periodic stress-testing of base assumptions is recommended, particularly around FDA software-as-medical-device guidance evolution and GDPR cross-border data governance enforcement patterns that could accelerate or delay procurement decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Specimen Radiography Systems Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Global Stroke Post Processing Software Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Image Guided Systems Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
Contrast Media Market
Medical Imaging
United States Mammography Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Global Mobile Medical Imaging Services Market