
 North America Biopsy Devices Market | 2026-2036
North America Biopsy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biopsy Devices Market Analytics
Modular disposable biopsy needle kits is pivoting how procurement teams evaluate total cost of ownership against capital equipment investments. Becton Dickinson leverages its integrated manufacturing scale to control supply continuity across North American distribution channels. Hologic anchors its position through dedicated R&D intensity in vacuum-assisted tissue acquisition systems. Cook Medical competes by sustaining geographic dominance in interventional radiology suites across Canadian and US tertiary centers.
Biopsy devices are precision-engineered instruments designed to extract tissue specimens from solid organs or lesions for histopathological examination, typically incorporating hollow needles, cannulas, or vacuum-assisted mechanisms with gauge specifications ranging from 8 to 21 depending on target tissue density. Their primary commercial purpose centers on enabling definitive disease diagnosis while minimizing patient trauma and procedural complications. Needle biopsy devices command the largest installed base due to widespread use in outpatient settings, while vacuum-assisted devices represent the fastest-expanding segment as breast imaging protocols expand across North American screening programs. Ultrasound-guided technology leads procedural volume owing to real-time visualization advantages and lower per-procedure cost structures compared to MRI-guided alternatives.
FDA 510(k) clearance pathways and Health Canada's Medical Devices Bureau licensing requirements shape product development timelines and clinical evidence standards for manufacturers seeking North American market access. The US Centers for Medicare & Medicaid Services reimbursement coding for image-guided biopsy procedures directly influences hospital capital allocation and device adoption velocity. Stakeholders must monitor evolving CMS technology add-on payment designations and provincial health authority procurement frameworks as determinants of commercial traction.
Market Dynamics
Minimally invasive tissue sampling protocols are compressing hospital procurement cycles and forcing device manufacturers to demonstrate total cost-of-ownership advantages alongside clinical efficacy. This structural shift toward outpatient-compatible biopsy systems is redistributing purchasing authority from surgical departments to ambulatory care administrators.
Growth Catalysts
- CMS Reimbursement Codes:Updated physician fee schedule designations for image-guided biopsy procedures accelerate capital equipment replacement cycles in US hospital networks. Facilities recoup device investments through procedure volume incentives embedded in outpatient payment bundles.
- Vacuum-Assisted Mechanisms:Breast imaging centers across Ontario and California deploy vacuum-assisted tissue acquisition for stereotactic core biopsies, reducing sampling insufficiency rates and repeat procedures. This technology pull concentrates demand among high-throughput screening programs.
- Interventional Radiology Suites:Canadian tertiary centers expand percutaneous biopsy capabilities for renal and hepatic lesions, creating installed base expansion for disposable needle kits. Toronto and Vancouver hospital systems anchor this geographic concentration.
Market Restraints
- Stainless Steel Cannula Costs:Raw material price volatility for medical-grade stainless steel compresses gross margins on disposable needle kits. Manufacturers face input cost pressure without proportional pricing flexibility in provincial procurement frameworks.
- FDA 510(k) Evidence Requirements:Substantial equivalence demonstrations for new biopsy needle designs demand predicate device comparisons and clinical validation studies. This regulatory friction extends product development timelines by 12-18 months for novel gauge configurations.
- Core Needle Sampling:Fine needle aspiration cytology retains cost advantages for certain thyroid and lymph node applications, limiting penetration of automated core biopsy systems in community pathology settings. Substitution threat concentrates in outpatient endocrinology practices.
Strategic Opportunities
- Texas and Florida Ambulatory Surgery Centers:Underpenetrated freestanding surgical facilities in these states present white-space expansion for disposable biopsy device vendors. Certificate-of-need deregulation enables independent center development outside hospital system control.
- Health Canada Medical Devices Bureau Streamlining:Harmonized review pathways with FDA 510(k) clearances reduce dual-market registration burdens. This regulatory tailwind accelerates Canadian commercial launches for US-approved vacuum-assisted systems.
- Robotic-Assisted Integration:Convergence of electromagnetic navigation with robotic needle positioning enables real-time trajectory correction during lung and prostate biopsies. Interventional radiology departments at academic medical centers pilot these convergent platforms.
Industry Challenges
- Interventional Radiology Training Pipelines:Fellowship program capacity constraints limit the supply of physicians qualified to perform complex image-guided biopsies. Skill gap bottlenecks procedural volume expansion regardless of device availability.
- ISO 13485 Certification Timelines:Quality management system audits for contract manufacturers of biopsy needle components face backlogs at notified bodies. Certification delays disrupt supply continuity for kit assemblers dependent on outsourced cannula production.
- PACS Integration Complexity:Biopsy device tracking systems must interface with proprietary picture archiving and communication platforms deployed across heterogeneous hospital IT environments. Legacy system interoperability demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biopsy Devices Market |
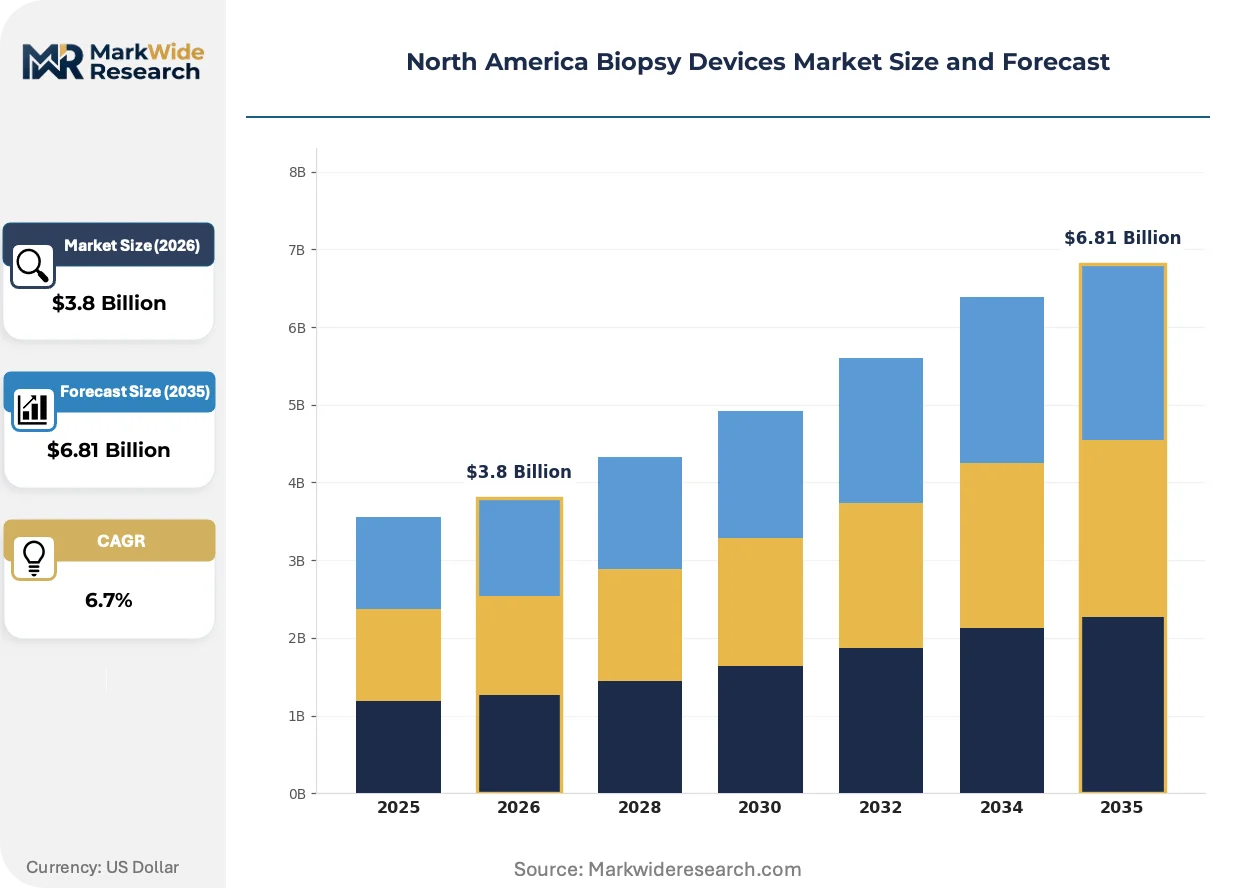
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Biopsy Devices, Core Biopsy Devices, Vacuum-Assisted Devices, Surgical Biopsy Devices End User: Hospitals, Diagnostic Laboratories, Specialty Clinics, Research Institutes Technology: Ultrasound-Guided, MRI-Guided, CT-Guided, X-Ray-Guided Application: Oncology, Infectious Diseases, Autoimmune Disorders, Hematology |
| Companies Covered | Becton Dickinson, Hologic, Boston Scientific Corporation, Cook Medical, Argon Medical Devices, Cardinal Health, Danaher Corporation, Devicor Medical Products, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biopsy Devices Market Evolving Landscape
Disposable component architectures are displacing reusable instrument platforms across North American biopsy workflows. This transformation compresses capital expenditure requirements while elevating consumable revenue predictability for device vendors.
Spring-loaded core needle systems with coaxial introducer designs are expanding into outpatient breast imaging centers and urology clinics. These devices enable single-operator tissue acquisition with reduced procedural time. The technology is expanding into community-based settings previously dependent on referral to academic medical centers, flattening geographic access disparities.
Health Canada's implementation of the Medical Devices Regulations (MDR) alignment initiative tightens post-market surveillance requirements for Class II biopsy instruments. Manufacturers must establish systematic complaint handling and adverse event reporting infrastructure. Small-to-mid sized device vendors face disproportionate compliance burden, accelerating market exit or acquisition by integrated manufacturers with established quality systems.
Hospital value analysis committees now dominate biopsy device selection, displacing individual physician preference as the primary purchase determinant. These committees evaluate total supply chain cost including waste disposal and sterilization against clinical outcome metrics. The shift is most visible in integrated delivery networks across Illinois and Pennsylvania, where standardized formulary restrictions limit vendor fragmentation.
North America Biopsy Devices Market Segmentation
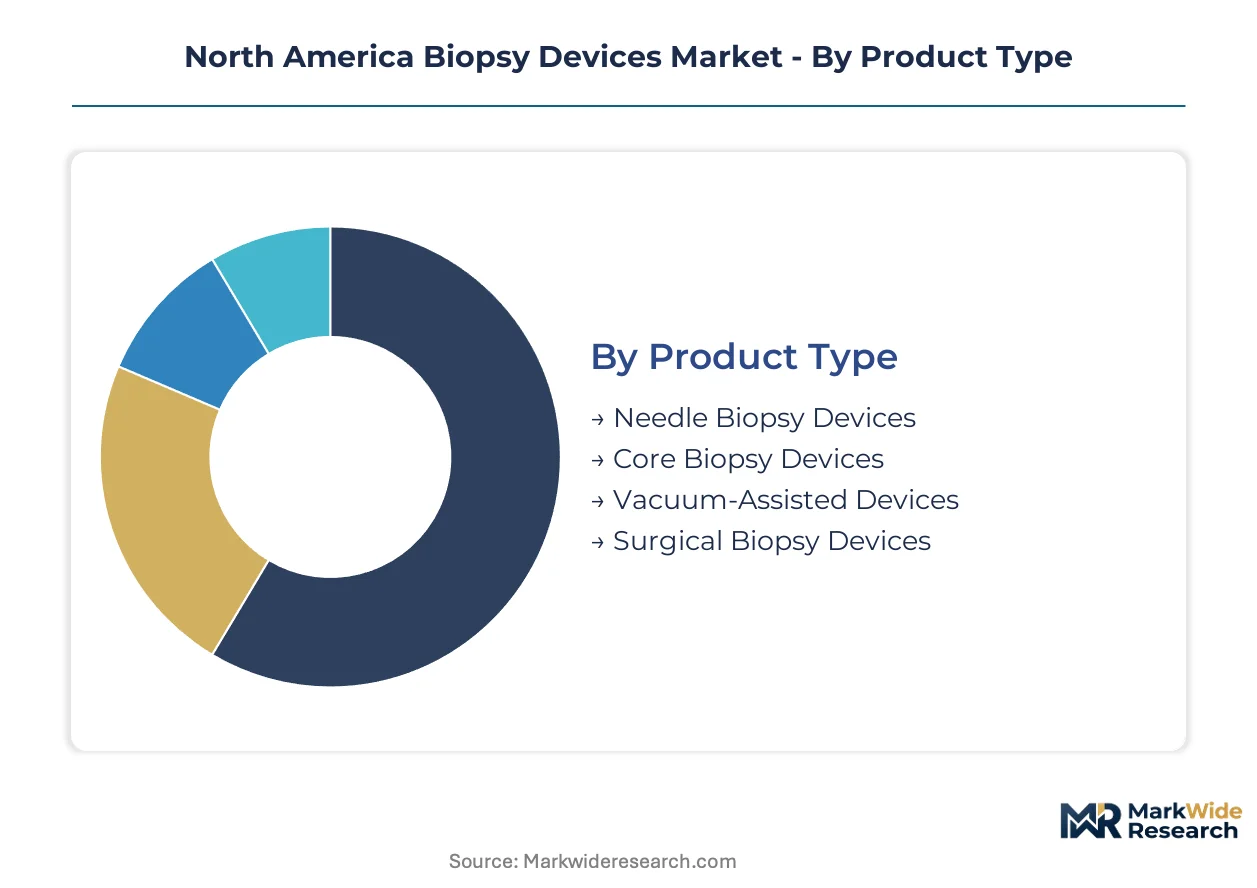
Biopsy device procurement patterns diverge sharply across clinical settings and imaging modalities. Hospital value analysis committees weight capital intensity against consumable throughput differently than freestanding imaging centers. Understanding these segment boundaries clarifies where manufacturers must adapt specification bundles versus pricing architectures.
Product Type:
Procurement teams in US hospital networks evaluate total cost of ownership differently than Canadian provincial authorities purchasing for regional health systems.
- Needle Biopsy Devices:Spring-loaded and manual cutting needles dominate outpatient breast imaging and thyroid clinics across California and Texas. Disposable 14- to 18-gauge configurations minimize sterilization logistics for high-throughput screening programs. Demand concentrates in community radiology practices seeking single-operator efficiency without capital equipment investment.
- Vacuum-Assisted Devices:These systems extract multiple tissue cores through a single needle insertion using continuous suction. Breast imaging centers in Ontario and Illinois deploy them for stereotactic core biopsies, reducing sampling insufficiency rates below 5%. Provincial screening programs in Canada drive volume concentration through centralized procurement.
- Core Biopsy Devices:Automated cutting mechanisms with coaxial introducer designs serve renal and hepatic applications in interventional radiology suites at academic medical centers in Boston and Toronto.
- Surgical Biopsy Devices:Excisional and incisional instruments retain relevance for lesion removal with diagnostic intent in hospital operating rooms across the US Southeast.
Needle biopsy devices lead volumes today; vacuum-assisted systems are gaining share fastest.
End User:
Capital availability and procedure reimbursement rates create tiered purchasing authority across the care continuum.
- Hospitals:Integrated delivery networks in Pennsylvania and Illinois dominate capital allocation for image-guided biopsy suites. Value analysis committees standardize device formularies across multiple campuses, favoring vendors with supply chain reliability and enterprise pricing agreements.
- Diagnostic Laboratories:Independent pathology groups in Florida and Arizona outsource tissue acquisition to affiliated imaging centers but retain influence over specimen handling protocols. Their demand centers on compatibility with automated processing systems.
- Specialty Clinics:Urology and breast imaging practices in Texas certificate-of-need deregulation zones purchase disposable kits for in-office procedures.
- Research Institutes:Academic medical centers in Vancouver and Boston acquire specialized instruments for translational oncology studies with distinct regulatory and documentation requirements.
Hospitals absorb the majority of capital expenditure; specialty clinics are expanding disposable kit volumes most rapidly.
Technology:
Imaging modality selection hinges on tissue target visibility, procedural cost structures, and real-time navigation requirements.
- Ultrasound-Guided:Real-time visualization without ionizing radiation dominates thyroid, breast, and superficial lymph node applications. Lower per-procedure costs compared to MRI alternatives drive adoption in community settings across the US Midwest.
- MRI-Guided:Closed-bore and open-configuration systems enable biopsy of MRI-only visible lesions in academic breast centers. High capital and operational costs restrict deployment to major metropolitan hospital networks.
- CT-Guided:Cross-sectional imaging serves deep thoracic and abdominal targets in interventional radiology departments.
- X-Ray-Guided:Stereotactic mammography systems anchor breast tissue acquisition in Ontario screening programs.
Ultrasound-guided technology commands procedural volume leadership; MRI-guided systems are climbing the fastest among academic centers.
Application:
Disease prevalence and screening protocol intensity shape segment-specific demand cycles across North American jurisdictions.
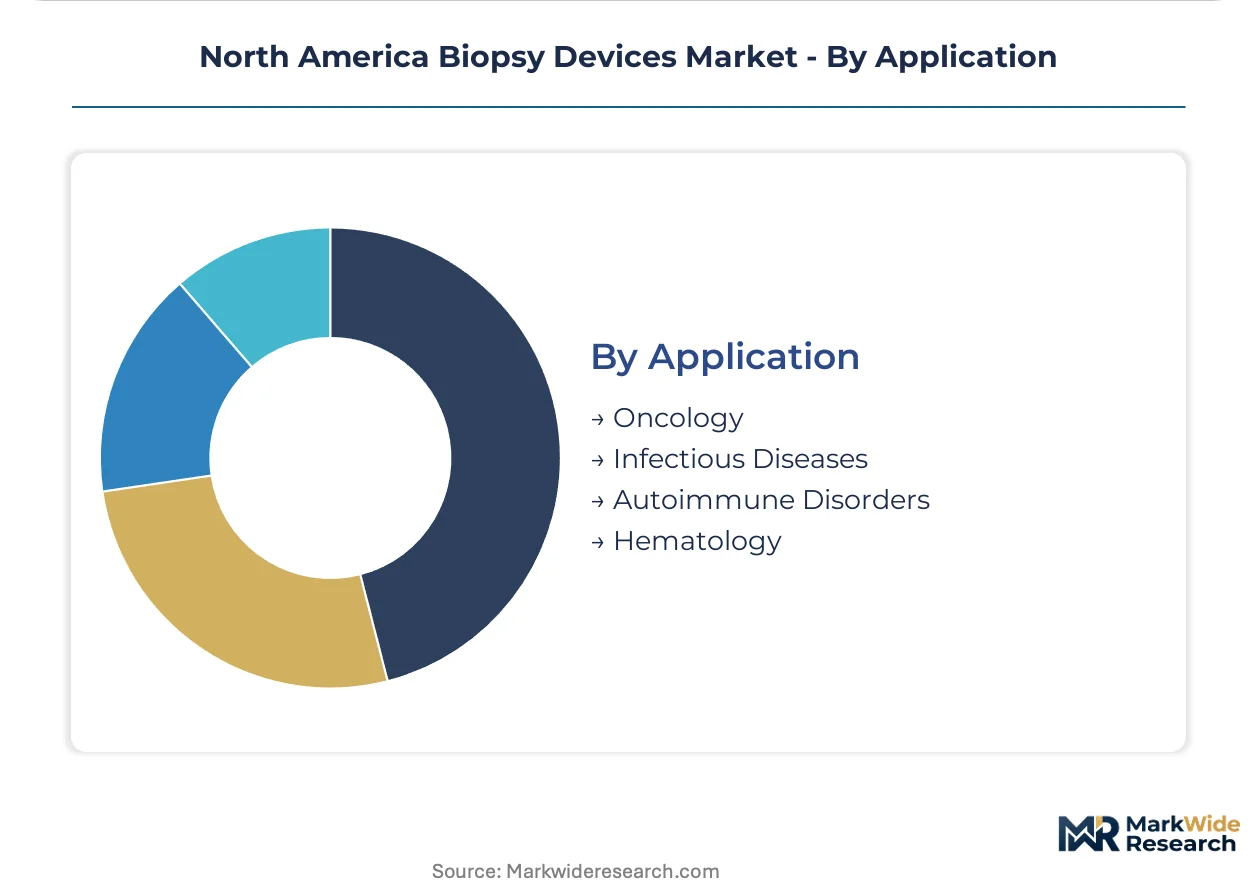
- Oncology:Solid tumor diagnosis drives the majority of biopsy device utilization across US integrated cancer centers. Breast, lung, and prostate screening program expansions in California and Ontario concentrate demand for vacuum-assisted and core needle systems.
- Infectious Diseases:Deep tissue sampling for atypical mycobacterial and fungal infections supports CT-guided procurement in tertiary pulmonary centers.
- Autoimmune Disorders:Renal and skin biopsies for lupus and vasculitis workups occur in rheumatology-dermatology collaborative practices.
- Hematology:Bone marrow aspiration and trephine biopsies retain specialized needle requirements in academic hematology units.
Oncology anchors current revenue concentration; infectious disease applications are expanding most quickly in southwestern US pulmonary institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American biopsy devices industry traces its commercial scale-up to post-war US hospital system expansion and the subsequent diffusion of image-guided intervention protocols across Canadian provincial health networks. Early vacuum-assisted technology development concentrated in Midwestern US manufacturing corridors before spreading to Ontario's medical device cluster. Today, procurement patterns and regulatory frameworks diverge meaningfully across the three North American jurisdictions.
United States
FDA 510(k) clearance pathways and CMS reimbursement coding for image-guided procedures shape commercial velocity across US hospital networks. Texas and Florida ambulatory surgery centers expand disposable kit volumes following certificate-of-need deregulation. Major metropolitan hospital networks in California and Illinois anchor vacuum-assisted system adoption through integrated cancer center expansions.
Canada
Health Canada's Medical Devices Bureau licensing requirements and provincial screening program centralization concentrate demand in Ontario and British Columbia. Harmonized review pathways with FDA clearances accelerate commercial launches for US-approved systems. Toronto and Vancouver tertiary centers drive percutaneous biopsy capability expansion for renal and hepatic applications.
Mexico
Federal Commission for the Protection against Sanitary Risk (COFEPRIS) registration requirements govern device importation and distribution across Mexican hospital systems. Private hospital chains in Mexico City and Monterrey absorb premium-priced vacuum-assisted systems for breast imaging centers. Public sector procurement through INSABI channels favors cost-optimized needle biopsy configurations for oncology departments.
North America Biopsy Devices Market Competitive Landscape
The competitive structure tilts toward integrated diversified manufacturers with established quality management systems and hospital supply chain relationships. Consolidation pressure favors players with captive manufacturing scale and multi-site service infrastructure. Three archetypes dominate: diversified medical technology conglomerates with broad hospital contracting authority, specialized interventional radiology device manufacturers with deep procedural workflow expertise, and disposable component suppliers leveraging contract manufacturing scale. Dominant competitive moves include strategic portfolio diversification into adjacent tissue acquisition modalities and backward integration into cannula production to secure stainless steel supply continuity.
Among integrated diversified manufacturers, Becton Dickinson and Hologic occupy positions reflecting contrasting strategic emphases on supply chain control versus R&D intensity in vacuum-assisted platforms. Cook Medical exemplifies the specialized interventional radiology archetype with geographic concentration in tertiary center suites. These three anchors illustrate how competitive positioning diverges across manufacturing scale, technology specialization, and clinical workflow integration vectors.
| Leading Market Players |
|---|
| Becton Dickinson |
| Hologic |
| Boston Scientific Corporation |
| Cook Medical |
| Argon Medical Devices |
| Cardinal Health |
| Danaher Corporation |
| Devicor Medical Products |
| CONMED Corporation |
| Others |
Value Network & Pricing Analysis
Medical-grade stainless steel price indices cascade through North American biopsy device supply chains into three-tier pricing structures across premium, standard, and economy levels. Procurement teams at integrated delivery networks and provincial health authorities calibrate total cost-of-ownership evaluations against raw material volatility and sterilization logistics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs North American biopsy device transactions. Price differentiation hinges on FDA 510(k) clearance tier and sterilization validation depth, with vacuum-assisted systems commanding premiums over spring-loaded alternatives. Cost compression in disposable needle kits is intensifying because stainless steel input volatility outpaces pricing flexibility in provincial procurement frameworks. Community radiology practices exhibit highest price sensitivity; academic medical centers with dedicated capital budgets show lowest.
Supply Chain Analysis
Dual-sourcing requirements for medical-grade stainless steel cannulas mandate multi-supplier qualification across US hospital networks and Canadian provincial authorities. Manufacturing concentration centers on Midwestern US corridors and Ontario's medical device cluster, with component sourcing from Germany and Japan for precision cutting mechanisms. Supply chain risk rests on single-source vulnerability for 14- to 18-gauge needle configurations. Distribution runs through integrated delivery network contracting offices and GPO aggregation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America biopsy devices function as a geographic-arbitrage play between US certificate-of-need deregulation zones and Canadian provincial screening program centralization. Texas and Florida ambulatory surgery centers absorb capital equipment faster than Ontario's budget-constrained procurement cycles.
For Market Incumbents: Cement supply continuity through captive cannula production and ISO 13485 certification investment at contract manufacturing partners. Emerging disposable component suppliers threaten margin compression in community radiology segments. Backward integration into stainless steel sourcing anchors pricing power against raw material volatility. For New Entrants and Emerging Players: Ambulatory surgery center distributors offer the fastest path to commercial traction in Texas and Florida certificate-of-need deregulation corridors. Underpenetrated freestanding breast imaging centers in Phoenix and Houston present white-space expansion. Reimbursement strategy alignment with CMS outpatient payment bundles accelerates hospital value analysis committee access. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized interventional radiology device manufacturers possessing deep procedural workflow expertise and Health Canada licensing infrastructure. Long-term viability frames around vacuum-assisted platform adoption and robotic-assisted integration convergence. Watch FDA 510(k) clearance velocity for novel gauge configurations as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access through streamlined substantial equivalence pathways for Class II instruments. |
| Hospital System Partnership | Secures enterprise pricing agreements with integrated delivery networks in Illinois and Pennsylvania. |
| Backward Integration | Captures stainless steel cannula production to insulate margins from raw material price volatility. |
| Software Companion Development | Enables PACS integration for biopsy device tracking across heterogeneous hospital IT environments. |
| Reimbursement Strategy | Aligns product specifications with CMS technology add-on payment designations for image-guided procedures. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured perspectives from interventional radiologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers across US and Canadian facilities. Secondary validation drew from FDA 510(k) filings, Health Canada Medical Devices Bureau licensing records, CMS Medicare reimbursement databases, and hospital procurement contracts. Bottom-up device shipment analysis and top-down healthcare expenditure triangulation anchored market sizing.
Comparable-period anchoring linked projection models to historical procedure volume trends and capital equipment replacement cycles across the analysis window. Segmentation dimensions modeled encompass product type, imaging modality, end-user setting, and application area. CAGRs derived from regression analysis against screening program expansion rates and reimbursement code adoption curves. Forecast inputs incorporated provincial procurement framework evolution and ambulatory surgery center development permits.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA review pathway modifications and provincial health authority budget allocations. Deviation in stainless steel commodity pricing or interventional radiology fellowship program capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Ear Tube Devices Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
North America Medical Device Regulatory Affairs Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Global Intra-Cranial Pressure (ICP) Monitor Market
Medical Devices
South Africa Respiratory Devices Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Distraction Osteogenesis Devices Market
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Annuloplasty System Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Digital Reading Micropipettes Market