
 Telemedicine Cart Market | 2026-2036
Telemedicine Cart Market Size, Share, and Industry Trends Forecast 2026-2036
Telemedicine Cart Market Analysis
Software-defined remote diagnostics is recalibrating how telemedicine cart value gets captured, shifting revenue from hardware sales toward recurring platform fees. AMD Global Telemedicine anchors its position through integrated software-hardware bundles for federal and military health systems. Ergotron competes on ergonomic engineering standards that reduce clinician strain during extended virtual consultations. Capsa Healthcare specializes in modular cart architectures that accommodate rapid peripheral swaps across clinical settings.
A telemedicine cart is a mobile or fixed workstation integrating display, computing, camera, audio, and medical device connectivity into a single clinical-grade unit, typically engineered to IEC 60601-1 electrical safety standards for patient vicinity use. Its primary purpose is to deliver real-time audio-visual consultation and diagnostic data transmission between remote clinicians and patients. Portable carts command the dominant volume position due to flexibility across ward rotations and emergency deployment, while wall-mounted systems concentrate margin pools in permanent specialty suites where installation complexity limits vendor competition. Telepresence systems within the technology dimension are gaining fastest as hospitals prioritize immersive specialist interaction over basic video conferencing.
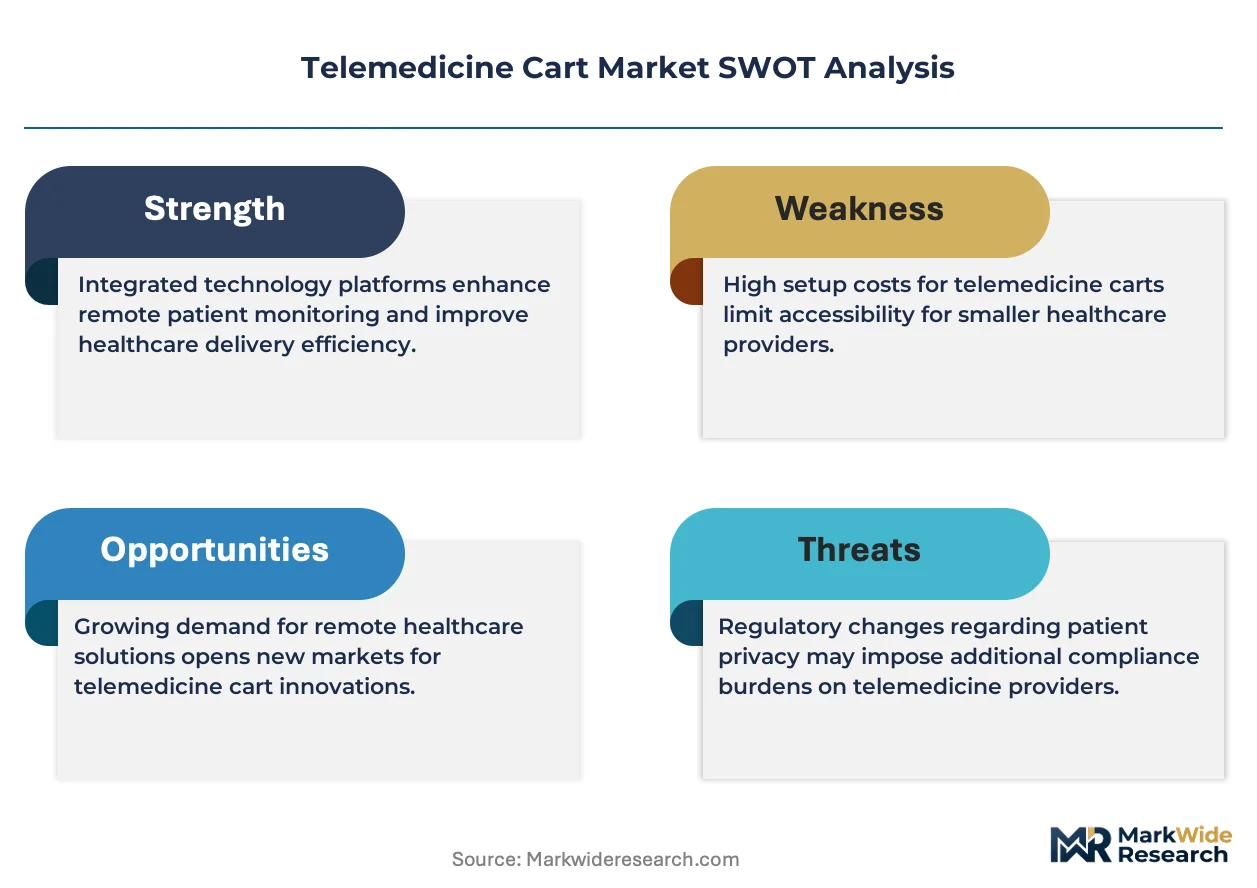
FDA oversight of cart-integrated software as a medical device, combined with HIPAA security rule requirements for patient data transmission, elevates compliance costs for new entrants while reinforcing incumbent technical moats. The EU MDR and CE marking framework for electrical medical equipment creates parallel certification demands for suppliers serving European health systems. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring, as payor policy shifts will directly determine which cart configurations hospitals can justify operationally.
Market Dynamics
Software-defined diagnostics is collapsing hardware margins into recurring platform revenue, forcing cart manufacturers to restructure from equipment vendors to clinical workflow service providers.
Growth Catalysts
- Telehealth Parity Mandates:State-level laws in the American Southeast now mandate equivalent reimbursement for virtual and in-person consultations, directly expanding hospital capital budgets for mobile diagnostic infrastructure.
- IEC 60601-1 Certification Harmonization:Electrical safety standard alignment across FDA and EU MDR pathways is reducing dual-certification costs for patient-vicinity medical equipment.
- Peripheral Miniaturization:USB-C and wireless diagnostic attachments are enabling rapid cart reconfiguration between cardiology, dermatology, and emergency department workflows without hardware swaps.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundries dominate medical-grade image processing chip fabrication, exposing cart manufacturers to single-source vulnerability for high-resolution camera modules.
- FDA Software-as-Medical-Device Pathways:Evolving 510(k) requirements for cart-integrated AI diagnostic tools are extending certification timelines and elevating legal exposure for algorithm-driven patient decisions.
- Copper and Lithium Pricing Volatility:Battery and power distribution components face raw material cost swings that compress hardware margins on portable cart configurations.
Strategic Opportunities
- Rural Health Clinic Penetration:Federally Qualified Health Centers in Montana, Alaska, and New Mexico remain underserved by specialist cart deployments despite CMS reimbursement expansion.
- AI-Assisted Triage Convergence:Integration of large language models with real-time vital sign streams is creating new subscription revenue layers for predictive deterioration alerts.
- Defense Health System Modernization:Military treatment facilities and VA hospitals are consolidating vendor relationships around single-source telehealth infrastructure contracts.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Hospitals lack sufficient IT-clinical hybrid staff to maintain cart fleets, forcing vendors to absorb remote monitoring and break-fix service costs.
- EHR Integration Complexity:Epic, Cerner, and Meditech system fragmentation requires custom API development for each health network deployment, extending implementation cycles.
- Cybersecurity Certification Burden:HIPAA security rule compliance plus FDA cybersecurity guidance demands continuous penetration testing and patch management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telemedicine Cart Market |
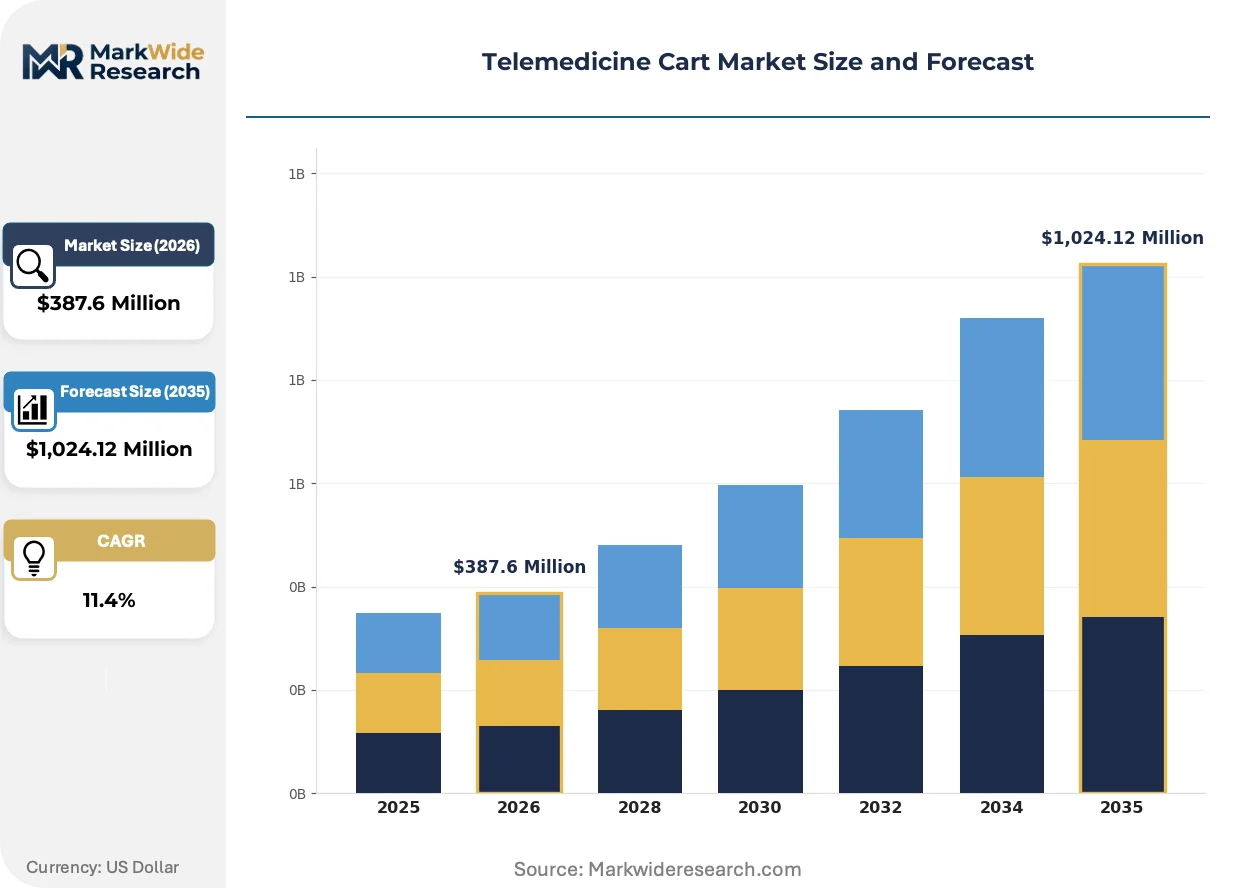
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Carts, Wall-Mounted Systems, Stationary Carts, Hybrid Solutions Technology: Telepresence Systems, Video Conferencing, Remote Monitoring, Telehealth Platforms End User: Hospitals, Clinics, Homecare Providers, Rehabilitation Centers Application: Emergency Care, Routine Check-ups, Specialist Consultations, Mental Health |
| Companies Covered | AFC Industries, AMD Global Telemedicine, American Well, Ergotron, First Healthcare Products, GlobalMed, Poly, Parsys, Capsa Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telemedicine Cart Market Emerging Trajectories
Real-time diagnostic data streaming is compressing the gap between remote consultation and bedside decision-making, with three structural shifts now defining vendor R&D priorities and hospital procurement specifications.
Edge-computing inference engines embedded directly into cart chassis are rewriting how clinical AI gets deployed. These localized processors run computer vision algorithms for wound assessment and dermatoscopic analysis without cloud latency. Academic medical centers in Boston and Houston are piloting these configurations for emergency department triage. The architecture is compressing specialist response times from hours to minutes for time-critical diagnoses.
FDA guidance on predetermined change control plans for machine learning-enabled devices is tightening documentation requirements for cart-integrated software updates. Manufacturers must now submit algorithm modification protocols before deployment rather than post-hoc reporting. This regulatory friction most affects vendors targeting multi-site health system rollouts where centralized software management is essential. European suppliers face parallel demands under EU MDR Annex XIV clinical evaluation requirements.
Subscription-based fleet management is displacing capital purchase models for hospital networks with over 500 licensed beds. HCA Healthcare and CommonSpirit Health are negotiating per-cart monthly fees bundling hardware, software, cybersecurity monitoring, and preventive maintenance. This shift concentrates vendor working capital requirements and rewards established players with service infrastructure scale.
Telemedicine Cart Market Segmentation
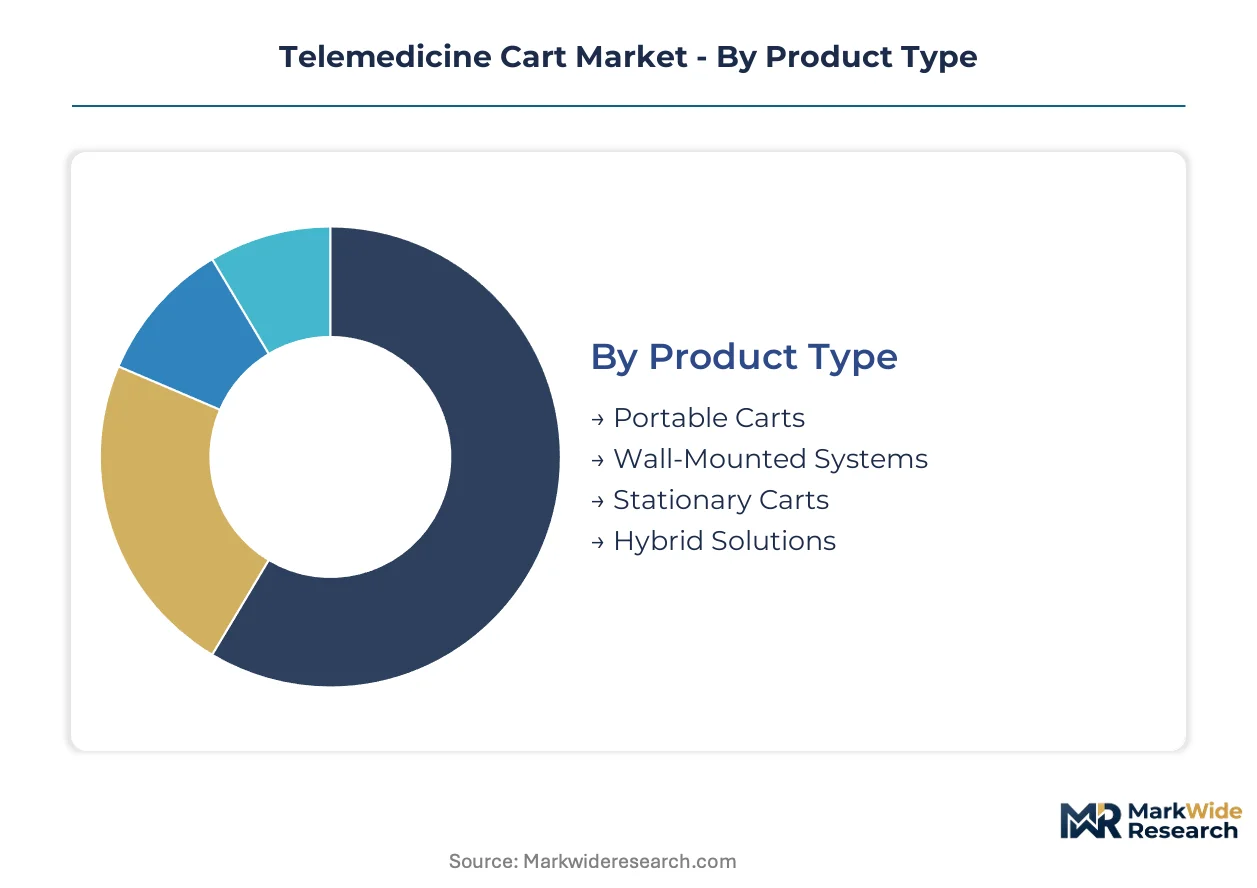
Telemedicine cart configurations diverge sharply between high-mobility deployments and fixed-installation environments, with each segment carrying distinct margin profiles, certification burdens, and replacement cycles that reshape vendor go-to-market strategies.
Product Type:
Portable carts dominate unit volumes while wall-mounted systems capture premium pricing through permanent infrastructure integration.
- Portable Carts:Battery-powered mobile units with motorized height adjustment and hot-swappable power systems enable ward-to-ward rotation across hospital networks. Demand concentrates in American Southeast health systems consolidating rural outreach programs under state telehealth parity mandates. The IEC 60601-1 certification pathway for patient-vicinity electrical safety elevates compliance costs for new entrants.
- Wall-Mounted Systems:Fixed installations integrate large-format surgical displays and permanent network backbone connections into specialty suites and operating theaters. Orthopedic and dermatology departments in academic medical centers drive procurement, prioritizing immersive specialist interaction over mobility flexibility. Installation complexity limits vendor competition and sustains margin premiums.
- Stationary Carts:Non-motorized floor-standing units serve semi-permanent clinic deployments where power infrastructure supports tethered operation.
- Hybrid Solutions:Convertible architectures allow wall-dock mounting with rapid detachment for emergency transport scenarios.
Today's leader: Portable Carts. Tomorrow's challenger: Wall-Mounted Systems.
Technology:
Telepresence systems command the steepest expansion trajectory as hospitals prioritize spatial audio and directional camera control for specialist-patient rapport.
- Telepresence Systems:Immersive platforms with 360-degree camera arrays, beam-forming microphones, and eye-tracking displays replicate physical presence for remote surgical consultation and emergency triage. Academic medical centers in Boston and Houston pilot edge-computing inference engines embedded directly into chassis for wound assessment without cloud latency.
- Video Conferencing:Standard-definition two-way communication modules satisfy basic consultation requirements in cost-constrained Federally Qualified Health Centers. Montana and Alaska rural clinics drive residual demand where bandwidth limitations preclude high-resolution streaming.
- Remote Monitoring:Continuous vital sign transmission with FDA 510(k)-cleared peripherals integrates blood pressure, pulse oximetry, and ECG into cart-mounted workflows.
- Telehealth Platforms:Software-layer solutions bundling scheduling, documentation, and reimbursement coding reduce EHR integration complexity for multi-site deployments.
Telepresence systems are gaining share fastest. Video Conferencing retains the largest installed base.
End User:
Hospital procurement concentrates capital budgets while homecare providers represent the emerging volume frontier.
- Hospitals:Integrated delivery networks with 500-plus licensed beds negotiate subscription-based fleet management bundling hardware, software, cybersecurity monitoring, and preventive maintenance. HCA Healthcare and CommonSpirit Health consolidate vendor relationships around single-source infrastructure contracts.
- Clinics:Federally Qualified Health Centers in New Mexico and rural Texas expand deployment despite biomedical engineering talent scarcity forcing vendors to absorb remote monitoring costs.
- Homecare Providers:CMS reimbursement expansion for remote patient monitoring enables post-acute and hospice organizations to justify mobile diagnostic infrastructure.
- Rehabilitation Centers:Skilled nursing facilities integrate carts for specialist access to stroke recovery and wound care protocols.
Hospitals anchor current revenue. Homecare Providers are expanding most quickly.
Application:
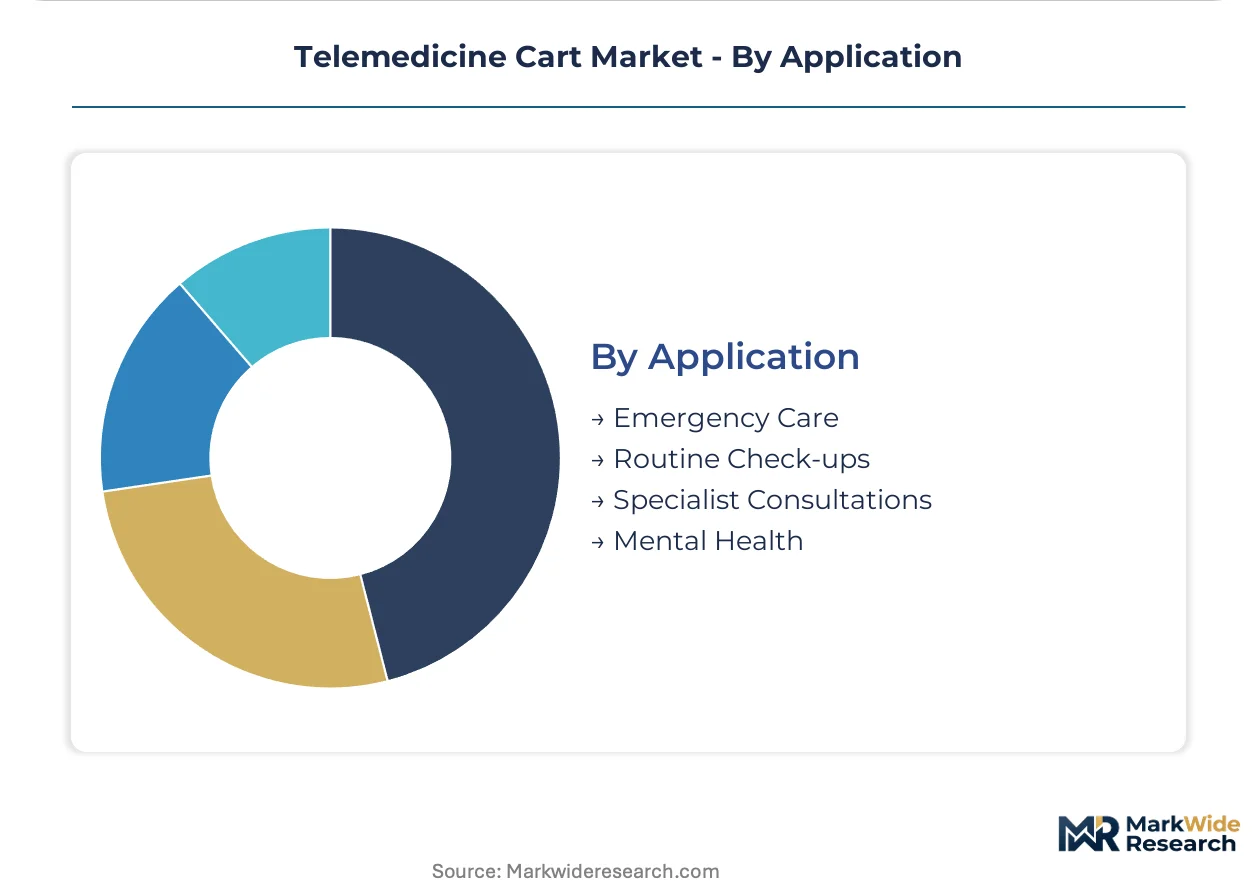
Emergency care applications justify premium configurations through time-critical diagnostic value, while mental health drives standardization at scale.
- Emergency Care:Edge-computing inference engines compress specialist response times from hours to minutes for trauma triage and stroke assessment. Academic medical centers prioritize these configurations for time-critical diagnosis workflows.
- Routine Check-ups:Primary care networks deploy standardized cart fleets across family medicine and internal medicine departments where diagnostic complexity remains moderate.
- Specialist Consultations:Cardiology, dermatology, and neurology workflows demand rapid peripheral swaps enabled by USB-C and wireless diagnostic attachments without hardware replacement.
- Mental Health:Behavioral health units prioritize audio clarity and privacy-compliant camera positioning over diagnostic peripheral integration.
Emergency Care commands the highest unit economics. Mental Health is scaling fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys telemedicine carts at triple the per-capita rate of Germany, yet both markets now face converging regulatory pressure around electrical safety harmonization and cybersecurity certification burdens that reshape procurement timelines.
United States
Hospital network consolidation across the American Southeast and state-level telehealth parity mandates in Florida and Georgia accelerate capital procurement cycles for mobile diagnostic infrastructure. FDA guidance on software-as-medical-device classifications and HIPAA security rule requirements elevate compliance costs while reinforcing incumbent technical positions. The Texas Medical Center in Houston and Massachusetts General Brigham in Boston pilot edge-computing inference engines embedded directly into cart chassis for emergency department triage.
Germany
University hospital networks in Baden-Württemberg and Bavaria prioritize IEC 60601-1 electrical safety certification alignment across EU MDR and FDA pathways to reduce dual-certification costs for patient-vicinity equipment. The EU MDR Annex XIV clinical evaluation requirements for machine learning-enabled devices tighten documentation protocols for cart-integrated software updates. The Rhine-Main cluster around Frankfurt and the Munich metropolitan area concentrate specialist cart deployments for orthopedic and dermatology workflows.
United Kingdom
NHS England's procurement frameworks for remote patient monitoring infrastructure expand deployment across integrated care systems in Greater London and the Midlands. MHRA recognition of FDA-510(k) cleared devices accelerates market access for US-origin cart manufacturers while maintaining CE marking requirements under retained EU law. The Cambridge-Oxford-London golden triangle anchors pilot programs for AI-assisted triage convergence with real-time vital sign streams.
Japan
Super-aging prefectures in rural Honshu and Kyushu deploy telemedicine carts to extend specialist access to isolated communities, with METI funding programs supporting digital health infrastructure modernization. PMDA consultation pathways for software medical devices create parallel certification demands distinct from FDA and EU MDR frameworks. The Osaka-Kobe medical device cluster and Tokyo's Shinagawa biotech corridor concentrate vendor technical support capabilities.
Australia
TGA approval pathways for telehealth devices align with FDA breakthrough device designation criteria, enabling rapid market entry for cart-integrated peripherals cleared under US regulatory frameworks. Rural health networks in Queensland and Western Australia expand deployment to address specialist workforce shortages across remote indigenous communities. The Melbourne biomedical precinct and Sydney's Macquarie Park innovation district host validation trials for subscription-based fleet management models.
Telemedicine Cart Market Vendor Landscape
Top-tier vendors anchor integrated software-hardware bundles for federal and military health systems, while mid-tier specialists compete on ergonomic engineering standards and modular cart architectures. The market structure concentrates around three strategic archetypes: platform-integrated systems vendors, ergonomic hardware specialists, and modular configuration providers. Dominant competitive moves include strategic partnerships with EHR platform vendors and geographic expansion through subscription-based fleet management contracts.
Among US-based platform-integrated vendors, AMD Global Telemedicine and GlobalMed exemplify the federal-health-system consolidation archetype, while Ergotron and Capsa Healthcare occupy positions within the ergonomic-modular specialization tier. Poly represents the communications-peripheral convergence archetype, leveraging enterprise video infrastructure expertise into clinical-grade deployments. These four companies collectively illustrate how vendor positioning stratifies across bundled service provision, hardware engineering differentiation, and modular adaptability for rapid clinical workflow reconfiguration.
| Leading Market Players |
|---|
| AFC Industries |
| AMD Global Telemedicine |
| American Well |
| Ergotron |
| First Healthcare Products |
| GlobalMed |
| Poly |
| Parsys |
| Capsa Healthcare |
| Others |
Supply Flow & Price Mechanics
Edge-computing inference engine miniaturization is collapsing per-unit hardware costs while concentrating procurement leverage among hospital networks with subscription-scale fleet requirements. This technological shift simultaneously compresses manufacturing margins for standalone cart vendors and elevates pricing power for integrated platform providers bundling cybersecurity monitoring and preventive maintenance.
Pricing Analysis
Capacity additions in Vietnam and Mexico are reshaping price floors for non-certified cart chassis and commodity power distribution components. Pricing stratifies across FDA-cleared, CE-marked, and uncertified tiers, with IEC 60601-1 electrical safety certification commanding substantial premiums over basic mobile workstation configurations. Cost compression in the standard tier is intensifying because Taiwanese foundry concentration for medical-grade image processing modules limits second-source alternatives. Federally Qualified Health Centers in rural Montana and Alaska exhibit highest price sensitivity, while academic medical centers in Boston and Houston prioritize diagnostic throughput over unit cost.
Supply Chain Analysis
FDA 510(k) and EU MDR Annex XIV qualification pathways gate component sourcing for patient-vicinity electrical equipment, filtering suppliers to those with documented clinical evaluation protocols. Medical-grade camera modules and edge-computing processors draw from Taiwan, South Korea, and Japan, while battery assemblies and motorized height-adjustment mechanisms rest on Chinese and Vietnamese manufacturing. Single-source vulnerability concentrates in Taiwan-based foundries fabricating high-resolution diagnostic imaging chips. Distribution runs through regional medical device distributors with GPO contracting relationships and direct hospital procurement channels for subscription-based fleet deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemedicine cart procurement operates as a geographic-arbitrage play between American Southeast states with telehealth parity mandates and underserved rural markets in Montana and Alaska where CMS reimbursement expansion lags regulatory adoption by eighteen to twenty-four months.
For Market Incumbents: Anticipate margin compression from software-defined diagnostics displacing hardware-centric revenue models by consolidating subscription-based fleet management contracts with hospital networks exceeding five hundred licensed beds. Defensive positioning requires backward integration into edge-computing inference engine design and captive cybersecurity monitoring infrastructure to offset service cost absorption forced by biomedical engineering talent scarcity. For New Entrants and Emerging Players: Federally Qualified Health Centers in New Mexico and rural Texas represent the most penetrable buyer archetype, with procurement cycles accelerating under CMS reimbursement expansion yet vendor competition remaining sparse relative to saturated metropolitan hospital networks. White-space entry demands modular cart architectures enabling rapid peripheral swaps across cardiology, dermatology, and emergency department workflows without hardware replacement. For Investors and Strategic Acquirers: Valuations sit cheapest among ergonomic hardware specialists without integrated software platforms, as recurring revenue multiples compress pure-play equipment manufacturers relative to clinical workflow service providers. Acquisition targets with established IEC 60601-1 certification pathways and existing GPO distributor relationships offer superior long-term viability. Signal to monitor: FDA predetermined change control plan submissions for machine learning-enabled cart-integrated devices, which will indicate which vendors have secured scalable regulatory infrastructure for multi-site health system rollouts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for AI-Integrated Peripherals | Clears algorithm-driven diagnostic tools for emergency department triage workflows in academic medical centers. |
| CE Marking Pathway Harmonization | Reduces dual-certification costs for patient-vicinity electrical equipment serving EU MDR and FDA jurisdictions simultaneously. |
| Hospital System Partnership Consolidation | Locks in subscription-based fleet management contracts with HCA Healthcare and CommonSpirit Health procurement frameworks. |
| Software Companion Development | Creates recurring platform revenue layers bundling cybersecurity monitoring and preventive maintenance beyond hardware margins. |
| Reimbursement Strategy Alignment | Positions cart configurations for CMS remote patient monitoring codes determining hospital operational justification. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and telehealth platform integration specialists with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR technical documentation. Bottom-up unit deployment estimates triangulated against top-down health system capital expenditure surveys across the analysis window.
Comparable-period anchoring tied projection models to historical deployment trajectories in telehealth parity mandate states versus lagging rural markets. Segmentation dimensions modeled include product mobility configuration, technology tier, end-user facility type, clinical application, and regional regulatory cluster. CAGRs derived from installed base growth rates adjusted for replacement cycle compression and subscription model transition effects. Forecast inputs incorporated semiconductor supply constraints, lithium battery pricing volatility, and evolving FDA software-as-medical-device pathway timelines.
Underlying measurement precision varies by segment; portable cart volumes in American Southeast hospital networks carry tighter precision than wall-mounted system deployments in specialty suites where installation complexity obscures unit economics. Forecasts reflect documented assumptions regarding telehealth parity law expansion, reimbursement code stability, and certification pathway harmonization. Deviation in FDA predetermined change control plan enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Global Telehealth Market
Telemedicine
Global Telemedicine Market
Telemedicine
Global Telepsychiatry Market
Telemedicine
AI in Telemedicine Market
Telemedicine
India Telemedicine Market
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
Europe Telemedicine Market
Telemedicine
Telemedicine Diagnostic Services Market
Telemedicine
Telepathology Service Market
Telemedicine
Telehealth Services Market
Telemedicine
Tele-ICU Services Market
Telemedicine
Global Online Therapy Services Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
Video Telemedicine Market
Telemedicine
Real-Time E-Healthcare System Market
Telemedicine
Europe Telehealth Service Market