
 Europe Telemedicine Market | 2026-2036
Europe Telemedicine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Telemedicine Market Analysis
Buyer concentration across Europe's telemedicine sector is rebalancing from fragmented individual practices toward consolidated hospital networks and regional health alliances. Siemens Healthineers leverages its imaging-integrated platforms to anchor large-scale telemedicine deployments in German university hospitals. Doctolib competes through dense physician network effects and scheduling infrastructure that dominates outpatient virtual consultation flows in France and expanding Southern European markets.
Telemedicine encompasses the remote delivery of clinical services through synchronous video, asynchronous store-and-forward imaging, and continuous biometric streaming from patient to provider, typically operating over encrypted IP networks with latency below 150 milliseconds for real-time diagnostic integrity. Its primary commercial purpose is extending specialist clinical capacity to underserved populations while reducing avoidable emergency utilization and travel burden. Real-time consultation occupies the largest revenue pool today, yet AI Diagnostics within the technology dimension is expanding fastest as regulators in France and Germany approve algorithm-assisted triage and radiology screening protocols. Mobile Health Apps face margin compression from platform fee structures, while Cloud Platforms concentrate infrastructure investment as national health systems mandate interoperable data architectures.
The EU's Medical Device Regulation and GDPR establish stringent clinical evidence and data residency requirements that shape product development roadmaps and market access timelines for platform vendors. France's ANSM and Germany's BfArM enforce divergent pre-market assessment pathways for software-as-a-medical-device, creating compliance complexity for cross-border operators. EMA's emerging digital health guidance and the European Health Data Space legislation will further reshape competitive boundaries. Stakeholders must monitor whether interoperability mandates consolidate vendor selection around a handful of certified platforms or preserve fragmentation across national procurement frameworks.
Market Dynamics
Cross-border interoperability mandates under the European Health Data Space are forcing platform vendors to rebuild data architectures around shared APIs, compressing procurement timelines for hospital networks that must achieve compliance before enforcement deadlines.
Growth Catalysts
- Rural Hospital Network Expansion:Central and Eastern European health alliances are consolidating telemedicine procurement across regional catchment areas, creating volume aggregation that justifies enterprise platform investments.
- EU AI Act Risk-Based Classification:Algorithm-assisted triage tools gain accelerated deployment pathways under harmonized conformity assessment procedures, reducing regulatory fragmentation for software-as-a-medical-device vendors.
- GDPR-Certified Cloud Infrastructure:National health systems in Germany and France are mandating data residency on sovereign cloud platforms, generating dedicated infrastructure buildouts by certified providers.
Market Restraints
- Input Cost Volatility in Edge Hardware:Biometric sensors and dedicated telehealth endpoints face component scarcity from concentrated Asian semiconductor foundry capacity, inflating device procurement budgets for hospital networks.
- Divergent National Assessment Pathways:France's ANSM and Germany's BfArM maintain non-harmonized pre-market requirements for diagnostic algorithms, forcing vendors to duplicate clinical evidence generation for cross-border market access.
- Technical Latency Constraints:Real-time surgical consultation and emergency triage demand sub-150-millisecond network performance that rural broadband infrastructure cannot consistently deliver, limiting service quality guarantees.
Strategic Opportunities
- Polish and Romanian Underserved Territories:Peripheral regions with specialist physician density below EU averages present whitespace for asynchronous store-and-forward imaging networks that bypass synchronous consultation bottlenecks.
- Remote Patient Monitoring Integration:Continuous biometric streaming from implantable cardiac devices is converging with telemedicine platforms, creating subscription revenue pools beyond episodic consultation fees.
- EMA Digital Health Guidance Alignment:Emerging centralized qualification pathways for digital therapeutics will reduce national regulatory duplication, enabling scaled deployment across multiple member states from single approval bases.
Industry Challenges
- Interoperability Engineering Talent Scarcity:Health information exchange implementation requires specialized expertise in HL7 FHIR standards and IHE profiles that European labor markets currently undersupply, extending project timelines.
- Legacy EHR Integration Complexity:Hospital networks operate heterogeneous electronic health record systems that resist standardized API connectivity, forcing costly middleware development for each deployment.
- MDR Clinical Evidence Burden:Software-as-a-medical-device classification under the EU Medical Device Regulation demands prospective clinical studies that extend time-to-revenue for algorithm-based diagnostic tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Telemedicine Market |
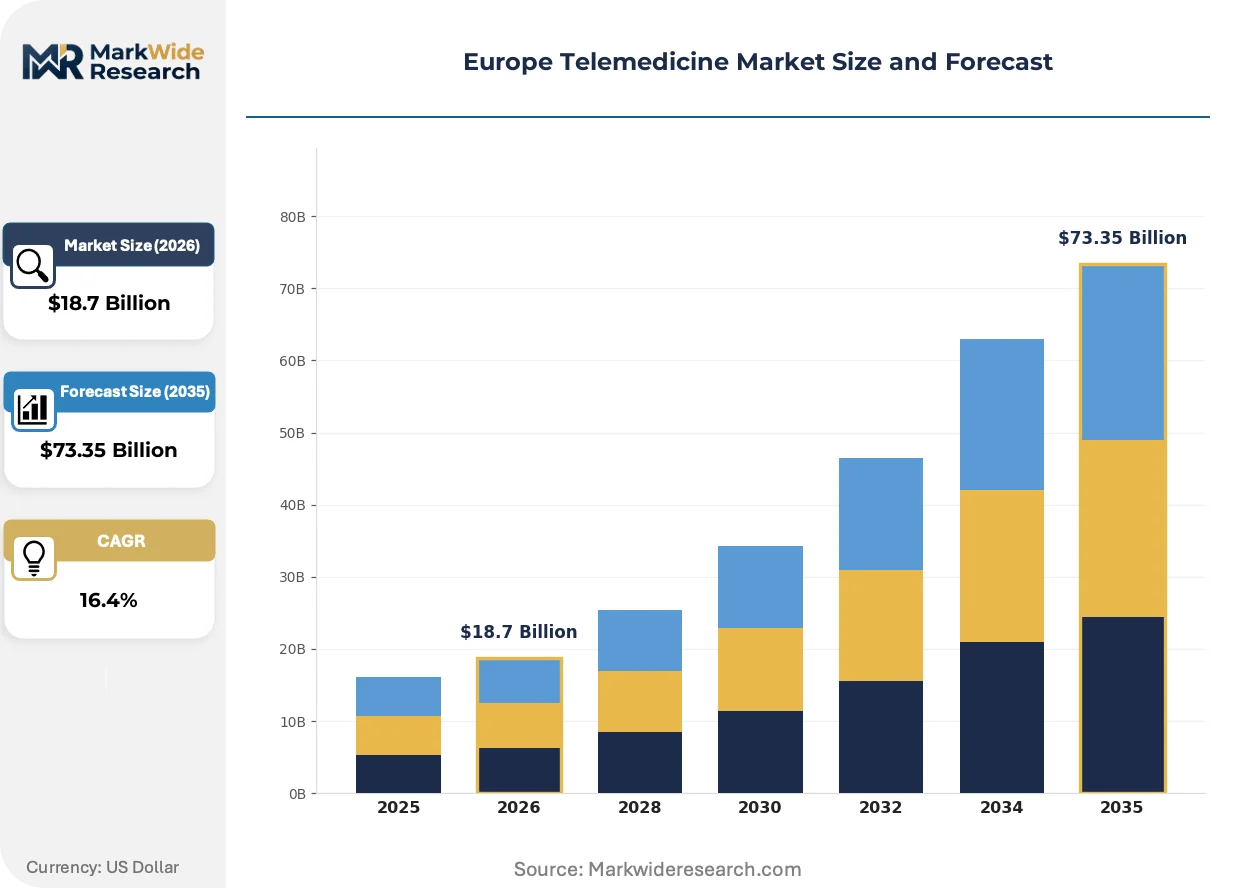
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Real-time Consultation, Remote Monitoring, Mobile Health Apps, Teletherapy Technology: Video Conferencing, AI Diagnostics, Wearable Devices, Cloud Platforms Delivery Mode: Web-based Services, Phone Consultations, Mobile Applications, Hybrid Solutions End User: Patients, Healthcare Providers, Insurance Companies, Corporate Wellness Programs |
| Companies Covered | Siemens Healthineers, Doctolib, Medtronic, DocPlanner, Kry, Teladoc Health, GE Healthcare, AMD Global Telemedicine, Koninklijke Philips, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Telemedicine Market Emerging Trajectories
Telemedicine platform architecture is pivoting from standalone video consultation tools toward integrated care orchestration systems that embed decision support, scheduling, and reimbursement processing within unified workflows.
Artificial intelligence diagnostic modules are converging with radiology and pathology workflows in German university hospitals, where BfArM-approved algorithms for diabetic retinopathy screening and mammography triage are displacing manual second-read protocols. French cancer centers are deploying similar tools for dermatology referral prioritization. This convergence is compressing the specialist consultation queue and reallocating physician capacity toward complex case management.
The European Health Data Space secondary use provisions are mandating standardized health data formats and cross-border exchange infrastructure by 2030, compelling platform vendors to rebuild data lakes around common European electronic health record exchange formats. Dutch and Finnish health data authorities are piloting implementation frameworks that will shape continental compliance templates. Hospital procurement specifications now embed interoperability certification as a mandatory technical requirement, disqualifying closed-architecture vendors from large-network tenders.
Subscription-based platform licensing is displacing per-consultation transaction models as dominant commercial structure in France and the Netherlands, where regional health alliances negotiate multi-year enterprise agreements covering entire physician networks. This shift transfers utilization risk from health systems to platform vendors and locks in switching costs through embedded workflow integration. German integrated care contracts are beginning to mirror this structure, though ambulatory physician associations resist volume commitments that cap fee-for-service revenue.
Europe Telemedicine Market Segmentation
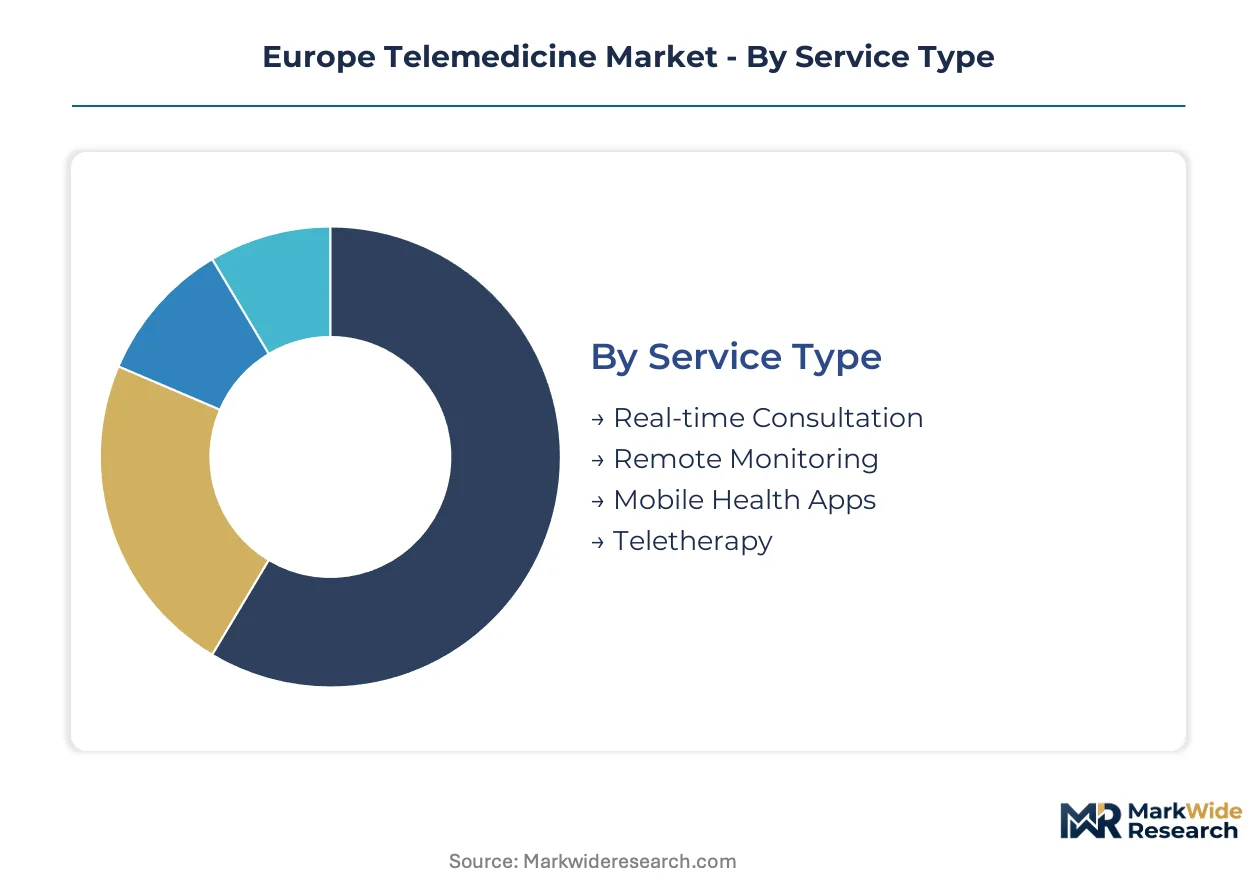
Telemedicine market segmentation reveals how procurement concentration and regulatory mandates reshape vendor selection criteria across European health systems. Distinct technology and service configurations align with divergent national reimbursement frameworks and interoperability requirements.
Service Type:
Supply concentration among regional hospital networks favors platforms that bundle multiple service modalities under enterprise licensing structures.
- Real-time Consultation:Synchronous video encounters between patients and clinicians operate over encrypted networks with sub-150-millisecond latency requirements. German university hospitals and French regional health alliances are consolidating procurement around integrated scheduling and billing workflows that displace standalone video tools.
- Remote Monitoring:Continuous biometric streaming from implantable cardiac devices and chronic disease sensors enables proactive intervention before acute episodes. Dutch integrated care networks and Polish rural hospital systems are expanding reimbursement coverage for subscription-based monitoring services.
- Mobile Health Apps:Patient-facing symptom checkers and medication adherence tools face margin pressure from platform fee structures and GDPR compliance costs.
- Teletherapy:Mental health counseling delivered via video encounters attracts reimbursement parity mandates in France and Germany.
Real-time Consultation absorbs the bulk of installed capacity; Remote Monitoring is expanding most quickly.
Technology:
Cost tier differentiation separates infrastructure-heavy deployments from lightweight application layers, with sovereign cloud mandates driving mid-tier investment concentration.
- AI Diagnostics:Algorithm-assisted triage and radiology screening tools approved by BfArM and ANSM are displacing manual second-read protocols in German and French cancer centers. Regulatory harmonization under the EU AI Act is accelerating cross-border deployment pathways for software-as-a-medical-device vendors.
- Cloud Platforms:GDPR-certified sovereign infrastructure hosts patient data lakes and interoperability exchange layers. National health systems in Germany and France mandate data residency on certified platforms, generating dedicated buildouts by compliant providers.
- Video Conferencing:Commoditized point solutions face procurement exclusion as hospital networks demand embedded workflow integration.
- Wearable Devices:Biometric sensors and dedicated telehealth endpoints encounter component scarcity from concentrated Asian semiconductor foundry capacity.
Cloud Platforms command the largest infrastructure investment flows; AI Diagnostics demonstrates the steepest expansion trajectory.
Delivery Mode:
Application context determines channel selection, with acute care favoring synchronous modalities and chronic management shifting toward asynchronous engagement.
- Hybrid Solutions:Blended synchronous and asynchronous pathways adapt to patient acuity and broadband availability. Rural networks across Central and Eastern Europe are piloting store-and-forward imaging combined with scheduled video follow-up to circumvent connectivity constraints.
- Web-based Services:Browser-accessible portals dominate enterprise deployments requiring no patient-side application installation.
- Mobile Applications:Native smartphone tools concentrate in outpatient mental health and chronic disease self-management segments.
- Phone Consultations:Audio-only encounters persist in elderly populations and low-bandwidth territories, though reimbursement frameworks increasingly favor video documentation.
Hybrid Solutions capture the broadest addressable demand; Web-based Services retain dominant share in institutional procurement.
End User:
Customer type segmentation reflects divergent purchasing authority, with consolidated buyers extracting volume discounts and technical compliance concessions from platform vendors.
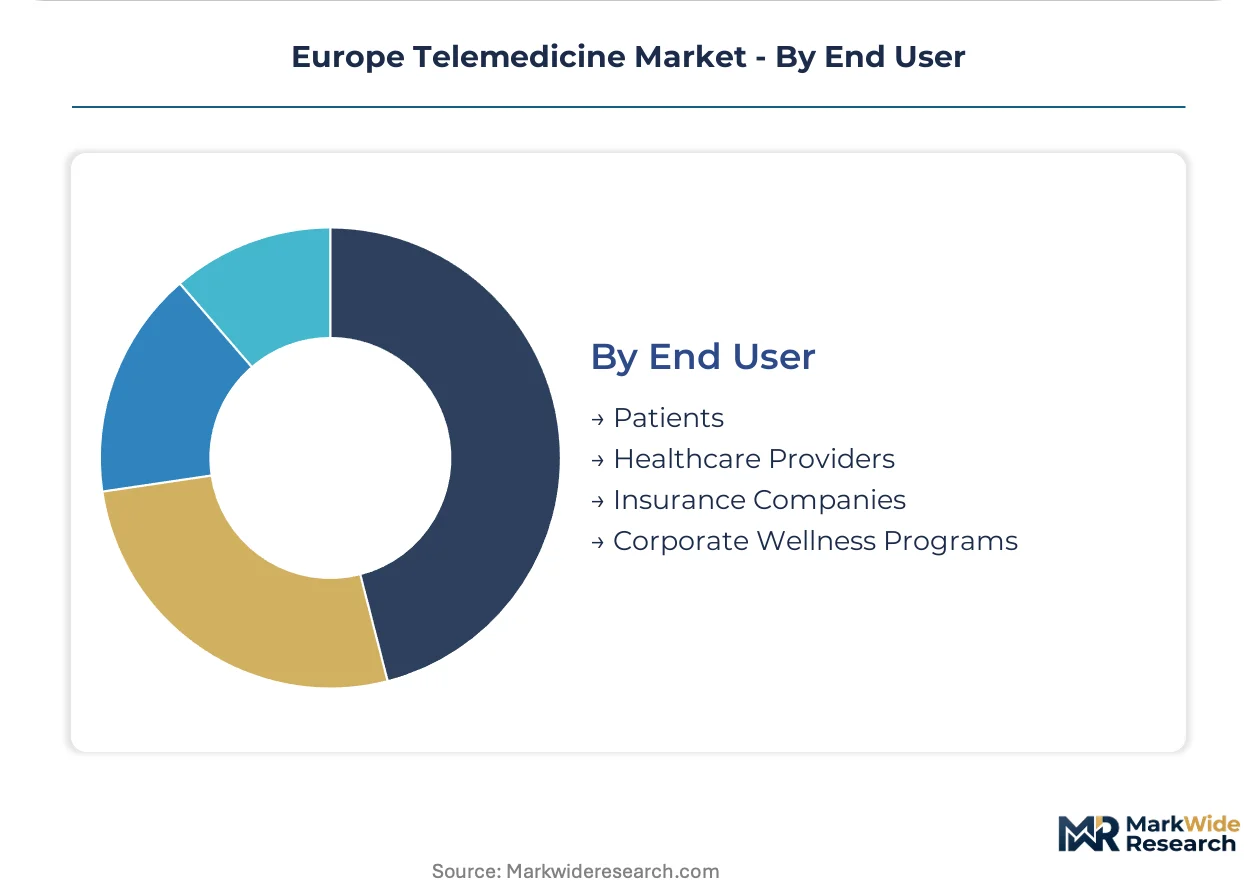
- Healthcare Providers:Hospital networks and physician alliances negotiate multi-year enterprise agreements covering scheduling infrastructure, EHR integration, and reimbursement processing. French regional health alliances and Dutch care cooperatives are consolidating vendor selection around interoperable platforms.
- Insurance Companies:Payers in Germany and the Netherlands are embedding telemedicine access requirements into integrated care contracts, shifting financial risk toward capitated reimbursement models.
- Patients:Direct-to-consumer subscription models face saturation in urban markets and regulatory friction from medical device classification thresholds.
- Corporate Wellness Programs:Employer-sponsored telemedicine benefits expand in Netherlands and Nordic markets, though penetration remains below healthcare provider channels.
Healthcare Providers absorb the bulk of platform deployment; Insurance Companies are gaining share fastest as reimbursement frameworks consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital network procurement concentration across Germany, France, and the Netherlands is redirecting vendor selection toward interoperable enterprise platforms. Central and Eastern European rural alliances are aggregating demand volume that justifies infrastructure investment. Southern European markets lag on reimbursement parity but accelerate on outpatient scheduling digitization.
Germany
Integrated care contracts digitize patient pathways through BfArM-approved AI diagnostics in university hospital networks. The Medical Device Regulation mandates prospective clinical studies for software-as-a-medical-device classification, extending approval timelines for algorithm vendors. Siemens Healthineers anchors large-scale deployments across Bavarian and North Rhine-Westphalian hospital systems with imaging-integrated telemedicine infrastructure.
France
Regional health alliances consolidate vendor selection around scheduling infrastructure and reimbursement processing workflows. ANSM enforces divergent pre-market assessment pathways for diagnostic algorithms, forcing cross-border operators to duplicate clinical evidence generation. Doctolib dominates outpatient virtual consultation flows in Paris and expanding Southern European markets through dense physician network effects.
Netherlands
Care cooperatives negotiate multi-year enterprise agreements covering entire physician networks with subscription-based platform licensing. GDPR-certified sovereign cloud infrastructure hosts patient data lakes under national health system mandates. Dutch health data authorities pilot cross-border exchange frameworks that shape continental compliance templates for the European Health Data Space.
Poland
Peripheral regions with specialist physician density below EU averages drive demand for asynchronous store-and-forward imaging networks. Rural hospital systems expand procurement budgets to bypass synchronous consultation bottlenecks caused by broadband infrastructure gaps. Warsaw-based health alliances aggregate telemedicine procurement across regional catchment areas, creating volume concentration for platform vendors.
Romania
Underserved territories present whitespace for telemedicine platforms that circumvent real-time latency constraints through hybrid delivery models. The country's national pharmaceutical regulator aligns emerging digital health guidance with EMA centralized qualification pathways. Cluj-Napoca and Bucharest hospital networks pilot store-and-forward imaging combined with scheduled video follow-up to address connectivity limitations in rural catchment areas.
Europe Telemedicine Market Vendor Landscape
German producers anchor one tier through imaging-integrated hospital infrastructure; French and Dutch specialists hold another through dense physician network effects and scheduling dominance. The vendor base stratifies across three tiers: enterprise platform vendors with EHR integration capabilities, modular application providers focused on single service modalities, and point-solution video conferencing tools facing procurement exclusion. Strategic moves concentrate on M&A for interoperability engineering talent and strategic partnerships with sovereign cloud providers to satisfy data residency mandates.
Within the enterprise platform tier, Siemens Healthineers and Koninklijke Philips occupy positions anchored by imaging hardware integration and hospital system relationships. Doctolib exemplifies the network-effects archetype through scheduling infrastructure dominance. Teladoc Health represents the cross-border scale-driven model attempting European market penetration. These three company types illustrate how competitive positioning diverges between hardware-anchored incumbents, software-native platform specialists, and international scale operators.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Doctolib |
| Medtronic |
| DocPlanner |
| Kry |
| Teladoc Health |
| GE Healthcare |
| AMD Global Telemedicine |
| Koninklijke Philips |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up telemedicine specialists in France and the Netherlands anchor pricing discipline through multi-year enterprise subscriptions that transfer utilization risk from hospital networks to platform vendors while compressing margins for per-consultation competitors. This ownership pattern concentrates procurement leverage among regional health alliances that extract technical compliance concessions and volume discounts from vendors seeking scale.
Pricing Analysis
Volume concentration among French regional health alliances and Dutch care cooperatives pulls pricing toward subscription-based SaaS tiers, while fragmented ambulatory practices in Germany cling to per-consultation transactional models. Price differentiation rests on EHR integration depth and GDPR-certified sovereign cloud certification, with German university hospitals least sensitive due to bundled imaging infrastructure and mobile health app developers most exposed to platform fee compression. Pricing pressure stems from component scarcity in Asian semiconductor foundries inflating biometric sensor costs for device-dependent offerings.
Supply Chain Analysis
Reverse-logistics flows for refurbished telehealth endpoints and redeployed cardiac monitoring devices remain underdeveloped across European hospital networks, creating stranded asset risk as hardware refresh cycles accelerate. Component manufacturing concentrates in Taiwan, South Korea, and China for biometric sensors and edge processing units, while final platform assembly localizes in Germany and Ireland to satisfy data residency mandates. Supply chains draw from concentrated Asian semiconductor foundry capacity, exposing procurement timelines to single-source vulnerability in advanced node production. Distribution runs through GPO contracts and regional health alliance tenders that mandate interoperability certification as table stakes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native AI diagnostic modules are displacing legacy video-first platforms as hospital procurement specifications embed algorithm-assisted triage requirements. This technology transition rewards vendors with regulatory pre-approval in multiple member states.
For Market Incumbents: To counter modular AI diagnostic entrants with faster BfArM approval pathways, Siemens Healthineers and Koninklijke Philips should deepen EHR integration moats through HL7 FHIR middleware investments and acquire interoperability engineering talent in Dutch and Finnish health data authority pilot zones. Certification investment in EU AI Act conformity assessment procedures anchors switching costs. For New Entrants and Emerging Players: Sovereign cloud providers with GDPR-certified infrastructure offer the fastest channel to German and French hospital procurement committees seeking compliant data residency. Polish and Romanian rural hospital alliances present whitespace for asynchronous store-and-forward imaging networks that bypass synchronous latency constraints. A reimbursement-first go-to-market targeting Dutch integrated care capitation contracts sidesteps fee-for-service resistance. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed mid-cap video conferencing point-solution vendors in Southern Europe facing procurement exclusion as interoperability mandates harden. Long-term viability hinges on platform consolidation around EHR-integrated enterprise architectures rather than standalone scheduling tools. Practitioners should monitor EMA digital health guidance alignment progress as inflection signal for cross-border scalability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | BfArM and ANSM harmonization reduces clinical evidence duplication for algorithm vendors seeking multi-state deployment. |
| Sovereign Cloud Partnership | GDPR-certified infrastructure buildouts in Germany and France satisfy national health system data residency mandates. |
| Interoperability Talent Acquisition | HL7 FHIR expertise scarcity in European labor markets extends project timelines for hospital network implementations. |
| Regional Health Alliance Tender | French and Dutch multi-year enterprise agreements lock in switching costs through embedded workflow integration. |
| Asynchronous Imaging Network Pilot | Polish and Romanian rural deployments circumvent broadband latency constraints via store-and-forward protocols. |
Methodological Framework
Hospital procurement databases, EMA digital health guidance filings, and GPO contract repositories formed the secondary backbone, supplemented by primary interviews with hospital purchasing committees, biomedical engineers, regional health alliance procurement directors, and sovereign cloud infrastructure architects. Bottom-up and top-down triangulation validated platform deployment volumes across German university hospital networks, French regional health alliances, and Dutch care cooperatives.
Bottom-up modeling aggregated installed base by service type and technology tier, while top-down cross-checks applied macro healthcare digitization spending patterns across the analysis window. Segmentation dimensions included service modality, technology layer, delivery mode, and end-user purchasing authority. CAGRs derived from weighted average of historical procurement trajectories and policy-mandated interoperability deadlines. Forecast inputs incorporated EU AI Act implementation timelines and European Health Data Space secondary use provisions.
Caveats apply where BfArM-ANSM regulatory divergence, semiconductor supply shocks, or rural broadband infrastructure gaps could materially shift the outlook. Practitioners should monitor EMA centralized qualification pathway progress and Polish health alliance procurement aggregation rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Global Telehealth Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
Global Virtual Care Market
Telemedicine
United States Telehealth Pre-Natal Services Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
Healthcare IoT Telemedicine Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
US Telehealth Market
Telemedicine
Remote Healthcare Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
Telehealth Software Market
Telemedicine
Telestroke Services Market
Telemedicine
Teledermatology Market