
 Tele-ICU Services Market | 2026-2036
Tele-ICU Services Market Size, Share, and Industry Trends Forecast 2026-2036
Tele-ICU Services Market Analytics
Hospital buyer concentration is expanding as regional health systems consolidate ICU oversight into fewer centralized command centers, reducing vendor fragmentation. Philips leverages its integrated monitoring hardware and software stack to anchor enterprise contracts across multi-hospital networks. GE HealthCare competes through its Edison platform and deep installed base in acute care settings. Advanced ICU Care specializes in physician-led remote coverage models that differentiate its service layer from equipment-centric rivals.
Tele-ICU services encompass continuous remote surveillance of critically ill patients via audiovisual links, physiological data streaming, and real-time clinical decision support from off-site intensivist teams. Systems typically integrate high-definition cameras, predictive algorithms, and cloud infrastructure to enable 24/7 oversight across dispersed hospital locations. Remote Monitoring commands the largest revenue share within service types due to recurring subscription structures and mandated critical care coverage gaps. AI Analytics within technology segments represents the fastest-expanding margin pool as algorithms advance from reactive alerting to predictive deterioration modeling. Hospitals dominate end-user demand, though Healthcare Networks represent the structural growth vector as system-wide standardization replaces site-by-site procurement.
FDA oversight of Software as a Medical Device governs algorithm-based patient monitoring tools, while CMS reimbursement policies directly shape hospital willingness to adopt fee-based remote intensivist models. HIPAA compliance requirements impose encryption and access-control standards that elevate infrastructure costs for platform providers. Stakeholders must monitor evolving state-level telemedicine licensure reciprocity, as intensivist credentialing restrictions remain the primary barrier to scaling across state lines.
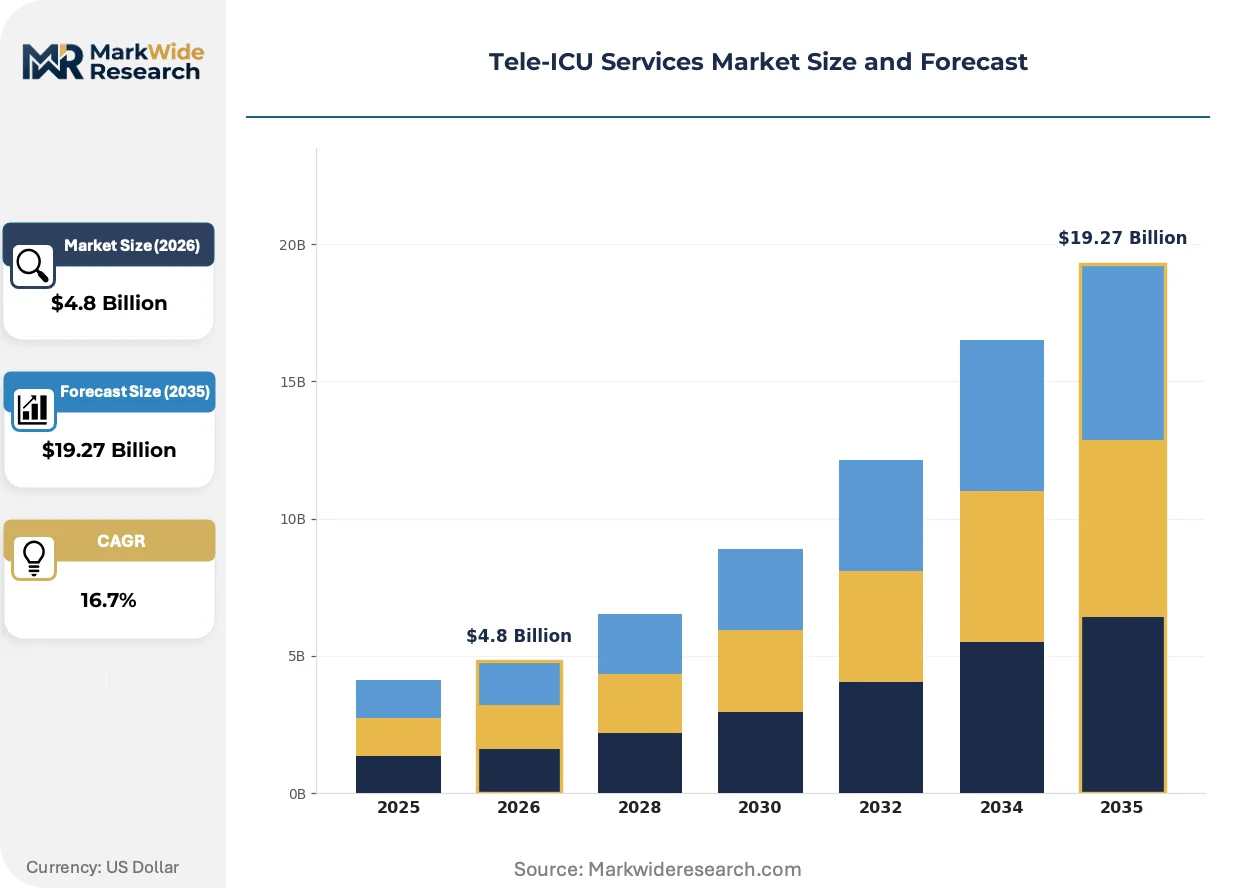
Market Dynamics
Hospital system consolidation is compressing vendor relationships into fewer enterprise contracts, while AI-enabled platforms replace fragmented bedside monitoring with centralized command architectures that demand seamless interoperability across dispersed ICU networks.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare coverage for remote intensivist consultations removes cost barriers for rural hospitals facing physician shortages, accelerating adoption of subscription-based tele-ICU models.
- Cloud Infrastructure Maturation:Healthcare-grade cloud deployments enable real-time physiological streaming with sub-second latency, eliminating the hardware-heavy capital requirements that previously constrained smaller facilities.
- Rural Hospital Closures:Over 130 rural US hospitals have shuttered since 2010, forcing remaining institutions to rely on external critical care expertise to maintain emergency service certifications and patient retention.
Market Restraints
- State Licensure Fragmentation:Intensivist credentialing reciprocity gaps across state lines restrict physician workforce mobility and inflate staffing costs for multi-state health networks.
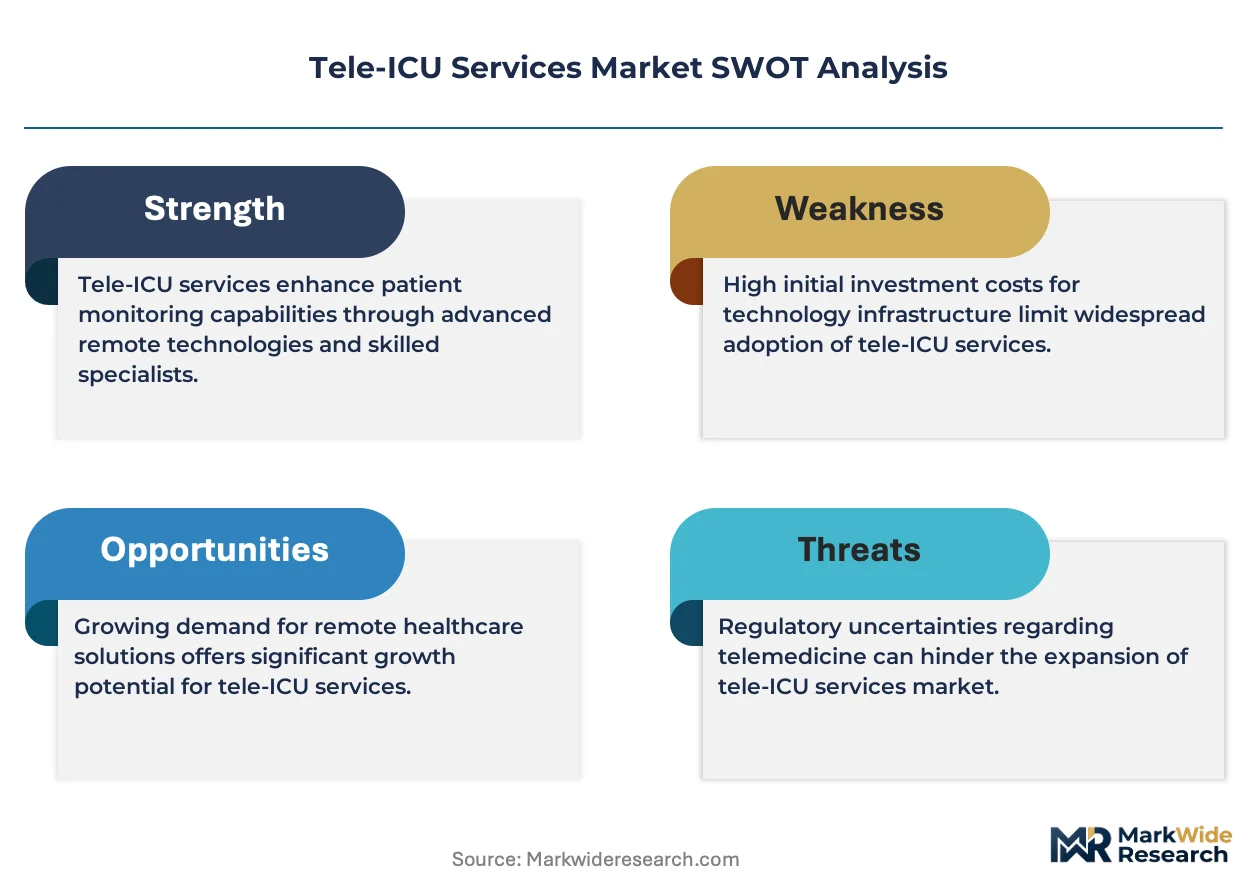
- Cybersecurity Infrastructure Burden:HIPAA-mandated encryption and access-control systems impose recurring compliance expenditures that disproportionately burden mid-sized hospital operators.
- Legacy Hardware Lock-in:Proprietary bedside monitoring protocols from incumbent equipment vendors create data interoperability barriers that delay cloud migration timelines.
Strategic Opportunities
- Post-Acute Care Extension:Skilled nursing facilities and long-term acute care hospitals represent underserved environments where continuous remote monitoring reduces preventable transfers.
- FDA SaMD Pathway Acceleration:Streamlined Software as a Medical Device approvals for predictive deterioration algorithms shorten commercialization timelines for AI-native platform entrants.
- Interoperability Standards Convergence:HL7 FHIR and IEEE 11073 integration requirements are forcing open architecture adoption, enabling modular vendors to displace closed-stack incumbents.
Industry Challenges
- Intensivist Workforce Scarcity:Fellowship-trained critical care physicians number fewer than 12,000 in the United States, constraining remote staffing pool depth for 24/7 coverage models.
- EMR Integration Complexity:Epic, Cerner, and Meditech system variations demand customized API development for each deployment, extending implementation cycles and inflating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tele-ICU Services Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Remote Monitoring, Consulting, Emergency Response, Data Analysis Technology: Telemedicine Platforms, AI Analytics, Wearable Devices, Cloud Solutions End User: Hospitals, Healthcare Networks, Emergency Rooms, Patient Monitoring Centers Application: Critical Care, Post-Surgery Monitoring, Chronic Disease Management, Bedside Assistance |
| Companies Covered | VISICU, Advanced ICU Care, Philips, Banner Health, inTouch Health, iMDsoft, GE HealthCare, Inova, INTeleICU, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tele-ICU Services Market Evolving Landscape
Tele-ICU architectures are pivoting from reactive alerting systems toward predictive intervention platforms, with algorithmic patient risk stratification and automated care protocol deployment emerging as the dominant technical investment vectors.
Machine learning-based early warning systems are consolidating fragmented monitoring data streams into unified deterioration indices that rank patients by acuity probability. Academic medical centers and large integrated delivery networks are deploying these platforms across 50+ bed ICU footprints within 18-month rollout windows. The technology is consolidating previously siloed clinical decision support functions into single-vendor enterprise contracts that bundle hardware, software, and physician staffing.
Europe's Medical Device Regulation (MDR) is imposing clinical evidence requirements on algorithm-based patient monitoring tools that previously operated under lighter notified body oversight. Manufacturers must now submit prospective validation studies for predictive algorithms, extending regulatory timelines by 12-24 months. German and French hospital procurement offices are responding by favoring vendors with established MDR technical documentation over newer market entrants lacking legacy device certifications.
Health system procurement offices are unbundling tele-ICU service contracts into separate technology, physician staffing, and implementation workstreams. Large IDNs now run competitive RFPs for each component rather than accepting turnkey vendor packages, compressing margins on bundled offerings. This pattern is most visible in California and Texas, where multi-hospital systems with 20+ ICU sites command sufficient volume to justify in-house integration management.
Tele-ICU Services Market Segmentation
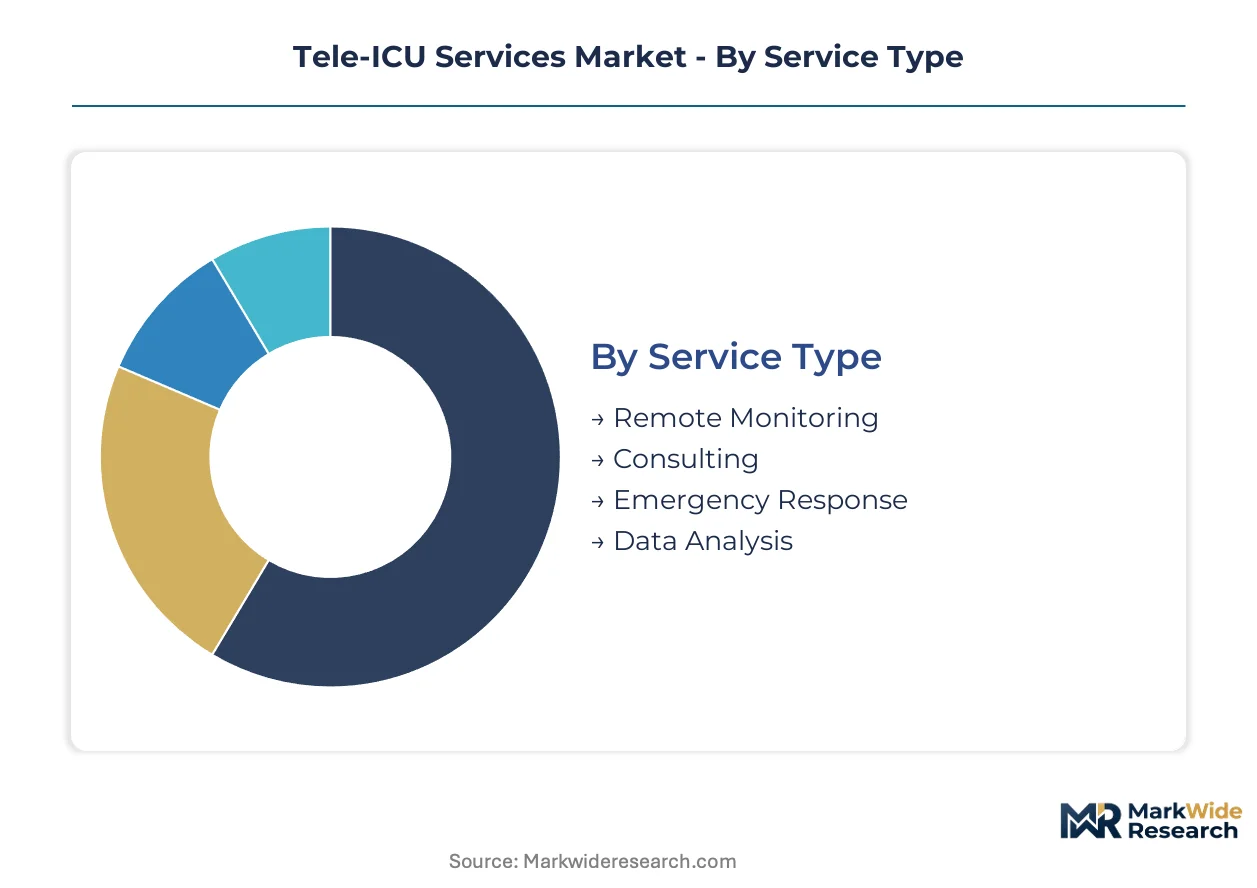
Tele-ICU service segmentation reflects the dual nature of this market: technology infrastructure must align with clinical workflow requirements across dispersed care settings. Procurement patterns vary sharply between capital-intensive hardware deployments and recurring physician staffing subscriptions.
Service Type:
Technology specifications determine contract structure and margin profile across service delivery models.
- Remote Monitoring:Continuous physiological surveillance via high-definition audiovisual links and real-time data streaming from dispersed ICU beds. Demand concentrates in rural US hospitals facing intensivist shortages, where CMS reimbursement for remote coverage removes cost barriers to 24/7 subscription models.
- Consulting:Scheduled specialist consultations for complex case review and care protocol optimization. Academic medical centers in California and Texas deploy these services across multi-hospital networks to standardize critical care practices without full-time staffing commitments.
- Emergency Response:On-demand intensivist activation for acute deterioration events.
- Data Analysis:Retrospective outcome analytics and quality metric reporting for regulatory compliance.
Mature deployment sits with Remote Monitoring. Newer deployment is concentrated in Data Analysis.
Technology:
Cost tier differentiation separates enterprise-grade integrated platforms from modular point solutions.
- AI Analytics:Machine learning algorithms advancing from reactive alerting to predictive deterioration modeling and automated risk stratification. Healthcare networks with 50+ ICU beds prioritize these platforms for enterprise standardization, though FDA Software as a Medical Device oversight extends validation timelines.
- Telemedicine Platforms:Integrated audiovisual and physiological data interfaces enabling real-time remote physician-patient interaction. Hospital systems in Germany and France favor vendors with established MDR technical documentation over newer entrants lacking legacy certifications.
- Wearable Devices:Ambulatory sensors extending monitoring beyond traditional bedside configurations.
- Cloud Solutions:Healthcare-grade infrastructure enabling sub-second latency data transmission without on-premise hardware.
Enterprise procurement gravitates toward Telemedicine Platforms. Cloud Solutions are climbing the fastest as mid-sized facilities bypass capital-intensive deployments.
End User:
Customer type dictates contract scale and integration complexity across the care continuum.
- Hospitals:Individual facility deployments spanning 10-50 ICU beds with customized EMR integration requirements. Epic, Cerner, and Meditech system variations demand tailored API development, extending implementation cycles and inflating professional services costs.
- Healthcare Networks:Multi-site standardization across 20+ ICU locations with centralized command center architectures. Large integrated delivery networks in the United States now unbundle contracts into separate technology, staffing, and implementation workstreams.
- Emergency Rooms:Rapid-response critical care support for undifferentiated acute presentations.
- Patient Monitoring Centers:Dedicated remote oversight facilities consolidating surveillance across external client hospitals.
Volume concentration favors Hospitals. Healthcare Networks are gaining share fastest as system-wide procurement replaces site-by-site adoption.
Application:
Clinical use case determines acuity thresholds and regulatory scrutiny intensity.
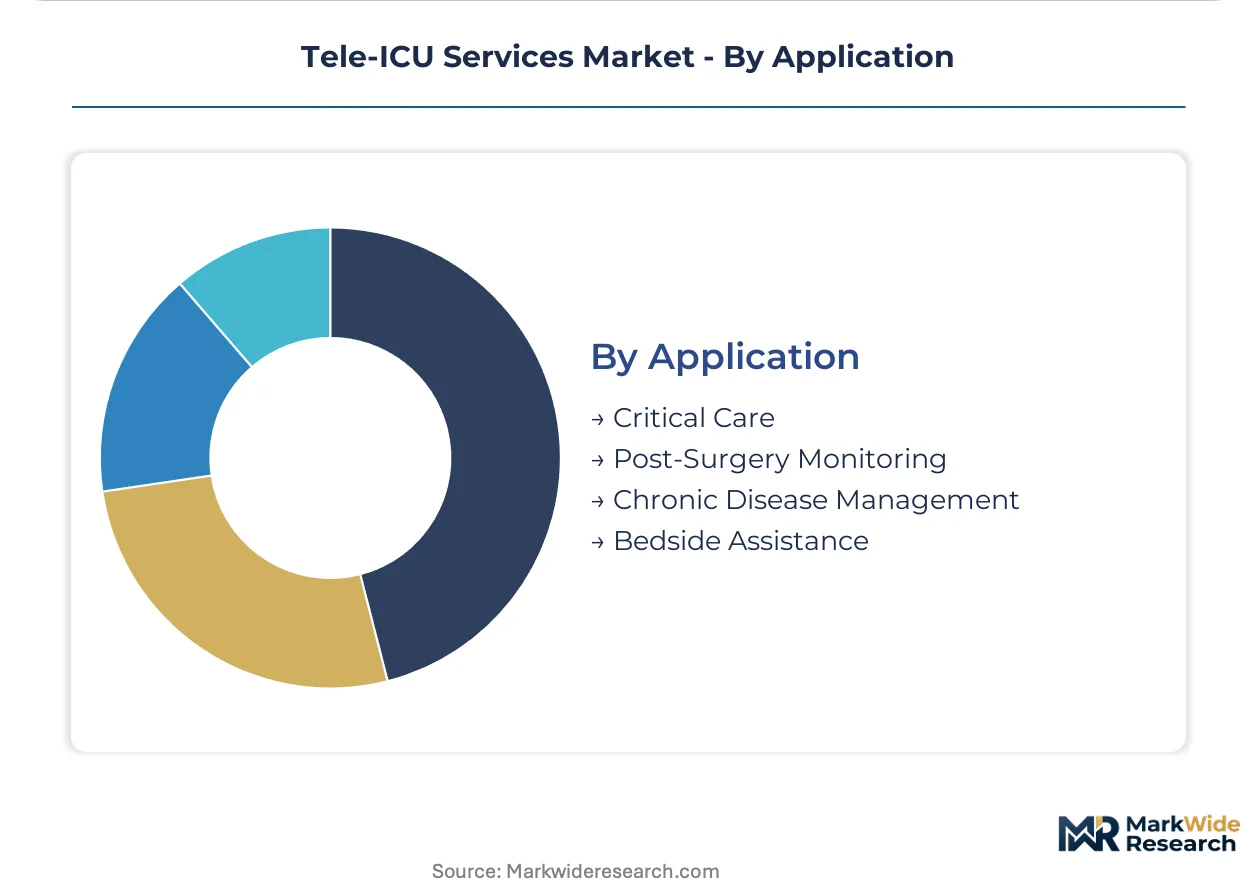
- Critical Care:High-acuity medical and surgical ICU management requiring continuous intensivist oversight and rapid intervention capability. US rural hospitals depend on external support to maintain emergency service certifications and prevent patient diversion.
- Post-Surgery Monitoring:Structured recovery surveillance for high-risk surgical patients transitioning from operative care. Skilled nursing facilities represent an underserved expansion vector where continuous remote oversight reduces preventable transfers to acute settings.
- Chronic Disease Management:Longitudinal oversight for patients with complex comorbidities requiring intermittent specialist input.
- Bedside Assistance:Real-time procedural guidance and decision support for on-site clinical staff.
Established penetration sits with Critical Care. Post-Surgery Monitoring shows the steepest expansion trajectory as health systems extend surveillance into lower-acuity settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital system consolidation and intensivist workforce gaps concentrate tele-ICU demand across five national markets. Regulatory frameworks and reimbursement policies determine adoption velocity in each geography.
United States
Rural hospital closures and critical care physician shortages drive subscription-based remote monitoring adoption. CMS reimbursement policies for telehealth intensivist consultations remove cost barriers for facilities under 50 beds. Texas and California health networks deploy centralized command centers across 20-plus ICU sites.
Germany
Europe's MDR compliance requirements favor established vendors with technical documentation over new algorithm entrants. Bavarian hospital procurement offices prioritize MDR-certified predictive monitoring platforms. Berlin-Brandenburg academic medical centers pilot AI-native deterioration modeling across multi-site networks.
France
Regional health agency consolidation creates enterprise-scale tele-ICU procurement opportunities. ANSM oversight of Software as Medical Device governs algorithm-based patient surveillance tools. Île-de-France hospital clusters unbundle contracts into separate technology and staffing components.
United Kingdom
NHS long-term workforce planning intensifies reliance on remote specialist coverage for district general hospitals. MHRA regulation of AI-enabled medical devices extends validation timelines for predictive algorithms. Greater Manchester and London integrated care systems standardize monitoring platforms across 15-plus hospital trusts.
Canada
Provincial health authority consolidation compresses vendor relationships into fewer enterprise agreements. Health Canada oversight of digital health technologies shapes platform certification requirements. Ontario and Quebec health networks deploy cloud-based surveillance to address intensivist distribution gaps across rural and northern facilities.
Tele-ICU Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-native predictive platforms and modular interoperability solutions. Market structure reflects consolidation around integrated hardware-software-physician bundles alongside fragmentation among specialized technology vendors. Three archetypes dominate: equipment incumbents with installed base leverage, physician-staffing specialists with clinical workflow integration, and AI-native entrants with algorithm-first architectures. Dominant competitive moves include strategic partnerships between technology vendors and health networks, plus portfolio diversification into post-acute care extensions.
Within the integrated equipment tier, Philips and GE HealthCare anchor enterprise contract positions across multi-hospital networks. Advanced ICU Care exemplifies the physician-staffing specialist archetype, differentiating through intensivist-led remote coverage models rather than hardware-centric offerings. These three companies represent contrasting strategic positions: equipment incumbents leverage monitoring hardware lock-in, while staffing specialists capture recurring clinical service revenue independent of capital equipment cycles.
| Leading Market Players |
|---|
| VISICU |
| Advanced ICU Care |
| Philips |
| Banner Health |
| inTouch Health |
| iMDsoft |
| GE HealthCare |
| Inova |
| INTeleICU |
| Others |
Value Network & Pricing Analysis
HIPAA-mandated encryption standards gate qualified supply access and premium-tier pricing power for tele-ICU platform providers, as mid-sized hospital operators face disproportionate compliance cost burdens that compress margins at the standard tier while enterprise networks capture volume discounts.
Pricing Analysis
Volume concentration versus margin capture splits sharply across contract tiers. Enterprise health networks with 20-plus ICU sites command subscription pricing 30-40 percent below standalone hospital rates through unbundled RFP processes. Price differentiation rests on EMR integration complexity and FDA Software as a Medical Device certification tier. Pricing pressure stems from health system procurement offices forcing competitive bidding on each contract component. Rural hospitals under 50 beds exhibit highest price sensitivity due to CMS reimbursement dependency.
Supply Chain Analysis
Single-source vulnerability sits with cloud infrastructure providers concentrated in the United States, as healthcare-grade sub-second latency requirements tether platform architectures to domestic data center networks. Hardware components draw from Taiwan for semiconductor fabrication, China for sensor assemblies, and Germany for precision monitoring equipment. Supply chain risk centers on tariff exposure for Chinese-manufactured wearable sensors and cameras. Distribution runs through direct enterprise sales teams serving health network procurement offices, with professional services margins capturing implementation and EMR integration workstreams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tele-ICU services function as a consolidation play where AI-native platform entrants and intensivist workforce scarcity pressure equipment-centric incumbents toward defensive integration moves.
For Market Incumbents: To counter unbundling pressure from health system procurement offices, anchor enterprise contracts through backward integration into physician staffing pools and deepen EMR interoperability investments across Epic and Cerner system variations. Prioritize MDR technical documentation completion to defend European market position against algorithm-native competitors. For New Entrants and Emerging Players: Enter via post-acute care extension into skilled nursing facilities and long-term acute care hospitals, where continuous remote monitoring demand runs ahead of incumbent coverage. Target California and Texas healthcare networks with modular AI analytics platforms that bypass hardware-heavy capital requirements. Lead with predictive deterioration algorithms seeking FDA Software as a Medical Device pathway acceleration. For Investors and Strategic Acquirers: FDA SaMD approval acceleration for predictive algorithms is the leading indicator that AI-native platform valuations will displace equipment-centric revenue multiples. Position acquisition screening around physician-staffing specialists with intensivist network depth and established CMS reimbursement relationships. Watch state-level licensure reciprocity expansion as the signal for multi-state scaling viability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA SaMD Pathway Investment | Accelerates commercialization timelines for predictive deterioration algorithms entering hospital networks. |
| Physician Staffing Network Acquisition | Captures recurring clinical service revenue independent of capital equipment procurement cycles. |
| EMR Interoperability Certification | Reduces implementation friction across Epic, Cerner, and Meditech system variations. |
| Post-Acute Care Platform Extension | Opens skilled nursing facility demand where preventable transfer reduction drives adoption. |
| Multi-State Licensure Infrastructure | Enables intensivist workforce mobility across state lines for health network consolidation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this tele-ICU services analysis, cross-referenced with primary interviews involving intensivist medical directors, hospital procurement committee members, biomedical engineers, and GPO contracts managers. CMS Medicare reimbursement databases, FDA 510(k) and SaMD submission records, hospital procurement databases, and state-level telemedicine licensure filings provided validation layers. Bottom-up service line modeling and top-down health system spending pattern analysis were triangulated to constrain estimate variance.
Granularity-level modeling operated at the ICU-bed-cluster level across service type, technology tier, and end-user archetype dimensions, with geographic segmentation tracking state-level regulatory variation and rural-urban hospital distribution. CAGRs were derived from subscription revenue run-rates and technology licensing patterns across the projection horizon. Forecast inputs incorporated intensivist workforce pipeline data, CMS telehealth policy trajectories, and cloud infrastructure capex disclosures from healthcare-grade providers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated state licensure reciprocity or MDR regulatory timeline extensions. Forecasts reflect documented assumptions regarding EMR integration cost trajectories and AI algorithm validation evidence requirements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Global Virtual Care Market
Telemedicine
Global Online Therapy Services Market
Telemedicine
Real-Time E-Healthcare System Market
Telemedicine
Next Generation Telehealth Market
Telemedicine
North America and Europe Ehealth Market
Telemedicine
Asia-Pacific Ehealth Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
Europe Telehealth Service Market
Telemedicine
Europe Telemedicine Market
Telemedicine
Telehealth Kiosk Market
Telemedicine
North America Telemedicine Market
Telemedicine
US Virtual Care Market
Telemedicine
India Telehealth Services Market
Telemedicine
Telehealth and Telemedicine Market