
 Global Medical Imaging Workstation Market | 2026-2036
Global Medical Imaging Workstation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Imaging Workstation Market Foresight
Radiologist workforce shortages across North America and Western Europe are redrawing deployment priorities for imaging workstation vendors. Siemens Healthineers leverages its integrated software-hardware ecosystem to sustain premium positioning in cardiology reading rooms. GE Healthcare anchors its competitive stance through deep backward integration into imaging modality source data. Koninklijke Philips differentiates via workflow orchestration tools that consolidate multi-modality reads onto unified displays.
Medical imaging workstations comprise dedicated computing platforms with specialized graphics processing units, high-fidelity grayscale or color displays calibrated to DICOM standards, and diagnostic software for rendering and manipulating anatomical visualizations from CT, MRI, ultrasound, X-ray, and nuclear medicine modalities. These systems enable radiologists and specialists to detect pathology, plan interventions, and communicate findings through structured reporting. Three-dimensional imaging stations command the strongest margin pools as surgical planning and volumetric analysis applications expand, while portable workstations represent the fastest-growing product category fueled by point-of-care ultrasound and emergency department adoption. Among end users, telemedicine providers are scaling workstation investments most aggressively as teleradiology networks extend into underserved geographies.
The FDA governs diagnostic workstation software through 510(k) and De Novo pathways, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for AI-augmented reading tools under CE marking obligations. Japan's PMDA maintains rigorous quality management system audits that shape vendor market access timelines. Stakeholders must monitor how regulatory divergence between the FDA's predetermined change control plans and the EU AI Act's risk classification framework affects product development roadmaps and geographic rollout sequencing.
Market Dynamics
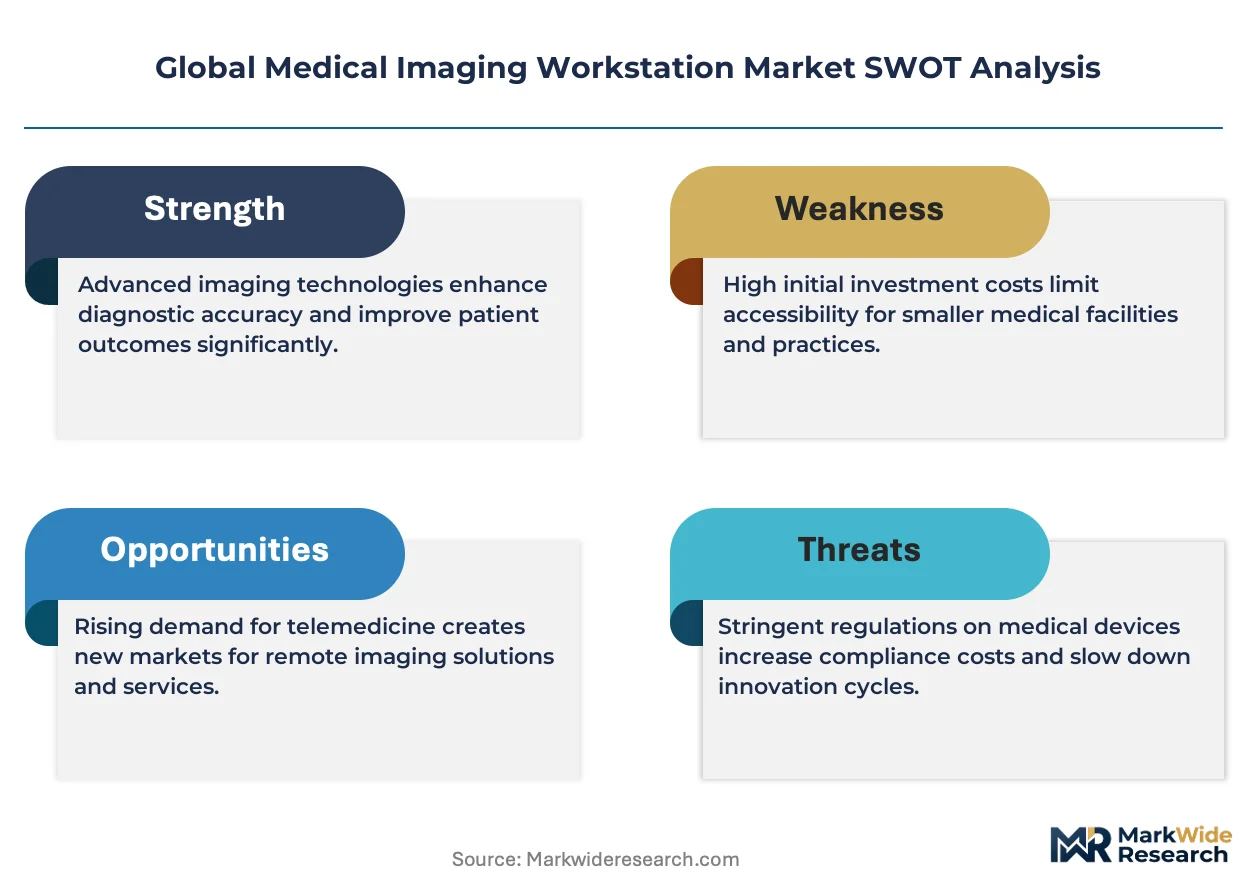
Radiologist workforce shortages across North America and Western Europe are compressing reading turnaround times and forcing hospitals to prioritize workflow automation and AI-assisted diagnostic tools in workstation procurement decisions.
Growth Catalysts
- Software-as-a-Medical-Device Framework:The FDA's SaMD pathway accelerates commercial clearance for AI-enabled diagnostic algorithms, reducing time-to-market for vendors integrating machine learning into reading room workflows.
- Point-of-Care Ultrasound Expansion:Emergency departments and intensive care units are deploying portable workstations at the bedside, creating demand for compact systems with real-time 3D rendering capabilities.
- Germany's Digital Healthcare Act:Reimbursement parity for teleradiology services incentivizes hospital networks to invest in cloud-connected workstations for distributed reading pools.
Market Restraints
- GPU Supply Concentration:Taiwan-based semiconductor fabrication creates vulnerability in graphics processing unit availability for high-performance rendering stations.
- EU MDR Clinical Evidence Burden:The Medical Device Regulation mandates extensive post-market surveillance for AI-augmented workstations, extending certification timelines and elevating compliance costs.
- Freemium Radiology Software:Open-source DICOM viewers and low-cost diagnostic applications threaten margins in the standard workstation tier.
Strategic Opportunities
- India's Diagnostic Imaging Expansion:Tier-2 and Tier-3 cities present white space for teleradiology networks requiring workstation infrastructure to serve underserved populations.
- Hybrid OR Integration:Convergence of surgical navigation systems with diagnostic imaging workstations enables real-time intraoperative guidance for neurosurgical and orthopedic procedures.
- Japan's Regulatory Streamlining:PMDA's accelerated review pathways for software-based medical devices create faster market access for vendors with quality management system maturity.
Industry Challenges
- AI Validation Expertise Gap:Clinical engineering teams lack specialized personnel to validate algorithm performance across diverse patient populations and imaging protocols.
- Legacy PACS Interoperability:Hospital IT departments face complex integration requirements when connecting modern workstations to aging picture archiving systems without native DICOMweb support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Imaging Workstation Market |
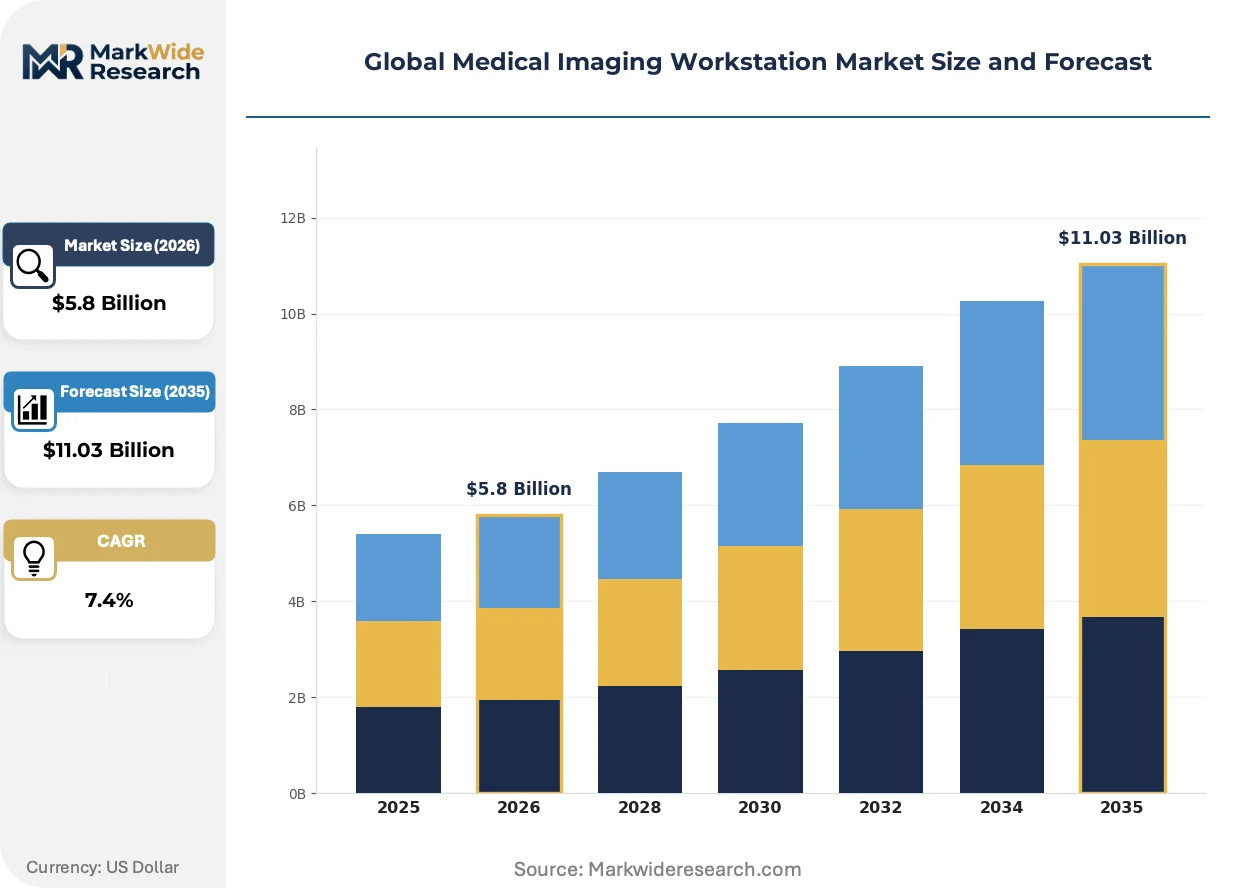
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.03 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Imaging Stations, 3D Imaging Stations, 4D Imaging Stations, Portable Workstations Technology: CT Imaging, MRI Imaging, Ultrasound Imaging, X-ray Imaging, Nuclear Imaging Application: Cardiovascular Analysis, Neurological Assessment, Orthopedic Imaging, Pulmonary Evaluation, Dental Diagnostics End User: Diagnostic Centers, Research Institutes, Specialty Clinics, Telemedicine Providers, Medical Schools |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Carestream Health, Carl Zeiss Meditec, Hologic, Agfa-Gevaert Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Imaging Workstation Market Shifts & Advancements
Cloud-native architecture is displacing on-premise workstation deployment models across hospital networks seeking elastic compute capacity for AI inference workloads.
GPU-accelerated volumetric rendering is displacing CPU-based reconstruction in cardiac imaging suites. Interventional cardiologists at academic medical centers in the United States and Germany are adopting real-time 3D echocardiography workstations that reduce procedural planning time. This displacement is compressing hardware refresh cycles from seven years to four years as imaging modality vendors bundle next-generation rendering engines with equipment sales.
The EU AI Act's risk classification framework is reshaping how workstation software with embedded algorithms gains CE marking. High-risk diagnostic applications now require conformity assessments by notified bodies with specialized AI expertise, elevating documentation burdens for vendors. Cardiology and oncology reading tools face the steepest compliance ramps, with several manufacturers restructuring quality management systems to satisfy the Act's post-market monitoring mandates.
Subscription-based workstation access is gaining traction among mid-sized radiology groups seeking to convert capital expenditure into operational outlays. Independent imaging centers in the United States are replacing perpetual license purchases with per-seat monthly fees that include hardware refreshes and software updates. This shift concentrates negotiating leverage with managed service providers and reduces switching costs for dissatisfied customers.
Global Medical Imaging Workstation Market Segmentation
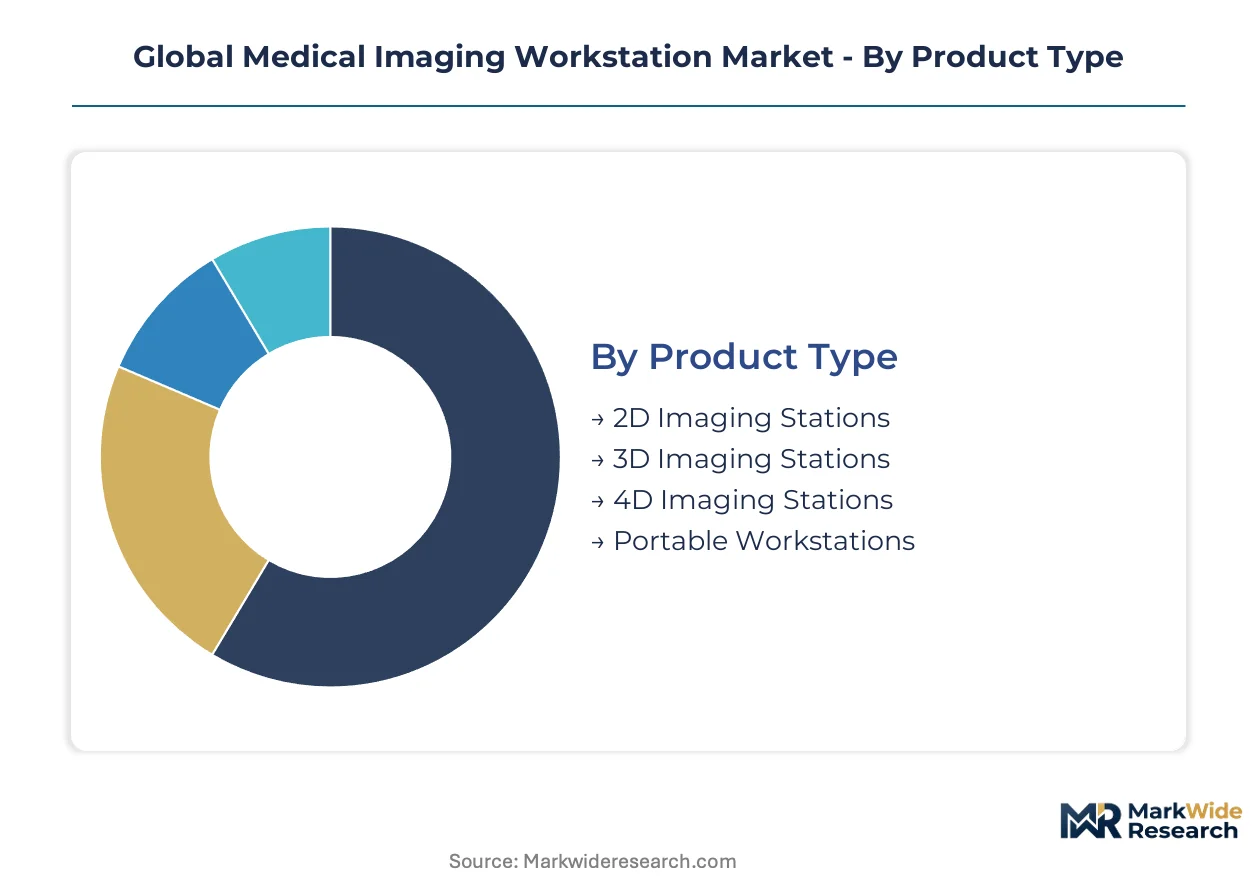
Segmentation in the medical imaging workstation market reveals how procurement priorities diverge across clinical settings and imaging modalities. Understanding these splits helps vendors align hardware specifications, software bundles, and service models with the operational constraints of distinct buyer types.
Product Type:
Domestic hospital networks in the United States and Germany drive demand for fixed-installation stations, while export markets across Southeast Asia and Latin America favor portable configurations for mobile health deployments.
- 3D Imaging Stations:These systems integrate GPU-accelerated volumetric rendering engines with multi-planar reconstruction capabilities for surgical planning. Academic medical centers in the United States and university hospitals in Germany concentrate procurement here, pressured by rising volumes of complex cardiac and orthopedic cases requiring real-time 3D echocardiography and CT angiography.
- Portable Workstations:Compact units with battery-backed power supplies and wireless DICOM transmission enable point-of-care deployment. Emergency departments in Japan and intensive care units across India are scaling purchases fastest, driven by bedside ultrasound expansion and teleradiology outreach into underserved geographies.
- 2D Imaging Stations:Grayscale-calibrated displays with standard DICOM viewing software serve routine radiology reads in cost-constrained settings.
- 4D Imaging Stations:Time-resolved volumetric systems capture dynamic cardiac and fetal imaging sequences for specialized obstetric and interventional suites.
3D Imaging Stations commands the established base. The steepest expansion runs through Portable Workstations.
Technology:
Technology selection tracks the installed base of underlying imaging modalities, with CT and MRI workstations carrying premium pricing due to computational intensity and specialized display requirements.
- CT Imaging:Workstations for computed tomography demand high-throughput reconstruction pipelines and dual-monitor setups for cross-sectional analysis. Large hospital networks in the United States and diagnostic chains in Germany are refreshing fleets to handle spectral CT and photon-counting detector data volumes.
- MRI Imaging:Functional MRI and diffusion tensor processing requires specialized post-processing software for neurosurgical planning. Academic centers in Japan and specialized neurology institutes in Switzerland are driving workstation upgrades to support advanced neuroimaging protocols and intraoperative navigation integration.
- Ultrasound Imaging:Real-time rendering stations with elastography and contrast-enhanced imaging capabilities serve cardiology and emergency medicine departments.
- X-ray Imaging:Digital radiography and fluoroscopy workstations prioritize rapid image access and PACS integration for high-volume screening programs.
- Nuclear Imaging:PET-CT and SPECT fusion workstations require quantitative analysis tools for oncology and cardiology radiotracer studies.
CT Imaging and MRI Imaging together anchor procurement volumes. Ultrasound Imaging is climbing the fastest as point-of-care deployment expands.
Application:
Application-focused segmentation aligns workstation specifications with the diagnostic complexity and reimbursement profiles of distinct clinical specialties.
- Cardiovascular Analysis:Cardiac CT, MRI, and echocardiography workstations require synchronized multi-phase reconstruction and strain analysis software. Cath labs in Germany and heart centers in the United States are investing heavily as structural heart interventions and coronary CT angiography volumes rise.
- Neurological Assessment:Advanced visualization for stroke imaging, tumor segmentation, and functional mapping demands high-resolution displays and AI-augmented detection tools. Neurological institutes in Japan and academic stroke centers in Switzerland are prioritizing these configurations to compress time-to-treatment metrics.
- Orthopedic Imaging:3D templating and surgical planning workstations support joint replacement and trauma procedures.
- Pulmonary Evaluation:Thoracic CT workstations with emphysema quantification and nodule tracking serve lung cancer screening programs.
- Dental Diagnostics:Cone-beam CT workstations with panoramic reconstruction target oral surgery and implant planning practices.
Cardiovascular Analysis holds the largest installed base. Neurological Assessment is gaining share fastest on AI integration and stroke protocol expansion.
End User:
End-user type determines procurement authority, budget scale, and service model preferences across the workstation market.
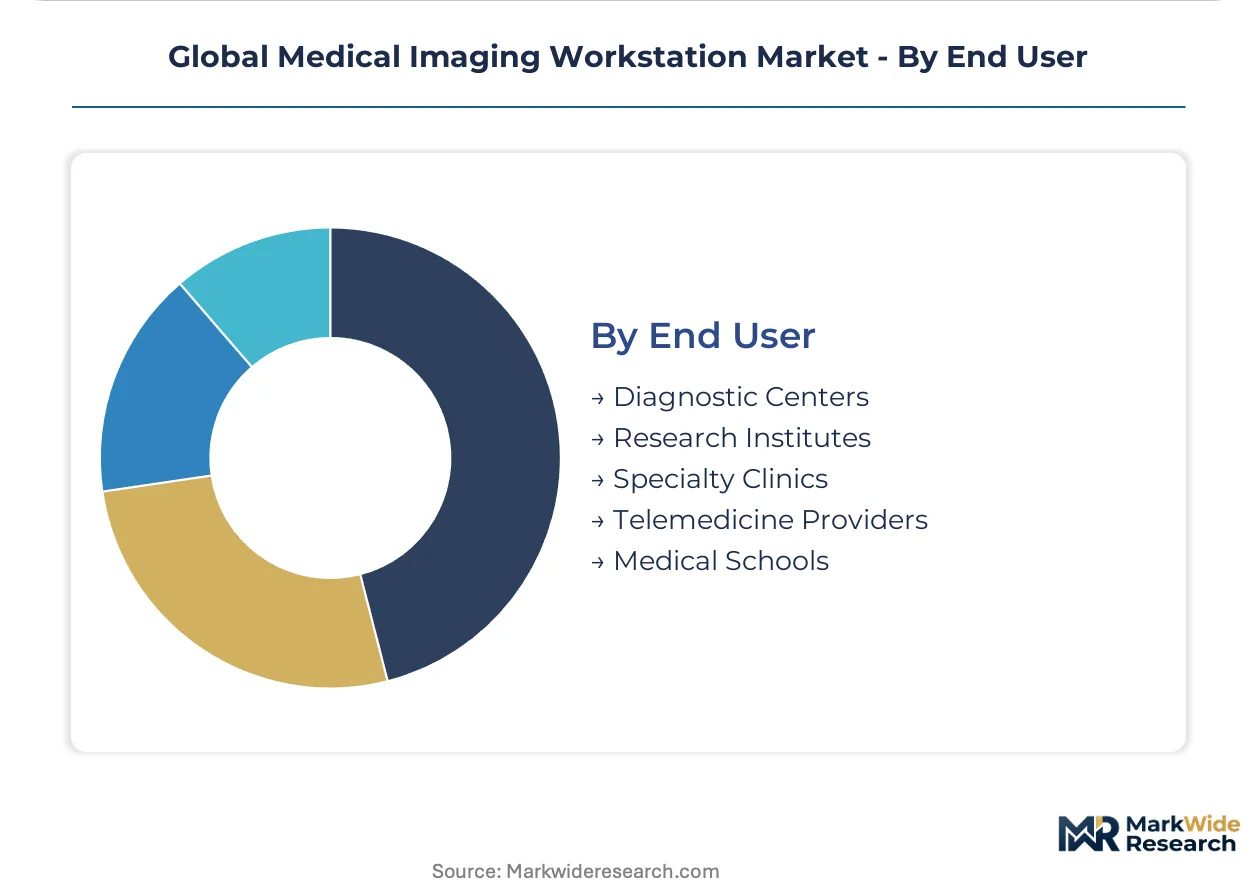
- Telemedicine Providers:Cloud-connected workstation pools with centralized quality assurance and distributed radiologist access are scaling fastest. Teleradiology networks in India and virtual care platforms in the United States are building infrastructure to serve rural and underserved markets under Germany's Digital Healthcare Act reimbursement parity.
- Diagnostic Centers:High-throughput independent imaging facilities prioritize workflow efficiency and rapid turnaround. Multi-site operators in the United States are adopting subscription-based workstation access to convert capital expenditure into operational outlays.
- Research Institutes:Preclinical and clinical trial imaging workstations require specialized quantification tools and regulatory documentation support.
- Specialty Clinics:Focused practices in cardiology, orthopedics, and women's health deploy modality-specific workstations with streamlined interfaces.
- Medical Schools:Teaching workstations with dual-display configurations and case library integration support radiology resident training programs.
Diagnostic Centers represent the largest customer base. Telemedicine Providers show the steepest expansion trajectory as distributed reading models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA governs diagnostic workstation software through 510(k) and De Novo pathways, while reimbursement policies in Germany and Japan concentrate procurement authority in hospital networks and academic medical centers.
United States
Academic medical centers in Boston and Houston are refreshing workstation fleets to handle photon-counting CT data volumes. The FDA's software-as-a-medical-device framework accelerates clearance timelines for AI-enabled diagnostic algorithms. Siemens Healthineers and GE Healthcare anchor competitive positioning through integrated software-hardware ecosystems serving cardiology reading rooms.
Germany
University hospitals in Munich and Berlin prioritize workflow automation to compress radiologist reading turnaround times. The Digital Healthcare Act establishes reimbursement parity for teleradiology services, incentivizing cloud-connected workstation investments. Baden-Württemberg's medical technology cluster hosts concentrated vendor R&D activity for hybrid OR integration.
Japan
Stroke centers in Tokyo and Osaka are scaling neurological assessment workstation deployments to compress time-to-treatment metrics. PMDA maintains accelerated review pathways for software-based medical devices with quality management system maturity. The Kansai region concentrates academic research institutes driving functional MRI workstation upgrades.
India
Telemedicine providers in Bangalore and Hyderabad are building distributed reading pools to serve Tier-2 and Tier-3 cities. CDSCO regulatory harmonization with IMDRF standards streamlines import clearance for AI-augmented diagnostic tools. Maharashtra's diagnostic imaging chains are adopting subscription-based workstation access models.
Switzerland
Specialized neurology institutes in Zurich and Geneva are investing in intraoperative navigation integration for neurosurgical planning workstations. Swissmedic enforces stringent post-market surveillance for high-risk diagnostic applications under MDR alignment. The Basel biotech corridor concentrates research workstation procurement for clinical trial imaging.
Global Medical Imaging Workstation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the medical imaging workstation market. The vendor base stratifies into three tiers: integrated modality manufacturers commanding premium positioning, independent software vendors competing on workflow specialization, and regional assemblers serving cost-constrained procurement. Dominant competitive moves include backward integration into GPU supply chains and strategic partnerships with teleradiology network operators.
Among integrated modality manufacturers, Siemens Healthineers and GE Healthcare exemplify the technology-leadership archetype through captive control over imaging source data and rendering engine development. Koninklijke Philips occupies a differentiated position within this tier via workflow orchestration tools that consolidate multi-modality reads. Canon Medical Systems Corporation represents the mid-tier specialist segment, anchoring competitive positioning in compact portable configurations for point-of-care deployment.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Carestream Health |
| Carl Zeiss Meditec |
| Hologic |
| Agfa-Gevaert Group |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with Taiwan-based GPU foundries lock in both semiconductor supply access and price visibility for workstation vendors serving United States hospital networks. These contracts insulate premium-tier manufacturers from spot-market volatility while exposing mid-tier assemblers to component cost swings.
Pricing Analysis
United States academic medical centers pay 40-60% premiums over Indian diagnostic chains for equivalent GPU-accelerated 3D imaging stations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared AI-augmented configurations from grayscale-only DICOM viewers. Cost compression in the standard tier is intensifying because open-source radiology software erodes perpetual license values. Independent imaging centers in Germany exhibit highest price sensitivity; large hospital networks in Japan show lowest sensitivity due to bundled modality procurement.
Supply Chain Analysis
Inventory buffers for high-fidelity grayscale displays stretch 12-16 weeks as panel fabrication concentrates in South Korea and Japan. Graphics processing units draw from Taiwan Semiconductor Manufacturing and NVIDIA supply allocations. Specialized DICOM calibration equipment sources from Germany and Switzerland. Single-source vulnerability in EUV lithography for advanced GPUs threatens workstation refresh timelines. Distribution runs through modality OEM direct sales teams in developed markets and regional medical device distributors in Southeast Asia and Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent workstation vendors face substitution pressure from cloud-native teleradiology platforms that displace on-premise hardware with browser-based diagnostic viewers. Defense requires locking in modality source data integration and accelerating AI validation pipelines.
For Market Incumbents: Compound software-hardware ecosystem stickiness by embedding FDA-cleared AI algorithms directly into imaging modality data streams. Deepen backward integration into GPU supply chains through strategic foundry partnerships. Prioritize quality management system maturity to exploit PMDA accelerated review pathways before EU MDR clinical evidence burdens harden.
For New Entrants and Emerging Players: Cloud-native workflow orchestration for mid-sized radiology groups represents the most penetrable white space, as Siemens Healthineers and GE Healthcare under-serve subscription-seeking buyers. Target India's Tier-2 and Tier-3 teleradiology networks with portable workstation-as-a-service models. Pursue CDSCO regulatory harmonization to streamline import clearance for AI-augmented tools.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated software vendors with captive AI validation expertise and established hospital system partnerships. Long-term viability hinges on regulatory navigation capabilities across FDA, EU MDR, and PMDA frameworks. Watch for EU AI Act conformity assessment bottlenecks as inflection indicator for vendor consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortens time-to-market for AI-enabled diagnostic algorithms competing for radiology department budgets. |
| GPU Supply Agreement | Secures semiconductor allocation from Taiwan foundries amid workstation hardware refresh cycles. |
| Hospital System Partnership | Locks in procurement preference through embedded workflow integration with Siemens or GE modality fleets. |
| Cloud-Native Platform Development | Enables subscription revenue conversion from capital expenditure models in United States imaging centers. |
| EU MDR Quality System Restructuring | Satisfies notified body AI expertise requirements for high-risk cardiology and oncology reading tools. |
Research Methodology
A standing panel of radiology department heads, biomedical engineers, hospital purchasing committee chairs, and GPO contracts managers provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body registers, hospital procurement transaction records, and imaging modality vendor SEC filings. Bottom-up unit demand estimates triangulated against top-down market sizing from installed base refresh modeling.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, imaging modality technology, clinical application, and end-user archetype. CAGRs were derived from logistic diffusion curves fitted to historical replacement rates and projected AI adoption S-curves. Forecast inputs incorporated radiologist workforce shortage severity indices and teleradiology reimbursement policy trajectories.
Forecasts assume regulatory continuity in FDA SaMD pathways, EU MDR transitional provisions, and Japan PMDA software review frameworks; material policy shifts would require re-modeling. Specific risks include GPU supply disruption from Taiwan semiconductor fabrication concentration and EU AI Act risk reclassification for diagnostic algorithms. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Brazil Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Spectroscopy Intravascular Imaging System Market
Medical Imaging
Germany Mammography Market
Medical Imaging
Spain Mammography Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Spain Nuclear Imaging Market
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
United Kingdom Computed Tomography Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
Europe Nuclear Imaging Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
Global MRI Scanner Market
Medical Imaging
Vendor Neutral Archive Market