
 Global Telepsychiatry Market | 2026-2036
Global Telepsychiatry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telepsychiatry Market Foresight
The capital-intensity divergence between full-stack platform operators and lightweight consultative intermediaries is rotating competitive advantage toward entities with proprietary infrastructure. Teladoc Health leverages its integrated health system contracts to sustain recurring revenue streams across enterprise clients. Array Behavioral Care anchors its position through clinician workforce ownership, controlling psychiatric provider supply in underserved markets. Advanced Telemed Services differentiates via state-level Medicaid partnerships, navigating fragmented reimbursement landscapes that exclude smaller competitors.
Telepsychiatry denotes the delivery of psychiatric assessment, diagnosis, and treatment through synchronous audiovisual communication, asynchronous messaging, and remote physiological monitoring, typically requiring HIPAA-compliant encryption, bandwidth thresholds exceeding 1.5 Mbps for video fidelity, and integration with electronic health record systems. The technology dimension shows cloud-based platforms capturing the largest installed base while AI-driven tools represent the fastest-expanding margin pool due to automated triage and predictive risk stratification capabilities. Video consultations dominate service-type revenue, though remote monitoring is accelerating as wearable integration enables continuous symptom tracking for bipolar disorder and schizophrenia management.
The FDA oversees digital therapeutic classification and software-as-medical-device determinations, while HIPAA mandates encryption and access controls that shape platform architecture decisions for US market entry. Australia's TGA regulates telehealth device claims, and the EU AI Act imposes risk-tiered conformity requirements on diagnostic algorithms deployed in member states. Stakeholders must monitor evolving interoperability mandates and cross-border licensure reciprocity agreements that will determine scalable operating models.
Market Dynamics
Cloud-native platform architectures are compressing deployment timelines for psychiatric service networks while simultaneously exposing legacy infrastructure operators to margin erosion from compute-intensive AI workloads.
Growth Catalysts
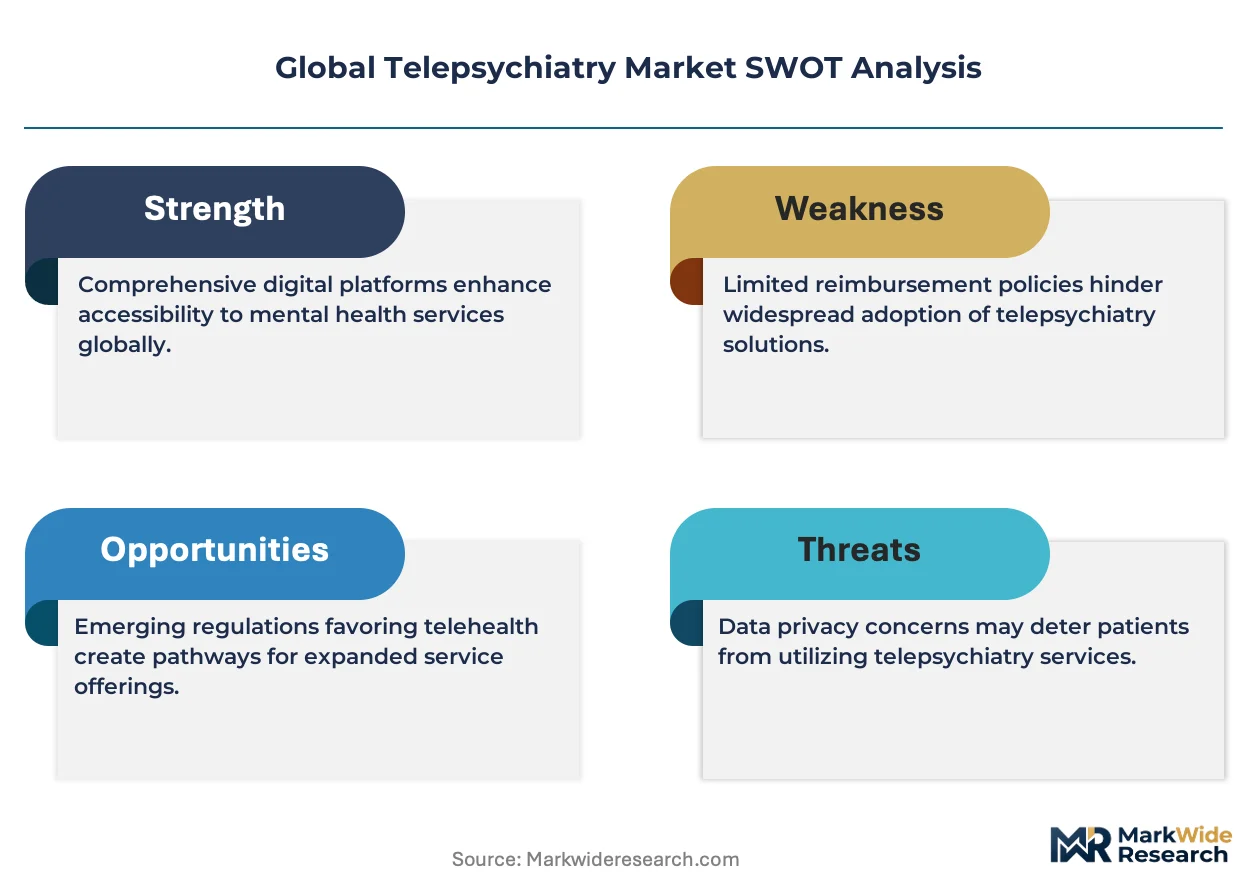
- Medicaid Reimbursement Expansion:The US Centers for Medicare and Medicaid Services has broadened parity mandates for virtual behavioral health, enabling fee-for-service billing in 38 states.
- Rural Workforce Shortages:Australia faces a psychiatrist-to-population ratio below 0.5 per 10,000 in remote territories, forcing health districts toward asynchronous consultation platforms.
- Wearable Integration:Continuous glucose monitors and accelerometers are feeding symptom data into bipolar disorder management protocols, creating new service revenue streams.
Market Restraints
- Bandwidth Infrastructure Gaps:Rural US counties with DSL speeds below 1.5 Mbps cannot sustain HIPAA-compliant video fidelity, excluding 12 million potential patients.
- Cross-Border Licensure Friction:The EU AI Act's risk-tiered conformity requirements impose documentation burdens that delay algorithm deployment in member states.
- Clinician Supply Concentration:Psychiatric nurse practitioners cluster in urban US corridors, leaving platform operators competing for the same limited credential pool.
Strategic Opportunities
- Underserved Correctional Facilities:US state prison systems operate with psychiatric staffing ratios below 1:500 inmates, creating captive demand for centralized telehealth hubs.
- Employer-Sponsored Mental Health:Fortune 500 self-insured plans are unbundling EAP contracts to direct-purchase specialty psychiatric networks.
- EU AI Act Convergence:Diagnostic algorithm developers who achieve CE marking under MDR-IVDR dual frameworks gain automatic recognition across 27 member states.
Industry Challenges
- EHR Integration Complexity:Epic and Cerner legacy instances require custom API bridges that extend implementation timelines by 8-14 months.
- Credentialing Bottlenecks:State medical boards maintain non-uniform telehealth privileging standards that delay provider onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telepsychiatry Market |
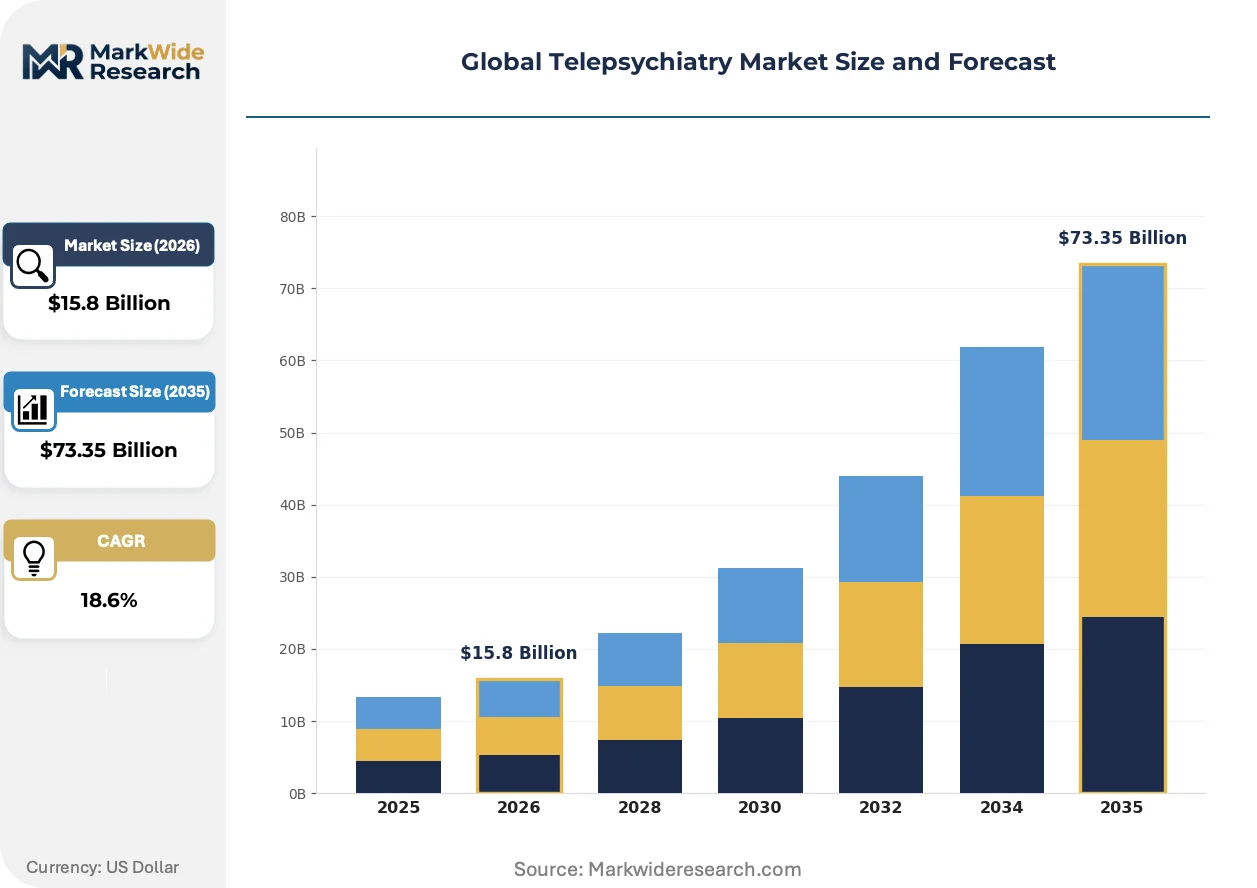
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video Consultations, Phone Consultations, Remote Monitoring, Online Therapy, Digital Assessments Technology: Cloud-based Platforms, Mobile Applications, AI-driven Tools, Wearable Devices, Virtual Reality Application: Depression, Anxiety Disorders, Bipolar Disorder, PTSD, Schizophrenia End User: Psychiatrists, Mental Health Clinics, Rehabilitation Centers, Counseling Centers, Universities |
| Companies Covered | Array Behavioral Care, Teladoc Health, Telemynd, American Well, MDLIVE, Advanced Telemed Services, Iris Telehealth, American Telepsychiatrists, innovaTel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telepsychiatry Market Shifts & Advancements
Artificial intelligence is restructuring how psychiatric risk gets assessed and priced, compressing the gap between symptom onset and clinical intervention while redistributing value toward predictive analytics vendors.
Natural language processing tools are fragmenting the traditional diagnostic interview by automating mood disorder screening through conversational analysis. Community health centers in Texas and Florida are deploying these systems to triage patient queues before psychiatrist involvement. The technology is fragmenting revenue pools away from synchronous consultation minutes toward software licensing and per-assessment fees.
The EU AI Act's high-risk system classification for diagnostic algorithms is forcing developers to maintain exhaustive training data documentation and human-in-the-loop protocols. This regulatory architecture favors well-capitalized platform operators with dedicated compliance functions. European psychiatric networks are responding by consolidating vendor relationships to reduce audit surface area.
Direct-to-employer contracting is displacing traditional payer-channel intermediation for behavioral health benefits. Self-insured manufacturers in Germany's automotive sector and US technology firms are negotiating carve-out arrangements with specialized telepsychiatry providers. This shift concentrates purchasing power among benefits managers who demand outcome guarantees and utilization reporting.
Global Telepsychiatry Market Segmentation
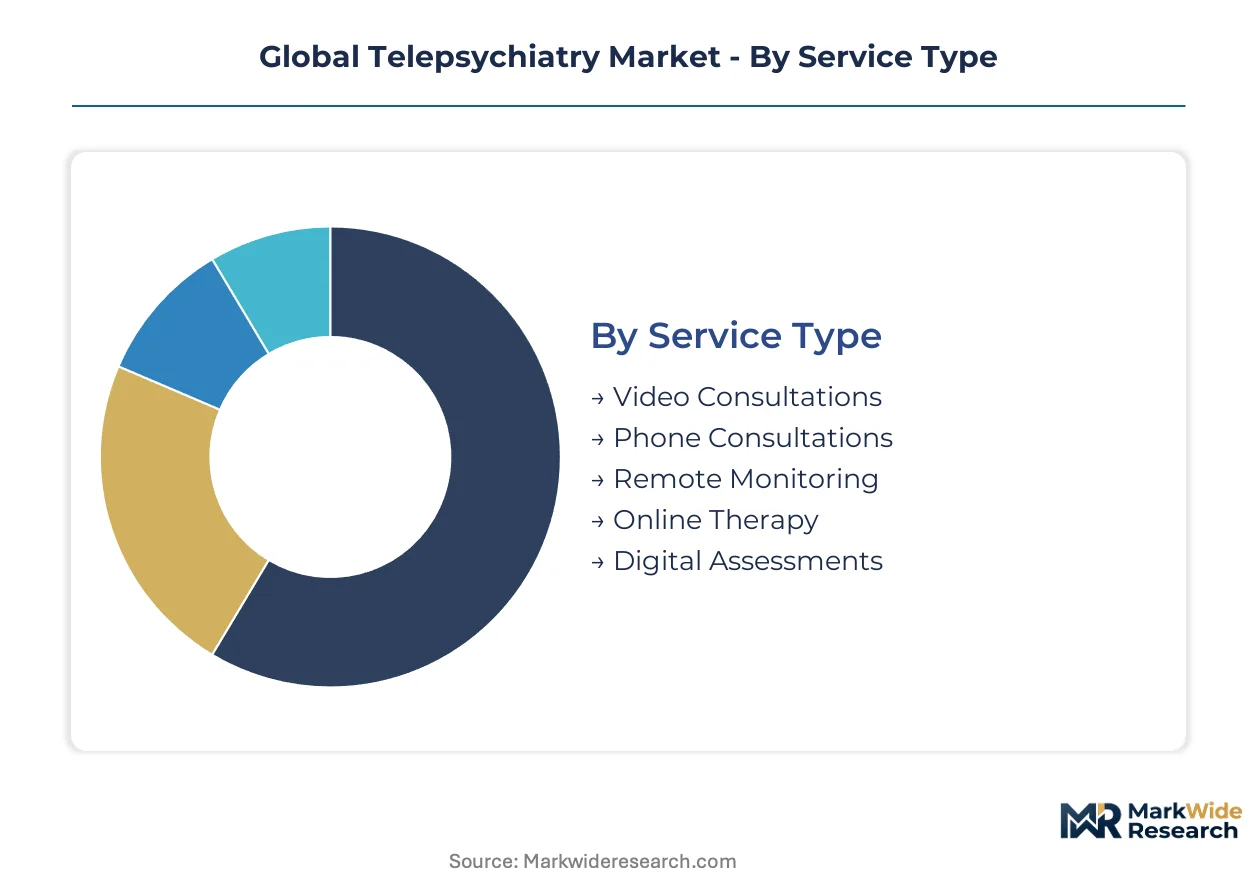
Telepsychiatry segmentation reveals divergent margin profiles across synchronous and asynchronous modalities. Cloud infrastructure investments and FDA software-as-medical-device classifications are fragmenting competitive positions by technology ownership depth.
Service Type:
Video consultations face mounting substitution pressure from asynchronous alternatives that bypass bandwidth constraints and clinician scheduling bottlenecks.
- Video Consultations:Synchronous audiovisual sessions requiring HIPAA-compliant encryption and sustained bandwidth above 1.5 Mbps. US rural hospital networks concentrate demand here as workforce shortages force virtual psychiatric coverage across dispersed geographies.
- Remote Monitoring:Continuous physiological tracking via wearable integration for bipolar disorder and schizophrenia symptom management. Australian remote territories show concentrated adoption where psychiatrist-to-population ratios fall below 0.5 per 10,000 and asynchronous triage becomes essential.
- Phone Consultations:Audio-only psychiatric assessments serving low-bandwidth patient populations and emergency crisis lines.
- Online Therapy:Text-based and structured digital therapeutic programs delivered through subscription models.
- Digital Assessments:Standardized screening tools and diagnostic questionnaires deployed for pre-visit triage and outcome tracking.
Video consultations retain volume leadership; remote monitoring holds the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive full-stack operators from lightweight intermediaries dependent on third-party infrastructure.
- Cloud-based Platforms:Enterprise-grade psychiatric service networks with EHR integration and multi-tenant architecture. US Medicaid expansion across 38 states drives concentrated procurement from health systems seeking scalable behavioral health capacity.
- AI-driven Tools:Natural language processing systems automating mood disorder screening and predictive risk stratification. EU AI Act high-risk system classification is forcing documentation-heavy compliance investments that favor well-capitalized developers.
- Mobile Applications:Consumer-facing therapy and medication management tools with direct-to-patient distribution.
- Wearable Devices:Accelerometer and glucose monitor integration feeding symptom data into clinical decision support.
- Virtual Reality:Immersive exposure therapy environments for PTSD and anxiety disorder treatment protocols.
Cloud-based platforms anchor current installed base; AI-driven tools are gaining share fastest through automated triage displacement.
Application:
Volume concentration varies sharply by condition severity and reimbursement pathway complexity across diagnostic categories.
- Depression:High-prevalence mood disorder with established telehealth reimbursement codes and employer-sponsored benefit penetration. Fortune 500 self-insured plans in the US and Germany's automotive sector concentrate demand through direct carve-out contracting.
- Bipolar Disorder:Chronic condition requiring continuous symptom monitoring and medication adherence tracking. Wearable integration enabling longitudinal data collection is accelerating platform deployment in Australia's remote health districts.
- Anxiety Disorders:Broad diagnostic category spanning generalized anxiety, panic disorder, and phobia spectrum conditions.
- PTSD:Trauma-related condition with specialized exposure therapy protocols and veteran-focused service lines.
- Schizophrenia:Severe mental illness with complex medication management and higher acuity intervention requirements.
Depression commands the largest addressable population; bipolar disorder shows the most rapid technology integration through remote monitoring adoption.
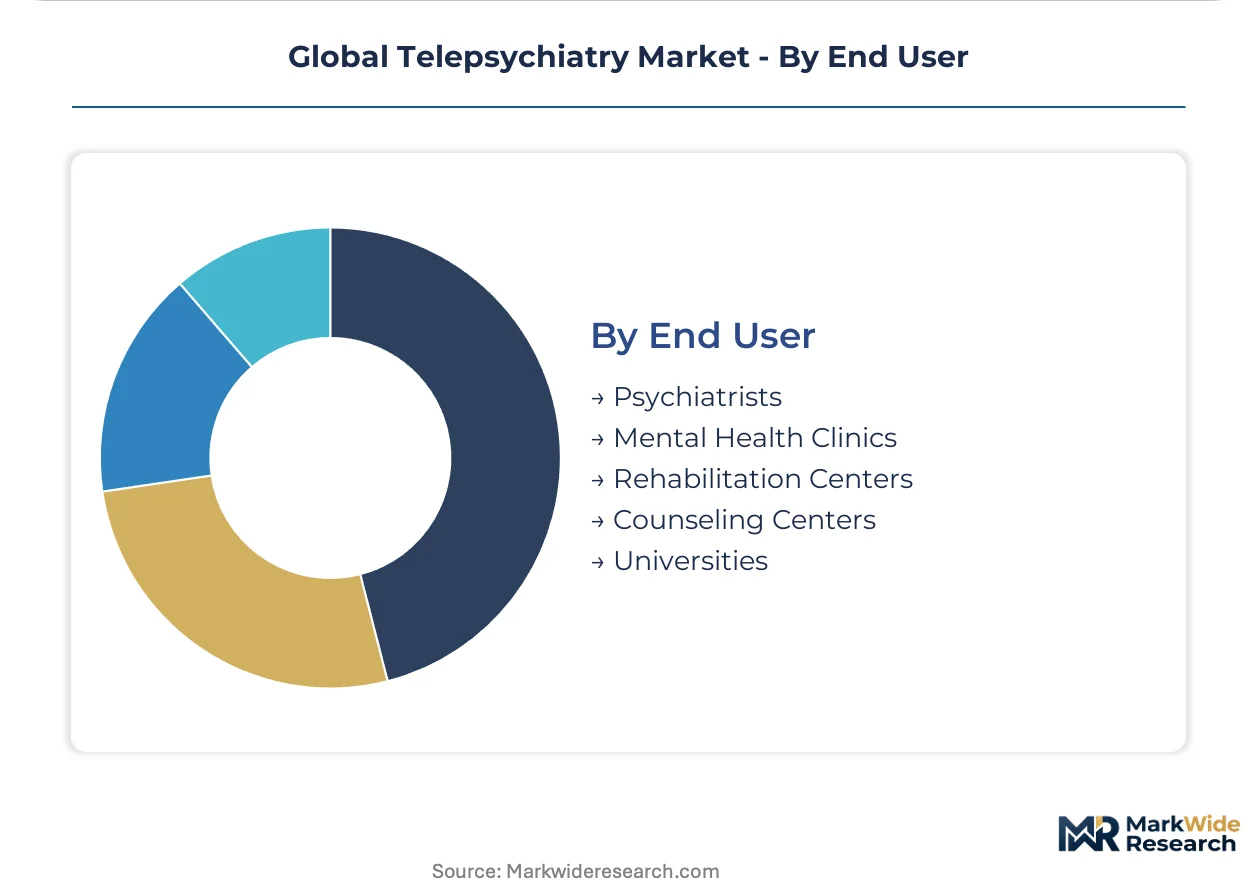
End User:
Customer type fragmentation reflects divergent procurement authority and outcome accountability structures across care settings.
- Mental Health Clinics:Specialized outpatient facilities with established psychiatric staffing and technology infrastructure. US community health centers in Texas and Florida concentrate NLP triage system deployment to manage patient queue throughput.
- Psychiatrists:Individual practitioners and small group practices seeking platform-enabled practice extension. State medical board non-uniform telehealth privileging standards create onboarding friction that delays individual adoption.
- Rehabilitation Centers:Substance use and dual-diagnosis treatment facilities integrating psychiatric care into recovery protocols.
- Counseling Centers:University and employer-based services with prevention-focused service models.
- Universities:Campus health services addressing student mental health demand surges with limited on-site psychiatric capacity.
Mental health clinics dominate enterprise contract value; psychiatrists represent the most dispersed but highest-margin customer segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform operators in the United States command premium reimbursement rates that Australian providers cannot replicate under government-funded fee schedules. This pricing-power asymmetry concentrates capital deployment toward North American infrastructure buildouts while compressing margins in subsidized markets.
United States
Rural hospital networks in Texas and Florida drive concentrated demand for synchronous video platforms as workforce shortages force virtual psychiatric coverage across dispersed geographies. The FDA's evolving guidance on digital therapeutics reshapes reimbursement pathways for telehealth platforms serving Medicaid populations. Community health centers in the Southeast deploy natural language processing triage systems to manage patient queue throughput before psychiatrist involvement.
Australia
Remote territories face psychiatrist-to-population ratios below 0.5 per 10,000, forcing health districts toward asynchronous consultation platforms and continuous monitoring protocols. The TGA regulates telehealth device claims and software-as-medical-device determinations that shape platform architecture decisions for market entry. Western Australia and Queensland health districts accelerate wearable integration for bipolar disorder management where longitudinal data collection becomes essential.
Germany
Self-insured manufacturers in the automotive sector negotiate direct carve-out arrangements with specialized telepsychiatry providers, displacing traditional payer-channel intermediation. The EU AI Act imposes risk-tiered conformity requirements on diagnostic algorithms that favor well-capitalized platform operators with dedicated compliance functions. Bavaria-based employer networks concentrate purchasing power among benefits managers demanding outcome guarantees and utilization reporting.
United Kingdom
NHS digital transformation programs expand procurement of cloud-based psychiatric service networks with EHR integration requirements. MHRA oversight of software-as-medical-device classifications creates documentation burdens that delay algorithm deployment relative to US timelines. London and Southeast England health systems lead adoption of AI-driven triage tools within community mental health frameworks.
Canada
Provincial health authorities in Ontario and Quebec expand telehealth parity mandates for virtual behavioral health, enabling fee-for-service billing across fragmented reimbursement landscapes. Health Canada and PMRA regulate remote patient monitoring claims that determine scalable operating models for platform operators. Prairie provinces and Atlantic Canada face bandwidth infrastructure gaps that compress adoption of video-intensive protocols in favor of audio-only alternatives.
Global Telepsychiatry Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the telepsychiatry value chain. Full-stack platform operators with proprietary cloud infrastructure capture enterprise contract value through EHR integration depth, while lightweight consultative intermediaries compete on deployment speed and capital efficiency. Three archetypes dominate: integrated health system contractors, clinician workforce owners, and state-level Medicaid navigators. Consolidation pressure intensifies through strategic partnerships between technology vendors and psychiatric provider networks, alongside geographic expansion into underserved correctional and rural markets.
Within the integrated health system tier, Teladoc Health and Array Behavioral Care exemplify divergent approaches to sustainable positioning. Teladoc Health occupies a position anchored through enterprise client relationships and multi-tenant architecture serving recurring revenue streams. Array Behavioral Care represents workforce ownership models that control psychiatric provider supply in markets with acute clinician scarcity. Advanced Telemed Services sits within the Medicaid specialization archetype, navigating fragmented state reimbursement landscapes that exclude smaller competitors from sustainable participation.
| Leading Market Players |
|---|
| Array Behavioral Care |
| Teladoc Health |
| Telemynd |
| American Well |
| MDLIVE |
| Advanced Telemed Services |
| Iris Telehealth |
| American Telepsychiatrists |
| innovaTel |
| Others |
Supply & Pricing Matrix
Long-term enterprise service contracts lock in multi-year platform access and fee visibility for US health systems navigating Medicaid reimbursement parity across 38 states. These arrangements tether psychiatric provider networks to predictable revenue streams while insulating against bandwidth infrastructure gaps that exclude 12 million rural patients from synchronous video protocols.
Pricing Analysis
The customization-premium spread separates full-stack platform operators from lightweight consultative intermediaries in telepsychiatry procurement. Enterprise EHR integration contracts command substantial premiums over standardized SaaS subscriptions due to Epic and Cerner legacy API complexity. Price differentiation hinges on HIPAA compliance certification tier and clinician workforce ownership depth. Cost compression in the audio-only consultation tier intensifies as DSL-constrained rural counties default to lower-fidelity alternatives. Community health centers exhibit acute price sensitivity; integrated health system contractors demonstrate inelastic demand for proprietary infrastructure.
Supply Chain Analysis
The United States anchors cloud-native psychiatric platform development, while Australia concentrates wearable integration manufacturing for remote monitoring protocols. India supplies NLP engineering talent pools that feed automated triage system development. Taiwan produces semiconductor components essential for HIPAA-compliant encryption hardware. The supply chain draws from single-source vulnerability in psychiatric nurse practitioner credentialing, where state medical board non-uniform privileging standards create onboarding bottlenecks. Distribution runs through health system procurement committees and direct-to-employer benefits managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telepsychiatry operates as a defensive-moat market where regulatory entrenchment through FDA software-as-medical-device classifications and state-level Medicaid partnerships creates durable barriers against new entrants.
For Market Incumbents: Secure exclusive clinician workforce ownership in psychiatrist-scarce territories to preempt competitor platform expansion. Deepen EHR integration capabilities through dedicated API engineering teams, reducing implementation timelines that currently extend 8-14 months for legacy Epic and Cerner instances. Vertical integration into wearable device data feeds addresses substitution pressure from asynchronous monitoring alternatives. For New Entrants and Emerging Players: Lead with AI-driven triage tools targeting community health centers in Texas and Florida, where patient queue throughput constraints create immediate deployment receptivity. Underserved US state prison systems with psychiatric staffing ratios below 1:500 inmates represent the most penetrable captive demand segment. Direct-to-employer carve-out contracting with Fortune 500 self-insured plans offers a channel bypassing traditional payer intermediation. For Investors and Strategic Acquirers: Medicaid-specialized platform operators with state-level navigation capabilities present the optimal acquisition target archetype for portfolio exposure to reimbursement expansion tailwinds. Long-term viability rests on regulatory entrenchment depth rather than technology differentiation alone. Watch EU AI Act CE marking achievement under MDR-IVDR dual frameworks as the signal for scalable European algorithm deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Clinician Workforce Acquisition | Psychiatric provider supply control in underserved markets locks out competitor platform expansion. |
| State Medicaid Partnership Navigation | Fragmented reimbursement landscapes exclude smaller competitors from sustainable participation. |
| Wearable Integration Development | Continuous symptom tracking for bipolar disorder creates differentiated service revenue streams. |
| EU AI Act Compliance Investment | CE marking under MDR-IVDR frameworks enables automatic recognition across 27 member states. |
| Direct-to-Employer Contracting | Fortune 500 self-insured plans concentrate purchasing power among benefits managers demanding outcome guarantees. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with telepsychiatry platform executives, psychiatric nurse practitioners, health system procurement directors, Medicaid program administrators, and FDA regulatory affairs specialists. Secondary validation drew from FDA digital therapeutic guidance documents, CMS Medicare reimbursement databases, Australian TGA device registration records, EU AI Act implementation texts, and hospital GPO contract filings. Bottom-up service volume estimates triangulated against top-down market sizing from health expenditure data.
Across the analysis window, the forecast framework modeled service type segmentation, technology deployment architecture, application severity tiers, and end-user procurement authority structures. CAGRs derived from regression analysis of historical platform adoption curves and reimbursement policy diffusion patterns. Industry-specific inputs included psychiatrist-to-population ratio trajectories in Australian remote territories and US rural hospital network virtual coverage expansion rates.
The analysis sits within stated boundaries; outcomes outside sustained Medicaid parity mandates, EU AI Act enforcement intensity, or bandwidth infrastructure investment levels would require recalibration. Forecasts reflect documented assumptions regarding clinician supply concentration and cross-border licensure reciprocity evolution. Recalibration cycles align with material shifts in FDA digital therapeutic classification guidance and state-level telehealth privileging standard harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telestroke Services Market
Telemedicine
Telehealth Kiosk Market
Telemedicine
United States Telehealth Pre-Natal Services Market
Telemedicine
Telepathology Service Market
Telemedicine
Teledermatology Market
Telemedicine
Real-Time E-Healthcare System Market
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
Remote Healthcare Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
Telehealth and Telemedicine Market
Telemedicine
Tele-Epilepsy Market
Telemedicine
Telehealth Services Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
GCC Telemedicine Market