
 Telemedicine Diagnostic Services Market | 2026-2036
Telemedicine Diagnostic Services Market Size, Share, and Industry Trends Forecast 2026-2036
Telemedicine Diagnostic Services Market Insights
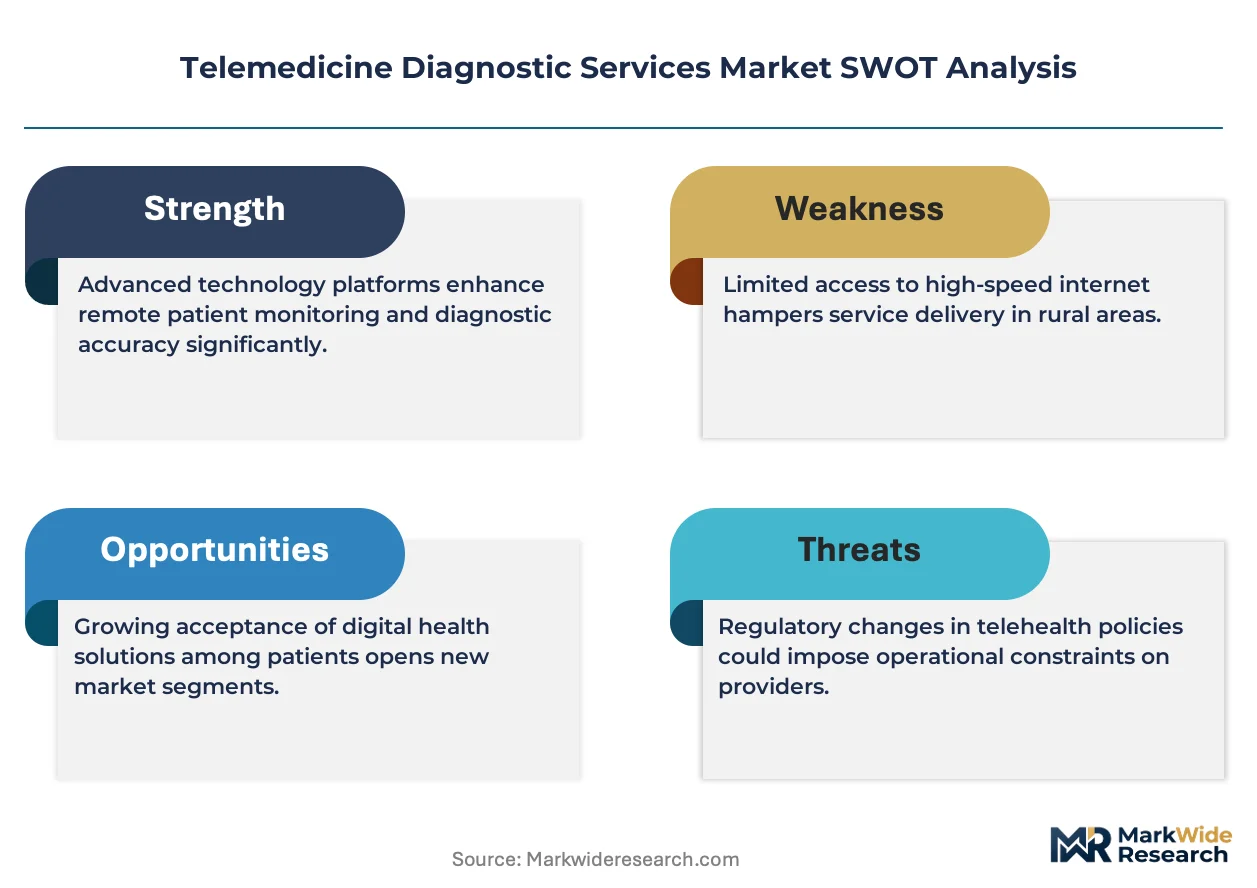
Market Dynamics
HIPAA compliance certification for telehealth platforms is collapsing as a market-access barrier, forcing vendors to rebuild security architectures around interoperable standards. Teladoc Health Inc leverages its longitudinal patient data infrastructure to sustain chronic care diagnostics at scale. American Well Corporation anchors enterprise contracts with large hospital networks, while Philips Healthcare differentiates through integrated imaging hardware and cloud-based radiology workflows.
Segmentation
Telemedicine diagnostic services encompass remote clinical assessment, digital pathology transmission, and algorithm-assisted interpretation delivered across distributed networks, typically requiring sub-200ms latency for real-time video consultation and DICOM-compliant imaging pipelines. The primary commercial purpose is to extend specialist diagnostic capacity into underserved geographies without physical infrastructure deployment. Remote monitoring and diagnostic imaging command the deepest margin pools as reimbursement codes mature, while wearable devices within the technology segment represent the fastest-expanding channel as biosensor fidelity improves. Cloud platforms dominate enterprise deployment but face margin compression from hyperscaler competition.
Regulatory Landscape
FDA oversight of software-as-a-medical-device and CMS reimbursement parity rules shape demand trajectories and platform design requirements in the United States. The EU AI Act and MDR frameworks impose conformity assessment burdens on diagnostic algorithms deployed across European member states. Stakeholders must monitor evolving cross-border licensure reciprocity agreements and algorithmic audit mandates to anticipate where regulatory arbitrage opportunities will open or close.
Market Dynamics
Specialist physician scarcity in rural geographies is compressing diagnostic timelines and forcing health systems to virtualize triage workflows, with reimbursement parity mandates from CMS and state Medicaid programs accelerating capital allocation toward asynchronous diagnostic platforms.
Growth Catalysts
- CMS Reimbursement Parity:Medicare's expanded coverage for remote diagnostic consultations removes payment barriers for synchronous video-based specialty assessments in federally qualified health centers.
- Biosensor Miniaturization:Continuous glucose monitors and photoplethysmography arrays embedded in consumer wearables now transmit clinical-grade data streams to cloud-based diagnostic algorithms.
- India's Tier-Two Hospital Networks:Domestic healthtech platforms deploy store-and-forward radiology and dermatology screening across 400+ secondary cities with fiber backhaul infrastructure.
Market Restraints
- Cross-Border Licensure Fragmentation:US state medical boards maintain non-reciprocal telehealth licensing requirements that block interstate specialist consultations without redundant credentialing.
- Cloud Infrastructure Concentration:Diagnostic imaging pipelines rely on three hyperscalers for DICOM-compliant storage, creating single-point vulnerability for enterprise hospital networks.
- Algorithmic Audit Burden:EU AI Act conformity assessments impose documentation requirements on machine-learning diagnostic tools that extend commercialization timelines by 18-24 months.
Strategic Opportunities
- Brazil's SUS Integration:Public health system procurement of asynchronous dermatology and ophthalmology screening for Amazon basin municipalities lacks qualified domestic vendors.
- FDA Software-as-a-Medical-Device Pathway:Predetermined change control plans enable iterative algorithm updates without repeated 510(k) submissions, reducing regulatory friction for adaptive diagnostic models.
- 5G Network Slicing:Ultra-reliable low-latency communication channels enable real-time haptic guidance for remote ultrasound probe manipulation in emergency department settings.
Industry Challenges
- Interoperability Architecture Gaps:HL7 FHIR implementation varies across EHR vendors, forcing custom integration layers that consume 30-40% of platform deployment resources.
- Diagnostic Liability Ambiguity:Malpractice jurisdiction disputes between originating site clinicians and remote specialists create insurance coverage gaps that delay contract finalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telemedicine Diagnostic Services Market |
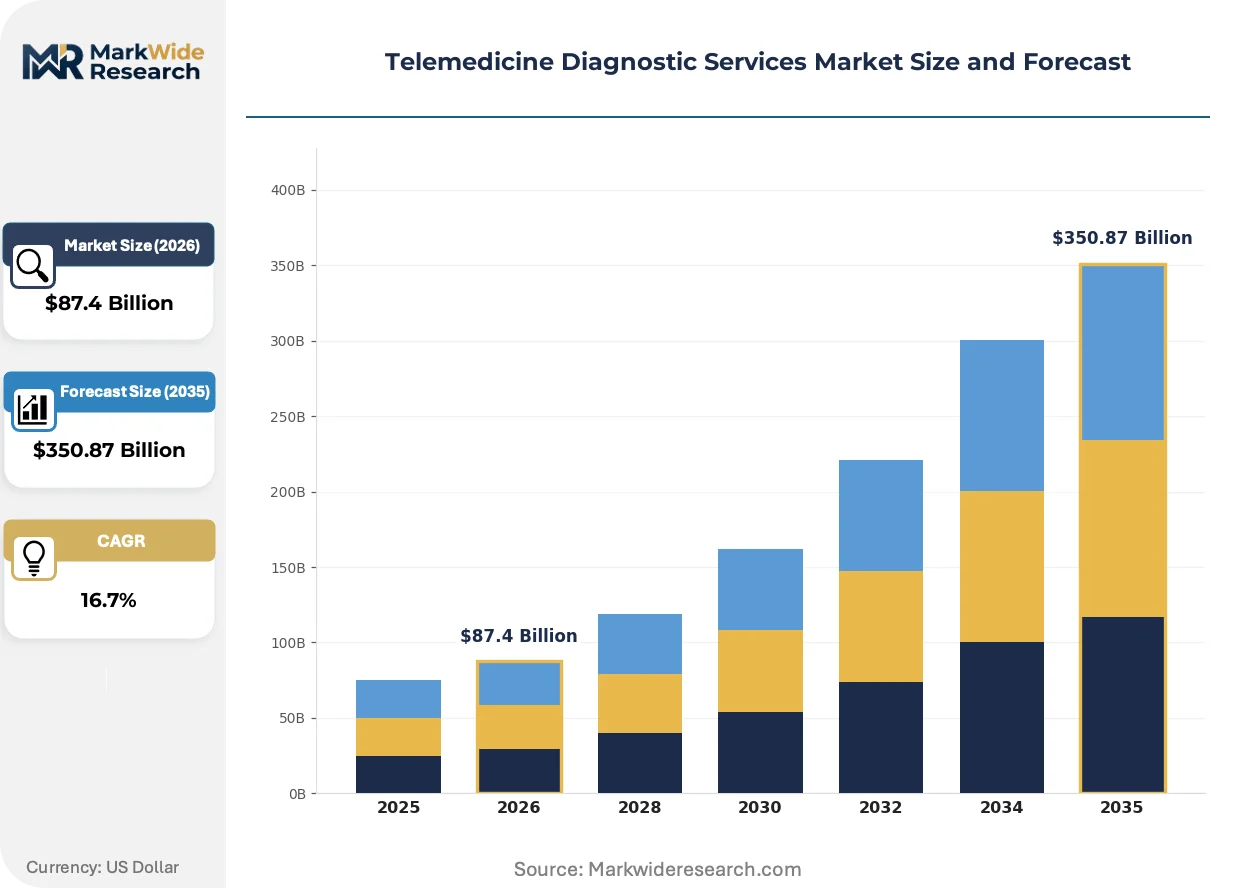
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $350.87 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultation, Remote Monitoring, Diagnostic Imaging, Laboratory Testing End User: Healthcare Providers, Patients, Insurance Companies, Employers Technology: Mobile Applications, Video Conferencing, Cloud Platforms, Wearable Devices Delivery Mode: Live Video, Asynchronous Messaging, Phone Consultation, Email Communication |
| Companies Covered | Teladoc Health Inc, American Well Corporation, Philips Healthcare, GE Healthcare, Siemens Healthineers, MDLive Inc, Babylon Health, Ping An Good Doctor, Practo Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telemedicine Diagnostic Services Market Trends and Innovations
Diagnostic workflow virtualization is fragmenting traditional radiology and pathology value chains, with algorithmic interpretation displacing human readers in low-complexity cases and platform vendors capturing margin from incumbent imaging equipment manufacturers.
Edge computing architectures for medical devices are decomposing centralized cloud dependency for diagnostic imaging. Portable CT and ultrasound units now deploy onboard NVIDIA Clara algorithms for immediate triage classification. Emergency medical services in Germany and Japan are piloting these units for pre-hospital stroke assessment. This compression of decision latency is reallocating capital from hospital-based imaging suites toward mobile diagnostic fleets.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on diagnostic algorithms that influence patient treatment pathways. MDR-notified bodies now audit machine-learning training datasets for demographic representativeness. European radiology AI vendors are restructuring quality management systems to satisfy both MDR technical documentation and AI Act transparency requirements, with mid-cap developers facing compliance costs that favor acquisition by integrated platform conglomerates.
Hospital procurement departments are unbundling diagnostic service contracts from traditional equipment leasing arrangements. Health systems in Texas and Florida now negotiate per-study pricing for teleradiology interpretations separate from PACS infrastructure subscriptions. This disaggregation exposes standalone imaging equipment manufacturers to margin pressure while enabling specialized diagnostic interpretation platforms to capture recurring revenue without capital equipment deployment.
Telemedicine Diagnostic Services Market Segmentation
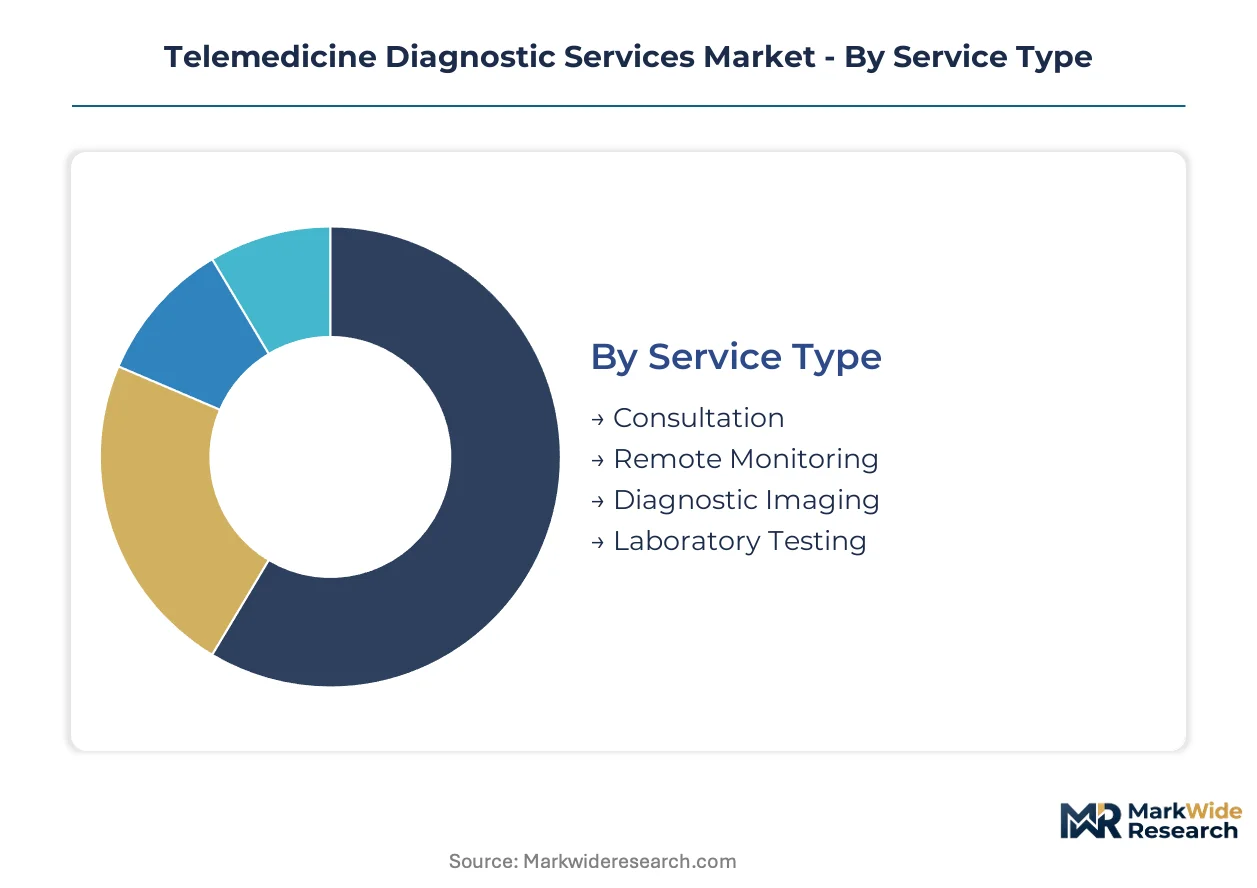
Segmentation in telemedicine diagnostics reveals where capital allocates across service delivery models and who captures value from reimbursement flows. Distinguishing synchronous from asynchronous modalities exposes which platforms scale profitably versus those requiring heavy specialist staffing.
Service Type:
Margin pools concentrate in services that automate interpretation or extend specialist reach without proportional labor cost expansion.
- Consultation:Real-time video-based specialist assessment requiring sub-200ms latency for diagnostic confidence. Demand clusters in rural United States hospital systems offsetting cardiology and neurology shortages, with CMS reimbursement parity removing payment friction for federally qualified health centers.
- Remote Monitoring:Continuous physiologic data transmission from ambulatory patients to cloud-based surveillance algorithms. Biosensor miniaturization in continuous glucose monitors and photoplethysmography arrays enables clinical-grade streaming to diagnostic platforms.
- Diagnostic Imaging:Store-and-forward radiology and DICOM-compliant image interpretation across distributed networks.
- Laboratory Testing:Remote specimen collection coordination with centralized reference laboratory analysis.
Remote Monitoring holds installed capacity. Diagnostic Imaging is rotating up the share rankings.
End User:
Procurement authority determines contract structure, with enterprise health systems negotiating platform licenses differently than individual patient subscriptions.
- Healthcare Providers:Hospital networks and physician groups purchasing enterprise diagnostic platform subscriptions. Texas and Florida health systems now unbundle teleradiology interpretation contracts from PACS infrastructure, enabling per-study pricing negotiations.
- Patients:Direct-to-consumer diagnostic access through mobile applications and wearable-integrated screening tools.
- Insurance Companies:Payers deploying asynchronous diagnostic networks to reduce emergency department utilization and specialist referral costs.
- Employers:Self-insured corporations contracting occupational health screening and chronic condition monitoring for workforce populations.
Healthcare Providers dominate contract value. Patients are gaining share fastest as biosensor fidelity improves.
Technology:
Technology selection determines latency tolerance, data sovereignty requirements, and integration complexity with incumbent EHR systems.
- Mobile Applications:Patient-facing diagnostic interfaces with embedded algorithmic triage tools. India's tier-two hospital networks deploy these across 400+ secondary cities with fiber backhaul infrastructure for asynchronous dermatology and radiology screening.
- Video Conferencing:Synchronous audiovisual consultation requiring HIPAA-compliant encryption and interoperability with clinical workflows.
- Cloud Platforms:Enterprise deployment backbone for DICOM storage and diagnostic algorithm hosting. Hyperscaler competition is compressing margins for independent platform vendors.
- Wearable Devices:Consumer and clinical-grade biosensors transmitting continuous physiologic data. Edge computing architectures in portable CT and ultrasound units now deploy onboard NVIDIA Clara algorithms for immediate triage classification.
Cloud Platforms anchor enterprise deployment. Wearable Devices are climbing the fastest as clinical-grade sensors penetrate consumer markets.
Delivery Mode:
Delivery mode selection reflects regulatory constraints on cross-border licensure and reimbursement code availability.
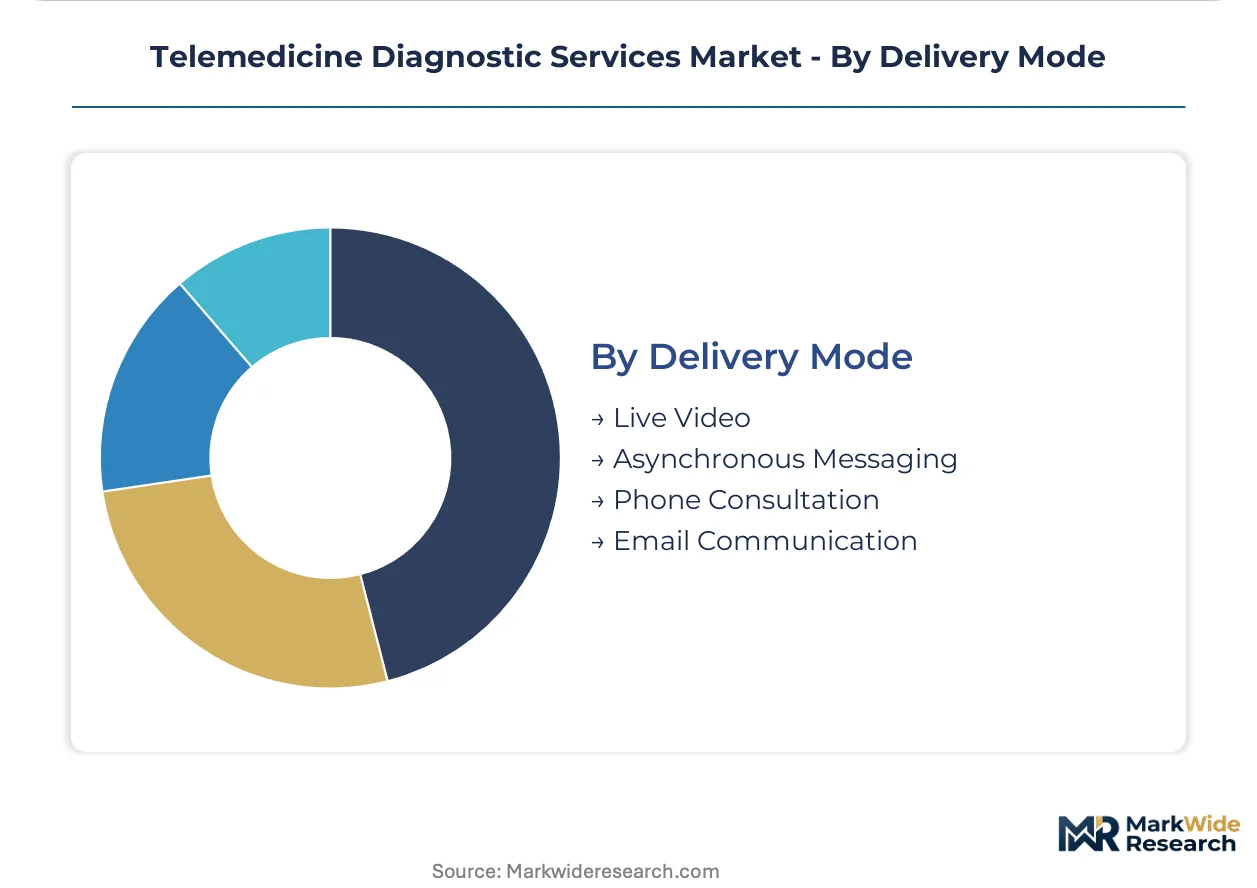
- Live Video:Synchronous real-time consultation demanding low-latency network infrastructure and immediate specialist availability. 5G network slicing enables ultra-reliable low-latency channels for emergency department applications.
- Asynchronous Messaging:Store-and-forward diagnostic workflows eliminating scheduling constraints. FDA software-as-a-medical-device pathways with predetermined change control plans reduce regulatory friction for iterative algorithm updates.
- Phone Consultation:Audio-only diagnostic assessment for bandwidth-constrained environments and elderly patient populations.
- Email Communication:Document-based diagnostic exchange with extended turnaround timelines for non-urgent specialist interpretation.
Live Video retains reimbursement advantage. Asynchronous Messaging is expanding most quickly where specialist scarcity compresses synchronous capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of clinical decision support software rules and CMS reimbursement parity mandates are accelerating platform standardization across national health systems, while India's tier-two hospital networks and Brazil's public procurement gaps create divergent commercial entry points.
United States
Rural hospital systems in Texas and Florida offset cardiology and neurology shortages through virtual diagnostic adoption. CMS reimbursement parity rules remove payment barriers for synchronous video-based specialty assessments in federally qualified health centers. The Mayo Clinic and Cleveland Clinic anchor enterprise diagnostic platform deployments across the Midwest and Southeast.
Germany
Emergency medical services pilot portable CT and ultrasound units with onboard NVIDIA Clara algorithms for pre-hospital stroke assessment. The EU AI Act and MDR frameworks impose conformity assessment burdens on diagnostic algorithms deployed across European member states. Berlin and Munich healthtech clusters restructure quality management systems to satisfy dual regulatory requirements.
India
Domestic healthtech firms scale asynchronous diagnostic networks across tier-two cities with fiber backhaul infrastructure for store-and-forward radiology and dermatology screening. CDSCO oversight of software-as-a-medical-device shapes platform design requirements for algorithmic interpretation tools. Practo Technologies anchors deployments across 400+ secondary cities including Pune, Jaipur, and Lucknow.
Brazil
Public health system procurement of asynchronous dermatology and ophthalmology screening for Amazon basin municipalities lacks qualified domestic vendors. ANVISA regulatory pathways for imported diagnostic platforms create compliance complexity for foreign entrants. São Paulo and Rio de Janeiro healthtech clusters concentrate private-sector telemedicine infrastructure while northern states remain underserved.
China
Ping An Good Doctor and domestic platforms deploy AI-assisted diagnostic interpretation across provincial hospital networks. NMPA oversight of software-as-a-medical-device accelerates platform standardization for algorithmic triage tools. Yangtze River Delta and Pearl River Delta clusters concentrate healthtech R&D capacity for cloud-based diagnostic infrastructure.
Telemedicine Diagnostic Services Market Competitive Landscape
Listed leaders compete with private specialists across capital access and regulatory compliance capabilities, creating a tiered structure where scale-driven conglomerates capture enterprise hospital contracts while niche platforms dominate single-modality interpretations. Three archetypes dominate: integrated imaging hardware vendors, pure-play telehealth platforms, and algorithm-centric AI diagnostics developers. Consolidation pressure intensifies as M&A activity absorbs mid-cap developers facing EU AI Act compliance costs, while strategic partnerships between cloud hyperscalers and hospital networks displace independent platform vendors.
Among US-based listed platforms, Teladoc Health Inc and American Well Corporation exemplify the enterprise-contract archetype, anchoring longitudinal patient data infrastructure and large hospital network relationships respectively. Philips Healthcare represents the integrated hardware-software model, combining imaging equipment manufacturing with cloud-based radiology workflows to capture margin from unbundled diagnostic service contracts.
| Leading Market Players |
|---|
| Teladoc Health Inc |
| American Well Corporation |
| Philips Healthcare |
| GE Healthcare |
| Siemens Healthineers |
| MDLive Inc |
| Babylon Health |
| Ping An Good Doctor |
| Practo Technologies |
| Others |
Pricing and Supply Chain Analysis
FDA software-as-a-medical-device classification gates both vendor qualification and reimbursement tier access, compressing margins for uncertified platforms while enabling premium pricing for 510(k)-cleared diagnostic algorithms. This regulatory filter simultaneously constrains supply base expansion and creates price stratification between compliant and non-compliant service tiers.
Pricing Analysis
Certification level (FDA 510(k)/CE-MDR/CDSCO-grade) creates the primary spread between premium diagnostic platforms and commodity telehealth vendors. Pricing stratifies across FDA-cleared, CE-marked, and uncertified tiers, with enterprise hospital systems commanding volume discounts against per-study rates for individual practitioners. Cost compression in the uncertified tier is intensifying because hyperscaler cloud infrastructure commoditizes storage and compute. Federally qualified health centers exhibit highest price sensitivity due to fixed CMS reimbursement ceilings, while integrated health systems in Texas and Florida negotiate least sensitivity through bundled teleradiology contracts.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for NVIDIA Clara edge computing modules and DICOM-compliant imaging sensors sourced from Taiwan, South Korea, and China. Component dependencies rest on CMOS biosensor arrays, fiber-optic transmission hardware, and cloud hyperscaler storage capacity. Single-source vulnerability concentrates in GPU accelerator supply from Taiwan Semiconductor Manufacturing. Distribution runs through hospital procurement departments unbundling diagnostic interpretation from PACS infrastructure subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through health system mergers in Texas and Florida, enabling enterprise procurement teams to extract per-study pricing concessions from teleradiology vendors and compress platform margins.
For Market Incumbents: Fortify longitudinal patient data infrastructure against cloud hyperscaler encroachment by deepening integration with hospital EHR systems. Invest in FDA predetermined change control plans to accelerate algorithm iteration cycles. Defend against mid-cap AI diagnostic developers facing EU AI Act compliance costs by acquiring their technical talent and regulatory documentation assets.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks market entry for stroke-triage algorithms and dermatology screening tools. Penetrate Brazil's Amazon basin municipalities where ANVISA complexity blocks foreign competitors and SUS procurement lacks qualified domestic vendors. Deploy store-and-forward asynchronous platforms through fiber-backhaul partnerships with tier-two Indian hospital networks.
For Investors and Strategic Acquirers: EU AI Act MDR-notified body audits reshape the acquisition landscape by elevating compliance documentation to primary due diligence priority. Target mid-cap European radiology AI vendors facing quality management system restructuring costs. Watch FDA enforcement patterns on clinical decision support software as inflection indicator for platform standardization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates reimbursement parity access for synchronous video-based specialty assessments. |
| CE Marking Pathway | Unlocks EU AI Act conformity assessment for algorithmic diagnostic tools deployed across member states. |
| Hospital System Partnership | Secures enterprise contract anchoring against unbundled teleradiology pricing pressure. |
| Software Companion Development | Enables DICOM-compliant integration with incumbent PACS infrastructure from GE Healthcare and Philips. |
| Reimbursement Strategy | Aligns platform design with CMS remote monitoring codes and Medicaid parity mandates. |
Research Methodology
A spread of perspectives from hospital procurement managers, telehealth platform CTOs, FDA regulatory affairs consultants, and GPO contracts directors converged on the working assumptions. Primary interviews with biomedical engineers and CMS reimbursement specialists combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and CDSCO software-as-a-medical-device registrations. Bottom-up service-line modeling and top-down health system expenditure triangulation anchored volume estimates.
Segmentation dimensions modeled include synchronous versus asynchronous delivery mode, cloud versus edge deployment architecture, and enterprise versus direct-to-consumer procurement channel across the analysis window. CAGRs derived from algorithmic adoption curves in rural cardiology and neurology shortages, biosensor miniaturization penetration rates, and tier-two city fiber infrastructure deployment timelines.
Decision-makers should treat outputs as directional under assumptions of sustained CMS reimbursement parity and EU AI Act enforcement continuity; material deviation would warrant model refresh. Specific risks include cross-border licensure reciprocity collapse, hyperscaler cloud concentration failures, and algorithmic audit burden escalation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Video Telemedicine Market
Telemedicine
Healthcare IoT Telemedicine Market
Telemedicine
US Virtual Care Market
Telemedicine
North America Telemedicine Market
Telemedicine
Global Virtual Care Market
Telemedicine
India Telemedicine Market
Telemedicine
Stroke Telemedicine Services Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
US Telehealth Market
Telemedicine
Telemedicine Workstations Market
Telemedicine
Pediatric Telemedicine Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
Emergency Telemedicine Services Market
Telemedicine
Telehealth Services Market
Telemedicine
Teledermatology Market