
 Video Telemedicine Market | 2026-2036
Video Telemedicine Market Size, Share, and Industry Trends Forecast 2026-2036
Video Telemedicine Market Intelligence
Expanded digital healthcare infrastructure in India is rewriting the rules of patient access and delivery. Cisco Systems Inc. leverages its enterprise networking and security expertise to provide high-bandwidth platforms for large hospital systems. Zoom Video Communications Inc. competes by offering a user-friendly, scalable software solution that integrates easily into existing clinical workflows. GlobalMed Inc. specializes in providing integrated hardware and software packages designed specifically for medical encounters.
Video telemedicine involves the use of real-time, two-way audiovisual technology to deliver clinical healthcare from a distance. These systems require stable, high-bandwidth connections to support high-definition video for accurate visual assessments and diagnostics. Within service types, consultation services represent the largest segment, while remote monitoring for chronic disease management shows significant growth potential. Cloud-based technology platforms are displacing on-premises solutions due to superior scalability, accessibility, and lower upfront capital expenditure for healthcare providers.
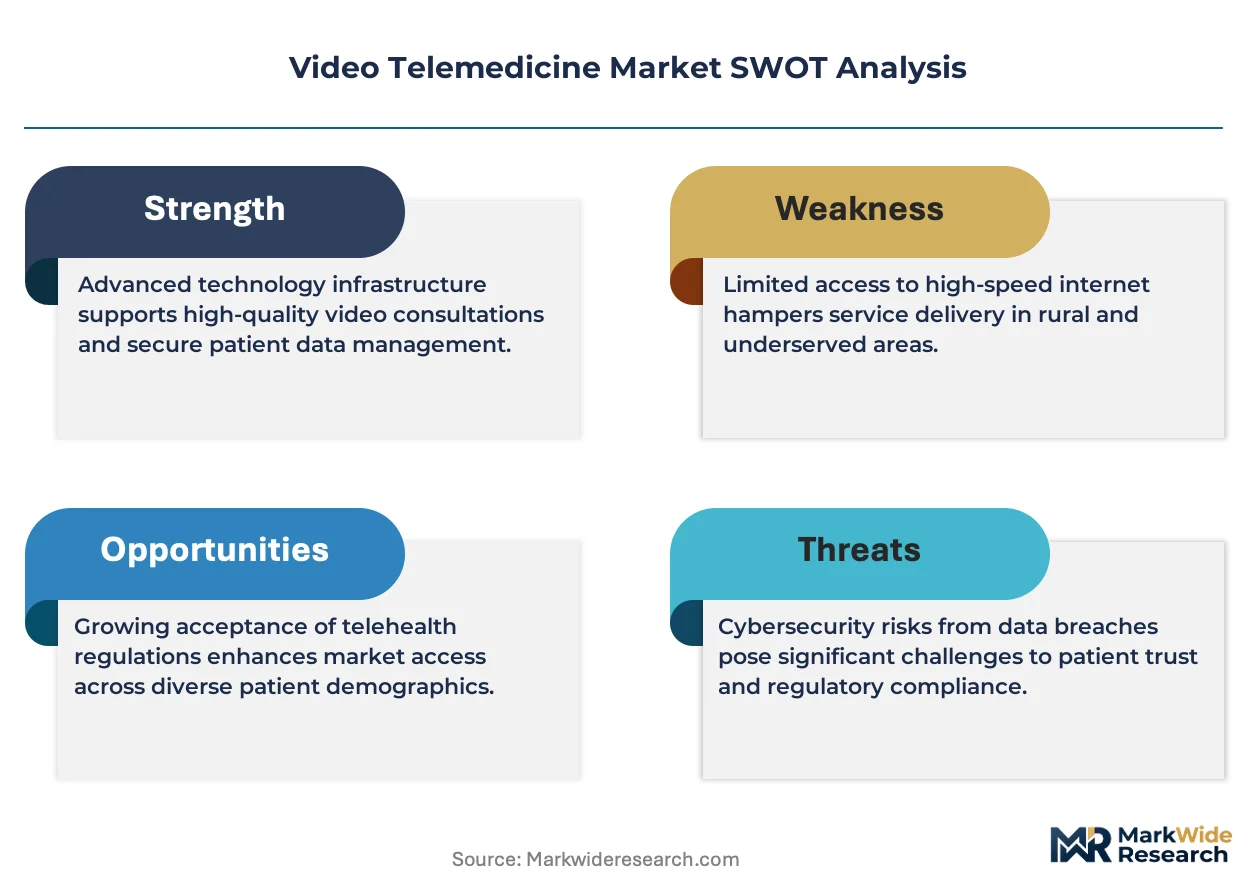
Regulatory frameworks such as the Health Insurance Portability and Accountability Act (HIPAA) in the United States and the General Data Protection Regulation (GDPR) in Europe impose strict data privacy and security mandates. National bodies like Health Canada and Australia's TGA establish specific guidelines for virtual care delivery and medical device software. These regulations directly influence platform architecture and data handling protocols. Consequently, vendors must navigate evolving cross-border data laws and reimbursement policies to sustain growth.
Market Dynamics
The central force shaping the video telemedicine market is the tension between rapid technological advancement and the strict, often fragmented, regulatory frameworks governing healthcare data. Platform architecture is directly influenced by compliance mandates like HIPAA, which dictate security protocols and data handling.
Growth Catalysts
- National Digital Health Policies:Government-led initiatives, such as Germany's digital health reforms, are creating structured reimbursement pathways and encouraging provider adoption of virtual care, directly stimulating market expansion for compliant platforms.
- Cloud Platform Adoption:The migration from on-premises hardware to scalable, cloud-based software-as-a-service (SaaS) models lowers the barrier to entry for smaller clinics and enables rapid deployment across large healthcare systems.
- Chronic Disease Management:Demand from providers for effective remote monitoring solutions for chronic conditions like diabetes and hypertension is a significant pull, expanding telemedicine's use case beyond simple acute consultations.
Market Restraints
- Bandwidth Dependency:The requirement for stable, high-bandwidth internet connectivity for high-definition video creates a significant barrier to adoption in rural and underserved regions with underdeveloped digital infrastructure.
- Cross-Border Data Regulation:Navigating the complex and sometimes conflicting data privacy laws, such as GDPR in Europe and HIPAA in the United States, increases compliance costs and complexity for vendors operating internationally.
- Legacy System Integration:Difficulty and high costs associated with integrating new telemedicine platforms into existing, often proprietary, Electronic Health Record (EHR) systems can delay or prevent adoption by established hospitals.
Strategic Opportunities
- Underpenetrated Geographies:Expanding digital infrastructure in countries like India presents a substantial opportunity for market entry, as healthcare systems leapfrog traditional models in favor of mobile-first virtual care delivery.
- AI-Powered Diagnostics:The integration of artificial intelligence and machine learning algorithms into video platforms to assist with diagnostic imaging analysis and clinical decision support represents a major area for value creation.
- Wearable Device Convergence:Combining real-time video consultations with data streamed from patient-owned wearable IoT devices offers a path to more comprehensive and data-rich remote examinations and monitoring.
Industry Challenges
- Clinical Workflow Adaptation:A primary operational hurdle is the redesign of clinical workflows and training of healthcare professionals to effectively and safely conduct virtual examinations, which differs significantly from in-person care.
- Maintaining Data Security:Vendors face the constant challenge of defending against sophisticated cyber threats to protect sensitive patient health information, requiring continuous investment in security infrastructure and compliance audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Telemedicine Market |
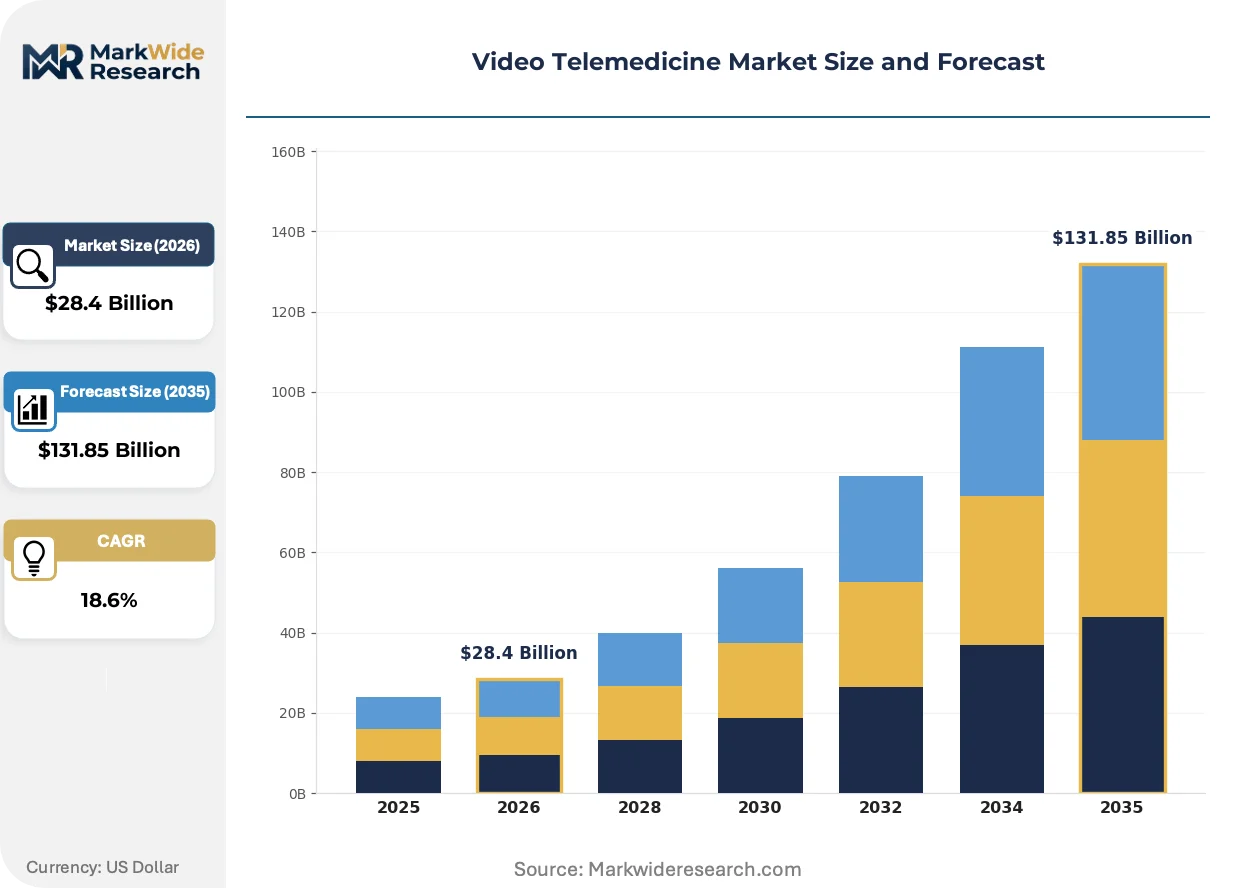
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $131.85 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Mobile Applications, Hardware Devices, Video Conferencing Tools End User: Patients, Healthcare Providers, Insurance Companies, Telehealth Organizations Technology: Web-Based, Cloud-Based, On-Premises, Mobile-Based Service Type: Consultation Services, Remote Monitoring, Post-Operative Care, Emergency Services |
| Companies Covered | Logitech International, Cisco Systems Inc., AMD Global Telemedicine, Polycom (Plantronics), Huawei Technologies Co Ltd., Vidyo Inc., GlobalMed Inc., Zoom Video Communications Inc, Life-Size Communication Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Telemedicine Market Strategic Shifts & Innovations
The market's evolution is defined by a move from basic communication tools to integrated clinical systems. This transition is powered by the convergence of specialized medical hardware, intelligent software, and an increasingly sophisticated regulatory environment that treats software as a medical device.
Integrated telemedicine peripherals, including digital stethoscopes and high-resolution otoscopes, are a key product evolution. Specialty clinics and hospital departments are adopting these tools to conduct more thorough remote examinations that require specific diagnostic data. This development is digitizing the physical examination, transforming a video call into a remote clinical data acquisition event and enabling more accurate virtual diagnoses.
Regulatory frameworks are evolving to manage the growing complexity of these platforms. The European Union's Medical Device Regulation (MDR) reclassifies certain advanced telemedicine software as a medical device, demanding rigorous clinical validation and post-market surveillance. This directly affects developers targeting the EU, forcing investment in quality management systems and clinical evidence generation to achieve and maintain CE marking for their software platforms.
A notable behavioral shift is visible in how healthcare organizations acquire this technology. Providers are moving away from monolithic, single-vendor platform licenses toward a more modular procurement strategy for specialty-specific applications like tele-dermatology or tele-psychiatry. This unbundling of services disrupts the traditional enterprise sales model. This trend is most prominent within large hospital networks in the United States and Germany seeking best-of-breed solutions for different clinical departments.
Video Telemedicine Market Segmentation
The video telemedicine market exhibits diverse operational characteristics, requiring a granular understanding of its constituent parts. Analyzing market segments reveals varying demands for functionality, integration complexity, and regulatory compliance across different user groups. This detailed breakdown illuminates specific growth pockets and areas of strategic investment for vendors.
Product Type:
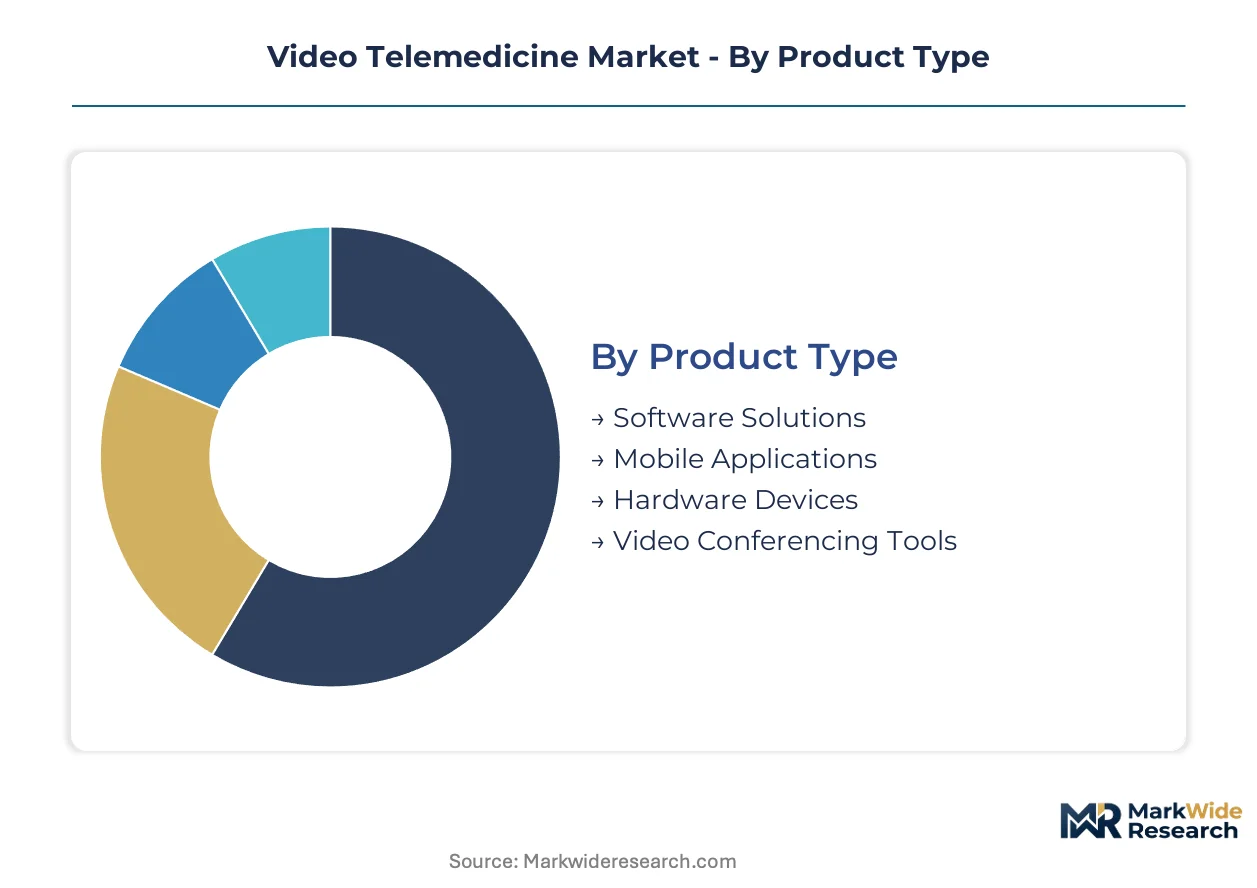
The after-sales service intensity varies significantly across product types, with complex integrated systems demanding continuous support and updates. Software solutions provide the core functionality for virtual consultations and patient data management.
- Software Solutions:These platforms offer comprehensive features for scheduling, secure communication, electronic health record integration, and billing. Demand concentrates in large hospital systems seeking scalable, customizable platforms that comply with HIPAA and GDPR regulations.
- Hardware Devices:This segment includes specialized medical peripherals like digital stethoscopes, otoscopes, and examination cameras, integrated with telemedicine platforms. Germany and the United States show strong demand for these devices to enhance diagnostic accuracy in remote settings.
- Mobile Applications:These applications provide convenient access to telemedicine services via smartphones and tablets, catering to individual patients and smaller clinics.
- Video Conferencing Tools:Generic video communication platforms are adapted for basic telemedicine consultations, often serving as entry-level solutions for new providers.
By volume, Software Solutions lead the market. By growth pace, Hardware Devices are expanding most quickly due to increasing demand for enhanced remote diagnostics.
End User:
End user applications for video telemedicine range from direct patient care to administrative support and reimbursement processing. Healthcare providers constitute a primary user base, integrating virtual care into their daily clinical workflows.
- Healthcare Providers:Hospitals, clinics, and individual practitioners utilize video telemedicine for remote consultations, follow-ups, and specialist referrals. Their demand centers on platforms offering robust EHR integration and compliance with national medical guidelines.
- Patients:Individuals access video telemedicine for convenient medical advice, prescription refills, and chronic disease management from their homes. India and other underpenetrated geographies drive significant patient adoption due to improved accessibility.
- Insurance Companies:These entities leverage telemedicine platforms for claims processing, utilization review, and to promote cost-effective care options for their policyholders.
- Telehealth Organizations:Dedicated telehealth service providers use these platforms to deliver a wide array of remote medical services, often serving as intermediaries between patients and specialists.
Healthcare Providers represent the largest segment in terms of platform deployment and utilization across various clinical settings.
Technology:
Technology deployment models vary significantly in terms of scalability, accessibility, and maintenance overhead for video telemedicine solutions. Cloud-based platforms are increasingly favored for their operational flexibility and reduced infrastructure requirements.
- Cloud-Based:These solutions host data and applications on remote servers, accessible via the internet, offering superior scalability and lower upfront costs. Healthcare providers in the United States and Europe are rapidly adopting cloud models for their agility and security features.
- Web-Based:These platforms operate through standard web browsers, requiring no specific software installation, providing broad accessibility for users. Their ease of access makes them popular for initial consultations and general practitioner services.
- On-Premises:Traditional systems installed and maintained on local servers offer maximum control over data but incur higher capital expenditure and maintenance burdens.
- Mobile-Based:Technology delivered through dedicated mobile applications caters to ubiquitous smartphone usage, facilitating convenient access for patients and clinicians on the go.
The market is experiencing a notable shift from on-premises to cloud-based solutions, reflecting evolving preferences for flexible and cost-efficient infrastructure.
Service Type:
The maturity of service types within video telemedicine ranges from established consultation models to emerging specialized applications. Consultation services form the bedrock of virtual care delivery, addressing a wide range of medical needs.
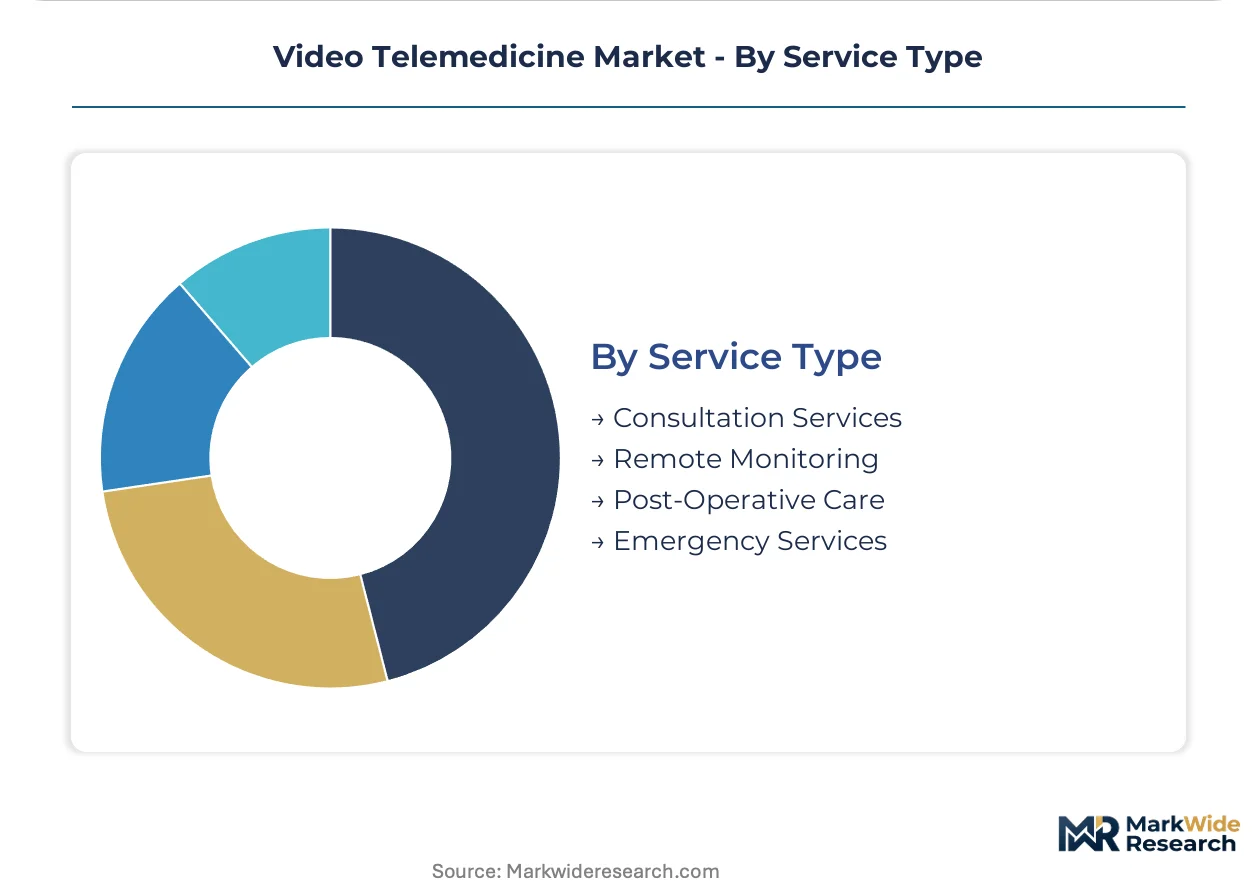
- Consultation Services:This segment encompasses general practitioner visits, specialist referrals, and mental health therapy delivered via live video. It represents the largest service type, driven by convenience and accessibility for routine medical needs across all geographies.
- Remote Monitoring:Telemedicine platforms facilitate continuous oversight of patients with chronic conditions, integrating data from wearable devices and providing alerts. This service type shows significant growth potential, particularly for diabetes and hypertension management.
- Post-Operative Care:Video consultations support recovery by allowing surgeons and specialists to monitor patients remotely, reducing the need for in-person follow-up appointments.
- Emergency Services:Limited but critical applications involve remote assessment and guidance for emergency situations, particularly in rural or underserved areas where immediate physical access to care is challenging.
Consultation Services remain foundational, while Remote Monitoring is strategically important for long-term patient management and preventative care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Expanded digital healthcare infrastructure in India underwrites its pivotal role in the video telemedicine market. This infrastructure facilitates broad patient access and delivery model innovation across the country. Government initiatives support the adoption of mobile-first virtual care solutions in underserved regions.
United States
Healthcare providers in the United States demand robust platforms for remote consultation and chronic disease management. The Health Insurance Portability and Accountability Act (HIPAA) significantly shapes platform security and data handling requirements. Major hospital systems in metropolitan areas, such as New York, drive adoption of scalable, compliant telemedicine solutions.
Germany
National digital health initiatives and reimbursement reforms stimulate market expansion for compliant platforms in Germany. The General Data Protection Regulation (GDPR) mandates strict data privacy and security protocols for all virtual care providers. Digital health startups in Berlin actively develop advanced telemedicine software meeting European Medical Device Regulation (MDR) standards.
India
India's expanding digital infrastructure presents a substantial opportunity for market entry and mobile-first virtual care delivery. National digital health policies encourage patient adoption and provider integration of telemedicine services. Technology hubs like Bengaluru develop innovative, accessible mobile applications for widespread use.
Canada
Health Canada establishes specific guidelines for virtual care delivery and medical device software, influencing platform architecture. Providers seek solutions for remote assessments and specialist referrals, particularly in vast geographic regions. Toronto's healthcare technology cluster focuses on developing integrated platforms for national deployment.
Australia
The Therapeutic Goods Administration (TGA) sets specific regulatory guidelines for virtual care and medical device software in Australia. Demand concentrates on enhancing diagnostic accuracy in remote settings through specialized hardware. Healthcare innovators in Sydney develop integrated telemedicine solutions for both urban and rural populations.
Video Telemedicine Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing essential hardware. The market exhibits a tiered structure, from generic video conferencing tools to specialized integrated clinical systems for advanced diagnostics. Key archetypes include comprehensive software platform providers, specialized medical hardware manufacturers, and mobile application developers. Strategic partnerships and portfolio diversification represent dominant competitive moves among market participants seeking to expand their service offerings.
Within the comprehensive software platform archetype, Cisco Systems Inc. leverages its enterprise networking and security expertise, providing high-bandwidth solutions for large hospital systems. Zoom Video Communications Inc. occupies a position as a scalable software solution provider, integrating easily into existing clinical workflows for broad accessibility. GlobalMed Inc. exemplifies a specialist in integrated hardware and software packages, designed specifically for medical encounters and enhancing diagnostic capabilities in remote settings.
| Leading Market Players |
|---|
| Logitech International |
| Cisco Systems Inc. |
| AMD Global Telemedicine |
| Polycom (Plantronics) |
| Huawei Technologies Co Ltd. |
| Vidyo Inc. |
| GlobalMed Inc. |
| Zoom Video Communications Inc |
| Life-Size Communication Inc. |
| Others |
Cost & Logistics Intelligence
Underutilized cloud infrastructure capacity in leading technology hubs like the United States and Ireland drives both competitive supplier behavior and flexible pricing postures for video telemedicine platforms. This excess capacity allows providers to scale services efficiently without significant capital expenditure, influencing market entry strategies.
Pricing Analysis
Volume-discount tiering structures characterize pricing for video telemedicine software solutions. The dominant pricing model involves SaaS-tiered subscriptions, with costs varying based on user count, feature sets, and data storage requirements. Price differentiation stems from the level of customization needed for EHR integration and the depth of after-sales technical support. Pricing softness reflects intense competition among platform providers, especially for basic consultation tools. Small clinics and individual practitioners exhibit the highest price sensitivity, while large hospital systems prioritize robust features and compliance, showing less elasticity.
Supply Chain Analysis
Named restricted-technology controls on advanced chipsets can limit flows for specialized telemedicine hardware components. Geographic supply concentration for electronic components resides primarily in China and Taiwan, impacting the manufacturing of integrated hardware devices. Key raw material dependencies include high-resolution camera modules, specialized audio processors, and secure data encryption chips. Single-source vulnerability for certain diagnostic peripherals represents a structural supply chain risk. Distribution runs through direct sales channels for large healthcare systems and through online marketplaces or channel partners for smaller clinics and mobile application providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a defensive-moat story, primarily justified by the significant regulatory entrenchment and high switching costs associated with integrated Electronic Health Record (EHR) systems.
For Market Incumbents:Harden core platform offerings by deepening integration with existing hospital EHR systems, creating sticky workflows. Invest significantly in AI-powered diagnostic modules to differentiate from generic video conferencing tools. Prioritize continuous R&D in remote monitoring capabilities for chronic disease management, leveraging regulatory compliance expertise as a competitive lever. This will counter the threat of emerging specialized AI startups.
For New Entrants and Emerging Players:Underpenetrated rural healthcare markets in countries like India present a substantial white-space target. Focus on developing mobile-first, accessible solutions for basic consultations and patient education, bypassing traditional infrastructure. Target niche specialties such as tele-dermatology or tele-ophthalmology with purpose-built applications. A freemium model for basic services, coupled with partnerships with local health non-governmental organizations, offers a viable go-to-market angle.
For Investors and Strategic Acquirers:Capital is best deployed toward acquiring specialized software firms with proven AI diagnostic capabilities or integrated hardware manufacturers enhancing remote examination accuracy. The long-term viability (5-10 year window) of this market remains strong, driven by persistent demand for convenient and accessible healthcare. Broader reimbursement for remote monitoring services and regulatory harmonization across major economies represent the key signals to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen EHR Integration | Enhances platform stickiness within large hospital systems by streamlining clinical workflows and data exchange. |
| Invest in AI Diagnostics | Differentiates offerings by improving diagnostic accuracy and clinical decision support for remote examinations. |
| Expand Remote Monitoring | Captures significant growth potential in chronic disease management and preventative care services. |
| Target Underpenetrated Geographies | Unlocks new patient populations and accelerates adoption of mobile-first virtual care models in emerging markets. |
| Pursue Regulatory Harmonization | Reduces compliance costs and complexity for vendors operating across diverse international healthcare markets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of government health reports, SEC filings of public technology companies, and medical journal articles. This approach combined in-depth interviews with hospital IT directors, telemedicine platform developers, and healthcare policy advisors. Bottom-up and top-down triangulation validated market size estimations and growth projections.
Forecast inputs being considered include digital health policy rollouts, internet penetration rates, and healthcare expenditure trends across the analysis window. The analytical framework modeled segmentation dimensions including product type, end-user, technology, service type, and geographic region. Compound Annual Growth Rates were derived through a comprehensive regression analysis of historical market data and projected future trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized AI startups or major cloud providers would shift outcomes. These projections reflect assumptions regarding technological advancements and regulatory stability. Material shifts in reimbursement policies or major cybersecurity breaches would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Pediatric Telemedicine Market
Telemedicine
North America and Europe Ehealth Market
Telemedicine
Telehealth Services Market
Telemedicine
US Telehealth Market
Telemedicine
Europe Telemedicine Market
Telemedicine
Stroke Telemedicine Services Market
Telemedicine
Telehealth Kiosk Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
GCC Telemedicine Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
Europe Telehealth Service Market
Telemedicine
Global Telepsychiatry Market
Telemedicine
North America Telemedicine Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
Asia-Pacific Ehealth Market