
 Europe Telehealth Service Market | 2026-2036
Europe Telehealth Service Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Telehealth Service Market Insights
France is rewriting telehealth infrastructure norms through national hospital digitization programs. Koninklijke Philips N.V. leverages connected care platforms to sustain chronic disease management contracts across Benelux. Siemens Healthineers AG anchors diagnostic imaging integration into remote consultation workflows. Teladoc Health, Inc. competes on employer-sponsored virtual primary care networks spanning multiple European jurisdictions.
Europe telehealth services encompass real-time clinical interaction, asynchronous data transmission, and remote physiological monitoring delivered through encrypted digital channels with latency thresholds below 150 milliseconds for synchronous video. These systems enable healthcare access extension, specialist shortage mitigation, and acute triage reduction in geographically dispersed populations. Virtual consultations lead service type adoption where reimbursement parity exists, while remote monitoring captures margin pools in cardiology and diabetes management. Mobile health applications represent the fastest-expanding delivery touchpoint among younger patient demographics seeking asynchronous engagement.
EMA medical device guidance, GDPR health data processing requirements, and the EU AI Act risk classification framework collectively determine product certification pathways and cross-border service legality. CE marking under MDR obligates clinical evidence standards for software-as-medical-device platforms, filtering market participants by validation capacity. Stakeholders must monitor national reimbursement catalog updates and interoperability mandate timelines to align platform investments with sustainable revenue models.
Market Dynamics
The EU AI Act risk classification framework is forcing telehealth platforms to re-engineer algorithmic diagnostic modules before enforcement deadlines, compressing product development cycles and raising compliance capital requirements across European health systems.
Growth Catalysts
- GDPR health data processing requirements:Standardized cross-border data flows enable French regional hospital networks to consolidate virtual care procurement at scale.
- Cardiology remote monitoring:Chronic disease management contracts are expanding physiological monitoring deployments in Benelux health systems.
- Germany:Hospital systems are expanding remote patient intake platforms to address specialist shortages in rural Bavaria and Saxony.
Market Restraints
- CE marking under MDR:Clinical evidence standards for software-as-medical-device platforms filter market participants by validation capacity, raising entry barriers.
- Latency thresholds:Synchronous video delivery requires infrastructure maintaining sub-150 millisecond response times, constraining platform architecture choices.
- Reimbursement catalog fragmentation:National variation in virtual consultation parity creates revenue model uncertainty across EU member states.
Strategic Opportunities
- Poland:Underpenetrated regional hospital networks present whitespace for asynchronous data transmission platform deployment.
- EU Green Deal alignment:Virtual care procurement criteria increasingly incorporate carbon footprint reduction metrics, favoring cloud-native platform architectures.
- Mobile health applications:Younger patient demographics in Scandinavia are driving fastest-expanding asynchronous engagement channel adoption.
Industry Challenges
- Interoperability mandate timelines:National health information exchange standards vary across France, Germany, and Italy, complicating cross-border platform scaling.
- Algorithmic audit capabilities:Shortage of clinical AI validation specialists is extending EU AI Act compliance timelines for diagnostic tool vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Telehealth Service Market |
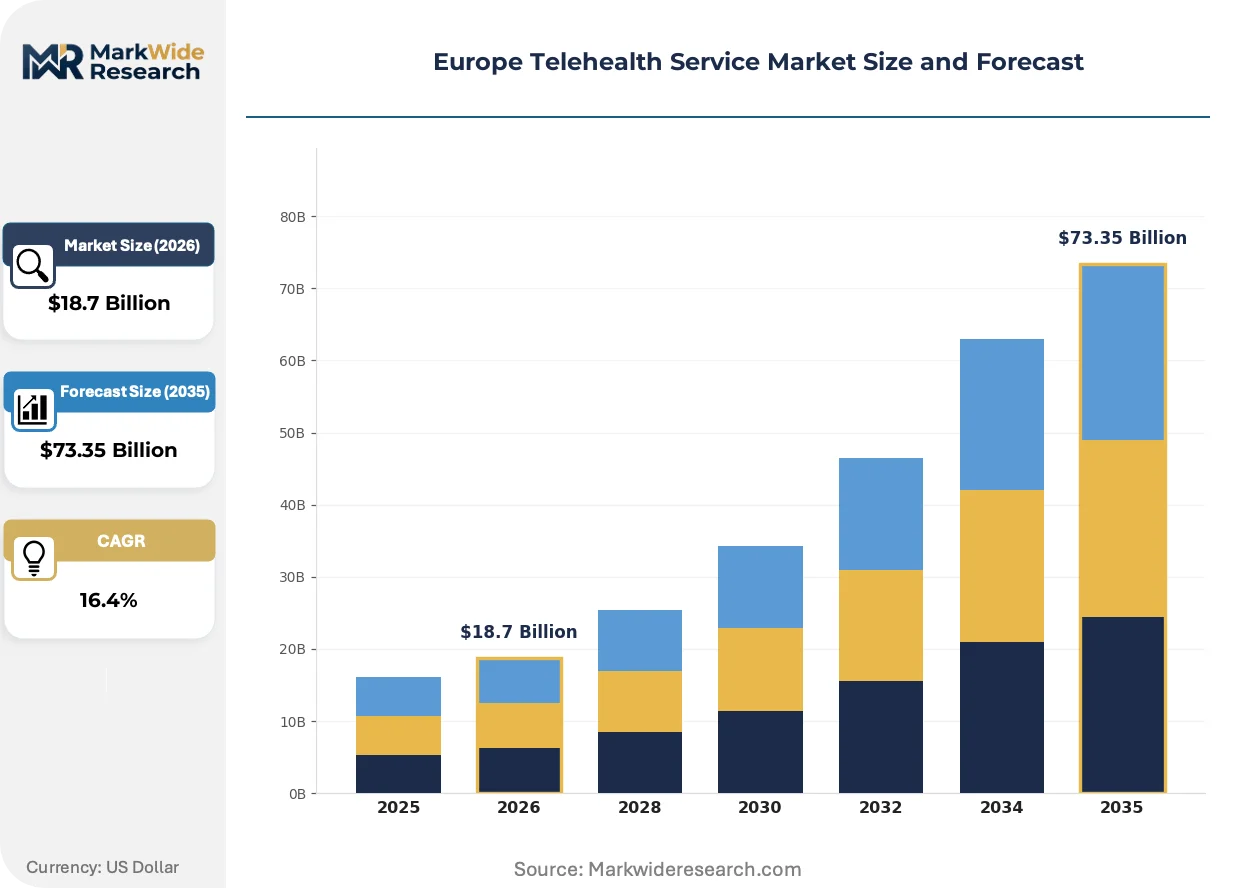
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Virtual Consultations, Remote Monitoring, Mobile Health Applications, Teletherapy Delivery Mode: Web-Based, Mobile-Based, Video Conferencing, Chat End User: Patients, Healthcare Providers, Insurance Companies, Employers Technology: IoT Devices, Artificial Intelligence, Cloud Computing, Blockchain |
| Companies Covered | Koninklijke Philips N.V., Siemens Healthineers AG, Doctolib, Babylon Health, Teladoc Health, Inc., Kry, GE HealthCare Technologies Inc., Medtronic plc, AMD Global Telemedicine, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Telehealth Service Market Trends and Innovations
Telehealth service architecture is converging around encrypted digital channels with embedded diagnostic decision support, reshaping how European health systems extend clinical access beyond traditional facility boundaries.
AI-powered symptom triage engines are digitizing primary care intake workflows across French and German hospital networks. Regional health authorities in Ile-de-France and North Rhine-Westphalia are deploying these tools to compress emergency department diversion times. The technology is digitizing clinical capacity allocation by automating severity stratification before human clinician engagement.
The EU AI Act risk classification framework mandates clinical evidence thresholds for algorithmic diagnostic outputs. MDR obligations now require software-as-medical-device platforms to demonstrate validation data before CE marking approval. Cardiology and diabetes management remote monitoring tools face heightened scrutiny under Class IIa and IIb designations, forcing vendors to restructure quality management systems.
Younger patient cohorts are abandoning scheduled synchronous consultations for asynchronous messaging and automated feedback loops. Employer-sponsored virtual primary care networks in the Netherlands and Belgium are unbundling traditional visit-based reimbursement. This behavioral pivot is most visible in Benelux urban corridors where digital-native consumers dominate commercially insured populations.
Europe Telehealth Service Market Segmentation
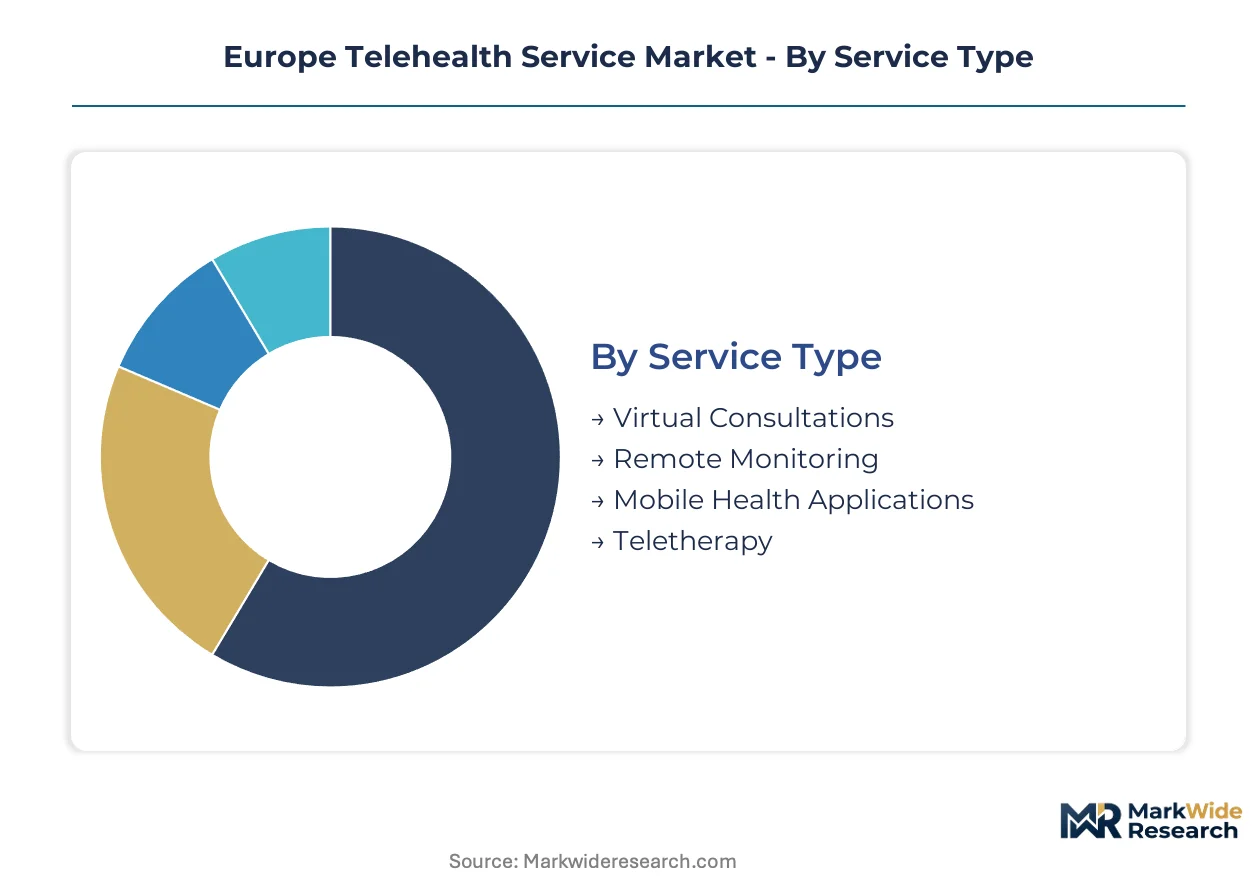
Telehealth service segmentation reveals divergent margin profiles and deployment velocities across European health systems. Understanding these category boundaries enables vendors to align platform investments with reimbursement pathways and regulatory compliance thresholds.
Service Type:
Virtual consultations turn over fastest as transactional encounters, while remote monitoring embeds into multi-year chronic disease contracts.
- Virtual Consultations:Real-time synchronous video encounters between clinicians and patients with sub-150 millisecond latency requirements. Demand concentrates in France where regional hospital networks consolidate procurement under national digitization programs, driven by reimbursement parity mandates.
- Remote Monitoring:Continuous physiological data transmission from implantable or wearable devices to clinical dashboards. Cardiology and diabetes management contracts across Benelux health systems are expanding deployments, constrained by MDR Class IIa and IIb validation requirements.
- Mobile Health Applications:Asynchronous patient engagement tools with automated feedback loops. Younger demographics in Scandinavia are driving steepest adoption curves.
- Teletherapy:Mental health counseling delivered through encrypted digital channels. Germany's rural specialist shortage is accelerating platform procurement in Bavaria and Saxony.
Virtual consultations dominate installed base. Remote monitoring is where expansion concentrates.
Delivery Mode:
Cost tiering separates enterprise-grade video infrastructure from lightweight consumer messaging tools.
- Web-Based:Browser-accessible platforms requiring no local software installation. French regional health authorities prefer these for rapid hospital network deployment.
- Mobile-Based:Native smartphone applications with offline data caching. Netherlands and Belgium employer-sponsored networks are unbundling visit-based reimbursement around this channel.
- Video Conferencing:HIPAA-grade synchronous communication with diagnostic-grade image sharing. GDPR health data processing requirements are standardizing cross-border deployment protocols.
- Chat:Text-based asynchronous triage and follow-up. AI-powered symptom engines in Ile-de-France and North Rhine-Westphalia are digitizing primary care intake workflows.
Video conferencing captures premium pricing. Mobile-based delivery is climbing fastest among digital-native patient cohorts.
End User:
Volume concentration sits with patients, while margin pools accrue to institutional purchasers with multi-year contracting power.
- Patients:Individual consumers accessing direct-to-virtual care services. Urban corridors in Benelux dominate commercially insured demand.
- Healthcare Providers:Hospital systems and physician practices integrating telehealth into clinical workflows. Germany's hospital systems are expanding remote patient intake platforms to address rural specialist gaps.
- Insurance Companies:Payers reimbursing virtual encounters and remote monitoring services. National catalog fragmentation across EU member states creates revenue model uncertainty.
- Employers:Corporations sponsoring virtual primary care as employee benefits. Teladoc Health competes across multiple European jurisdictions for these contracts.
Healthcare providers anchor procurement volume. Employers represent the steepest expansion trajectory in commercially insured segments.
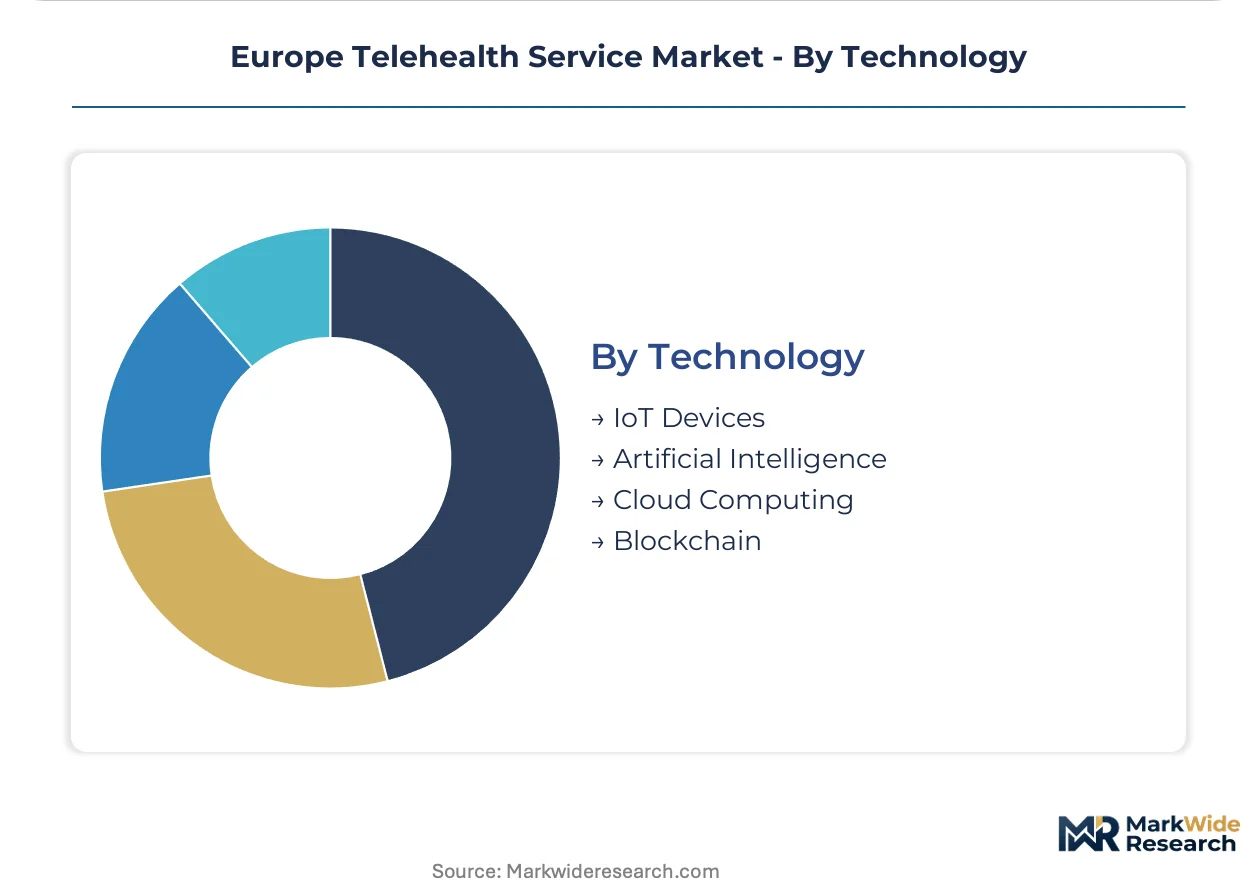
Technology:
Supply concentration clusters around cloud-native architectures that satisfy EU Green Deal carbon footprint criteria.
- IoT Devices:Connected physiological sensors and wearable monitors. Cardiology remote monitoring deployments in Benelux rely on these endpoints.
- Artificial Intelligence:Algorithmic diagnostic modules and symptom triage engines. EU AI Act risk classification is forcing re-engineering before enforcement deadlines.
- Cloud Computing:Scalable infrastructure for encrypted health data storage and transmission. GDPR cross-border data flow standardization is enabling French regional network consolidation.
- Blockchain:Distributed ledger for audit trails and consent management. Clinical evidence standards for software-as-medical-device platforms are filtering adoption by validation capacity.
Cloud computing underpins current deployments. Artificial intelligence is where vendor R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France deploys telehealth predominantly through hospital network consolidation, whereas Germany emphasizes rural specialist access and the Netherlands prioritizes employer-sponsored commercial channels. This consumption-mix differential shapes vendor platform architecture and reimbursement negotiations across the region.
Germany
Hospital systems in Bavaria and Saxony are expanding remote patient intake platforms to address acute rural specialist shortages. The country's national hospital digitization program mandates interoperability standards that compress platform deployment timelines. Berlin-Brandenburg health authorities are piloting AI-powered triage integration into emergency department workflows.
France
Regional hospital networks in Ile-de-France are consolidating virtual care procurement under national digitization mandates. The national pharmaceutical regulator enforces MDR clinical evidence standards for software-as-medical-device platforms. Lyon-based health technology clusters are developing asynchronous data transmission infrastructure for chronic disease management contracts.
Netherlands
Employer-sponsored virtual primary care networks are unbundling traditional visit-based reimbursement models in Randstad urban corridors. GDPR health data processing requirements standardize cross-border deployment protocols for Benelux operations. Eindhoven Region health insurers are negotiating outcome-based contracts for remote physiological monitoring services.
Belgium
Cardiology and diabetes management contracts are expanding physiological monitoring deployments across Flemish and Walloon health systems. The EU AI Act risk classification framework is forcing algorithmic diagnostic module re-engineering before enforcement deadlines. Brussels-based hospital networks are integrating diagnostic imaging into remote consultation workflows.
Poland
Underpenetrated regional hospital networks present whitespace for asynchronous data transmission platform deployment in Warsaw and Kraków metropolitan areas. National reimbursement catalog updates are creating revenue model uncertainty for virtual consultation providers. Silesian health authorities are evaluating cloud-native architectures aligned with EU Green Deal carbon footprint criteria.
Europe Telehealth Service Market Competitive Landscape
Capability concentration sits with specialized health technology developers; scale advantage sits with diversified industrial conglomerates. The vendor base separates into three distinct tiers: medical device incumbents with CE marking validation capacity, pure-play telehealth platforms with reimbursement navigation expertise, and diversified technology conglomerates with cloud infrastructure assets. Dominant competitive moves include strategic partnerships with regional hospital networks and portfolio diversification into chronic disease management contracts.
Within the medical device incumbent tier, Koninklijke Philips N.V. and Siemens Healthineers AG exemplify archetypes with diagnostic imaging integration capabilities. Teladoc Health, Inc. occupies a position among pure-play platforms competing for employer-sponsored contracts across multiple European jurisdictions. These three entities represent distinct strategic postures: Amsterdam-based conglomerate structure, German engineering-focused health technology, and US-originated virtual care specialization.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Siemens Healthineers AG |
| Doctolib |
| Babylon Health |
| Teladoc Health, Inc. |
| Kry |
| GE HealthCare Technologies Inc. |
| Medtronic plc |
| AMD Global Telemedicine |
| Others |
Pricing and Supply Chain Analysis
EU AI Act compliance deadlines compressing product development cycles determine both pricing tier spreads and supply chain shape, as vendors restructure quality management systems to meet Class IIa and IIb validation requirements before enforcement triggers.
Pricing Analysis
Benelux and Scandinavia command 15-25% premiums over Eastern European markets for equivalent telehealth platform deployments. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade hospital network contracts from lightweight employer-sponsored offerings. Cost compression in the standard tier is intensifying because MDR clinical evidence obligations filter market participants by validation capacity. Employer-sponsored networks in the Netherlands exhibit highest price sensitivity, while French regional hospital networks prioritize interoperability certification over unit cost.
Supply Chain Analysis
Cloud infrastructure feeds from hyperscaler data centers concentrated in Ireland, Germany, and the Netherlands, with edge computing nodes expanding into Poland and Spain to meet sub-150 millisecond latency thresholds. IoT sensor manufacturing draws from Taiwan, Germany, and South Korea, while AI training compute relies on NVIDIA GPU supply chains anchored in Taiwan and USA. Single-source vulnerability concentrates in advanced semiconductor components for diagnostic-grade imaging integration. Distribution runs through regional health technology distributors with CE marking validation expertise, bypassing general IT channels for hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe telehealth service expansion constitutes high-growth disruption justified by the EU AI Act risk classification framework forcing algorithmic diagnostic module re-engineering across vendor portfolios.
For Market Incumbents: Harden CE marking validation capacity through backward integration into clinical AI audit capabilities, addressing the shortage of specialists extending compliance timelines. Consolidate cloud-native platform architectures aligned with EU Green Deal carbon footprint criteria to defend procurement positioning in French and German hospital networks against emerging pure-play competitors. For New Entrants and Emerging Players: Establish a beachhead in Poland's underpenetrated regional hospital networks, where asynchronous data transmission platform deployment faces lower competitive density. Target employer-sponsored virtual primary care contracts in Benelux urban corridors, unbundling visit-based reimbursement through mobile-native delivery models that bypass legacy video infrastructure requirements. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward vendors with pre-validated Class IIa and IIb software-as-medical-device platforms. Long-term viability over the next decade hinges on reimbursement navigation expertise across fragmented national catalogs. Monitor national health information exchange standard harmonization timelines as the critical inflection signal for cross-border platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evidence standards filter market participants by validation capacity before platform deployment. |
| Hospital System Partnership | French regional network consolidation under national digitization mandates creates multi-year contract anchors. |
| Software Companion Development | AI-powered symptom triage engines digitize primary care intake workflows across Ile-de-France and North Rhine-Westphalia. |
| Reimbursement Strategy | Navigation of national catalog fragmentation determines revenue model sustainability across EU member states. |
| Platform Integration | Diagnostic imaging integration into remote consultation workflows differentiates Siemens Healthineers and Philips positioning. |
Research Methodology
A standing panel of hospital CIOs, health technology procurement leads, regulatory affairs specialists, and GPO contracts managers provided ongoing calibration across primary interview rounds, validated against EMA medical device guidance documents, GDPR implementation rulings, national reimbursement catalog updates, and hospital procurement database extracts. Bottom-up service type segmentation triangulated against top-down regional market sizing.
Scenario-bracketing framed low, base, and high cases across the projection horizon, modeling adoption curves for virtual consultations, remote monitoring, and mobile health applications by delivery mode, end user archetype, and technology stack. CAGRs derived from segmented volume-to-value conversion with elasticity adjustments for reimbursement parity timing and interoperability mandate compliance.
Stress conditions across EU AI Act enforcement timelines, MDR audit backlogs, and national reimbursement catalog revision cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory acceleration or delay. Cross-checking against hospital capital expenditure disclosures and health insurer benefit design filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
North America Telemedicine Market
Telemedicine
Telemedicine Service Market
Telemedicine
Tele-Care Market
Telemedicine
India Telehealth Services Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
US Telehealth Market
Telemedicine
Tele-Epilepsy Market
Telemedicine
Pediatric Telemedicine Market
Telemedicine
United States Telehealth Pre-Natal Services Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
Global Virtual Care Market
Telemedicine
Healthcare IoT Telemedicine Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
Video Telemedicine Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
Telemedicine Cart Market