
 Telehealth Services Market | 2026-2036
Telehealth Services Market Size, Share, and Industry Trends Forecast 2026-2036
Telehealth Services Market Intelligence
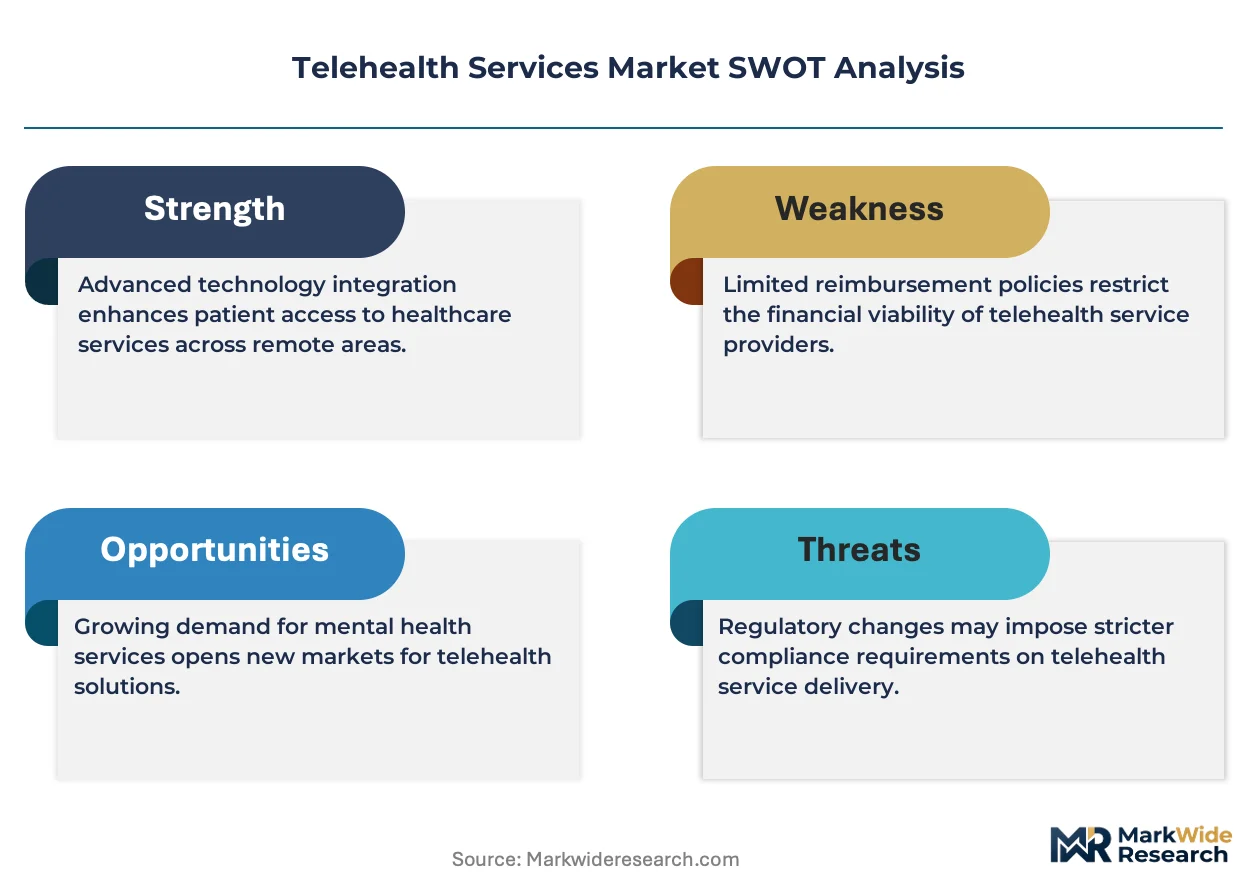
Consolidation among rural hospital networks is repositioning vendor selection criteria toward integrated platforms. Teladoc Health leverages its multi-specialty physician network to anchor enterprise contracts with large health systems. American Well sustains competitive pressure through its white-label infrastructure that lets insurers deploy branded virtual care portals.
Telehealth services encompass real-time and store-and-forward digital delivery of clinical consultation, remote patient monitoring, and therapeutic intervention using video conferencing, mobile platforms, and cloud-hosted infrastructure. These systems transmit encrypted health data between patients and providers to extend care access beyond physical facility boundaries. Virtual consultations currently occupy the largest service-type share, while remote monitoring captures expanding margin pools as chronic disease management programs scale. Wearable devices within the technology segment are accelerating fastest, driven by continuous glucose monitors and cardiac event recorders that feed real-time biometrics into cloud analytics pipelines.
FDA oversight of software-as-a-medical-device and HIPAA security rule enforcement shape platform design requirements and data architecture investments in the United States. State medical boards impose licensing reciprocity constraints that fragment service availability across jurisdictions. Stakeholders must monitor evolving reimbursement parity legislation and cross-border credentialing agreements to anticipate where platform investments will unlock addressable patient populations.
Market Dynamics
Rural hospital consolidation is compressing vendor rosters and forcing platform providers to bundle virtual care, remote monitoring, and analytics into single-contract offerings. This procurement rationalization favors integrated suites over point solutions.
Growth Catalysts
- Medicare reimbursement parity:The US Centers for Medicare & Medicaid Services now reimburses synchronous video visits, asynchronous store-and-forward consultations, and remote physiological monitoring at rates matching in-person care. This payment equivalence removes the primary financial barrier to virtual adoption.
- Continuous glucose monitors:Wearable metabolic sensors from Dexcom and Abbott feed real-time glucose data into cloud-hosted care platforms, enabling endocrinologists to intervene before acute events. Chronic disease management programs are scaling rapidly around this biometrics pipeline.
- State licensing reciprocity compacts:The Interstate Medical Licensure Compact now covers 37 US states, allowing physicians to practice telehealth across member jurisdictions with a single credential. This regulatory harmonization expands addressable patient populations for multi-state health systems.
Market Restraints
- HIPAA security rule compliance:The US Department of Health and Human Services enforces encryption standards, access controls, and audit logging requirements that add 15-25% to platform development costs. Smaller vendors lack capital to build compliant infrastructure.
- State-level licensing fragmentation:Non-compact states maintain independent medical board requirements that force platforms to maintain 50-state credential tracking systems. This jurisdictional complexity limits service availability in holdout states.
- Broadband infrastructure gaps:Rural census tracts with download speeds below 25 Mbps cannot support high-definition video consultations. The Federal Communications Commission maps 14 million unserved rural households where telehealth remains technically infeasible.
Strategic Opportunities
- Behavioral health integration:Psychiatric consultations via video platform show 40% lower no-show rates than in-person appointments. Health systems are embedding virtual behavioral health into primary care workflows to capture this adherence advantage.
- Remote therapeutic monitoring codes:The US introduced new CPT billing codes in 2022 reimbursing providers for monitoring patient-reported outcomes between visits. Platforms that automate outcome collection capture incremental revenue streams.
- AI-enabled clinical decision support:Machine learning models analyzing video consult transcripts and wearable biometrics are unifying diagnostic assistance with care delivery. Early adopters in cardiology and dermatology report 20% faster time-to-diagnosis.
Industry Challenges
- Interoperability with legacy EHR systems:Epic, Cerner, and Meditech installations use incompatible data formats that require costly custom integration layers. Health systems report 12-18 month implementation timelines for seamless virtual care workflows.
- Physician burnout from platform fragmentation:Clinicians toggle between 4-6 distinct applications per patient encounter. Health systems face retention risk as administrative burden from disconnected systems compounds existing workforce strain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telehealth Services Market |
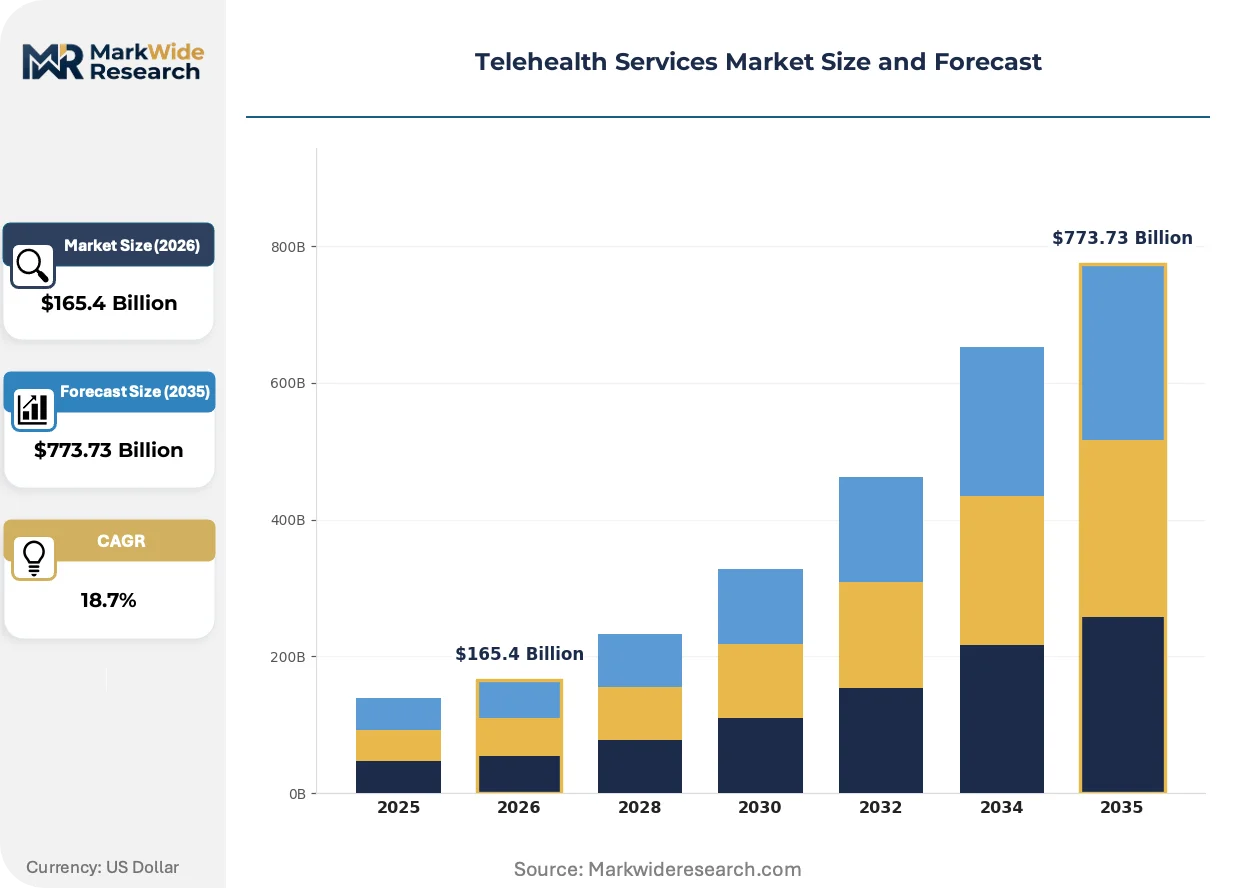
| Market Size in 2026 | $165.4 Billion |
| Market Size in 2035 | $773.73 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Virtual Consultations, Remote Monitoring, Mobile Health Apps, Teletherapy Technology: Video Conferencing, Mobile Platforms, Cloud Services, Wearable Devices End User: Patients, Healthcare Providers, Insurance Companies, Employers Delivery Mode: Asynchronous, Synchronous, Hybrid, On-Demand |
| Companies Covered | Teladoc Health, American Well, MDLIVE, Doctor on Demand, Koninklijke Philips N.V., Siemens Healthineers, Medtronic, GE Healthcare, Cerner Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telehealth Services Market Strategic Shifts & Innovations
Platform architecture is converging around API-first designs that embed virtual care into existing clinical workflows rather than operating as standalone portals. This integration imperative is reshaping competitive positioning toward health system incumbents.
Cloud-native telehealth infrastructure is unifying video, chat, and asynchronous messaging into single-pane clinician interfaces. Large health systems including Kaiser Permanente and Mayo Clinic are migrating from bolt-on virtual platforms to embedded modules within their Epic EHR environments. This consolidation is compressing standalone vendor margins and forcing point-solution providers to pursue white-label partnerships with incumbent EHR vendors.
The US Department of Health and Human Services has intensified HIPAA security rule enforcement through its Office for Civil Rights, issuing 15 resolution agreements in 2023 with penalties exceeding $15 million for encryption failures. Platform providers are responding by shifting from consumer-grade video infrastructure to HITRUST-certified private cloud deployments. Telehealth vendors serving Medicare Advantage populations bear the highest compliance burden as they face concurrent CMS audit scrutiny.
Employer-sponsored health plans are unbundling virtual primary care from traditional insurance contracts and contracting directly with telehealth platforms. This disintermediation is most visible among Fortune 500 technology and financial services firms with self-insured plans. Direct-to-employer sales channels now account for a growing share of new platform revenue, bypassing payer intermediaries that previously controlled distribution.
Telehealth Services Market Segmentation
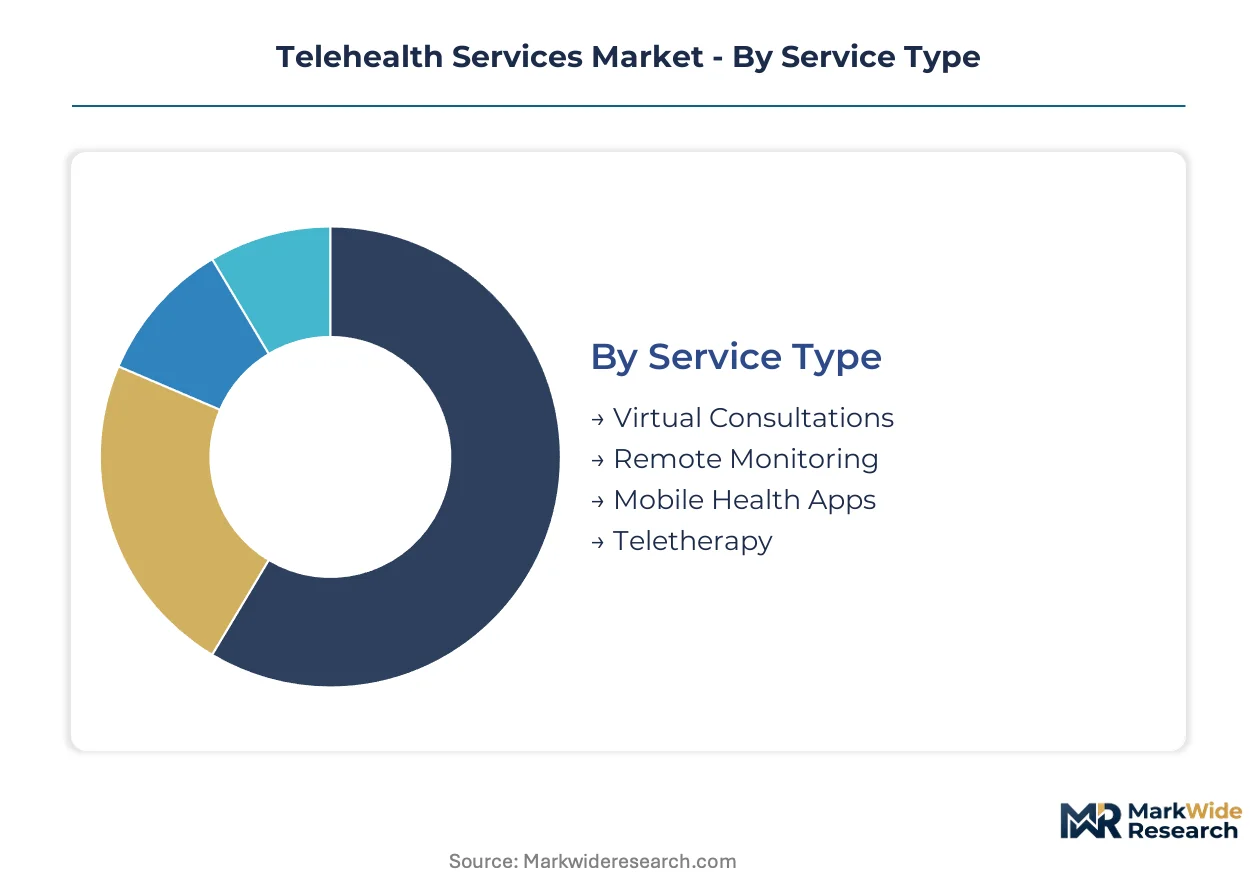
Telehealth services fragment across four intersecting dimensions that determine platform architecture and revenue capture. Service type dictates clinical workflow design, while technology choices shape HIPAA compliance investments. Delivery mode and end user preferences together determine whether vendors pursue enterprise contracts or direct-to-consumer channels.
Service Type:
Virtual consultations command the largest volume share, yet remote monitoring delivers superior margins through recurring revenue structures. Teletherapy and mobile health apps occupy distinct growth trajectories shaped by reimbursement parity and consumer adoption patterns.
- Virtual Consultations:Real-time video and audio encounters between patients and licensed clinicians for diagnosis, prescription, and follow-up care. Demand concentrates among Medicare Advantage populations in Florida, Texas, and Arizona where rural access gaps persist and CMS reimburses at parity with in-person visits.
- Remote Monitoring:Continuous physiological surveillance using connected devices that transmit biometric data to cloud-hosted care platforms. Chronic disease management programs in the United States scale rapidly around continuous glucose monitors and cardiac event recorders, capturing expanding margin pools through monthly per-patient fees.
- Mobile Health Apps:Patient-facing software for appointment scheduling, medication adherence, and symptom tracking. Employers in the self-insured technology sector drive procurement through direct contracts that bypass traditional payer intermediaries.
- Teletherapy:Licensed mental health delivery via secure video platform with documented 40% lower no-show rates than in-person psychiatric appointments. Health systems embed these services into primary care workflows to capture adherence advantages in behavioral health integration.
Today's leader: Virtual Consultations. Tomorrow's challenger: Remote Monitoring.
Technology:
Cloud infrastructure and wearable sensors are gaining share fastest as health systems migrate from bolt-on platforms to embedded EHR modules. Video conferencing retains volume dominance but faces margin compression from commoditization of consumer-grade tools.
- Video Conferencing:HIPAA-compliant encrypted transmission of real-time audio-visual clinical encounters. Epic EHR-embedded modules at Kaiser Permanente and Mayo Clinic displace standalone vendor solutions, compressing point-provider margins and forcing white-label partnerships.
- Mobile Platforms:Native iOS and Android applications enabling patient access across smartphone and tablet devices. Direct-to-employer sales channels among Fortune 500 self-insured plans prioritize native app performance for workforce populations.
- Cloud Services:HITRUST-certified private cloud deployments hosting patient data, analytics pipelines, and clinician interfaces. CMS audit scrutiny for Medicare Advantage populations drives migration from consumer-grade infrastructure to hardened compliance architectures.
- Wearable Devices:Continuous glucose monitors from Dexcom and Abbott, plus cardiac event recorders, feeding real-time biometrics into care platforms. Endocrinology and cardiology practices scale chronic disease programs around this data pipeline.
Cloud Services anchor current procurement decisions. Wearable Devices are climbing the fastest as metabolic and cardiac sensors penetrate Medicare reimbursement codes.
End User:
Healthcare providers and insurance companies dominate contract value, though employers represent the steepest expansion trajectory through disintermediation of traditional payer channels. Patient-facing direct revenue remains limited by out-of-pocket payment friction.
- Patients:Individual consumers accessing telehealth through insurance benefits or direct payment. High-deductible plan holders in the United States show price sensitivity that limits adoption of non-reimbursed services.
- Healthcare Providers:Hospital systems, physician groups, and accountable care organizations procuring enterprise platform licenses. Rural hospital consolidation compresses vendor rosters toward integrated suites bundling virtual care, remote monitoring, and analytics.
- Insurance Companies:Payers deploying white-label virtual care portals through American Well infrastructure and similar vendor partnerships. Medicare reimbursement parity rules now cover synchronous video, asynchronous store-and-forward, and remote physiological monitoring at matching rates.
- Employers:Self-insured corporations contracting directly with telehealth platforms for workforce health benefits. Technology and financial services firms with captive insurance arrangements bypass payer intermediaries that previously controlled distribution.
Healthcare Providers control today's procurement volume. Employers are gaining share fastest through direct platform relationships.
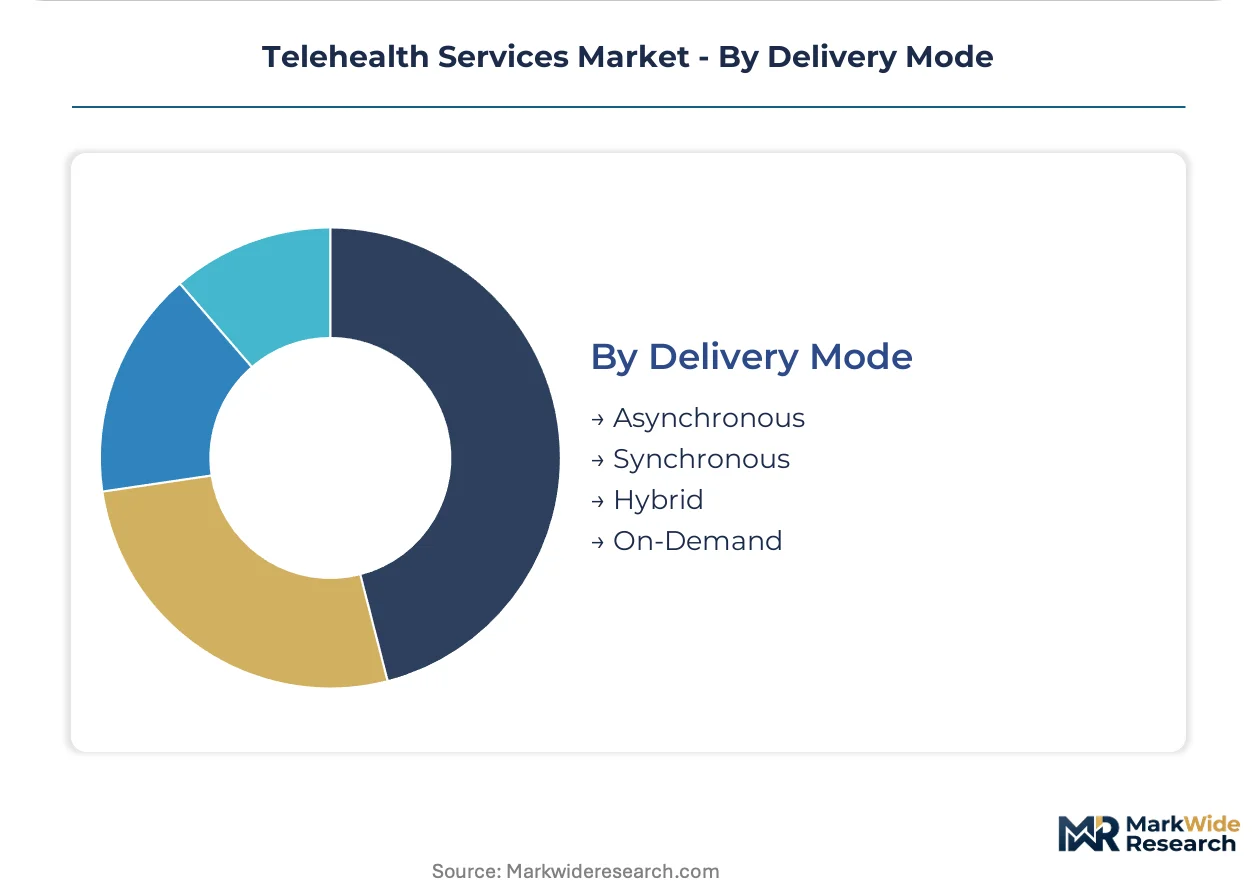
Delivery Mode:
Synchronous delivery captures the majority of current encounters, yet asynchronous and hybrid models are expanding most quickly as state licensing compacts enable multi-jurisdictional practice and store-and-forward reimbursement achieves parity.
- Asynchronous:Store-and-forward transmission of clinical data, images, and patient questionnaires for delayed provider review. The Interstate Medical Licensure Compact covering 37 US states enables dermatology and radiology platforms to aggregate specialist capacity across member jurisdictions.
- Synchronous:Real-time video, audio, or chat encounters requiring simultaneous patient and clinician presence. Primary care and urgent care workflows depend on this mode where immediate diagnostic interaction determines treatment pathways.
- Hybrid:Combined synchronous and asynchronous elements within single care episodes, such as pre-visit questionnaires followed by live consultation. Health systems design these workflows to reduce clinician time per encounter while maintaining reimbursement eligibility.
- On-Demand:Immediate access to available clinicians without scheduled appointments, typically for urgent care or behavioral health crises. Platforms serving this mode maintain 24/7 physician networks with state-specific credential tracking systems.
Synchronous delivery dominates encounter volume. Hybrid models are expanding most quickly as workflow optimization priorities reshape platform design requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands reimbursement parity advantages that Germany and Japan cannot match, while India's platform economics attract capital despite infrastructure gaps. Each geography shapes vendor strategy through distinct regulatory, payment, and connectivity environments.
United States
Medicare Advantage penetration in Florida, Texas, and Arizona drives virtual consultation volume as CMS reimburses synchronous video and remote monitoring at in-person rates. The Department of Health and Human Services enforces HIPAA security rule encryption standards through its Office for Civil Rights, levying penalties exceeding $15 million for compliance failures in 2023. Kaiser Permanente and Mayo Clinic anchor enterprise platform consolidation in California and Minnesota, migrating from standalone vendors to Epic-embedded modules.
Germany
Digital Health Act reimbursement for video consultations expanded patient access beyond statutory insurance restrictions. The Federal Institute for Drugs and Medical Devices oversees software-as-a-medical-device classifications that shape platform architecture investments. Berlin and Munich health networks consolidate procurement around integrated suites, compressing vendor rosters as rural hospital systems seek bundled virtual care and analytics contracts.
Japan
Aging demographics in rural prefectures accelerate remote monitoring adoption for diabetes and cardiovascular disease management. The Ministry of Economy, Trade and Industry promotes cloud infrastructure standards that align with international data portability requirements. Tokyo and Osaka metropolitan health systems lead platform integration, while Kyushu and Hokkaido regions confront broadband gaps that limit high-definition video feasibility.
India
Self-insured technology employers in Bangalore and Hyderabad drive direct-to-platform contracting that bypasses traditional payer channels. The Central Drugs Standard Control Organization regulates software-based medical devices, creating compliance thresholds for foreign vendors. Maharashtra and Telangana state governments deploy telehealth kiosks in rural districts where physician density falls below World Health Organization minimums.
United Kingdom
NHS England's digital-first primary care mandate expanded video consultation capacity following pandemic-era infrastructure investments. The Medicines and Healthcare products Regulatory Agency governs software medical device standards that align with EU MDR transition timelines. London and Manchester health systems consolidate around integrated platforms, while Scotland and Wales negotiate devolved procurement frameworks that fragment vendor access.
Telehealth Services Market Key Industry Players
United States vendors anchor the enterprise contract tier; European medical technology specialists hold hardware-integrated positions. The vendor base stratifies across three tiers: integrated health system platforms, white-label infrastructure providers, and device-linked monitoring services. Two dominant competitive moves reshape positioning: API-first architecture investments that embed virtual care within Epic and Cerner workflows, and direct-to-employer sales channel development that disintermediates traditional payer distribution.
Within the integrated platform tier, Teladoc Health and American Well exemplify divergent archetypes. Teladoc Health represents the multi-specialty physician network model, anchoring enterprise contracts through owned clinician capacity. American Well occupies the white-label infrastructure position, enabling insurer-branded virtual care portals without patient-facing brand presence. MDLIVE sits within the urgent care and behavioral health specialization tier, targeting health systems seeking discrete service line expansion rather than comprehensive platform replacement.
| Leading Market Players |
|---|
| Teladoc Health |
| American Well |
| MDLIVE |
| Doctor on Demand |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Medtronic |
| GE Healthcare |
| Cerner Corporation |
| Others |
Cost & Logistics Intelligence
Rural hospital network consolidation concentrates procurement leverage among integrated health system buyers, forcing platform vendors toward subscription-based SaaS tiers with embedded remote monitoring bundles. This buyer concentration shifts pricing power away from point-solution providers toward vendors offering HIPAA-compliant cloud infrastructure with Epic EHR integration.
Pricing Analysis
Capacity additions in cloud services are reshaping price floors for telehealth infrastructure as AWS and Azure expand HITRUST-certified private cloud availability. Three-tier pricing structure across enterprise, mid-market, and basic levels dominates, with differentiation driven by EHR integration depth and CMS audit readiness. Cost compression in the mid-market tier is intensifying because American Well and similar white-label providers compete on implementation speed. Self-insured employers show highest price sensitivity, while Medicare Advantage health systems prioritize compliance certification over cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for semiconductor components powering wearable glucose monitors and cardiac event recorders. Cloud infrastructure draws from US-based AWS, Azure, and Google Cloud data centers, while video encoding hardware sources from China and Mexico assembly facilities. Tariff exposure on Chinese-manufactured patient-facing tablets creates margin risk for platform vendors. Distribution runs through direct enterprise sales teams for health systems and employer channels, with insurer partnerships serving as secondary route.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Medicare reimbursement parity and HIPAA enforcement are filtering demand toward HITRUST-certified platforms with proven EHR integration. The shift toward premium specifications favors vendors with embedded Epic modules over standalone portals.
For Market Incumbents: Deploy API-first architecture investments to deepen Epic and Cerner workflow embedding before point-solution competitors establish white-label partnerships. Consolidate remote monitoring capabilities through targeted capability acquisition in continuous glucose monitor data analytics, as Dexcom and Abbott device penetration accelerates. Defensive positioning requires preempting employer direct-contracting channels that American Well currently dominates through insurer portal infrastructure. For New Entrants and Emerging Players: The Interstate Medical Licensure Compact covering 37 US states opens a window for asynchronous dermatology and radiology platforms to aggregate specialist capacity across member jurisdictions. Behavioral health integration into primary care workflows represents the most penetrable segment, with documented 40% lower no-show rates creating adherence advantages health systems will pay premium pricing to capture. Go-to-market should target self-insured Fortune 500 technology employers in Bangalore and Hyderabad through direct platform relationships that bypass traditional payer intermediaries. For Investors and Strategic Acquirers: Health system IT departments are the most active acquirer in this space, seeking to consolidate virtual care modules within existing Epic environments rather than managing standalone vendor relationships. Long-term viability favors platforms with demonstrated CMS audit survival and state-level licensing reciprocity infrastructure across compact member states. Acquisition target archetype: remote monitoring specialists with FDA-cleared software-as-a-medical-device classifications and established cardiac event recorder data pipelines. Watch Interstate Medical Licensure Compact expansion to non-member states as the signal for addressable market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Epic EHR Module Embedding | Kaiser Permanente and Mayo Clinic migrations validate embedded virtual care as the dominant procurement specification. |
| HITRUST Cloud Certification | HIPAA security rule enforcement through HHS Office for Civil Rights penalties exceeding $15 million demands hardened infrastructure. |
| Continuous Glucose Monitor Integration | Dexcom and Abbott sensor data feeds enable endocrinology practices to scale chronic disease management programs. |
| Direct-to-Employer Channel Development | Fortune 500 self-insured technology and financial services firms bypass payer intermediaries through captive insurance arrangements. |
| Behavioral Health Workflow Embedding | Psychiatric consultations via video platform demonstrate 40% lower no-show rates than in-person appointments. |
Research Approach
Bottom-up health system procurement modeling reconciled against top-down cloud infrastructure capacity tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, Epic integration specialists, GPO contracts managers, and Medicare Advantage plan executives combined with secondary validation against CMS reimbursement databases, HHS Office for Civil Rights resolution agreements, and Interstate Medical Licensure Compact participation records. Top-down validation draws from AWS and Azure healthcare cloud expansion disclosures alongside FDA software-as-a-medical-device clearance databases.
Input-output matrices map service-type demand flows across virtual consultations, remote monitoring, and teletherapy segments against technology infrastructure availability through the projection horizon. Segmentation dimensions modeled include service type, delivery mode, end-user category, and technology stack, with CAGRs derived from elasticity-adjusted adoption curves reflecting reimbursement parity timing and state licensing reciprocity expansion. Forecast inputs incorporate broadband infrastructure coverage gaps from FCC mapping data and wearable device penetration rates from continuous glucose monitor prescription volumes.
Revisions become necessary when state medical board licensing reciprocity agreements expand or contract, when CMS reimbursement parity rules shift modality coverage, or when HIPAA security rule enforcement intensity changes materially. Forecasts reflect documented assumptions about EHR integration timelines and employer direct-contracting adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Asia-Pacific Ehealth Market
Telemedicine
India Telehealth Services Market
Telemedicine
Tele-ICU Services Market
Telemedicine
Video Telemedicine Market
Telemedicine
Telemedicine Cart Market
Telemedicine
Telemedicine Service Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
Global Online Therapy Services Market
Telemedicine
Global Virtual Care Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
Tele-Epilepsy Market
Telemedicine
Pediatric Telemedicine Market
Telemedicine
Telehealth Software Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
Telemedicine Diagnostic Services Market
Telemedicine
GCC Telemedicine Market