
 Global Telemedicine Market | 2026-2036
Global Telemedicine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telemedicine Market Outlook
Platform licensing revenue is tilting toward subscription-based chronic care models as providers seek predictable cost structures. Teladoc Health Inc. leverages its multispecialty physician network to anchor enterprise contracts with large hospital systems. American Well Corporation competes through white-label infrastructure that lets insurers embed telehealth into existing member portals. Siemens Healthineers extends its imaging hardware dominance into remote diagnostic software, creating captive demand for its device ecosystem.
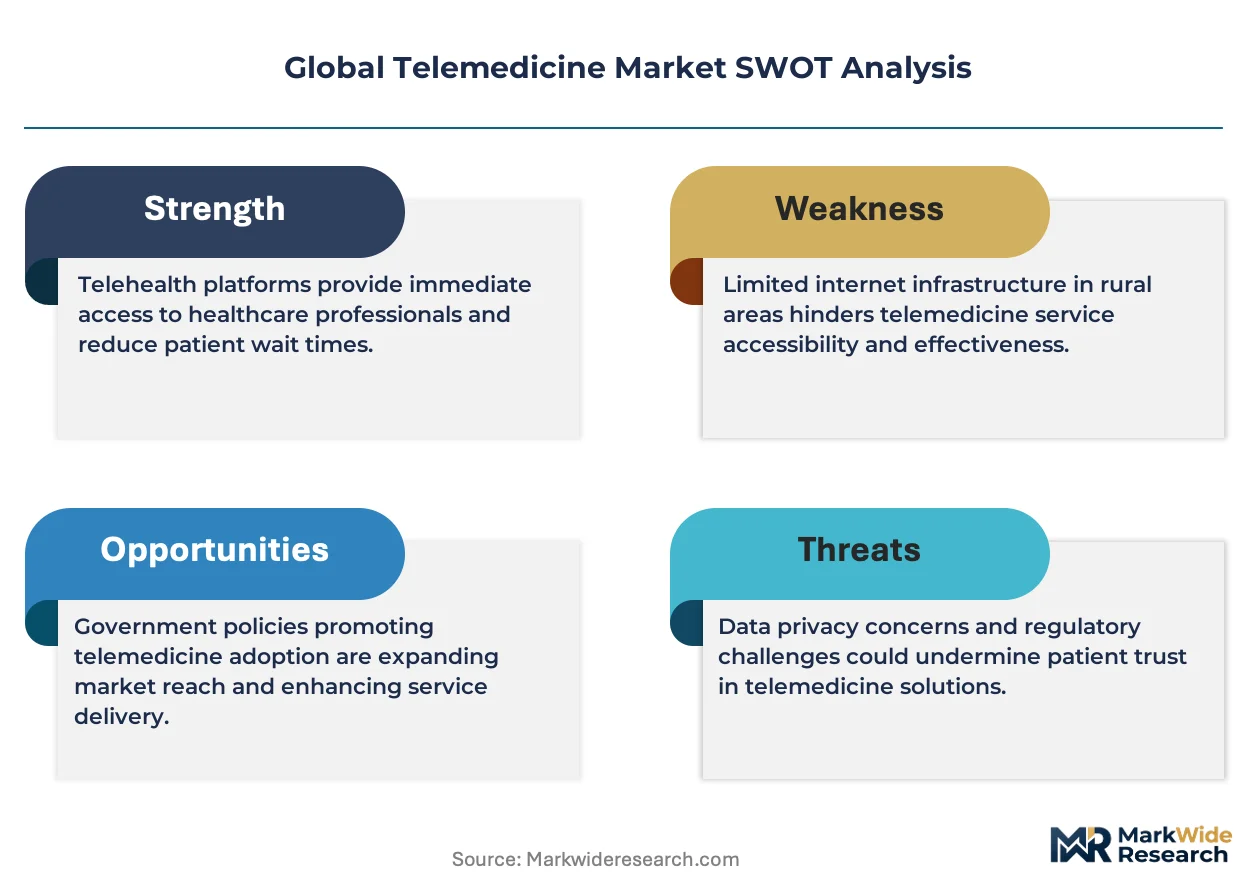
Telemedicine encompasses real-time and asynchronous delivery of clinical services through digital communication channels, typically requiring HIPAA-compliant encryption, minimum bandwidth thresholds of 1.5 Mbps for video, and integration with electronic health record systems to maintain care continuity. Its primary purpose is to extend specialist access to underserved populations while reducing facility overhead. Remote monitoring leads in technology investment as wearable-integrated platforms capture continuous vital streams for heart failure and diabetes management. Mental health services represents the fastest-growing application segment, driven by workforce shortages and reduced stigma around virtual therapy. Cloud-based delivery dominates infrastructure deployment, though on-premises installations persist among defense and prison health systems with strict data sovereignty requirements.
FDA digital health pre-certification and CMS telehealth reimbursement parity directly determine which platforms achieve sustainable provider adoption in the United States, while GDPR and the EU AI Act shape data governance obligations for European deployments. India's Telemedicine Practice Guidelines under the Ministry of Health establish liability frameworks that separate professional medical judgment from platform operator responsibility. Stakeholders must monitor evolving cross-border licensure reciprocity as workforce shortages force jurisdictions to relax geographic restrictions on virtual care delivery.
Market Dynamics
CMS reimbursement parity rules and FDA digital health pre-certification are compressing provider decision cycles, forcing platform vendors to restructure pricing from per-consultation fees toward subscription-based chronic care bundles.
Growth Catalysts
- Rural Hospital Network Expansion:Underserved regions in the United States, India, and Germany are deploying satellite-connected virtual consultation hubs to offset specialist shortages.
- CMS Reimbursement Parity:Medicare payment equivalence between telehealth and in-person visits eliminates financial disincentives for provider adoption across American health systems.
- Wearable-Integrated Remote Monitoring:Continuous vital stream capture for heart failure and diabetes management creates recurring data revenue streams beyond episodic consultations.
Market Restraints
- HIPAA Compliance Infrastructure Costs:End-to-end encryption and audit trail systems impose fixed cost burdens that disproportionately constrain small independent practices.
- Cross-Border Licensure Fragmentation:State-level medical board restrictions in the United States and provincial variations in Canada block seamless interstate virtual care delivery.
- Bandwidth Access Disparities:Minimum 1.5 Mbps video thresholds exclude rural and low-income populations in India and parts of the American South from synchronous consultation services.
Strategic Opportunities
- Mental Health Service Virtualization:Workforce shortages and reduced therapy stigma create unmet demand for asynchronous cognitive behavioral health platforms in Germany and the United States.
- EU AI Act Compliance Services:European telemedicine vendors can monetize algorithmic transparency and bias auditing tools as premium add-ons for risk-averse hospital procurement committees.
- Cloud-to-Edge Infrastructure Migration:Defense and prison health systems with strict data sovereignty requirements present captive markets for on-premises telemedicine installations.
Industry Challenges
- EHR Integration Complexity:Proprietary data formats from Epic, Cerner, and regional systems force costly custom API development for care continuity maintenance.
- Interoperability Standardization Delays:HL7 FHIR implementation gaps between platforms, devices, and hospital IT departments stall enterprise contract finalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telemedicine Market |
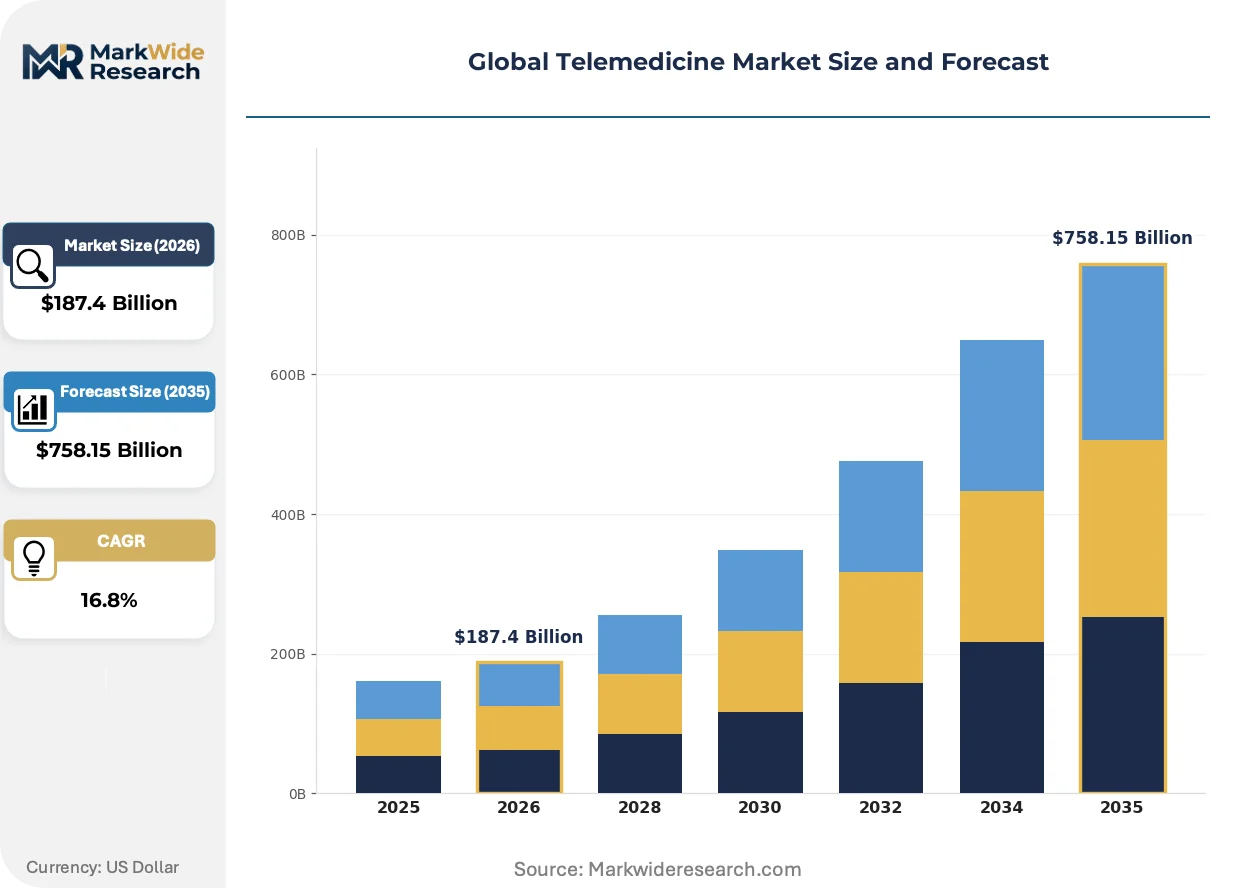
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $758.15 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Video Conferencing, Remote Monitoring, Mobile Health, Store-and-Forward Application: Chronic Disease Management, Consultation, Follow-Up Care, Mental Health Services End User: Hospitals, Healthcare Providers, Patients, Insurance Companies Delivery Mode: Web-Based, App-Based, Cloud-Based, On-Premises |
| Companies Covered | Teladoc Health Inc., American Well Corporation, GE Healthcare, Medtronic, Koninklijke Philips N.V., MDLIVE, Cerner Corporation, Siemens Healthineers, AMD Global Telemedicine Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telemedicine Market Strategic Shifts
Artificial intelligence diagnostic assistance and ambient clinical documentation are compressing physician time-per-consultation while raising quality benchmarks. Platform economics are tilting from transaction fees toward recurring chronic disease management subscriptions.
AI-powered ambient clinical documentation is rendering obsolete manual EHR data entry during video consultations. Large hospital systems in the United States are deploying natural language processing tools that auto-generate structured visit notes from physician-patient dialogue. This technology is rendering obsolete the administrative burden that previously capped daily consultation volumes.
The EU AI Act's risk classification system for medical decision-support algorithms is forcing European telemedicine platforms to reengineer their AI governance frameworks. High-risk diagnostic tools now require conformity assessments and post-market monitoring that extend product launch timelines. German hospital procurement committees are prioritizing vendors with established CE-marked AI components to preempt regulatory liability.
Employer-sponsored telehealth benefits are consolidating purchasing power among Fortune 500 human resource departments. Traditional per-employee-per-month pricing is giving way to outcome-based contracts tied to emergency department visit reduction metrics. This shift is most visible in the United States, where self-insured employers in manufacturing and logistics sectors demand hard dollar savings verification.
Global Telemedicine Market Segmentation
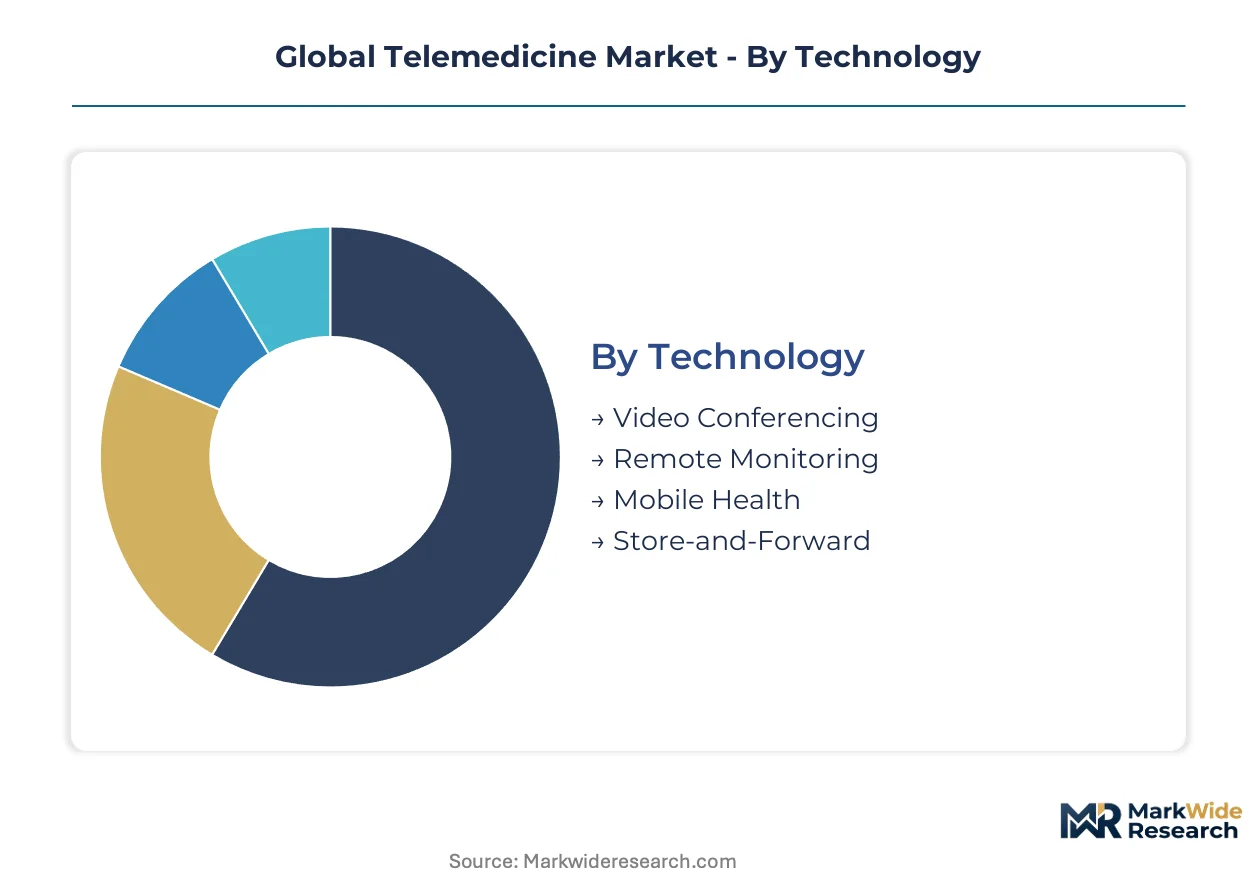
Technology modality determines reimbursement eligibility and infrastructure investment requirements across health systems. Application focus shapes platform architecture and regulatory compliance obligations. Understanding these dimensions reveals where capital is concentrating and which segments face margin compression.
Technology:
Technical architecture governs bandwidth requirements, device integration depth, and revenue model viability across deployment scenarios.
- Remote Monitoring:Wearable-integrated platforms capture continuous vital streams for heart failure and diabetes management. German hospital networks and American accountable care organizations are standardizing on these systems to reduce emergency department utilization.
- Video Conferencing:Real-time synchronous consultation requires minimum 1.5 Mbps bandwidth and HIPAA-compliant encryption protocols. Rural hospital networks in the United States and satellite-connected hubs in India deploy this technology to offset specialist shortages.
- Mobile Health:Smartphone-native applications enable asynchronous symptom tracking and medication adherence programs.
- Store-and-Forward:Asynchronous image and data transmission supports dermatology and radiology workflows without real-time physician availability.
Remote Monitoring holds installed capacity. Video Conferencing is rotating up the share rankings.
Application:
Clinical use case dictates platform certification requirements, physician specialty integration, and pricing structure complexity.
- Mental Health Services:Asynchronous cognitive behavioral therapy platforms address workforce shortages and reduced therapy stigma. Demand concentrates in Germany and the United States where employer-sponsored benefits are consolidating purchasing power.
- Chronic Disease Management:Subscription-based care bundles for diabetes and cardiovascular conditions generate recurring revenue beyond episodic consultations. CMS reimbursement parity rules are accelerating provider adoption of these models.
- Consultation:Acute symptom assessment and specialist referral routing.
- Follow-Up Care:Post-discharge monitoring and surgical recovery tracking.
Chronic Disease Management holds installed capacity. Mental Health Services is climbing the fastest.
End User:
Customer type determines procurement authority, budget cycle timing, and integration complexity with existing health IT infrastructure.
- Hospitals:Enterprise contracts demand EHR integration with Epic and Cerner systems plus HL7 FHIR interoperability. Large American health systems are deploying natural language processing tools for ambient clinical documentation.
- Healthcare Providers:Individual and group practice subscriptions prioritize low-friction onboarding and minimal IT support requirements. HIPAA compliance infrastructure costs disproportionately constrain small independent practices.
- Patients:Direct-to-consumer payment models bypass insurance preauthorization.
- Insurance Companies:White-label platform licensing embeds telehealth into existing member portals.
Hospitals hold installed capacity. Healthcare Providers is rotating up the share rankings.
Delivery Mode:
Infrastructure deployment choice reflects data sovereignty requirements, capital expenditure constraints, and scalability priorities.
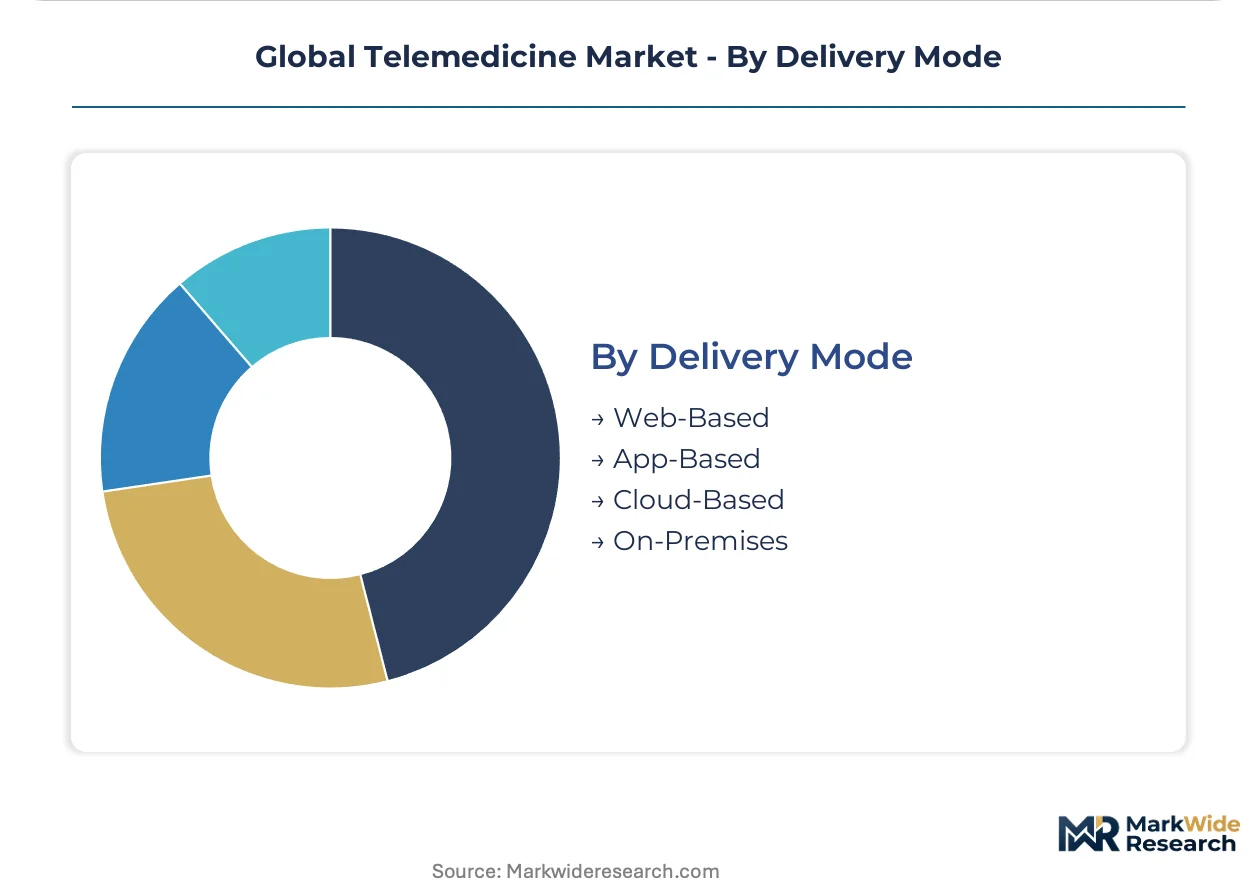
- Cloud-Based:Scalable infrastructure dominates deployment with automatic updates and reduced IT overhead. German hospital procurement committees prioritize vendors with EU AI Act compliance frameworks.
- On-Premises:Local server installations serve defense and prison health systems with strict data sovereignty requirements. These captive markets demand specialized security clearances and physical infrastructure.
- Web-Based:Browser-accessible platforms eliminate app store dependencies.
- App-Based:Native mobile applications enable push notifications and device sensor integration.
Cloud-Based holds installed capacity. On-Premises is gaining share fastest among regulated environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telemedicine deployment patterns diverge sharply by geography. The United States prioritizes chronic disease management subscriptions, Germany emphasizes AI governance compliance, and India scales satellite-connected rural hubs despite bandwidth constraints.
United States
Employer-sponsored benefits and Medicare reimbursement parity drive enterprise contract consolidation. FDA digital health pre-certification and CMS telehealth parity rules compress provider procurement cycles. Large hospital systems in Texas and the Midwest deploy ambient clinical documentation tools to expand daily consultation volumes.
Germany
Hospital procurement committees demand CE-marked AI components and EU AI Act conformity assessments. The country's national pharmaceutical regulator enforces post-market monitoring for high-risk diagnostic algorithms. Bavarian health networks standardize on wearable-integrated remote monitoring platforms to reduce emergency department utilization.
India
Satellite-connected virtual consultation hubs address specialist shortages in underserved districts. The Ministry of Health's Telemedicine Practice Guidelines establish liability frameworks separating medical judgment from platform operator responsibility. Telangana and Karnataka health clusters scale asynchronous mobile health applications for medication adherence programs.
United Kingdom
NHS integrated care systems consolidate purchasing power for white-label telehealth infrastructure. GDPR and MHRA guidance shape data governance obligations for cloud-based deployments. London and Greater Manchester health innovation clusters pilot natural language processing tools for administrative burden reduction.
Australia
Rural health networks leverage store-and-forward technology for dermatology and radiology workflows. The Therapeutic Goods Administration regulates software as a medical device under risk-based classification. Queensland and Western Australia deploy video conferencing infrastructure to offset specialist shortages in remote communities.
Global Telemedicine Market Competitive Environment
Capability concentration sits with specialized telehealth platforms; scale advantage sits with diversified health technology conglomerates. The market structures around three tiers: pure-play virtual care providers, diversified medical device manufacturers extending into software, and health IT vendors embedding telehealth into existing infrastructure. Dominant competitive moves include strategic partnerships with hospital systems and portfolio diversification into chronic disease management subscriptions.
Among pure-play telehealth specialists, Teladoc Health Inc. and American Well Corporation exemplify contrasting platform strategies. Teladoc anchors enterprise contracts through multispecialty physician network scale. American Well occupies a position enabling insurer white-label integration. Siemens Healthineers represents the diversified manufacturer archetype, extending imaging hardware dominance into remote diagnostic software to create captive demand for its device ecosystem.
| Leading Market Players |
|---|
| Teladoc Health Inc. |
| American Well Corporation |
| GE Healthcare |
| Medtronic |
| Koninklijke Philips N.V. |
| MDLIVE |
| Cerner Corporation |
| Siemens Healthineers |
| AMD Global Telemedicine Inc. |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure concentration in the United States and Germany anchors margin distribution downstream, with hyperscale data center operators capturing fixed-cost efficiencies that telemedicine platforms pass through as subscription tiers. Hospital procurement committees and employer benefits administrators sit at opposing ends of price sensitivity, forcing vendors to stratify offerings around EHR integration depth rather than core consultation features.
Pricing Analysis
Long-term enterprise subscriptions dominate contract structures, with hospital systems negotiating three-to-five-year bundled agreements for chronic care management platforms. Price differentiation centers on HL7 FHIR interoperability certification and ambient clinical documentation capabilities, with premium tiers commanding substantial uplifts for AI-powered diagnostic assistance. Cost compression in the small-practice segment is intensifying because HIPAA compliance infrastructure imposes fixed burdens that per-physician pricing cannot absorb. Employer-sponsored benefits departments exhibit lowest price sensitivity, prioritizing outcome-based contracts tied to emergency department reduction metrics over per-employee-per-month economics.
Supply Chain Analysis
Contract manufacturing for telemedicine endpoints concentrates with Foxconn, Jabil, and Flex operating assembly capacity across China, Mexico, and Malaysia. Component sourcing draws from Taiwanese semiconductor foundries for video encoding chipsets, South Korean display manufacturers for clinical-grade monitors, and Japanese sensor suppliers for wearable-integrated remote monitoring devices. Single-source vulnerability in cloud infrastructure creates exposure to regional data sovereignty restrictions. Distribution runs through health system IT procurement channels and insurance carrier technology integration teams rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in telemedicine are tilting toward ecosystem control, with HL7 FHIR interoperability and ambient clinical documentation capabilities determining which vendors capture enterprise contract renewals. The shift from transactional consultation fees to subscription-based chronic disease management bundles rewards first-movers with integrated EHR workflows.
For Market Incumbents: Build switching-cost moats through deep Epic and Cerner EHR integration that embeds ambient clinical documentation into physician workflow habits. Defensive moves should prioritize CE-marked AI component certification for EU AI Act compliance and captive wearable device ecosystems that lock in continuous vital stream data revenue. Ambient documentation specialists represent the most credible substitute threat to incumbent platform margins.
For New Entrants and Emerging Players: Mental health service virtualization in Germany and employer-sponsored benefits administration in the United States represent the most penetrable entry points for platform-native vendors without legacy infrastructure debt. Asynchronous cognitive behavioral therapy platforms targeting workforce shortage regions bypass real-time bandwidth constraints that disadvantage synchronous competitors. Go-to-market positioning through white-label licensing to regional insurers avoids direct enterprise sales cycle competition with established multispecialty networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed telehealth platforms that expanded rapidly during reimbursement parity expansion but lack AI governance frameworks for EU market access. Long-term viability across a five-to-ten year window favors vendors with demonstrated hospital system partnership density and recurring revenue concentration above episodic consultation dependency. Watch for CMS reimbursement parity rule modifications as the critical inflection signal for platform revenue model sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Epic and Cerner EHR integration creates captive demand for ambient clinical documentation tools. |
| CE Marking Pathway | EU AI Act conformity assessments unlock German hospital procurement committee vendor shortlists. |
| Reimbursement Strategy | CMS telehealth parity alignment determines Medicare payment eligibility for chronic care bundles. |
| Software Companion Development | Wearable-integrated remote monitoring platforms capture continuous vital streams beyond episodic visits. |
| Platform Integration | White-label infrastructure licensing embeds telehealth into insurer member portals without custom development. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital CIOs, telemedicine platform product managers, employer benefits directors, and CMS policy specialists. Secondary validation drew from FDA digital health pre-certification filings, CMS Medicare claims data, hospital procurement databases, and EU AI Act implementation guidance documents. Bottom-up platform revenue modeling triangulated against top-down health system IT spending forecasts.
Calibration against historical reimbursement rule changes and technology adoption curves anchored projection reliability across the modeling period. Segmentation dimensions modeled include technology modality, clinical application, end-user type, and delivery infrastructure deployment. CAGRs were derived from spline interpolation between anchor points with cross-validation against analogous digital health market maturation patterns. Forecast inputs incorporated wearable device shipment trajectories and cloud infrastructure capex disclosures from hyperscale operators.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement policy, EU AI Act enforcement intensity, or cloud infrastructure pricing would shift the trajectory. Forecasts reflect documented assumptions around bandwidth access expansion and cross-border licensure reciprocity evolution. Quarterly review of CMS rulemaking dockets and EU conformity assessment body capacity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telemedicine Cart Market
Telemedicine
AI in Telemedicine Market
Telemedicine
US Virtual Care Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
GCC Telemedicine Market
Telemedicine
US Telemedicine Market
Telemedicine
Next Generation Telehealth Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
Telemedicine Diagnostic Services Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
Pediatric Telemedicine Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
Global Telepsychiatry Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
Asia-Pacific Ehealth Market