
 Global Online Therapy Services Market | 2026-2036
Global Online Therapy Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online Therapy Services Market Foresight
The employer-to-employee benefits channel is reshaping how online therapy services reach end users, with large organizations contracting directly for workforce mental health coverage. BetterHelp leverages its direct-to-consumer brand strength to sustain subscription volumes outside institutional procurement cycles. Talkspace anchors its competitive position through in-house production of licensed clinician networks, controlling therapist supply quality at scale. Teladoc Health extends its telemedicine infrastructure into behavioral health, occupying a hybrid medical-mental health niche that competitors navigate with narrower specialization.
Online therapy services encompass digitally delivered psychological and psychiatric interventions conducted through synchronous or asynchronous communication technologies, typically requiring encrypted platforms that comply with clinical privacy standards and maintain session continuity across devices. The primary commercial purpose is to democratize access to licensed mental health professionals while reducing geographic and scheduling barriers that constrain traditional in-office practice. Cognitive behavioral therapy dominates service type revenue due to its structured protocol suitability for digital delivery and measurable outcomes that satisfy employer-sponsored program administrators. Video conferencing leads delivery model adoption among adults seeking synchronous clinician relationships, while mobile apps capture fastest-growing demand among adolescents and students accustomed to smartphone-native interfaces. Subscription-based payment models concentrate margin pools through predictable recurring revenue, though insurance-covered segments expand total addressable market by aligning with existing reimbursement infrastructure.
The FDA exercises oversight over digital therapeutics with clinical claims in the United States, while HIPAA mandates encryption and access controls that shape platform development costs for all vendors serving American patients. Europe's GDPR imposes cross-border data localization requirements that fragment cloud architecture for services operating in multiple member states, with the EU AI Act adding algorithmic transparency obligations for platforms deploying automated intake or triage tools. Stakeholders must monitor evolving state-level licensure compacts that determine whether therapists can legally serve clients across jurisdictional boundaries, as regulatory clarity on interstate practice will determine which platforms can achieve national scale without duplicating credentialing infrastructure.
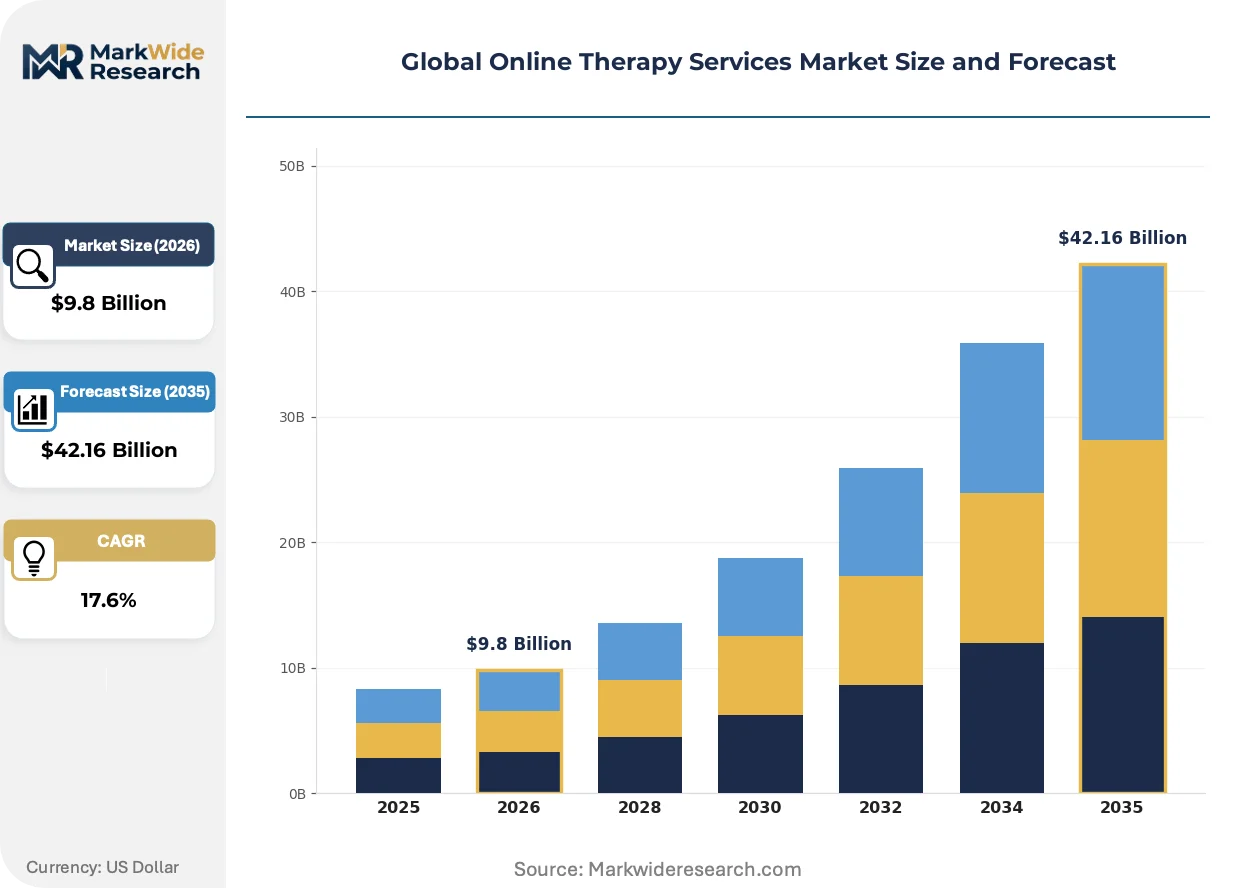
Market Dynamics
Employer-sponsored digital mental health procurement is concentrating demand into multi-year enterprise contracts, reshaping platform economics away from individual subscription models toward population-scale pricing and outcome guarantees.
Growth Catalysts
- HIPAA Encryption Mandates:US federal privacy requirements drive platform investment in end-to-end encrypted video infrastructure, creating certified vendor ecosystems that accelerate enterprise adoption through reduced procurement risk.
- Corporate Wellness Expansion:Large employers across Germany, the United Kingdom, and the United States now contract directly for workforce mental health coverage, channeling reimbursement through existing benefits administration.
- Smartphone-Native Interfaces:Asynchronous messaging and mobile-first intake flows capture adolescent and student populations accustomed to text-based communication, expanding addressable demographics beyond traditional telehealth users.
Market Restraints
- GDPR Cross-Border Fragmentation:EU data localization requirements force cloud architecture duplication across member states, elevating operational costs for platforms serving multiple European markets.
- Licensed Clinician Supply Concentration:Therapist credentialing remains jurisdiction-locked, preventing platforms from achieving national scale without replicating in-house licensing infrastructure state-by-state.
- Synchronous Bandwidth Limitations:Rural broadband gaps in Australia, Canada, and parts of the United States exclude patient populations most in need of geographic barrier removal.
Strategic Opportunities
- Brazil and Mexico Underpenetration:Latin American markets lack established reimbursement frameworks, creating first-mover advantage for platforms building direct-pay models before insurance integration matures.
- AI-Assisted Triage Convergence:Natural language processing and clinical decision support tools hybridize to automate intake severity assessment, reducing clinician time spent on administrative screening.
- India Mental Health Access Gap:Psychiatrist concentration in urban centers leaves 70% of districts without specialists, positioning asynchronous platforms to address supply-demand asymmetry through tiered provider models.
Industry Challenges
- Interstate Licensure Compacts:US state-level regulatory fragmentation forces platforms to maintain redundant credentialing systems, complicating therapist workforce deployment across jurisdictions.
- Outcome Measurement Standardization:Employer sponsors demand validated clinical metrics, yet no consensus framework exists for comparing effectiveness across CBT, DBT, and psychodynamic modalities delivered digitally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online Therapy Services Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $42.16 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cognitive Behavioral Therapy, Psychodynamic Therapy, Humanistic Therapy, Family Therapy, Group Therapy, Solution-Focused Brief Therapy Delivery Model: Video Conferencing, Telephone Therapy, Mobile Apps, Text Messaging, Email Counseling, Virtual Reality Therapy End User: Adolescents, Adults, Elderly, Couples, Military Veterans, Students Payment Model: Subscription-Based, Pay-Per-Session, Insurance Covered, Employer Sponsored, Free Services, Sliding Scale Fees |
| Companies Covered | BetterHelp, Talkspace, Teladoc Health, Amwell, Lyra Health, Cerebral, Wysa, Doctor on Demand, Calmerry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online Therapy Services Market Shifts & Advancements
Platform architecture is bifurcating between synchronous video fidelity and asynchronous scalability, with vendor investment flowing toward hybrid delivery models that preserve clinical relationship depth while capturing efficiency gains.
Natural language processing is hybridizing with encrypted session transcription to generate real-time clinical documentation, reducing administrative burden on licensed therapists. Large employer contracts in the United States and Germany now mandate such automation as a condition of population health pricing. The technology compresses per-session labor costs while raising HIPAA compliance complexity around stored conversation data.
The EU AI Act imposes algorithmic transparency obligations on platforms deploying automated intake or triage tools, requiring explainability documentation for clinical decision-support systems. European vendors must maintain audit trails for AI-driven severity assessments that determine patient routing. France and Germany are responding with specialized legal engineering functions that US and Asian competitors have not yet replicated.
Benefits administrators are consolidating vendor selection into centralized procurement functions, displacing decentralized HR-led purchasing that previously allowed multiple point solutions. Large self-insured employers in the United States now demand single-platform accountability for utilization rates and clinical outcomes. This concentration shifts negotiation leverage toward buyers capable of steering tens of thousands of covered lives.
Global Online Therapy Services Market Segmentation
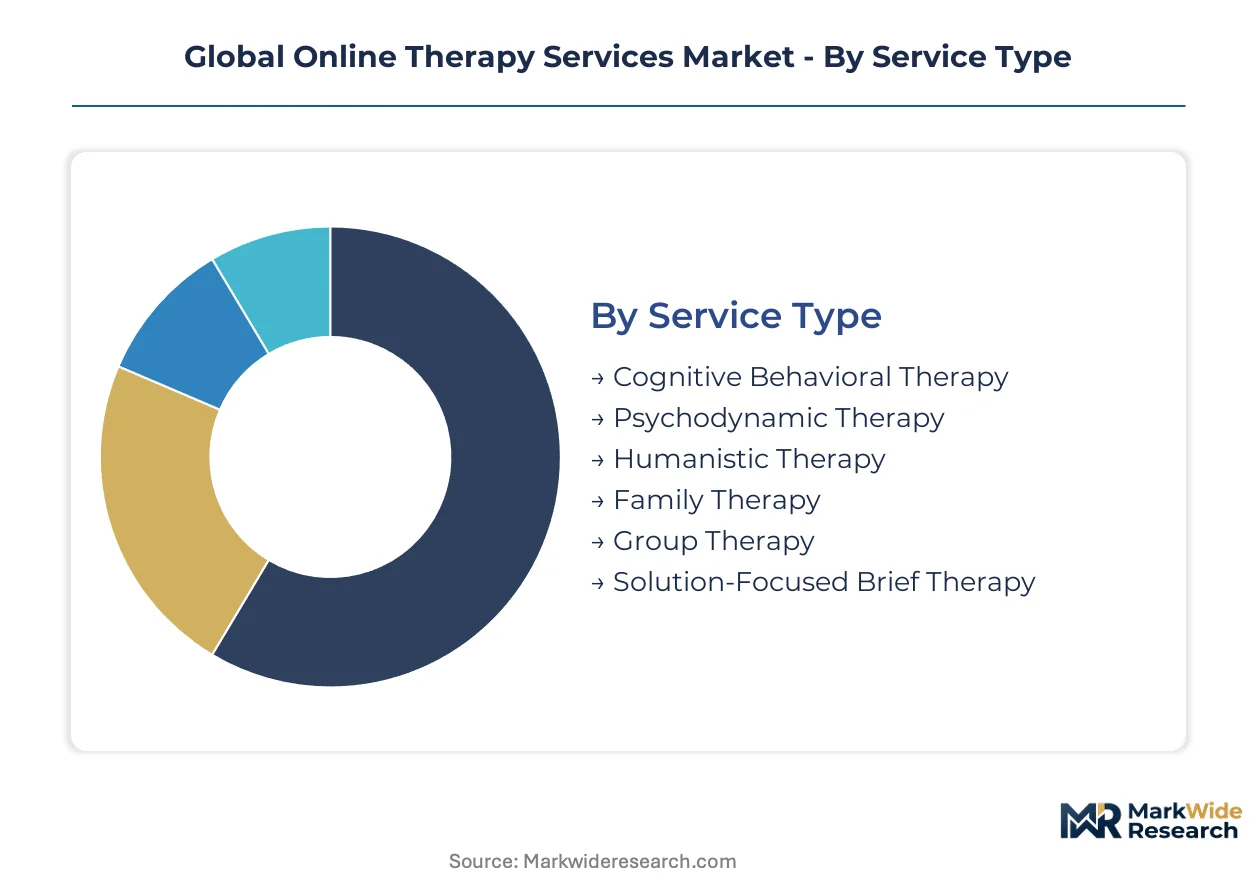
Online therapy services fragment across multiple dimensions that determine platform architecture, reimbursement pathways, and clinical workforce requirements. Each segmentation axis reveals distinct competitive battlegrounds where vendor specialization and regulatory compliance intersect.
Service Type:
The use-case spectrum spans from structured, protocol-driven interventions to relationship-centered approaches that resist digitization.
- Cognitive Behavioral Therapy:Structured protocols with measurable homework assignments and symptom tracking translate cleanly into digital workflows. Employer-sponsored programs in the United States and Germany concentrate procurement here due to validated outcome metrics that satisfy benefits administrators.
- Psychodynamic Therapy:Long-term therapeutic relationships emphasizing unconscious processes and transference dynamics demand sustained synchronous engagement. Demand clusters among higher-income individual subscribers in urban centers where traditional in-office access remains constrained by therapist supply shortages.
- Humanistic Therapy:Client-centered approaches emphasizing empathy and unconditional positive regard adapt moderately well to video formats.
- Family Therapy:Multi-participant sessions require sophisticated platform features for managing concurrent video streams and household privacy.
- Group Therapy:Cost efficiency through shared clinician time attracts institutional purchasers seeking population-scale coverage.
- Solution-Focused Brief Therapy:Short-term goal orientation aligns with employer demands for rapid return-to-work outcomes.
The dominant share belongs to Cognitive Behavioral Therapy, while Solution-Focused Brief Therapy is closing the gap fastest.
Delivery Model:
Technical infrastructure investments diverge sharply between real-time fidelity requirements and asynchronous scalability economics.
- Video Conferencing:HIPAA-compliant end-to-end encryption and low-latency streaming dominate enterprise procurement specifications in the United States. Large employer contracts now mandate 99.9% uptime SLAs and multi-device session continuity.
- Mobile Apps:Smartphone-native interfaces with asynchronous messaging capture adolescent and student demographics in India and Brazil where desktop penetration lags. These platforms reduce per-session infrastructure costs while expanding addressable populations beyond traditional telehealth users.
- Telephone Therapy:Audio-only delivery persists in rural broadband gaps across Australia and Canada.
- Text Messaging:Asynchronous written exchange enables therapist multitasking and extended availability windows.
- Email Counseling:Delayed-response formats serve time-zone dispersed populations and written-expression preferences.
- Virtual Reality Therapy:Immersive exposure environments for phobia and PTSD treatment require specialized hardware integration.
Video Conferencing commands the largest revenue pool, though Mobile Apps are expanding most quickly among younger demographics.
End User:
Demographic targeting shapes platform design priorities from crisis intervention protocols to age-appropriate interface conventions.
- Adults:The primary revenue base for synchronous video counseling, with demand concentrated among employed populations accessing employer-sponsored benefits. Platform features emphasize scheduling flexibility and insurance integration.
- Adolescents:School-based programs and parental consent workflows drive specialized platform requirements. Text-first interfaces and gamified engagement mechanics distinguish youth-focused offerings in the United Kingdom and United States.
- Elderly:Simplified navigation and telephone fallback options address technology adoption barriers.
- Couples:Joint session architecture and conflict-sensitive intake protocols require distinct platform modules.
- Military Veterans:Trauma-informed design and VA integration specifications create dedicated vendor ecosystems.
- Students:Campus counseling partnerships and academic calendar alignment shape procurement in higher education.
Adults retain the dominant share, while Students are gaining share fastest through university procurement consolidation.
Payment Model:
Revenue stability versus market expansion tradeoffs define competitive positioning across reimbursement architectures.
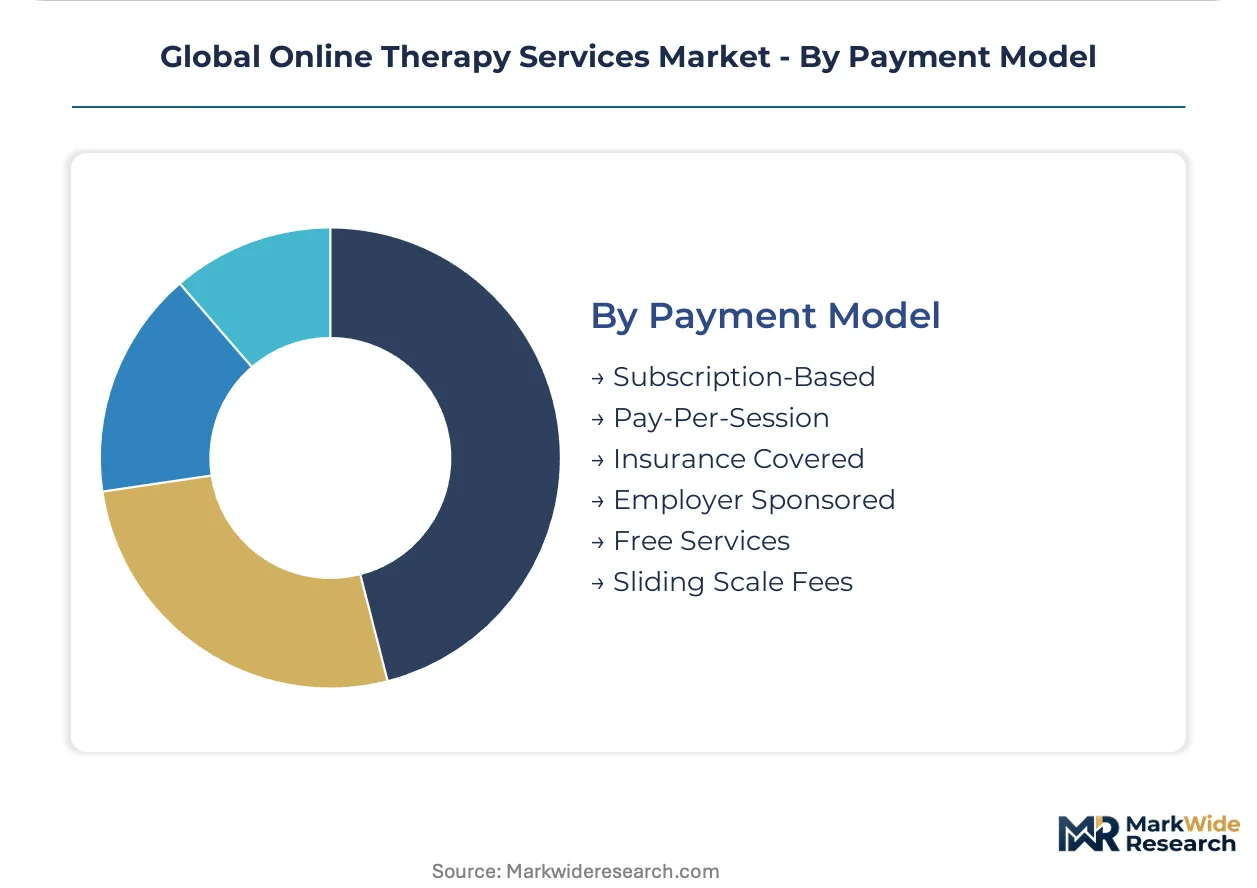
- Subscription-Based:Predictable recurring revenue concentrates margin pools and enables platform investment in clinician network expansion. Direct-to-consumer brands leverage this model to sustain volumes outside institutional procurement cycles.
- Employer Sponsored:Multi-year enterprise contracts with outcome guarantees reshape platform economics toward population health pricing. Benefits administrators in Germany and the United States now demand utilization rate accountability.
- Insurance Covered:Alignment with existing reimbursement infrastructure expands total addressable market but requires complex credentialing and claims processing capabilities.
- Pay-Per-Session:Transactional flexibility attracts price-sensitive individual users.
- Free Services:Grant-funded and nonprofit models address access gaps in underpenetrated markets.
- Sliding Scale Fees:Income-adjusted pricing responds to equity mandates from public health purchasers.
Employer Sponsored models are climbing the fastest as corporate wellness procurement concentrates, though Subscription-Based retains structural margin advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HIPAA compliance requirements in the United States anchor the most mature revenue pool for synchronous video-based counseling services, while GDPR data protection rules in Europe reshape platform architecture for cross-border operations.
United States
Large employer contracts and insurance reimbursement frameworks concentrate demand for synchronous video-based services. The FDA exercises oversight over digital therapeutics with clinical claims, mandating rigorous validation for platforms deploying automated therapeutic interventions. Employer-sponsored procurement in California and New York Metro concentrates multi-year enterprise contracts with outcome guarantees.
Germany
Corporate wellness programs across industrial sectors expand adoption of employer-sponsored digital mental health platforms. The EU AI Act imposes algorithmic transparency obligations on automated intake systems, requiring explainability documentation for clinical decision-support tools. Berlin-Brandenburg hosts specialized legal engineering functions that US competitors have not yet replicated.
United Kingdom
School-based programs and parental consent workflows drive specialized platform requirements for adolescent populations. GDPR cross-border data localization requirements fragment cloud architecture for services operating across European markets. London anchors procurement consolidation among benefits administrators demanding single-platform accountability.
India
Psychiatrist concentration in urban centers leaves the majority of districts without specialists, positioning asynchronous platforms to address supply-demand asymmetry. The country's national pharmaceutical regulator maintains oversight frameworks for digital health claims. Maharashtra and Karnataka host emerging platform development clusters targeting tiered provider models.
Brazil
Latin American markets lack established reimbursement frameworks, creating first-mover advantage for platforms building direct-pay models. ANVISA exercises regulatory authority over digital health applications with therapeutic claims. São Paulo concentrates demand for smartphone-native interfaces among adolescent and student populations.
Global Online Therapy Services Market Competitive Landscape
Direct-to-consumer subscription specialists and enterprise-focused platform providers split the market between predictable recurring revenue models and population-scale pricing structures. The vendor ecosystem concentrates around three strategic archetypes: brand-driven consumer platforms controlling therapist supply quality, telemedicine incumbents extending infrastructure into behavioral health, and AI-augmented automation specialists reducing administrative burden. Competitive moves center on multi-year enterprise contract acquisition and in-house clinician network expansion.
Within the direct-to-consumer tier, BetterHelp leverages brand strength to sustain subscription volumes outside institutional procurement cycles. Talkspace anchors competitive positioning through in-house production of licensed clinician networks. Teladoc Health occupies a hybrid medical-mental health niche that narrower specialists navigate with difficulty.
| Leading Market Players |
|---|
| BetterHelp |
| Talkspace |
| Teladoc Health |
| Amwell |
| Lyra Health |
| Cerebral |
| Wysa |
| Doctor on Demand |
| Calmerry |
| Others |
Supply & Pricing Matrix
Berlin-Brandenburg and Bengaluru clusters anchor platform development capacity, with their concentration of legal engineering and technical talent feeding directly into downstream pricing power for enterprise-grade HIPAA and GDPR-compliant services. This geographic specialization enables vendors serving large employer contracts to command premium positioning against commodity direct-to-consumer alternatives.
Pricing Analysis
US-Germany price spreads exceed three-to-one against Brazil-India direct-pay markets, reflecting reimbursement infrastructure maturity. Employer-sponsored contracts operate on per-member-per-month population health pricing with outcome guarantees, while subscription tiers stratify across premium licensed-clinician access, standard therapist-matching, and economy self-guided tools. Cost compression in the economy tier intensifies as venture-backed platforms subsidize user acquisition. Benefits administrators exhibit lowest price sensitivity; uninsured individual subscribers in emerging markets show highest.
Supply Chain Analysis
Cloud infrastructure providers Amazon Web Services, Microsoft Azure, and Google Cloud Platform hold dominant capacity for encrypted health data hosting across the United States, Germany, and United Kingdom. Platform operations draw from licensed clinician networks, video streaming SDKs, and AI/ML inference engines as critical inputs. Single-source vulnerability concentrates in interstate licensure databases that determine therapist eligibility. Distribution runs through benefits administration intermediaries and direct-to-consumer app stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from employer benefits consolidation steering covered lives toward single-platform accountability, compressing margins for point-solution specialists unable to match population-scale pricing.
For Market Incumbents: Harden enterprise contract retention by deepening in-house clinician network production in California and New York Metro, insulating against Teladoc Health's telemedicine infrastructure extension. Pursue backward integration into AI-assisted triage tooling to reduce per-session labor costs and defend margin position against automation specialists.
For New Entrants and Emerging Players: Build out asynchronous mobile-first platforms for adolescent and student demographics in São Paulo and Mumbai, where smartphone-native interfaces face minimal incumbent saturation. Target direct-pay subscription models in Brazil and Mexico before insurance reimbursement frameworks mature, establishing brand presence ahead of reimbursement integration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with hybrid synchronous-asynchronous architecture and established GDPR-AI Act compliance engineering. Long-term viability rests on enterprise contract concentration and clinician supply control. Monitor state-level licensure compact ratification as inflection signal for national scaling feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| In-House Clinician Network Expansion | Talkspace and Lyra Health control therapist supply quality at scale through direct employment models. |
| AI-Assisted Triage Development | Natural language processing automation reduces administrative screening burden and compresses per-session costs. |
| Enterprise Contract Acquisition | Multi-year employer sponsorship with outcome guarantees shifts platform economics toward population health pricing. |
| GDPR-AI Act Compliance Engineering | Algorithmic transparency documentation requirements in Germany and France create specialized legal engineering barriers. |
| Asynchronous Platform Architecture | Mobile-first messaging formats capture adolescent demographics in India and Brazil with lower infrastructure costs. |
Research Methodology
A standing panel of chief clinical officers, benefits administration procurement leads, platform engineering directors, and licensed therapist network managers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against HIPAA compliance documentation, FDA digital therapeutics filings, EU AI Act regulatory guidance, and employer benefits RFP databases. Bottom-up triangulation across service type, delivery model, and payment model segmentation reconciled with top-down market sizing.
Scenario-bracketing framed demand projections across the analysis window, modeling baseline, accelerated employer adoption, and reimbursement contraction pathways. Segmentation dimensions included service type, delivery model, end user demographic, and payment structure, with regional regulatory clusters treated as distinct adoption environments. CAGRs derived from logistic diffusion curves fitted to historical telehealth penetration patterns, adjusted for corporate wellness program expansion rates and clinician supply constraints.
Stress conditions across interstate licensure compact ratification, GDPR enforcement intensity, and employer benefits budget cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement framework maturation and platform certification requirements. Quarterly review of enterprise contract win rates and state-level regulatory clarity indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telemedicine Technologies Market
Telemedicine
US Telemedicine Market
Telemedicine
North America and Europe Ehealth Market
Telemedicine
AI in Telemedicine Market
Telemedicine
Pediatric Telemedicine Market
Telemedicine
Telemedicine Service Market
Telemedicine
Video Telemedicine Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
Telepathology Service Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
Next Generation Telehealth Market
Telemedicine
Healthcare IoT Telemedicine Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
Telemedicine Equipment Market