
 Real-Time E-Healthcare System Market | 2026-2036
Real-Time E-Healthcare System Market Size, Share, and Industry Trends Forecast 2026-2036
Real-Time E-Healthcare System Market Outlook
The FDA's Software as a Medical Device guidance is recalibrating the cost-of-entry calculus for new platform developers, forcing earlier investment in clinical validation and quality management systems. Epic Systems Corporation sustains dominant positioning in hospital-centric EHR integration, while Oracle Health leverages its cloud infrastructure to compete for enterprise contracts with large health systems. Teladoc Health anchors the virtual care delivery segment through its established payer relationships and direct-to-employer channels.
Real-time e-healthcare systems integrate continuous data capture from connected medical devices, patient-facing applications, and clinical information systems to enable immediate clinical decision support and automated care coordination. These platforms typically process biometric streams at sub-minute latency thresholds to trigger alerts, adjust treatment protocols, or escalate cases to human clinicians. Telemedicine solutions occupy the largest revenue pool within product categories, while wearable health tech represents the fastest-expanding segment as consumer-grade sensors achieve clinical-grade accuracy. Cloud computing dominates technology deployment, though AI-driven analytics commands the highest margin profile due to proprietary algorithm development and recurring licensing structures.
The FDA, HIPAA privacy frameworks, and CMS reimbursement policies collectively shape market access and product design requirements for US-focused vendors, with European entrants navigating parallel EMA and GDPR compliance obligations. The EU AI Act introduces additional conformity assessment burdens for algorithmic diagnostic tools, creating divergent regulatory investment requirements across Atlantic markets. Stakeholders must monitor how interoperability mandates from the Office of the National Coordinator for Health IT reshape competitive advantage toward open-architecture platforms over proprietary ecosystems.
Market Dynamics
Real-time e-healthcare systems face intensifying pressure from the FDA's Software as a Medical Device framework, which forces developers to front-load clinical validation costs and quality management investments before market entry.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare coverage for remote patient monitoring services creates direct payment pathways for connected care platforms in the United States.
- Chronic Disease Prevalence:Hospital systems deploy continuous monitoring infrastructure to manage diabetes, heart failure, and COPD populations outside acute settings.
- Sensor Miniaturization:Consumer-grade wearable devices achieve clinical-grade accuracy, expanding the addressable patient base for real-time data capture.
Market Restraints
- Interoperability Fragmentation:Proprietary data formats from Epic Systems and Oracle Health block seamless information exchange between competing platforms.
- Cloud Concentration Risk:AWS, Microsoft Azure, and Google Cloud dominate health data hosting, creating single-point-of-failure vulnerabilities for platform operators.
- GDPR Compliance Burden:European market entrants face divergent data localization requirements that inflate engineering overhead relative to US-only deployments.
Strategic Opportunities
- Rural Health Underservice:Federally Qualified Health Centers in the United States lack specialist access, creating demand for asynchronous telemedicine and AI triage tools.
- EU AI Act Conformity:Early compliance with algorithmic risk classification requirements positions vendors for preferential procurement in European hospital systems.
- Edge Computing Convergence:On-device inference reduces latency for critical alerts, enabling deployment in bandwidth-constrained environments.
Industry Challenges
- Clinical Informatics Talent Scarcity:Health systems compete for data scientists capable of translating raw biometric streams into actionable care protocols.
- Legacy EHR Integration Complexity:HL7 FHIR implementation varies across hospital systems, forcing costly custom middleware development for each enterprise deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real-Time E-Healthcare System Market |
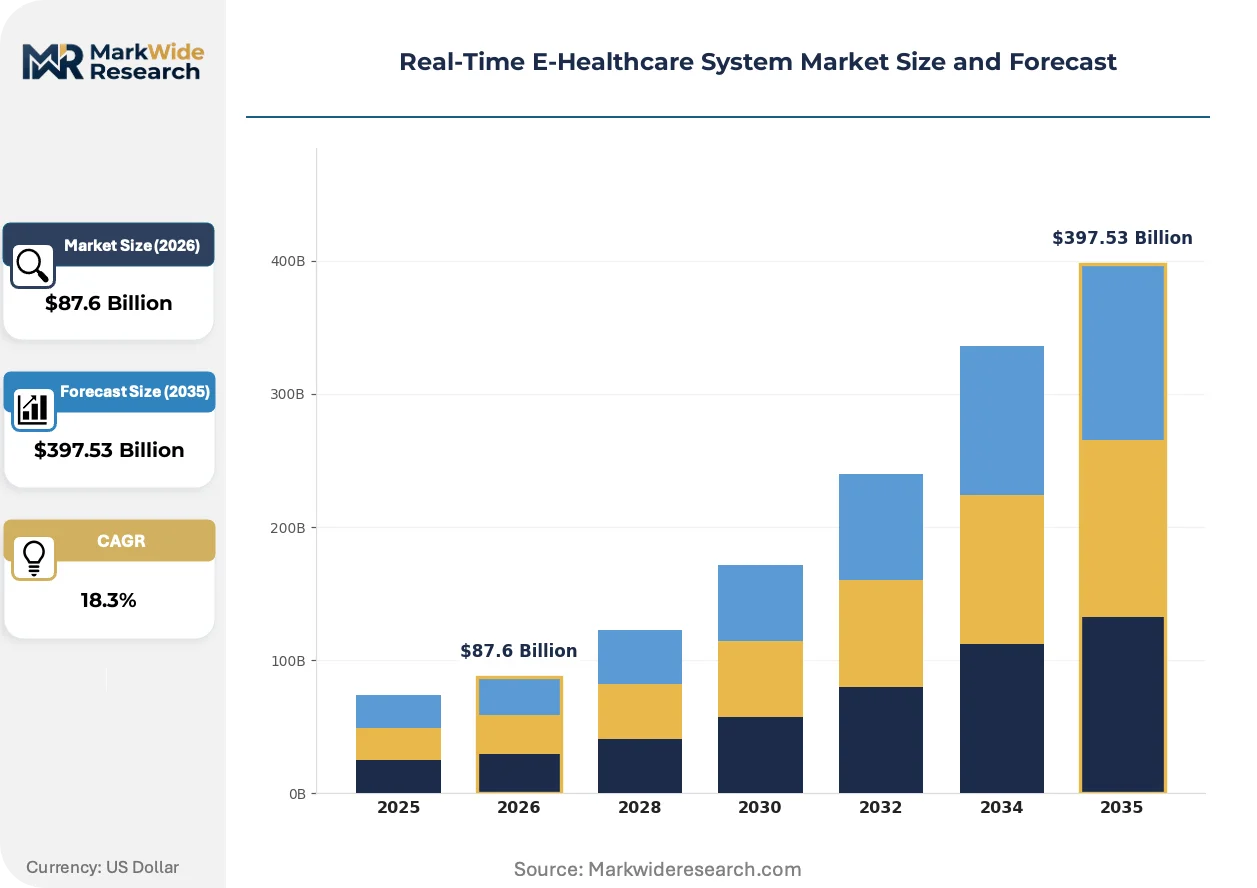
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $397.53 Billion |
| CAGR (2026 – 2036) | 18.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telemedicine Solutions, Remote Monitoring Devices, Wearable Health Tech, Electronic Health Records Technology: Cloud Computing, AI-Driven Analytics, Mobile Applications, IoT Devices End User: Healthcare Providers, Patients, Insurance Companies, Corporate Wellness Delivery Mode: As-a-Service, On-Premises, Hybrid Solutions, Mobile Delivery |
| Companies Covered | Oracle Health, Epic Systems Corporation, MEDITECH, GE Healthcare, Medtronic, Abbott Laboratories, DexCom Inc., Teladoc Health, Fitbit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real-Time E-Healthcare System Market Strategic Shifts
Algorithmic diagnostic tools are absorbing regulatory scrutiny while clinical workflows reorient around continuous rather than episodic data collection. Platform developers must now engineer for explainability and auditability from initial architecture.
Edge AI processors are absorbing inference workloads that previously required cloud round-trips. Cardiac monitoring patches and continuous glucose monitors now embed neural networks for arrhythmia detection and glucose prediction. Hospital IT departments are absorbing these devices into existing network security frameworks, though device heterogeneity complicates patch management and vulnerability scanning.
The EU AI Act's risk-based classification system is absorbing development roadmaps for diagnostic algorithms. High-risk applications face mandatory conformity assessment by notified bodies, extending time-to-market by twelve to eighteen months. Developers targeting European health systems are absorbing these requirements through dedicated regulatory affairs hires and quality management system upgrades.
Employer-sponsored virtual care programs are absorbing preference share from traditional payer channels. Large self-insured employers contract directly with Teladoc Health and competing platforms, bypassing insurance intermediaries. This channel shift concentrates purchasing power among benefits administrators rather than clinical operations teams, altering sales cycle dynamics and contract structures.
Real-Time E-Healthcare System Market Segmentation
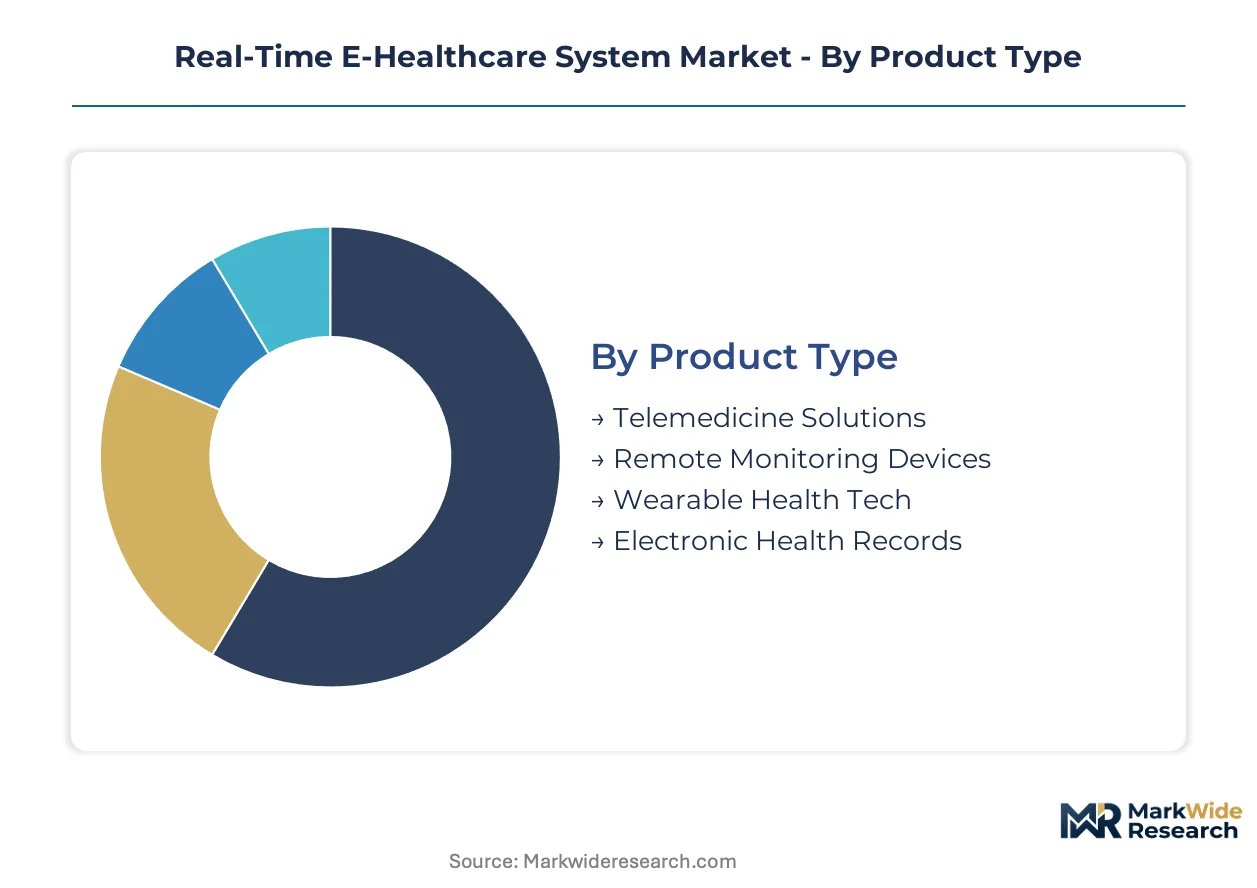
Real-time e-healthcare systems fragment across four distinct taxonomies that determine regulatory exposure, margin profiles, and sales cycle complexity. Each segmentation axis reveals divergent compliance burdens and deployment economics that vendors must navigate.
Product Type:
FDA Software as a Medical Device clearance requirements vary sharply across this category, with diagnostic-adjacent products facing 510(k) or De Novo pathways while administrative tools bypass premarket review.
- Telemedicine Solutions:Synchronous video platforms with integrated clinical documentation and prescribing workflows. Hospital systems in the United States concentrate procurement here as CMS reimbursement codes mature for virtual visits.
- Remote Monitoring Devices:Connected hardware capturing continuous biometrics—pulse oximeters, blood pressure cuffs, weight scales—transmitting data to cloud dashboards. Cardiology and endocrinology departments drive enterprise adoption for heart failure and diabetes management populations.
- Wearable Health Tech:Consumer-grade sensors achieving clinical validation for arrhythmia detection and sleep apnea screening.
- Electronic Health Records:Real-time data repositories with embedded clinical decision support and interoperability layers.
Leading the category by volume: Telemedicine Solutions. Growing fastest: Wearable Health Tech.
Technology:
Margin structures diverge sharply here—proprietary algorithm licensing commands premium pricing while commoditized infrastructure layers compete on operational efficiency.
- Cloud Computing:Scalable hosting infrastructure for patient data, clinical applications, and analytics workloads. AWS, Microsoft Azure, and Google Cloud dominate health system procurement in the United States, though European deployments face GDPR data localization mandates that fragment vendor selection.
- AI-Driven Analytics:Machine learning models for risk stratification, diagnostic inference, and treatment recommendation. EU AI Act high-risk classification is forcing conformity assessment investments for European market entry.
- Mobile Applications:Patient-facing software for symptom tracking, medication adherence, and care plan engagement.
- IoT Devices:Networked sensors and gateways enabling continuous data capture from home and clinical environments.
Highest margin capture: AI-Driven Analytics. Widest deployment base: Cloud Computing.
End User:
Procurement authority and budget cycles vary dramatically across this axis, from hospital IT capital committees to employer benefits administrators.
- Healthcare Providers:Hospitals, physician practices, and specialty clinics deploying systems for clinical operations and population health management. United States health systems concentrate investment here as value-based care contracts penalize readmissions.
- Patients:Direct-to-consumer purchases of wearable devices and wellness applications. Out-of-pocket spending concentrates in fitness-oriented demographics with chronic condition risk profiles.
- Insurance Companies:Payers integrating remote monitoring into care management programs to reduce emergency utilization.
- Corporate Wellness:Self-insured employers contracting directly with virtual care platforms for workforce health benefits.
Primary revenue concentration: Healthcare Providers. Fastest budget growth: Corporate Wellness.
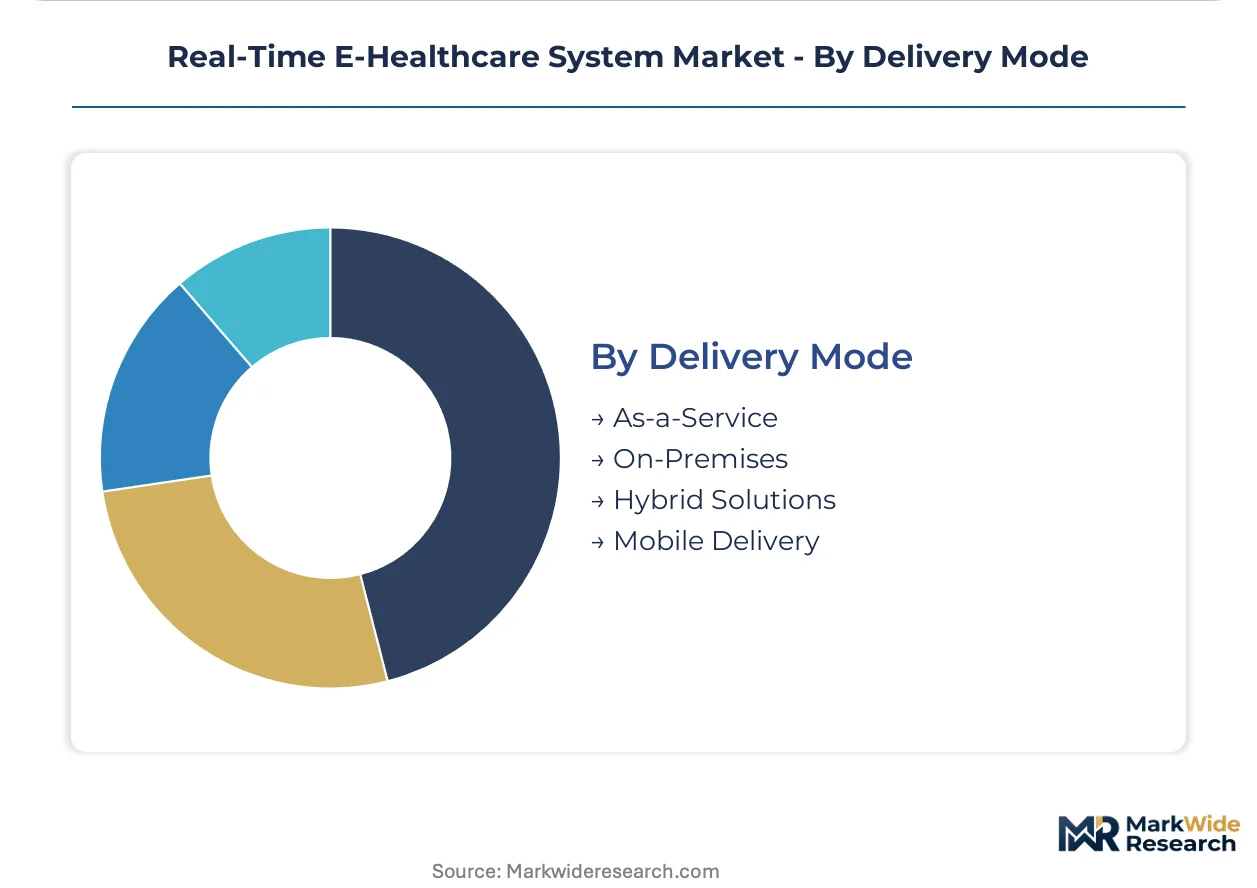
Delivery Mode:
Capital intensity and recurring revenue profiles define competitive positioning across deployment architectures.
- As-a-Service:Subscription-based access to software, infrastructure, and support without ownership transfer. Hospital CIOs in the United States favor this model to convert capital expenditures to operational budgets and accelerate implementation timelines.
- On-Premises:Licensed software deployed within client data centers with full operational control. Defense and intelligence health systems mandate this architecture for security classification requirements.
- Hybrid Solutions:Split architectures with sensitive data on-premises and analytics workloads in cloud environments.
- Mobile Delivery:Smartphone-native applications with offline functionality and periodic synchronization.
Dominant contract structure: As-a-Service. Fastest architecture innovation: Hybrid Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Hyderabad concentrate contract manufacturing for connected medical devices, attracting developers through tax holidays and streamlined customs clearance for sensor components.
United States
Medicare Advantage plans and employer self-insurance programs drive procurement of remote patient monitoring platforms. FDA Software as a Medical Device guidance forces developers toward 510(k) and De Novo pathways. The Boston-Cambridge corridor anchors digital therapeutics clusters where startups co-locate with academic medical centers for clinical validation partnerships.
Germany
Hospital digitization funds from the Hospital Future Act accelerate EHR modernization and telemedicine infrastructure. EU AI Act high-risk classification requirements extend conformity assessment timelines for diagnostic algorithms. The Rhine-Ruhr metropolitan region concentrates health IT vendors serving university hospitals with interoperability mandates.
China
Internet hospital licenses and provincial reimbursement pilots expand virtual care access beyond tier-one cities. NMPA medical device regulations apply to software with diagnostic functions, creating parallel review tracks. The Yangtze River Delta cluster in Shanghai and Hangzhou hosts wearable device manufacturers integrating clinical-grade sensors into consumer form factors.
India
Telemedicine practice guidelines issued by the national medical commission legitimize remote consultations across state boundaries. CDSCO medical device rules now capture software-as-device products, requiring registration for risk-classified applications. Hyderabad's Genome Valley and Bengaluru's HealthTech corridor attract venture capital for chronic disease management platforms targeting diabetes and cardiovascular conditions.
United Kingdom
NHS Long Term Plan targets for digital-first primary care reshape procurement toward asynchronous consultation platforms. MHRA post-Brexit regulatory autonomy maintains alignment with MDR while streamlining innovative device pathways. London's Golden Triangle biotech cluster increasingly overlaps with health AI development, with Imperial College and UCL spinning out diagnostic algorithm ventures.
Real-Time E-Healthcare System Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology layers. Market structure tilts toward consolidation in EHR and cloud infrastructure, while fragmentation persists in wearable hardware and point-solution analytics. Three archetypes dominate: enterprise platform vendors with hospital system relationships, device manufacturers extending into software services, and virtual care pure-plays with direct-to-employer channels. Competitive moves center on strategic partnerships for interoperability and portfolio diversification into adjacent diagnostic categories.
Within the enterprise platform tier, Epic Systems Corporation and Oracle Health occupy positions defined by EHR integration depth and cloud infrastructure scale respectively. Teladoc Health exemplifies the virtual care pure-play archetype, anchoring direct contracting relationships with self-insured employers outside traditional payer channels. These three entities represent divergent strategic bets on where value accumulates in connected care delivery.
| Leading Market Players |
|---|
| Oracle Health |
| Epic Systems Corporation |
| MEDITECH |
| GE Healthcare |
| Medtronic |
| Abbott Laboratories |
| DexCom Inc. |
| Teladoc Health |
| Fitbit |
| Others |
Value Chain & Pricing Dynamics
FDA Software as a Medical Device clearance tiers bifurcate the market between premium-priced validated platforms and commodity administrative tools, with that divergence mapping directly onto supply chain configurations. Cloud infrastructure vendors and sensor manufacturers cluster in distinct geographic zones, while algorithm developers face tier-specific regulatory qualification costs that reshape procurement patterns.
Pricing Analysis
Short lead-time delivery commands premium pricing for AI-driven analytics modules, while spot inventory of commoditized cloud hosting faces discount pressure. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic algorithms from wellness applications and basic data dashboards. Price differentiation rests on clinical validation depth and interoperability certification with Epic Systems or Oracle Health. Pricing pressure stems from hyperscaler commoditization of base infrastructure layers. Hospital systems show highest price sensitivity for hardware peripherals, while payers accept premium rates for proven readmission reduction outcomes.
Supply Chain Analysis
ISO 13485 quality management certification gates component sourcing for wearable health tech, filtering suppliers into qualified and unqualified tiers. Manufacturing concentrates in China for sensor fabrication, Taiwan for edge AI processors, and the United States for cloud infrastructure. Raw material dependencies include lithium-ion cells for wearable power, medical-grade silicon for biosensors, and rare earth elements for miniaturized electronics. Single-source vulnerability concentrates in AWS, Microsoft Azure, and Google Cloud hosting. Distribution runs through hospital GPO contracts, direct-to-employer channels, and retail consumer pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around platform vendors with embedded EHR relationships, as FDA clearance costs and interoperability complexity force weaker point-solution providers toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through exclusive Epic Systems integration partnerships and captive AI algorithm development. Oracle Health's cloud infrastructure investments threaten margin compression for standalone SaaS vendors. Backward integration into edge AI chip design preserves latency advantages for cardiac monitoring applications. For New Entrants and Emerging Players: CMS reimbursement expansion in the United States opens a window for asynchronous telemedicine platforms targeting Federally Qualified Health Centers. Rural specialist access gaps represent the most penetrable white space. White-label wearable partnerships with established sensor manufacturers accelerate time-to-clinical-validation. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by EHR conglomerates seeking interoperability assets. Five-to-ten-year viability favors vendors with recurring SaaS revenue above hardware-dependent models. Watch FDA 510(k) clearance velocity as the signal for platform scalability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for diagnostic algorithms in cardiology and endocrinology segments. |
| Hospital System Partnership | Locks in procurement preference through embedded Epic Systems or Oracle Health workflows. |
| CE Marking Pathway | Enables European market entry ahead of EU AI Act high-risk classification enforcement. |
| Software Companion Development | Extends wearable device utility into reimbursable remote patient monitoring services. |
| Reimbursement Strategy | Aligns platform design with CMS billing codes for virtual visits and chronic care management. |
Study Parameters
SEC 10-K filings, CMS reimbursement databases, and FDA 510(k) clearance records formed the secondary backbone for market sizing and competitive positioning. Primary interviews with hospital CIOs, biomedical engineers, GPO contracts managers, and digital therapeutics regulatory leads validated demand assumptions and procurement timelines. Bottom-up triangulation across product segments combined with top-down macroeconomic validation anchored volume and value estimates.
Bottom-up modeling of installed base and pricing by deployment mode, end-user archetype, and technology layer generated segment-level outputs across the analysis window. Top-down cross-checks against hospital IT capital expenditure surveys and payer remote monitoring adoption indices ensured consistency. CAGRs derived from regression analysis of historical adoption curves, adjusted for regulatory inflection points and reimbursement policy shifts. Edge AI processor cost trajectories and cloud infrastructure pricing elasticity served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for on-device inference would alter the outlook for cloud-dependent analytics vendors. Forecasts reflect assumptions about FDA enforcement consistency and CMS reimbursement stability that regulatory shifts could revise. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
US Virtual Care Market
Telemedicine
Telemedicine Diagnostic Services Market
Telemedicine
Tele-Care Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
North America Telemedicine Market
Telemedicine
Video Telemedicine Market
Telemedicine
Telemedicine Workstations Market
Telemedicine
GCC Telemedicine Market
Telemedicine
Global Telemedicine Market
Telemedicine
Healthcare IoT Telemedicine Market
Telemedicine
Asia-Pacific Ehealth Market
Telemedicine
Global Telehealth Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
AI in Telemedicine Market
Telemedicine
Telemedicine EMR Software Market