
 AI in Telemedicine Market | 2026-2036
AI in Telemedicine Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Telemedicine Market Insights
Shortages of radiologists and dermatologists trained in AI-augmented diagnostics is redrawing competitive boundaries across the telemedicine landscape. Teladoc Health leverages its established virtual care infrastructure to anchor North American deployment of algorithmic triage tools. Koninklijke Philips N.V. sustains technology leadership through integrated imaging-to-diagnosis workflows that connect hospital PACS systems with remote consultation platforms. GE Healthcare differentiates by dominating the hardware-software interface where edge computing devices feed real-time patient data into centralized AI models.
AI in telemedicine encompasses machine learning algorithms, natural language processing engines, and computer vision systems deployed through cloud or edge architectures to deliver remote clinical assessment, automated symptom checking, and predictive risk stratification with sub-second inference latency for acute care scenarios. Natural language processing occupies the largest margin pool as conversational agents reduce per-consultation labor costs across virtual consultation platforms. Computer vision is accelerating fastest in diagnostic support applications where retinal scans and dermatological imaging achieve specialist-grade accuracy without physical specialist presence. Predictive analytics remains comparatively mature within remote patient monitoring as continuous glucose and cardiac telemetry feeds already integrate risk-scoring algorithms at scale.
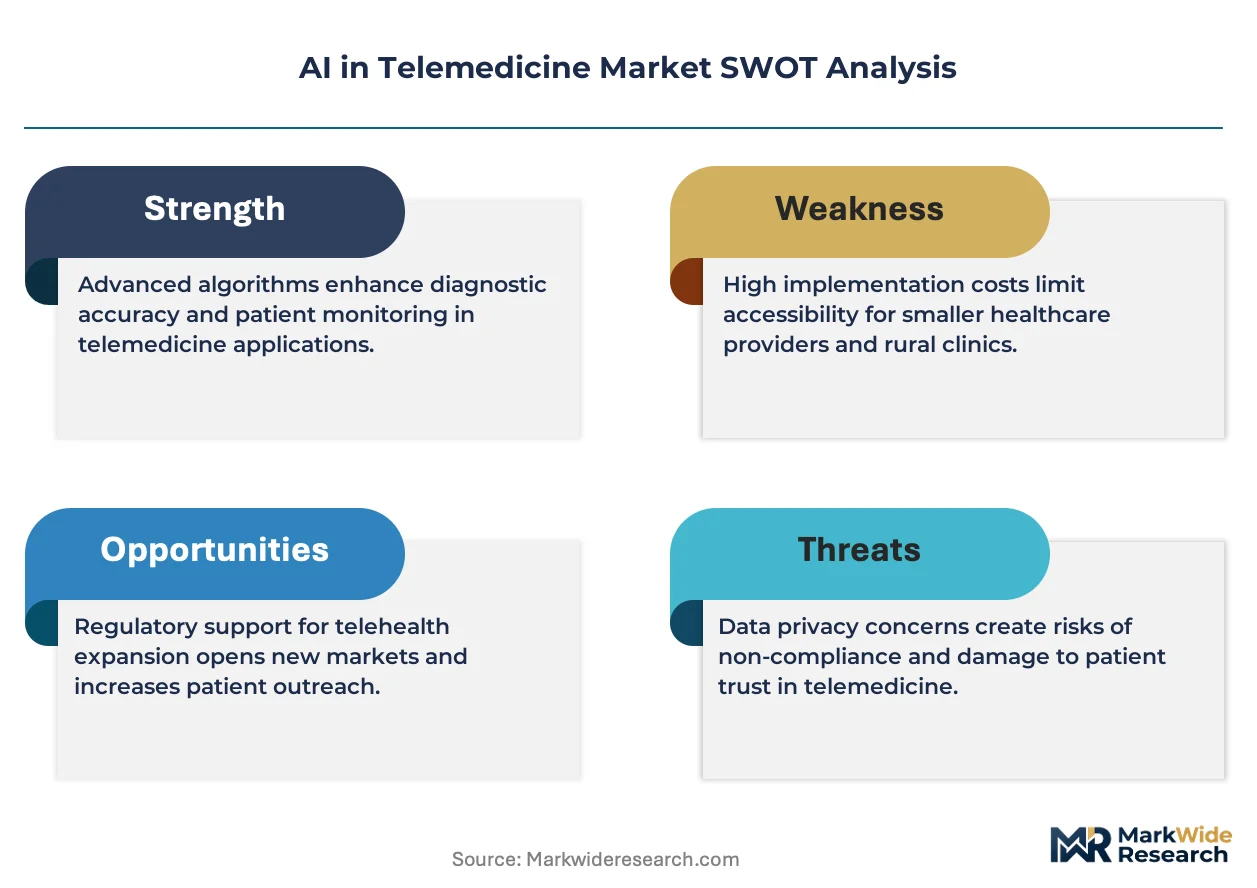
FDA pre-certification pathways for software-as-a-medical-device and HIPAA interoperability mandates shape product development timelines and data architecture requirements for vendors seeking US market access. EMA's Medical Device Regulation and GDPR health data provisions impose parallel compliance burdens on European deployments, while India's CDSCO digital health guidelines and the PLI scheme for electronics manufacturing create localized incentive structures for domestic AI diagnostic platforms. Stakeholders must weigh regulatory fragmentation against the cost of maintaining jurisdiction-specific algorithm validation datasets and audit trails.
Market Dynamics
Machine learning inference latency requirements for acute care triage are compressing hardware refresh cycles across telemedicine infrastructure, forcing platform operators to rebuild around edge-native architectures rather than cloud-centralized models.
Growth Catalysts
- FDA pre-certification pathways:Software-as-a-medical-device frameworks accelerate algorithm deployment timelines for US virtual care platforms.
- Rural health networks:CMS reimbursement parity rules expand telehealth access across underserved US geographies.
- Computer vision:Retinal and dermatological diagnostic algorithms achieve specialist-grade accuracy without physical specialist presence.
Market Restraints
- Algorithm validation costs:Jurisdiction-specific audit trail requirements multiply compliance expenditures for multi-market deployments.
- Physician density gaps:Shortages of radiologists and dermatologists trained in AI-augmented diagnostics limit adoption velocity in tier-two Indian cities.
- GDPR health data provisions:EMA's Medical Device Regulation imposes parallel data architecture burdens on European telemedicine rollouts.
Strategic Opportunities
- India's PLI scheme:Electronics manufacturing incentives create localized production advantages for domestic AI diagnostic platforms.
- Natural language processing:Conversational agents reduce per-consultation labor costs across virtual consultation platforms.
- Edge-to-cloud convergence:Federated learning architectures enable model training without centralized patient data pooling.
Industry Challenges
- Interoperability mandates:HIPAA technical standards require costly re-engineering of legacy EHR integration layers.
- Hardware-software interface complexity:Real-time telemetry feeds demand specialized engineering talent scarce outside major medical device clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Telemedicine Market |
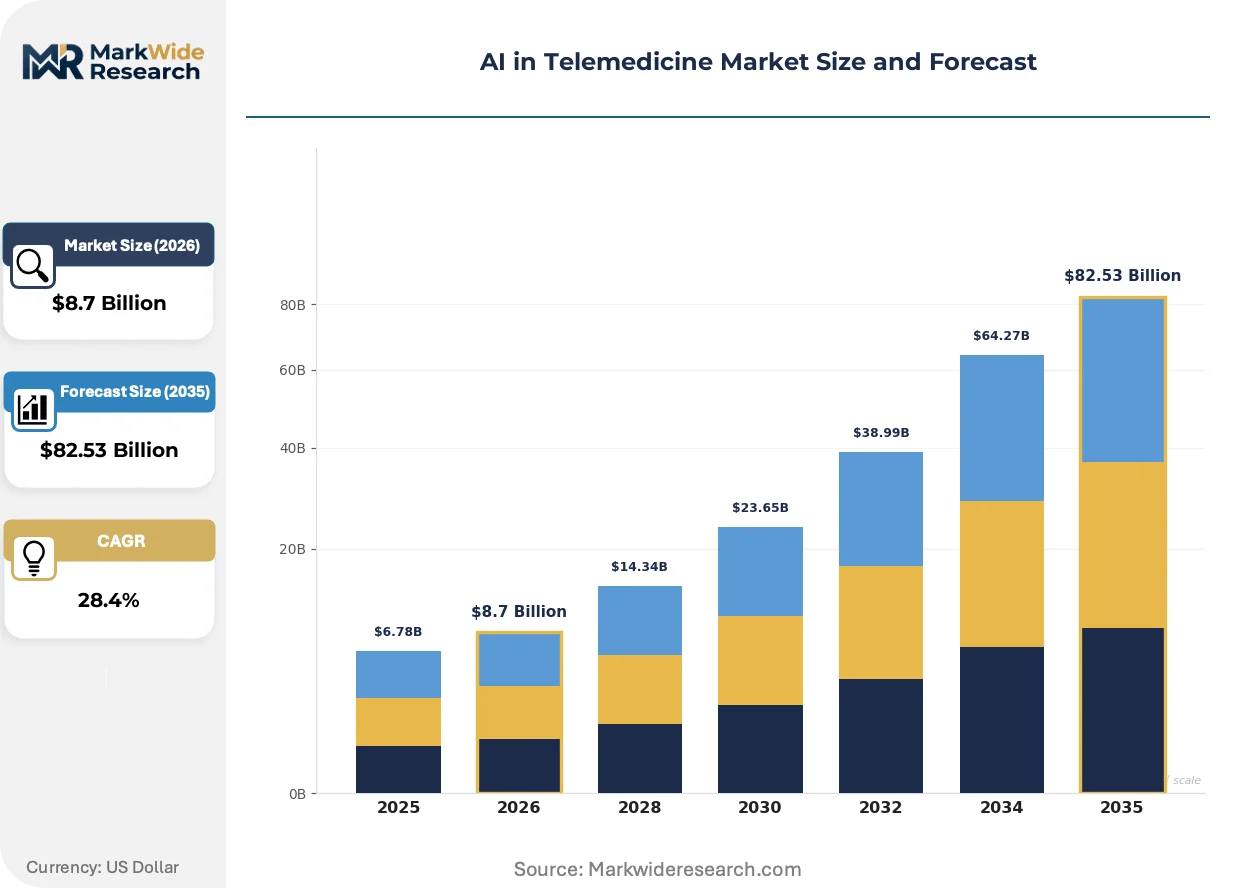
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Predictive Analytics Application: Remote Patient Monitoring, Virtual Consultations, Diagnostic Support, Treatment Recommendations End User: Hospitals, Clinics, Home Care, Patients Service Type: Consultation Services, Health Monitoring Services, Data Analysis Services, Support Services |
| Companies Covered | Teladoc Health, Koninklijke Philips N.V., GE Healthcare, Medtronic, Amwell, IBM, Siemens Healthcare GmbH, HealthTap, Inc., Ada Health GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Telemedicine Market Trends and Innovations
Diagnostic hardware is migrating toward ambulatory form factors that bypass traditional clinical settings, compressing the distance between sensor capture and algorithmic interpretation while redrawing competitive boundaries between device manufacturers and platform operators.
Edge computing devices for cardiac and glucose monitoring are miniaturizing to wearable scales without sacrificing inference accuracy. Rural health networks in the United States are adopting these units fastest to circumvent specialist travel requirements. The technology is miniaturizing the physical footprint of acute care triage, enabling hospital-at-home models that displace emergency department visits.
EMA's Medical Device Regulation now mandates clinical evidence standards for AI diagnostic algorithms equivalent to Class IIb hardware devices. European telemedicine vendors must rebuild quality management systems around post-market surveillance of algorithm performance drift. Dermatology screening platforms face the steepest compliance recertification burden as software update cycles compress.
Hospital procurement committees now require AI transparency documentation before contracting virtual care platforms, shifting vendor selection criteria from interoperability checklists to explainability standards. Academic medical centers in Germany and Switzerland lead this behavioral shift, demanding algorithmic decision trails for malpractice liability coverage. The pattern is compressing sales cycles for black-box diagnostic tools while extending evaluation periods for interpretable alternatives.
AI in Telemedicine Market Segmentation
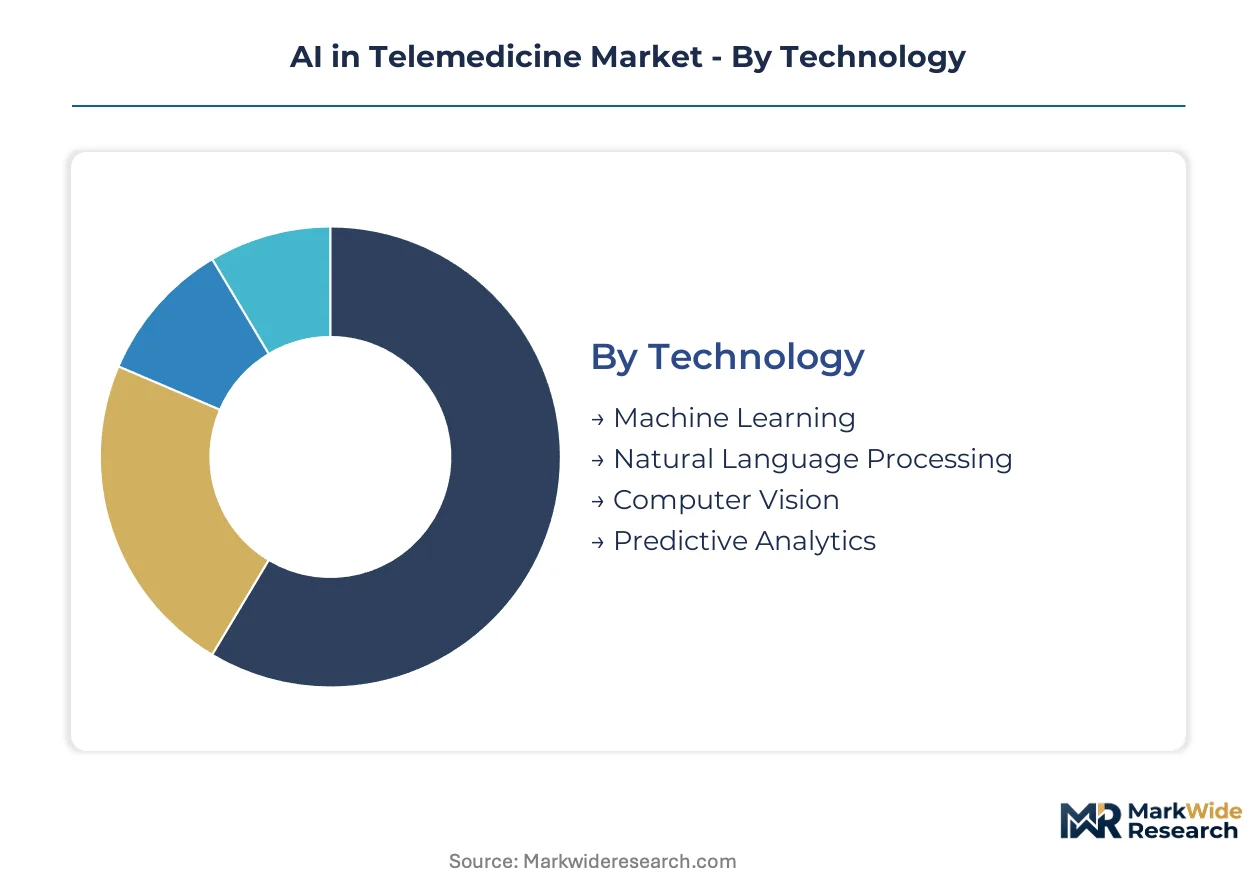
Technology architecture and service delivery models determine where capital flows concentrate in AI telemedicine. Margin pools shift between algorithmic sophistication layers and the infrastructure required to deploy them at clinical scale.
Technology:
Natural language processing commands the widest margin spreads as conversational interfaces eliminate per-consultation labor overhead across virtual care platforms.
- Machine Learning:Supervised and unsupervised learning frameworks power diagnostic triage algorithms with sub-second inference latency for acute care scenarios. Demand concentrates in Indian tier-two cities where physician density gaps drive AI-assisted triage adoption alongside CDSCO digital health compliance requirements.
- Natural Language Processing:Conversational agents automate patient intake, symptom elicitation, and clinical documentation through transformer-based architectures. US rural health networks deploy these tools fastest under CMS reimbursement parity rules that expand telehealth access across underserved geographies.
- Computer Vision:Retinal scanning and dermatological imaging achieve specialist-grade diagnostic accuracy without physical specialist presence.
- Predictive Analytics:Continuous risk scoring from cardiac telemetry and glucose monitoring feeds already operates at scale in remote patient monitoring deployments.
The dominant share belongs to natural language processing, while computer vision is closing the gap fastest through diagnostic imaging breakthroughs.
Application:
Volume concentration tracks reimbursement policy rather than technical sophistication, with virtual consultations capturing patient flow through regulatory-enabled access expansion.
- Remote Patient Monitoring:Continuous physiological data streams from wearable cardiac and glucose devices feed centralized risk-scoring models. US rural health networks adopt these systems fastest to circumvent specialist travel requirements under federal reimbursement frameworks.
- Virtual Consultations:Synchronous video encounters augmented by AI triage pre-screening reduce emergency department utilization. Indian tier-two cities concentrate demand here where physician density gaps exceed national averages by substantial margins.
- Diagnostic Support:Algorithmic interpretation of medical imaging and laboratory results augments specialist capacity constraints.
- Treatment Recommendations:Evidence-based protocol suggestions from clinical decision support systems standardize care pathways across distributed provider networks.
Virtual consultations hold the volume lead, though remote patient monitoring exhibits the steepest expansion trajectory as hospital-at-home models displace traditional acute care delivery.
End User:
Procurement authority and technical integration capacity separate segments, with hospitals commanding the infrastructure investment required for enterprise AI deployment.
- Hospitals:Academic medical centers in Germany and Switzerland now require AI transparency documentation before contracting virtual care platforms, shifting procurement criteria toward explainability standards and algorithmic decision trails for malpractice liability coverage.
- Clinics:Federated learning architectures enable smaller facilities to benefit from centralized model training without patient data pooling, addressing GDPR health data provisions across European deployments.
- Home Care:Ambulatory diagnostic hardware miniaturization enables acute care triage outside traditional clinical settings.
- Patients:Direct-to-consumer symptom checkers and wellness monitoring applications operate with lighter regulatory burdens than clinical-grade tools.
Hospitals retain the procurement advantage, yet home care is gaining share fastest as wearable form factors compress the distance between sensor capture and algorithmic interpretation.
Service Type:
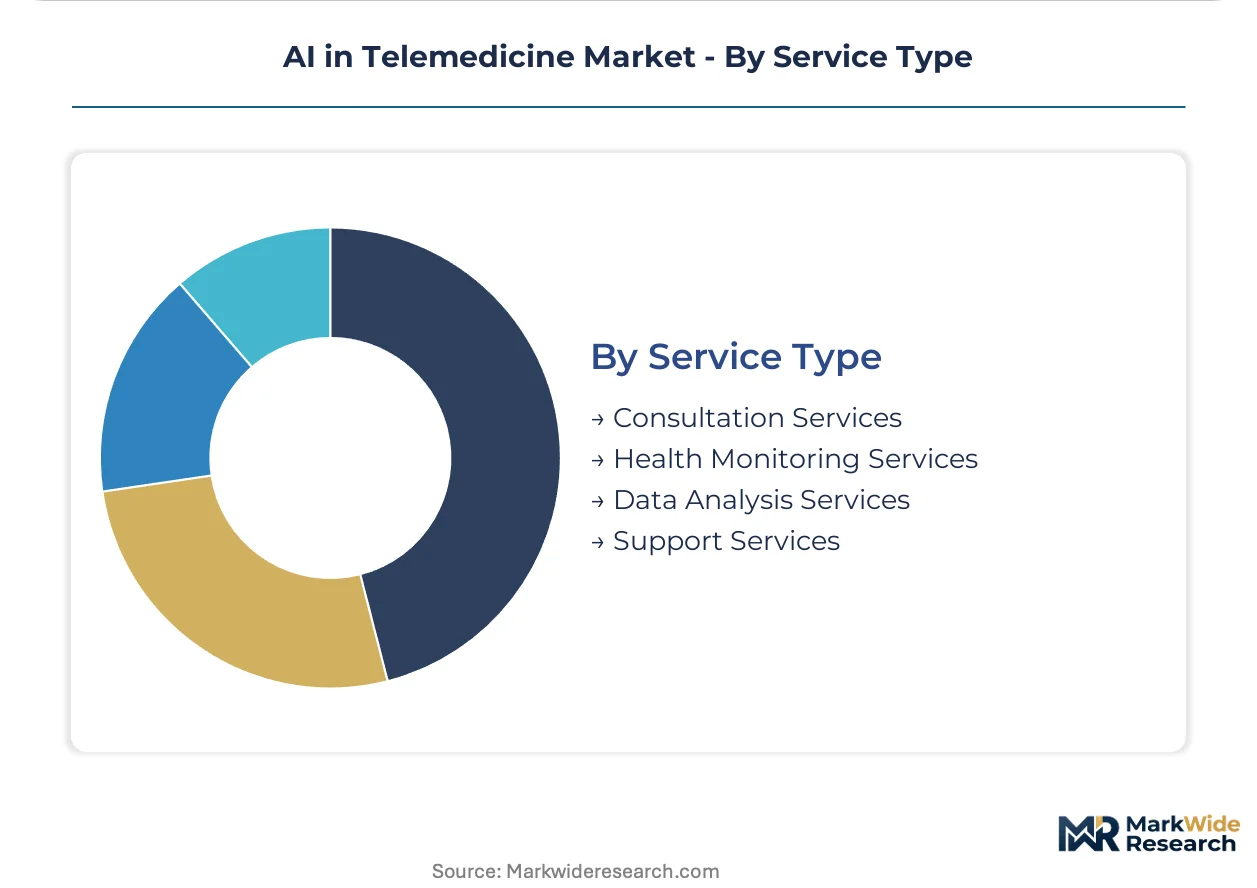
Revenue stability varies by contractual structure, with subscription-based monitoring services outperforming transactional consultation models in retention metrics.
- Consultation Services:Per-encounter virtual visits augmented by AI pre-screening reduce average handle time while maintaining clinical quality thresholds for reimbursement eligibility.
- Health Monitoring Services:Continuous telemetry oversight with automated escalation protocols commands premium pricing through outcome-linked contractual structures.
- Data Analysis Services:Population health insights derived from aggregated telemedicine encounter data support payer risk stratification and network optimization decisions.
- Support Services:Technical integration, training, and algorithm maintenance contracts extend customer lifetime value beyond initial platform deployment.
Health monitoring services capture the most durable revenue streams, while data analysis services are climbing fastest as payer organizations seek operational intelligence from telemedicine platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pre-certification pathways for software-as-a-medical-device anchor United States market expansion, while reimbursement parity rules under CMS reshape rural health network procurement patterns.
United States
Rural health networks drive platform adoption fastest under CMS reimbursement parity rules that expand telehealth access across underserved geographies. FDA pre-certification pathways accelerate algorithm deployment timelines for virtual care platforms. Academic medical centers in Boston and Stanford clusters now require AI transparency documentation before contracting, shifting procurement toward explainability standards.
Germany
Academic medical centers command procurement authority through demands for algorithmic decision trails covering malpractice liability. EMA's Medical Device Regulation mandates clinical evidence standards for AI diagnostic algorithms equivalent to Class IIb hardware devices. The Munich and Heidelberg clusters lead post-market surveillance rebuilds for quality management systems tracking algorithm performance drift.
India
Tier-two cities concentrate demand where physician density gaps exceed national averages by substantial margins. CDSCO digital health guidelines and the PLI scheme for electronics manufacturing create localized incentive structures for domestic AI diagnostic platforms. Bengaluru and Hyderabad clusters anchor production advantages for algorithm validation datasets serving multi-market deployments.
Switzerland
Swissmedic oversight intersects with academic medical center procurement committees demanding explainability standards before platform contracting. GDPR health data provisions impose data architecture requirements on European telemedicine rollouts affecting cross-border deployments. The Basel and Zurich clusters concentrate federated learning architecture development enabling model training without centralized patient data pooling.
United Kingdom
Virtual consultation platforms capture patient flow through NHS-enabled access expansion in London and Manchester metropolitan clusters. MHRA alignment with EMA Medical Device Regulation shapes software-as-a-medical-device compliance timelines for vendors seeking market access. The Cambridge life sciences corridor anchors natural language processing development for conversational agents reducing per-consultation labor overhead.
AI in Telemedicine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in AI telemedicine, with hospital-grade platform operators commanding procurement relationships through EHR integration depth. The structure consolidates around three archetypes: virtual care infrastructure incumbents, imaging-to-diagnosis workflow integrators, and hardware-software interface specialists. Dominant competitive moves include strategic partnerships for edge computing deployment and portfolio diversification into hospital-at-home telemetry services.
Within the integrated infrastructure tier, Teladoc Health and Koninklijke Philips N.V. exemplify contrasting geographic and capability positioning. Teladoc Health anchors North American virtual care deployment through established platform scale. Koninklijke Philips N.V. occupies a position connecting hospital PACS systems with remote consultation platforms across European and select Asian markets. GE Healthcare sits within the hardware-software interface specialist archetype, representing edge computing device integration where real-time patient data feeds centralized AI models.
| Leading Market Players |
|---|
| Teladoc Health |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Medtronic |
| Amwell |
| IBM |
| Siemens Healthcare GmbH |
| HealthTap, Inc. |
| Ada Health GmbH |
| Others |
Pricing and Supply Chain Analysis
Outcome-linked contractual structures for continuous health monitoring services lock in multi-year revenue visibility while anchoring hardware procurement schedules to patient enrollment trajectories. US rural health networks and Indian tier-two hospital systems favor these arrangements because CMS reimbursement parity and CDSCO digital health frameworks reduce payment uncertainty.
Pricing Analysis
US-based virtual consultation platforms command premium positioning against Indian domestic deployments where physician density gaps compress margins. Three-tier pricing structure across enterprise-grade, mid-market, and basic SaaS levels separates hospital systems with EHR integration requirements from standalone clinic deployments. Cost compression in the basic tier intensifies because edge computing hardware commoditization erodes device margins. Tier-two Indian cities exhibit the highest price sensitivity; academic medical centers in Germany and Switzerland demonstrate the lowest due to malpractice liability coverage requirements.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes inflate inbound logistics costs for GPU and specialized inference chip shipments. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States; edge device assembly clusters in China, Mexico, and Vietnam. NVIDIA tensor processing units and Qualcomm mobile inference engines anchor algorithm deployment hardware. Single-source vulnerability around advanced node semiconductor access represents the dominant structural risk. Distribution runs through hospital procurement committees and GPO contracts in developed markets, with direct OEM relationships prevailing in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm maintenance and model retraining contracts expand faster than initial platform licensing as EMA Medical Device Regulation mandates post-market surveillance of performance drift. This service-attach dynamic reorients vendor economics toward recurring revenue.
For Market Incumbents: Consolidate around federated learning infrastructure investments that address GDPR health data provisions without centralized patient data pooling. Acquire edge computing deployment specialists to tighten hardware-software interface control against GE Healthcare's dominance. FDA pre-certification pathway acceleration and HIPAA interoperability mandate compliance represent the critical defensive levers. For New Entrants and Emerging Players: Differentiate on explainability standards for diagnostic algorithms where academic medical centers in Germany and Switzerland have shifted procurement criteria. Target home care monitoring applications where ambulatory hardware miniaturization is displacing traditional clinical settings. Pursue CDSCO digital health guideline alignment for tier-two Indian city entry. For Investors and Strategic Acquirers: Capital is best deployed toward platform operators with established hospital EHR integration depth and recurring algorithm maintenance revenue. Long-term viability across the analysis window hinges on regulatory compliance automation capabilities. Watch for FDA software-as-a-medical-device pre-certification pathway expansions as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Deep EHR integration with Epic and Cerner systems anchors procurement relationships for virtual care platforms. |
| FDA Pre-Certification Pathway | Software-as-a-medical-device frameworks compress algorithm deployment timelines for US market access. |
| Edge Computing Deployment | Real-time cardiac and glucose telemetry feeds require specialized hardware-software interface engineering. |
| Reimbursement Strategy | CMS parity rules for rural health networks determine patient flow capture in underserved geographies. |
| Software Companion Development | Conversational agents for symptom checking reduce per-consultation labor costs across virtual platforms. |
Research Methodology
A standing panel of hospital CIOs, telemedicine platform engineers, FDA regulatory consultants, and GPO contracts managers provided ongoing calibration against secondary validation sources. Primary interviews with biomedical engineers and health system procurement directors combined with CMS Medicare reimbursement data, FDA 510(k) filings, CDSCO digital health registrations, and hospital procurement database extracts. Bottom-up patient encounter volume modeling and top-down technology spending allocation analysis were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated technology architecture, application type, end-user procurement authority, and regional regulatory cluster dimensions. CAGRs were derived from algorithm adoption curve analysis and infrastructure deployment timelines. Edge computing hardware refresh cycles and NLP conversational agent penetration rates served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FDA pre-certification pathway access, CMS reimbursement parity maintenance, or GDPR health data provision stability would require recalibration. Forecasts reflect documented assumptions around algorithm validation cost trajectories and physician training pipeline expansion. Regulatory fragmentation acceleration or semiconductor supply disruption would revise modeled outcomes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Global Telehealth Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
US Telemedicine Market
Telemedicine
Tele-Care Market
Telemedicine
Global Virtual Care Market
Telemedicine
Video Telemedicine Market
Telemedicine
Telestroke Services Market
Telemedicine
Telehealth Kiosk Market
Telemedicine
Real-Time E-Healthcare System Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
Telepathology Service Market
Telemedicine
Telemedicine Workstations Market
Telemedicine
Teledermatology Market
Telemedicine
Telehealth Services Market
Telemedicine
Tele-Epilepsy Market