
 Global Tele Intensive Care Unit Market | 2026-2036
Global Tele Intensive Care Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tele Intensive Care Unit Market Foresight
Enterprise-grade interoperability standards are reorganizing procurement criteria across health system networks. Philips leverages its intensive care informatics ecosystem to anchor multi-hospital command center contracts in North America. GE Healthcare sustains R&D intensity in edge-computing telemetry architectures that reduce latency for remote ventilator adjustments. Siemens Healthineers competes on integrated imaging-to-ICU workflows that differentiate its platform in European university hospital networks.
A tele intensive care unit integrates audio-visual communication, physiological monitoring, clinical decision support, and alarm management to enable remote intensivist oversight of critically ill patients across distributed hospital sites. Systems typically operate with sub-second latency requirements for real-time intervention and employ predictive algorithms trained on multi-parameter ICU data streams to flag deterioration before conventional threshold breaches. Real-time monitoring solutions command the largest installed base, while predictive analytics represents the fastest-expanding margin pool as hospitals seek to reduce false-alarm fatigue and optimize resource allocation. Cloud-based deployment is displacing on-premise installations among mid-sized hospital systems that lack dedicated IT infrastructure for 24/7 critical care operations.
FDA clearance pathways for software-as-medical-device algorithms shape product development timelines and commercialization scope for vendors targeting US health systems. The EU AI Act and MDR requirements impose additional conformity obligations on predictive analytics modules deployed in European critical care settings. Stakeholders must monitor evolving reimbursement determinations from CMS and parallel national health technology assessment bodies, as payment parity between remote and bedside intensivist services remains the decisive variable for hospital adoption decisions.
Market Dynamics
Cloud-native telemetry architectures are compressing deployment cycles from eighteen months to under six weeks, forcing incumbent vendors to restructure professional services revenue models around subscription-based clinical support rather than perpetual license sales.
Growth Catalysts
- Intensivist staffing deficits:US hospital systems face projected shortfalls exceeding ten thousand critical care physicians by decade end, compelling centralized command center investments to extend specialist coverage across rural and community facilities.
- CMS reimbursement parity:Medicare payment frameworks now recognize remote critical care services as equivalent to bedside delivery, eliminating historical financial penalties for tele-ICU adoption.
- Edge computing latency reduction:Sub-100 millisecond response thresholds for ventilator adjustments and alarm triage now enable real-time intervention quality comparable to physical presence.
Market Restraints
- Interoperability fragmentation:Proprietary data protocols from dominant EMR vendors create integration friction that extends implementation timelines and inflates customization costs for mid-sized health systems.
- Cybersecurity liability concentration:Cloud-based patient data streams expose hospitals to HIPAA breach penalties and ransomware targeting of critical care infrastructure, elevating insurance and compliance expenditures.
- Clinical workflow disruption:Bedside nursing staff resistance to remote oversight protocols generates adoption friction that slows utilization rates even after technical deployment completion.
Strategic Opportunities
- Post-acute extension:Skilled nursing facilities and long-term acute care hospitals in Germany and Japan present underpenetrated demand for step-down monitoring that prevents costly ICU readmissions.
- Predictive algorithm licensing:FDA-cleared deterioration models trained on multi-parameter ICU data streams create recurring revenue pools through software-as-medical-device subscriptions independent of hardware sales.
- EU AI Act compliance services:Conformity assessment requirements for algorithmic decision support in European critical care settings generate advisory and validation revenue streams for vendors with established notified body relationships.
Industry Challenges
- Tele-intensivist credentialing complexity:State-level medical licensure compacts remain incomplete across US jurisdictions, forcing multi-state health systems to maintain redundant staffing pools or restrict remote coverage to licensed territories.
- Alarm fatigue remediation:False-positive rates exceeding eighty-five percent in conventional ICU monitoring erode clinical trust in automated alerts, requiring substantial retraining of predictive models on institution-specific patient populations.
- Legacy EMR integration:Decades-old hospital information systems lack API architectures capable of real-time bidirectional data exchange, necessitating expensive middleware development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tele Intensive Care Unit Market |
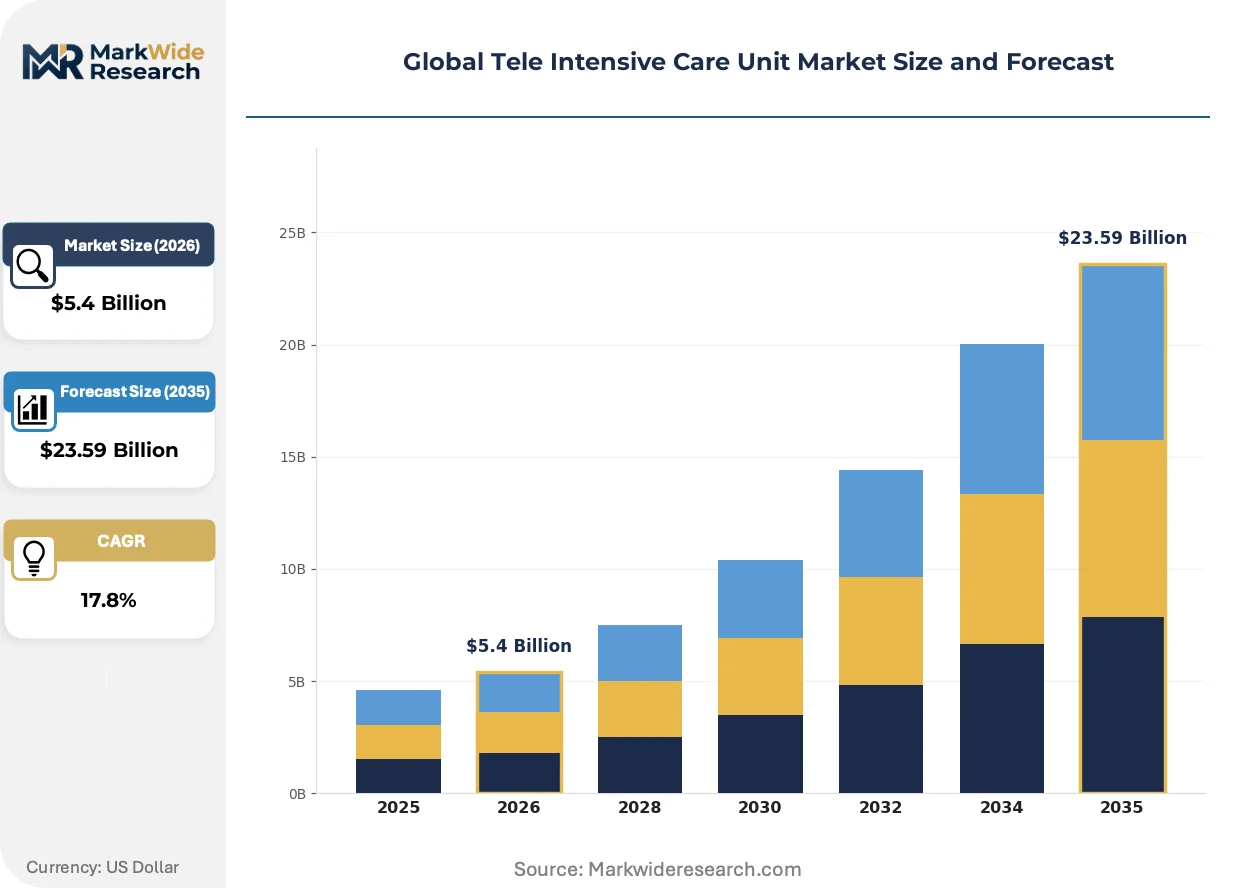
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $23.59 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Real-Time Monitoring, Remote Consultation, Predictive Analytics, Alarm Management Application: Critical Care, Respiratory Support, Postoperative Care, Neurological Monitoring, Trauma Management End User: Specialty Clinics, Emergency Departments, Long-Term Care Facilities, Rehabilitation Centers Deployment Mode: Cloud-Based, On-Premise, Hybrid, Edge Computing |
| Companies Covered | Philips, GE Healthcare, Siemens Healthineers, Medtronic, Inova, Banner Health, Hicuity Health, Advanced ICU Care, iMDsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tele Intensive Care Unit Market Shifts & Advancements
Tele-ICU platforms are converging with ambient clinical intelligence and generative diagnostic interfaces, transforming remote monitoring from reactive alarm management to anticipatory clinical decision orchestration.
Multiparameter wearable sensors are miniaturizing from bedside tethered devices to patch-based continuous monitoring systems that transmit core vitals, respiratory patterns, and neuromuscular signals through low-energy Bluetooth protocols. Community hospitals and surgical recovery wards are adopting these platforms to extend critical care surveillance beyond traditional ICU boundaries without capital-intensive infrastructure. This sensor miniaturization is compressing the addressable market for conventional telemetry hardware while expanding software and algorithmic revenue pools.
The EU AI Act's risk classification framework for medical decision support algorithms imposes conformity obligations on predictive analytics modules deployed in European critical care settings, mandating human oversight protocols and algorithmic transparency documentation. Vendors must now maintain separate product development tracks for US FDA clearance pathways and European conformity assessment, fragmenting engineering resources and extending commercialization timelines. University hospital networks in France and Germany are prioritizing procurement of platforms with established notified body certifications, creating first-mover advantages for early compliance investments.
Health system procurement departments are consolidating vendor relationships around enterprise-wide platform contracts that bundle tele-ICU services with broader critical care informatics ecosystems, displacing best-of-breed point solutions. This buyer concentration compresses sales cycles for integrated platform vendors while marginalizing specialized telemetry suppliers lacking EMR or imaging workflow adjacencies. The shift is most pronounced in US health systems exceeding five hundred licensed beds, where procurement committees now mandate interoperability certification with dominant EMR architectures as a threshold qualification criterion.
Global Tele Intensive Care Unit Market Segmentation
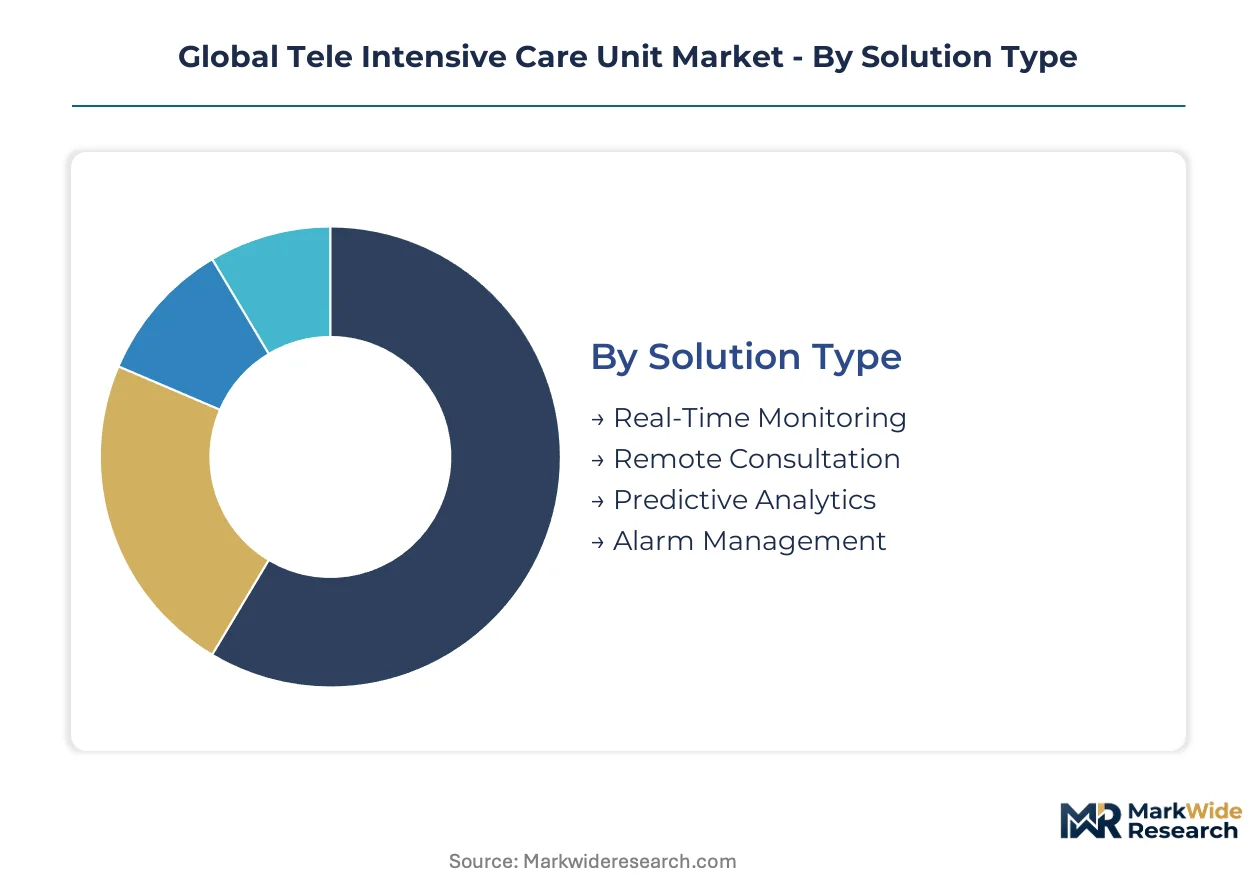
Tele-ICU procurement patterns diverge sharply across solution architectures and care settings, with cloud-native platforms displacing legacy infrastructure while predictive modules command premium pricing. Understanding segment-level substitution dynamics helps vendors prioritize R&D investment and distribution partnerships.
Solution Type:
Real-time monitoring solutions face intensifying substitution pressure from wearable telemetry and ambient clinical intelligence platforms that bypass traditional bedside hardware.
- Real-Time Monitoring:Continuous audio-visual and physiological surveillance systems transmit vital signs, ventilator parameters, and video feeds to centralized command centers with sub-second latency. Demand concentrates in US health systems exceeding three hundred licensed beds, where CMS reimbursement parity for remote critical care services justifies infrastructure expenditure. Staffing deficits exceeding projected intensivist shortfalls compel centralized coverage models.
- Predictive Analytics:Machine learning algorithms trained on multi-parameter ICU data streams flag patient deterioration before conventional threshold breaches, reducing false-alarm fatigue. German university hospital networks prioritize procurement of FDA-cleared and EU MDR-conformant modules, where the EU AI Act's risk classification framework mandates human oversight protocols and algorithmic transparency documentation.
- Remote Consultation:Synchronous video-based intensivist access for rural and community facilities lacking on-site specialist coverage.
- Alarm Management:Intelligent triage systems that suppress clinically insignificant alerts and escalate critical events to appropriate response teams.
Real-time monitoring retains volume leadership; predictive analytics holds the steepest expansion curve.
Application:
Cost tier differentiation separates capital-intensive critical care deployments from lower-acuity extensions where sensor miniaturization enables scalable subscription models.
- Critical Care:Full-spectrum remote oversight of mechanically ventilated, hemodynamically unstable patients requiring continuous specialist intervention. US academic medical centers anchor demand, where Joint Commission accreditation standards and malpractice liability considerations accelerate tele-ICU infrastructure investment.
- Respiratory Support:Specialized monitoring of ventilator-dependent patients with emphasis on weaning protocols and acute respiratory distress syndrome management. Japanese long-term acute care hospitals present underpenetrated demand for step-down surveillance that prevents costly ICU readmissions.
- Postoperative Care:Surveillance of surgical recovery patients transitioning from ICU to step-down units.
- Neurological Monitoring:Remote interpretation of intracranial pressure, cerebral perfusion, and seizure activity patterns.
- Trauma Management:Time-critical coordination between field emergency services and receiving trauma centers.
Critical care commands the highest per-bed revenue; respiratory support is gaining share fastest among post-acute extensions.
End User:
Customer type fragmentation creates divergent procurement pathways, with health system consolidation favoring enterprise-wide platform contracts over point solutions.
- Emergency Departments:Triage and resuscitation oversight for undifferentiated critically ill patients presenting through unscheduled admission. US urban safety-net hospitals concentrate demand, where ED boarding of ICU-level patients stretches physical capacity and intensivist availability.
- Long-Term Care Facilities:Skilled nursing and post-acute settings seeking to reduce preventable transfers through continuous physiological surveillance. German and Japanese reimbursement frameworks increasingly recognize remote monitoring as equivalent to on-site physician presence.
- Specialty Clinics:Procedure-focused centers requiring peri-procedural critical care backup.
- Rehabilitation Centers:Step-down monitoring for patients recovering from critical illness with residual physiological instability.
Emergency departments retain volume leadership; long-term care facilities show the steepest expansion trajectory.
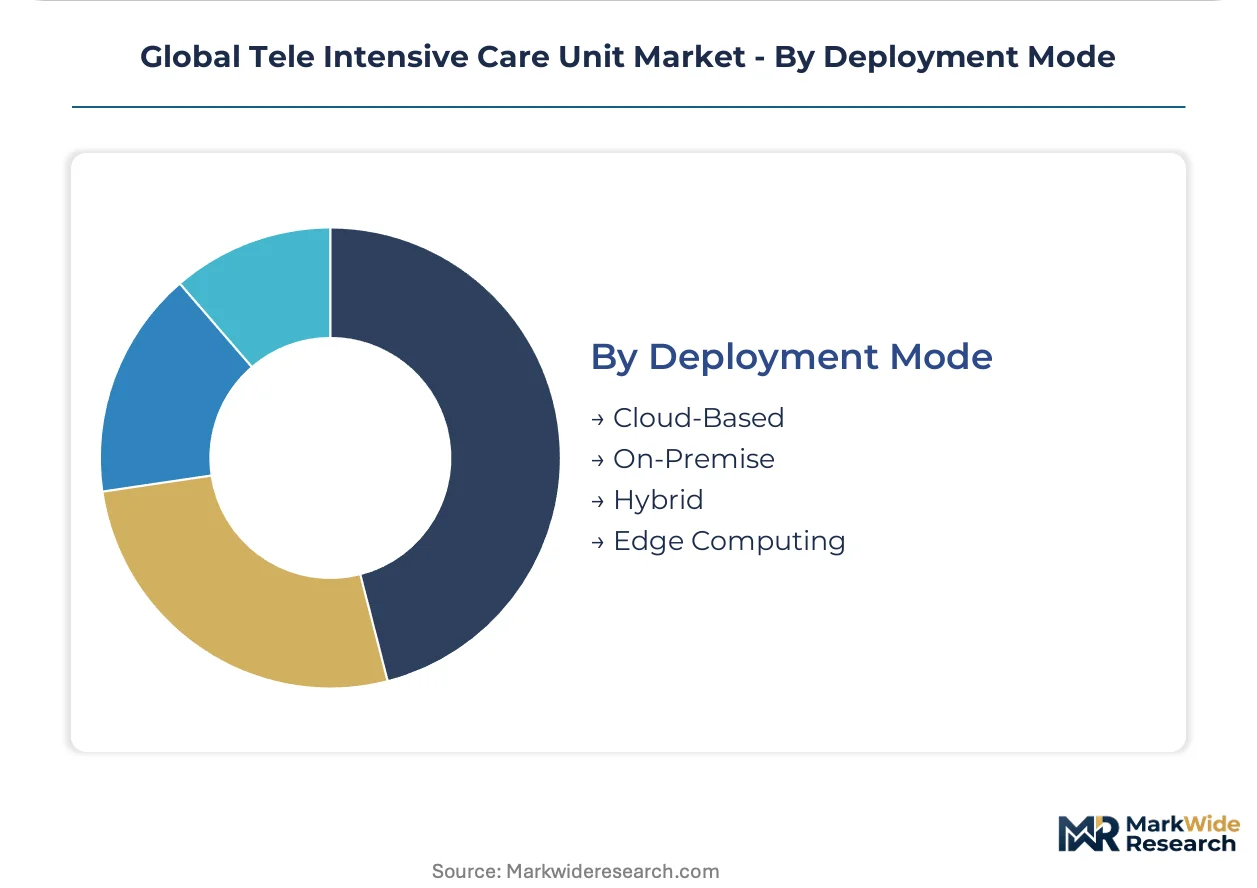
Deployment Mode:
Supply concentration among hyperscale cloud providers is compressing deployment timelines and restructuring vendor professional services revenue models.
- Cloud-Based:Scalable architectures hosted on third-party infrastructure eliminating capital expenditure and IT staffing requirements for individual hospitals. Mid-sized US health systems lacking dedicated 24/7 critical care IT operations concentrate demand, where eighteen-month deployment cycles compress to under six weeks.
- Edge Computing:Distributed processing architectures reducing latency for ventilator adjustments and alarm triage through local computation. Siemens Healthineers and GE Healthcare anchor development in European university hospital networks, where sub-100 millisecond response thresholds enable intervention quality comparable to physical presence.
- On-Premise:Legacy installations retaining data within hospital-controlled infrastructure for cybersecurity or regulatory compliance.
- Hybrid:Architectures combining local processing for latency-sensitive functions with cloud analytics for population-level model training.
Cloud-based deployment retains volume leadership; edge computing holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates among health systems in the United States, Germany, and Japan where intensivist staffing deficits and reimbursement parity create immediate deployment incentives. Cloud infrastructure investments by hyperscale providers in these markets compress implementation timelines from months to weeks.
United States
Academic medical centers in Boston, Houston, and the San Francisco Bay Area anchor demand for multi-hospital command center contracts. CMS reimbursement frameworks now recognize remote critical care services as equivalent to bedside delivery, eliminating financial penalties for tele-ICU adoption. The Joint Commission accreditation standards accelerate infrastructure investment across health systems exceeding three hundred licensed beds.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia prioritize procurement of EU MDR-conformant predictive analytics modules. The EU AI Act's risk classification framework mandates human oversight protocols and algorithmic transparency documentation for clinical decision support algorithms. Siemens Healthineers leverages its established notified body certifications to capture first-mover advantages in European conformity assessment.
Japan
Long-term acute care hospitals in Tokyo and Osaka present underpenetrated demand for step-down monitoring that prevents costly ICU readmissions. METI reimbursement frameworks increasingly recognize remote monitoring as equivalent to on-site physician presence in post-acute settings. Japanese health systems prioritize edge-computing architectures that reduce latency for ventilator adjustments through local processing.
United Kingdom
NHS Trusts in London and the Midlands consolidate procurement around enterprise-wide platform contracts that bundle tele-ICU services with broader critical care informatics ecosystems. MHRA regulatory pathways for software-as-medical-device algorithms shape product development timelines for vendors targeting UK health systems. Procurement committees mandate interoperability certification with dominant EMR architectures as threshold qualification criteria.
Australia
Rural and remote hospitals in Queensland and Western Australia concentrate demand for synchronous video-based intensivist access lacking on-site specialist coverage. The TGA clearance pathways for predictive deterioration models extend commercialization timelines for algorithm vendors entering Australian markets. Health system networks in Sydney and Melbourne pilot wearable telemetry platforms that extend critical care surveillance beyond traditional ICU boundaries.
Global Tele Intensive Care Unit Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates that leverage intensive care informatics ecosystems to anchor multi-hospital command center contracts. The vendor base spans three strategic tiers: integrated platform providers with EMR and imaging workflow adjacencies, specialized telemetry suppliers focused on real-time monitoring hardware, and cloud-native software vendors offering predictive analytics subscriptions. Dominant competitive moves include portfolio diversification into ambient clinical intelligence and strategic partnerships with hyperscale cloud providers to reduce deployment latency.
Within the integrated platform tier, Philips and GE Healthcare exemplify archetypes that bundle hardware, software, and clinical support services into enterprise-wide contracts. Siemens Healthineers occupies a differentiated position emphasizing imaging-to-ICU workflow integration in European university hospital networks. Among specialized service providers, Hicuity Health and Advanced ICU Care represent pure-play tele-ICU operators that compete on clinical staffing depth and command center scale rather than technology manufacturing.
| Leading Market Players |
|---|
| Philips |
| GE Healthcare |
| Siemens Healthineers |
| Medtronic |
| Inova |
| Banner Health |
| Hicuity Health |
| Advanced ICU Care |
| iMDsoft |
| Others |
Supply & Pricing Matrix
FDA clearance pathways for software-as-medical-device algorithms gate both supply qualification and price differentiation in tele-ICU procurement, with EU MDR and EU AI Act conformity obligations creating parallel certification premiums that segment vendor pricing power across Atlantic markets.
Pricing Analysis
FDA 510(k) and De Novo pathways dictate the pricing tier structure for predictive analytics modules, separating FDA-cleared deterioration models from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales clinical support bundling. Cost compression in mid-sized health systems is intensifying because cloud-native deployment eliminates perpetual license revenue pools. Community hospitals under three hundred licensed beds exhibit highest price sensitivity; academic medical centers with Joint Commission accreditation requirements show lowest.
Supply Chain Analysis
Strategic stockpiling of edge-computing hardware components dominates procurement behavior as hospitals prioritize sub-100 millisecond latency guarantees for ventilator adjustments. Component manufacturing concentrates in Taiwan, South Korea, and Germany for specialized telemetry chipsets and medical-grade sensors. Supply chains draw from semiconductor foundries, optical sensor suppliers, and hyperscale cloud infrastructure providers. Single-source vulnerability in FDA-designated contract manufacturers for software-as-medical-device algorithms elevates supply risk. Distribution runs through health system GPO contracts and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tele-ICU markets are recovering from pandemic-era deployment saturation as intensivist staffing deficits reaccelerate hospital command center investments, with CMS reimbursement parity eliminating cyclical financing constraints that previously delayed procurement cycles.
For Market Incumbents: Secure multi-hospital command center contracts through intensive care informatics ecosystem bundling that displaces best-of-breed point solutions. Deepen backward integration into edge-computing telemetry hardware to defend margin position against cloud-native software vendors. Invest in EU AI Act conformity assessment capabilities ahead of MDR renewal waves in German university hospital networks.
For New Entrants and Emerging Players: Lead with predictive analytics subscriptions targeting skilled nursing facilities and long-term acute care hospitals in Japan and Germany where reimbursement frameworks increasingly recognize remote monitoring equivalence. Post-acute step-down surveillance presents the most penetrable segment given lower capital intensity requirements. Pursue hospital system partnership models that embed algorithms within existing EMR workflows rather than standalone platform sales.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment architectures as hyperscale infrastructure eliminates hospital-side IT expenditure requirements. Five-to-ten year viability favors vendors with established notified body relationships and FDA-cleared algorithm portfolios over hardware-dependent legacy players. Monitor CMS reimbursement determinations for remote critical care services as the decisive inflection indicator for hospital adoption acceleration. Revision becomes warranted when intensivist staffing deficit projections cross ten thousand physician thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance for deterioration prediction algorithms unlocks US health system procurement eligibility. |
| EU MDR Conformity Assessment | Notified body certification enables access to German and French university hospital networks. |
| Hospital System Partnership | Enterprise-wide platform contracts with US health systems exceeding five hundred licensed beds anchor recurring revenue. |
| Software Companion Development | FDA-cleared software-as-medical-device modules create subscription revenue independent of hardware sales. |
| Reimbursement Strategy | CMS remote critical care parity documentation accelerates hospital finance committee approval timelines. |
Research Methodology
Initial hypotheses were tested against primary input from tele-ICU clinical directors, hospital procurement committee chairs, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body registers, and hospital procurement records. Bottom-up bed-level deployment estimates were triangulated with top-down health system expenditure analysis.
Variance decomposition across solution type, deployment mode, end-user facility category, and regional regulatory framework shaped the analytical framework over the projection horizon. CAGRs were derived from modeled adoption curves weighted by reimbursement policy implementation timelines and intensivist supply-demand gap projections. Forecast inputs incorporated EMR interoperability certification requirements and cloud infrastructure capex disclosures from hyperscale providers.
Forecasts assume regulatory continuity in CMS reimbursement frameworks and EU AI Act implementation; material policy shifts would require re-modeling. Specific risks include state-level medical licensure compact fragmentation, cybersecurity liability concentration in cloud-based deployments, and alarm fatigue remediation failures that erode clinical trust. Revision becomes warranted when false-positive rates in predictive algorithms cross institutional abandonment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telemedicine Technologies Market
Telemedicine
Healthcare IoT Telemedicine Market
Telemedicine
Tele-Epilepsy Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
Remote Healthcare Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
US Telehealth Market
Telemedicine
Global Virtual Care Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
Global Telepsychiatry Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
Telehealth Services Market
Telemedicine
Global Online Therapy Services Market
Telemedicine
Europe Telehealth Service Market
Telemedicine
Teledermatology Market
Telemedicine
Telemedicine Workstations Market