
 India Telemedicine Market | 2026-2036
India Telemedicine Market Size, Share, and Industry Trends Forecast 2026-2036
India Telemedicine Market Insights
Karnataka is narrowing the urban-rural care divide through its cluster of health-tech infrastructure investments. Apollo TeleHealth Services leverages its hospital network density to sustain dominance in specialty teleconsultations across southern states. Practo Technologies anchors the software platform segment with its physician-facing practice management tools, while MFine differentiates through diagnostic integration with tier-1 hospital chains.
Telemedicine encompasses real-time clinical consultation, asynchronous store-and-forward diagnostics, and remote patient monitoring delivered through digital communication infrastructure. The practice relies on Health Level Seven International standards for data interoperability, end-to-end encryption protocols for patient confidentiality, and minimum bandwidth thresholds of 2 Mbps for synchronous video encounters to enable reliable clinical decision-making. Software Platforms occupy the largest value pool due to recurring licensing revenue and EMR integration requirements, while Remote Monitoring within Delivery Mode represents the fastest structural expansion as chronic disease management shifts from episodic clinic visits to continuous data streams. Specialty Care services command premium pricing relative to General Practice owing to neurologist and cardiologist scarcity outside metropolitan corridors.
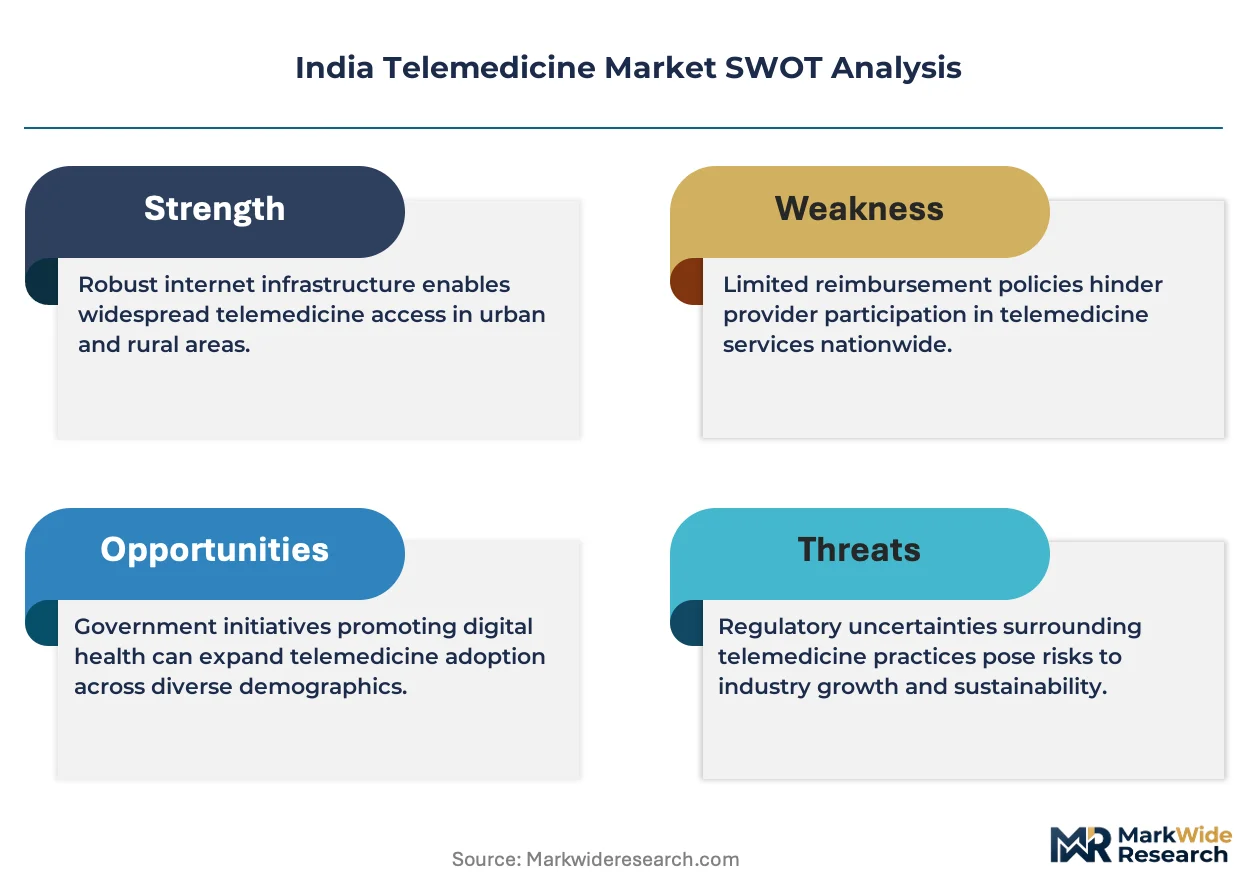
CDSCO governs software-as-medical-device classifications for diagnostic algorithms, while the Medical Council of India and state-level telemedicine boards enforce practitioner credentialing and cross-border prescription validity. The Telemedicine Practice Guidelines issued by the Ministry of Health mandate informed consent documentation and define the scope of teleconsultation versus in-person referral requirements. Stakeholders must monitor whether the PLI scheme for domestic electronics manufacturing extends to wearable diagnostic hardware, as local production incentives would reshape procurement economics for hospital systems and insurance-linked preventive care programs.
Market Dynamics
The Ministry of Health and Family Welfare's eSanjeevani platform is consolidating provider participation through standardized credentialing workflows, while state-level health missions in Maharashtra and Karnataka are digitizing public hospital networks at scale.
Growth Catalysts
- Telemedicine Practice Guidelines:The Ministry of Health's updated framework mandates informed consent documentation and clarifies teleconsultation scope, reducing legal ambiguity for practitioners entering virtual care delivery.
- Rural broadband expansion:BharatNet infrastructure deployment is connecting tier-3 cities and village clusters, enabling synchronous video consultations that previously failed minimum bandwidth thresholds.
- Chronic disease prevalence:Rising diabetes and cardiovascular case loads in Telangana and Karnataka are pushing patients toward remote patient monitoring solutions that reduce episodic clinic visits.
Market Restraints
- Hardware cost concentration:Wearable diagnostic devices and peripheral equipment remain import-dependent, exposing procurement budgets to currency volatility and customs duty fluctuations.
- Credentialing fragmentation:State-level telemedicine boards operate with inconsistent cross-border prescription validity rules, creating compliance complexity for multi-state hospital networks.
- Diagnostic algorithm classification:CDSCO's evolving software-as-medical-device framework delays product commercialization timelines for AI-enabled triage tools.
Strategic Opportunities
- PLI scheme extension:Domestic electronics manufacturing incentives could shift procurement economics for hospital systems if wearable diagnostic hardware gains eligibility under the production-linked incentive framework.
- Insurance-linked preventive care:IRDAI-mandated health coverage expansion is creating reimbursement pathways for continuous monitoring services tied to risk-adjusted premium models.
- Diagnostic integration:Convergence of teleconsultation platforms with laboratory information systems enables end-to-end care orchestration from symptom triage to pathology report delivery.
Industry Challenges
- EMR integration complexity:Hospital information systems built on legacy architectures require costly middleware development to achieve Health Level Seven International interoperability with cloud-native telemedicine platforms.
- Specialist workforce distribution:Neurologist and cardiologist scarcity outside metropolitan corridors limits the clinical depth of virtual consultations in tier-2 and tier-3 catchment areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Telemedicine Market |
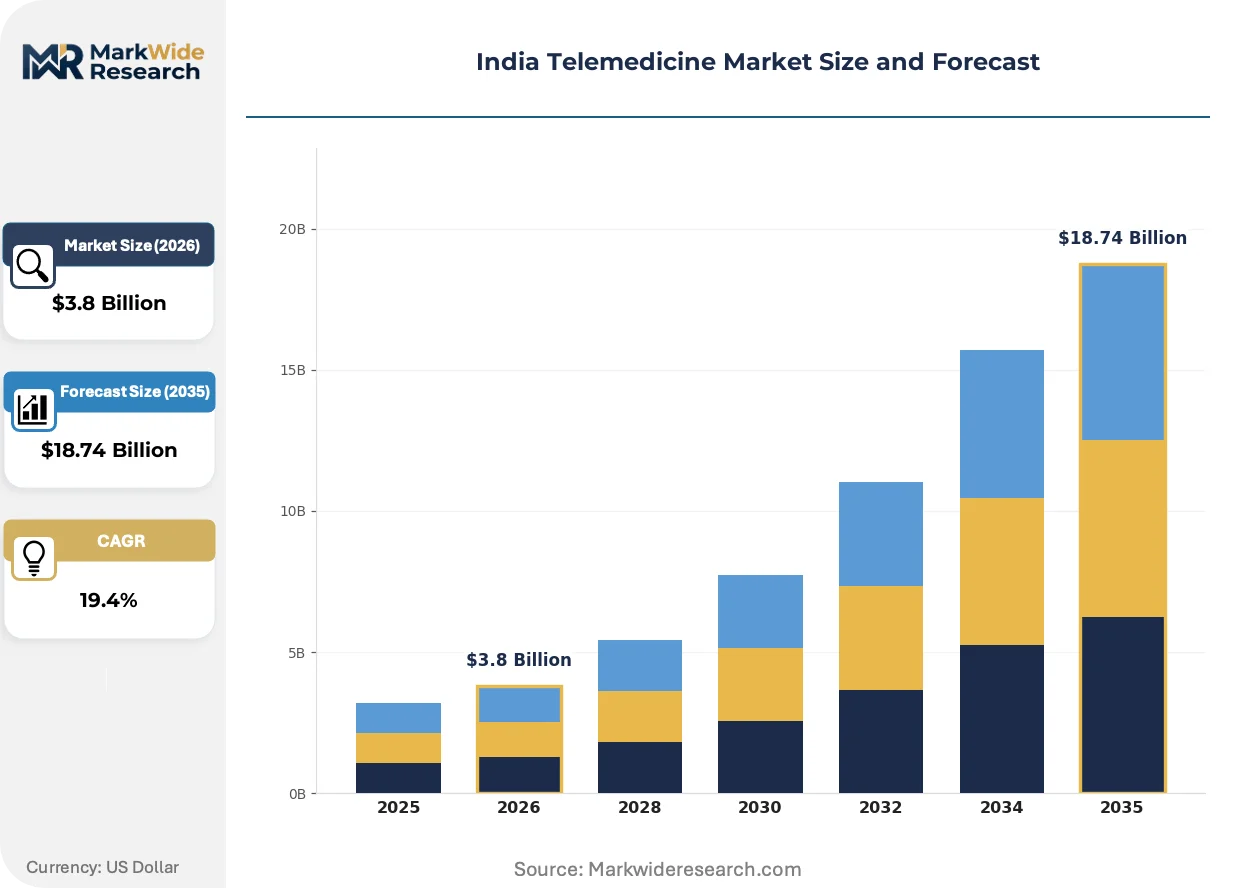
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Platforms, Communication Devices, Diagnostic Tools, Wearable Technology End User: Patients, Healthcare Providers, Insurance Companies, Corporate Sector Delivery Mode: Video Consultation, Remote Monitoring, Mobile Apps, Chat-based Services Service Type: General Practice, Specialty Care, Mental Health Services, Preventive Care |
| Companies Covered | eSanjeevani, Lybrate, Apollo TeleHealth Services, Netmeds Marketplace, PharmEasy, Tata 1mg Healthcare Solutions, MediBuddy, MFine, Practo Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Telemedicine Market Trends and Innovations
Digital infrastructure investments are compressing the urban-rural care divide while regulatory clarity is accelerating platform consolidation among organized hospital networks.
Artificial intelligence-enabled triage engines are virtualizing the initial patient encounter layer. Primary health centers in Karnataka and Telangana are deploying symptom-checker algorithms to route cases before physician involvement. This compression of front-line assessment is reallocating specialist bandwidth toward complex diagnostic decisions.
The Telemedicine Practice Guidelines issued by the Ministry of Health are mandating audit trails for prescription issuance and consultation documentation. Hospital compliance departments are restructuring workflows to capture timestamped video recordings and encrypted data transmission logs. Specialty care providers in Maharashtra are investing most heavily in medico-legal infrastructure to satisfy cross-border consultation requirements.
Subscription-based care packages are displacing per-consultation billing in employer-sponsored health programs. Corporate wellness vendors are bundling unlimited teleconsultation access with preventive screening credits, shifting revenue predictability toward recurring models. This transition is most visible in Bangalore and Hyderabad's technology sector employee bases, where annual contracts now dominate procurement negotiations.
India Telemedicine Market Segmentation
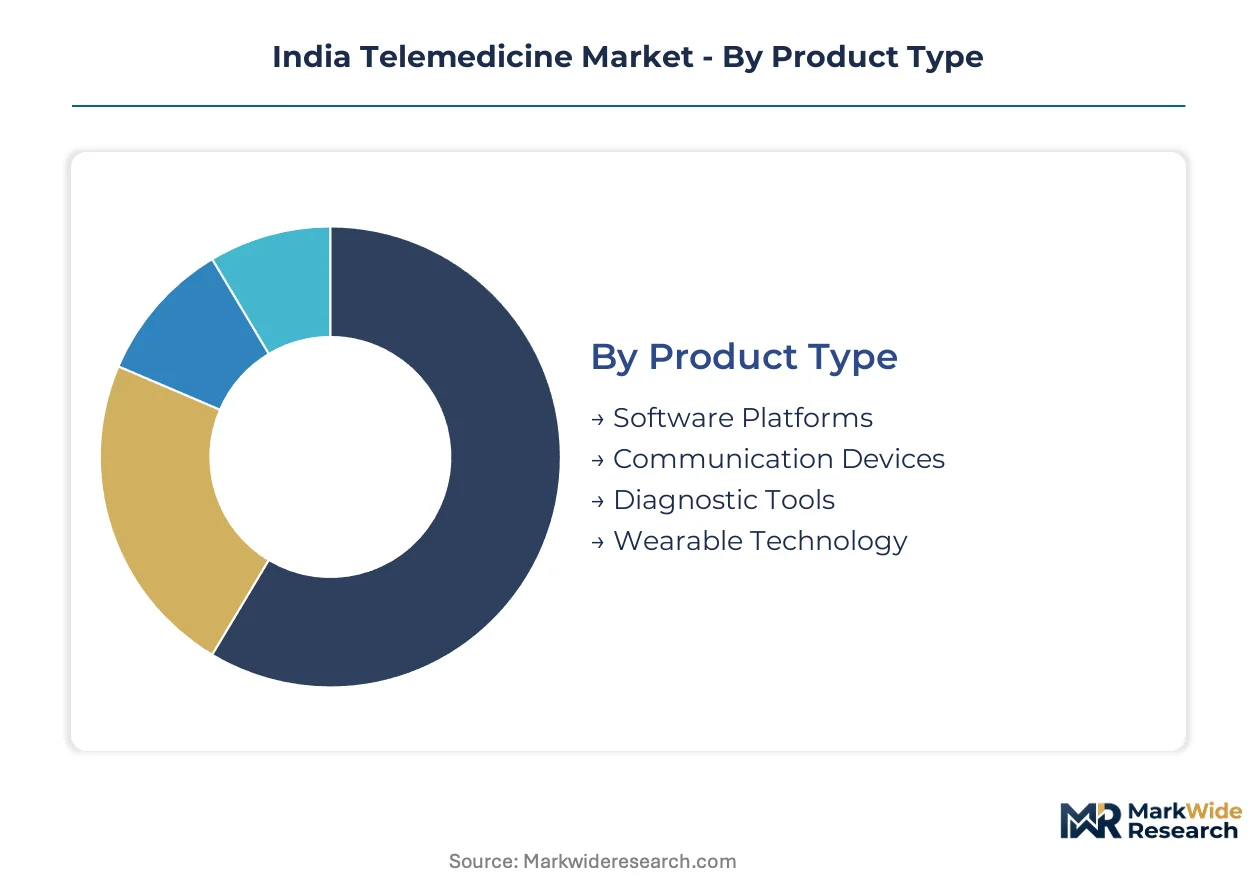
Telemedicine market segmentation reveals how technology infrastructure, clinical workflows, and payment models intersect to create distinct value pools. Each dimension captures different procurement behaviors and regulatory exposure across India's heterogeneous healthcare landscape.
Product Type:
Cost tier determines procurement cycles and margin structures across hardware-dependent versus software-native offerings.
- Software Platforms:Cloud-native architectures with EMR integration and Health Level Seven International interoperability form the technical backbone. Maharashtra and Karnataka hospital networks are consolidating vendor relationships here to reduce middleware expenditure.
- Communication Devices:Dedicated video endpoints and peripheral kits with minimum 2 Mbps bandwidth optimization. BharatNet infrastructure expansion in Telangana is unlocking addressable demand previously constrained by connectivity gaps.
- Diagnostic Tools:Digital stethoscopes, otoscopes, and dermoscopes with store-and-forward capability.
- Wearable Technology:Continuous glucose monitors and cardiac event recorders with cellular telemetry.
Software Platforms hold installed capacity. Wearable Technology is rotating up the share rankings.
End User:
Customer type dictates pricing power, contract duration, and regulatory compliance burden across the ecosystem.
- Patients:Individual consumers accessing direct-to-consumer teleconsultation through mobile interfaces. Tier-2 and tier-3 city adoption is accelerating as eSanjeevani platform penetration deepens.
- Healthcare Providers:Hospital systems and physician practices licensing enterprise platforms with credentialing workflow integration. CDSCO software-as-medical-device classifications are extending procurement due diligence timelines for this segment.
- Insurance Companies:Payors reimbursing teleconsultation and remote monitoring as covered benefits under IRDAI-mandated expansion.
- Corporate Sector:Employers bundling unlimited access into wellness programs with annual contract structures.
Healthcare Providers anchor current revenue concentration. Corporate Sector contracts are climbing the fastest as Bangalore and Hyderabad technology employers scale enrollment.
Delivery Mode:
Application determines bandwidth requirements, clinical use cases, and reimbursement eligibility under Telemedicine Practice Guidelines.
- Video Consultation:Synchronous encounters with real-time audiovisual transmission meeting 2 Mbps thresholds. Rural broadband deployment is expanding serviceable geography beyond metropolitan corridors.
- Remote Monitoring:Continuous physiological data streams from implantable or wearable sensors. Chronic disease management in Karnataka and Telangana is shifting from episodic visits to this model.
- Mobile Apps:Smartphone-native interfaces with asynchronous messaging and appointment scheduling.
- Chat-based Services:Text-first triage with escalation protocols to video or in-person referral.
Video Consultation maintains volume leadership. Remote Monitoring exhibits the steepest expansion trajectory as diabetes and cardiovascular case loads mount.
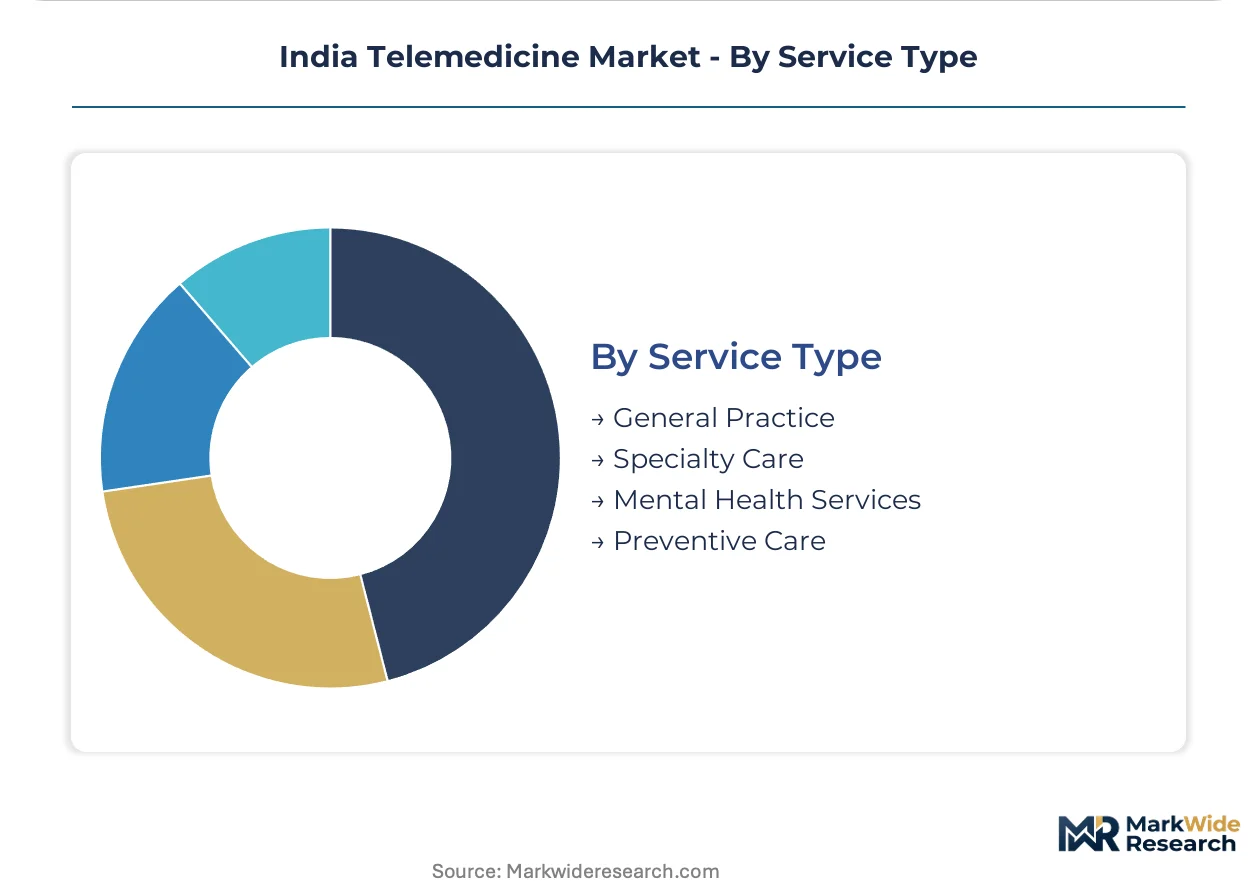
Service Type:
Maturity and margin profile separate established generalist offerings from emerging specialty verticals with premium pricing.
- General Practice:First-contact care for acute complaints and chronic disease follow-up. Primary health centers across Maharashtra are virtualizing this layer to decompress specialist queues.
- Specialty Care:Cardiology, neurology, and endocrinology consultations with scarcity-driven pricing. Metropolitan corridor concentration of qualified specialists limits virtual reach into tier-3 catchment areas.
- Mental Health Services:Psychiatric consultation and cognitive behavioral therapy with lower infrastructure requirements.
- Preventive Care:Wellness coaching, risk stratification, and screening coordination bundled into subscription packages.
General Practice commands transaction volume. Specialty Care is gaining share fastest as hospital networks monetize scarce clinical expertise through virtual channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BharatNet's fiber optic backbone underwrites telemedicine penetration into tier-3 towns and village clusters across India's interior. The national broadband mission is compressing latency thresholds that previously blocked synchronous video encounters outside metropolitan corridors.
Maharashtra
Mumbai-Pune hospital networks are consolidating enterprise telemedicine licenses to reduce middleware expenditure across legacy EMR architectures. The state health mission digitizes public hospital inventory management and referral workflows. Nashik and Nagpur clusters are deploying dedicated video endpoints with BharatNet backhaul to decompress specialist queues at tertiary centers.
Karnataka
Bangalore's health-tech infrastructure investments narrow the urban-rural care divide through cluster-based deployment models. The state telemedicine board enforces credentialing protocols that align with Ministry of Health Practice Guidelines. Mysore and Hubli-Dharwad corridors are integrating Apollo TeleHealth Services into district hospital networks for cardiology and neurology virtual consultations.
Telangana
Hyderabad's chronic disease prevalence is pushing diabetes and cardiovascular management toward continuous remote monitoring models. The state's eHealth mission mandates timestamped prescription audit trails for cross-border consultation validity. Warangal and Karimnagar sub-regions are receiving wearable diagnostic hardware through public-private partnerships with tier-1 hospital chains.
Tamil Nadu
Chennai's medical tourism infrastructure is repurposing specialty consultation capacity for domestic virtual care delivery. The state health department integrates telemedicine modules into its existing hospital information system backbone. Coimbatore and Madurai industrial corridors are piloting employer-sponsored subscription packages for manufacturing sector workforces.
Delhi-NCR
The National Capital Region's regulatory proximity to CDSCO and the Medical Council of India concentrates compliance infrastructure for multi-state hospital networks. Central government health schemes are piloting diagnostic algorithm integration with eSanjeevani platform workflows. Gurugram and Noida technology parks are driving corporate wellness procurement toward annual unlimited-access contracts.
India Telemedicine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in device manufacturing and algorithm development. The vendor base organizes around three archetypes: hospital network affiliates leveraging captive patient flows, independent software platforms monetizing physician practice management tools, and diagnostic-integrated services bundling laboratory connectivity. Consolidation pressure is accelerating through strategic partnerships between teleconsultation providers and pathology chains, while credentialing workflow standardization is raising compliance costs for sub-scale entrants.
Among hospital network-affiliated platforms, Apollo TeleHealth Services anchors the specialty consultation tier through its southern India infrastructure density. Practo Technologies occupies a position within the software-native segment, exemplifying physician-facing practice management archetypes. MFine represents the diagnostic-integrated model, sitting within the convergence space between teleconsultation and laboratory information systems. These three patterns illustrate how market position depends on upstream control over either clinical workforce, software distribution, or diagnostic data flows.
| Leading Market Players |
|---|
| eSanjeevani |
| Lybrate |
| Apollo TeleHealth Services |
| Netmeds Marketplace |
| PharmEasy |
| Tata 1mg Healthcare Solutions |
| MediBuddy |
| MFine |
| Practo Technologies |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in software platform licensing across Maharashtra and Karnataka hospital networks is compressing vendor margins while pushing procurement toward bundled diagnostic-integrated contracts. This utilization dynamic rewards Apollo TeleHealth Services and MFine with pricing power from captive patient flows, while independent SaaS vendors absorb discount pressure to maintain installed base.
Pricing Analysis
Volume-discount tiering structures separate enterprise hospital network licenses from per-physician SaaS subscriptions and direct-to-consumer pay-per-consult models. Three-tier pricing stratifies across premium specialty consultations, standard general practice encounters, and economy-tier chat-based triage. Pricing pressure stems from BharatNet-enabled rural expansion forcing tier-3 market entry at lower price points. Corporate wellness buyers in Bangalore and Hyderabad exhibit lowest price sensitivity due to annual contract bundling, while individual patients in tier-2 cities drive hardest bargain hunting.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Dixon Technologies, and domestic EMS providers for wearable diagnostic hardware assembly. Component sourcing draws from China for MEMS sensors, Taiwan for semiconductor modules, and South Korea for display panels. Single-source vulnerability concentrates in cellular telemetry chipsets subject to DGFT import licensing fluctuations. Distribution runs through hospital system procurement committees, GPO contracts, and direct-to-patient e-commerce channels with state-level telemedicine board compliance overlay.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India telemedicine market is recovering from pandemic-era demand spikes toward sustainable chronic disease management baselines. PLI scheme eligibility expansion for wearable hardware represents the cyclical catalyst resetting procurement economics.
For Market Incumbents: Build credentialing workflow moats through Apollo TeleHealth Services' state telemedicine board integrations to lock out sub-scale competitors. Defensive consolidation should prioritize backward integration into diagnostic laboratory partnerships, countering the threat from MFine's end-to-end care orchestration. Capacity addition in Telangana's Warangal-Karimnagar corridor captures BharatNet infrastructure deployment ahead of rival platform licensing. For New Entrants and Emerging Players: Tier-3 city mental health services in Karnataka's Mysore-Hubli corridor represent the most penetrable entry point given lower specialist concentration and lighter regulatory scrutiny. Preventive care subscription packaging for manufacturing sector employers in Tamil Nadu's Coimbatore industrial belt offers second white-space target. Go-to-market should anchor in IRDAI-mandated insurance reimbursement pathway navigation rather than direct consumer acquisition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic-integrated platforms with laboratory information system connectivity. Long-term viability across the analysis window favors hospital network-affiliated models over standalone SaaS vendors facing middleware integration cost compression. Acquisition target archetype: specialty consultation platforms with established CDSCO software-as-medical-device classification. Signal to watch: PLI scheme notification for wearable diagnostic hardware eligibility as margin structure inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Software-as-Medical-Device Classification | Accelerates commercialization timelines for AI-enabled triage tools through regulatory clarity. |
| Hospital System Partnership | Apollo TeleHealth Services leverages southern India infrastructure density for specialty consultation lock-in. |
| Diagnostic Integration | MFine's laboratory connectivity enables end-to-end care orchestration from symptom to pathology. |
| Reimbursement Strategy | IRDAI-mandated coverage expansion creates payor pathways for continuous monitoring services. |
| Geographic Expansion | BharatNet backhaul unlocks tier-3 addressable demand previously blocked by bandwidth thresholds. |
Research Methodology
A standing panel of hospital CIOs, state telemedicine board administrators, CDSCO regulatory affairs specialists, and GPO contracts managers provided ongoing calibration against secondary validation. Primary interviews combined with Ministry of Health eSanjeevani platform statistics, IRDAI coverage expansion filings, BharatNet infrastructure deployment reports, and hospital procurement database extracts. Bottom-up patient encounter volume modeling triangulated against top-down healthcare expenditure flow analysis.
Scenario-bracketing framed optimistic, baseline, and constrained demand paths across the projection horizon. Segmentation dimensions modeled include delivery mode, service type, end-user archetype, and state-level regulatory cluster. CAGRs derived from compound growth trajectory fitting to annualized encounter volume and platform licensing revenue estimates. Industry-specific forecast inputs incorporated chronic disease prevalence curves from Karnataka and Telangana health mission data.
Stress conditions across PLI scheme implementation timing, CDSCO algorithm classification delays, and BharatNet deployment pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about specialist workforce distribution and reimbursement pathway maturation. Quarterly review of state telemedicine board credentialing standardization and wearable hardware import duty schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
India Telehealth Services Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
Emergency Telemedicine Services Market
Telemedicine
US Virtual Care Market
Telemedicine
US Virtual Visits Market
Telemedicine
Telemedicine Service Market
Telemedicine
Tele-Care Market
Telemedicine
Remote Healthcare Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
Tele-ICU Services Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
Telehealth Software Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
GCC Telemedicine Market
Telemedicine
AI in Telemedicine Market
Telemedicine
Asia-Pacific Ehealth Market