
 Telepathology Service Market | 2026-2036
Telepathology Service Market Size, Share, and Industry Trends Forecast 2026-2036
Telepathology Service Market Outlook
CE marking under the EU MDR is pivoting the cost-of-entry calculus for telepathology platform vendors seeking European market access. Danaher Corporation leverages its diagnostics conglomerate structure to sustain integrated hardware-software ecosystems across clinical laboratories. Proscia Inc. anchors its competitive position through cloud-native pathology workflows that dominate enterprise deployments in academic medical centers.
Telepathology service denotes the remote practice of pathology via digital image transmission, encompassing whole-slide imaging at 20x-40x magnification, real-time video microscopy, and asynchronous consultation platforms designed to render diagnostic opinions without physical specimen handling. Diagnostic Services command the largest revenue share within Service Type segmentation, while Cloud Storage within Technology is displacing on-premises architectures as health systems prioritize interoperability and disaster recovery. Hospitals represent the most concentrated End User segment, though Research Laboratories are capturing margin pools through high-value contract pathology services.
FDA digital pathology device regulations, EU MDR CE marking requirements, and HIPAA security rule provisions collectively shape platform validation, data governance, and cross-border image exchange protocols in this market. The FDA's enforcement discretion policies for artificial intelligence-assisted diagnosis are forcing vendors to clarify algorithmic performance claims prior to commercial deployment. Stakeholders must monitor evolving reimbursement codes for remote pathology interpretation, as payer coverage decisions will determine adoption velocity in community hospital settings.
Market Dynamics
Hospital networks in the United States are consolidating diagnostic workflows around cloud-native platforms, compressing vendor selection cycles and elevating interoperability requirements above standalone imaging performance.
Growth Catalysts
- FDA enforcement discretion policies:Artificial intelligence-assisted diagnostic algorithms now face clarified validation pathways, accelerating commercial deployment timelines for vendors with robust clinical evidence packages.
- Integrated delivery networks:Health system consolidation across the United States is standardizing remote pathology procurement across dozens of affiliated hospitals simultaneously.
- Whole-slide imaging at 40x magnification:Diagnostic-grade resolution thresholds now match physical microscopy, eliminating technical barriers to remote primary diagnosis.
Market Restraints
- EU MDR CE marking costs:European market entry now demands substantially expanded clinical validation budgets, compressing margins for mid-scale platform vendors.
- Cloud storage dependency:Health system disaster recovery requirements are concentrating vendor selection around hyperscaler partnerships, limiting niche provider competitiveness.
- Specialist pathologist availability:Remote consultation demand is outstripping credentialed diagnostic workforce expansion, creating service delivery bottlenecks.
Strategic Opportunities
- Community hospital settings:Payer coverage decisions for remote pathology interpretation remain unsettled, creating first-mover advantage for vendors securing favorable reimbursement codes.
- Research laboratory contract services:High-value pathology outsourcing is capturing margin pools from pharmaceutical clinical trials and academic biospecimen analysis.
- HIPAA security rule convergence with state privacy laws:Unified compliance frameworks are enabling cross-border image exchange protocols previously blocked by jurisdictional fragmentation.
Industry Challenges
- Digital pathology device platform validation:FDA 510(k) clearance timelines for novel imaging hardware extend 18-24 months, delaying revenue recognition for R&D-intensive vendors.
- Legacy laboratory information system integration:Hospital IT departments face substantial middleware development costs to connect cloud-native pathology workflows with entrenched on-premises infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telepathology Service Market |
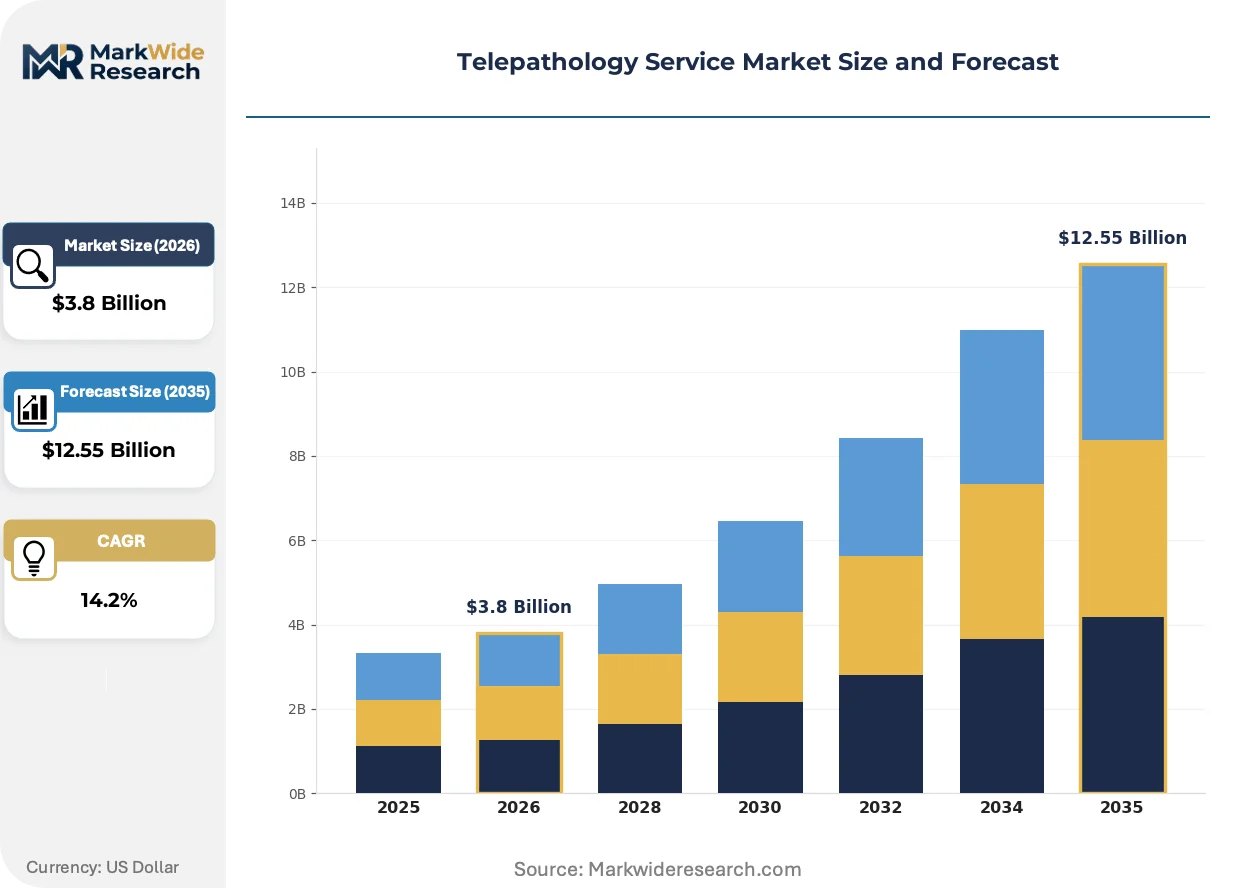
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Diagnostic Services, Therapeutic Services, Educational Services, Research Services Technology: Image Analysis, Digital Scanning, Remote Consulting, Cloud Storage End User: Hospitals, Research Laboratories, Educational Institutions, Private Clinics Delivery Mode: Web-based, Mobile Application, Software-as-a-Service, On-premises |
| Companies Covered | Danaher Corporation, Proscia Inc., F. Hoffmann-La Roche Ltd., Sectra AB, 3DHISTECH Ltd., Leica Biosystems Nussloch Gmbh, PathAI Inc., Visiopharm A/S, Koninklijke Philips NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telepathology Service Market Strategic Shifts
Telepathology platforms are converging around software-defined architectures that decouple image acquisition from diagnostic interpretation, enabling new service delivery models.
Whole-slide imaging scanners is modularizing hardware configurations, allowing laboratories to scale throughput incrementally rather than committing to monolithic capital investments. Academic medical centers in the United States are adopting expandable chassis designs that accommodate fluorescence and brightfield modalities within identical footprints. This architecture is modularizing vendor competitive dynamics, compressing switching costs and elevating software ecosystem stickiness above hardware lock-in.
EU MDR CE marking requirements are recalibrating European market access strategies, forcing vendors to front-load clinical performance studies ahead of commercial launch. The regulation's heightened scrutiny of software-as-medical-device classifications is extending validation timelines for algorithm-assisted diagnostic platforms. Vendors targeting Germany, France, and the Netherlands are establishing dedicated regulatory affairs functions to navigate notified body capacity constraints.
Subscription-based platform licensing is displacing perpetual software purchases across United States hospital networks, aligning vendor incentives with ongoing system utilization. Integrated delivery networks are negotiating enterprise-wide agreements that bundle image storage, pathologist access, and AI-assisted screening tools under single contracts. This shift is most visible in the southeastern and midwestern United States, where health system consolidation has concentrated purchasing authority within centralized procurement functions.
Telepathology Service Market Segmentation
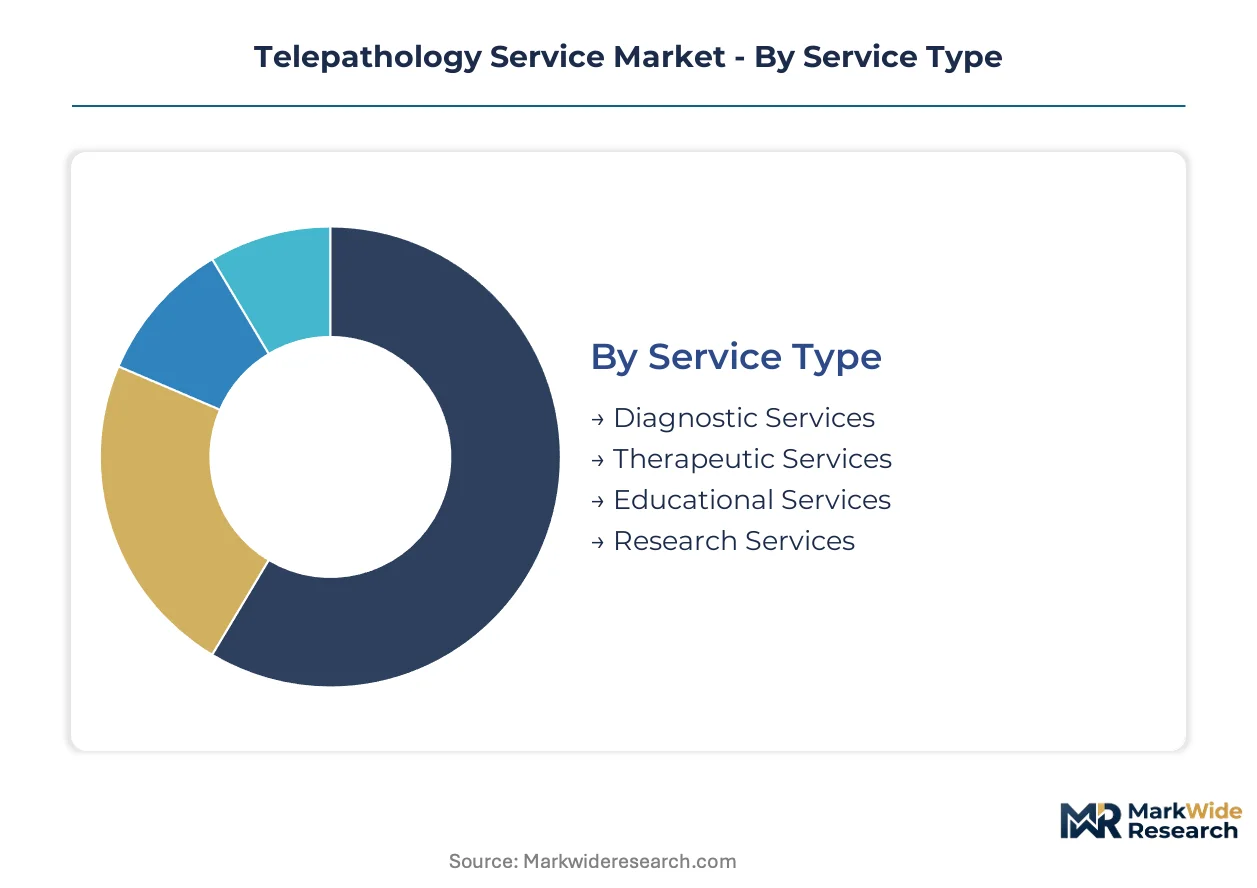
Telepathology service segmentation reflects divergent buyer priorities across clinical urgency, infrastructure maturity, and regulatory exposure. Procurement patterns cluster around diagnostic workflow integration needs rather than standalone technology specifications.
Service Type:
Cost tier differentiation separates episodic consultative purchases from recurring operational expenditures across health system budgets.
- Diagnostic Services:Primary diagnosis of histopathology specimens via whole-slide imaging at 20x-40x magnification supports remote primary diagnosis without physical slide handling. United States hospital networks concentrate procurement here as integrated delivery networks consolidate pathology workflows across affiliated facilities. FDA enforcement discretion policies for AI-assisted algorithms are accelerating validation investments among vendors serving this segment.
- Therapeutic Services:Treatment planning support through molecular pathology consultation and biomarker interpretation guides oncology therapeutic selection. Academic medical centers in the United States drive demand as precision medicine programs expand molecular tumor board operations. Reimbursement code development for remote therapeutic pathology interpretation remains unsettled, compressing near-term adoption velocity.
- Educational Services:Remote training and competency assessment for pathology residents leverages archived case libraries and live streaming microscopy.
- Research Services:Contract pathology services for pharmaceutical clinical trials and biospecimen analysis capture high-margin outsourcing opportunities.
Volume sits with Diagnostic Services; growth tilts toward Research Services.
Technology:
Application maturity determines whether buyers prioritize acquisition hardware, interpretation software, or infrastructure resilience.
- Cloud Storage:Scalable image archiving with disaster recovery capabilities and cross-site accessibility displaces on-premises architectures as health systems prioritize interoperability. United States integrated delivery networks negotiate enterprise-wide agreements bundling storage with pathologist access and AI tools. Hyperscaler partnership requirements concentrate vendor selection around Amazon Web Services, Microsoft Azure, and Google Cloud Platform relationships.
- Image Analysis:Algorithm-assisted quantification of histological features and biomarker scoring accelerates diagnostic throughput in high-volume laboratories. FDA 510(k) clearance timelines for novel imaging algorithms extend validation cycles for vendors targeting clinical deployment. Academic medical centers adopt these tools for research-validated screening workflows prior to regulatory submission.
- Digital Scanning:Whole-slide imaging hardware converting glass slides into digital formats at diagnostic resolution.
- Remote Consulting:Real-time video microscopy and asynchronous consultation platforms connecting pathologists with referring sites.
Deployment scale favors Cloud Storage; capability expansion centers on Image Analysis.
End User:
Customer type dictates procurement authority concentration and contract complexity tolerance.
- Hospitals:Inpatient and outpatient diagnostic services requiring 24/7 pathology coverage drive the most concentrated procurement volumes. United States community hospital settings face specialist pathologist availability constraints that remote consultation platforms address. Subscription-based licensing models align vendor incentives with ongoing utilization across standardized enterprise deployments.
- Research Laboratories:High-throughput biospecimen analysis and pharmaceutical contract services command premium pricing for specialized expertise. EU MDR CE marking requirements for software-as-medical-device classifications extend validation timelines for vendors targeting European research institutions. Dedicated regulatory affairs functions in Germany, France, and the Netherlands navigate notified body capacity constraints.
- Educational Institutions:Pathology residency training programs and continuing medical education deploy remote case review platforms.
- Private Clinics:Outpatient dermatopathology and gastrointestinal pathology consults for independent practice groups.
Revenue concentration rests with Hospitals; margin capture shifts toward Research Laboratories.
Delivery Mode:
Supply concentration among cloud infrastructure providers shapes competitive dynamics for hosted versus installed solutions.
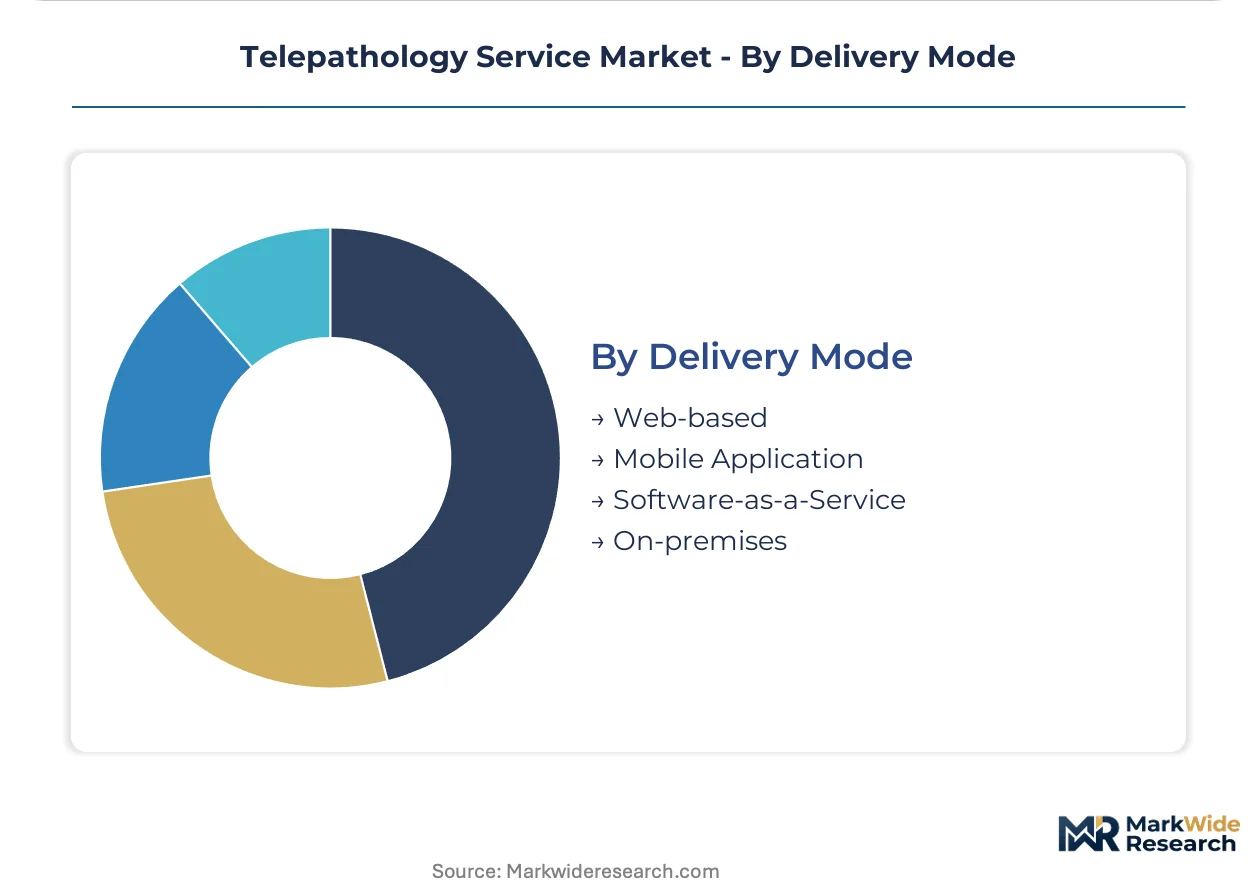
- Software-as-a-Service:Subscription licensing with continuous feature updates and managed security compliance reduces internal IT burden. United States southeastern and midwestern health systems centralize procurement authority within integrated delivery network headquarters for enterprise-wide agreements. HIPAA security rule convergence with state privacy laws enables cross-border image exchange previously blocked by jurisdictional fragmentation.
- Web-based:Browser-accessible platforms requiring minimal endpoint configuration support rapid deployment across distributed clinical sites. Legacy laboratory information system integration challenges elevate middleware development costs for hospital IT departments connecting cloud-native workflows with entrenched on-premises infrastructure.
- Mobile Application:Smartphone and tablet interfaces for urgent consultation access and image review on demand.
- On-premises:Installed software maintaining complete data custody within institutional firewalls for security-sensitive environments.
Procurement momentum favors Software-as-a-Service; compliance requirements sustain On-premises niche demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical technology zones in Massachusetts and North Carolina are concentrating telepathology R&D investment alongside FDA regulatory expertise. These clusters attract venture funding for digital pathology platforms seeking 510(k) clearance pathways. Tax incentives for life sciences infrastructure accelerate commercialization timelines for remote diagnostic technologies.
United States
Integrated delivery networks across the southeastern and midwestern states are consolidating pathology procurement under centralized headquarters functions. FDA enforcement discretion policies for AI-assisted diagnostic algorithms are clarifying validation requirements for vendors targeting clinical deployment. The Research Triangle Park in North Carolina hosts multiple digital pathology startups developing cloud-native workflows for academic medical centers.
Germany
Notified body capacity constraints under EU MDR are extending CE marking timelines for software-as-medical-device classifications. The country's national pharmaceutical regulator enforces heightened scrutiny of algorithm-assisted diagnostic platforms. Berlin and Munich industrial clusters concentrate regulatory affairs functions for vendors navigating European market access requirements.
United Kingdom
NHS pathology network consolidation is standardizing remote consultation procurement across regional hospital trusts. The country's national pharmaceutical regulator aligns with EU MDR transitional provisions for CE-marked devices. London's academic medical centers drive adoption of expandable whole-slide imaging chassis designs supporting fluorescence and brightfield modalities.
Japan
PMDA regulatory pathways for digital pathology devices are harmonizing with FDA technical standards to accelerate market entry. METI industrial policy supports precision medicine infrastructure investments in major metropolitan hospitals. The Kansai region around Osaka concentrates diagnostic equipment manufacturing partnerships with cloud storage hyperscalers.
India
CDSCO medical device regulations are evolving to accommodate software-based diagnostic platforms under risk-based classification frameworks. The country's national pharmaceutical regulator is developing guidance for AI-assisted pathology interpretation. Hyderabad and Bengaluru technology corridors attract contract research organizations delivering high-throughput biospecimen analysis for pharmaceutical clinical trials.
Telepathology Service Market Competitive Environment
United States producers anchor one tier; European specialists hold regulatory compliance advantages under EU MDR frameworks. The market structure concentrates around conglomerate diagnostics divisions with integrated hardware-software ecosystems and cloud-native platform specialists with enterprise deployment expertise. Three archetypes dominate: diversified life sciences conglomerates, pure-play digital pathology software vendors, and precision medicine AI developers. Competitive moves center on hyperscaler cloud partnerships and middleware integration capabilities for legacy laboratory information systems.
Within the conglomerate tier, Danaher Corporation and F. Hoffmann-La Roche Ltd. represent integrated diagnostics ecosystems spanning imaging hardware through clinical decision support. Proscia Inc. exemplifies the cloud-native specialist archetype with enterprise workflow platforms. These three entities occupy positions reflecting divergent strategic bets on vertical integration versus software-defined service models.
| Leading Market Players |
|---|
| Danaher Corporation |
| Proscia Inc. |
| F. Hoffmann-La Roche Ltd. |
| Sectra AB |
| 3DHISTECH Ltd. |
| Leica Biosystems Nussloch Gmbh |
| PathAI Inc. |
| Visiopharm A/S |
| Koninklijke Philips NV |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery network consolidation across the United States is compressing vendor selection cycles and mandating enterprise-wide platform standardization, forcing suppliers to absorb upfront integration costs and recoup through multi-year subscription structures rather than transactional licensing.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as hospital networks prioritize rapid deployment over capital-efficient phased rollouts. Subscription-based SaaS licensing has displaced perpetual purchases, with three-tier pricing structure across premium, standard, and economy levels differentiated by AI tool inclusion and storage scalability. Price differentiation hinges on FDA 510(k) clearance status and hyperscaler partnership tier. Pricing pressure stems from EU MDR CE marking cost absorption demands. Community hospital settings exhibit highest price sensitivity; academic medical centers prioritize capability over cost.
Supply Chain Analysis
Dual-sourcing requirements from United States integrated delivery networks mandate qualified secondary suppliers for whole-slide imaging hardware and cloud storage infrastructure. Manufacturing concentrates in the United States, Germany, and Japan for precision optics and scanning mechanics. Component dependencies include CMOS sensors, high-precision linear motors, and hyperscaler data center capacity. Single-source vulnerability runs through concentrated hyperscaler partnerships. Distribution runs through direct enterprise sales teams and specialized medical device distributors serving hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR CE marking requirements construct a cost-of-compliance moat that favors established players with dedicated regulatory affairs functions and front-loaded clinical validation budgets.
For Market Incumbents: Extend cloud-native workflow capabilities through middleware investments that bridge legacy laboratory information systems, neutralizing switching cost advantages held by entrenched on-premises vendors. Deepen hyperscaler partnerships to secure disaster recovery specifications that hospital networks now mandate. Prioritize FDA enforcement discretion policy alignment for AI-assisted diagnostic algorithms to accelerate commercial deployment timelines against emerging pure-play software competitors. For New Entrants and Emerging Players: Direct-to-pathologist SaaS platforms offer the lowest barrier-to-entry route, bypassing centralized procurement authority within integrated delivery networks. Target research laboratory contract services in pharmaceutical clinical trials, where high-value outsourcing tolerates premium pricing and regulatory timelines are less compressed. Pursue white-label middleware development for legacy system integration, capturing margin from hospital IT departments facing substantial connectivity costs. For Investors and Strategic Acquirers: The window for entry favors cloud-native platform specialists with proven enterprise deployment expertise in academic medical centers. Long-term viability rests on software-defined architectures that decouple hardware dependency and enable recurring revenue expansion. Watch FDA reimbursement code development for remote pathology interpretation as the inflection signal determining adoption velocity in community hospital settings.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperscaler Cloud Partnership | Amazon Web Services and Microsoft Azure relationships satisfy hospital disaster recovery mandates. |
| FDA 510(k) Submission Pathway | Clearance for whole-slide imaging hardware unlocks United States hospital procurement eligibility. |
| CE Marking Under EU MDR | Notified body approval enables European market access for software-as-medical-device platforms. |
| Legacy LIS Middleware Development | Integration capabilities with entrenched laboratory information systems reduce hospital IT burden. |
| Reimbursement Strategy Formulation | Favorable remote pathology interpretation codes accelerate community hospital adoption velocity. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR notified body guidance, hospital procurement databases, and GPO contracts, complemented by interviews with pathology department chairs, biomedical engineers, hospital purchasing committee members, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, hyperscaler capex disclosures, and SEC filings from diversified diagnostics conglomerates. Bottom-up service demand modeling and top-down market sizing triangulation anchored volume estimates.
Segment-level outputs across the analysis window reflect discrete modeling of service type, technology deployment mode, end user concentration, and regional regulatory cluster variations. CAGRs were derived from trend extrapolation adjusted for enforcement discretion policy impacts and reimbursement code development timelines. Forecast inputs incorporated pathologist workforce expansion constraints and integrated delivery network consolidation trajectories.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in real-time pricing transparency for enterprise SaaS agreements introduce uncertainty bands around vendor revenue share assumptions. Deviation in FDA reimbursement code finalization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
GCC Telemedicine Market
Telemedicine
Remote Healthcare Market
Telemedicine
US Telehealth Market
Telemedicine
Europe Telemedicine Market
Telemedicine
Real-Time E-Healthcare System Market
Telemedicine
Telemedicine Workstations Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
Telemedicine Cart Market
Telemedicine
US Telemedicine Market
Telemedicine
Telehealth and Telemedicine Market
Telemedicine
US Virtual Visits Market
Telemedicine
North America Telemedicine Market
Telemedicine
Global Virtual Care Market
Telemedicine
Tele-ICU Services Market
Telemedicine
Telehealth Services Market
Telemedicine
Telemedicine EMR Software Market