
 Global Telehealth Market | 2026-2036
Global Telehealth Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telehealth Market Outlook
Enterprise-grade encryption and FDA 510(k) clearance standards are redrawing competitive boundaries in telehealth delivery. Teladoc Health leverages its multispecialty physician network to sustain market presence across acute and chronic care verticals. Koninklijke Philips anchors its position through integrated remote patient monitoring hardware-software ecosystems. Epic Systems dominates hospital-centric deployment with deep electronic health record interoperability that competitors struggle to replicate.
Telehealth encompasses synchronous and asynchronous digital health service delivery through real-time video, store-and-forward imaging, and remote physiological monitoring platforms operating over encrypted IP networks. These systems transmit clinical data with latency thresholds below 400 milliseconds to support diagnostic-grade consultations across cardiology, dermatology, and behavioral health specialties. Remote patient monitoring and mobile health apps capture the fastest expansion as reimbursement codes mature and wearable biosensor accuracy improves. Cloud-based delivery modes concentrate margin pools through subscription scalability, while web-based interfaces retain share in elderly populations with limited smartphone proficiency.
FDA digital health pre-certification, HIPAA security rule enforcement, and EU MDR requirements for software-as-a-medical-device govern platform compliance costs and market access timelines. The FDA's evolving artificial-intelligence-enabled device guidance creates additional validation burdens for algorithmic diagnostic tools. Brazil's ANVISA telemedicine resolutions and India's Telemedicine Practice Guidelines under the Medical Council of India add layered jurisdictional complexity for cross-border service providers. Stakeholders must monitor reimbursement parity legislation at the state and federal levels as the decisive variable for patient volume conversion.
Market Dynamics
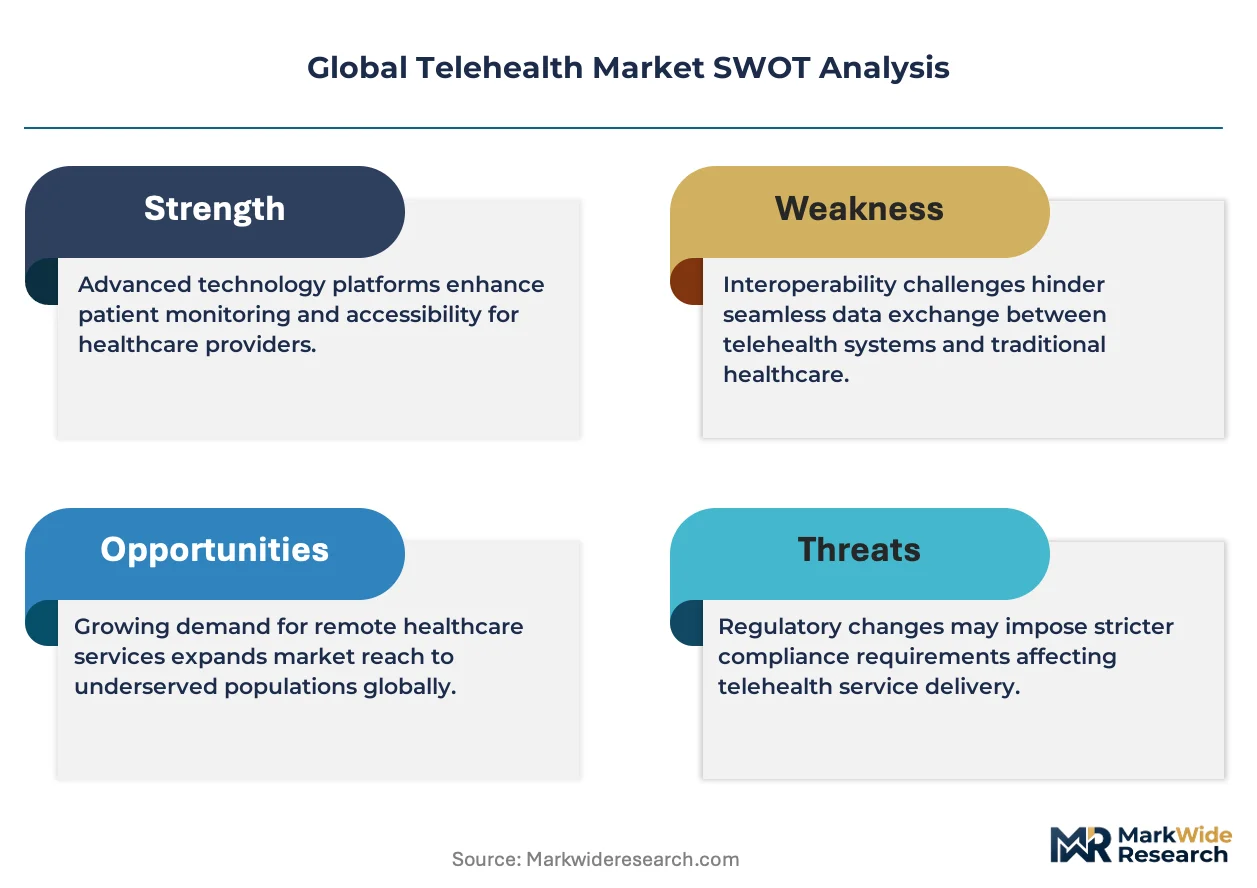
Reimbursement parity legislation at state and federal levels constitutes the decisive structural force reshaping patient volume conversion and platform viability across telehealth delivery models.
Growth Catalysts
- CMS reimbursement expansion:The Centers for Medicare and Medicaid Services has broadened coverage for remote patient monitoring CPT codes, directly incentivizing chronic disease management adoption in the United States.
- Rural broadband infrastructure:Federal communications subsidies and fiber deployment programs in Brazil and India are eliminating connectivity barriers that previously excluded geographically dispersed populations from virtual care access.
- Artificial intelligence diagnostic tools:FDA guidance on AI-enabled software-as-a-medical-device is creating regulatory clarity that accelerates algorithmic triage and dermatology screening deployment.
Market Restraints
- HIPAA security rule compliance costs:Enterprise-grade encryption infrastructure and third-party audit requirements impose substantial operational overhead on mid-sized platform operators.
- Physician licensing fragmentation:State-level medical board jurisdiction restrictions prevent seamless cross-border consultation delivery, forcing redundant credentialing investments.
- Wearable biosensor accuracy limitations:Current-generation photoplethysmography devices exhibit insufficient precision for diagnostic-grade cardiovascular monitoring in ambulatory settings.
Strategic Opportunities
- Brazil's ANVISA telemedicine resolutions:Regulatory clarity around asynchronous consultation and prescription digitization opens white space for platform operators targeting Latin America's largest healthcare market.
- Behavioral health integration:Unmet demand for mental health services creates expansion potential for synchronous video platforms serving anxiety, depression, and substance use verticals.
- Hospital-at-home reimbursement pilots:Acute-level remote monitoring combined with in-person nursing visits represents an emerging care delivery model with favorable margin structures.
Industry Challenges
- Interoperability with legacy EHR systems:HL7 FHIR implementation gaps force costly custom integration work for platforms seeking health system partnerships.
- Algorithmic bias validation:FDA pre-certification requirements for machine learning diagnostic tools demand extensive demographic representation testing that extends development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telehealth Market |
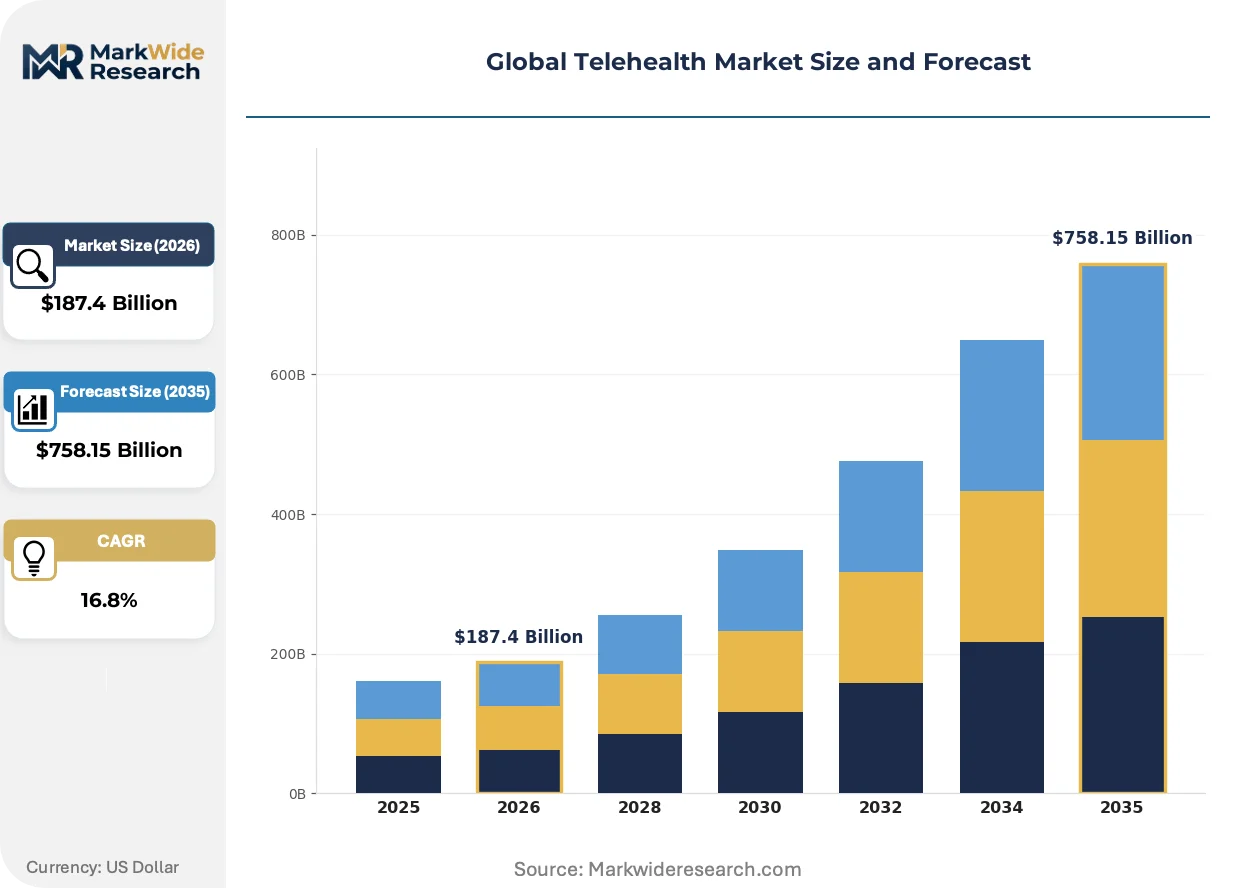
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $758.15 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Video Conferencing, Mobile Health Apps, Remote Patient Monitoring, Digital Therapeutics End User: Hospitals, Clinics, Patients, Healthcare Providers Service Type: Virtual Consultations, Chronic Disease Management, Mental Health Services, Post-operative Care Delivery Mode: Web-based, Mobile-based, Software as a Service, Cloud-based |
| Companies Covered | Teladoc Health, American Well, MDLIVE, Doctor on Demand, GE Healthcare, Koninklijke Philips, Medtronic, Amwell, Epic Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telehealth Market Strategic Shifts
Platform architectures are pivoting from standalone video consultation tools toward integrated remote patient monitoring ecosystems that capture continuous physiological data streams.
Edge computing architectures for real-time vital sign processing is supplanting cloud-only data transmission models in cardiac and respiratory monitoring applications. Hospital systems and accountable care organizations are adopting these distributed processing frameworks to reduce latency below diagnostic thresholds. The shift is compressing infrastructure requirements for rural clinic deployments while enabling algorithmic alert generation without persistent broadband connectivity.
EU MDR requirements for software-as-a-medical-device are mandating clinical evidence standards for algorithmic diagnostic tools that previously operated under lighter conformity assessment pathways. Manufacturers must now generate prospective validation data for AI-enabled triage and imaging interpretation functions. Dermatology and ophthalmology screening platforms face the steepest compliance burden as notified bodies apply stricter scrutiny to decision-support algorithms.
Self-insured employers are consolidating vendor relationships through direct contracting arrangements that bypass traditional payer intermediaries. Large manufacturing and technology firms in the United States are negotiating capitated per-employee-per-month rates for comprehensive virtual primary care and behavioral health access. This channel rotation is most visible among Fortune 500 employers seeking to reduce medical cost trends through early intervention and care navigation services.
Global Telehealth Market Segmentation
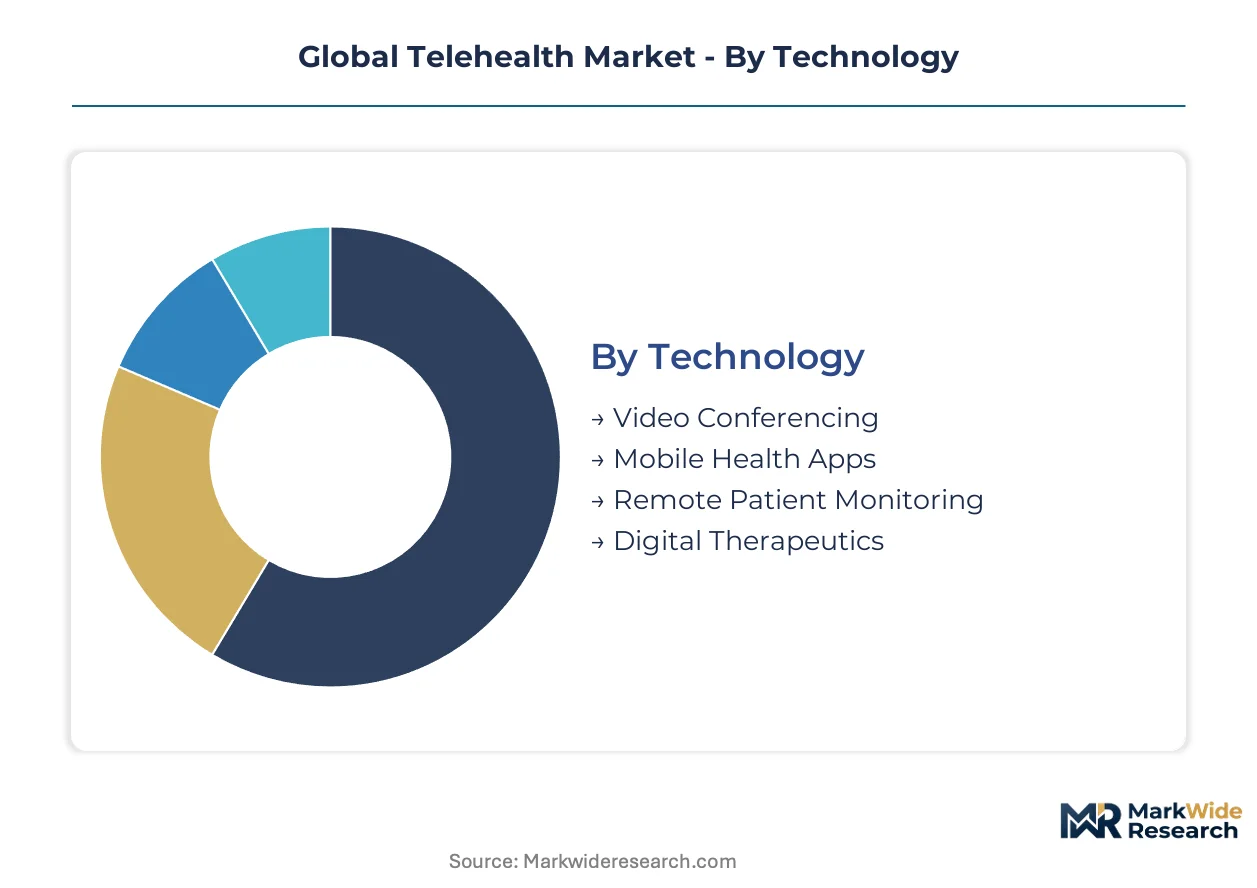
Telehealth market segmentation reveals divergent growth mechanics across technology interfaces and care delivery models. Distinct reimbursement pathways and regulatory compliance burdens shape viability within each category, forcing platform operators to prioritize specific combinations.
Technology:
Geographic demand patterns split sharply between domestically concentrated infrastructure segments and export-scalable software platforms.
- Remote Patient Monitoring:Integrated biosensor networks and hub-and-spoke data architectures capture continuous physiological streams from implantable and wearable devices. Demand concentrates in United States accountable care organizations and Brazilian public hospital networks where CMS and ANVISA reimbursement codes now cover ambulatory cardiac and respiratory surveillance. Regulatory validation timelines at FDA and EU MDR create entry barriers that favor established device manufacturers.
- Video Conferencing:Real-time encrypted consultation platforms with sub-400 millisecond latency thresholds enable diagnostic-grade telemedicine across cardiology and dermatology. Domestic deployment dominates in India and United States markets where physician licensing restrictions prevent cross-border service delivery, forcing localized infrastructure investment.
- Mobile Health Apps:Asynchronous patient engagement tools for medication adherence and symptom tracking.
- Digital Therapeutics:FDA-regulated software interventions requiring clinical evidence packages for behavioral health and chronic disease indications.
Remote Patient Monitoring commands the established base. The steepest expansion runs through Digital Therapeutics.
End User:
Procurement authority and budget scale determine segment attractiveness, with institutional buyers driving volume and individual patients representing emerging direct-pay channels.
- Hospitals:Integrated health systems deploy enterprise telehealth platforms with deep electronic health record interoperability, particularly Epic Systems environments. United States hospital networks and India's corporate hospital chains anchor demand, with capital budgets concentrated in tier-one urban centers. HL7 FHIR implementation gaps force costly custom integration work that advantages incumbent vendors.
- Patients:Direct-to-consumer virtual care subscriptions bypass traditional payer intermediaries, with self-insured employers in United States negotiating capitated per-employee-per-month rates. Brazil's expanding middle class and India's smartphone penetration create addressable populations for asynchronous primary care access.
- Clinics:Federally qualified health centers and rural primary care facilities.
- Healthcare Providers:Individual physician practices and specialty group practices.
Hospitals anchor procurement volume. Patients are gaining share fastest through employer-sponsored direct contracting.
Service Type:
Maturity gradients separate reimbursable clinical services from emerging categories still seeking parity coverage.
- Chronic Disease Management:Structured remote monitoring protocols for diabetes, hypertension, and heart failure with defined clinical workflows and quality metrics. United States Medicare Advantage plans and Brazil's SUS integrated care networks concentrate demand, with CMS remote patient monitoring CPT codes directly incentivizing platform adoption. Outcome-based contracting models are displacing fee-for-service structures in mature markets.
- Mental Health Services:Synchronous video therapy and asynchronous cognitive behavioral therapy platforms address unmet demand in anxiety, depression, and substance use verticals. United States commercial payers and India's urban corporate wellness programs drive volume, with regulatory clarity at state medical board level enabling cross-licensure compacts.
- Virtual Consultations:On-demand acute care triage and primary care access.
- Post-operative Care:Remote surgical site monitoring and rehabilitation coordination.
Chronic Disease Management holds the revenue base. Mental Health Services are climbing the fastest as parity legislation expands.
Delivery Mode:
Margin structures and scalability characteristics diverge between cloud-native architectures and legacy web interfaces.
- Cloud-based:Subscription-scalable infrastructure with multi-tenant architecture enables rapid health system onboarding and automatic regulatory compliance updates. United States hospital-at-home pilots and India's telemedicine platform aggregators concentrate demand, with edge computing deployments reducing latency for cardiac monitoring applications.
- Web-based:Browser-accessible interfaces retain share among elderly populations with limited smartphone proficiency and rural clinics with intermittent broadband connectivity. India's tier-two cities and Brazil's Amazon region deployments rely on lower-bandwidth accessibility.
- Mobile-based:Native iOS and Android applications for patient-facing engagement.
- Software as a Service:White-label platform licensing for health system branded deployments.
Cloud-based delivery dominates new deployments. Web-based interfaces defend legacy installed base in connectivity-constrained geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for telehealth services varies sharply across markets. United States employers absorb premium pricing for integrated platforms, while Indian and Brazilian patients gravitate toward low-cost asynchronous models. This elasticity divergence shapes regional deployment strategies and reimbursement negotiations.
United States
Medicare Advantage plans and self-insured employers drive enterprise telehealth procurement with substantial per-member-per-month budgets. CMS reimbursement expansion for remote patient monitoring CPT codes accelerates chronic disease management adoption. Hospital networks in Boston, Nashville, and the San Francisco Bay Area anchor platform deployment, with Epic Systems interoperability requirements dominating health system procurement criteria.
Brazil
ANVISA telemedicine resolutions clarified asynchronous consultation legality, unlocking demand among São Paulo and Rio de Janeiro corporate health plans. The SUS integrated care network expansion targets remote cardiac monitoring for heart failure patients in underserved interior states. Telehealth platforms cluster in São Paulo's healthcare technology corridor, where Portuguese-language service delivery meets strict local prescription digitization protocols.
India
Smartphone penetration exceeding thresholds in tier-two cities enables direct-to-consumer virtual primary care at price points below traditional clinic visits. The Medical Council of India's Telemedicine Practice Guidelines established liability frameworks that attracted venture investment into Bangalore and Hyderabad platform developers. Corporate hospital chains in Delhi-NCR and Chennai deploy hybrid models combining in-person specialist access with remote follow-up protocols.
Germany
EU MDR software-as-a-medical-device requirements impose clinical evidence burdens that favor established device manufacturers over startup competitors. The Digitale-Versorgung-Gesetz reimbursement framework expanded video consultation coverage for statutory health insurance patients. Berlin and Munich health technology clusters concentrate regulatory expertise for CE marking and notified body navigation, with university hospital partnerships validating algorithmic diagnostic tools.
Australia
Geographic isolation and rural physician shortages create structural demand for specialist teleconsultation across Queensland and Western Australia. The Medicare Benefits Schedule permanent telehealth items established sustainable reimbursement following pandemic-era temporary measures. Sydney and Melbourne platform operators focus on indigenous health access and remote chronic disease management in the Northern Territory and Tasmania.
Global Telehealth Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the telehealth value chain. Integrated hardware-software ecosystems command premium positioning in remote patient monitoring, while lightweight video consultation platforms compete on implementation speed and subscription pricing. The market structures around three strategic archetypes: multispecialty physician network operators, device-anchored platform vendors, and electronic health record-integrated software providers. Dominant competitive moves include strategic partnerships with health systems for interoperability certification and geographic expansion through regulatory pathway replication.
Within the integrated device-platform tier, Koninklijke Philips and Medtronic exemplify hardware-anchored ecosystem strategies. Teladoc Health occupies a position representing the multispecialty network archetype. Epic Systems anchors the EHR-integrated software category. These three patterns—device integration, physician network scale, and health system interoperability—define the competitive vectors shaping procurement decisions.
| Leading Market Players |
|---|
| Teladoc Health |
| American Well |
| MDLIVE |
| Doctor on Demand |
| GE Healthcare |
| Koninklijke Philips |
| Medtronic |
| Amwell |
| Epic Systems |
| Others |
Value Chain & Pricing Dynamics
Cloud-native platform architectures replacing legacy on-premise deployments simultaneously concentrates supply among United States hyperscale infrastructure providers and compresses subscription pricing toward SaaS benchmarks. This substitution dynamic redistributes margin pools from hardware-anchored vendors to software-native operators while amplifying buyer negotiating leverage through multi-tenant comparability.
Pricing Analysis
After-sales revenue from remote patient monitoring device servicing and extended clinical support contracts drives lifetime value capture across platform tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared diagnostic-grade systems from wellness-tier consumer devices, with certification level and integration depth as primary differentiation drivers. Pricing pressure stems from employer direct-contracting bypassing traditional payer intermediaries. Self-insured employers exhibit lowest price sensitivity, while individual direct-pay subscribers in India and Brazil demonstrate highest elasticity.
Supply Chain Analysis
Inventory lead times for wearable biosensors and edge computing hardware stretch across semiconductor fabrication cycles, creating working capital intensity for platform operators. Supply concentrates in Taiwan for sensor microcontrollers, China for lithium-ion power components, and United States for FDA-regulated algorithmic software. Raw material dependencies include photoplethysmography chips, medical-grade polymers, and cloud compute capacity. Single-source vulnerability in Taiwan semiconductor foundries poses structural risk. Distribution runs through health system procurement committees and employer benefits administrators as dominant downstream channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in telehealth are approaching an inflection where EHR interoperability, not physician network scale, determines competitive survival. Epic Systems' deep hospital system integration exemplifies this ecosystem shift toward data liquidity as the primary moat.
For Market Incumbents: Fortify EHR interoperability certification through HL7 FHIR investment to defend against cloud-native challengers. Deepen vertical integration into remote patient monitoring hardware to capture device-service bundled margins. Prioritize United States Medicare Advantage channel control as reimbursement parity legislation stabilizes.
For New Entrants and Emerging Players: Differentiate on asynchronous consultation workflows for Brazil's ANVISA-regulated prescription digitization market. Target India's tier-two cities with low-bandwidth web-based interfaces as the most penetrable geography. Pursue white-label SaaS licensing to corporate hospital chains as the fastest go-to-market path.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors EHR-integrated software providers over standalone video platforms. Long-term viability across the projection horizon hinges on reimbursement code expansion and regulatory clarity. Acquisition target archetype: mid-scale platforms with existing hospital system partnerships and FDA pre-certification progress. Watch CMS remote patient monitoring CPT code expansion velocity as the decisive inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Epic Systems interoperability certification unlocks enterprise procurement pipelines and recurring SaaS revenue. |
| FDA Pre-Certification Pathway | AI-enabled diagnostic software gains accelerated review timelines reducing competitive time-to-market gaps. |
| Reimbursement Strategy | CMS remote patient monitoring CPT code coverage directly converts platform adoption into billable clinical volume. |
| Geographic Expansion | ANVISA regulatory pathway replication in Brazil opens Latin America's largest employer-sponsored health plan market. |
| Platform Integration | Edge computing deployment for cardiac monitoring reduces latency below diagnostic thresholds in rural broadband-constrained regions. |
Study Parameters
Initial hypotheses were tested against primary input from hospital CIOs, telehealth platform product managers, biomedical engineers, and GPO contracts managers and refined through secondary validation. Primary fieldwork combined structured interviews with health system procurement committees and telemedicine operations directors. Secondary sources included FDA 510(k) filings, CMS Medicare reimbursement databases, ANVISA regulatory resolutions, and hospital procurement contract disclosures. Bottom-up platform deployment counts triangulated against top-down healthcare IT spending estimates.
Variance decomposition across technology interface, end-user segment, service type, and delivery mode dimensions structured the analytical framework. Segmentation modeling incorporated deployment model, health system scale, reimbursement pathway maturity, and regional regulatory cluster as core dimensions. CAGRs were derived from fitted growth curves calibrated to reimbursement expansion timelines and broadband infrastructure deployment schedules. Forecast inputs included CMS CPT code coverage velocity, ANVISA implementation guidance evolution, and EU MDR software-as-a-medical-device notified body capacity.
Forecasts assume regulatory continuity in United States CMS reimbursement frameworks, Brazil ANVISA telemedicine resolutions, and India Medical Council guidelines; material policy shifts would require re-modeling. Algorithmic diagnostic tool FDA pre-certification timelines and cross-state physician licensing compact expansion represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telepathology Service Market
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
Tele-Care Market
Telemedicine
Tele-ICU Services Market
Telemedicine
Oceania Telemedicine Market
Telemedicine
Telehealth Kiosk Market
Telemedicine
India Telemedicine Market
Telemedicine
US Telemedicine Market
Telemedicine
Global Telepsychiatry Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
Remote Healthcare Market
Telemedicine
Telemedicine Service Market
Telemedicine
United States Telehealth Pre-Natal Services Market
Telemedicine
Online Doctor Consultation Market
Telemedicine
AI in Telemedicine Market