
 Telecom Managed Services Market | 2026-2036
Telecom Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Managed Services Market Intelligence
The rise of software-defined networking is shifting the core value proposition from hardware maintenance to agile, on-demand feature activation. Telefonaktiebolaget LM Ericsson leverages its deep integration with telecom operators to deliver comprehensive network management solutions. Cisco Systems, Inc. competes on the strength of its extensive portfolio of networking hardware and security software. Huawei Technologies Co., Ltd. specializes in providing end-to-end infrastructure solutions, particularly in rapidly developing economies.
Telecom managed services involve the outsourcing of network operations, infrastructure management, and IT functions to a third-party provider. These services are governed by service-level agreements that define performance metrics such as network uptime, latency, and security incident response times. While Network Management remains the foundational service type, Security Management represents the fastest-growing segment due to escalating cyber threats. Deployment models are moving from traditional on-premises setups toward cloud-based and hybrid solutions to improve scalability and cost efficiency.
Regulatory frameworks such as the FCC's data security rules in the United States and the EU's GDPR impose strict compliance obligations on service providers. In China, directives from the MIIT on network infrastructure and data localization influence service delivery models and technology choices. Vendor selection increasingly depends on a provider's ability to navigate these complex, divergent regulatory landscapes while delivering consistent service levels.
Market Dynamics
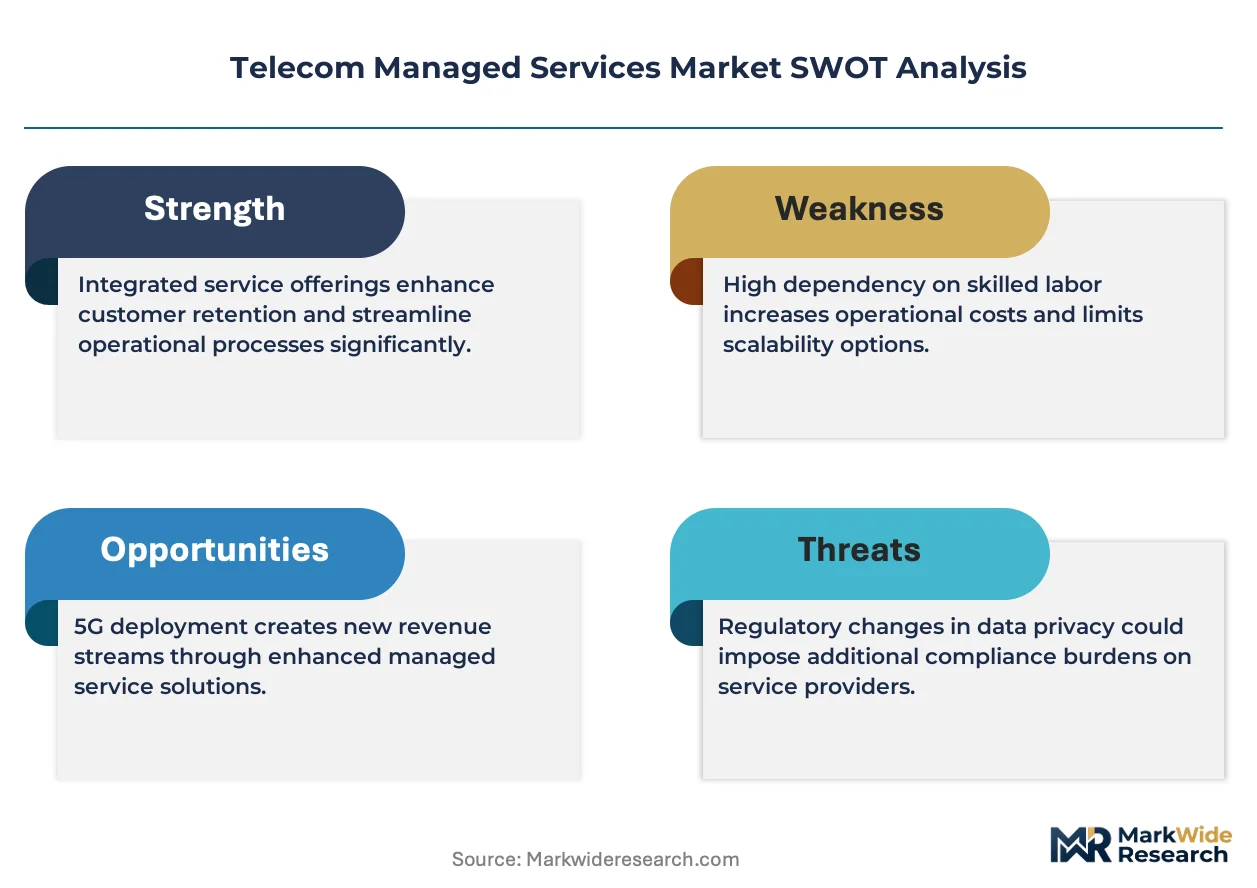
The central tension in the telecom managed services market is the simultaneous demand for hyper-specialized technical skills to manage 5G and cloud-native networks, and the increasing operational burden imposed by divergent global data sovereignty and security regulations.
Growth Catalysts
- 5G and SDN Adoption:The architectural shift to 5G and software-defined networking (SDN) requires operational expertise that many enterprises and even some service providers lack, creating a direct demand pull for specialized third-party management services.
- Digital Infrastructure Investment:Government-backed initiatives, such as India's push for nationwide digital connectivity, are creating large-scale opportunities for managing new fiber and wireless infrastructure, particularly in rapidly developing economies.
- Data Center Outsourcing:The expansion of hyperscale and edge data centers generates consistent demand for outsourced infrastructure management, monitoring, and security services to ensure high levels of uptime and performance.
Market Restraints
- Legacy System Integration:The complexity and cost of integrating modern managed services with entrenched, legacy telecom hardware and OSS/BSS platforms can delay or limit the scope of outsourcing contracts for established operators.
- Regulatory Compliance Overhead:Navigating disparate regulatory frameworks, such as the EU's GDPR and the FCC's data security rules in the US, adds significant legal and operational costs for providers offering services across multiple jurisdictions.
- Service-Level Agreement Risks:Strict service-level agreements (SLAs) with significant financial penalties for downtime or security breaches create high-stakes operational risks for managed service providers, pressuring margins and demanding heavy investment in redundant systems.
Strategic Opportunities
- Managed IoT Connectivity:Providing managed services for large-scale Internet of Things (IoT) deployments, including device lifecycle management and network security, offers a significant growth vector beyond traditional telecom infrastructure.
- Private Network Management:The emergence of private 5G and LTE networks for industrial campuses, ports, and large venues creates a new market for specialized, on-premises, or hybrid managed services.
- AI-Driven Network Automation:Developing service offerings that leverage artificial intelligence for predictive network maintenance and automated security response can create significant value and differentiation for providers.
Industry Challenges
- Cybersecurity Talent Scarcity:A persistent shortage of skilled cybersecurity professionals capable of managing the complex threat landscape of modern telecom networks constrains the ability of providers to scale their security management operations.
- Multi-Vendor Interoperability:Ensuring seamless operation and management across a diverse ecosystem of hardware and software from different vendors remains a significant technical hurdle, particularly in open, software-defined environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Managed Services Market |
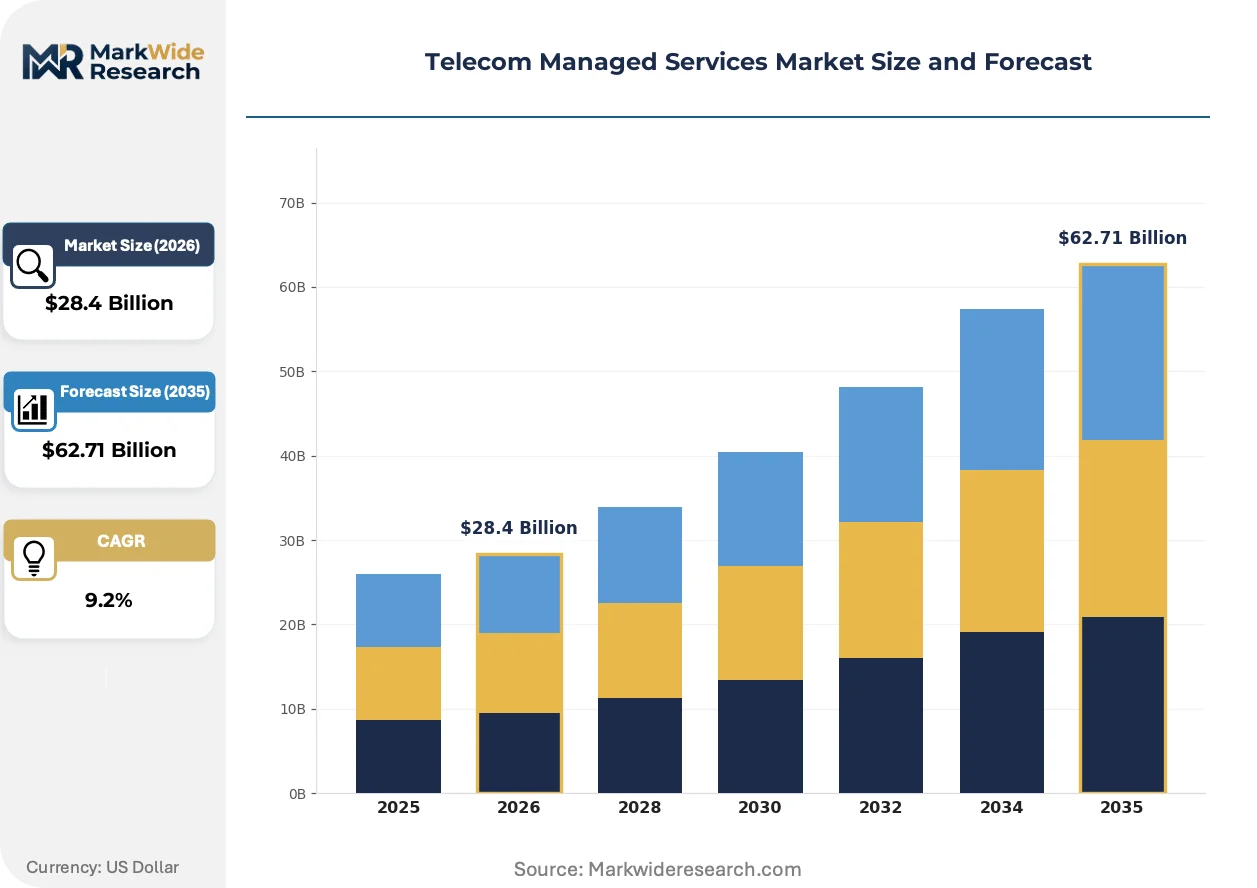
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $62.71 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Management, Infrastructure Management, Security Management, Application Management, Cloud Services Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Customer Type: Telecom Operators, Internet Service Providers, Data Centers, Content Delivery Networks, System Integrators Application: Network Optimization, Fault Management, Service Assurance, Provisioning & Activation, Billing Management |
| Companies Covered | Telefonaktiebolaget LM Ericsson, AT&T Inc., Cisco Systems, Inc., Cognizant Technology Solutions Corporation, Capgemini SE, Huawei Technologies Co., Ltd., Verizon Communications Inc., HCL Technologies Limited, International Business Machines Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Managed Services Market Strategic Shifts & Innovations
Automation and intelligence are fundamentally changing the delivery of telecom managed services. The market is pivoting from a model based on manual intervention and hardware maintenance toward one defined by software-driven, predictive, and autonomous network operations.
The adoption of AI for IT Operations (AIOps) platforms provides the core technology for this shift. These systems ingest vast amounts of telemetry data from network elements to automatically detect performance anomalies and predict potential failures. Large telecom operators and cloud providers are the primary adopters, seeking to reduce mean time to resolution (MTTR). AIOps is unifying previously separate domains of network performance monitoring, security information management, and IT service management into a single, cohesive operational dashboard.
Data sovereignty regulations, including the EU's GDPR and specific directives from China's MIIT, are reshaping service delivery architectures. These rules mandate how and where user data can be stored and processed, forcing providers to abandon one-size-fits-all global models. Cloud and hybrid deployment models are most affected, now requiring providers to build geographically distributed infrastructure to ensure data residency and compliance for customers in sensitive regions.
Enterprises are moving away from long-term, fixed-scope contracts toward more agile and consumption-based procurement models. This change disrupts the traditional outsourcing business case, favoring providers that offer on-demand feature activation and pay-as-you-go pricing through self-service portals. This trend is most pronounced in the SD-WAN and secure access service edge (SASE) segments, where business agility and cost efficiency are key purchasing criteria.
Telecom Managed Services Market Segmentation
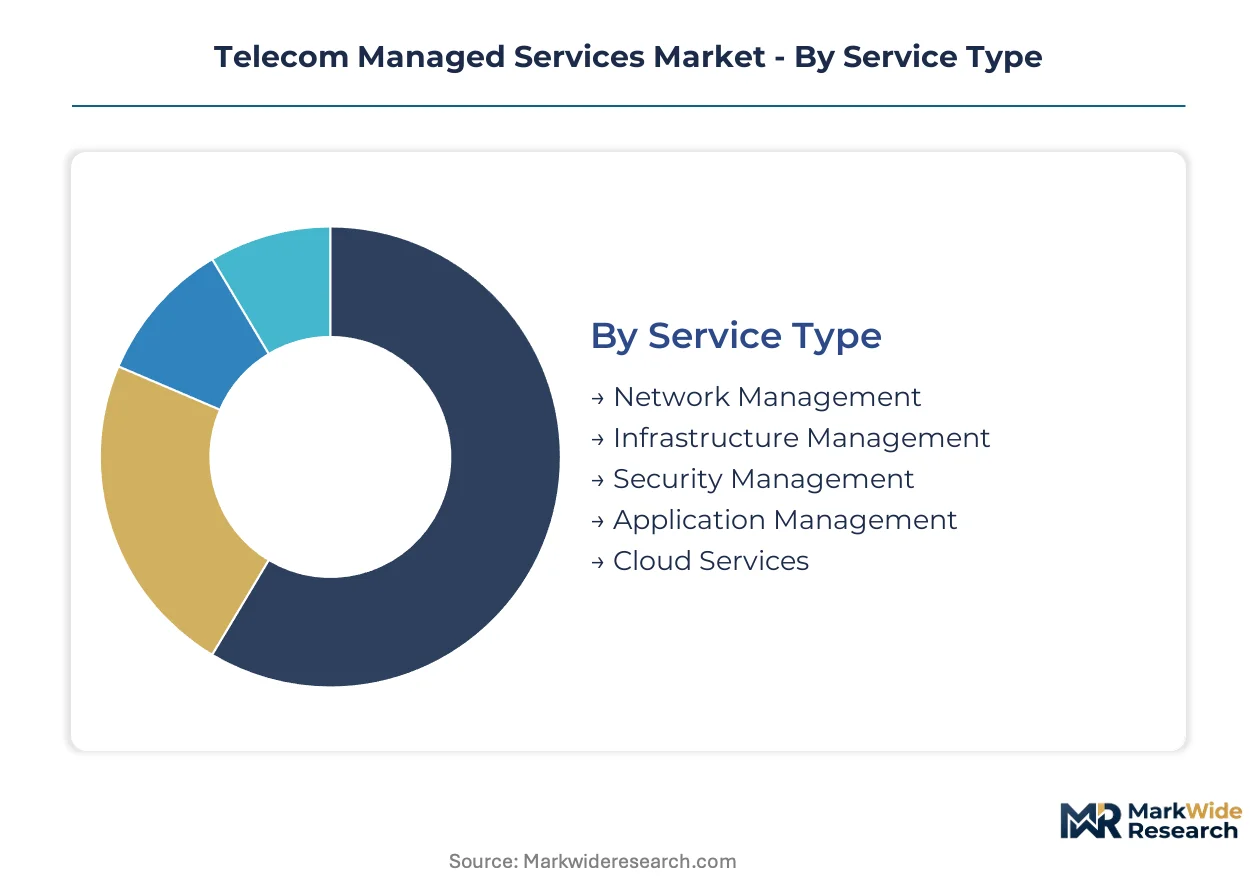
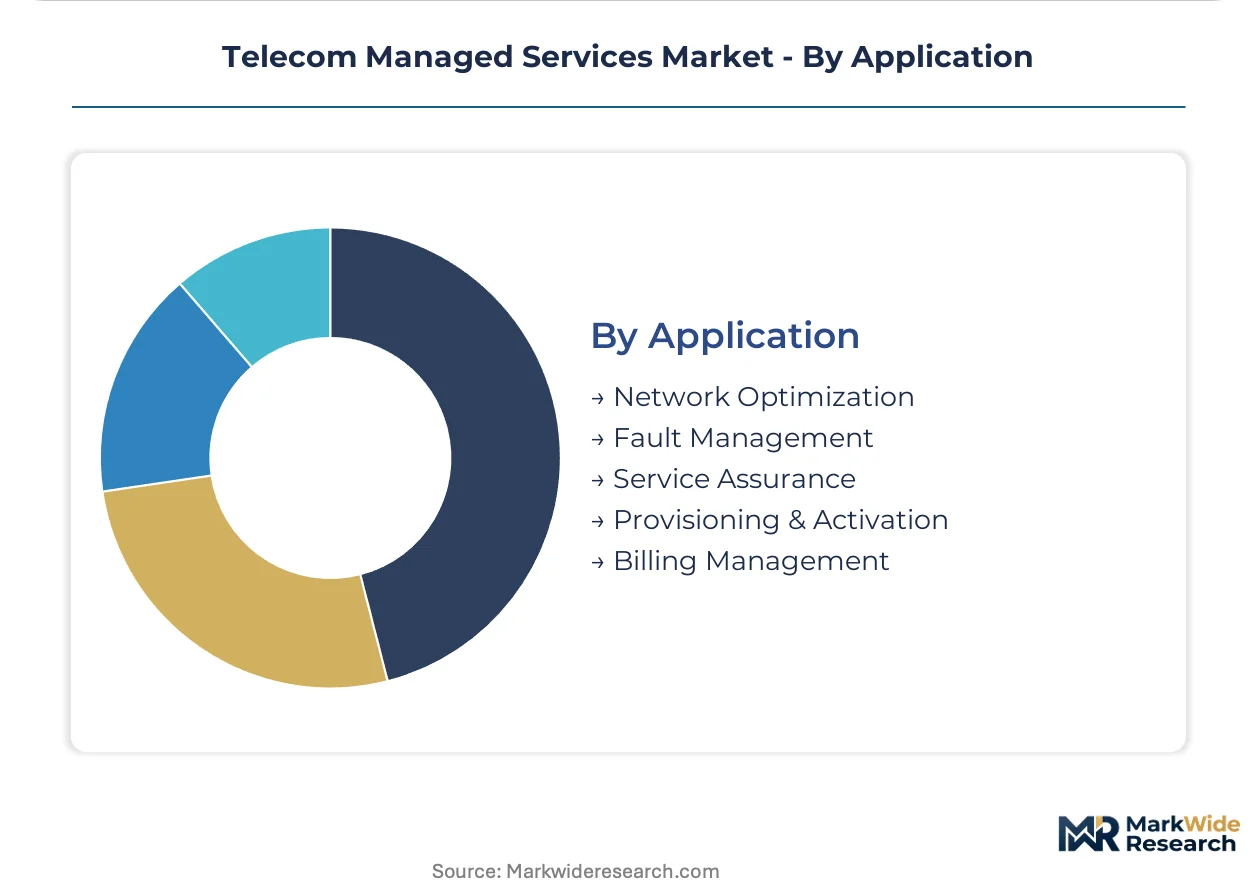
The telecom managed services market segments across several critical dimensions, reflecting the diverse operational needs of network infrastructure and service delivery. Understanding these segments clarifies where specialized expertise and investment are concentrating, enabling providers to tailor offerings for specific client requirements and technological shifts.
Service Type:
Service capabilities are differentiated by the specific technical domains managed by third-party providers.
- Network Management:This foundational service encompasses the day-to-day operation, monitoring, and maintenance of network infrastructure, ensuring optimal performance and availability. Demand for these services is consistently high from large telecom operators seeking to offload routine but critical functions.
- Security Management:This segment provides specialized services for safeguarding network assets and data from cyber threats, including threat detection, incident response, and compliance management. Escalating cyber threats and stringent regulatory mandates are driving significant demand for these expert services across all customer types.
- Infrastructure Management:Providers handle the physical and virtual components of IT infrastructure, including servers, storage, and operating systems.
- Application Management:This involves the maintenance, support, and optimization of software applications running on telecom networks.
- Cloud Services:These services manage cloud-based network components and applications, including migration, optimization, and security within public, private, or hybrid cloud environments.
Network Management leads on scale; Security Management leads on momentum.
Deployment Model:
Procurement is shifting based on infrastructure location and operational flexibility requirements.
- Cloud-Based:Services are delivered entirely through cloud infrastructure, offering high scalability, reduced capital expenditure, and remote accessibility. Enterprises are increasingly adopting cloud-based models for their agility and cost-efficiency in managing network functions.
- Hybrid:This model combines elements of both on-premises and cloud-based deployments, allowing organizations to leverage existing infrastructure while benefiting from cloud scalability. Many established telecom operators favor hybrid solutions for a phased transition and data residency control.
- On-Premises:Managed services are delivered using hardware and software located within the client's own data center or facilities.
- Multi-Cloud:This involves managing services across two or more public cloud providers, enhancing resilience and avoiding vendor lock-in.
Cloud-based solutions are gaining significant traction, while on-premises deployments maintain a core operational role.
Customer Type:
The market targets distinct enterprise and service provider segments with unique operational scales and regulatory needs.
- Telecom Operators:These are the primary consumers, outsourcing large-scale network operations and infrastructure management to enhance efficiency and focus on core service delivery. Investment in 5G network architectures by these operators creates substantial demand for specialized managed services.
- Data Centers:Hyperscale and edge data centers outsource management, monitoring, and security services to ensure high availability and performance for their critical infrastructure. The rapid expansion of data center capacity globally necessitates continuous third-party support.
- Internet Service Providers:ISPs leverage managed services to optimize network performance, manage customer connectivity, and ensure service reliability.
- Content Delivery Networks:CDNs utilize managed services for distributed infrastructure maintenance and performance optimization to deliver digital content efficiently.
- System Integrators:These firms often partner with managed service providers to deliver comprehensive solutions to their end clients, leveraging specialized network expertise.
Telecom Operators represent the largest customer base, with Data Centers showing considerable expansion.
Application:
Service offerings are categorized by the specific functional outcomes they deliver within a network environment.
- Network Optimization:This application focuses on improving network performance, efficiency, and resource utilization through advanced monitoring and configuration adjustments. Service providers use these tools to meet strict service-level agreements and enhance user experience.
- Service Assurance:This involves proactively monitoring and managing service quality to ensure defined performance levels are met, including fault detection and resolution. Operators rely on service assurance to minimize downtime and maintain customer satisfaction.
- Fault Management:This application identifies, isolates, and resolves network issues and outages to restore service quickly.
- Provisioning & Activation:These services automate the setup and activation of new network services and user accounts.
- Billing Management:This application handles the complex processes of tariff management, usage tracking, and invoice generation for telecom services.
Network optimization drives efficiency gains, while service assurance ensures system resilience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While India's digital infrastructure expansion drives substantial demand for managed services, the United States focuses on advanced 5G and cloud-native network management. Each region presents unique growth trajectories influenced by local regulatory environments and technological priorities. Providers must adapt their offerings to diverse market conditions.
United States
The United States market sees significant demand from hyperscale data centers for outsourced infrastructure and security management. FCC data security rules impose stringent compliance requirements on service providers operating within the country. Major technology hubs like Silicon Valley and Seattle concentrate expertise in cloud-native network management and AI-driven automation.
India
India's rapid digital infrastructure investment, supported by government initiatives, creates extensive opportunities for managing new fiber and 5G networks. The Telecom Regulatory Authority of India (TRAI) guides network expansion and service quality standards. Bengaluru and Hyderabad serve as key centers for IT and telecom managed services, attracting significant provider investment.
China
China's market is characterized by a strong emphasis on end-to-end infrastructure solutions, particularly for its rapidly expanding digital economy. Directives from the MIIT on network infrastructure and data localization heavily influence service delivery models. Shenzhen and Beijing host major telecom equipment manufacturers and service providers, driving innovation in network management.
Germany
Germany exhibits strong demand for managed services in private 5G networks and industrial IoT deployments, driven by its advanced manufacturing sector. GDPR regulations significantly impact data processing and residency requirements for managed service providers. Munich and Stuttgart represent industrial clusters requiring specialized network management for automotive and automation industries.
United Kingdom
The United Kingdom's market is pivoting towards cloud-based and hybrid solutions, particularly for enterprise network functions. Ofcom regulations ensure fair competition and service quality across the telecom sector. London's financial services and technology sectors demand high-performance, secure managed network solutions.
Telecom Managed Services Market Key Industry Players
Top-tier vendors anchor the managed services market, while a diverse array of specialized firms competes in niche segments. The market structure is tiered, with large infrastructure providers offering comprehensive solutions and smaller firms focusing on specific technologies. Strategic partnerships and portfolio diversification are common competitive moves among market participants.
Among established network infrastructure providers, Telefonaktiebolaget LM Ericsson represents a global leader with deep integration into telecom operator networks. Cisco Systems, Inc. exemplifies a strong position through its extensive networking hardware and security software portfolio. Huawei Technologies Co., Ltd. anchors a significant portion of end-to-end infrastructure solutions, particularly in rapidly developing economies.
| Leading Market Players |
|---|
| Telefonaktiebolaget LM Ericsson |
| AT&T Inc. |
| Cisco Systems, Inc. |
| Cognizant Technology Solutions Corporation |
| Capgemini SE |
| Huawei Technologies Co., Ltd. |
| Verizon Communications Inc. |
| HCL Technologies Limited |
| International Business Machines Corporation |
| Others |
Cost & Logistics Intelligence
EU's GDPR mandates on data residency gate qualified cloud-based service supply, creating a premium for providers with compliant, localized infrastructure. This regulatory compliance limits market access for those without suitable geographically distributed resources.
Pricing Analysis
Capacity additions in India are reshaping price floors for foundational network management services. The dominant pricing model is consumption-based, often incorporating tiered service level agreements. Price differentiation stems from specialized 5G and SDN expertise, and robust regulatory compliance. Pricing pressure intensifies due to stringent service-level agreement penalties, driving cost-efficiency for enterprises. Large telecom operators prioritize service reliability over marginal cost savings.
Supply Chain Analysis
Single-source vulnerability sits with specialized software licenses from dominant vendors, while geographic supply for core infrastructure components concentrates in China and the United States. Key dependencies include advanced networking hardware and a limited global pool of cybersecurity talent, creating a structural risk. Regulatory restrictions, such as data localization mandates from China's MIIT, further complicate service delivery models. Distribution runs through direct contracts with managed service providers and partnerships with system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The telecom managed services market acts as a regulatory compounder, with stringent frameworks like the EU's GDPR driving demand for specialized compliance and data residency solutions. These mandates necessitate sophisticated operational expertise across multiple jurisdictions.
For Market Incumbents: Acquire specialized AI-driven automation platforms to counter emerging threats from agile, cloud-native competitors. Deepen existing integration with large telecom operators by offering comprehensive 5G network management and security solutions, mitigating revenue erosion from new consumption models. Invest in cybersecurity talent development to address the persistent scarcity. Leverage AIOps to enhance predictive maintenance capabilities.
For New Entrants and Emerging Players: Enter via specialized private 5G network management for industrial campuses, leveraging the demand for localized, secure connectivity. Target managed IoT connectivity services, focusing on device lifecycle management and network security for large-scale deployments. Offer agile, consumption-based pricing models through self-service portals to appeal to enterprises seeking cost efficiency. Penetrate underserved mid-market segments with tailored cloud-based solutions.
For Investors and Strategic Acquirers: Roll-up economics work for specialized managed service providers because hyper-specialized technical skills are at a premium. Focus on targets offering advanced security management, AI-driven network automation, or private network expertise for long-term viability. The market will see sustained growth over the next decade, driven by 5G and IoT deployments. Monitor the expansion of private 5G networks in industrial sectors as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AIOps Platforms | Enables predictive network maintenance and automated security response, reducing mean time to resolution for telecom operators. |
| Expand Security Management Portfolio | Addresses escalating cyber threats and stringent regulatory mandates, capturing the fastest-growing segment in telecom managed services. |
| Develop Private 5G Managed Services | Creates new revenue streams by supporting industrial campuses and large venues requiring specialized, on-premises network solutions. |
| Pursue Regulatory Compliance Certifications | Ensures service delivery across diverse jurisdictions, particularly with data localization rules from the EU's GDPR and China's MIIT. |
| Form Partnerships with System Integrators | Extends market reach and leverages specialized network expertise to deliver comprehensive solutions to end clients. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. This analysis combines in-depth interviews with telecom operator CTOs, data center IT procurement managers, and managed service provider executives. Secondary validation draws from regulatory filings such as FCC data security rules, TRAI guidelines, and MIIT directives on network infrastructure. A rigorous bottom-up and top-down triangulation approach ensures data consistency.
Granularity in modeling extended to service type, deployment model, customer type, application, and regional regulatory compliance. The analytical framework projects market growth across the analysis window, with compound annual growth rates derived through regression analysis. Key industry-specific forecast inputs included 5G network rollout schedules and hyperscale data center expansion plans. This detailed approach captures nuanced market dynamics.
Inputs from major telecom operators and regulatory bodies were available through the study window; gaps in real-time cybersecurity threat intelligence introduce uncertainty bands. Forecasts reflect assumptions regarding future 5G adoption, subject to geopolitical shifts and unforeseen regulatory changes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Argentina ICT Market
Telecommunications
Private LTE in Mining Industry Market
Telecommunications
5G System Integration Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Asia-Pacific IPTV Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
Oman Telecom Market
Telecommunications
Tetra Terminals Market
Telecommunications
Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
Call Control (PBX-IP PBX) Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
Indonesia Volte Market
Telecommunications
MVNO Market