
 Telecom Radio System Software Market | 2026-2036
Telecom Radio System Software Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Radio System Software Market Analytics
Open vRAN software is repositioning silicon economics away from dedicated baseband hardware toward general-purpose processors and programmable accelerators. Nokia Corporation leverages its Bell Labs heritage to sustain deep R&D intensity in massive MIMO algorithms. Ericsson anchors European operator relationships through long-term managed services contracts that bundle software with network operations. Huawei Technologies competes on manufacturing scale in pico-cell and macro-cell baseband software despite geopolitical restrictions in select markets.
Telecom radio system software comprises the programmable control, signal processing, and resource orchestration layers that manage electromagnetic spectrum allocation, beamforming computations, and handover protocols between cell towers and core networks. These systems execute real-time Layer 1 through Layer 3 functions on distributed compute fabrics spanning centralized data centers and edge nodes. Radio access network software dominates current deployment value as operators virtualize distributed units and centralized units. Cloud-based deployment grows fastest where hyperscaler infrastructure absorbs elastic traffic spikes. Service orchestration software captures expanding margin pools as multi-vendor interoperability becomes operationally critical.
The Federal Communications Commission shapes US market access through spectrum auction rules that mandate software-upgradeable equipment, while the European Telecommunications Standards Institute enforces open interfaces that fragment vendor lock-in. Japan's Ministry of Internal Affairs and Communications drives local 5G software requirements through dedicated spectrum allocations for enterprise-private networks. Stakeholders must monitor whether operator consolidation in key markets compresses procurement timelines or extends vendor evaluation cycles.
Market Dynamics
Cloud-native disaggregation of radio access network architectures is collapsing the traditional hardware-software bundling model, forcing incumbent vendors to unbundle proprietary stacks while enabling new software entrants to capture value from orchestration and optimization layers previously locked inside integrated baseband units.
Growth Catalysts
- Japan's Open RAN interoperability mandates:Japan's Ministry of Internal Affairs and Communications requires multi-vendor interface certification, compelling operators to procure software components separately from radio hardware and expanding the addressable market for standalone RAN software vendors.
- Enterprise private 5G deployments:Manufacturing, logistics, and energy facilities in Germany and South Korea are deploying localized radio systems that demand flexible, software-defined spectrum management rather than operator-managed network slices.
- AI-driven beamforming algorithms:Machine learning-based massive MIMO optimization is reducing computational overhead on distributed units, allowing general-purpose processors to replace dedicated baseband chips and lowering entry barriers for software specialists.
Market Restraints
- Silicon supply concentration:Advanced programmable accelerators for Layer 1 processing depend on fabrication capacity concentrated in Taiwan and South Korea, creating input cost volatility and procurement lead time uncertainty for software vendors packaging hardware-dependent solutions.
- Legacy integration friction:Existing 4G macro deployments rely on tightly coupled baseband-radio interfaces that resist virtualization without forklift upgrades, slowing cloud-native adoption among operators with substantial sunk investment in distributed antenna systems.
- Geopolitical export controls:US Bureau of Industry and Security restrictions on semiconductor manufacturing equipment are constraining Chinese vendors' access to advanced node chips, fragmenting global supply chains and complicating multi-region software deployment strategies.
Strategic Opportunities
- India's network virtualization imperative:Indian telecom service providers face acute capital intensity pressure with among the world's lowest ARPU levels, creating urgent demand for software-defined RAN solutions that reduce per-subscriber infrastructure costs through resource pooling and automation.
- Neutral host infrastructure models:Shared radio access networks deployed by tower companies and real estate investment trusts are displacing operator-captive systems, requiring multi-tenant orchestration software that enables slice isolation across competing service providers.
- Eu Cybersecurity Certification Scheme:The EU's forthcoming 5G network equipment security framework creates compliance service opportunities for software vendors capable of delivering attested supply chain transparency and runtime integrity verification as bundled offerings.
Industry Challenges
- Real-time software engineering scarcity:Development of deterministic Layer 1 signal processing code requires specialized expertise in fixed-point arithmetic and hardware-software co-design that concentrates among a small pool of engineers with cellular baseband experience.
- Multi-vendor integration complexity:Open RAN specifications leave implementation-specific gaps in timing synchronization and fault management, forcing operators to maintain expensive system integration teams or accept degraded service reliability during interoperability testing phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Radio System Software Market |
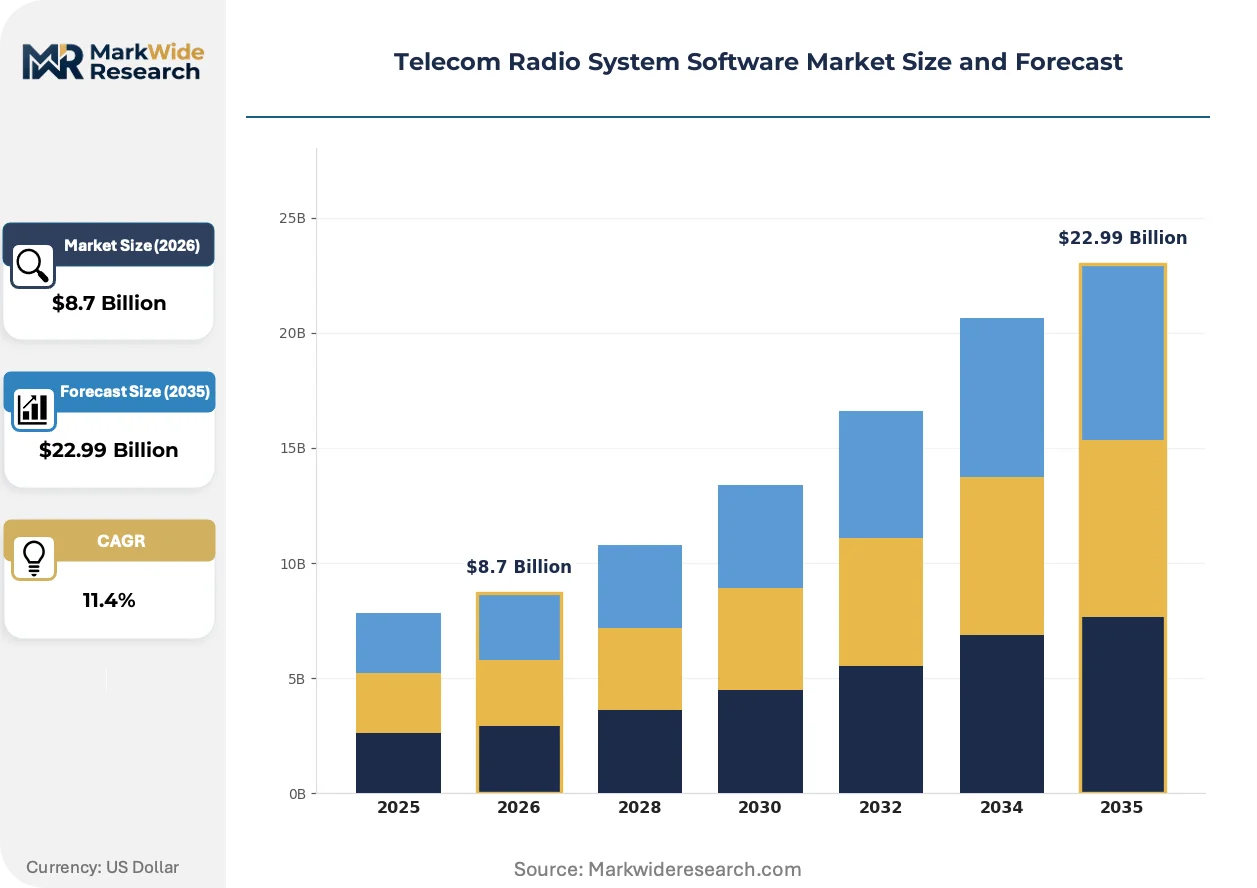
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Network Management, Radio Access Network, Core Network, Service Orchestration Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Telecommunication Service Providers, Enterprises, Government Agencies, Managed Service Providers Application: Voice Services, Data Services, Network Security, Traffic Management |
| Companies Covered | Nokia Corporation, Ericsson, Huawei Technologies, Cisco Systems, Oracle Corporation, NEC Corporation, Amdocs, Alcatel-Lucent, ZTE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Radio System Software Market Evolving Landscape
Intelligent automation is penetrating radio network operations at an accelerating pace, compressing manual optimization cycles while enabling dynamic resource allocation that responds to traffic patterns in milliseconds rather than hours.
Containerized network functions are integrating cloud-native orchestration principles into distributed unit software stacks, allowing mobile operators in South Korea and Germany to deploy elastic capacity that scales with stadium events or industrial peak loads without permanent hardware overprovisioning. Telecom equipment vendors are releasing Kubernetes-based radio software distributions that abstract underlying silicon diversity, reducing porting costs across Intel, AMD, and ARM processor variants. This integration is compressing time-to-market for new radio features by decoupling software release cycles from hardware qualification timelines.
REACH restrictions on per- and polyfluoroalkyl substances are extending into electronics manufacturing supply chains, compelling European baseband hardware suppliers to reformulate thermal interface materials and conformal coatings used in outdoor radio units. The European Chemicals Agency's substance evaluation timeline is forcing parallel qualification of alternative chemistries, adding six to twelve months to product certification cycles for vendors serving EU operator deployments. Radio software vendors with European manufacturing partners are absorbing these compliance costs into hardware-software bundle pricing, creating margin pressure distinct from pure software competitors with Asian supply chains.
Outcome-based network performance contracting is displacing traditional capital expenditure procurement for radio infrastructure among European and Asia-Pacific operators, transferring traffic-handling risk from buyers to vendors. Software suppliers are responding with tiered service level agreements that guarantee specific latency, throughput, and availability metrics in exchange for recurring revenue streams tied to actual network utilization. This model concentrates most visibly in Germany, where Deutsche Telekom and Vodafone have structured managed RAN deals that compensate vendors based on delivered quality of experience rather than installed equipment counts.
Telecom Radio System Software Market Segmentation
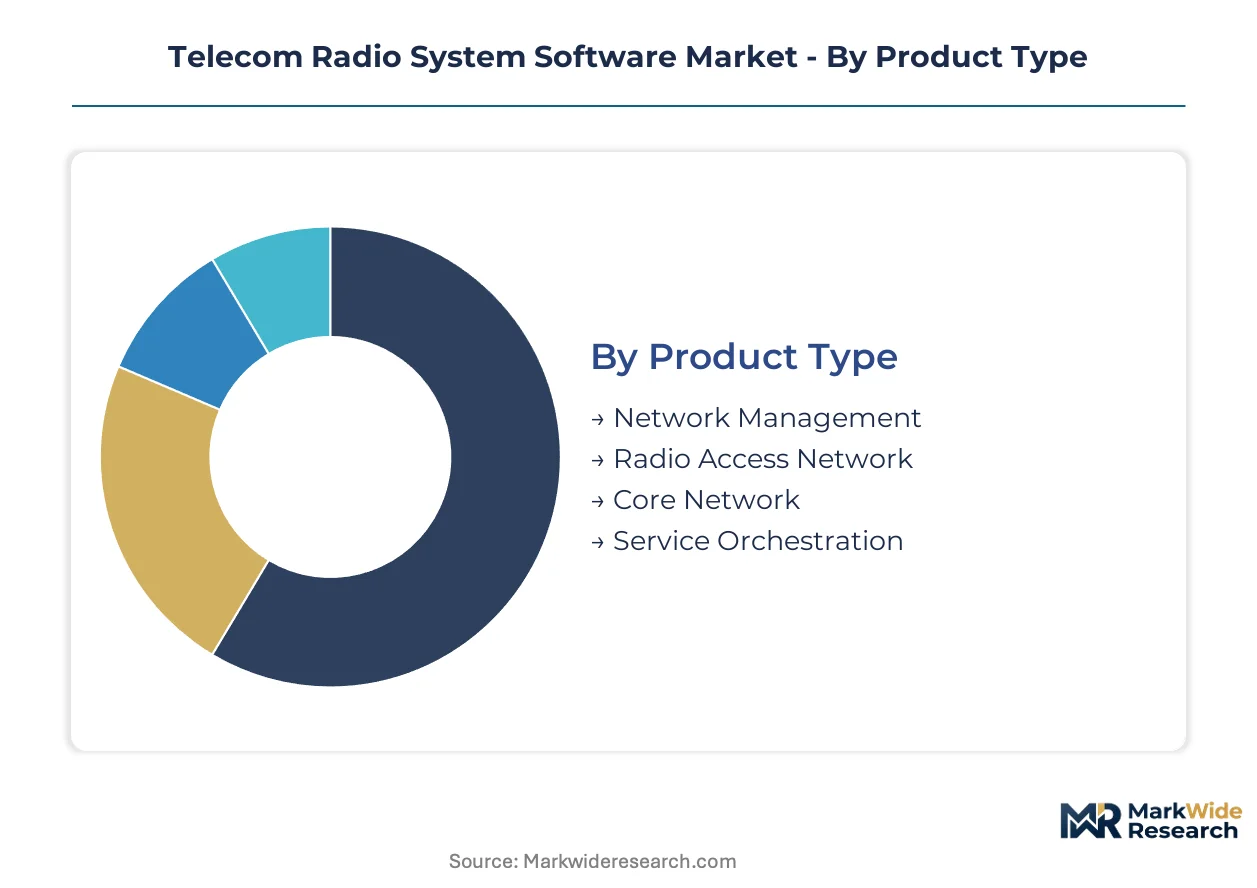
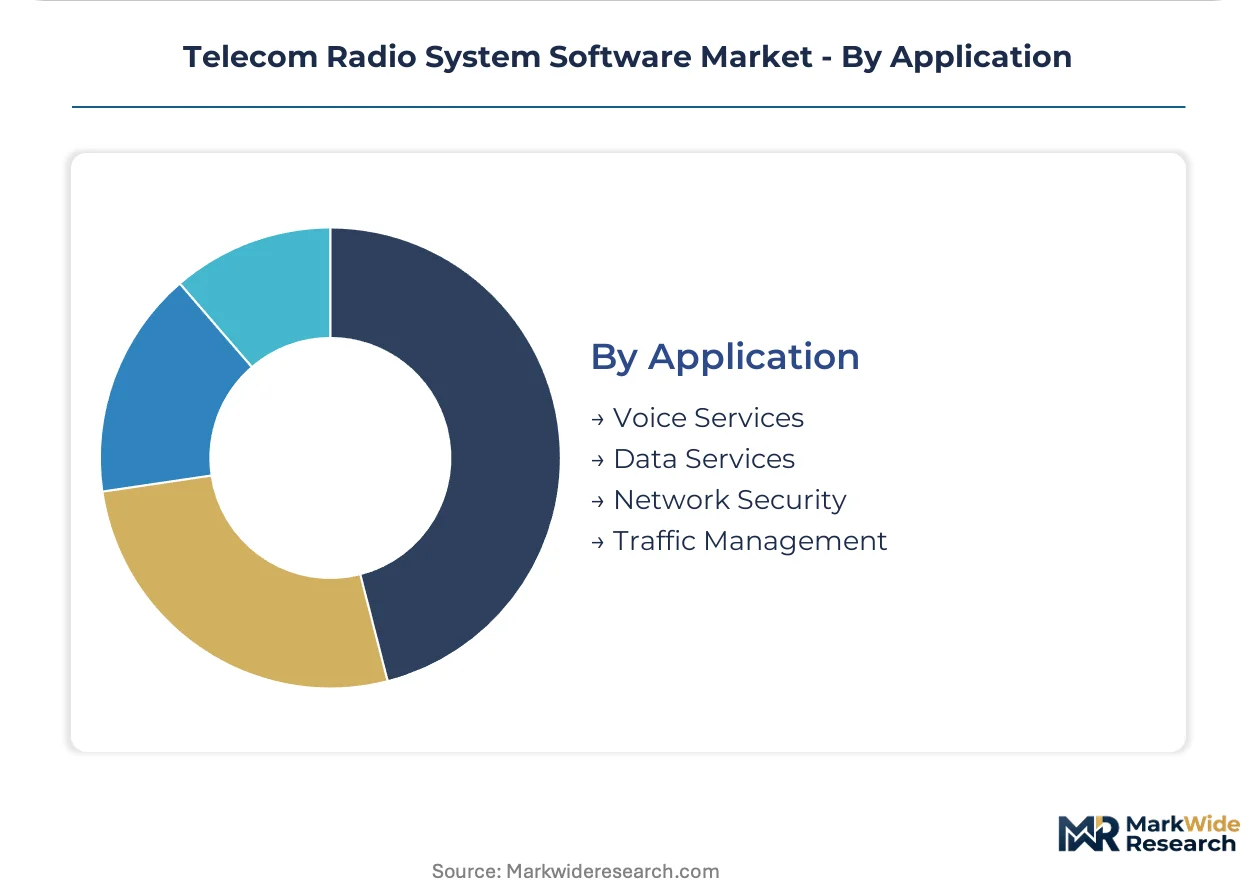
Segmentation in telecom radio system software reveals how value migrates between hardware-dependent legacy stacks and cloud-native programmable layers. Operators prioritize segments that reduce capital intensity while regulators force interoperability that fragments vendor control.
Product Type:
Radio Access Network software commands the largest deployment volumes, while Service Orchestration captures expanding margin pools as multi-vendor complexity grows.
- Radio Access Network:Layer 1 through Layer 3 signal processing functions execute on distributed units and centralized units, managing beamforming and handover protocols. Demand concentrates in South Korea where mobile network operators accelerate cloud-native procurement for 5G standalone expansion.
- Service Orchestration:Multi-vendor interoperability management and resource scheduling software enables operators to mix radio hardware from competing suppliers. Procurement is expanding in Germany and Japan where Open RAN mandates force separation of software from proprietary baseband stacks.
- Network Management:Fault monitoring and performance optimization platforms for heterogeneous radio infrastructure.
- Core Network:Packet routing and session management software connecting radio access to internet gateways.
Mature deployment sits with Radio Access Network. Newer deployment is concentrated in Service Orchestration.
Deployment:
Cloud-Based architectures are gaining share fastest where hyperscaler infrastructure absorbs elastic traffic spikes, while On-Premises retains dominance in security-sensitive installations.
- Cloud-Based:Kubernetes-orchestrated network functions run on hyperscaler infrastructure, enabling elastic capacity scaling without permanent hardware overprovisioning. South Korean operators deploy this model for stadium events and industrial peak loads.
- Edge Computing:Radio software executes on localized compute nodes to minimize latency for time-critical applications. German manufacturing facilities and South Korean logistics centers drive private 5G adoption requiring software-defined spectrum management at the edge.
- On-Premises:Dedicated data center installations maintaining full operator control over physical infrastructure.
- Hybrid:Split workloads between private facilities and public cloud resources based on latency and compliance requirements.
Established operators favor Hybrid deployments. Edge Computing is climbing the fastest among enterprise private network adopters.
End User:
Telecommunication Service Providers account for the dominant procurement volume, though Enterprises are forcing architectural shifts through private spectrum deployments.
- Telecommunication Service Providers:Mobile network operators procure radio software to virtualize distributed units and reduce per-subscriber infrastructure costs. Indian carriers pursue aggressive network virtualization given acute capital intensity pressure from among the world's lowest ARPU levels.
- Enterprises:Manufacturing, energy, and logistics facilities deploy localized radio systems demanding flexible software-defined spectrum management. German industrial conglomerates and South Korean automotive manufacturers lead this segment.
- Government Agencies:Public safety and defense networks requiring hardened, sovereign-controlled radio infrastructure.
- Managed Service Providers:Third-party operators delivering radio network operations as outsourced services.
Procurement scale sits with Telecommunication Service Providers. Stakeholder attention is shifting toward Enterprises as private 5G spectrum allocations multiply.
Application:
Data Services absorb the majority of radio software investment as mobile traffic shifts from voice-centric to bandwidth-intensive applications.
- Data Services:High-throughput packet processing for video streaming, cloud access, and industrial IoT connectivity. South Korean and German operators prioritize this application for 5G network slicing.
- Network Security:Encryption, authentication, and threat detection software protecting radio interfaces from interception and manipulation. EU Cybersecurity Certification Scheme requirements are expanding procurement in European markets.
- Voice Services:Circuit-switched fallback and VoLTE packet voice processing.
- Traffic Management:Dynamic resource allocation and congestion control algorithms.
Legacy investment remains in Voice Services. Security and data optimization together represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates acute demand for capital-efficient radio software solutions as carriers confront the world's lowest ARPU levels. South Korea and Germany drive procurement velocity through aggressive 5G standalone and Open RAN mandates respectively. Japan's enterprise spectrum allocations are fragmenting traditional operator-centric deployment models.
United States
FCC spectrum auction rules mandate software-upgradeable equipment across all new radio deployments. The Bureau of Industry and Security export controls on semiconductor manufacturing equipment are constraining supply chain options for domestic vendors. Silicon Valley and Austin clusters host the largest concentration of cloud-native RAN software engineering talent.
Germany
Industrial conglomerates in Bavaria and Baden-Württemberg are procuring private 5G radio systems for manufacturing automation. The Federal Network Agency enforces Open RAN interoperability standards that fragment proprietary vendor lock-in. The Stuttgart automotive cluster drives edge computing radio deployments for real-time quality control systems.
South Korea
Mobile network operators in Seoul are accelerating cloud-native RAN procurement for 5G standalone network expansion. The Ministry of Science and ICT funds domestic software vendors through national R&D programs. The Pangyo Techno Valley concentration houses the primary development centers for containerized radio orchestration platforms.
Japan
Enterprise manufacturers in Aichi and Osaka prefectures demand localized radio software for logistics and energy facility automation. The Ministry of Internal Affairs and Communications requires multi-vendor interface certification for all new radio deployments. The Yokohama industrial corridor hosts the densest concentration of private 5G spectrum license holders.
India
Telecom service providers pursue aggressive network virtualization to reduce per-subscriber infrastructure costs amid severe capital intensity pressure. TRAI regulations encourage domestic software development through production-linked incentive schemes. The Bangalore and Hyderabad technology corridors concentrate indigenous RAN software engineering capabilities.
Telecom Radio System Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as incumbent vendors rearchitect proprietary stacks to comply with interoperability mandates. The market structure remains tiered between integrated equipment suppliers, pure-play software specialists, and hyperscaler-affiliated orchestration platforms. Three archetypes define competitive positioning: heritage telecom equipment vendors with deep R&D intensity, cloud-native software entrants capturing orchestration value, and Asian manufacturing-scale players competing on cost. M&A activity and technology licensing agreements represent the dominant competitive vectors.
Within the heritage equipment tier, Nokia Corporation and Ericsson exemplify vendors leveraging Bell Labs heritage and European operator relationships respectively. Huawei Technologies occupies a position as a manufacturing-scale competitor despite geopolitical market access constraints. These three anchors represent distinct strategic postures: algorithmic R&D intensity, managed services bundling, and cost-optimized hardware-software integration.
| Leading Market Players |
|---|
| Nokia Corporation |
| Ericsson |
| Huawei Technologies |
| Cisco Systems |
| Oracle Corporation |
| NEC Corporation |
| Amdocs |
| Alcatel-Lucent |
| ZTE |
| Others |
Value Network & Pricing Analysis
Cloud-native disaggregation of radio access network architectures is collapsing traditional hardware-software bundling economics while concentrating procurement leverage among operators with multi-vendor qualification mandates. This structural shift simultaneously compresses margins on legacy integrated baseband units and redistributes value capture toward orchestration software vendors with containerized deployment expertise.
Pricing Analysis
Volume concentrates in Radio Access Network software while margin pools migrate toward Service Orchestration tiers. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade under EU Cybersecurity Certification Scheme requirements and volume scale of distributed unit deployments. Pricing pressure stems from Indian operators' acute capital intensity constraints amid among the world's lowest ARPU levels. Telecommunication Service Providers in South Korea and Germany exhibit lowest price sensitivity given 5G standalone deployment urgency, while Indian carriers demand aggressive per-subscriber cost reduction.
Supply Chain Analysis
Dual-sourcing requirements from Japanese and German operators mandate multi-supplier qualification for programmable accelerators and general-purpose processors. Fabrication capacity concentrates in Taiwan and South Korea for advanced Layer 1 processing chips, with assembly and testing distributed across China and Vietnam. Raw material dependencies include silicon wafers, rare earth elements for thermal management, and fluoropolymer-based conformal coatings facing REACH regulatory scrutiny. Single-source vulnerability around Taiwan semiconductor fabrication creates procurement lead time uncertainty. Distribution runs through direct vendor-operator contracts for Tier 1 deployments, with systems integrators mediating multi-vendor Open RAN configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced node semiconductor fabrication capacity constraints in Taiwan and South Korea are propping software pricing power as operators compete for limited engineering resources to port containerized network functions.
For Market Incumbents: Extend managed services bundling into outcome-based network performance contracting to capture recurring revenue streams and lock out pure-play software entrants. Deepen backward integration into programmable accelerator design through Bell Labs-style R&D partnerships with foundries. Prioritize certification investment under EU Cybersecurity Certification Scheme to maintain premium positioning against Asian cost competitors facing geopolitical market access restrictions. For New Entrants and Emerging Players: Launch via Kubernetes-based radio software distributions targeting Indian operators desperate for capital-efficient virtualization solutions. Target enterprise private 5G deployments in German manufacturing corridors where incumbent vendor lock-in is weakest. Pursue white-space in multi-tenant orchestration software for neutral host infrastructure models displacing operator-captive systems. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by hyperscaler-affiliated orchestration platforms seeking cellular expertise to complement edge computing infrastructure. Long-term viability favors pure-play software specialists with deterministic Layer 1 signal processing capabilities and containerized deployment track records. Monitor Open RAN interoperability testing timelines as inflection indicator for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Kubernetes-orchestrated network functions reduce porting costs across Intel, AMD, and ARM processor variants. |
| Strategic Partnership | Long-term managed services contracts with Deutsche Telekom and Vodafone transfer traffic-handling risk to vendors. |
| Acquisition of Specialist Firm | Containerized radio orchestration expertise from Pangyo Techno Valley clusters accelerates cloud-native RAN deployment. |
| Geographic Expansion | Indian production-linked incentive schemes under TRAI encourage domestic RAN software engineering in Bangalore and Hyderabad. |
| Product Launch | AI-driven beamforming algorithms reduce computational overhead and lower entry barriers for software specialists. |
Research Methodology
Independent corroboration across CTOs at South Korean mobile network operators, procurement directors at German industrial conglomerates, and platform engineers at Indian telecom service providers underwrites the qualitative findings. Secondary validation draws from FCC spectrum auction filings, ETSI open interface specifications, TRAI production-linked incentive disclosures, and Bureau of Industry and Security export control notifications. Bottom-up deployment volume estimates triangulate against top-down addressable market calculations derived from operator capex guidance and hyperscaler infrastructure investment disclosures.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, deployment model, end user category, and regional regulatory cluster. CAGRs derive from fitted growth curves incorporating 5G standalone deployment velocity, Open RAN interoperability mandate compliance timelines, and enterprise private spectrum allocation trajectories. Forecast inputs include semiconductor fabrication capacity expansion announcements, REACH substance evaluation timelines affecting thermal interface materials, and outcome-based contracting adoption rates among European operators.
Geopolitical export control expansion, REACH restriction extension into conformal coatings, and operator consolidation in key markets are the dominant revision risks. Deviation in Taiwan semiconductor fabrication capacity utilization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Digital Mobile Radio (DMR) Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
Satcom Terminal Market
Telecommunications
5G RAN Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Global SMB Telecom Voice and Data Services Market
Telecommunications
Cambodia Telecom Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Mftpaas Market
Telecommunications
Russia Telecom Market
Telecommunications
LTE Emergency Networks Market
Telecommunications
South Africa MNO - MVNO Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
Indonesia Volte Market
Telecommunications
Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market
Telecommunications
Luxembourg Telecom Market