
 Tetra Terminals Market | 2026-2036
Tetra Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Tetra Terminals Market Analytics
Project finance tied to nationwide public safety networks is rewriting competitive entry requirements for Tetra terminal suppliers. Motorola Solutions leverages its installed base across government trunking contracts to sustain recurring service revenue. Hytera Communications competes through manufacturing scale in digital handheld production. Thales Group anchors European defense and security procurement with encryption-certified devices.
Tetra terminals are professional mobile radio devices operating on Terrestrial Trunked Radio standards, typically supporting 25 kHz channel spacing with TDMA architecture for mission-critical voice and data dispatch. These terminals serve police, fire, ambulance, and utility coordination where cellular networks fail or lack priority access. Handheld terminals dominate unit shipments due to frontline officer deployment, while vehicle-mounted terminals capture higher average selling prices in fleet command applications. Digital transmission technology leads technology segmentation as analog sunset deadlines approach across European networks. Public safety applications concentrate the largest installed base, though utilities represent the fastest-growing application as grid operators modernize field workforce communications.
ETSI mandates CE marking and interoperability certification for Tetra equipment across European member states, while national regulators such as BNetzA in Germany and Ofcom in the United Kingdom enforce spectrum allocation and encryption export controls. The FCC in the United States governs narrowbanding requirements that influence Tetra-adjacent P25 migration decisions. Stakeholders must monitor spectrum refarming timelines and dual-mode LTE-Tetra device certification pathways to align product roadmaps with procurement cycles.
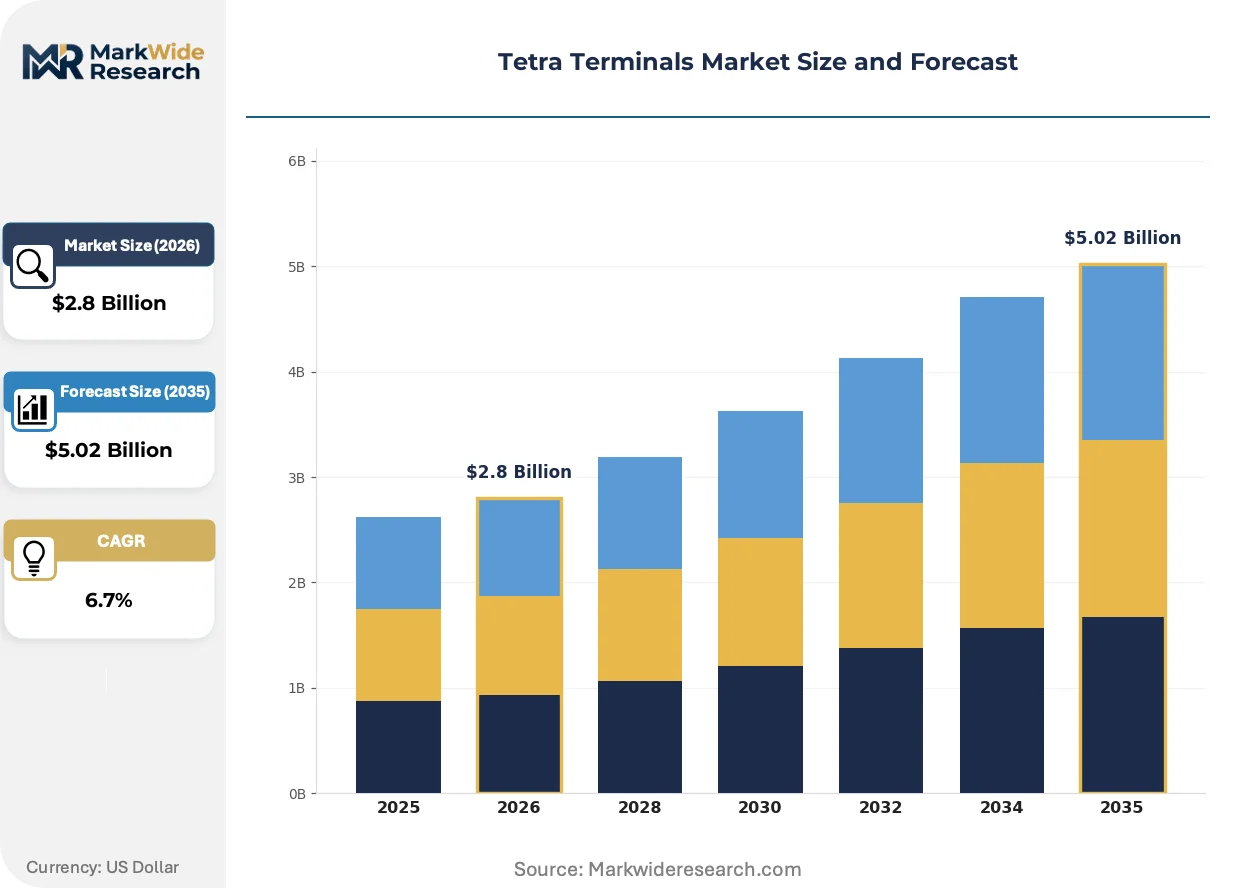
Market Dynamics
ETSI-mandated encryption standards and LTE-Tetra interoperability protocols are forcing terminal suppliers to reengineer product roadmaps around dual-mode certification requirements, compressing development cycles and raising competitive entry barriers.
Growth Catalysts
- German Public Safety Mandates:BNetzA enforcement of encrypted digital trunking for police and emergency services creates replacement demand across state procurement frameworks.
- Critical Infrastructure Modernization:Nordic grid operators deploy Tetra terminals for field workforce coordination, expanding addressable market beyond traditional first responder segments.
- TDMA Architecture Advantages:25 kHz channel spacing with time-division multiple access delivers superior spectral efficiency in spectrum-constrained environments versus analog alternatives.
Market Restraints
- Semiconductor Supply Concentration:Specialized baseband processors for Tetra modems source from limited foundry capacity in Taiwan, exposing procurement timelines to geopolitical disruption.
- Certification Cost Burden:CE marking and ETSI interoperability testing require six-figure euro investments per terminal variant, disadvantaging smaller equipment vendors.
- LTE Mission-Critical Substitution:3GPP Release 16 MCX standards enable broadband push-to-talk over commercial cellular, threatening Tetra's voice-dispatch dominance in non-security applications.
Strategic Opportunities
- Utility Sector Expansion:Water and electricity distribution operators in France and Spain adopt Tetra for SCADA integration and workforce safety, opening industrial verticals.
- Dual-Mode Device Convergence:Hybrid LTE-Tetra terminals bridge narrowband reliability with broadband data, capturing migration budgets from agencies delaying full network replacement.
- Swiss Alpine Infrastructure:Mountain rescue and tunnel operators require ruggedized terminals with extended temperature ranges, supporting premium product positioning.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized expertise in TDMA waveform design and spectrum planning concentrates among aging European engineering cohorts, constraining R&D scaling.
- Legacy System Integration Complexity:Tetra terminals must interface with decades-old dispatch consoles and CAD systems, requiring costly custom protocol adaptation per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetra Terminals Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Terminals, Desktop Terminals, Vehicle-Mounted Terminals, Fixed Terminals Technology: Analog Transmission, Digital Transmission, IP Networking, Encryption Methods Application: Public Safety, Transportation, Utilities, Security Services End User: Government Agencies, Emergency Services, Industrial Users, Commercial Enterprises |
| Companies Covered | Motorola Solutions, Inc., Hytera Communications Corporation Limited, Airbus Defence and Space, Sepura plc, JVCKenwood Corporation, Thales Group, DAMM Cellular Systems A/S, Simoco Wireless Solutions, Tait Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetra Terminals Market Evolving Landscape
Digital transmission protocols are displacing analog voice across European public safety networks, while encryption certification requirements and procurement model evolution reshape how terminals reach end users.
Software-defined radio architectures are digitizing baseband processing functions previously handled by dedicated hardware chipsets. Police departments in Germany and the Netherlands accelerate procurement of SDR-enabled handhelds to future-proof against evolving ETSI standards. This transition is digitizing supply chain economics by collapsing multiple hardware variants into firmware-configurable platforms.
CE marking requirements under the EU Radio Equipment Directive now mandate cybersecurity assessments for Tetra terminals handling classified communications. Manufacturers must demonstrate resistance to side-channel attacks and secure boot protocols before market entry. Defense and interior ministry procurement in France and Italy now prioritizes terminals with Common Criteria certification, filtering vendor participation.
Agency purchasing departments increasingly bundle terminal supply with multi-year maintenance and encryption key management services. This unbundles hardware margins from recurring revenue streams, pressuring pure equipment vendors to build service capabilities. The shift concentrates in German federal state tenders, where BNetzA licensing rules favor suppliers offering integrated network operations.
Tetra Terminals Market Segmentation
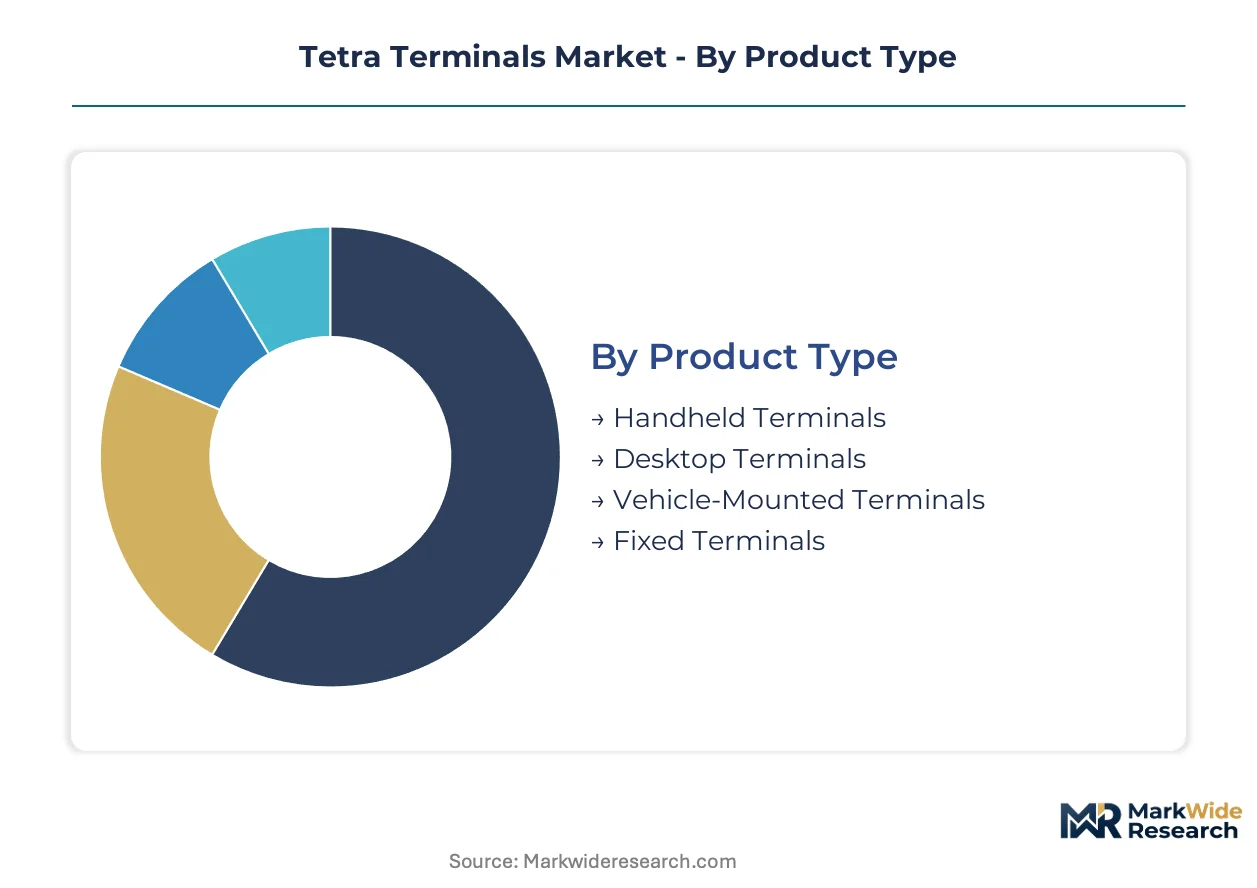
Tetra terminal segmentation reveals how procurement priorities diverge across mission-critical use cases. Product form factors, transmission protocols, and end-user security classifications each create distinct competitive battlegrounds for suppliers.
Product Type:
Form factor determines unit economics and ruggedization requirements across deployment environments.
- Handheld Terminals:Portable devices with IP67 ingress protection and TDMA baseband processors serve frontline police and fire personnel. German state procurement frameworks concentrate demand for encrypted handhelds under BNetzA mandates, with officers requiring push-to-talk reliability in underground transit and dense urban environments.
- Vehicle-Mounted Terminals:Dash-installed units with higher transmit power and external antenna interfaces command premium pricing in fleet command applications. Nordic critical infrastructure operators deploy these for grid maintenance vehicle coordination, where broadband data integration with SCADA systems drives specification requirements.
- Desktop Terminals:Base station control units with multi-channel dispatch interfaces anchor command center operations.
- Fixed Terminals:Permanent-installation units with AC power and wired network backhaul serve control room and infrastructure monitoring points.
Handheld terminals hold installed capacity. Vehicle-mounted terminals are rotating up the share rankings.
Technology:
Transmission architecture governs spectral efficiency, interoperability certification, and product lifecycle positioning.
- Digital Transmission:TDMA-based voice and data protocols operating in 25 kHz channels deliver encrypted trunked communications with superior spectral efficiency versus analog alternatives. ETSI mandates across European member states are accelerating replacement cycles as analog sunset deadlines approach in German and Dutch public safety networks.
- Encryption Methods:Hardware-accelerated AES and proprietary algorithms with Common Criteria certification protect classified communications. French and Italian defense ministry procurement now requires side-channel attack resistance and secure boot protocols, filtering vendor participation to encryption-certified suppliers.
- Analog Transmission:Legacy FM voice systems persist in transitional networks awaiting full digital migration.
- IP Networking:Packet-switched backhaul and control plane integration enable LTE-Tetra hybrid architectures.
Digital transmission holds installed capacity. Encryption methods are rotating up the share rankings.
Application:
End-use verticals impose divergent reliability, integration, and regulatory compliance requirements.
- Public Safety:Police, fire, and ambulance dispatch networks require ETSI-interoperable encrypted trunking with priority access and group call management. German federal state tenders under BNetzA licensing rules favor integrated network operations, bundling terminal supply with multi-year maintenance services.
- Utilities:Electricity and water distribution operators adopt Tetra for field workforce safety and SCADA integration. Grid modernization in France and Spain is expanding this vertical beyond traditional first responder markets, with operators requiring ruggedized terminals for remote substation access.
- Transportation:Rail, airport, and port authorities coordinate logistics and emergency response across geographically dispersed facilities.
- Security Services:Private guarding and facility protection operations utilize Tetra where cellular coverage is unreliable or priority access unavailable.
Public safety holds installed capacity. Utilities represent the steepest expansion trajectory.
End User:
Customer type shapes procurement authority, budget cycles, and service bundling expectations.
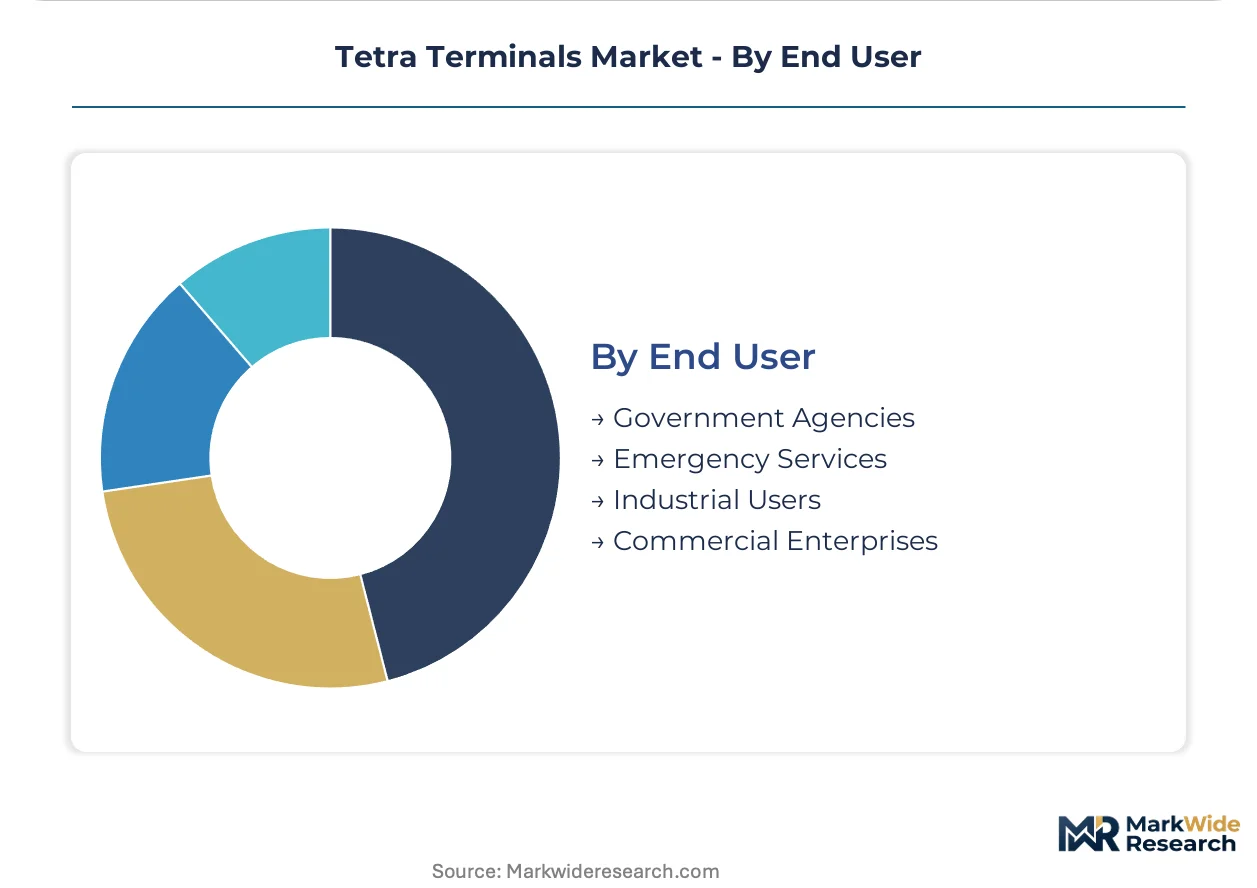
- Government Agencies:Federal and state interior ministries with sovereign encryption requirements drive premium-certified terminal demand. CE marking under the EU Radio Equipment Directive now mandates cybersecurity assessments, with procurement concentrated in German and Dutch frameworks.
- Emergency Services:Police, fire, and medical dispatch organizations with frontline officer deployment concentrate handheld terminal volume.
- Industrial Users:Energy, transportation, and manufacturing operators with private network licenses prioritize workforce safety and operational continuity.
- Commercial Enterprises:Logistics, construction, and event management firms utilize Tetra where cellular fails or group coordination demands dedicated spectrum.
Government agencies hold installed capacity. Industrial users are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European terminal suppliers export encryption-certified devices to Middle Eastern public safety agencies while importing specialized baseband processors from Asian foundries. This trade flow concentrates manufacturing value-add in Germany and France while sourcing critical semiconductors from Taiwan and South Korea.
Germany
BNetzA mandates encrypted digital trunking for all state police forces, driving replacement procurement across sixteen federal frameworks. The EU Radio Equipment Directive requires CE marking with cybersecurity assessments for classified communications. Bavaria's Munich-Stuttgart corridor hosts system integrators delivering bundled terminal and network operations to interior ministries.
United Kingdom
Ofcom spectrum refarming deadlines accelerate migration from analog systems in rural emergency services. The UK National Cyber Security Centre certifies encryption standards for defense-adjacent procurement. Greater Manchester and West Midlands police forces deploy hybrid LTE-Tetra terminals for underground transit coverage.
France
ANSM and defense ministry procurement prioritize Common Criteria certified terminals with side-channel attack resistance. The country's national pharmaceutical regulator framework influences adjacent critical infrastructure security standards. Île-de-France region concentrates demand from Paris metropolitan fire and emergency medical services.
Netherlands
Police and security services mandate ETSI-interoperable trunking with priority access for port and airport authorities. The Dutch Authority for Digital Infrastructure enforces encryption export controls on terminal shipments. Rotterdam-The Hague corridor operators deploy ruggedized handhelds for chemical facility emergency response.
Switzerland
Federal Office of Communications licensing supports alpine rescue and tunnel operator requirements for extended temperature range devices. Swissmedic certification pathways for secure communications filter vendor participation. Gotthard Base Tunnel and Simplon Tunnel networks specify dual-mode terminals for cross-border coordination with Italian authorities.
Tetra Terminals Market Competitive Landscape
On the supply side, the industry is consolidating around encryption-certified specialists with government trunking experience. Three strategic archetypes dominate: integrated network operators bundling terminals with maintenance services, manufacturing-scale producers optimizing digital handheld unit economics, and defense-anchored suppliers leveraging security clearance advantages. Competitive moves concentrate on dual-mode LTE-Tetra certification partnerships and multi-year service contract capture.
Within the integrated solutions tier, Motorola Solutions, Inc. and Thales Group exemplify archetypes combining terminal supply with recurring network operations revenue. Hytera Communications Corporation Limited occupies a manufacturing-scale position optimizing production economics for digital handheld volume. These three anchors illustrate how procurement bundling, encryption certification, and manufacturing scale constitute distinct competitive vectors in public safety and critical infrastructure verticals.
| Leading Market Players |
|---|
| Motorola Solutions, Inc. |
| Hytera Communications Corporation Limited |
| Airbus Defence and Space |
| Sepura plc |
| JVCKenwood Corporation |
| Thales Group |
| DAMM Cellular Systems A/S |
| Simoco Wireless Solutions |
| Tait Communications |
| Others |
Value Network & Pricing Analysis
Undercapacity in Taiwanese foundry capacity for specialized baseband processors drives supplier allocation discipline and sustains pricing power for encryption-certified terminal variants. BNetzA procurement timelines in Germany compress buyer negotiation windows, reinforcing premium positioning for vendors with CE marking and Common Criteria certification already secured.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure where three-tier pricing stratifies across government-grade encrypted, commercial ruggedized, and economy handheld tiers. Price differentiation centers on Common Criteria certification level and after-sales service bundling, with German federal tenders requiring integrated maintenance contracts. Cost compression in the economy tier intensifies because Hytera's manufacturing scale advantages force pure-equipment vendors toward margin erosion. Government agencies show least price sensitivity due to sovereign encryption mandates, while commercial logistics operators exhibit highest sensitivity to per-unit acquisition costs.
Supply Chain Analysis
Geopolitical exposure across the Taiwan Strait dominates supply chain risk assessment for Tetra terminal manufacturers. Specialized baseband processors source from Taiwan and South Korea, while final assembly concentrates in China and Vietnam. Raw material dependencies include gallium arsenide substrates, precision RF filters, and hardware security modules. Single-source vulnerability in ETSI-certified encryption chipsets constrains vendor qualification timelines. Distribution runs through system integrators delivering bundled network operations to German federal states and Nordic grid operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across sixteen German federal frameworks and divergent Nordic utility specifications creates specialist vendor niches. Dual-mode LTE-Tetra certification requirements favor players with parallel cellular and narrowband development capabilities.
For Market Incumbents: Pre-empt emerging substitution threats from 3GPP Release 16 MCX broadband push-to-talk by accelerating hybrid terminal roadmaps. Deepen backward integration into encryption chipset supply through captive relationships with Common Criteria-certified semiconductor vendors. Lock channel control via multi-year service bundling in BNetzA framework tenders to raise competitive entry barriers for manufacturing-scale challengers.
For New Entrants and Emerging Players: Utility sector field workforce safety applications in France and Spain represent the most penetrable entry point given less stringent sovereign encryption requirements than defense-adjacent procurement. Swiss alpine infrastructure specifications for extended temperature range devices offer premium positioning without direct competition from volume-optimized handheld producers. Pursue SCADA integration partnerships with grid operators as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated network operators bundling terminals with encryption key management and maintenance services. Long-term viability over a multi-year horizon rests on dual-mode certification completion and ETSI interoperability maintenance. Acquisition candidates with established German federal state relationships and active LTE-Tetra hybrid development programs signal readiness for procurement cycle inflection. Monitor BNetzA licensing rule evolution as the critical demand trigger.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Certification Completion | ETSI interoperability validation unlocks German federal procurement frameworks and migration budgets. |
| Encryption Chipset Backward Integration | Captive supply of Common Criteria-certified components reduces qualification timelines and geopolitical exposure. |
| Utility Sector SCADA Partnership | French and Spanish grid operator relationships open fastest-growing application vertical beyond public safety. |
| Multi-Year Service Contract Capture | BNetzA framework preference for integrated network operations unbundles hardware margins from recurring streams. |
| Alpine Infrastructure Specification Development | Swiss tunnel and mountain rescue requirements support premium positioning with extended temperature range devices. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tetra network operators, procurement officers at German interior ministries, and RF engineering directors at terminal manufacturers; and secondary validation through ETSI interoperability certification databases, BNetzA licensing records, and customs trade data for baseband processor imports. Primary fieldwork captured procurement timeline dynamics and certification cost structures. Secondary sources included SEC filings for listed equipment vendors, EU Radio Equipment Directive implementation reports, and Nordic grid operator capital expenditure disclosures. Bottom-up unit shipment estimates by product form factor and application vertical were triangulated against top-down market value reconstructions.
Forecast inputs spanned technology migration curves, spectrum refarming timelines, and dual-mode device adoption rates across the analysis window. Segmentation dimensions modeled include product type, transmission protocol, encryption certification tier, end-use application, and customer procurement authority. CAGRs were derived from logistic diffusion curves fitted to replacement cycle data and procurement framework award patterns. Industry-specific forecast inputs incorporated ETSI analog sunset deadlines and 3GPP Release 16 MCX standard commercialization trajectories.
Macroeconomic conditions sit as an overlay; deviation in semiconductor foundry utilization rates, European defense budget allocations, or cross-strait trade flows would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline continuity and procurement bundling persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Finland Telecom Market
Telecommunications
South Africa Telecom Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
Indonesia Telecom Towers Market
Telecommunications
Free Space Optics (FSO) Communication Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
IP PBX Market
Telecommunications
Thailand ICT Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Cambodia ICT Market
Telecommunications
South Africa MNO - MVNO Market
Telecommunications
China ICT Market
Telecommunications
Global Radio Access Network Market
Telecommunications
Egypt Telecom Tower Market
Telecommunications
CDMA Mobile Phone Market
Telecommunications
South Africa Telecom Tower Market