
 Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market | 2026-2036
Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market Analytics
Taiwanese chipset fabrication capacity is shifting toward Wi-Fi 7 baseband silicon to support higher-density VoWLAN deployments in enterprise environments. Cisco Systems, Inc. leverages its Meraki cloud stack to dominate mid-market campus rollouts, while Aruba Networks anchors its position through deep integration with HPE's edge-to-cloud architecture. Huawei Technologies Co., Ltd. competes aggressively in Asia-Pacific carrier-managed VoWLAN services despite access restrictions in Western markets.
Voice Over Internet Protocol Over WLAN denotes the transmission of packetized voice traffic across IEEE 802.11 wireless local area networks, typically employing QoS markings via WMM and low-latency codec profiles to maintain sub-150ms mouth-to-ear delay for conversational clarity. The technology serves primarily to untether workers from desk phones while preserving PBX feature parity across corporate, healthcare, and hospitality environments. Hardware deployments currently generate the largest revenue pool, though cloud-based deployment models are capturing the fastest expansion as IT departments offload session border controller management to managed service providers. SIP Trunking technology leads enterprise migration paths from TDM circuits, while WebRTC adoption is accelerating among call center operators seeking browser-based agent workstations without softphone client installation.
The FCC governs unlicensed spectrum allocation and Part 15 device certification, directly constraining which frequency bands and power levels VoWLAN handsets may legally operate. ETSI harmonizes European interoperability through EN 301 893 and CE marking requirements for radio equipment, while China's MIIT issues GB standards for wireless voice terminal type approval that foreign vendors must satisfy for market entry. Stakeholders must monitor spectrum reallocation proceedings and codec patent pool developments to anticipate hardware refresh cycles and interoperability testing burdens.
Market Dynamics
Enterprise migration from TDM trunking to SIP-based VoWLAN architectures is compressing refresh cycles and forcing infrastructure vendors to bundle session border controllers with wireless access point management platforms.
Growth Catalysts
- Wi-Fi 6E spectrum allocation:The FCC's 6 GHz unlicensed band opening in the United States enables 160 MHz channel bonding for high-density voice deployments in healthcare campuses.
- Mobile clinician workflows:Hospital systems are replacing bedside phones with VoWLAN handsets to support nurse roaming and alert integration with patient monitoring systems.
- E-Rate program modernization:Federal subsidies for K-12 institutions are accelerating hybrid classroom connectivity investments across rural and urban school districts.
Market Restraints
- Codec patent pool complexity:Licensing disputes around Opus and G.729 royalty structures inflate per-seat costs for multi-vendor deployments.
- Taiwanese foundry concentration:Wi-Fi 7 baseband silicon supply bottlenecks at TSMC and MediaTek constrain enterprise access point shipment volumes.
- Legacy PBX integration friction:TDM-to-IP gateway requirements extend deployment timelines for organizations with sunk investment in digital phone infrastructure.
Strategic Opportunities
- WebRTC browser-native voice:Call center operators are eliminating softphone client installation through Chrome and Firefox embedded real-time communications.
- India's Smart Cities Mission:Municipal Wi-Fi deployments in Bangalore and Hyderabad create carrier-managed VoWLAN service opportunities for public safety and field worker communications.
- Cloud SBC offloading:IT departments are outsourcing session border controller management to MSPs, reducing on-premise hardware refresh burdens.
Industry Challenges
- RF interference mitigation:Co-channel contention from IoT sensors and video streaming degrades voice MOS scores in 2.4 GHz dense environments.
- Roaming handoff latency:Sub-50 ms access point transitions require controller architecture redesigns that strain mid-market IT skill bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market |
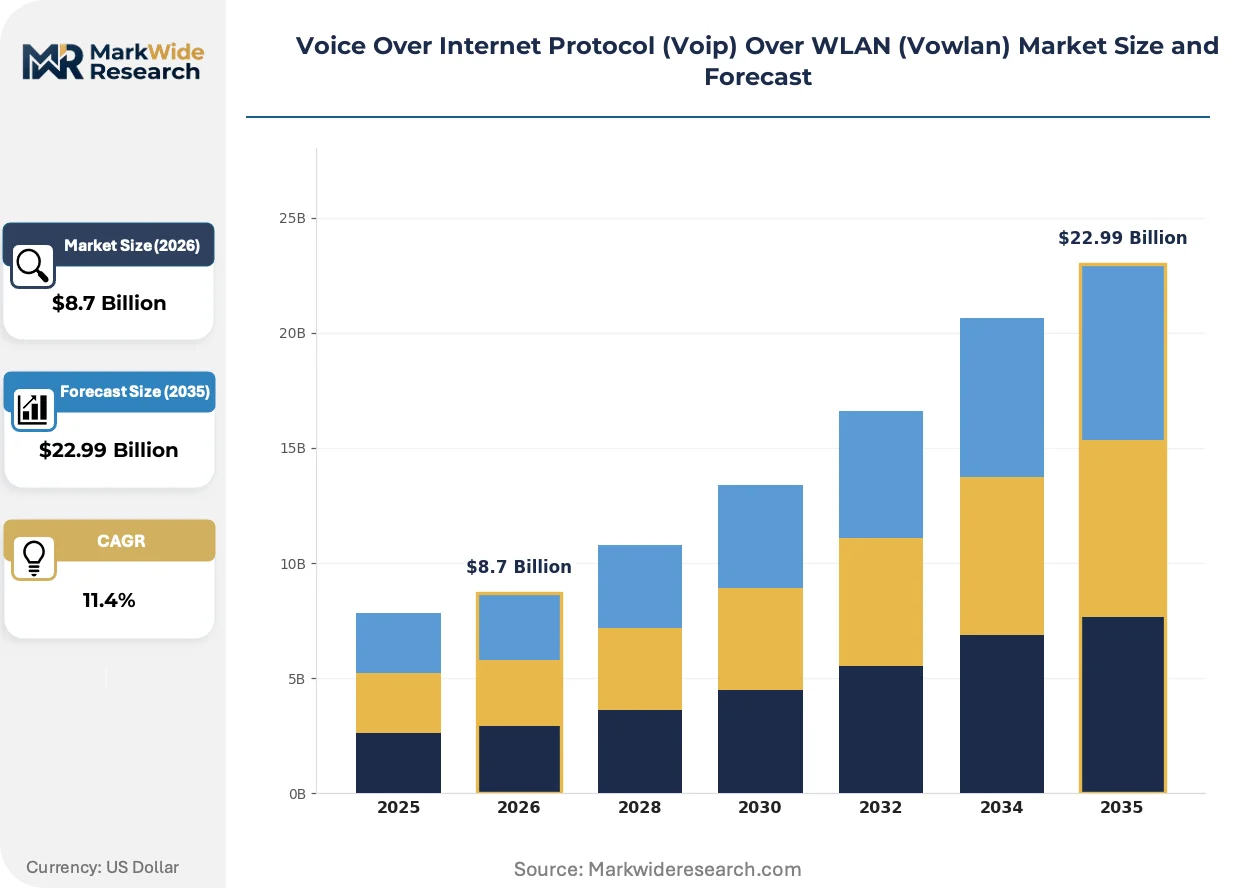
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Service, Application Technology: Session Initiation Protocol, SIP Trunking, WebRTC, Softswitch End User: Enterprises, Call Centers, Hospitality, Residential Users Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services |
| Companies Covered | Cisco Systems, Inc., Aruba Networks, Huawei Technologies Co., Ltd., Alcatel-Lucent Enterprise, Extreme Networks, Inc., Avaya Inc., Ruckus Wireless Inc., Aerohive Networks, Zebra Technology Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market Evolving Landscape
Codec efficiency improvements and spectrum policy liberalization are converging to enable voice-grade wireless density previously reserved for wired Ethernet deployments.
Wi-Fi 7 baseband silicon is absorbing multi-link operation capabilities that bond 2.4 GHz, 5 GHz, and 6 GHz bands into single logical channels. Enterprise campus networks in the United States are piloting these chipsets for conference room density targets exceeding fifty simultaneous voice streams per access point. The technology is absorbing switching infrastructure investment that previously flowed into dedicated DECT-over-IP overlay networks.
The FCC's Part 15 device certification process is tightening power spectral density limits for 6 GHz low-power indoor devices. Manufacturers must redesign front-end modules to satisfy revised conducted emissions templates before market entry. Healthcare systems in Texas and California are delaying procurement until Q3 certification lists stabilize.
Facility managers are unbundling voice service contracts from hardware lease agreements. HPE Aruba and Cisco Meraki are responding with subscription-based WLAN assurance tiers that include SLA-backed MOS monitoring. This purchasing pattern shift is most visible in United States educational institutions navigating E-Rate reimbursement compliance.
Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market Segmentation
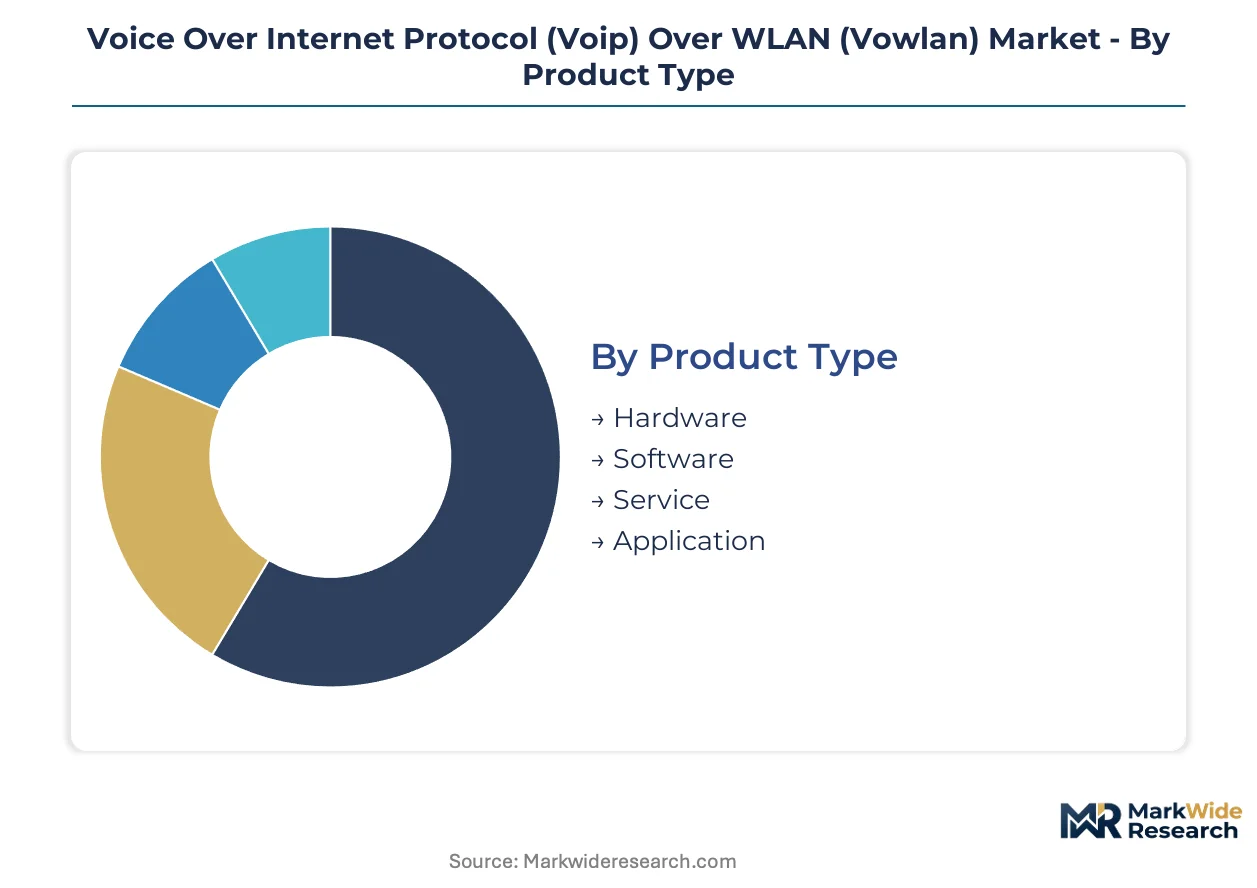
VoWLAN market segmentation reveals how infrastructure investment flows across physical equipment, enabling software, and operational services. Each category reflects distinct procurement patterns between organizations building in-house expertise versus those outsourcing voice infrastructure management.
Product Type:
Standalone hardware deployments dominate enterprise campus budgets while embedded software solutions penetrate mobile-first workforces.
- Hardware:Access points, VoWLAN handsets, and session border controllers constitute the foundational equipment layer. Hospital systems in Texas and California concentrate procurement here for nurse roaming and patient alert integration.
- Software:Call control platforms, codec optimization engines, and network management suites enable feature parity with legacy PBX systems. Cloud-native licensing models are displacing perpetual seat purchases in mid-market enterprises.
- Service:Professional implementation, training, and ongoing technical support contracts.
- Application:Vertical-specific solutions for hospitality guest services and healthcare clinical workflows.
Hardware leads volumes today; cloud software licensing is gaining share fastest.
Technology:
Protocol selection determines interoperability scope and migration complexity from TDM infrastructure.
- Session Initiation Protocol:The dominant signaling standard for enterprise VoWLAN, enabling handset registration and call routing across multi-vendor environments. SIP trunking consolidation is compressing refresh cycles for organizations exiting PRI circuits.
- SIP Trunking:Direct IP connectivity to carriers eliminates local loop charges. Educational institutions navigating E-Rate reimbursement concentrate demand here for hybrid classroom connectivity.
- WebRTC:Browser-native real-time communications eliminate softphone client installation. Call center operators in United States metropolitan markets adopt this for agent workstation flexibility.
- Softswitch:Software-based call control replacing hardware-centric Class 5 switches.
SIP Trunking anchors current deployment value; WebRTC shows the steepest expansion trajectory.
End User:
Organizational scale and mobility requirements segment procurement priorities across vertical markets.
- Enterprises:Campus-wide unified communications with wireless handset roaming. Corporate headquarters in United States technology corridors drive access point density requirements exceeding fifty simultaneous voice streams.
- Call Centers:Agent workstation virtualization and browser-based voice clients. Quality monitoring integration with workforce management platforms shapes vendor selection.
- Hospitality:Guest room voice services and staff communication systems.
- Residential Users:Consumer-grade VoWLAN through broadband provider bundles.
Enterprises dominate current spending; call center modernization is expanding most quickly.
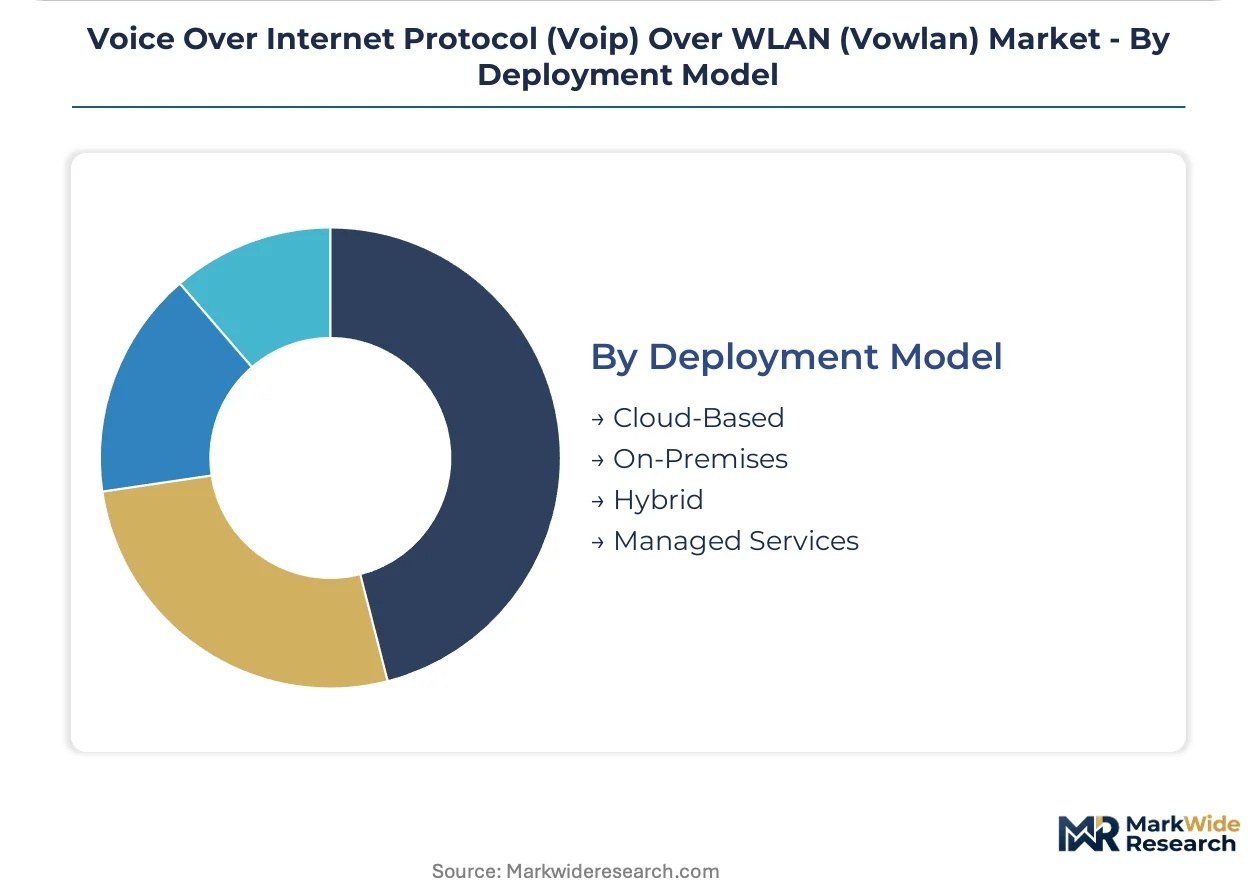
Deployment Model:
Control retention versus operational offloading defines infrastructure strategy across IT maturity levels.
- Cloud-Based:Fully hosted voice platforms with subscription pricing and automatic feature updates. K-12 institutions leveraging E-Rate subsidies concentrate procurement here to minimize on-premise hardware.
- On-Premises:Dedicated call control servers and session border controllers within organizational data centers. Healthcare systems with strict patient data sovereignty requirements maintain this model.
- Hybrid:Split architecture preserving local survivability with cloud feature delivery.
- Managed Services:Outsourced operations including monitoring, patching, and capacity planning.
On-Premises retains the largest installed base; cloud deployments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage around spectrum allocation and E-Rate subsidies is shifting VoWLAN deployment gravity toward jurisdictions with permissive unlicensed band policies and institutional procurement support programs.
United States
Healthcare systems in Texas and California are driving dense access point rollouts for nurse roaming workflows. The FCC's Wi-Fi 6E spectrum opening and E-Rate program modernization compress procurement timelines for K-12 hybrid classrooms. Austin and San Antonio hospital networks currently pilot multi-link operation chipsets for fifty-plus simultaneous voice streams per access point.
Germany
Industrial campuses in Bavaria and Baden-Württemberg prioritize wireless unified communications for factory floor mobility. ETSI harmonization through EN 301 893 enables cross-border handset interoperability for multinational manufacturers. Stuttgart automotive suppliers are replacing DECT-over-IP overlays with 6 GHz enterprise WLAN for production line communications.
China
Carrier-managed VoWLAN services expand through municipal smart city contracts in Shenzhen and Hangzhou. MIIT GB standards for wireless voice terminal type approval constrain foreign vendor market entry while accelerating domestic chipset ecosystem development. Beijing-Tianjin-Hebei corridor enterprises deploy cloud-native call control for distributed workforce mobility.
Japan
Corporate headquarters in Tokyo and Osaka demand sub-50 millisecond roaming handoffs for executive mobility. METI spectrum coordination enables 160 MHz channel bonding in dense metropolitan office towers. Nagoya manufacturing clusters integrate VoWLAN handsets with legacy PBX infrastructure through SIP trunking consolidation.
India
Bangalore and Hyderabad municipal Wi-Fi deployments create carrier-managed service opportunities for public safety field workers. TRAI guidelines on unlicensed spectrum usage shape enterprise procurement decisions for campus voice networks. Karnataka technology parks pilot browser-native WebRTC workstations to eliminate softphone client installation costs.
Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native delivery models and browser-based voice clients. The vendor base stratifies across three maturity levels: legacy infrastructure incumbents with PBX integration expertise, cloud-first challengers with subscription pricing, and semiconductor specialists supplying Wi-Fi 7 baseband silicon. Dominant competitive moves include strategic partnerships between access point manufacturers and session border controller vendors, plus geographic expansion through carrier-managed service contracts in Asia-Pacific markets.
Within the cloud-managed infrastructure tier, Cisco Systems, Inc. and Aruba Networks exemplify contrasting architectural approaches to enterprise campus deployment. Cisco's Meraki cloud stack anchors mid-market rollouts through integrated WLAN assurance and SLA-backed voice quality monitoring. Aruba Networks occupies a position within HPE's edge-to-cloud architecture, emphasizing deep integration between wireless access points and campus switching fabric. Huawei Technologies Co., Ltd. represents the carrier-managed services archetype, competing aggressively in Asia-Pacific markets through turnkey VoWLAN offerings for municipal and institutional clients despite access restrictions in Western jurisdictions.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Aruba Networks |
| Huawei Technologies Co., Ltd. |
| Alcatel-Lucent Enterprise |
| Extreme Networks, Inc. |
| Avaya Inc. |
| Ruckus Wireless Inc. |
| Aerohive Networks |
| Zebra Technology Corporation |
| Others |
Value Network & Pricing Analysis
The FCC's Wi-Fi 6E power spectral density limits for 6 GHz low-power indoor devices gate qualified supply for enterprise access point manufacturers while reserving premium-tier pricing access for vendors with front-end module redesign capabilities. Healthcare systems in Texas and California delay procurement until Q3 certification lists stabilize, compressing margin buffers for mid-tier hardware suppliers.
Pricing Analysis
Distributor margin layers in VoWLAN hardware compress as cloud-managed infrastructure vendors bypass traditional channel partners through direct-to-enterprise subscription models. Three-tier pricing structure across premium, standard, and economy levels differentiates by access point density capacity and SLA-backed MOS monitoring inclusion. Pricing pressure stems from Taiwanese foundry concentration constraining Wi-Fi 7 baseband silicon availability. Educational institutions navigating E-Rate reimbursement exhibit highest price sensitivity; healthcare systems with patient data sovereignty requirements show lowest.
Supply Chain Analysis
Freight cost volatility from Asian manufacturing hubs to North American distribution centers strains margin structures for hardware-centric VoWLAN deployments. Supply concentrates in Taiwan for baseband silicon, China for handset assembly, and the United States for session border controller software development. Raw material dependencies span gallium nitride for power amplifiers, high-purity silicon for chip fabrication, and lithium-ion cells for handset batteries. Single-source vulnerability at TSMC and MediaTek constrains enterprise access point shipment volumes. Distribution runs through carrier-managed service contracts in Asia-Pacific and value-added resellers in North American mid-markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
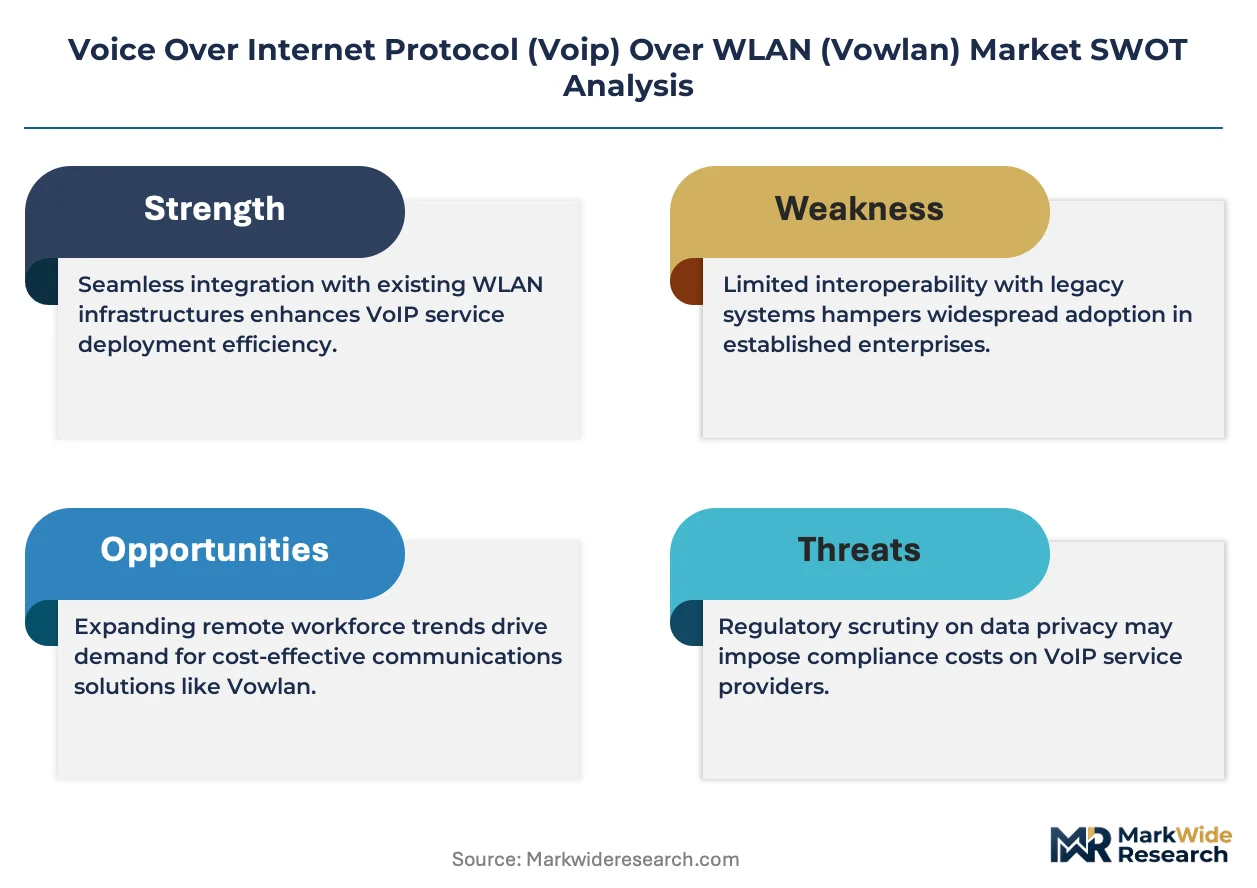
This market functions as a geographic-arbitrage play where E-Rate subsidy availability in United States K-12 institutions contrasts against carrier-managed service deregulation in India's Smart Cities Mission, creating divergent cost structures for identical hardware deployments.
For Market Incumbents: Cement cloud-native delivery architecture dominance through backward integration into session border controller software stacks, countering emerging browser-native WebRTC challengers. Fortify position by embedding SLA-backed MOS monitoring into subscription tiers, raising switching costs for healthcare and education verticals with compliance-sensitive procurement.
For New Entrants and Emerging Players: Launch via carrier-managed service partnerships in municipal Wi-Fi deployments across Bangalore and Hyderabad, exploiting underdeveloped local expertise in roaming handoff latency optimization. Target call center operators in United States metropolitan markets with WebRTC workstation bundles that eliminate softphone client installation friction.
For Investors and Strategic Acquirers: Roll-up economics work for regional MSPs with E-Rate certification expertise because K-12 procurement consolidation favors scaled service providers over fragmented hardware resellers. Long-term viability centers on cloud SBC offloading adoption curves. Watch FCC certification list stabilization for Wi-Fi 7 front-end modules as inflection indicator for hardware refresh cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Wi-Fi 7 Multi-Link Operation Deployment | Enables fifty-plus simultaneous voice streams per access point in Texas hospital pilots. |
| Cloud SBC Offloading Partnership | Reduces on-premise hardware burdens for E-Rate eligible K-12 institutions. |
| WebRTC Browser-Native Integration | Eliminates softphone installation costs for call center operators in metropolitan markets. |
| Carrier-Managed Service Expansion | Captures municipal smart city contracts in India for public safety communications. |
| SLA-Backed MOS Monitoring Tier | Differentiates subscription pricing for healthcare systems with patient alert integration needs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with WLAN infrastructure procurement officers, hospital biomedical engineers, K-12 IT directors, call center operations managers, and carrier service planners with secondary validation against FCC equipment authorization databases, E-Rate program disbursement records, ETSI harmonization standards, and MIIT GB certification lists. Bottom-up access point shipment aggregation and top-down enterprise communications budget allocation models triangulated market sizing.
Comparable-period anchoring tied projection assumptions to historical refresh cycles observed across TDM-to-SIP migration waves and Wi-Fi standard transitions. Segmentation dimensions modeled encompassed deployment model, organization scale, vertical application, protocol technology, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating E-Rate modernization timelines and spectrum allocation proceedings. Industry-specific inputs included Taiwanese foundry capacity utilization rates and healthcare system mobility workflow adoption indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated Wi-Fi 7 certification delays or codec patent pool litigation expansion. Forecasts embed assumptions regarding E-Rate reimbursement continuity and unlicensed spectrum stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Denmark Telecom Market
Telecommunications
TV White Space Spectrum Market
Telecommunications
Cloud PBX Market
Telecommunications
Diameter Signaling Control Market
Telecommunications
Satcom Terminal Market
Telecommunications
Video Door Phones Market
Telecommunications
United States Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Africa Roaming Tariff Market
Telecommunications
Russia ICT Market
Telecommunications
IP PBX Market
Telecommunications
Private LTE in Mining Industry Market
Telecommunications
Telecom Services Market
Telecommunications
South Africa Telecom Tower Market
Telecommunications
Global Hosted PBX Market
Telecommunications
France Telecom Market
Telecommunications
Brazil Telecom Market