
 Global Cognitive Radio Market | 2026-2036
Global Cognitive Radio Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cognitive Radio Market Foresight
Defense communications is repositioning cognitive radio from experimental procurement to program-of-record status across NATO-aligned militaries. BAE Systems leverages its electronic warfare heritage to anchor spectrum dominance solutions for the UK Ministry of Defence. Thales Group sustains Franco-German defense contracts through adaptive waveform architectures. RTX Corporation competes in the US Department of Defense ecosystem with machine-learning-enabled signal classification platforms.
Cognitive radio denotes transceiver systems that autonomously detect available spectrum, reconfigure operating parameters, and coordinate access without human intervention, typically employing real-time spectrum sensing below 6 GHz and dynamic frequency adaptation across licensed and unlicensed bands. Its primary purpose is maximizing spectral efficiency for mission-critical and commercial networks facing bandwidth scarcity. Software Defined Radio dominates hardware deployments due to programmable baseband flexibility, while Machine Learning represents the fastest-expanding technology layer as neural networks replace rule-based spectrum decisions. Military Communications captures the largest value pool given classified waveform requirements, though Public Safety applications are widening as first responders adopt interoperable broadband.
The FCC governs US spectrum-sharing protocols through CBRS and dynamic protection zones, while ETSI enforces harmonized standards under the EU Radio Equipment Directive for cross-border equipment certification. In Asia-Pacific, Japan's MIC coordinates 5G spectrum refarming that indirectly shapes cognitive radio testbed requirements. Stakeholders must monitor how national spectrum auctions and defense modernization cycles determine which technology layers receive procurement priority.
Market Dynamics
Defense procurement cycles are compressing cognitive radio development timelines as NATO-aligned militaries transition experimental spectrum-aware systems into formal program-of-record acquisitions, forcing vendors to accelerate machine-learning integration while navigating multi-jurisdictional certification requirements.
Growth Catalysts
- CBRS Framework Expansion:The FCC's dynamic protection zone protocols are mandating spectrum-sharing infrastructure across US commercial networks, creating immediate procurement pull for adaptive transceiver systems in enterprise and industrial deployments.
- Military Waveform Modernization:Classified communications requirements across NATO defense agencies are accelerating demand for software-defined architectures capable of real-time reconfiguration under contested electromagnetic conditions.
- Neural Network Signal Processing:Machine learning is displacing rule-based spectrum sensing algorithms, enabling sub-millisecond interference detection that satisfies 5G network slicing requirements in South Korean and German testbeds.
Market Restraints
- Gallium Nitride Supply Concentration:High-frequency power amplifier substrates face sourcing constraints from concentrated Chinese rare earth processing capacity, creating input cost volatility for millimeter-wave cognitive radio hardware.
- Cross-Border Certification Friction:The EU Radio Equipment Directive's harmonized standards impose divergent testing protocols from FCC Part 90 rules, forcing vendors to maintain parallel compliance workflows that extend product launch timelines.
- Spectrum Auction Timing Uncertainty:National regulatory bodies in key demand centers are delaying mid-band spectrum releases, freezing capital deployment decisions for infrastructure-scale cognitive radio deployments.
Strategic Opportunities
- Public Safety Broadband Convergence:First responder agencies in the United States are adopting interoperable LTE networks that require cognitive interference management, opening a civilian procurement channel adjacent to defense-centric vendor portfolios.
- AI-Edge Compute Integration:Convergence of neuromorphic processing chips with software-defined radio architectures is enabling on-device spectrum decisions without cloud dependency, reducing latency for autonomous vehicle and drone applications.
- India's Defense Modernization:The country's military electronics procurement is accelerating under indigenous production mandates, creating entry pathways for spectrum-aware systems compliant with BIS telecommunications equipment standards.
Industry Challenges
- RF Engineering Talent Scarcity:The specialized skill set combining microwave engineering with machine learning deployment is concentrating among defense contractors, constraining vendor scaling for commercial market entry.
- Multi-Domain Integration Complexity:Cognitive radio systems must interface with legacy tactical networks, satellite terminals, and cellular infrastructure simultaneously, requiring extensive interoperability testing that extends deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cognitive Radio Market |
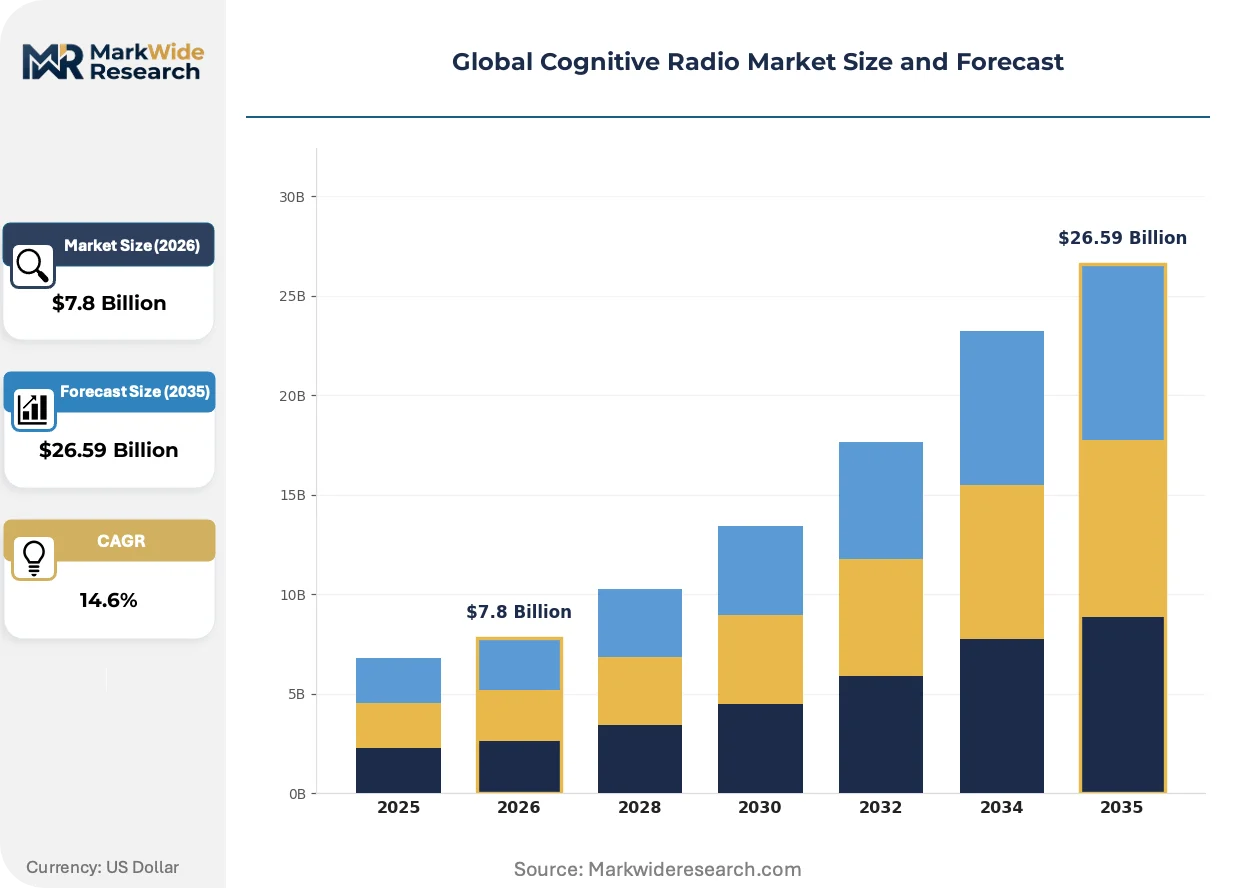
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $26.59 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Defined Radio, Reconfigurable Radio, Smart Radio, Adaptive Radio, Hybrid Radio Technology: Frequency Hopping, Spectrum Sensing, Dynamic Spectrum Access, Machine Learning, Signal Classification Application: Military Communications, Public Safety, Wireless Broadband, Emergency Management, Satellite Communications End User: Telecommunication Providers, Defense Agencies, Government Organizations, Network Operators, Research Institutes |
| Companies Covered | BAE Systems, Thales Group, RTX Corporation, Rohde & Schwarz, L3Harris Technologies, Shared Spectrum, EpiSys Science, DataSoft Corporation, General Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cognitive Radio Market Shifts & Advancements
Real-time spectrum intelligence is migrating from centralized baseband processing to distributed edge nodes, compressing decision latency while expanding the attack surface for electromagnetic domain operations across contested environments.
Neuromorphic computing architectures are unifying spiking neural network inference with analog RF front-ends, enabling sub-microsecond spectrum sensing without digital sampling bottlenecks. Defense primes in the United States and Germany are piloting these merged hardware-software stacks for electronic warfare applications. This convergence is compressing the traditional separation between signal intelligence and communications functions, forcing vendors to restructure product lines around unified electromagnetic spectrum operations.
ETSI's harmonized standards under the EU Radio Equipment Directive are mandating cybersecurity certification for radio equipment before CE marking approval, adding mandatory penetration testing and secure boot requirements to hardware development workflows. European infrastructure vendors are restructuring supply chains to satisfy these concurrent safety and security protocols. The directive's cross-border enforcement is most acutely affecting small-cell and private network equipment categories where software update mechanisms require continuous vulnerability management.
Defense procurement offices are consolidating vendor relationships around multi-year platform contracts rather than discrete hardware purchases, compressing supplier margins while demanding continuous algorithmic performance improvements. This behavioral shift is displacing traditional equipment leasing models in NATO-aligned military communications. The United Kingdom Ministry of Defence and US Department of Defense ecosystems exhibit the most pronounced concentration, with program offices now requiring machine-learning model retraining as a contracted deliverable rather than a post-sale service option.
Global Cognitive Radio Market Segmentation
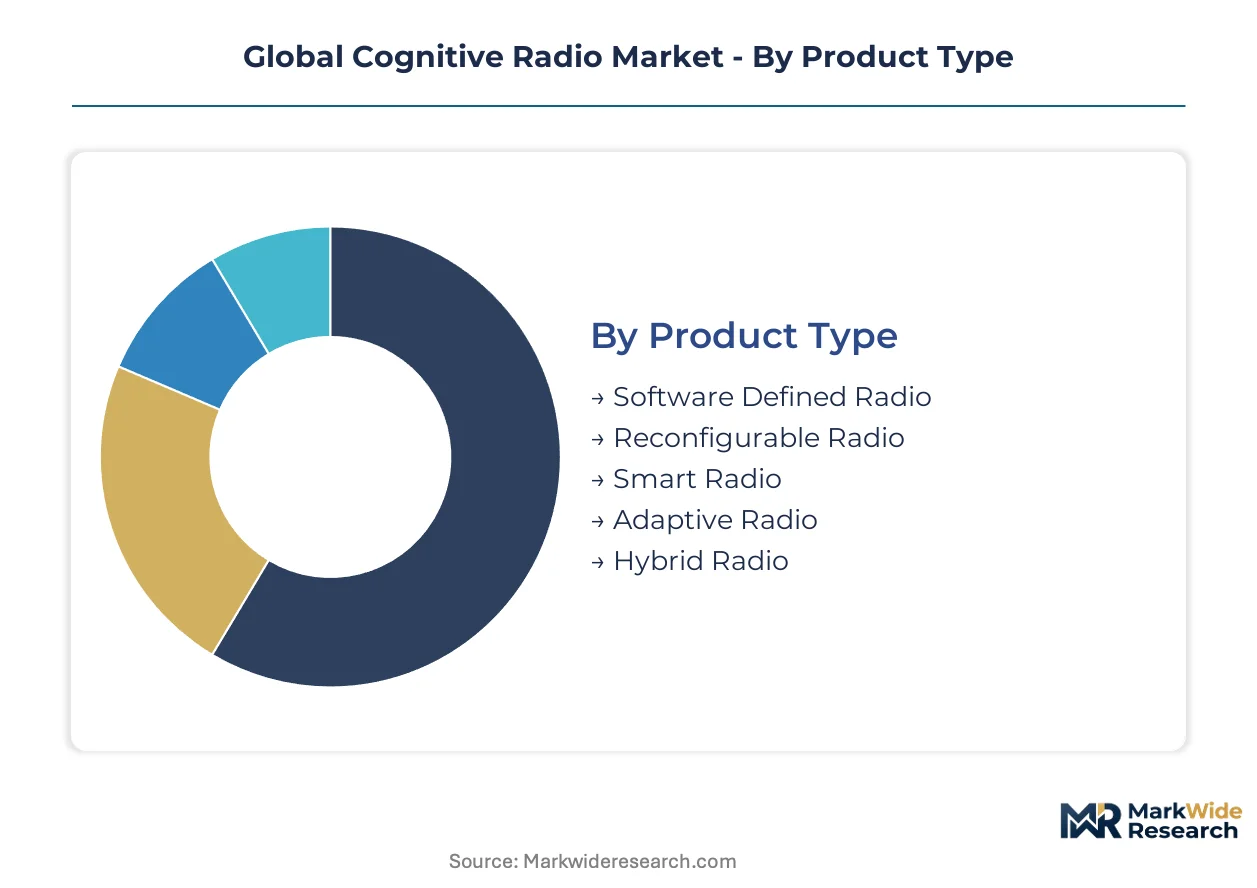
Cognitive radio architectures vary dramatically across deployment contexts, from hardened military transceivers to commercial cellular infrastructure. Segment boundaries reflect fundamental trade-offs between hardware flexibility, algorithmic sophistication, and regulatory compliance requirements.
Product Type:
Software Defined Radio commands volume leadership through programmable baseband economics, while Reconfigurable Radio captures premium positioning via field-upgradable RF chains.
- Software Defined Radio:Digitizes RF signals at intermediate frequency, enabling waveform reconfiguration through firmware updates rather than hardware swaps. Demand concentrates in US and German defense procurement, where multi-mission platforms must adapt to classified waveform requirements without depot-level modification.
- Reconfigurable Radio:Integrates field-programmable gate arrays with wideband RF front-ends, supporting real-time parameter adjustment across 30 MHz to 6 GHz. South Korean testbeds and UK Ministry of Defence programs drive adoption, prioritizing electromagnetic resilience over unit cost.
- Smart Radio:Embeds policy engines for autonomous spectrum decisions within unlicensed bands.
- Adaptive Radio:Modulates power and modulation schemes in response to link quality feedback.
- Hybrid Radio:Combines legacy narrowband with cognitive wideband modes for interoperability bridging.
Today's leader: Software Defined Radio. Tomorrow's challenger: Reconfigurable Radio.
Technology:
Machine Learning is climbing the fastest as neural networks displace rule-based spectrum sensing, while Spectrum Sensing anchors near-term deployment economics.
- Machine Learning:Convolutional neural networks classify interference signatures in sub-millisecond windows, enabling predictive channel selection before link degradation. South Korean 5G network slicing trials and German automotive testbeds concentrate demand, driven by latency requirements for autonomous coordination.
- Spectrum Sensing:Energy detection and cyclostationary feature extraction identify vacant channels through passive monitoring. FCC CBRS deployments and Indian defense modernization programs sustain procurement volumes despite algorithmic obsolescence pressure.
- Frequency Hopping:Pseudorandom sequence agility for anti-jam communications in contested electromagnetic environments.
- Dynamic Spectrum Access:Database-coordinated secondary use of licensed bands with incumbent protection guarantees.
- Signal Classification:Modulation recognition for electronic warfare and spectrum enforcement applications.
Machine Learning is expanding most quickly. Spectrum Sensing retains installed-base dominance.
Application:
Military Communications concentrates value through classified procurement premiums, while Public Safety widens addressable market through first-responder broadband mandates.
- Military Communications:Encrypted tactical networks requiring cognitive adaptation to jamming and interception threats. NATO-aligned programs in the United States, United Kingdom, and Germany anchor demand, with waveform modernization cycles compressing replacement timelines.
- Public Safety:Interoperable LTE networks for emergency services requiring interference coordination across agency boundaries. US FirstNet deployment and German BDBOS expansion drive procurement, as spectrum scarcity forces shared infrastructure models.
- Wireless Broadband:Enterprise private networks leveraging CBRS and similar frameworks for industrial connectivity.
- Emergency Management:Rapidly deployable communications for disaster response coordination.
- Satellite Communications:Dynamic spectrum sharing between geostationary and non-geostationary constellations.
Military Communications holds revenue concentration. Public Safety is gaining share fastest.
End User:
Defense Agencies sustain premium pricing through mission-critical reliability requirements, while Telecommunication Providers scale volume through infrastructure standardization.
- Defense Agencies:Classified program offices in the US Department of Defense, UK Ministry of Defence, and French DGA procure spectrum-aware systems with multi-decade support obligations. Machine-learning model retraining is now a contracted deliverable rather than post-sale service.
- Telecommunication Providers:Spectrum sharing infrastructure for cellular densification and private network offerings. Verizon, Deutsche Telekom, and SK Telecom testbeds concentrate demand, driven by mid-band refarming economics.
- Government Organizations:Civilian spectrum management and regulatory enforcement applications.
- Network Operators:Neutral host and wholesale infrastructure providers managing shared spectrum resources.
- Research Institutes:Standardization testbeds and algorithm validation for regulatory certification.
Defense Agencies dominate contract value. Telecommunication Providers are scaling deployment volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as vendors relocate certification testing to jurisdictions with streamlined electromagnetic compliance workflows, narrowing the cost gap between FCC Part 90 validation and EU Radio Equipment Directive conformity assessment.
United States
Defense procurement from the Pentagon and spectrum-sharing mandates under FCC CBRS protocols drive transceiver demand. The FCC's dynamic protection zone frameworks require real-time interference management infrastructure. Huntsville, Alabama and Boston's Route 128 corridor host concentrated electronic warfare development clusters where BAE Systems and RTX Corporation operate spectrum-dominance laboratories.
Germany
Franco-German defense integration and automotive 5G testbeds sustain adaptive radio procurement. ETSI harmonized standards under the EU Radio Equipment Directive impose cybersecurity certification prerequisites for CE marking. Munich and Stuttgart industrial zones concentrate Rohde & Schwarz validation facilities alongside Thales Group's adaptive waveform engineering centers.
South Korea
SK Telecom's network slicing trials and military modernization programs accelerate machine-learning-enabled signal processing adoption. The country's spectrum refarming coordination through MIC shapes cognitive radio testbed requirements. Seoul Capital Area and Daejeon-Sejong host concentrated 5G infrastructure development where neural network spectrum sensing achieves sub-millisecond latency targets.
United Kingdom
UK Ministry of Defence program-of-record acquisitions and FirstNet-adjacent public safety broadband expansion sustain demand. Ofcom's shared spectrum licensing frameworks parallel FCC CBRS architecture for enterprise private networks. Bristol and Farnborough defense technology clusters concentrate BAE Systems electronic warfare integration facilities with adjacent satellite communications development.
India
Indigenous defense electronics procurement under BIS telecommunications equipment standards creates entry pathways for spectrum-aware systems. The country's military electronics modernization accelerates through production-linked incentive schemes. Bengaluru and Hyderabad host concentrated RF engineering talent pools where vendors establish compliance laboratories for dual-use civilian-military certification.
Global Cognitive Radio Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense primes capturing premium program-of-record contracts while commercial infrastructure vendors scale through standardized hardware platforms. The vendor base concentrates among electromagnetic spectrum operations integrators with multi-decade government relationships, supplemented by niche algorithm developers serving 5G testbed applications. Three archetypes dominate: legacy electronic warfare houses with classified waveform heritage, software-defined radio platform specialists, and machine-learning inference chip integrators. Consolidation through multi-year platform contracts and continuous algorithmic performance requirements as contracted deliverables represent the dominant competitive vectors.
Within the defense prime tier, BAE Systems, Thales Group, and RTX Corporation exemplify spectrum-dominance solution providers with established NATO-aligned military relationships. BAE Systems occupies a position reflecting UK Ministry of Defence electronic warfare heritage. Thales Group represents Franco-German defense integration capabilities. RTX Corporation anchors US Department of Defense ecosystem participation. These three entities collectively illustrate how classified procurement requirements concentrate contract value among vendors with multi-jurisdictional certification capabilities and machine-learning model retraining infrastructure.
| Leading Market Players |
|---|
| BAE Systems |
| Thales Group |
| RTX Corporation |
| Rohde & Schwarz |
| L3Harris Technologies |
| Shared Spectrum |
| EpiSys Science |
| DataSoft Corporation |
| General Dynamics |
| Others |
Supply & Pricing Matrix
Defense procurement offices consolidating around multi-year platform contracts are squeezing supplier margins while demanding continuous algorithmic performance improvements, forcing vendors to absorb retraining costs or forfeit program-of-record eligibility. This buyer-driven compression cascades through Gallium Nitride substrate sourcing and RF engineering talent acquisition, reshaping where value accumulates across the cognitive radio value chain.
Pricing Analysis
Distributor margins for commercial-grade software-defined radio platforms compress under direct-to-OEM contracting favored by US and German defense agencies. Three-tier pricing structure across MIL-SPEC certified, industrial-grade, and commercial-off-the-shelf levels separates mission-critical reliability premiums from testbed economy units. Cost compression in the commercial tier intensifies because neural network inference chips commoditize faster than anticipated. Telecommunication providers exhibit highest price sensitivity due to infrastructure scale procurement, while defense agencies prioritize performance guarantees over unit economics.
Supply Chain Analysis
RF engineering talent scarcity in Huntsville, Alabama and Bengaluru constrains vendor scaling for commercial market entry, forcing reliance on defense contractor skill concentrations. Manufacturing draws from the United States, Germany, and South Korea for final assembly, with Taiwan and Japan feeding specialized semiconductor foundry capacity. Gallium Nitride substrates and rare earth processing create single-source vulnerability concentrated in Chinese supply chains. Distribution runs through defense prime direct contracting for military applications and systems integrator channels for enterprise private networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cognitive radio hinges on algorithmic differentiation commanding premium pricing tiers, as hardware commoditization shifts value capture toward machine-learning model performance and continuous retraining service contracts.
For Market Incumbents: Hedge against neural network inference chip commoditization by deepening proprietary dataset advantages for spectrum sensing algorithms. Lock in multi-year platform contracts with UK Ministry of Defence and US Department of Defense program offices before emerging chip integrators achieve certification. Prioritize backward integration into Gallium Nitride substrate sourcing to dampen input cost volatility from concentrated rare earth processing. For New Entrants and Emerging Players: Cloud-native spectrum management platforms offer the lowest customer acquisition cost entry vector for mid-market enterprise private networks in India and Southeast Asia. Public safety broadband convergence in US FirstNet-adjacent deployments presents the most penetrable white-space, given incumbent defense primes' limited civilian channel presence. Pursue partnership-first go-to-market positioning with systems integrators rather than direct certification investment. For Investors and Strategic Acquirers: Asymmetric upside sits with neuromorphic computing chip developers possessing analog RF front-end integration capabilities, given the sub-microsecond latency requirements driving next-generation electronic warfare procurement. Long-term viability favors vendors with dual-use civilian-military certification infrastructure spanning FCC Part 90 and EU Radio Equipment Directive frameworks. Monitor ETSI cybersecurity certification enforcement timelines as inflection indicator for European infrastructure vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Machine-Learning Model Retraining Infrastructure | Defense primes now contract algorithmic performance improvements as deliverables rather than post-sale services. |
| Neuromorphic-RF Convergence Development | BAE Systems and Thales Group pilot merged hardware-software stacks for sub-microsecond spectrum sensing. |
| Multi-Jurisdictional Certification Investment | Vendors maintaining parallel FCC Part 90 and EU Radio Equipment Directive workflows capture NATO-aligned procurement. |
| Gallium Nitride Supply Diversification | Backward integration into substrate sourcing mitigates cost volatility from Chinese rare earth processing concentration. |
| Public Safety Channel Partnership | FirstNet-adjacent broadband expansion opens civilian procurement channel adjacent to defense-centric portfolios. |
Research Methodology
Bottom-up defense procurement and telecommunications infrastructure modeling reconciled against top-down spectrum equipment production tracking forms the analytical core of this study. Primary interviews with program office procurement leads, RF engineering directors at defense primes, cellular network planning executives, and regulatory certification specialists combined with secondary validation from FCC equipment authorization databases, ETSI harmonized standards filings, and EU Radio Equipment Directive conformity assessment records. Bottom-up and top-down triangulation cross-validates vendor shipment data against national spectrum auction timelines and defense modernization budget allocations.
Historical trendline analysis of software-defined radio procurement cycles and machine-learning integration adoption curves informs projection methodology. Segmentation dimensions modeled include product architecture, technology layer, application vertical, and end-user procurement authority across the analysis window. CAGRs derive from regression analysis of defense electronics spending patterns and commercial spectrum-sharing infrastructure deployment rates. Neural network inference chip cost curves and Gallium Nitride substrate pricing volatility constitute key industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for neuromorphic computing architectures would alter the outlook if analog RF front-end integration achieves production scale faster than projected. Forecasts reflect assumptions regarding FCC CBRS framework expansion continuity and EU cybersecurity certification enforcement timelines. Material deviation in NATO defense procurement consolidation patterns or mid-band spectrum auction schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Fixed LTE Market
Telecommunications
Indonesia Telecom Towers Market
Telecommunications
Myanmar ICT Market
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
South Africa Telecom Market
Telecommunications
IP DECT Phones Market
Telecommunications
TD-LTE Ecosystem Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Esim Subscription Market
Telecommunications
GPON Equipment Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Mftpaas Market
Telecommunications
Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market
Telecommunications
IP PBX Market
Telecommunications
Global Small Cell 5G Network Market
Telecommunications
Indonesia Volte Market