
 Argentina ICT Market | 2026-2036
Argentina ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina ICT Market Outlook
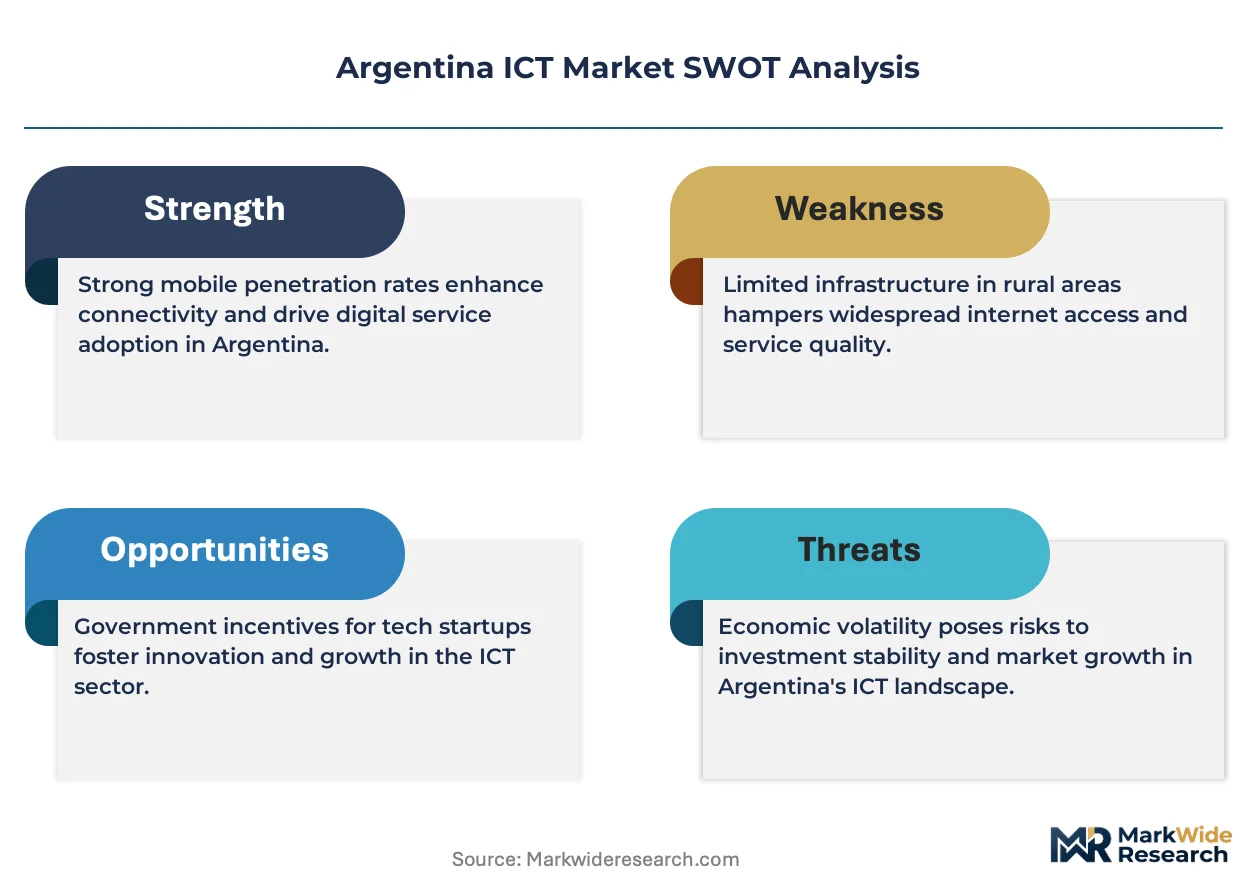
Cloud platform licensing is rewriting margin distribution across the Argentina ICT landscape, pulling profitability from hardware resale toward recurring software subscriptions. Telecom Argentina leverages its fiber backbone to dominate enterprise connectivity in Buenos Aires and Córdoba. Oracle anchors its position through database and ERP installations at large Argentine corporations and public-sector agencies. Microsoft competes aggressively on productivity suites and Azure infrastructure services, extending its reach into mid-market enterprises previously served by local systems integrators.
Information and communications technology in Argentina encompasses computing hardware, telecommunications infrastructure, software applications, and digital services that enable data processing, storage, transmission, and retrieval across enterprise and consumer environments. The sector relies on fiber-optic backbones, 4G/5G radio access networks, server virtualization, and API-based software architectures to deliver operational capabilities to end users. Software and cloud computing segments command expanding margin pools as Argentine enterprises shift capital expenditure toward operational expenditure models. Hardware retains structural importance in data center buildouts and endpoint refresh cycles, though growth velocity lags services. Government agencies and large corporations represent the most concentrated demand nodes, with educational institutions emerging as a faster-growing end-user category under federal digital inclusion programs.
ENACOM, Argentina's national communications regulator, shapes market access through spectrum auctions, interconnection mandates, and infrastructure-sharing requirements that directly affect carrier economics and service pricing. The Argentine Central Bank's cybersecurity protocols for financial institutions, combined with personal data protection frameworks aligned with regional standards, elevate compliance costs while creating specialized demand for security services and audit consulting. Stakeholders must monitor regulatory rulings on cross-border data flows and cloud localization requirements, as these determinations will reshape vendor selection criteria and infrastructure deployment timelines for multinational providers serving Argentine clients.
Market Dynamics
Cloud migration is compressing traditional hardware margins while redistributing value toward recurring software subscriptions and managed services across Argentine enterprises.
Growth Catalysts
- ENACOM spectrum modernization:The national communications regulator's 5G frequency reallocation is accelerating radio access network investments by mobile carriers.
- Financial sector compliance mandates:Argentine Central Bank cybersecurity protocols for banks and fintech platforms are generating specialized demand for security consulting and audit services.
- Greater Buenos Aires data center clustering:Enterprise IT spending concentrates in the capital region, creating infrastructure density that attracts hyperscale cloud providers.
Market Restraints
- Import dependency for server hardware:Argentina's foreign exchange controls create procurement delays and cost volatility for data center equipment sourced from abroad.
- Skilled DevOps talent scarcity:The domestic labor market lacks sufficient certified cloud architects and cybersecurity specialists to meet enterprise demand.
- Legacy ERP integration friction:Large Argentine corporations face technical debt burdens when migrating from on-premise Oracle installations to cloud-native alternatives.
Strategic Opportunities
- Interior provincial connectivity gaps:Mendoza, Rosario, and Tucumán present underpenetrated markets for fiber-to-the-business services and edge computing nodes.
- Public-sector digital inclusion programs:Federal education technology initiatives are expanding hardware and software procurement from primary through tertiary institutions.
- API-based banking convergence:Open banking regulations are creating integration opportunities between fintech platforms and traditional financial infrastructure.
Industry Challenges
- Cross-border data localization uncertainty:Pending ENACOM rulings on cloud data residency requirements are delaying multinational vendor commitment timelines.
- Certification timeline compression:Personal data protection compliance aligned with regional standards demands specialized legal-technical coordination that outpaces available consulting capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina ICT Market |
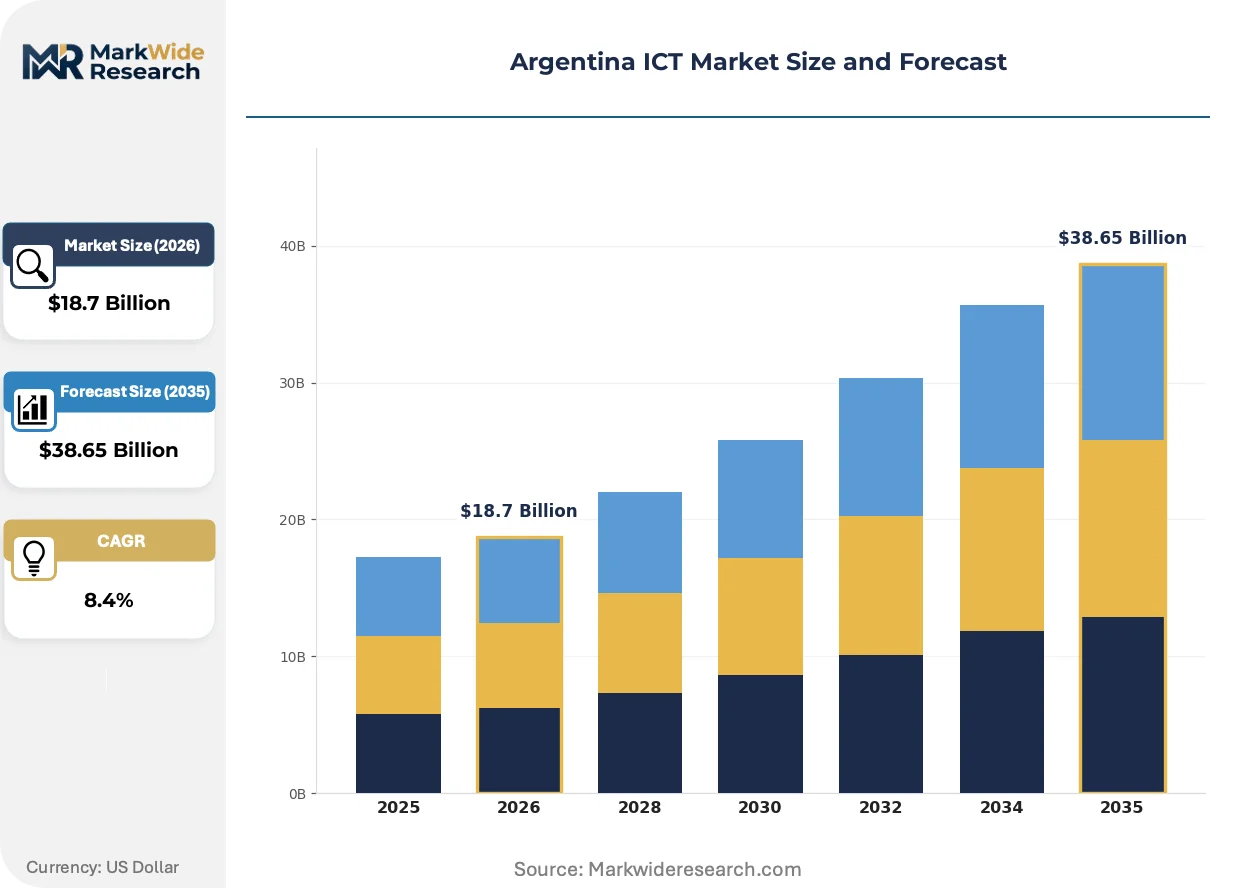
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Infrastructure End User: Small Enterprises, Large Corporations, Government Agencies, Educational Institutions Technology: Cloud Computing, Cybersecurity, AI Solutions, Networking Service Type: Consulting, Managed Services, System Integration, Support Services |
| Companies Covered | Alphabet (Google), Telecom Argentina, America Movil, Oracle, Telefonica De Argentina (Movistar), Globant, IBM, SAP, Microsoft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina ICT Market Strategic Shifts
Hybrid cloud architectures are displacing binary on-premise versus public cloud decisions, forcing infrastructure vendors to reposition around workload portability and interoperability.
Software-defined wide area networking is hybridizing branch office connectivity across Argentine retail and logistics chains. Mid-market enterprises previously dependent on MPLS circuits from Telecom Argentina are adopting SD-WAN overlays to aggregate multiple access technologies. This convergence is compressing router hardware refresh cycles while expanding managed service attach rates.
ENACOM's infrastructure-sharing mandates are reshaping carrier economics by requiring dominant operators to open fiber ducts and tower assets to competitors. Mobile network operators must now negotiate commercial terms for passive infrastructure access rather than building parallel facilities. The regulatory friction falls heaviest on 5G densification projects in Córdoba and Buenos Aires metropolitan zones.
Subscription-based software procurement is displacing perpetual license purchases among Argentine professional services firms and healthcare providers. Finance departments favor operational expenditure treatment for productivity suites and collaboration tools. The behavioral shift is most pronounced in Greater Buenos Aires, where mid-market enterprises previously served by local systems integrators now contract directly with cloud vendors.
Argentina ICT Market Segmentation
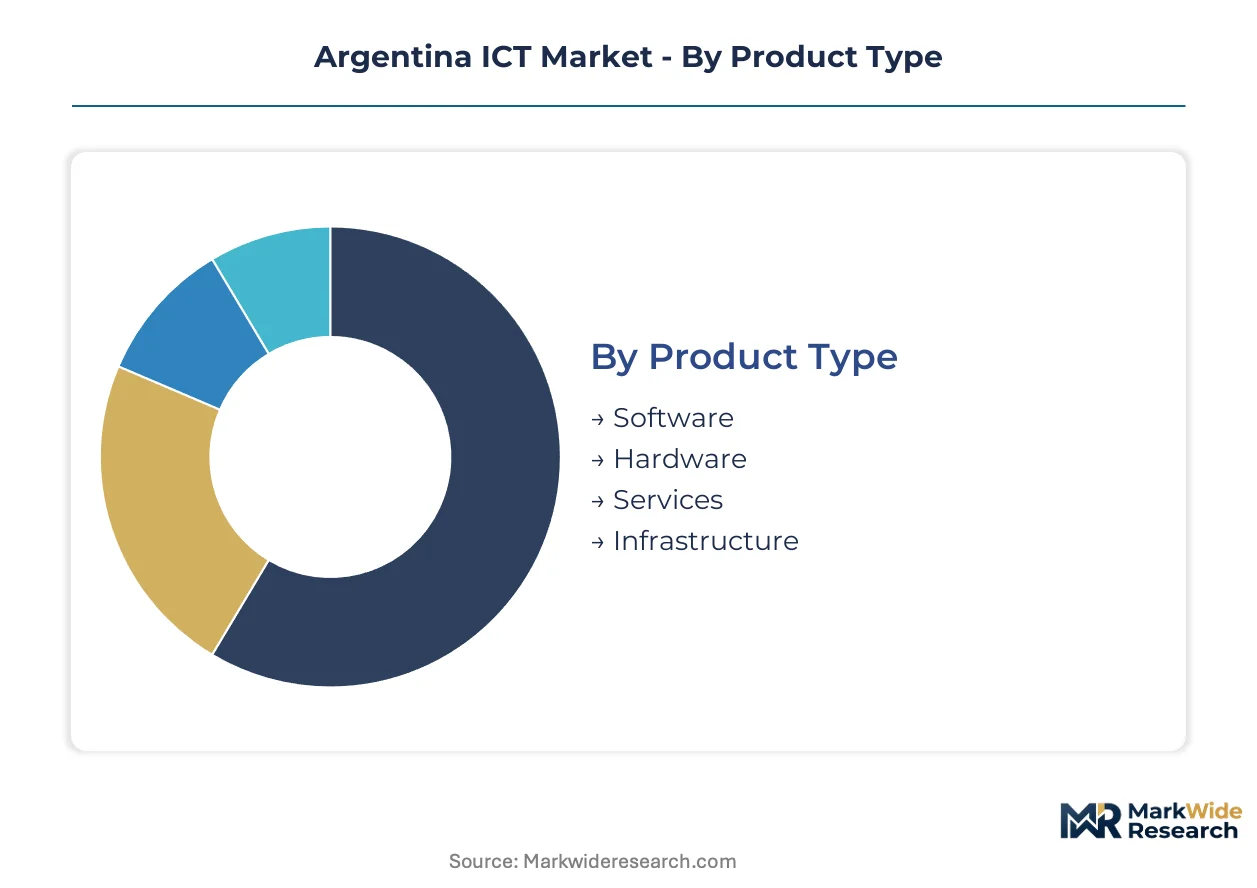
Segmentation in Argentina's ICT market reveals distinct procurement patterns across enterprise maturity levels and regulatory exposure. Technology choices diverge sharply between capital-intensive public-sector deployments and agile fintech implementations.
Product Type:
Software and infrastructure command premium margins as Argentine enterprises shift from capital expenditure to operational expenditure models, while hardware retains structural importance in data center buildouts.
- Software:Cloud-native applications and subscription-based productivity suites dominate procurement in Greater Buenos Aires. Argentine banks and professional services firms favor recurring license models that align with Central Bank cybersecurity compliance budgets.
- Hardware:Server virtualization equipment and endpoint devices face procurement delays from foreign exchange controls. Data center operators in Buenos Aires and Córdoba absorb cost volatility to maintain infrastructure refresh cycles.
- Services:Managed service contracts expand as mid-market enterprises outsource IT operations.
- Infrastructure:Fiber-optic backbones and 5G radio access networks attract carrier investment under ENACOM spectrum modernization mandates.
The dominant share belongs to Software, while Infrastructure is closing the gap fastest.
End User:
Customer type determines solution complexity and sales cycle duration across Argentine ICT procurement.
- Large Corporations:ERP migrations and hybrid cloud architectures drive enterprise-wide transformation programs. These organizations face technical debt burdens when integrating legacy Oracle installations with modern platforms.
- Government Agencies:Federal digital inclusion programs and public-sector cybersecurity protocols create concentrated demand nodes. ENACOM infrastructure-sharing requirements shape vendor selection for national connectivity projects.
- Small Enterprises:SD-WAN overlays and software-defined connectivity replace traditional MPLS circuits.
- Educational Institutions:Federal education technology initiatives accelerate hardware and software procurement from primary through tertiary levels.
Large Corporations anchor current revenue concentration, though Educational Institutions are expanding most quickly.
Technology:
Technology selection reflects risk tolerance and regulatory pressure intensity across Argentine verticals.
- Cloud Computing:Hybrid architectures displace binary on-premise versus public cloud decisions. Workload portability requirements force infrastructure vendors to reposition around interoperability standards.
- Cybersecurity:Argentine Central Bank protocols for financial institutions generate specialized demand for audit consulting and security architecture services. Compliance costs elevate procurement budgets across banking and fintech platforms.
- AI Solutions:Predictive analytics applications emerge in logistics and agricultural technology sectors.
- Networking:Software-defined wide area networking hybridizes branch office connectivity across retail and logistics chains.
Cloud Computing maintains the largest installed base, while Cybersecurity shows the steepest expansion trajectory.
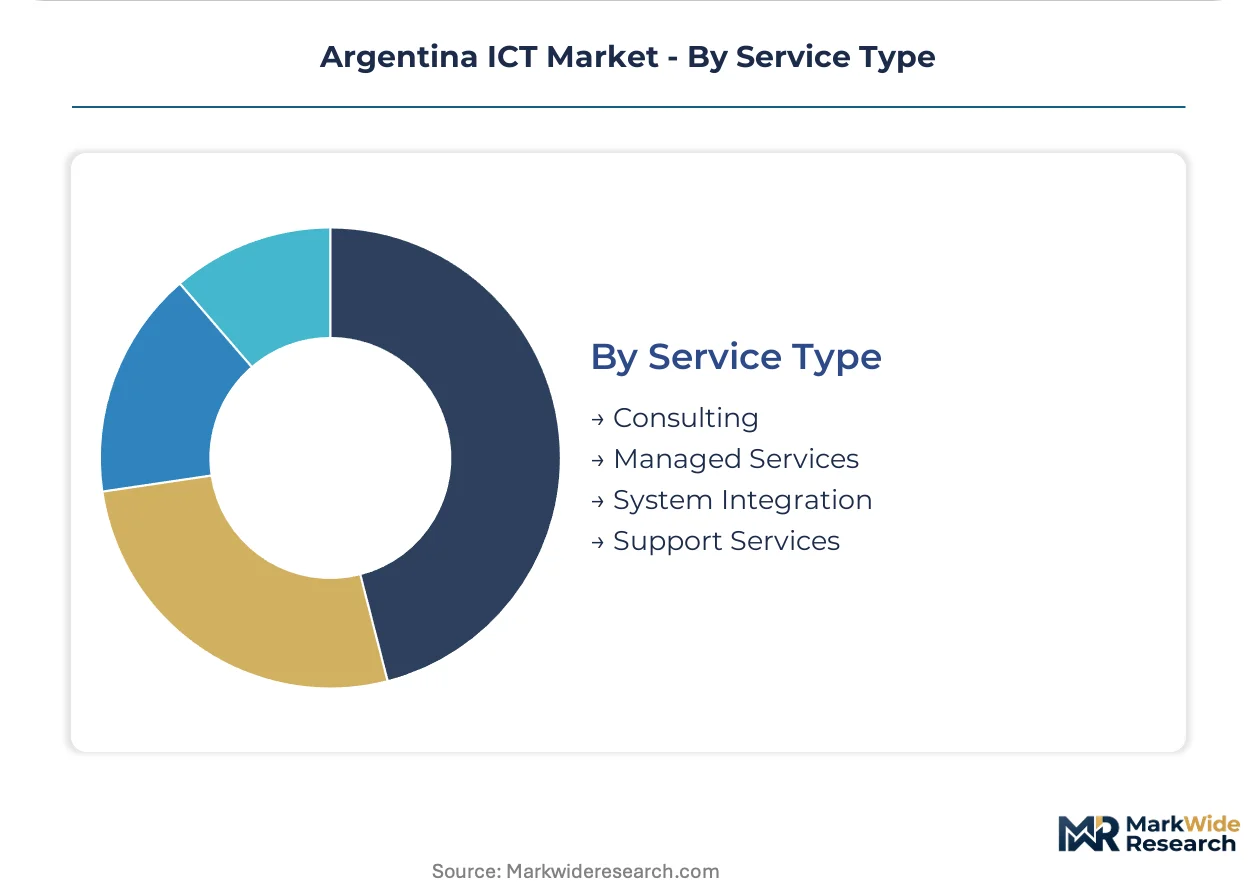
Service Type:
Service delivery models stratify by client technical sophistication and in-house capability gaps.
- Managed Services:Comprehensive IT outsourcing contracts gain traction as Argentine enterprises confront skilled DevOps talent scarcity. Providers assume operational responsibility for cloud infrastructure and security operations centers.
- Consulting:Regulatory compliance and digital transformation advisory services command premium rates. Personal data protection frameworks aligned with regional standards demand specialized legal-technical coordination.
- System Integration:Legacy ERP integration projects face timeline compression from pending ENACOM rulings on data residency requirements.
- Support Services:Break-fix and maintenance contracts retain importance in hardware-dependent environments.
Managed Services holds the dominant position, while Consulting is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Greater Buenos Aires demonstrate the lowest price elasticity for enterprise software and cloud services, while interior provincial markets remain acutely sensitive to connectivity costs and hardware import volatility. This demand-elasticity gradient shapes vendor investment priorities and go-to-market sequencing across Argentine ICT procurement.
Greater Buenos Aires
Enterprise IT spending concentrates in the capital region, where data center clusters attract hyperscale cloud providers and financial institutions drive cybersecurity compliance budgets. ENACOM's infrastructure-sharing mandates reshape carrier economics in metropolitan Buenos Aires and Córdoba. The Palermo and Vicente López technology corridors host the densest concentrations of fintech development and ERP integration projects.
Córdoba Metropolitan Area
Argentina's second-largest urban center generates sustained demand for fiber-to-the-business services and software-defined networking solutions. Provincial government digital inclusion programs expand hardware procurement for educational institutions. The Córdoba Technology Park anchors regional systems integration capacity and mid-market enterprise cloud migrations.
Mendoza
Western Argentina's wine and agricultural technology sectors drive specialized demand for IoT connectivity and predictive analytics platforms. ENACOM spectrum reallocation enables mobile carrier 5G densification projects in the metropolitan zone. The Mendoza City industrial corridor remains underpenetrated for enterprise-grade cloud infrastructure relative to coastal markets.
Rosario
Santa Fe Province's logistics and commodity trading hub generates distinctive demand for API-based banking integration and supply chain software. The Rosario Board of Trade's technology requirements influence regional cybersecurity procurement standards. The city's port district clustering supports edge computing deployments for agricultural commodity tracking.
Tucumán
Northwestern Argentina's smallest major metro presents the most acute connectivity infrastructure gaps and lowest current cloud penetration. Federal education technology initiatives accelerate primary and secondary school hardware procurement. The San Miguel de Tucumán urban core lacks redundant fiber paths, creating opportunity for wireless backhaul and satellite hybrid solutions.
Argentina ICT Market Competitive Environment
Capability concentration sits with multinational platform providers; scale advantage sits with domestic telecommunications incumbents. The Argentine ICT market structures around three tiers: hyperscale cloud operators with global R&D footprints, regional carrier groups with captive infrastructure assets, and local systems integrators with vertical specialization. Competitive dynamics center on strategic partnerships between global software vendors and domestic connectivity providers, plus portfolio diversification into adjacent cybersecurity and managed services.
Among global platform operators, Alphabet, Microsoft, and Oracle exemplify the capability-intensive archetype, anchoring enterprise cloud and productivity software procurement in Greater Buenos Aires. Telecom Argentina and Telefonica De Argentina occupy the infrastructure-integrated tier, leveraging fiber backbone ownership to bundle connectivity with managed service offerings. The specialist integration segment includes Globant, whose Buenos Aires-origin structure reflects the regional systems integration model serving mid-market enterprises and public-sector agencies.
| Leading Market Players |
|---|
| Alphabet (Google) |
| Telecom Argentina |
| America Movil |
| Oracle |
| Telefonica De Argentina (Movistar) |
| Globant |
| IBM |
| SAP |
| Microsoft |
| Others |
Value Chain & Pricing Dynamics
The Buenos Aires-Rosario freight corridor absorbs elevated logistics costs from foreign exchange volatility, concentrating procurement power among data center operators with dollar-denominated revenue streams while pushing mid-market enterprises toward subscription-based software models that bypass hardware import exposure.
Pricing Analysis
Long-term managed service contracts dominate enterprise procurement, compressing spot-market hardware transactions to emergency replacement scenarios. Three-tier pricing structure across premium, standard, and economy levels separates hyperscale cloud deployments from mid-market SaaS bundles and basic connectivity packages. Cost compression in server hardware intensifies because import dependency amplifies peso depreciation effects. Large corporations anchored in Buenos Aires demonstrate lowest price elasticity, while interior provincial small enterprises face acute sensitivity to connectivity cost fluctuations.
Supply Chain Analysis
Extended payment terms from 90 to 180 days now characterize supplier relationships with Argentine systems integrators, reflecting working capital constraints from central bank foreign exchange rationing. Server hardware draws from China, the United States, and Brazil; fiber-optic cable rests on Chinese and European inputs; specialized cooling equipment hinges on German and Japanese suppliers. Single-source vulnerability concentrates in enterprise storage arrays from dominant multinational vendors. Distribution runs through Telecom Argentina and Telefonica De Argentina's captive infrastructure networks, with regional systems integrators serving as secondary fulfillment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's ICT market sits in cyclical recovery from foreign exchange crisis compression, with ENACOM's spectrum modernization and Central Bank compliance mandates providing the demand floor for sustained expansion.
For Market Incumbents: Entrench fiber backbone ownership through accelerated duct deployment in Córdoba and Mendoza metropolitan zones before infrastructure-sharing mandates erode exclusivity. Deepen managed service attach rates to offset hardware margin compression from import cost volatility. Prioritize certification investments in Central Bank cybersecurity audit capabilities to capture compliance-driven consulting demand.
For New Entrants and Emerging Players: Build out edge computing nodes in Rosario and Tucumán where hyperscale cloud penetration remains underdeveloped and fiber redundancy gaps create wireless backhaul opportunities. Target educational institutions under federal digital inclusion programs as the most penetrable procurement channel with standardized tender specifications. Pursue API-based banking integration partnerships as the go-to-market angle for fintech infrastructure entry.
For Investors and Strategic Acquirers: ENACOM's pending data localization rulings reshape the acquisition landscape by elevating domestic infrastructure assets above regional platform plays in valuation premiums. Frame five-to-ten year viability around recurring revenue conversion rates rather than hardware shipment volumes. Target regional systems integrators with vertical specialization in financial services or public sector as the preferred acquisition archetype. Monitor ENACOM cloud data residency determinations as the critical inflection signal for multinational vendor commitment timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership | Hyperscale cloud providers partner with Telecom Argentina to leverage fiber backbone access in Buenos Aires. |
| Acquisition of Specialist Firm | Platform vendors acquire local cybersecurity consultancies to satisfy Central Bank compliance service demand. |
| Geographic Expansion | Data center operators establish edge nodes in Mendoza and Tucumán to capture interior provincial latency requirements. |
| Platform Integration | Fintech platforms integrate legacy Oracle ERP installations through API middleware to accelerate cloud migration timelines. |
| Product Launch | SD-WAN vendors introduce multi-access overlay solutions targeting mid-market enterprises replacing MPLS circuits. |
Study Parameters
Cross-validation between primary interviews with CTOs, IT procurement officers, platform engineers, and ENACOM regulatory affairs specialists anchors the qualitative findings against secondary validation from SEC filings of listed carriers, hyperscaler capex disclosures, and ENACOM spectrum auction documentation. Bottom-up demand modeling from enterprise installation records triangulates with top-down market sizing from trade flow analysis across the analysis window.
Calibration against historical subscription conversion rates and infrastructure deployment timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derive from trend extrapolation of software-as-a-service penetration and data center capacity expansion, with foreign exchange volatility and regulatory ruling timelines as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud entrants or unexpected ENACOM infrastructure-sharing enforcement would shift outcomes. Macroeconomic stabilization, accelerated spectrum allocation, or data localization mandate clarity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Egypt Telecom Tower Market
Telecommunications
IP PBX Market
Telecommunications
Brazil Telecom Market
Telecommunications
Nigeria Telecom Market
Telecommunications
Global Roaming Tariff Market
Telecommunications
Africa Roaming Tariff Market
Telecommunications
Thailand Telecom Market
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
Colombia Telecom Market
Telecommunications
Rich Communication Services (RCS) Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
Angola Telecom Market
Telecommunications
Mobile Fronthaul and Backhaul Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
5G Equipment Market