
 Malaysia Telecom Market | 2026-2036
Malaysia Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Telecom Market Outlook
Market Context
Malaysian mobile infrastructure is hardening around shared 5G access obligations. CelcomDigi Berhad leverages its merged spectrum position to sustain nationwide coverage depth. Maxis Berhad anchors premium enterprise contracts through fiber backhaul integration. U Mobile competes on aggressive data pricing for urban youth segments.
Technical Definition and Structural Segments
Malaysia Telecom encompasses the provision of voice, data, and internet services through wireless and wireline infrastructure operating across licensed spectrum and fiber-optic cable networks with throughput thresholds from 100 Mbps residential fiber to 10 Gbps enterprise leased lines, serving consumer connectivity, business productivity, and government digital service delivery. Mobile and broadband service types command the dominant revenue pools as subscriber migration from legacy fixed-line accelerates. 5G and fiber optic technology segments attract capital deployment priority while DSL infrastructure enters managed decline. Residential customer type volume underpins cash flow stability, though large enterprise and government segments yield superior per-account margins.
Regulatory Framework and Outlook
Malaysian Communications and Multimedia Commission licensing frameworks govern spectrum allocation and service obligations, while Digital Nasional Berhad's 5G wholesale model mandates operator-neutral infrastructure access. BIS-equivalent equipment certification and MCMC consumer protection codes shape device approval timelines and pricing transparency requirements. Stakeholders must monitor wholesale access rate negotiations and potential policy pivots on 5G network ownership structure.

Market Dynamics
Digital Nasional Berhad's 5G single wholesale network policy is restructuring competitive access across Malaysian telecom, forcing operators to differentiate through service layers rather than infrastructure ownership while enterprise cloud migration accelerates service uptake among manufacturers and logistics operators.
Growth Catalysts
- Enterprise Cloud Migration:Malaysian manufacturers and logistics operators are accelerating service uptake as they migrate critical workloads to cloud infrastructure, driving demand for high-throughput connectivity.
- Digital Nasional Berhad 5G Wholesale Framework:The single wholesale network policy mandates operator-neutral infrastructure access, reducing duplication costs and accelerating nationwide 5G coverage deployment.
- Klang Valley Demand Concentration:The corridor spanning Kuala Lumpur and Selangor generates disproportionate connectivity demand from financial services, technology firms, and government digital service delivery.
Market Restraints
- Wholesale Access Rate Uncertainty:Ongoing negotiations between Digital Nasional Berhad and mobile network operators create margin pressure and investment planning friction.
- Legacy DSL Infrastructure Decline:Managed decline of copper-based networks requires coordinated subscriber migration investments while maintaining service continuity.
- Spectrum Allocation Constraints:Malaysian Communications and Multimedia Commission licensing frameworks limit available frequency blocks for operator differentiation.
Strategic Opportunities
- Penang and Johor Bahru Expansion:Secondary urban centers outside the Klang Valley corridor remain underpenetrated for enterprise-grade fiber and 5G services.
- Government Digital Service Delivery:National digitalization mandates create captive demand for secure, high-availability connectivity solutions.
- Fixed-Mobile Convergence:Integration of fiber backhaul with 5G access networks enables unified service bundling for residential and small business segments.
Industry Challenges
- 5G Radio Access Network Integration:Mobile network operators face technical complexity integrating shared wholesale infrastructure with existing core networks and billing systems.
- Fiber Backhaul Capex Intensity:Enterprise premium positioning requires continuous densification of fiber-optic cable networks to maintain latency and throughput guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Telecom Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Fixed Line, Broadband, VoIP Technology: 4G, 5G, Fiber Optic, DSL Customer Type: Residential, Small Business, Large Enterprise, Government Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | CelcomDigi Berhad, Maxis Berhad, U Mobile, YTL Communications, Telekom Malaysia, TIME dotCom, Axiata Group Berhad, Unifi Mobile, Yes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Telecom Market Strategic Shifts
Malaysian telecom infrastructure is undergoing fundamental architecture shifts as policy mandates reshape competitive dynamics, enterprise requirements evolve, and operational models adapt to shared network economics.
Network function virtualization is decentralizing core network processing from centralized data centers to distributed edge locations. Enterprise manufacturing and logistics operators are adopting these architectures to support real-time automation and predictive maintenance applications. This technology compression is reducing reliance on legacy hardware appliances while enabling faster service provisioning cycles.
Malaysian Communications and Multimedia Commission consumer protection codes are tightening pricing transparency requirements and service obligation enforcement. The regulatory pressure is compressing operator margin flexibility while accelerating standardization of contract terms. Residential and small business segments are responding through heightened switching activity and demand for simplified tariff structures.
Enterprise procurement of connectivity services is consolidating around outcome-based performance guarantees rather than speed-tier specifications. Large manufacturers and logistics operators are unbundling connectivity from equipment and managed services, creating direct relationships with infrastructure providers. This pattern is most visible in Selangor-based industrial zones where operational technology teams control technology vendor selection.
Malaysia Telecom Market Segmentation
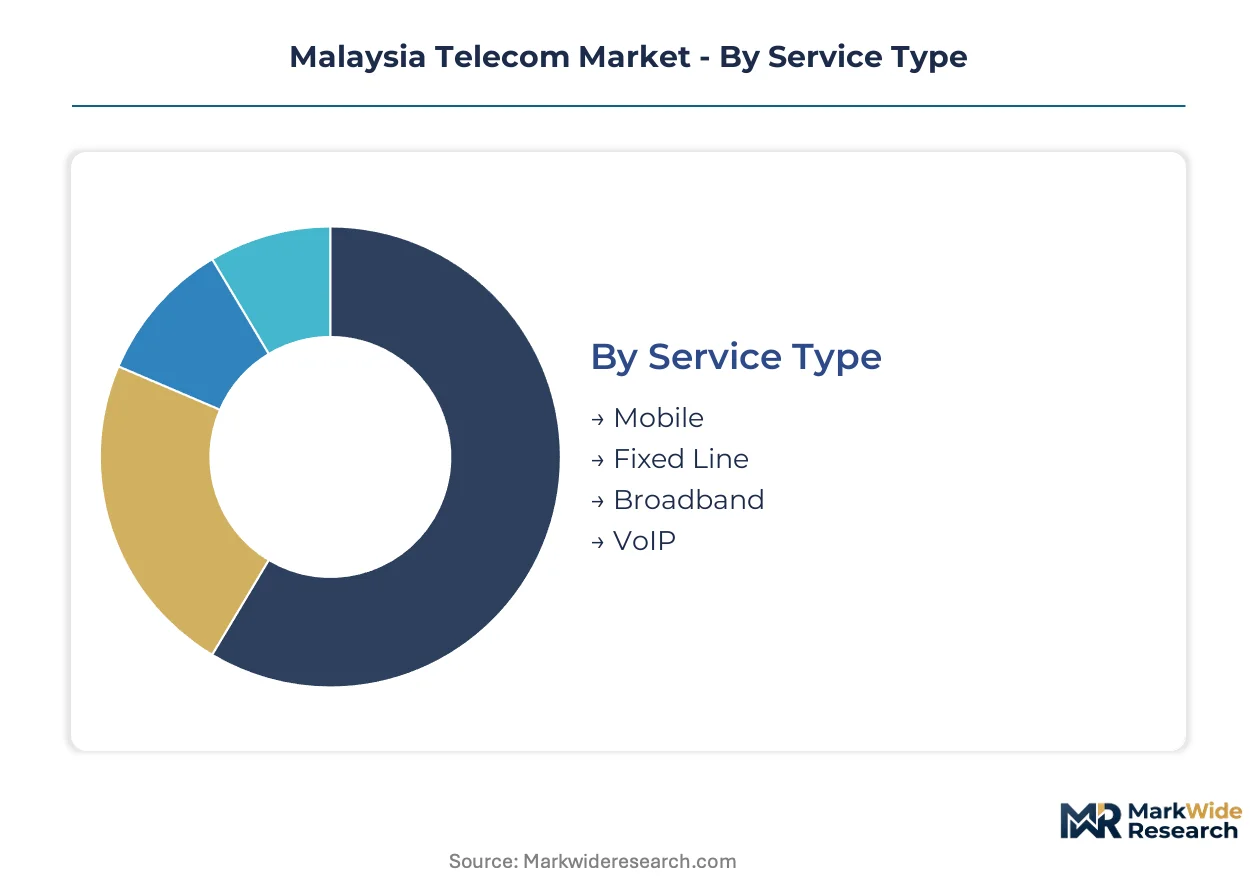
Malaysian telecom operators structure their portfolios across four distinct dimensions that determine capital allocation priorities and margin profiles. Service type and technology segments dictate infrastructure investment cycles, while customer type and deployment model selections shape go-to-market economics and operational complexity.
Service Type:
Standalone connectivity services operate independently of bundled IT infrastructure, while embedded service types integrate with broader enterprise technology stacks.
- Mobile:Wireless voice and data services delivered over licensed spectrum with subscriber identity module authentication. Demand concentrates in the Klang Valley corridor where financial services and technology firms require seamless workforce mobility; Digital Nasional Berhad's wholesale 5G access is compressing operator differentiation to coverage depth and retail pricing.
- Broadband:High-throughput internet access through fiber-to-the-home and fixed wireless architectures. Residential uptake in Selangor and Kuala Lumpur drives volume stability; enterprise-grade symmetrical fiber in Penang and Johor Bahru industrial zones commands premium positioning.
- Fixed Line:Legacy copper-based voice connectivity with declining subscriber bases. Government and rural institutions in East Malaysia maintain residual demand for universal service obligation fulfillment.
- VoIP:Packet-switched voice services riding over IP infrastructure with codec compression. Small business segments in urban centers adopt these for cost arbitrage against traditional circuit-switched alternatives.
Volume placements concentrate in Mobile; the faster expansion belongs to Broadband.
Technology:
Cost tier stratification separates premium performance infrastructure from legacy maintenance obligations and transitional deployments.
- 5G:New radio access technology with massive MIMO and network slicing capabilities enabling sub-10 millisecond latency. Manufacturing automation and logistics optimization in Selangor industrial parks concentrate enterprise demand; Digital Nasional Berhad's single wholesale network mandates operator-neutral access.
- Fiber Optic:Glass-core transmission media delivering symmetrical throughput from 100 Mbps to 10 Gbps. Dense deployment in the Klang Valley supports residential streaming and enterprise cloud migration workloads.
- 4G:LTE-Advanced infrastructure providing fallback coverage and capacity overflow. Nationwide subscriber migration to 5G is compressing capital renewal timelines for this installed base.
- DSL:Copper-pair digital subscriber line technology with asymmetric throughput limitations. Managed decline protocols govern subscriber migration to fiber in urban corridors while maintaining rural service continuity.
Volume placements concentrate in 4G; the steepest expansion trajectory belongs to 5G.
Customer Type:
Margin profiles diverge sharply between mass-market residential subscriptions and high-touch enterprise engagements with customized service level agreements.
- Large Enterprise:Multinational manufacturers and logistics operators with dedicated account teams and bespoke infrastructure. Cloud migration mandates in Penang and Johor Bahru electronics corridors drive demand for redundant fiber paths and guaranteed latency thresholds.
- Government:National digital service delivery mandates requiring secure, high-availability connectivity. Procurement centralization under the Malaysian Communications and Multimedia Commission framework creates captive demand pools.
- Residential:Individual households and family units purchasing standardized speed-tier packages. Price sensitivity in secondary urban centers constrains average revenue per user growth.
- Small Business:Independent retailers and professional services firms with limited IT staff. Fixed-mobile convergence bundles reduce churn through service simplification.
Volume placements concentrate in Residential; the fastest margin expansion belongs to Large Enterprise.
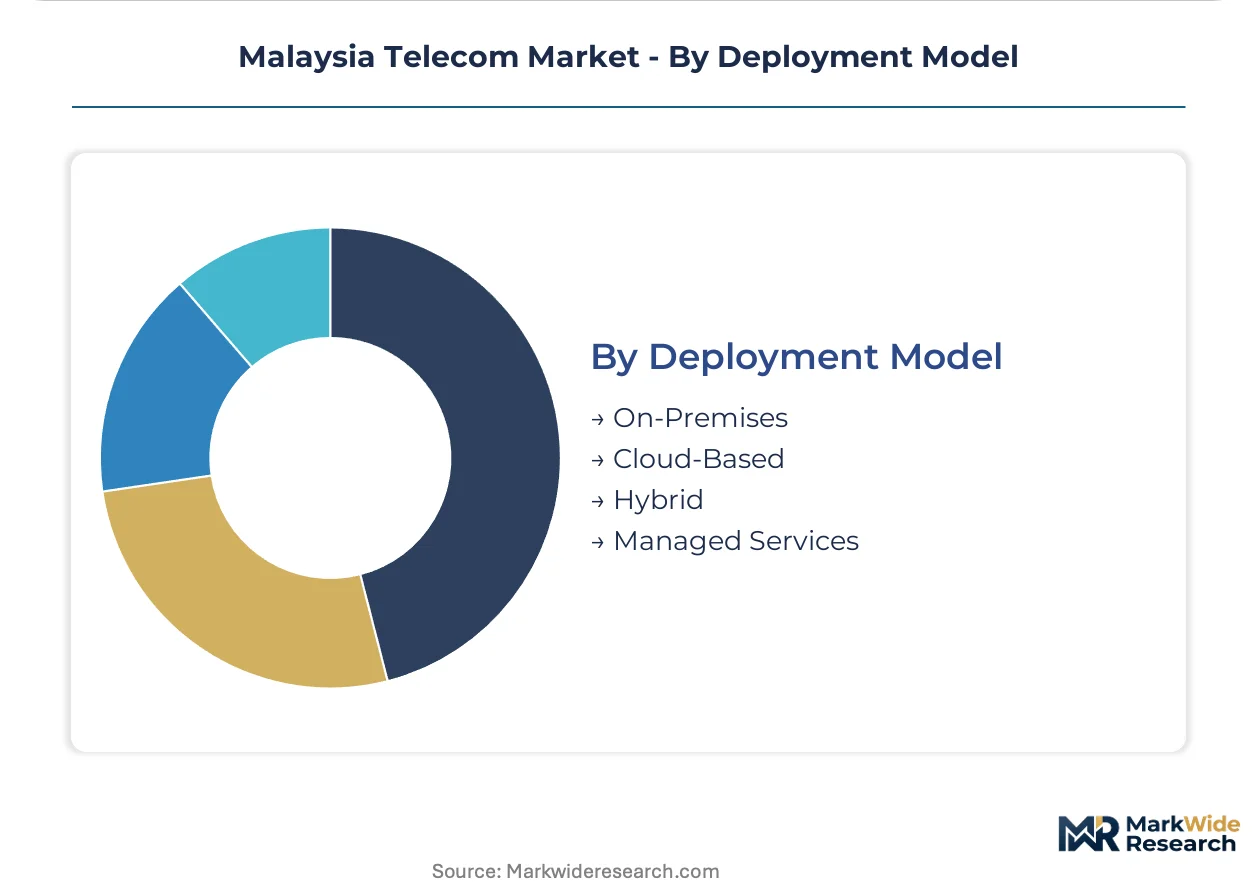
Deployment Model:
Application criticality determines whether customers retain infrastructure control or outsource operational complexity to managed service providers.
- Managed Services:End-to-end network operations outsourced to telecom operators with performance-based contracting. Large manufacturers in Selangor adopt these to redirect IT staff toward core production systems.
- Cloud-Based:Software-defined network functions delivered from hyperscaler or operator edge locations. Real-time automation requirements in logistics and warehousing drive uptake.
- Hybrid:Partitioned architectures combining on-premises control planes with cloud-delivered services. Government agencies favor these for sensitive workload isolation.
- On-Premises:Customer-owned and operated infrastructure with direct equipment procurement. Declining share as operational complexity drives outsourcing preferences.
Volume placements concentrate in On-Premises; the fastest adoption velocity belongs to Managed Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spectrum allocation and fiber deployment patterns concentrate in peninsular Malaysia's industrial corridors. The Malaysian Communications and Multimedia Commission governs licensing across all states.
Selangor
Electronics manufacturing and logistics automation drive enterprise connectivity demand. The Selangor Information Technology and E-Commerce Council promotes digital infrastructure investment. Cyberjaya and Shah Alam host dense fiber backhaul networks serving multinational contract manufacturers.
Kuala Lumpur
Financial services and technology firms require sub-10 millisecond latency for trading platforms. Bank Negara Malaysia's digital banking licensing framework mandates resilient connectivity standards. The city center and KL Eco City cluster fintech operations demanding redundant network paths.
Penang
Semiconductor packaging and testing facilities generate high-throughput data requirements. The Penang Development Corporation coordinates industrial zone fiber deployment. Bayan Lepas Free Industrial Zone anchors cloud migration among precision electronics suppliers.
Johor Bahru
Cross-border logistics and warehousing operations connect to Singapore data centers. Iskandar Malaysia's special economic zone status attracts managed service providers. Pasir Gudang industrial estates adopt edge computing for real-time supply chain visibility.
Sarawak
Universal service obligations sustain satellite and fixed wireless access in rural divisions. The Sarawak Digital Economy Strategy funds last-mile connectivity expansion. Kuching and Miri serve as regional hubs for oil and gas sector communications.
Malaysia Telecom Market Competitive Environment
Global infrastructure vendors compete with regional champions across equipment supply and managed services. The Malaysian operator base consolidated through the CelcomDigi merger while wholesale 5G access under Digital Nasional Berhad neutralizes infrastructure differentiation. Three archetypes dominate: merged spectrum-heavy incumbents, fiber-integrated premium providers, and agile price competitors. Strategic moves center on fixed-mobile convergence bundling and enterprise cloud partnership formations.
Among merged-entity operators, CelcomDigi Berhad occupies the spectrum depth position. Maxis Berhad anchors premium enterprise relationships through fiber backhaul integration. U Mobile exemplifies the urban youth-focused pricing competitor archetype.
| Leading Market Players |
|---|
| CelcomDigi Berhad |
| Maxis Berhad |
| U Mobile |
| YTL Communications |
| Telekom Malaysia |
| TIME dotCom |
| Axiata Group Berhad |
| Unifi Mobile |
| Yes |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed infrastructure financing through Digital Nasional Berhad shapes both supply commitments and retail pricing discipline across Malaysian telecom, as state-directed 5G deployment removes infrastructure duplication costs while compressing operator margin flexibility through mandated wholesale access terms.
Pricing Analysis
Service-bundling configurations separate connectivity-only subscriptions from managed-service packages with performance guarantees. Three-tier pricing structure across premium, standard, and economy levels stratifies residential fiber in Selangor against enterprise-grade symmetrical circuits in Penang industrial zones. Price differentiation rests on latency thresholds and after-sales response commitments. Cost compression in economy tiers intensifies because U Mobile's aggressive data pricing anchors consumer expectations. Small business segments exhibit highest price sensitivity; large enterprise manufacturers with cloud migration mandates show lowest.
Supply Chain Analysis
Domestic-content mandates under Malaysian Communications and Multimedia Commission equipment certification rules reshape sourcing toward BIS-equivalent approved vendors for radio access network gear. Geographic supply concentration centers on China, South Korea, and Finland for massive MIMO antennas, fiber-optic cable, and core network processors. Raw material dependencies span gallium nitride semiconductors, high-purity glass preforms, and lithium-ion backup power systems. Single-source vulnerability runs through specialized 5G chipset suppliers. Distribution runs through direct operator procurement with original equipment manufacturer integration.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysian telecom is becoming a vertical-integration race where fiber backhaul ownership determines enterprise pricing power, as operators without captive infrastructure face margin compression under Digital Nasional Berhad's wholesale 5G regime.
For Market Incumbents: Anchor enterprise retention through exclusive fiber paths into Cyberjaya and Shah Alam manufacturing zones. Deepen upstream control over last-mile conduit rights to defend against TIME dotCom's infrastructure-light overbuild threat. Prioritize certification investment for MCMC-managed service licensing to lock government digital service contracts. For New Entrants and Emerging Players: Capture white-space in Johor Bahru cross-border logistics corridors where Singapore data center connectivity commands premium positioning. Target underpenetrated small business segments in secondary urban centers with fixed-mobile convergence bundles. Lead with cloud-based network function virtualization to bypass heavy radio access network capital requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor fiber-heavy regional operators in Penang and Sarawak where universal service obligation subsidies stabilize cash flows. Long-term viability hinges on infrastructure ownership rather than retail brand value. Watch Digital Nasional Berhad wholesale rate renegotiations as the inflection signal for operator margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Backhaul Densification | Maxis Berhad's enterprise premium positioning depends on sub-10 millisecond latency guarantees to Bank Negara Malaysia-licensed fintechs. |
| Fixed-Mobile Convergence Bundling | CelcomDigi Berhad leverages merged spectrum depth to reduce residential churn through unified billing and service simplification. |
| Edge Computing Partnership | Iskandar Malaysia logistics operators adopt real-time supply chain visibility through distributed cloud infrastructure at Pasir Gudang estates. |
| Managed Services Outsourcing | Selangor manufacturers redirect IT staff toward core production by contracting end-to-end network operations to telecom operators. |
| Wholesale Access Rate Negotiation | Mobile network operator margins hinge on Digital Nasional Berhad pricing reviews affecting nationwide 5G service economics. |
Study Parameters
Document review covered Malaysian Communications and Multimedia Commission licensing records, Digital Nasional Berhad wholesale framework disclosures, and operator financial filings, complemented by interviews with network planning executives at mobile operators, fiber infrastructure procurement leads, enterprise IT directors in Selangor manufacturing zones, and regulatory affairs specialists. Secondary validation drew from MCMC annual reports, Bank Negara Malaysia digital banking licensing documentation, and Penang Development Corporation industrial zone connectivity plans. Bottom-up subscriber and revenue modeling triangulated against top-down market size estimates from infrastructure deployment trajectories.
Historical deployment patterns cross-referenced against panel input from infrastructure vendor sales directors and tower company leasing managers shaped the analytical framework across the analysis window. Segmentation dimensions modeled include service type, technology tier, customer size category, and deployment architecture complexity. CAGRs were derived from subscriber migration curves and enterprise cloud connectivity uptake rates. Forecast inputs incorporated 5G radio access network rollout schedules and fiber-to-the-home penetration assumptions by state.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Digital Nasional Berhad ownership structure policy pivots and wholesale access rate revisions. Forecasts reflect documented assumptions about enterprise cloud migration velocity and residential fiber substitution patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Video Door Phones Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
Global SMB Telecom Voice and Data Services Market
Telecommunications
Denmark Telecom Market
Telecommunications
Rich Communication Services (RCS) Messaging Market
Telecommunications
Denmark ICT Market
Telecommunications
DECT System Market
Telecommunications
Cambodia Telecom Market
Telecommunications
Kenya Telecom Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Cloud PBX Market
Telecommunications
Turkey Telecom Market
Telecommunications
GSM Mobile Phone Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
Ireland Telecom Market
Telecommunications
GPON Equipment Market