
 Satellite Broadband Communication in Public Safety Market | 2026-2036
Satellite Broadband Communication in Public Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Broadband Communication in Public Safety Market Intelligence
Managed maintenance and software-defined bandwidth allocation is realigning how public safety agencies procure satellite connectivity, shifting capital expenditure into operational models. Viasat Inc. leverages its integrated ground-segment architecture to anchor multi-agency contracts across federal and state tiers. Iridium Communications Inc. specializes in L-band resilience for polar and remote terrain where terrestrial infrastructure fails. Hughes Network Systems dominates high-throughput geostationary deployments for urban emergency operations centers.
Satellite broadband communication in public safety denotes a dedicated wide-area network service using geostationary, medium-Earth orbit, or low-Earth orbit constellations to deliver IP-based voice, video, and data streams to first responders when cellular and fiber infrastructure is degraded or destroyed. Systems typically operate in Ku-band, Ka-band, or L-band spectra with terminal sizes ranging from man-portable flyaway units to vehicle-mounted phased arrays, engineered for sub-300ms latency tolerance in command-and-control scenarios. VSAT technology leads installed base across disaster management applications due to proven interoperability with legacy government networks, while LEO-based fixed wireless represents the fastest-expanding segment as agencies validate low-latency performance for real-time surveillance backhaul. Government agencies command the deepest procurement budgets, though fire departments represent a concentrated margin pool where ruggedized terminal requirements justify premium service tiers.
The FCC governs spectrum allocation and FirstNet interoperability certification for U.S. public safety broadband, while the NTIA administers grant programs that condition funding on satellite backup redundancy in state emergency communications plans. ETSI standards in Europe mandate encryption and priority-access protocols that vendors must embed to qualify for cross-border disaster response frameworks. Stakeholders must monitor how LEO constellation density affects regulatory spectrum reallocation proceedings and whether agency procurement shifts from bandwidth leases toward sovereign payload hosting.
Market Dynamics
The migration from legacy geostationary terminals to software-defined multi-orbit networks is compressing procurement cycles and forcing incumbent vendors to restructure service delivery models around operational expenditure frameworks rather than capital equipment sales.
Growth Catalysts
- FirstNet Interoperability Mandates:FCC certification requirements under the FirstNet Authority are compelling state emergency management agencies to procure satellite backup systems that meet stringent public safety broadband standards.
- Polar Terrain Connectivity Gaps:Arctic and high-latitude jurisdictions across Alaska, Canada, and Nordic territories lack reliable terrestrial alternatives, creating captive demand for L-band resilient architectures.
- Software-Defined Networking:Dynamic bandwidth allocation protocols allow fire departments and search-and-rescue units to scale throughput on demand during active incidents without permanent capacity commitments.
Market Restraints
- Terminal Cost Concentration:Phased array antennas and ruggedized man-portable units remain prohibitively expensive for rural county budgets, limiting penetration outside federally subsidized programs.
- Spectrum Licensing Friction:NTIA coordination with commercial satellite operators creates deployment delays for agencies seeking dedicated Ka-band priority access during disasters.
- Terrestrial 5G Substitution:Private 5G networks for urban emergency operations centers threaten to displace geostationary VSAT deployments in metropolitan corridors with fiber backhaul redundancy.
Strategic Opportunities
- LEO Constellation Sovereignty Partnerships:National governments in Australia and the United Kingdom are exploring hosted payload arrangements that reserve orbital capacity for exclusive public safety use during crises.
- Integrated Drone Command Links:Convergence of satellite backhaul with beyond-visual-line-of-sight UAV control systems opens new procurement categories for wildfire management and maritime search operations.
- Grant-Conditioned Redundancy:FEMA preparedness grants now explicitly score applications higher for satellite backup provisions, creating a funding tailwind for vendor qualification.
Industry Challenges
- Multi-Orbit Integration Complexity:Agencies struggle to unify network management across geostationary, medium-Earth orbit, and low-Earth orbit assets into single command interfaces.
- Field Technician Certification Backlogs:Vendor-specific terminal maintenance credentials create staffing bottlenecks when agencies attempt to expand satellite-equipped vehicle fleets rapidly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Broadband Communication in Public Safety Market |
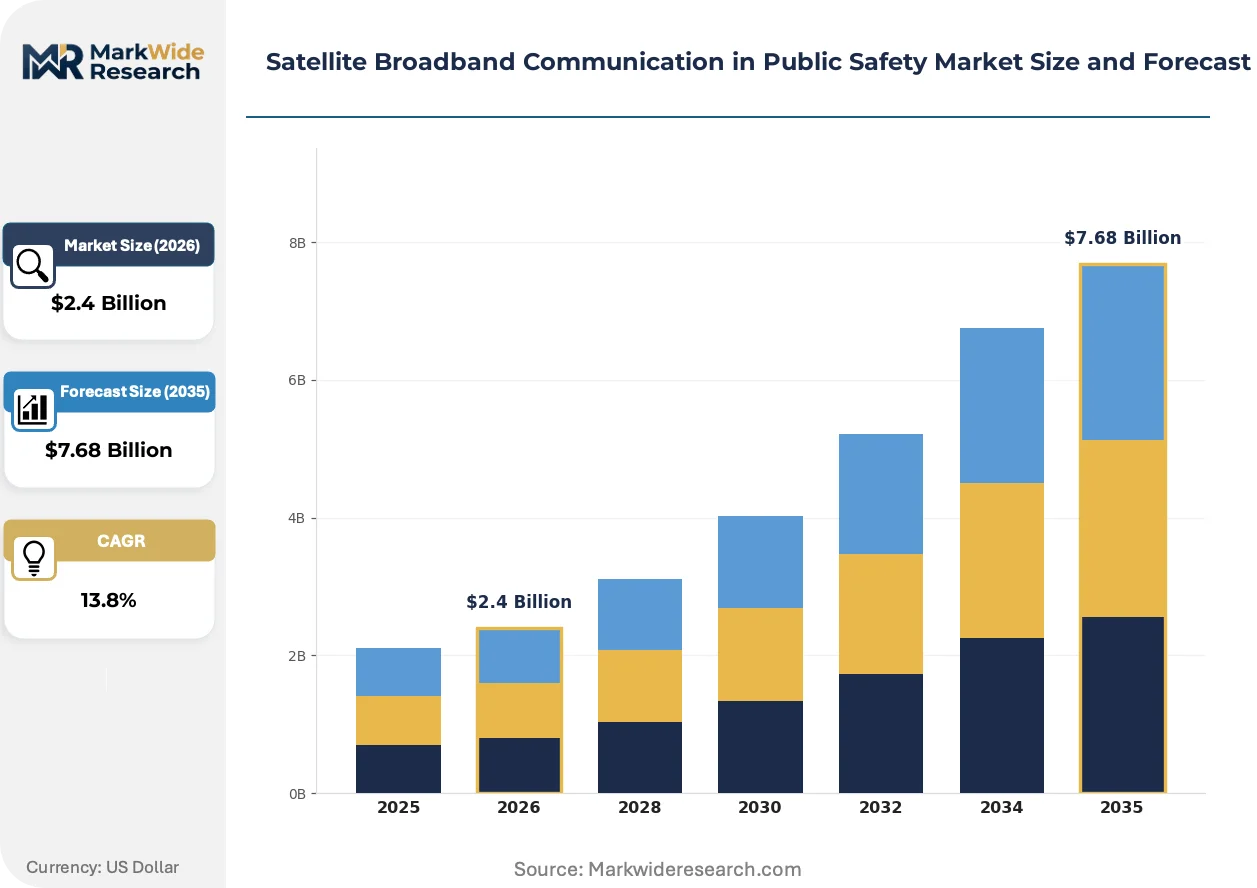
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.68 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: VSAT, Fiber Optics, Microwave, Satellite, Fixed Wireless Application: Disaster Management, Emergency Response, Surveillance, Search and Rescue End User: Fire Departments, Police Services, Emergency Medical Services, Government Agencies Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | Viasat Inc., SES S.A., Inmarsat Limited, Iridium Communications Inc., L3Harris Technologies Inc., Intelsat S.A., Hughes Network Systems, Globalstar Inc., Speedcast International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Broadband Communication in Public Safety Market Strategic Shifts & Innovations
Terminal miniaturization and orbit-agnostic modem architectures are collapsing the traditional trade-off between portability and throughput, enabling new deployment patterns that bypass fixed infrastructure entirely.
Software-defined flat-panel antennas are consolidating multiple frequency bands and orbital regimes into single terminal form factors. State emergency management directors in Texas and Florida are piloting these units for mobile command post deployment. The technology is consolidating vendor relationships by eliminating the need for separate L-band, Ku-band, and Ka-band hardware procurement streams.
ETSI priority-access encryption standards are mandating embedded security modules for cross-border disaster response interoperability. European vendors must certify terminals against these protocols to qualify for pooled procurement frameworks. Border regions in the Alps and Balkans are experiencing accelerated replacement cycles as agencies align with these certification requirements.
Agency buying committees are unbundling hardware ownership from service delivery, favoring bandwidth-as-a-service contracts with guaranteed availability tiers. Municipal fire departments in California and Arizona are leading this transition, replacing capital budgets with operational line items. This pattern is most visible in jurisdictions with volatile annual appropriations that cannot absorb large terminal procurement spikes.
Satellite Broadband Communication in Public Safety Market Segmentation
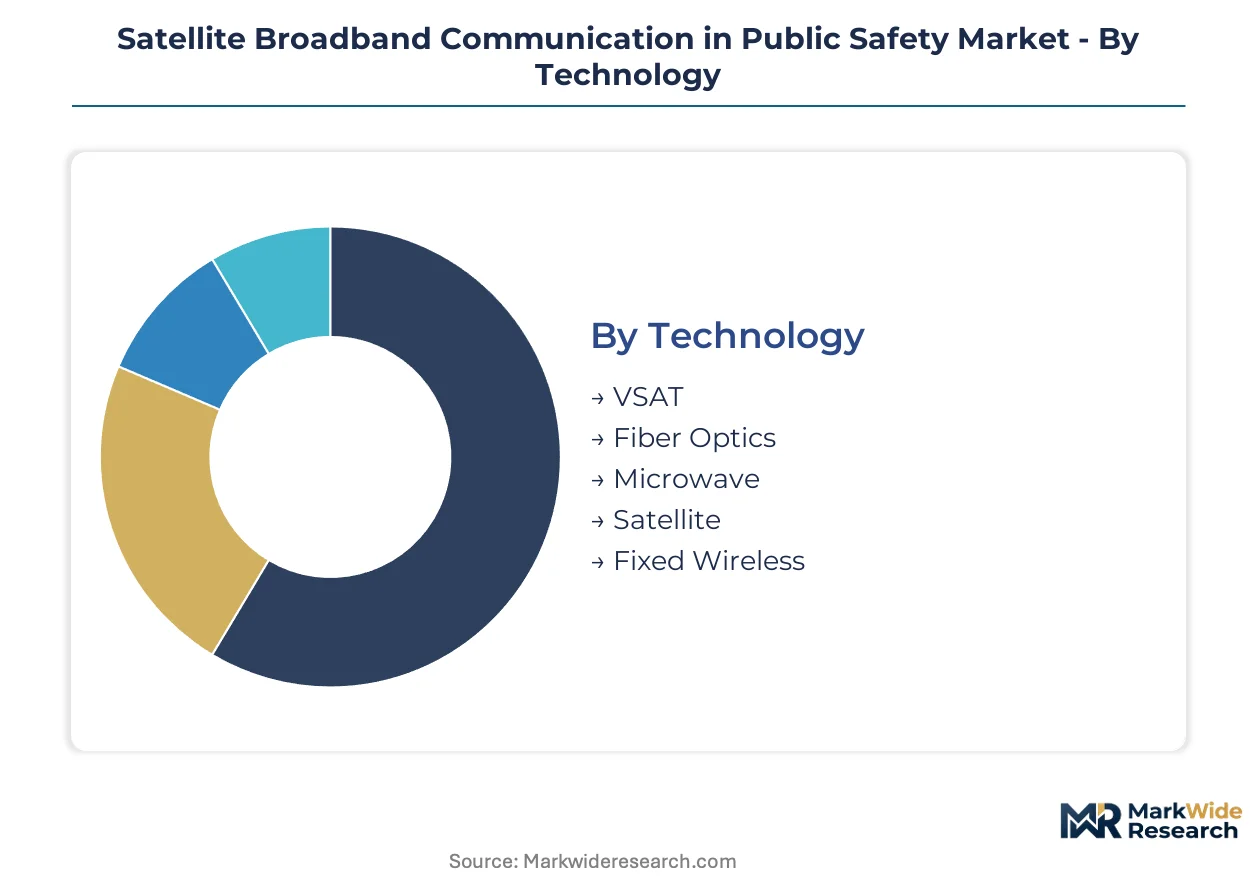
Segmentation in satellite broadband for public safety reveals how procurement priorities diverge across operational contexts. Technology choices determine spectrum licensing burdens, while end-user categories face distinct federal certification requirements that reshape vendor qualification pathways.
Technology:
FCC FirstNet interoperability certification applies unevenly across these segments, with VSAT and LEO-based architectures facing divergent testing protocols for public safety broadband access.
- VSAT:Geostationary-based very small aperture terminal systems deliver Ku-band and Ka-band connectivity through 0.6-meter to 2.4-meter dish configurations. State emergency operations centers in Texas and Florida concentrate procurement here, driven by proven interoperability with legacy federal networks and established maintenance technician pipelines. FCC Part 25 licensing governs deployment.
- Satellite:LEO and MEO constellation services provide sub-300ms latency through flat-panel phased arrays. Arctic jurisdictions across Alaska and Nordic territories anchor demand, compelled by polar terrain gaps where geostationary footprints fail. NTIA spectrum coordination creates deployment friction for dedicated public safety capacity.
- Fiber Optics:Terrestrial fiber backhaul with satellite failover redundancy for fixed emergency operations centers.
- Microwave:Point-to-point radio links for last-mile connectivity in mountainous or obstructed terrain.
- Fixed Wireless:Ground-based wireless backhaul systems with satellite integration for mobile command posts.
Leading the category by volume: VSAT. Growing fastest: Satellite.
Application:
Cost tier stratification separates capital-intensive disaster management infrastructure from operational expenditure frameworks dominating emergency response.
- Disaster Management:Wide-area network restoration following infrastructure destruction requires multi-megabit sustained throughput for video conferencing and geographic information system synchronization. FEMA grant scoring explicitly weights satellite backup provisions, concentrating procurement in hurricane-prone Gulf Coast states and wildfire corridors across California. Systems must maintain 99.9% availability tiers.
- Emergency Response:Incident-level connectivity for active operations demands rapid-deploy terminals with sub-15-minute setup protocols. Urban police and fire departments in Phoenix and Los Angeles drive demand here, compelled by software-defined bandwidth scaling that converts capital budgets to operational line items without permanent capacity commitments.
- Surveillance:Real-time video backhaul from remote sensors and drone platforms for border and critical infrastructure monitoring.
- Search and Rescue:Man-portable terminal requirements for wilderness and maritime operations where weight and battery duration constrain equipment selection.
Disaster Management commands the deepest procurement budgets. Emergency Response is expanding most quickly as agencies adopt bandwidth-as-a-service models.
End User:
Customer type determines ruggedization specifications and maintenance certification pathways, with federal interoperability mandates creating tiered vendor qualification barriers.
- Government Agencies:Federal and state emergency management departments procure multi-agency network hubs requiring NTIA-compliant encryption and priority-access protocols. Department of Homeland Security funding streams in the United States anchor volume, with sovereign payload hosting discussions accelerating in Australia and the United Kingdom.
- Fire Departments:Municipal and wildland fire services demand vehicle-mounted and portable terminals engineered for thermal extremes and particulate exposure. California and Arizona jurisdictions concentrate procurement, justifying premium service tiers through ruggedized hardware requirements that exceed standard commercial specifications.
- Police Services:Law enforcement mobile command posts require covert deployment capabilities and secure voice integration with existing radio systems.
- Emergency Medical Services:Ambulance and aeromedical platforms need compact terminals for patient data transmission and telemedicine consultation during transport.
Government Agencies lead by volume. Fire Departments represent the concentrated margin pool where hardware ruggedization justifies premium pricing.
Service Type:
Procurement maturity separates established implementation and maintenance markets from emerging consulting and support frameworks.
- Implementation:System integration encompassing terminal installation, network configuration, and interoperability testing with existing public safety communications infrastructure.
- Maintenance:Managed service contracts covering hardware refresh cycles, firmware updates, and field technician dispatch for terminal repair.
- Consulting:Advisory services for spectrum strategy, grant application preparation, and multi-orbit architecture design.
- Support:Help desk and remote diagnostics for agency IT staff managing satellite-equipped vehicle fleets.
Implementation leads by volume. Consulting shows the steepest expansion trajectory as agencies navigate multi-orbit procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of satellite broadband terminals clusters in aerospace manufacturing corridors, while procurement concentrates in jurisdictions with federal interoperability mandates and disaster-prone terrain. Consumption patterns diverge sharply between Arctic connectivity gaps and hurricane-response corridors.
United States
FEMA preparedness grants and FirstNet Authority certification requirements drive agency-level procurement across Gulf Coast and wildfire-prone states. The FCC governs spectrum allocation and public safety broadband interoperability standards under FirstNet. Texas and Florida emergency management directors pilot software-defined flat-panel antennas for mobile command post deployment.
Canada
Arctic sovereignty operations and remote northern communities create captive demand for L-band resilient architectures beyond geostationary reach. The country's national telecommunications regulator coordinates spectrum priority access for federal emergency response frameworks. Yukon and Northwest Territories jurisdictions anchor procurement for search-and-rescue satellite connectivity.
United Kingdom
Cross-border disaster response frameworks with European neighbors mandate ETSI-compliant encryption and priority-access protocols. Sovereign payload hosting discussions accelerate for exclusive public safety orbital capacity during crises. Border regions in Scotland and Northern England experience accelerated terminal replacement cycles.
Australia
Bushfire management agencies and maritime search operations drive demand for integrated drone command links with satellite backhaul. The country's national infrastructure investment programs condition funding on satellite backup redundancy in state emergency communications plans. Queensland and New South Wales rural fire services concentrate ruggedized terminal procurement.
Germany
Industrial automation corridors and Alpine terrain gaps sustain dual-use demand for public safety and critical infrastructure protection. ETSI standards mandate embedded security modules for cross-border interoperability with neighboring jurisdictions. Bavarian and Baden-Württemberg emergency management agencies align procurement with these certification requirements.
Satellite Broadband Communication in Public Safety Market Key Industry Players
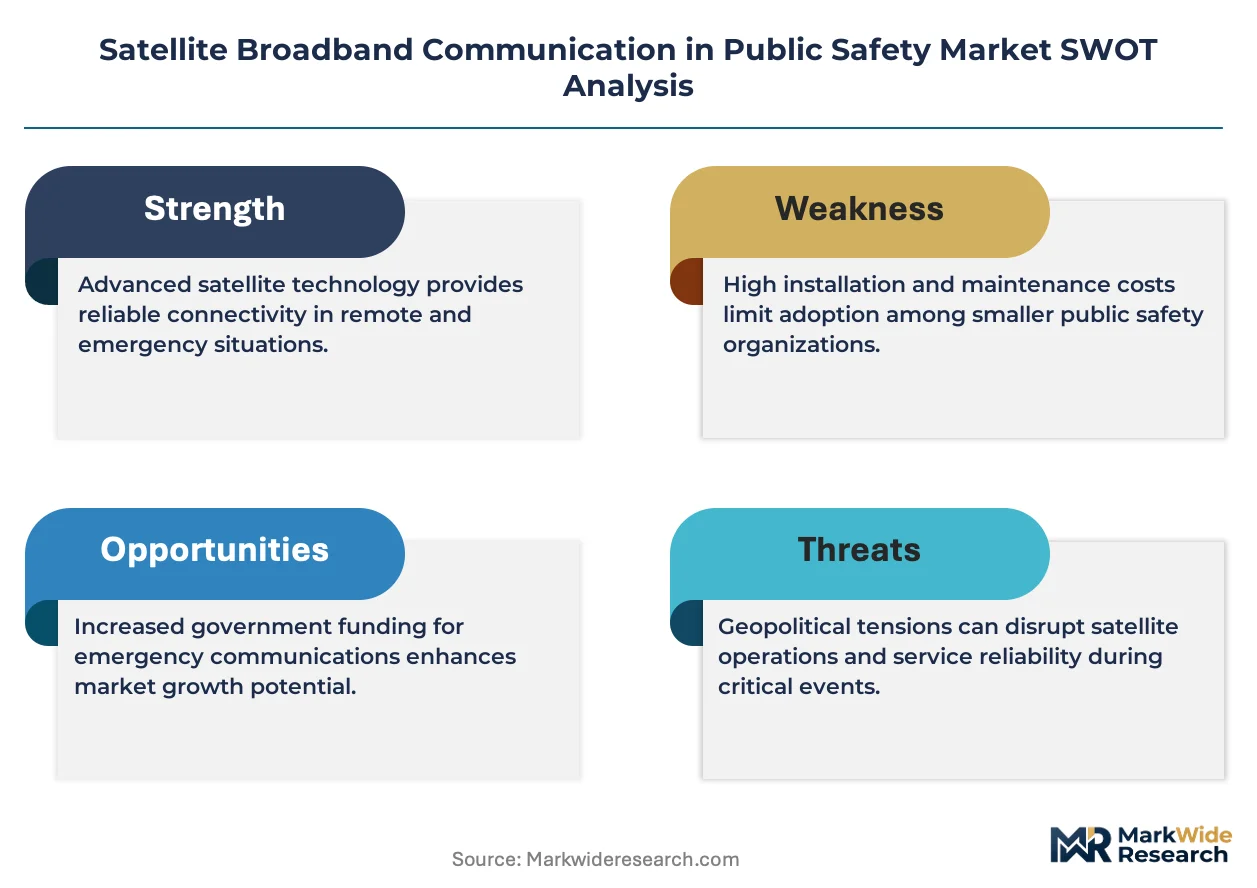
Capital-heavy satellite operators compete with asset-light service integrators for agency procurement contracts. The vendor base spans three tiers: constellation owners with integrated ground infrastructure, terminal manufacturers with ruggedized hardware specialization, and managed service providers bundling bandwidth with field support. Consolidation pressure intensifies as software-defined networking collapses procurement cycles. Dominant competitive moves include multi-orbit partnership formations and bandwidth-as-a-service contract restructuring.
Within the integrated operator tier, Viasat Inc. and Iridium Communications Inc. exemplify divergent architectural bets—geostationary high-throughput systems versus L-band polar resilience. Hughes Network Systems occupies a position bridging geostationary capacity with federal emergency operations center deployments. These three anchors represent how vendor qualification standards under FirstNet and ETSI frameworks reshape competitive positioning.
| Leading Market Players |
|---|
| Viasat Inc. |
| SES S.A. |
| Inmarsat Limited |
| Iridium Communications Inc. |
| L3Harris Technologies Inc. |
| Intelsat S.A. |
| Hughes Network Systems |
| Globalstar Inc. |
| Speedcast International Limited |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FirstNet-compliant terminals and commercial-grade hardware bifurcates procurement budgets, with ruggedized L-band units commanding three-to-five-fold premiums over standard VSAT configurations while supply chains segregate between aerospace-qualified component vendors and consumer electronics suppliers.
Pricing Analysis
Price erosion across commercial-grade VSAT terminals traces to commoditized Ku-band chipset availability and volume manufacturing scale in East Asian electronics corridors. Three-tier pricing structure across FirstNet-certified, ruggedized industrial, and standard commercial levels separates municipal fire departments with FEMA grant backing from rural counties with constrained operational budgets. Cost-down pressure on man-portable phased arrays accelerates because LEO constellation operators compete for emergency response contracts with bandwidth-as-a-service models that eliminate upfront hardware ownership. Government agencies exhibit lowest price sensitivity due to sovereign payload hosting mandates, while rural county emergency management departments face acute budget constraints that delay procurement cycles.
Supply Chain Analysis
Refurbishment flows for field-damaged terminals create secondary supply channels that extend hardware lifecycles and compress new unit demand in mature installed bases. Manufacturing concentrates in United States, United Kingdom, and Germany for aerospace-qualified phased arrays, while commercial-grade chipset fabrication draws from Taiwan and South Korea. Raw material dependencies span gallium nitride semiconductors, carbon-fiber composite substrates, and radiation-hardened memory components. Single-source vulnerability persists for L-band power amplifiers qualified under MIL-STD-810G thermal and shock specifications. Distribution runs through federal procurement vehicles, state cooperative purchasing agreements, and direct vendor relationships with large municipal agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FirstNet interoperability certification operates as a cost-of-compliance moat that protects qualified vendors from commodity competition while creating structural barriers for unqualified entrants seeking public safety procurement access.
For Market Incumbents: Lock in multi-orbit service bundling that anchors agencies to integrated geostationary-LEO architectures, complicating competitive displacement. Deepen backward integration into flat-panel antenna manufacturing to capture margin pools currently flowing to specialized hardware suppliers. Defend against emerging LEO-native entrants by accelerating software-defined terminal refresh cycles that obsolete legacy dish configurations before competitors achieve FirstNet certification. For New Entrants and Emerging Players: Begin with sovereign payload hosting discussions in Australia and United Kingdom jurisdictions where national governments seek crisis-exclusive orbital capacity outside commercial operator control. Target rural Canadian territories and Nordic Arctic regions where L-band resilience gaps persist beyond geostationary footprint coverage. Pursue bandwidth-as-a-service contracting models that convert capital-averse municipal fire departments from hardware ownership to operational expenditure frameworks. For Investors and Strategic Acquirers: Re-rating potential sits with terminal manufacturers possessing FirstNet certification and ruggedized hardware IP given consolidation pressure from constellation operators seeking vertical control over ground-segment margins. Long-term viability hinges on multi-orbit interoperability capabilities that span geostationary, MEO, and LEO architectures without hardware replacement. Monitor NTIA spectrum reallocation proceedings and LEO constellation density thresholds as early signals of competitive intensity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FirstNet Certification Investment | FCC interoperability standards anchor vendor qualification for federal and state procurement vehicles. |
| Multi-Orbit Partnership Formation | Software-defined networking collapses procurement cycles by unifying geostationary and LEO service delivery. |
| Bandwidth-as-a-Service Restructuring | Operational expenditure models convert capital-constrained fire departments from hardware ownership to service subscriptions. |
| Sovereign Payload Hosting | National governments in Australia and United Kingdom reserve orbital capacity for exclusive crisis-period public safety use. |
| Integrated Drone Command Link Development | Beyond-visual-line-of-sight UAV control converges with satellite backhaul for wildfire and maritime search operations. |
Research Approach
Independent corroboration across emergency communications directors, satellite terminal procurement officers, and FCC regulatory affairs specialists underwrites the qualitative findings. Primary interviews with state emergency management agency IT directors, municipal fire department technology leads, and LEO constellation commercial executives combined with secondary validation from FCC Part 25 licensing databases, NTIA grant allocation records, and FirstNet Authority certification registries. Bottom-up terminal shipment analysis and top-down bandwidth demand modeling triangulate market sizing across the projection horizon.
Rate-of-change decomposition across technology adoption curves, regulatory compliance timelines, and procurement cycle durations structures the analytical framework. Segmentation dimensions span orbital regime, terminal form factor, end-user agency type, and service delivery model throughout the forecast period. CAGRs derive from installed base replacement velocities, grant-conditioned deployment accelerators, and LEO constellation capacity expansion schedules. Industry-specific inputs include FEMA preparedness grant scoring weights and ETSI encryption standard adoption trajectories across European border regions.
Underlying measurement precision varies by segment; government agency procurement volumes carry tighter precision than rural county discretionary spending estimates. Forecasts reflect documented assumptions regarding spectrum allocation continuity, constellation deployment timelines, and federal interoperability mandate enforcement intensity. Practitioners should monitor NTIA-FCC coordination delays, LEO satellite launch cadence disruptions, and terrestrial 5G private network deployment rates for early signals of demand trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G Remote Radio Head Market
Telecommunications
Myanmar ICT Market
Telecommunications
Telecom Managed Services Market
Telecommunications
Fixed Voice Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Ghana Telecom Market
Telecommunications
Indonesia Volte Market
Telecommunications
Norway Telecom Market
Telecommunications
5G Equipment Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
Rich Communication Services (RCS) Messaging Market
Telecommunications
Smart SIM Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
Global IP Phone Market
Telecommunications
Middle East and Africa Telecom Market