
 Global LTE and 5G Broadcast Market | 2026-2036
Global LTE and 5G Broadcast Market Size, Share, and Industry Trends Forecast 2026-2036
Global LTE and 5G Broadcast Market Foresight
EU AI Act compliance is broadening the cost-of-entry calculus for 5G broadcast infrastructure vendors serving European mobile network operators. Cisco Systems leverages its router and core network portfolio to anchor broadcast-grade latency requirements in carrier architectures. Huawei Technologies competes through integrated RAN-to-core portfolios that compress deployment complexity for operators pursuing multicast services.
LTE and 5G Broadcast encompasses cellular-based multimedia distribution using evolved Multimedia Broadcast Multicast Service and 3GPP-standardized broadcast modes operating in dedicated or shared spectrum below 6 GHz, designed to deliver simultaneous video, audio, and data streams to mass audiences without congesting unicast networks. LTE Broadcast maintains structural dominance in live event streaming where stadium and concert venue deployments generate recurring operator revenue, while 5G Broadcast occupies the fastest-expanding position in emergency alert systems as governments mandate population-wide warning capabilities. Digital signage applications sustain mature margin pools through retail and transit infrastructure refresh cycles.
FCC Part 27 rules govern broadcast spectrum allocation in the United States, while ETSI standards shape European interoperability mandates and South Korea's MSIT drives spectrum harmonization for terrestrial-broadcast-to-mobile convergence. Regulatory fragmentation across these jurisdictions forces equipment vendors to maintain multi-standard certification pipelines, elevating R&D overhead for market participants. Stakeholders must monitor 3GPP Release 18 timelines and national spectrum auction outcomes to calibrate product roadmaps against shifting compliance requirements.
Market Dynamics
Migration from satellite to cellular distribution for live events is compressing deployment timelines and forcing infrastructure vendors to recalibrate RAN-to-core integration roadmaps around 3GPP multicast specifications.
Growth Catalysts
- 3GPP Release 17 multicast-broadcast services:Standardized broadcast modes in sub-6 GHz spectrum enable simultaneous video delivery without unicast congestion, accelerating operator trials in South Korea and Germany.
- Emergency alert mandates:Population-wide warning capabilities required by national governments are driving 5G Broadcast deployment for public safety networks.
- Stadium and concert venue deployments:Recurring revenue from live event streaming sustains LTE Broadcast infrastructure refresh cycles across North American and European sports franchises.
Market Restraints
- Spectrum licensing costs:Dedicated broadcast spectrum below 6 GHz commands premium auction prices, elevating total cost of ownership for mobile network operators.
- Multi-standard certification overhead:Regulatory fragmentation across FCC Part 27, ETSI, and South Korean MSIT requirements forces vendors to maintain parallel compliance pipelines.
- Satellite distribution incumbency:Established broadcasters with sunk satellite infrastructure investments resist cellular migration timelines.
Strategic Opportunities
- Retail digital signage refresh:Transit infrastructure and commercial real estate operators in Japan and Australia are replacing legacy displays with cellular-connected screens.
- EU AI Act compliance services:Infrastructure vendors can bundle broadcast-grade latency guarantees with automated compliance tooling for European mobile operators.
- Terrestrial-broadcast-to-mobile convergence:Spectrum harmonization initiatives create white space for hybrid network architectures in South Korea and select European markets.
Industry Challenges
- Multicast RAN engineering talent scarcity:Specialized expertise in evolved Multimedia Broadcast Multicast Service configuration remains concentrated among legacy equipment vendors.
- Legacy unicast network integration:Operators face operational complexity when overlaying broadcast capabilities onto existing 4G and 5G standalone cores without service disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global LTE and 5G Broadcast Market |
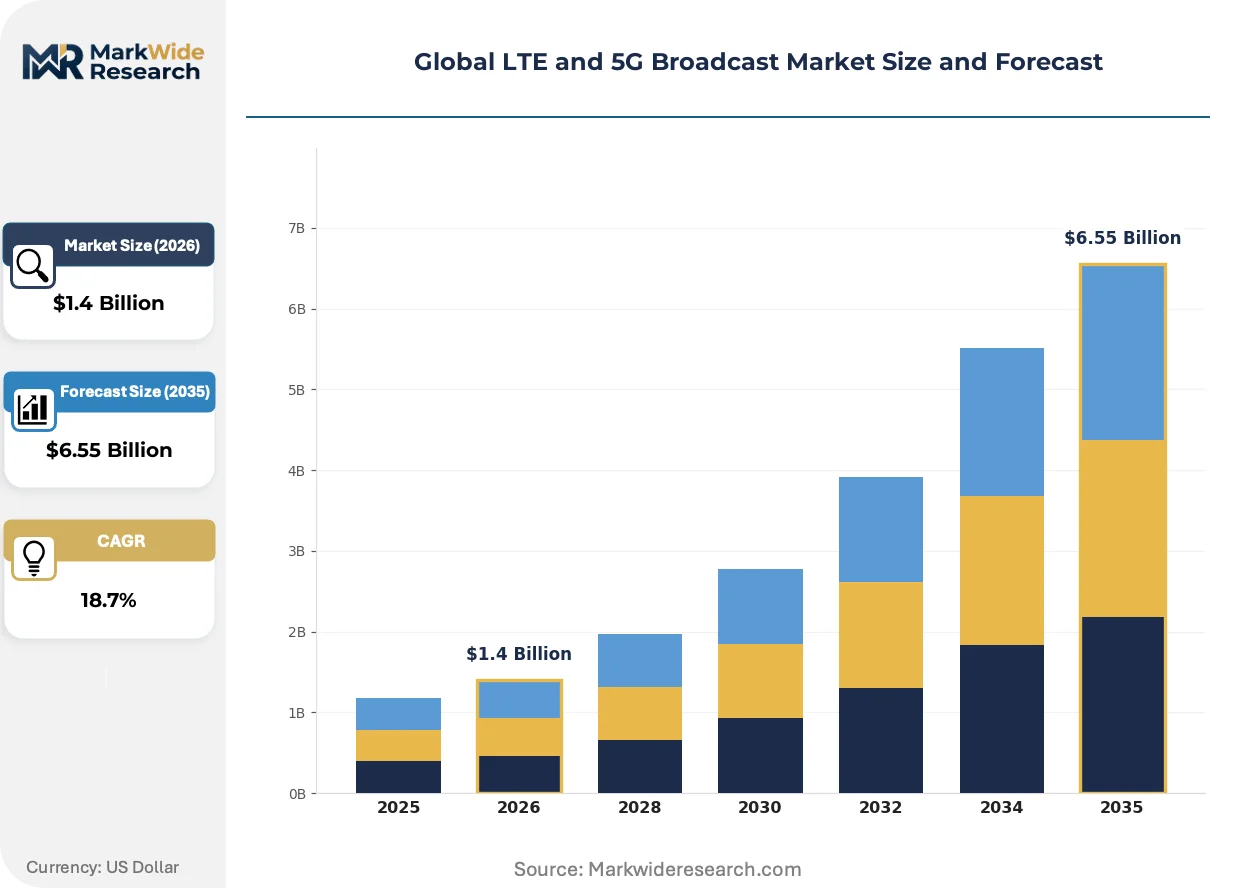
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LTE Broadcast, 5G Broadcast, eMBMS, MIMO, Beamforming, Carrier Aggregation Application: Live Event Streaming, Emergency Alert Systems, Public Safety Communications, Digital Signage, IoT Data Broadcasting, Content Delivery Networks Device Type: Smartphones, Tablets, Set-Top Boxes, In-Vehicle Entertainment Systems, Wearables, Smart TVs End User: Television Broadcasters, Government Agencies, Mobile Network Operators, Event Organizers, Disaster Management Authorities, Transportation Providers |
| Companies Covered | Cisco Systems, KT Corporation, Huawei Technologies, AT&T, Verizon Wireless, Qualcomm, ZTE, Nokia Corporation, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global LTE and 5G Broadcast Market Shifts & Advancements
Broadcast infrastructure is pivoting from hardware-centric deployment models toward software-defined architectures that compress time-to-service for multicast offerings.
Network function virtualization is converging with containerized core platforms to displace purpose-built broadcast hardware. Tier-one operators in Germany and South Korea are adopting cloud-native multicast controllers to reduce physical footprint in stadium deployments. This convergence is compressing vendor qualification cycles and enabling faster feature velocity for live event streaming.
The EU AI Act is mandating automated documentation and audit trails for network infrastructure serving artificial intelligence workloads. European mobile operators must now embed compliance telemetry directly into broadcast-grade latency paths. Carriers serving media distribution are responding by pre-certifying RAN equipment against forthcoming 3GPP Release 18 security specifications.
Stadium operators and venue managers are consolidating vendor relationships around integrated cellular and Wi-Fi coverage contracts. Procurement teams now require single-source accountability for dense-environment connectivity rather than siloed radio access negotiations. This pattern is most pronounced in North American professional sports franchises and large-scale entertainment venues.
Global LTE and 5G Broadcast Market Segmentation
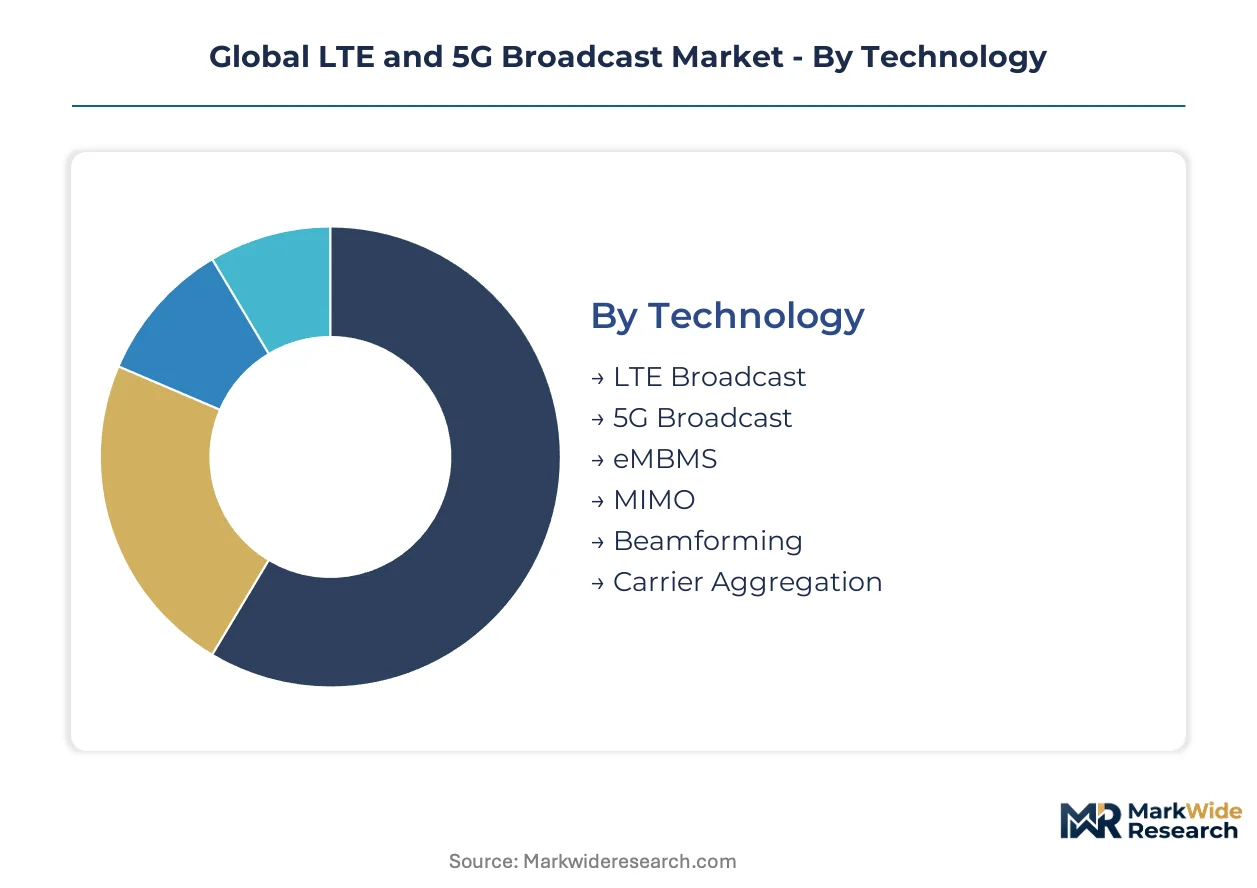
Technology choice dictates spectrum efficiency and deployment cost for cellular broadcast networks. Application focus determines whether operators prioritize latency-sensitive live streaming or reliable mass-alert distribution. End-user concentration shapes procurement scale and integration complexity across infrastructure vendors.
Technology:
Buyers differentiate primarily by spectrum licensing strategy and legacy network compatibility requirements.
- LTE Broadcast:Evolved Multimedia Broadcast Multicast Service technology operating in licensed cellular bands delivers simultaneous video streams to mass audiences without unicast congestion. Stadium operators in the United States and Germany favor this mature standard for proven reliability during high-density events, though spectrum costs constrain greenfield deployments.
- 5G Broadcast:3GPP Release 17 multicast modes enable sub-6 GHz transmission with lower latency and higher spectral efficiency than LTE predecessors. South Korea's KT Corporation anchors global deployment volume, while German operators trial hybrid architectures for emergency alert mandates.
- eMBMS:Enhanced Multimedia Broadcast Multicast Service extends LTE broadcast capabilities with improved carrier aggregation support.
- MIMO:Multiple-input multiple-output antenna configurations boost spectral efficiency in dense urban deployments.
- Beamforming:Directional signal focusing concentrates transmission power toward receiver clusters.
- Carrier Aggregation:Bonding multiple frequency channels expands effective bandwidth for high-definition streaming.
LTE Broadcast leads volumes today; 5G Broadcast is climbing the fastest as Release 17 commercialization accelerates.
Application:
Revenue concentration tracks regulatory mandate intensity and recurring event calendar density.
- Live Event Streaming:Real-time video distribution to stadium and concert venues generates recurring operator revenue through seasonal sports franchises and touring entertainment. North American professional leagues and European football clubs drive infrastructure refresh cycles, with procurement teams demanding single-source accountability for dense-environment connectivity.
- Emergency Alert Systems:Population-wide warning capabilities mandated by national governments exploit 5G Broadcast's simultaneous reach without network congestion. South Korea's MSIT and Germany's Federal Network Agency shape deployment timelines through spectrum harmonization initiatives.
- Public Safety Communications:First responder networks prioritize reliability over bandwidth in mission-critical scenarios.
- Digital Signage:Retail and transit infrastructure refresh cycles sustain mature margin pools in Japan and Australia.
- IoT Data Broadcasting:Massive machine-type communication benefits from multicast efficiency for firmware updates.
- Content Delivery Networks:Edge caching integration reduces backhaul pressure for over-the-top video platforms.
Live Event Streaming dominates revenue today; Emergency Alert Systems show steepest expansion trajectory as government mandates proliferate.
Device Type:
Hardware refresh velocity varies by consumer replacement cycles versus embedded automotive timelines.
- Smartphones:Handset ecosystem readiness determines addressable audience scale for broadcast services.
- Tablets:Larger screens suit venue-based second-screen experiences during live events.
- Set-Top Boxes:Hybrid broadcast-broadband receivers bridge terrestrial and cellular distribution in European markets.
- In-Vehicle Entertainment Systems:Automotive integration cycles extend five to seven years, delaying mass-market penetration despite strong use case alignment for passenger streaming.
- Wearables:Limited display constraints restrict video applicability to audio and data alerts.
- Smart TVs:Native cellular modems remain rare; external adapters bridge connectivity gaps.
Smartphones anchor installed base today; In-Vehicle Entertainment Systems are gaining share fastest as connected car penetration deepens.
End User:
Procurement sophistication spans commercial revenue optimization to public mission assurance.
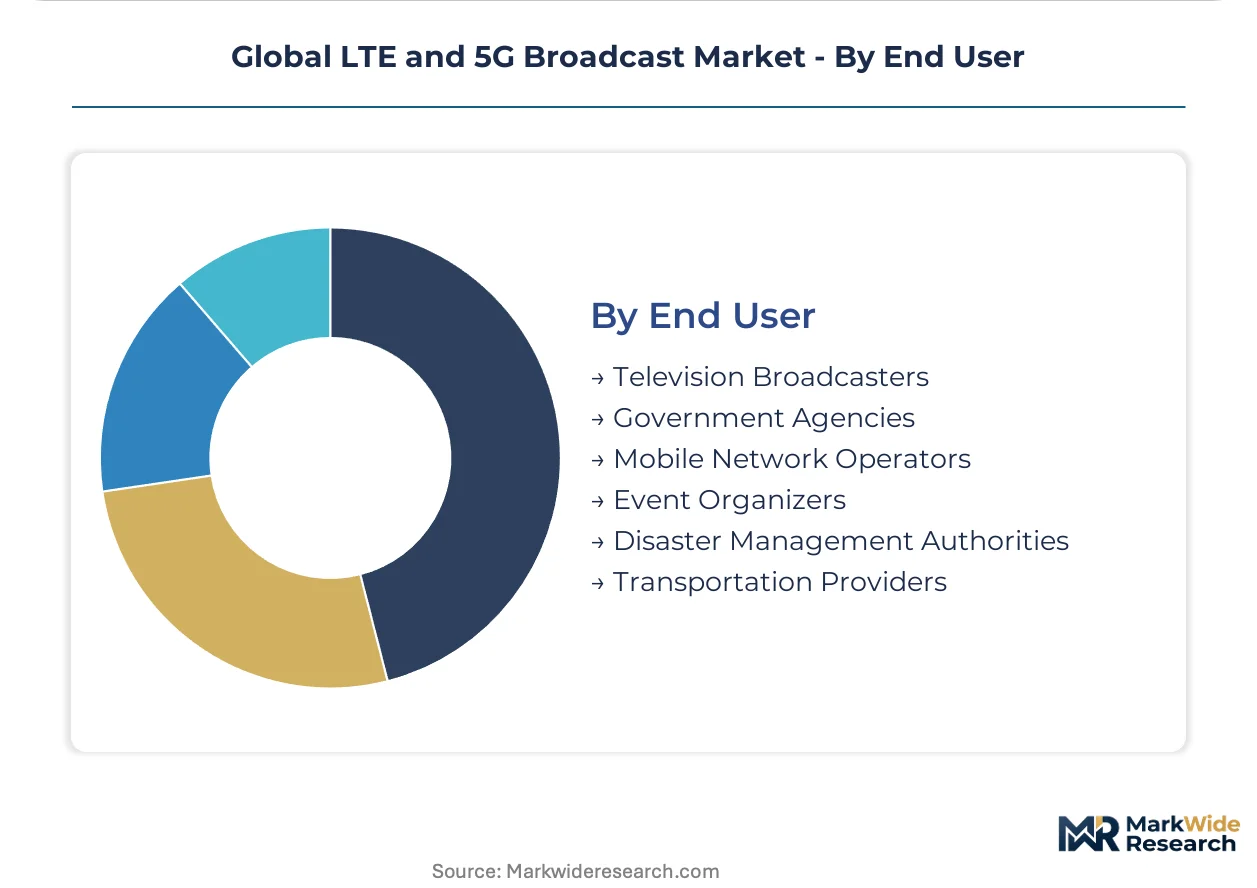
- Television Broadcasters:Satellite-dependent incumbents evaluate cellular migration timelines against sunk infrastructure investments.
- Government Agencies:Civil defense and public information offices prioritize coverage reliability over cost minimization.
- Mobile Network Operators:Carriers balance unicast congestion relief against dedicated broadcast spectrum auction prices.
- Event Organizers:Sports franchises and concert promoters demand guaranteed quality-of-service for premium attendee experiences.
- Disaster Management Authorities:Earthquake and hurricane-prone jurisdictions in Japan and California drive hardened network requirements.
- Transportation Providers:Airlines and rail operators explore passenger entertainment and operational data distribution.
Mobile Network Operators lead contract volumes today; Government Agencies are expanding procurement fastest amid emergency alert mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineers specializing in evolved Multimedia Broadcast Multicast Service configuration concentrate in South Korea, Germany, and the United States, anchoring global deployment expertise for multicast RAN integration.
United States
FCC Part 27 rules govern broadcast spectrum allocation below 6 GHz, shaping operator investment timelines. Professional sports franchises in North America drive stadium infrastructure refresh cycles through recurring live event streaming contracts. Dense-venue connectivity procurement in cities like Los Angeles and Atlanta now demands single-source accountability for cellular and Wi-Fi coverage.
South Korea
KT Corporation operates the world's largest commercial 5G broadcast network, validating Release 17 multicast specifications at scale. The Ministry of Science and ICT (MSIT) drives spectrum harmonization for terrestrial-broadcast-to-mobile convergence. Seoul anchors deployment volume, while Busan-Ulsan clusters support R&D for hybrid emergency alert architectures.
Germany
ETSI standards shape European interoperability mandates for multicast-broadcast services. The Federal Network Agency (BNetzA) coordinates spectrum policy with neighboring jurisdictions, compressing cross-border deployment complexity. Munich and Berlin host operator trials combining 5G Broadcast with cloud-native multicast controllers for stadium and public safety applications.
Japan
METI guidelines influence cellular broadcast infrastructure standards across earthquake-prone jurisdictions. Disaster management authorities prioritize hardened network requirements for population-wide warning capabilities. Tokyo and Osaka metropolitan areas sustain digital signage refresh cycles through retail and transit infrastructure investments.
United Kingdom
Ofcom regulates shared spectrum access for broadcast-to-mobile services below 6 GHz. The country's national broadcast regulator coordinates with mobile operators on hybrid distribution trials. London's dense venue ecosystem generates procurement demand for integrated cellular-Wi-Fi coverage contracts across entertainment and sports infrastructure.
Global LTE and 5G Broadcast Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the LTE and 5G Broadcast infrastructure stack. The vendor base spans router and core network providers, integrated RAN-to-core portfolio suppliers, and specialized multicast controller developers. Three archetypes dominate: telecommunications equipment giants with end-to-end portfolios, network infrastructure specialists anchoring broadcast-grade latency paths, and mobile network operators operating captive broadcast services. Competitive moves concentrate on RAN-to-core integration partnerships and cloud-native multicast controller certifications against 3GPP security specifications.
Within the integrated equipment tier, Cisco Systems and Huawei Technologies exemplify contrasting geographic positioning strategies. KT Corporation occupies a distinctive position as both infrastructure deployer and service operator. ZTE and Nokia Corporation sit within the telecommunications equipment archetype, while Samsung Electronics and Qualcomm represent component and device-level specialists. AT&T and Verizon Wireless anchor the mobile network operator segment with direct broadcast service deployment experience.
| Leading Market Players |
|---|
| Cisco Systems |
| KT Corporation |
| Huawei Technologies |
| AT&T |
| Verizon Wireless |
| Qualcomm |
| ZTE |
| Nokia Corporation |
| Samsung Electronics |
| Others |
Supply & Pricing Matrix
Mobile network operators in South Korea and Germany anchor procurement volume for 5G broadcast infrastructure, concentrating bargaining power around bundled RAN-to-core service contracts rather than discrete hardware transactions. This buyer concentration elevates the importance of certification-backed latency guarantees in vendor selection.
Pricing Analysis
Bundled multicast controller and core network packages command premium positioning against unbundled radio access network components. Three-tier pricing structure across premium, standard, and economy levels separates stadium-grade deployments with sub-50ms latency guarantees from transit infrastructure refreshes and rural emergency alert coverage. Price differentiation hinges on 3GPP Release 17 certification status and spectrum licensing cost pass-through structures. Margins are tightening due to cloud-native multicast controller commoditization in German operator trials. Tier-two mobile network operators in Japan and Australia exhibit highest price sensitivity, while government agencies prioritize coverage reliability over cost minimization.
Supply Chain Analysis
Specialized semiconductor fabrication for broadcast-optimized baseband processors rests on Taiwanese foundry capacity and South Korean memory component suppliers. Radio frequency front-end modules draw from Japanese substrate manufacturers and Chinese assembly operations. Sub-6 GHz power amplifier supply concentrates in South Korea, Japan, and the United States. Single-source vulnerability persists for evolved Multimedia Broadcast Multicast Service configuration engineering talent concentrated among legacy equipment vendors. Distribution runs through direct carrier procurement teams for tier-one operators and systems integrator channels for stadium and venue deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where operator procurement teams now demand 3GPP Release 18 pre-certification as a baseline qualification threshold, compressing margins for vendors without forward-compatible roadmaps.
For Market Incumbents: Anticipate cloud-native multicast controller displacement of purpose-built hardware by accelerating software-defined architecture certifications against forthcoming 3GPP security specifications. Defensive consolidation around RAN-to-core integration partnerships will counter margin pressure from containerized core platform commoditization. Prioritize retaining evolved Multimedia Broadcast Multicast Service engineering talent through captive development centers in Seoul and Munich. For New Entrants and Emerging Players: Cloud-native multicast controller specialization offers a technology-first wedge into European operator procurement cycles ahead of EU AI Act compliance mandates. White-space targets include retail digital signage refresh in Australian transit infrastructure and hybrid emergency alert architectures in Japanese earthquake-prone jurisdictions. A channel partnership route through systems integrators serving North American sports franchises bypasses direct incumbent relationships. For Investors and Strategic Acquirers: Telecommunications equipment conglomerates are the most active acquirer in this space, seeking broadcast-grade latency capability to anchor carrier architecture contracts. Long-term viability centers on vendors with software-defined multicast portfolios and 3GPP standard-setting influence. Watch for national spectrum auction outcomes as inflection indicators for infrastructure deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Multicast Controller Certification | Reduces physical footprint in KT Corporation stadium deployments while accelerating feature velocity. |
| 3GPP Release 18 Pre-Certification Investment | Positions vendors for EU AI Act compliance telemetry requirements in German operator architectures. |
| Terrestrial-Broadcast-to-Mobile Convergence Partnership | Captures South Korean MSIT spectrum harmonization initiatives for hybrid network architectures. |
| Evolved MBMS Engineering Talent Acquisition | Addresses scarcity concentration among legacy vendors for multicast RAN configuration expertise. |
| Integrated Cellular-Wi-Fi Coverage Contract Consolidation | Aligns with North American sports franchise procurement demands for single-source accountability. |
Research Methodology
Coverage spans South Korea, Germany, the United States, Japan, and the United Kingdom, with primary inputs from each market anchoring regional demand calibration. The approach combines structured interviews with mobile network operator procurement directors, stadium technology managers, and regulatory affairs specialists with secondary validation through 3GPP specification documents, FCC Part 27 filings, ETSI standards releases, and national spectrum auction records. Bottom-up deployment tracking across commercial broadcast networks triangulates against top-down infrastructure spending estimates from carrier capex disclosures.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include technology generation, application use case, and end-user procurement sophistication. CAGRs derive from installed base evolution for LTE Broadcast against greenfield deployment velocity for 5G multicast modes. Industry-specific forecast inputs incorporate 3GPP Release timeline milestones and national emergency alert mandate implementation schedules.
The model holds under steady 3GPP standardization cadence and sustained spectrum licensing demand; deviation in regulatory fragmentation intensity or satellite distribution incumbent resistance would shift deployment timelines. Forecasts reflect documented assumptions about operator unicast congestion relief economics and government public safety network prioritization. A small set of named triggers warrants ongoing watch: 3GPP Release 18 security specification finalization, EU AI Act enforcement precedent, and South Korean terrestrial-broadcast-to-mobile convergence policy implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Mexico Telecom Market
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
India Optical Transport Network (OTN) Market
Telecommunications
Mission Critical Communication (MCX) Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
Cambodia ICT Market
Telecommunications
Global Small Cell 5G Network Market
Telecommunications
Digital Mobile Radio (DMR) Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
Global GPON Technology Market
Telecommunications
Global IP Phone Market
Telecommunications
Global 5G Services Market
Telecommunications
Argentina ICT Market
Telecommunications
SIP Trunking Services Market
Telecommunications
Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market
Telecommunications
Mobile Virtual Network Operator (MVNO) Market