
 Managed Mobility Services (MMS) Market | 2026-2036
Managed Mobility Services (MMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Managed Mobility Services (MMS) Market Foresight
The migration from in-house IT mobility teams to outsourced managed service arrangements is shifting procurement patterns across enterprise technology budgets. Tangoe leverages extensive telecom expense management heritage to anchor multi-carrier negotiation capabilities for Fortune 500 clients. Fujitsu sustains competitive positioning through integrated hardware-software service bundles spanning device lifecycle logistics across Asia-Pacific and European accounts. Stratix Corporation specializes in ruggedized mobility deployments, dominating verticals such as warehouse automation and field service operations where device durability commands premium pricing.
Managed Mobility Services encompass the end-to-end procurement, provisioning, security, and support of mobile devices, applications, and connectivity infrastructure for organizational workforces, typically delivered through cloud-native orchestration platforms with real-time usage analytics and policy enforcement engines. The primary commercial purpose centers on reducing total cost of ownership while ensuring compliance, security, and operational continuity across geographically dispersed employee populations. Device Management and Security Management segments lead current revenue pools as enterprises confront escalating cyber threats and fragmented endpoint landscapes. Cloud-Based deployment models represent the fastest-expanding structural category, displacing on-premise alternatives as organizations prioritize scalability and reduced capital expenditure in mobility infrastructure.
FCC guidelines on wireless spectrum allocation and device certification shape connectivity standards and carrier interoperability requirements for MMS providers serving US enterprise accounts. GDPR in Europe and ISO 27001 globally impose data residency and information security governance obligations that directly influence platform architecture and service delivery boundaries. Stakeholders must monitor evolving AI-driven endpoint detection mandates and zero-trust network architectures as regulatory frameworks tighten around mobile threat vectors and cross-border data flows.
Market Dynamics
Enterprise migration toward zero-trust security architectures is compressing procurement cycles for integrated endpoint management platforms as CISOs demand unified policy enforcement across fragmented device fleets.
Growth Catalysts
- GDPR and EU AI Act mandates:European enterprises face escalating compliance penalties for cross-border data flows, accelerating outsourcing of mobile governance to specialized MMS providers with certified data residency controls.
- 5G private network deployments:Manufacturing and logistics verticals in Germany and South Korea are commissioning dedicated wireless infrastructure, requiring managed service overlays for device provisioning and spectrum optimization.
- Hybrid workforce permanence:Distributed employee populations across United States and United Kingdom enterprises sustain demand for cloud-native device lifecycle management with real-time usage analytics.
Market Restraints
- Carrier consolidation risk:United States wireless market concentration among three national operators limits multi-carrier negotiation leverage for enterprise clients and elevates switching costs.
- Silicon supply volatility:Semiconductor fabrication constraints for mobile chipsets create device procurement delays and force inventory pre-commitments that strain working capital.
- Legacy system interoperability:On-premise identity management directories resist API integration with cloud-native MMS platforms, extending deployment timelines and inflating professional services costs.
Strategic Opportunities
- India enterprise mobility underpenetration:Mid-market manufacturers and pharmaceutical distributors lack dedicated IT mobility functions, creating whitespace for subscription-based managed services with localized Hindi support.
- AI-driven endpoint detection integration:Convergence of machine learning threat analytics with mobile device management consoles enables predictive security posture scoring as a premium service tier.
- CSRD sustainability reporting:European Corporate Sustainability Reporting Directive mandates device carbon footprint disclosure, positioning MMS providers to monetize e-waste recycling and circular logistics as compliance services.
Industry Challenges
- Zero-trust architecture skill scarcity:Enterprise IT departments lack personnel proficient in micro-segmentation policy design and continuous device verification protocols, forcing reliance on vendor professional services.
- Multi-cloud integration complexity:Fragmented identity provider ecosystems across Microsoft Azure AD, Okta, and Ping Identity require custom connector development for unified policy enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed Mobility Services (MMS) Market |
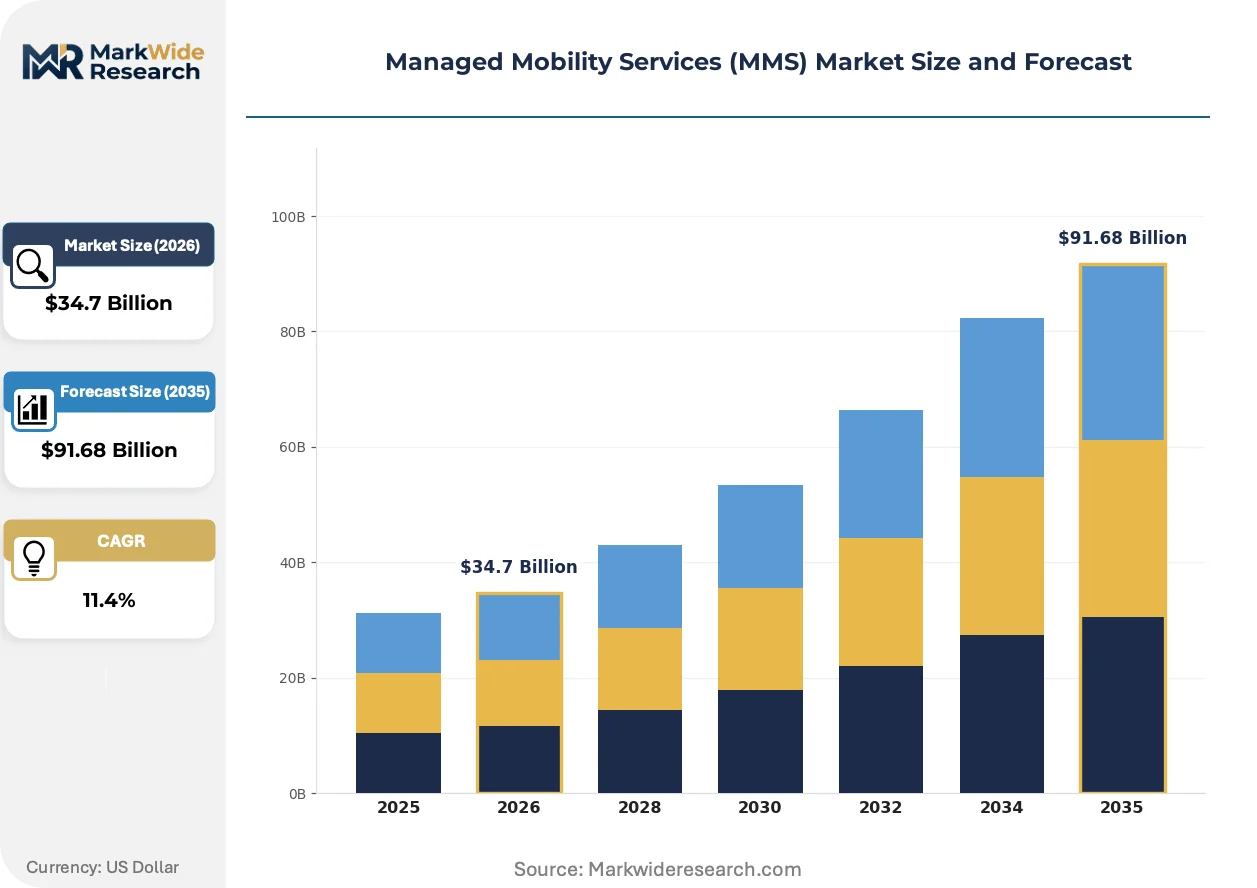
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $91.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Device Management, Application Management, Network Management, Security Management Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed End User: Enterprises, SMEs, Government Organizations, Educational Institutions Technology: MDM, MAM, VPN, AI-Driven Solutions |
| Companies Covered | Brightfin, DMI, Stratix Corporation, Motorola Solutions, Fujitsu, Motus, DecisionPoint Technologies, Tangoe, Commbitz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed Mobility Services (MMS) Market Shifts & Advancements
Platform consolidation around unified endpoint management is eroding standalone mobile device management vendors as buyers prioritize security-operations convergence over point solutions.
Unified endpoint management is consolidating previously siloed mobile, desktop, and IoT device administration into single policy engines. Financial services and healthcare enterprises in the United States and United Kingdom are standardizing on these platforms within eighteen-month refresh cycles. This consolidation is compressing vendor margins for standalone mobile specialists while elevating cybersecurity-native providers with integrated threat response capabilities.
EU AI Act risk classification requirements are mandating algorithmic transparency for automated endpoint security decisions. European enterprises deploying AI-driven threat detection must now document decision audit trails and human oversight protocols. Device management platforms serving Germany, France, and Netherlands accounts are embedding compliance dashboards as standard features to preempt regulatory scrutiny.
Consumption-based service contracts are displacing per-device subscription pricing among Fortune 500 procurement teams. United States enterprise buyers now negotiate outcome metrics around security incident response times and device uptime rather than seat counts. This shift concentrates contract value with vendors demonstrating measurable operational resilience in manufacturing and field service verticals.
Managed Mobility Services (MMS) Market Segmentation
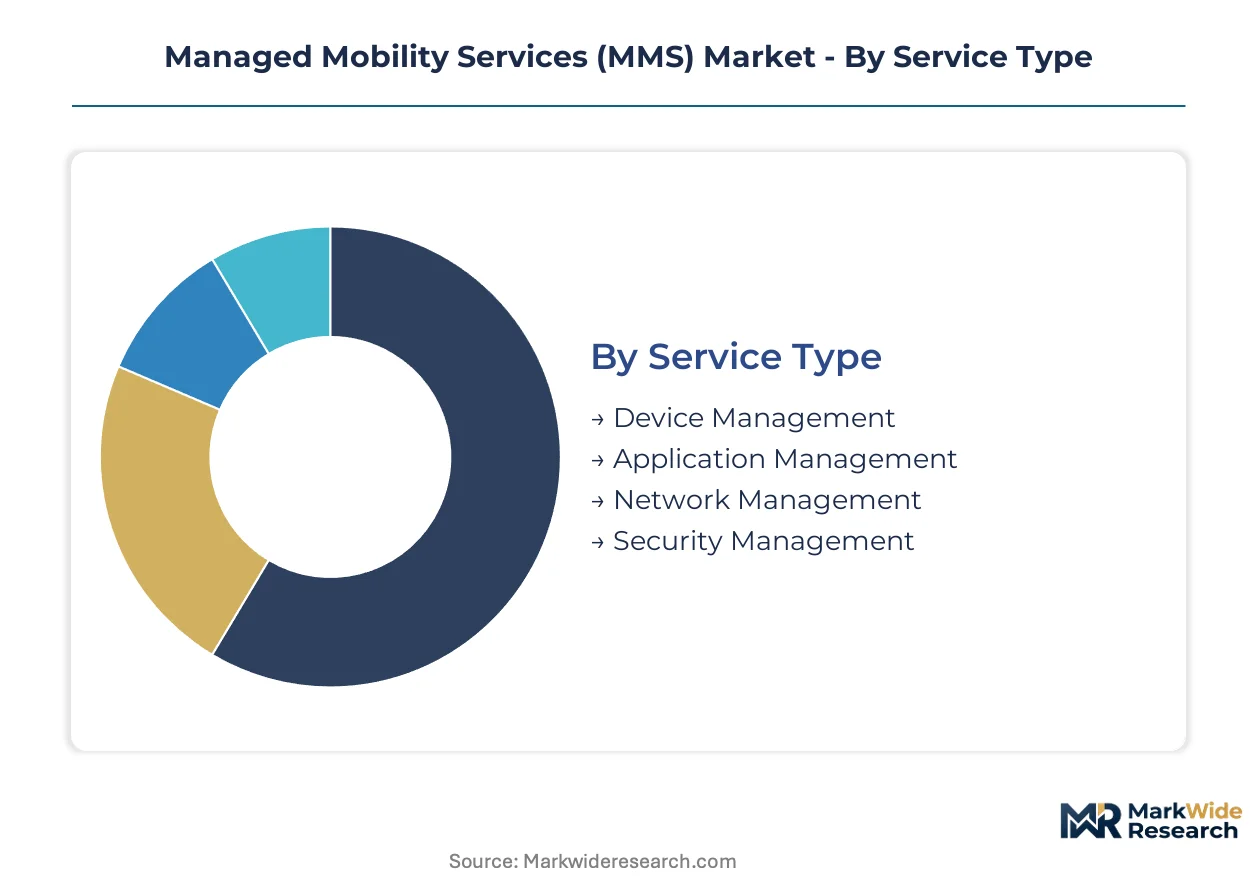
Segmentation in Managed Mobility Services reveals how procurement priorities diverge across technical architectures and organizational scale. Understanding these divides enables vendors to calibrate platform investments toward the highest-velocity revenue pools.
Service Type:
Integration depth varies sharply across service categories, with standalone security modules commanding premium pricing while bundled device-application stacks dominate volume contracts.
- Device Management:Encompasses procurement, provisioning, configuration, and end-of-life logistics for smartphones, tablets, and ruggedized field hardware. Demand concentrates among United States manufacturing and logistics enterprises confronting fragmented Android and iOS fleets with divergent update cycles. FCC device certification requirements and carrier interoperability testing extend deployment timelines for multi-national deployments.
- Security Management:Delivers endpoint threat detection, encryption policy enforcement, and zero-trust access orchestration through cloud-native policy engines. Financial services and healthcare organizations in the United Kingdom and Germany prioritize this segment amid GDPR breach notification mandates and EU AI Act algorithmic transparency requirements. Integration with Microsoft Azure AD and Okta identity providers dominates procurement specifications.
- Application Management:Controls enterprise app distribution, version control, and containerized data separation across managed devices.
- Network Management:Optimizes carrier contracts, roaming cost containment, and private 5G spectrum utilization for distributed workforces.
Device Management leads volumes today; Security Management is gaining share fastest.
Deployment Model:
Cost tier stratification separates capital-intensive on-premise installations from operational expenditure models favoring cloud elasticity.
- Cloud-Based:Delivers multi-tenant orchestration platforms with API-driven policy propagation and real-time usage analytics. United States and United Kingdom enterprises with hybrid workforces favor this model for scalability without data center expansion. GDPR data residency controls and ISO 27001 certification requirements shape vendor selection criteria in European accounts.
- Hybrid:Combines on-premise identity directories with cloud-delivered device management for regulated industries. German automotive and pharmaceutical manufacturers deploy this architecture to satisfy works council data localization demands while leveraging cloud analytics. The model inflates professional services costs due to custom connector development.
- On-Premise:Maintains complete infrastructure control within organizational firewalls for classified government environments.
- Managed:Outsources entire mobility function to third-party providers with outcome-based service level agreements.
Cloud-Based deployments dominate new contract value; Hybrid architectures show the steepest expansion trajectory among regulated verticals.
End User:
Customer type determines contract structure complexity, with enterprise accounts demanding customized integrations and mid-market buyers prioritizing rapid deployment templates.
- Enterprises:Requires unified endpoint management across tens of thousands of devices with multi-carrier negotiation and global help desk support. Fortune 500 manufacturers in the United States commission these services for warehouse automation and field service operations. Procurement teams negotiate consumption-based pricing tied to security incident response metrics rather than per-device fees.
- SMEs:Seeks standardized subscription tiers with pre-configured security policies and limited customization. Mid-market pharmaceutical distributors and regional logistics operators in India represent underpenetrated whitespace with localized Hindi and regional language support requirements. TRAI mobile number portability regulations influence carrier switching flexibility.
- Government Organizations:Mandates FedRAMP or equivalent certification with air-gapped deployment options for classified mobility.
- Educational Institutions:Prioritizes bulk device procurement with content filtering and student privacy compliance.
Enterprises capture the majority of contract value today; SME adoption is climbing fastest as subscription economics democratize access.
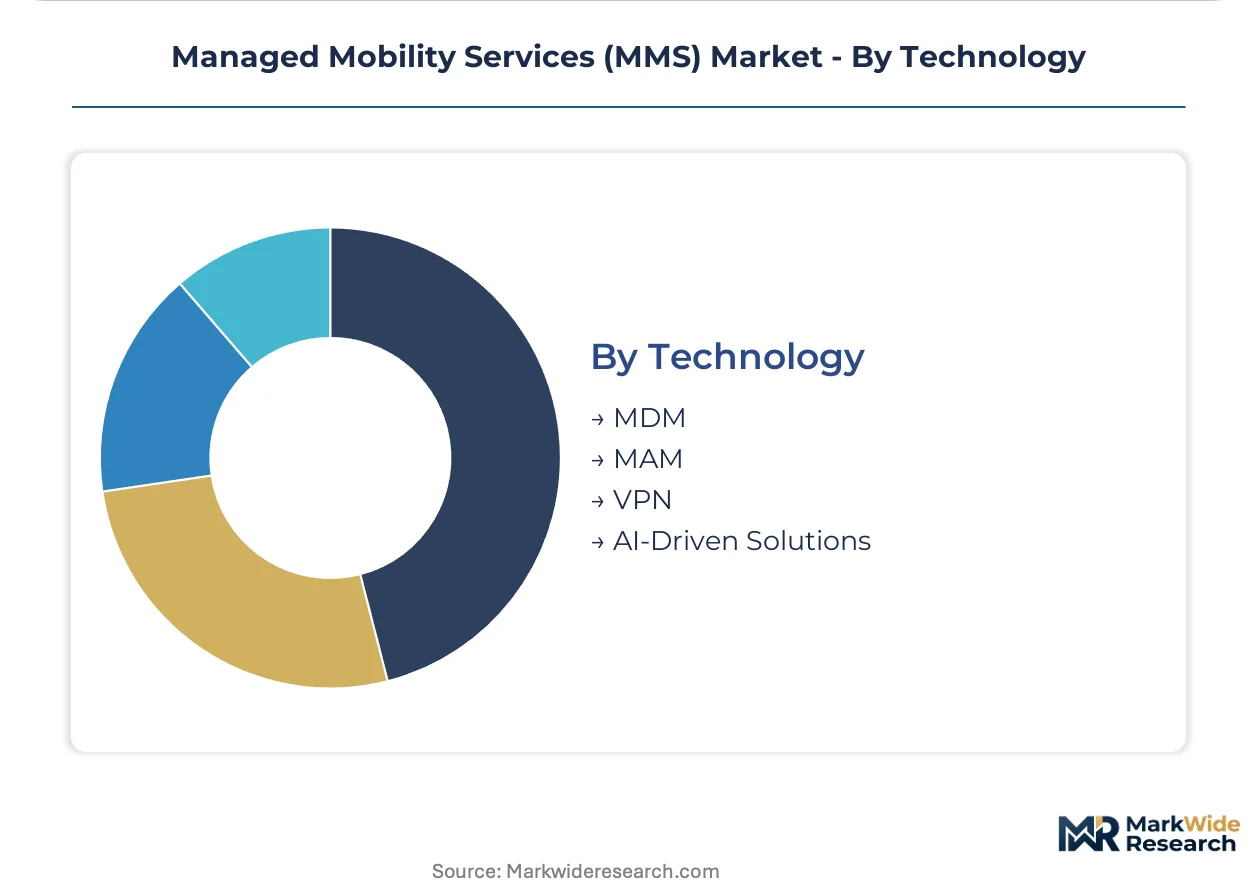
Technology:
Maturity gradients separate established Mobile Device Management protocols from emerging AI-driven threat detection capabilities.
- MDM:Provides foundational device enrollment, configuration profile distribution, and remote wipe capabilities across iOS and Android ecosystems. Legacy deployments persist across educational institutions and government organizations with limited cybersecurity staffing. The technology faces margin compression as platforms consolidate toward unified endpoint management.
- AI-Driven Solutions:Deploys machine learning models for behavioral anomaly detection and predictive security posture scoring. United States financial services enterprises pilot these capabilities for zero-trust continuous verification. EU AI Act risk classification requirements mandate algorithmic transparency dashboards for automated endpoint decisions in Germany and France.
- MAM:Isolates corporate applications and data within encrypted containers without full device control.
- VPN:Secures data transmission across untrusted networks with split-tunneling optimization for bandwidth efficiency.
MDM retains installed base dominance; AI-Driven Solutions are expanding most quickly as CISOs demand predictive threat capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fortune 500 headquarters in the United States concentrate enterprise mobility procurement decisions. FCC wireless spectrum allocations and carrier interoperability standards shape vendor qualification requirements across North American deployments. GDPR and EU AI Act mandates in Europe redirect investment toward certified data residency controls.
United States
Hybrid workforce permanence sustains demand for unified endpoint management across distributed employee populations. FCC guidelines on device certification and wireless spectrum allocation govern multi-carrier interoperability for enterprise accounts. Chicago and Dallas logistics corridors commission ruggedized mobility deployments for warehouse automation and field service operations.
Germany
Automotive and pharmaceutical manufacturers commission private 5G network infrastructure requiring managed service overlays for spectrum optimization. EU AI Act risk classification mandates algorithmic transparency dashboards for automated endpoint security decisions. Bavarian automotive clusters deploy hybrid cloud architectures to satisfy works council data localization demands.
United Kingdom
Financial services and healthcare enterprises prioritize security management segments amid GDPR breach notification requirements. ISO 27001 certification shapes vendor selection criteria for cloud-native platform deployments. London financial district and Manchester healthcare technology corridors standardize on unified endpoint management within compressed refresh cycles.
India
Mid-market manufacturers and pharmaceutical distributors lack dedicated IT mobility functions, creating whitespace for subscription-based managed services. TRAI mobile number portability regulations influence carrier switching flexibility for enterprise accounts. Maharashtra and Gujarat industrial belts represent underpenetrated demand with localized Hindi support requirements.
South Korea
Electronics manufacturing verticals commission dedicated wireless infrastructure with managed service overlays for device provisioning. National spectrum policy supports private 5G deployments for industrial automation. Seoul metropolitan area and Busan logistics hubs anchor demand for cloud-native orchestration platforms with real-time analytics.
Managed Mobility Services (MMS) Market Competitive Landscape
Established providers occupy the standard tier; emerging entrants pursue AI-driven security integration and circular logistics services. The vendor base stratifies across telecom expense management heritage, integrated hardware-software bundles, and ruggedized vertical specialists. Three archetypes dominate: negotiation-heavy incumbents with carrier relationships, diversified technology conglomerates with lifecycle logistics capabilities, and niche players commanding premium pricing in durability-critical deployments. Competitive moves concentrate on strategic partnerships for zero-trust architecture integration and portfolio diversification into sustainability compliance services.
Among negotiation-focused service providers, Tangoe leverages extensive telecom expense management heritage to anchor multi-carrier capabilities for enterprise accounts. Fujitsu sustains positioning through integrated hardware-software service bundles spanning device lifecycle logistics. Stratix Corporation occupies a specialist position in ruggedized mobility deployments, dominating warehouse automation and field service verticals where device durability commands premium pricing structures.
| Leading Market Players |
|---|
| Brightfin |
| DMI |
| Stratix Corporation |
| Motorola Solutions |
| Fujitsu |
| Motus |
| DecisionPoint Technologies |
| Tangoe |
| Commbitz |
| Others |
Supply & Pricing Matrix
Zero-trust architecture skill scarcity in the United States and Germany widens pricing-tier spreads between premium security-integrated MMS bundles and basic device-management subscriptions, compressing margins for vendors lacking certified personnel pools.
Pricing Analysis
Input-cost pass-through from semiconductor fabrication constraints and certified cybersecurity labor shortages shapes contract structures across the MMS landscape. Three-tier pricing structure across premium, standard, and economy levels separates AI-driven threat detection platforms with EU AI Act compliance dashboards from basic MDM configurations. Price differentiation hinges on ISO 27001 certification tier and customization depth for hybrid cloud deployments. Pricing pressure stems from carrier consolidation in the United States limiting multi-carrier negotiation leverage. Mid-market pharmaceutical distributors in India exhibit highest price sensitivity; Fortune 500 manufacturers with warehouse automation mandates show lowest.
Supply Chain Analysis
Reverse-logistics flows for device refurbishment and e-waste recycling gain structural importance as European CSRD mandates require carbon footprint disclosure across mobility fleets. Component sourcing concentrates in Taiwan for semiconductor fabrication, China for battery cell production, and Vietnam for final device assembly. Raw material dependencies span lithium-ion cells, ruggedized display panels, and 5G modem chipsets. Single-source vulnerability in advanced chipset supply creates procurement risk for enterprise refresh cycles. Distribution runs through carrier-direct channels, systems integrators, and managed service providers with regional help desk capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in MMS rests on automation-driven cost compression in device provisioning workflows and premium-tier migration toward AI-integrated security platforms with outcome-based pricing.
For Market Incumbents: Deepen vertical integration into reverse-logistics and circular device lifecycle services to capture CSRD compliance revenue streams. Fortify zero-trust architecture professional services capabilities against emerging AI-native security vendors. Prioritize certification investment in FedRAMP and ISO 27001 to defend public sector and regulated vertical positioning.
For New Entrants and Emerging Players: Launch via subscription-based managed services targeting mid-market manufacturers and pharmaceutical distributors in Maharashtra and Gujarat industrial belts with localized Hindi support. Exploit whitespace in India enterprise mobility where dedicated IT functions remain underdeveloped. Pursue outcome-based contracting anchored to security incident response metrics rather than per-device fees.
For Investors and Strategic Acquirers: Telecom expense management specialists with carrier negotiation heritage are the most active acquirer in this space, seeking security-operations convergence capabilities. Long-term viability favors vendors with unified endpoint management platforms spanning mobile, desktop, and IoT administration. Monitor private 5G network deployment velocity in German automotive and South Korean electronics manufacturing as inflection indicator for managed service overlay demand.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Endpoint Detection Integration | EU AI Act algorithmic transparency mandates in Germany and France require embedded compliance dashboards. |
| Reverse-Logistics and Circular Services | CSRD sustainability reporting positions e-waste recycling as premium compliance revenue stream. |
| Private 5G Network Managed Overlays | Bavarian automotive clusters and Busan logistics hubs commission spectrum optimization services. |
| Zero-Trust Architecture Professional Services | Enterprise IT departments lack micro-segmentation proficiency, forcing vendor reliance. |
| Unified Endpoint Management Platform Consolidation | Financial services in London and Manchester standardize on single policy engines within compressed refresh cycles. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with CISOs, IT procurement officers, carrier account executives, and systems integration specialists alongside secondary validation. Primary fieldwork draws from FCC regulatory filings, GDPR implementation guidance, TRAI mobile number portability records, and hyperscaler capex disclosures for cloud infrastructure investment patterns. Bottom-up device deployment modeling triangulates against top-down enterprise mobility budget allocations.
Rate-of-change decomposition separates volume growth from value-per-unit expansion across the analysis window. Segmentation dimensions include service type, deployment model, organization scale, vertical industry, and regional regulatory cluster. CAGRs derive from logistic curve fitting of enterprise adoption patterns and technology refresh cycle compression. Forecast inputs incorporate 5G private network deployment pipelines and AI-driven security platform pilot program scaling trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carrier consolidation acceleration or semiconductor supply disruption scenarios. Practitioners should monitor EU AI Act enforcement intensity, private 5G spectrum auction velocity, and mid-market India subscription adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Argentina ICT Market
Telecommunications
Belgium ICT Market
Telecommunications
Sri Lanka Telecom Market
Telecommunications
Norway Telecom Market
Telecommunications
Ireland Telecom Market
Telecommunications
Land Professional Mobile Radio Market
Telecommunications
Global GPON Technology Market
Telecommunications
Fixed Voice Market
Telecommunications
Indonesia Communication Services Market
Telecommunications
Virtualized RAN (Vran) Market
Telecommunications
Tetra Terminals Market
Telecommunications
5G Technology Market
Telecommunications
Utility Communications Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Indonesia Volte Market
Telecommunications
Vietnam Telecom Market