
 5G System Integration Market | 2026-2036
5G System Integration Market Size, Share, and Industry Trends Forecast 2026-2036
5G System Integration Market Intelligence
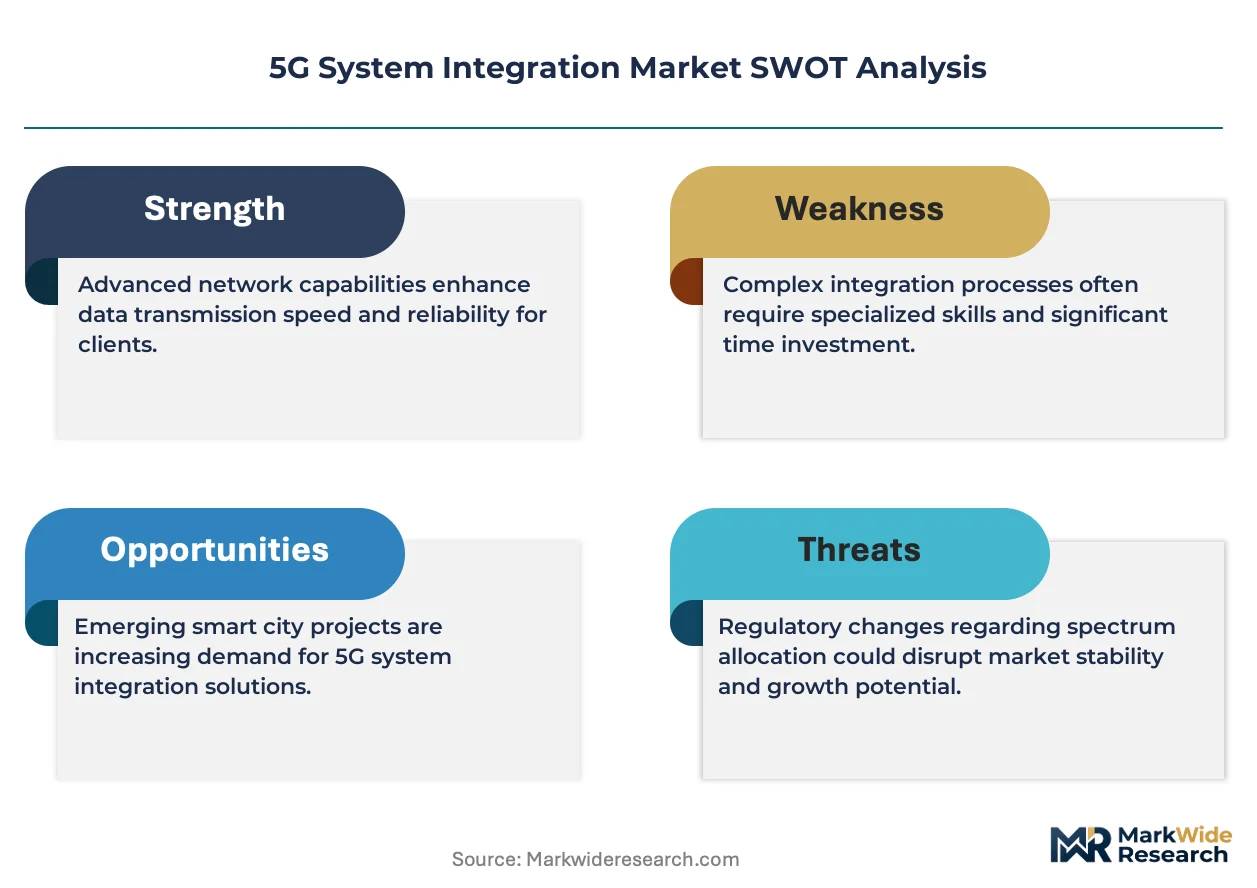
Open RAN disaggregation is reconfiguring how 5G networks are architected, forcing system integrators to orchestrate multi-vendor interoperability layers rather than monolithic deployments. Samsung Electronics leverages its semiconductor-to-radio vertical stack to dominate baseband integration complexity. Ericsson anchors European operator confidence through its cloud-native portfolio, while Nokia competes aggressively in private wireless system design for industrial campuses.
5G system integration encompasses the engineering, testing, and deployment services that unify radio access networks, core infrastructure, and edge computing resources into production-grade connectivity platforms. The discipline requires sub-millisecond latency validation, end-to-end network slicing orchestration, and seamless handoff between macro cells and distributed antenna systems for mission-critical applications. Managed services and integration segments capture the deepest margin pools as operators outsource operational complexity rather than building in-house competencies. Edge computing and network slicing technologies are expanding fastest as enterprises demand localized processing for industrial IoT and connected vehicle workloads.
FCC spectrum auctions and equipment authorization rules shape vendor market access in the United States, while the EU AI Act and cybersecurity certification schemes impose binding security requirements on 5G infrastructure procurement. China's MIIT enforces domestic GB standards and dual carbon goals that filter foreign participation in national deployments. Stakeholders must monitor evolving national security review mechanisms that increasingly classify 5G integration contracts as critical infrastructure subject to foreign investment screening.
Market Dynamics
Open RAN disaggregation is fragmenting vendor hierarchies and forcing system integrators to engineer interoperability layers across multi-vendor radio units, distributed units, and centralized units. This architectural rupture demands new testing protocols and orchestration competencies that reshape margin structures across the integration value chain.
Growth Catalysts
- Smart city infrastructure mandates:Municipal governments in China, Germany, and South Korea are embedding 5G connectivity into traffic management, public safety, and utility grids, generating sustained integration contracts for neutral host networks.
- FCC spectrum auction outcomes:Mid-band allocation in the United States unlocked C-band deployment capital, compelling operators to accelerate system integration timelines for nationwide coverage targets.
- Private wireless campus demand:Manufacturing facilities and logistics hubs are procuring dedicated 5G networks for deterministic latency, creating specialized integration requirements distinct from public macro deployments.
Market Restraints
- Semiconductor supply concentration:Advanced baseband processor fabrication depends on Taiwan-based foundry capacity, exposing integration timelines to geopolitical disruption and allocation constraints.
- EU cybersecurity certification friction:The EU's 5G cybersecurity toolbox imposes vendor qualification delays and supply chain audit requirements that extend procurement cycles for European operators.
- Optical transport cost volatility:Fiber backhaul and coherent optics pricing fluctuates with rare earth element markets, compressing margins on rural and suburban deployment projects.
Strategic Opportunities
- India spectrum liberalization:TRAI's 5G spectrum pricing reforms and PLI scheme incentives are attracting system integrators to establish local engineering centers for subcontinent-wide deployment programs.
- Network slicing monetization:The convergence of 5G core virtualization and edge computing enables guaranteed service-level agreements for enterprise verticals, creating recurring integration revenue streams.
- Neutral host infrastructure models:Third-party tower companies and real estate investment trusts are emerging as primary 5G deployment sponsors, bypassing traditional operator procurement channels.
Industry Challenges
- Multi-vendor interoperability validation:Open RAN deployments require exhaustive lab testing across radio unit, distributed unit, and centralized unit combinations, extending project timelines and escalating engineering headcount requirements.
- Legacy 4G core migration complexity:Operators maintaining non-standalone 5G architectures face intricate handoff engineering between evolved packet cores and 5G standalone cores, complicating subscriber management integration.
- Sub-6 GHz and mmWave coexistence optimization:System integrators must engineer seamless mobility between coverage-layer and capacity-layer spectrum, demanding specialized propagation modeling and antenna calibration expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G System Integration Market |
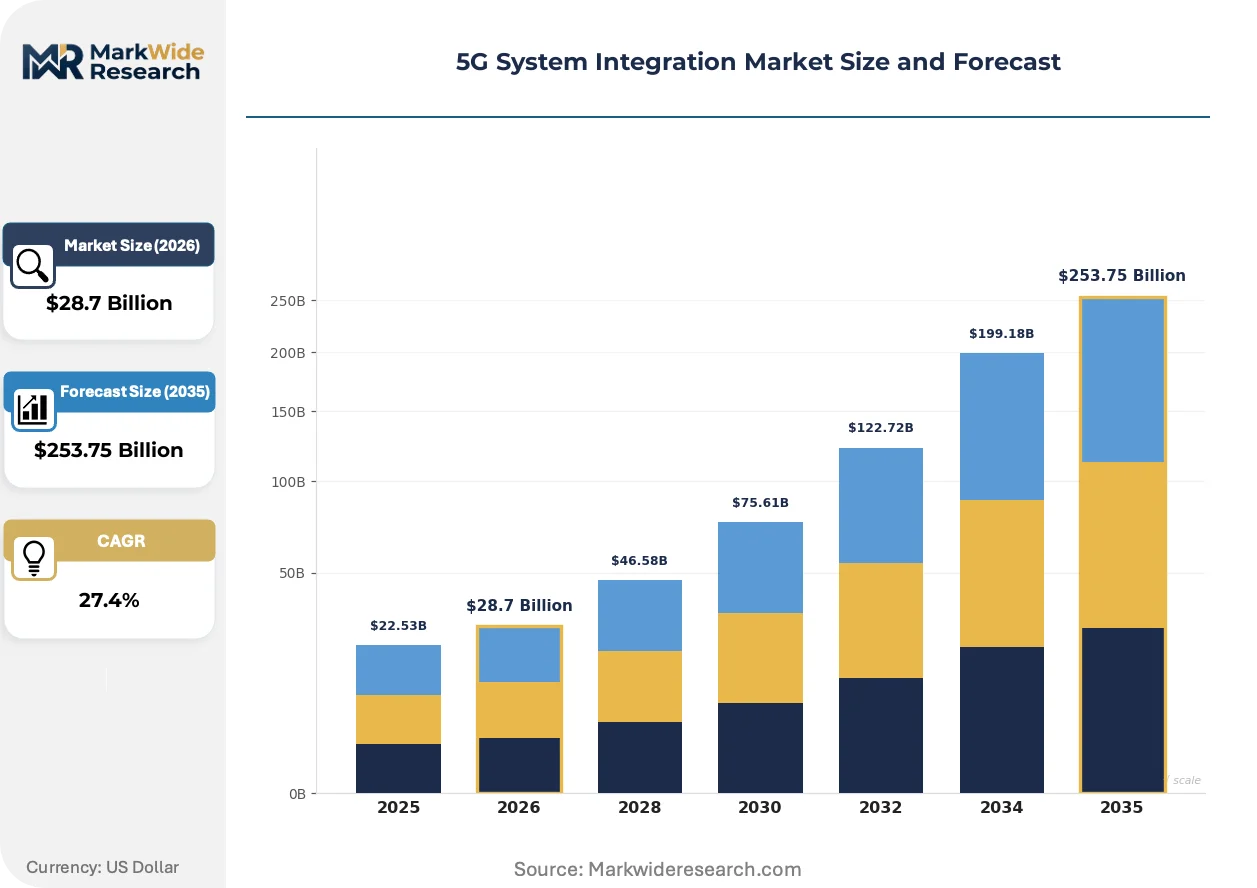
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $253.75 Billion |
| CAGR (2026 – 2036) | 27.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Cities, Industrial IoT, Healthcare, Connected Vehicles Service Type: Consulting, System Design, Integration, Managed Services Technology: Network Slicing, Edge Computing, Cloud-Native, Software-Defined Networking End User: Telecom Operators, Enterprises, Government, Utilities |
| Companies Covered | Samsung Electronics, JMA Wireless, Ericsson, Amphenol, SOLiD, Nokia, Corning, Parallel Wireless, Huawei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G System Integration Market Strategic Shifts & Innovations
Containerized network functions and cloud-native core architectures are displacing appliance-based infrastructure, compressing hardware refresh cycles and elevating software engineering competencies within integration contracts.
Virtualized radio access network (vRAN) technology is virtualizing baseband processing functions onto commercial off-the-shelf servers, collapsing proprietary hardware dependencies. Tier-1 operators in Japan and the United States are deploying vRAN at scale for urban dense deployments. This transition is virtualizing capital allocation patterns, shifting expenditure toward server infrastructure and orchestration software while commoditizing traditional radio equipment margins.
The EU AI Act and accompanying cybersecurity certification schemes are binding artificial intelligence governance requirements to 5G infrastructure procurement. Equipment vendors must now document algorithmic transparency and risk management protocols for network automation functions. European industrial campuses and smart city authorities are responding by inserting AI audit clauses into integration contracts, extending vendor qualification timelines.
Enterprise buyers are consolidating procurement authority for private wireless networks under chief information officers rather than facilities or operations departments. System integrators are responding with IT-centric service models that emphasize API-driven network management and cloud billing integration. This pattern is most pronounced in German automotive manufacturing and South Korean semiconductor fabrication facilities, where OT-IT convergence accelerates.
5G System Integration Market Segmentation
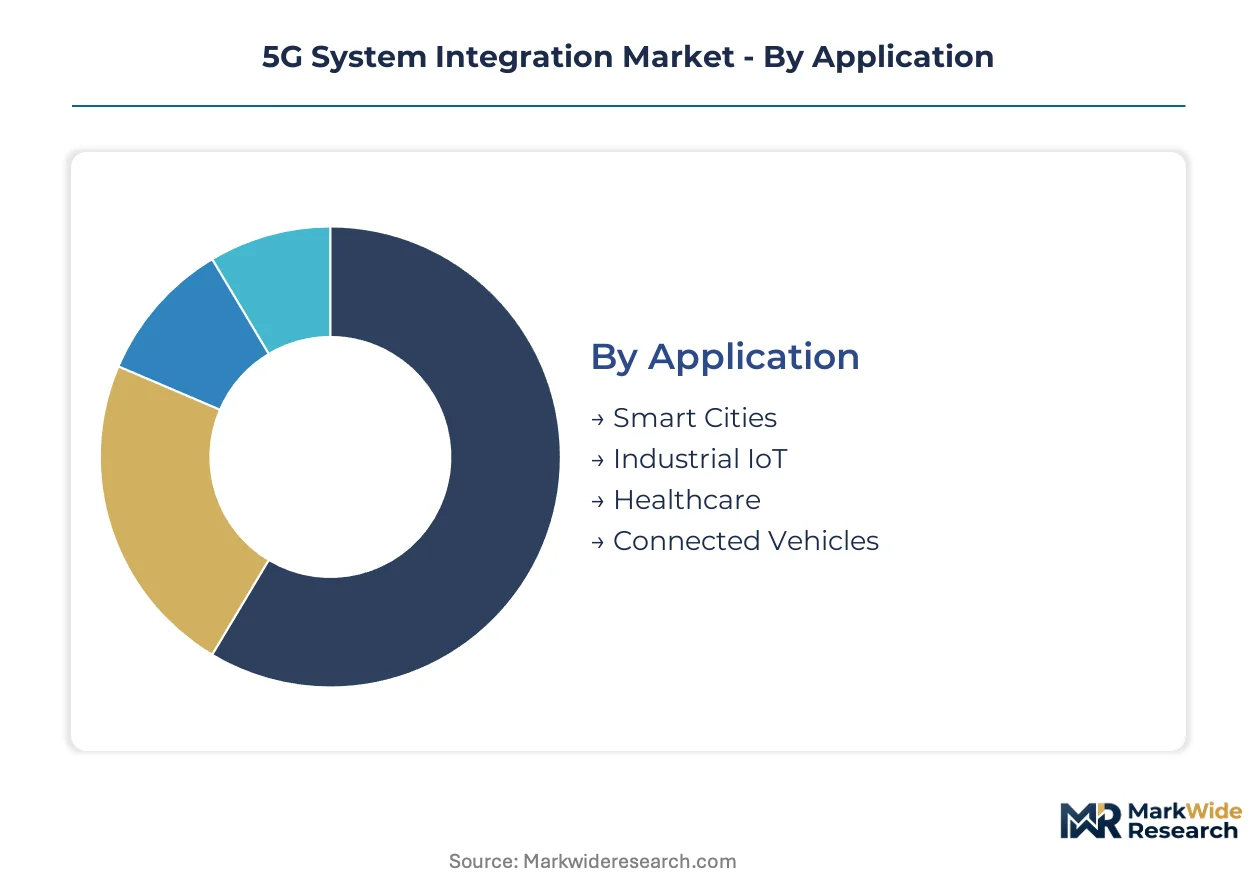
Segmentation in 5G system integration reveals distinct margin profiles and contract durations across service types, with technology layers cycling faster than infrastructure buildouts. Understanding these velocity differentials enables integrators to allocate engineering resources and pricing power effectively.
Application:
Cycle times compress from municipal procurement cycles exceeding 36 months to industrial deployments closing in under 12 months, reshaping how integrators stage their delivery organizations.
- Smart Cities:Municipal infrastructure mandates span traffic management, public safety networks, and utility grid modernization. Contracts concentrate in China, Germany, and South Korea where governments embed connectivity into master planning frameworks.
- Industrial IoT:Manufacturing facilities and logistics hubs demand deterministic latency for robotic control and automated guided vehicles. German automotive plants and South Korean semiconductor fabrication facilities are consolidating procurement under CIO authority.
- Healthcare:Remote surgery and connected ambulance networks require sub-millisecond reliability validation. Hospital systems prioritize FDA-compliant integration protocols over speed-to-deployment.
- Connected Vehicles:V2X roadside unit deployment follows automotive OEM release schedules, creating lumpy demand tied to model year cycles.
Smart Cities anchors the volume base while Industrial IoT gains share at the steepest rate.
Service Type:
Margin concentration follows complexity escalation from advisory work through operational handover, with recurring managed services capturing the deepest profit pools.
- Consulting:Spectrum strategy and vendor selection advisory commands premium pricing during initial deployment phases. European operators facing EU cybersecurity certification friction extend procurement cycles, increasing advisory attach rates.
- System Design:Radio access network planning and core architecture specification demands specialized propagation modeling expertise. Projects scale with mmWave and sub-6 GHz coexistence requirements.
- Integration:Multi-vendor interoperability testing and orchestration layer engineering constitutes the largest headcount deployment. Open RAN disaggregation is fragmenting vendor hierarchies and forcing exhaustive lab validation protocols.
- Managed Services:Operational outsourcing of network functions generates recurring revenue streams with 3-5 year contract tenors. Operators are building in-house competencies more slowly than planned, extending vendor retention.
Integration commands the largest absolute contract value while Managed Services delivers the most predictable cash flow profile.
Technology:
Adoption velocity stratifies between proven virtualization layers and emerging orchestration capabilities still maturing in production environments.
- Network Slicing:5G core virtualization enables guaranteed service-level agreements for enterprise verticals. Manufacturing campuses in Japan and the United States are deploying slicing at scale for quality-of-service differentiation.
- Edge Computing:Localized processing for industrial IoT and connected vehicle workloads is expanding fastest. Containerized network functions displace appliance-based infrastructure, compressing hardware refresh cycles.
- Cloud-Native:Containerized core architectures elevate software engineering competencies within integration contracts. Tier-1 operators prioritize cloud-native portfolios for operational flexibility.
- Software-Defined Networking:Transport layer programmability supports dynamic bandwidth allocation across converged access and core networks. Maturity lags radio virtualization by approximately 18-24 months.
Edge Computing is climbing the fastest as enterprise buyers demand localized processing, while Software-Defined Networking matures more gradually.
End User:
Procurement authority concentration varies sharply, with enterprise buyers consolidating under CIOs while utilities fragment across regional operating companies.
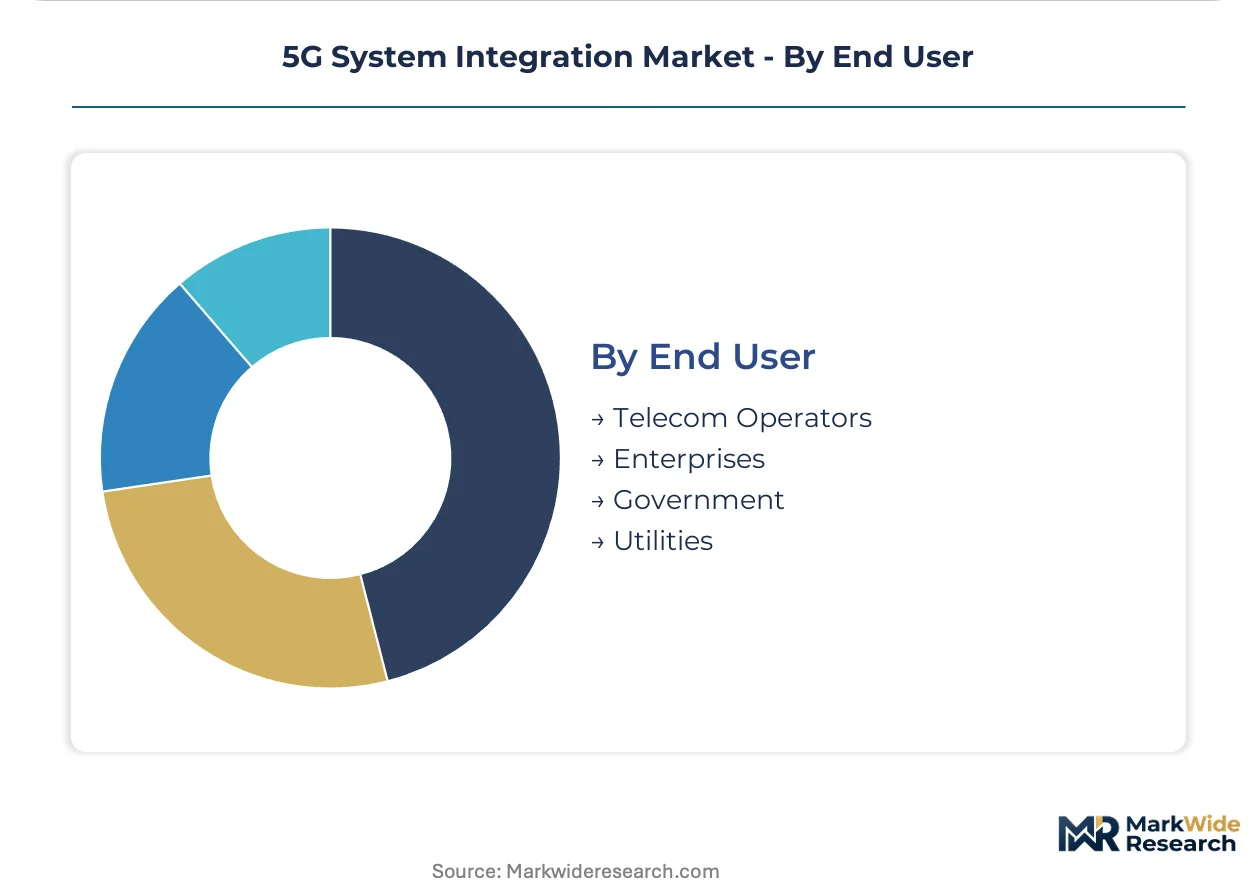
- Telecom Operators:Public macro network buildouts constitute the foundational revenue base. FCC spectrum auction outcomes and MIIT infrastructure targets in China are accelerating nationwide coverage timelines.
- Enterprises:Private wireless campus networks for deterministic latency are creating specialized integration requirements distinct from public deployments. OT-IT convergence acceler in automotive and semiconductor manufacturing.
- Government:Defense and public safety networks impose stringent security certification requirements. National security review mechanisms increasingly classify integration contracts as critical infrastructure.
- Utilities:Smart grid and distributed energy resource management drive sustained integration demand. Procurement fragments across regional operating companies with varying technical maturity.
Telecom Operators anchor the volume base while Enterprises expand most quickly as private network adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in 5G system integration equipment and services reveal pronounced asymmetries, with China running substantial integration service surpluses while the United States and Germany maintain deficits offset by technology licensing revenues. Capital equipment flows concentrate in East Asian manufacturing clusters, creating dependency patterns that reshape procurement strategies.
United States
Mid-band spectrum deployment and private wireless campus networks drive integration demand across manufacturing and logistics sectors. FCC spectrum auctions and equipment authorization rules govern vendor market access and deployment timelines. Integration contracts concentrate in Dallas-Fort Worth and Detroit automotive corridors, where Tier-1 suppliers are deploying deterministic latency networks.
China
MIIT infrastructure targets and smart city master planning generate sustained large-scale integration contracts for municipal connectivity. Domestic GB standards and dual carbon goals filter foreign participation in national 5G buildouts. Yangtze River Delta clusters around Shanghai and Suzhou anchor the highest density of private network deployments for semiconductor fabrication.
Germany
Industrial IoT adoption in automotive manufacturing and OT-IT convergence accelerate private 5G procurement under consolidated CIO authority. EU cybersecurity certification schemes and the EU AI Act impose binding vendor qualification requirements. Bavarian automotive plants around Munich and Ingolstadt represent Europe's densest concentration of campus network integration projects.
South Korea
Smart city infrastructure mandates and connected vehicle V2X deployment create synchronized demand across public and private networks. METI-aligned spectrum policies and national 5G coverage targets compress integration timelines. Seoul Capital Area and Busan-Ulsan manufacturing corridors host the most advanced network slicing implementations for quality-of-service differentiation.
India
TRAI spectrum pricing reforms and PLI scheme incentives attract system integrators to establish local engineering centers for subcontinent-wide programs. Government procurement preferences for domestic value-added reshape vendor qualification. Maharashtra and Gujarat industrial zones are emerging as primary concentration points for manufacturing campus private networks.
5G System Integration Market Key Industry Players
On the supply side, the industry is consolidating around three distinct capability tiers: full-stack infrastructure vendors, specialized radio access integrators, and cloud-native orchestration specialists. Strategic archetypes include semiconductor-to-radio vertical integrators, open RAN interoperability enablers, and edge computing platform architects. Dominant competitive moves encompass strategic partnerships for multi-vendor certification and geographic expansion through local engineering center establishment.
Within the full-stack infrastructure tier, Samsung Electronics, Ericsson, and Nokia occupy positions that exemplify divergent architectural bets. Samsung Electronics anchors the semiconductor-to-radio vertical integration archetype through its captive silicon and radio unit manufacturing. Ericsson exemplifies the cloud-native portfolio approach that European operators favor for operational flexibility. Nokia represents the private wireless specialization vector, with industrial campus system design capabilities that manufacturing buyers prioritize. These three vendors collectively illustrate how integration complexity is fragmenting competitive advantage across hardware, software, and vertical-specific service layers.
| Leading Market Players |
|---|
| Samsung Electronics |
| JMA Wireless |
| Ericsson |
| Amphenol |
| SOLiD |
| Nokia |
| Corning |
| Parallel Wireless |
| Huawei |
| Others |
Cost & Logistics Intelligence
Semiconductor supply concentration in Taiwan-based foundry capacity exposes integration timelines to geopolitical disruption while simultaneously compressing pricing spreads between premium certified and standard-tier deployment packages. This single-source dependency for advanced baseband processors forces system integrators to absorb allocation risk premiums into project quotes, widening the cost gap between mission-critical and best-effort service tiers.
Pricing Analysis
Standalone 5G core deployments command premium pricing over non-standalone architectures due to complex subscriber management handoff engineering requirements. Three-tier pricing structure across premium certified, standard compliant, and economy-tier integration levels reflects EU cybersecurity certification friction and FCC equipment authorization compliance costs. Pricing pressure stems from optical transport cost volatility in fiber backhaul markets, with rare earth element price swings compressing margins on rural deployment projects. Enterprise buyers consolidating procurement under CIO authority demonstrate lowest price sensitivity, while municipal governments in smart city tenders exhibit highest bid-driven compression.
Supply Chain Analysis
Export control restrictions on advanced semiconductor manufacturing equipment limit foundry capacity expansion in China, constraining global baseband processor availability. Supply concentrates in Taiwan, South Korea, and the United States for advanced chip fabrication, while radio unit assembly clusters in China and Vietnam. Raw material dependencies span gallium nitride substrates, rare earth elements for RF components, and high-purity silicon wafers. Single-source vulnerability in Taiwan-based advanced node production represents the dominant structural risk. Distribution runs through Tier-1 operator procurement channels, neutral host infrastructure sponsors, and direct enterprise campus contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed services and recurring integration revenue streams expand faster than hardware-centric deployment contracts, creating service-attach opportunities that deepen vendor retention and margin capture.
For Market Incumbents: Insulate core relationships by embedding managed services contracts with 3-5 year tenors before competitors establish orchestration layer footholds. Invest in multi-vendor Open RAN certification labs to defend against specialized radio access integrators. Prioritize backward integration into captive baseband silicon supply to offset Taiwan foundry allocation constraints.
For New Entrants and Emerging Players: India spectrum liberalization under TRAI pricing reforms offers the most penetrable geographic entry point for subcontinent-wide engineering center establishment. Target private wireless campus networks in German automotive manufacturing corridors where OT-IT convergence accelerates CIO-led procurement consolidation. Lead with IT-centric API-driven service models rather than traditional radio engineering positioning.
For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors cloud-native orchestration specialists over hardware-centric vendors. Long-term viability across the projection horizon hinges on software engineering competencies and edge computing platform architecture. Monitor EU AI Act compliance timeline acceleration as the primary inflection signal for vendor qualification cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Vendor Certification Lab Investment | Open RAN interoperability testing capabilities differentiate integrators in European operator procurement. |
| Edge Computing Platform Development | Containerized network functions capture enterprise verticals demanding localized processing for industrial IoT. |
| Managed Services Capability Buildout | Recurring revenue streams extend vendor retention as operators delay in-house competency development. |
| Geographic Engineering Center Expansion | Local presence in India and Southeast Asia aligns with spectrum liberalization and PLI scheme incentives. |
| Cloud-Native Core Architecture Migration | Software engineering competencies displace appliance-based infrastructure in Tier-1 operator evaluations. |
Research Approach
Desk research of regulatory filings, spectrum auction outcomes, and equipment authorization databases preceded structured interviews with network engineering directors, procurement leads at Tier-1 operators, system integration project managers, and edge computing platform architects. Secondary validation drew from FCC auction records, MIIT infrastructure target disclosures, EU cybersecurity certification scheme documentation, and customs trade data for baseband processor flows. Bottom-up project pipeline analysis triangulated against top-down infrastructure spend estimates.
Forecast assumptions held spectrum allocation timelines, export control regimes, and carbon neutrality policy trajectories within observed patterns across the analysis window. Segmentation dimensions modeled include service type complexity tiers, application vertical velocity differentials, technology layer adoption curves, and end-user procurement authority concentration. CAGRs derived from weighted scenario analysis across infrastructure buildout, enterprise private network, and smart city deployment pathways. Industry-specific inputs encompassed Open RAN disaggregation pace, vRAN virtualization penetration, and network slicing monetization maturity.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by semiconductor-to-radio stack vendors would shift competitive outcomes. Material shifts in Taiwan Strait stability, EU cybersecurity certification acceleration, or India PLI scheme expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Digital Mobile Radio (DMR) Market
Telecommunications
LTE and 5G NR-Based CBRS Networks Market
Telecommunications
IP PBX Market
Telecommunications
Promotional Sms Market
Telecommunications
Denmark Telecom Market
Telecommunications
Diameter Signaling Control Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Cellular Modem Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
CDMA Mobile Phone Market
Telecommunications
Global Virtual PBX Market
Telecommunications
Global Dense Wave Digital Multiplexing (DWDM) System Market
Telecommunications
Free Space Optics (FSO) Communication Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
Singapore Telecom Market