
 Asia-Pacific IPTV Market | 2026-2036
Asia-Pacific IPTV Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific IPTV Market Insights
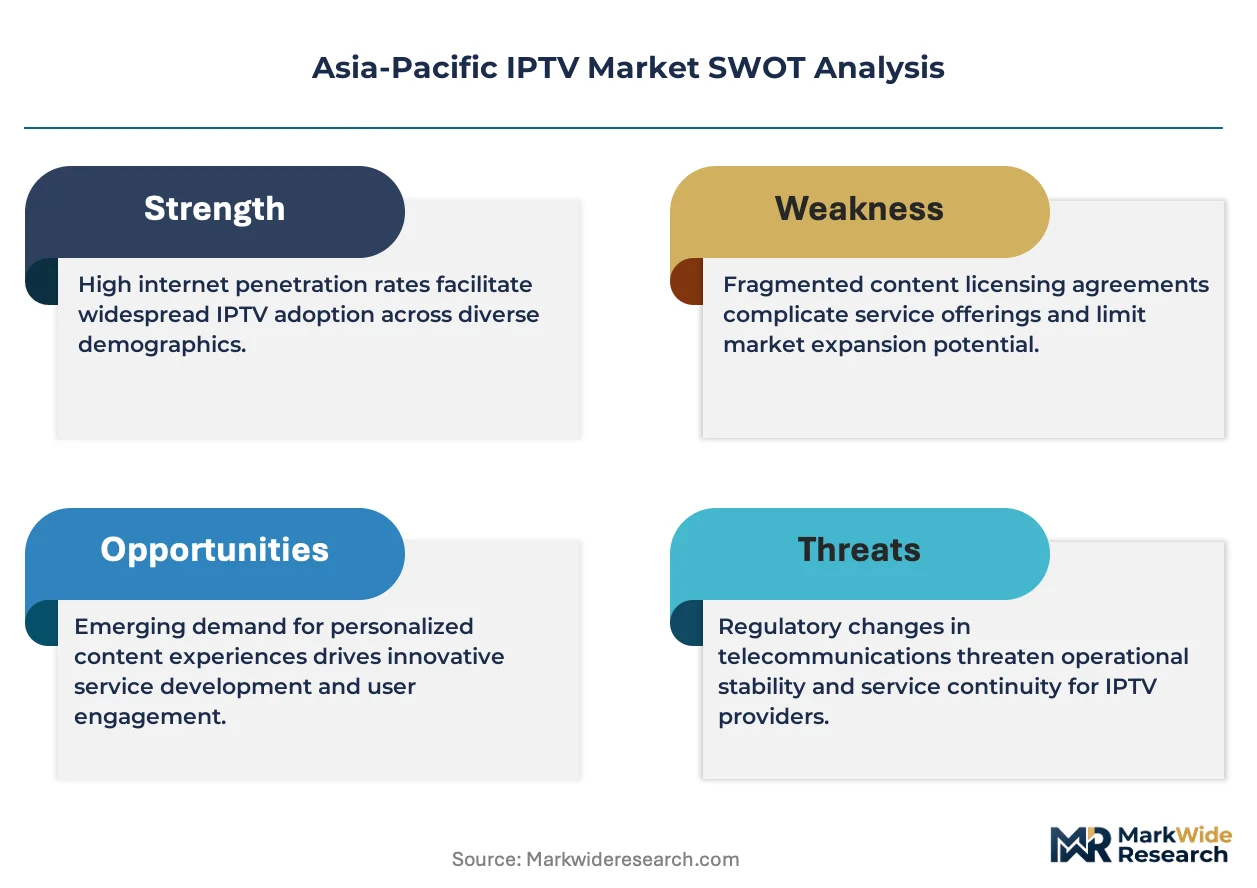
Shortages of fiber-optic technicians and cloud-native video engineers is collapsing deployment timelines across Southeast Asian markets. China Telecom Corporation Limited leverages its state-backed fiber backbone to dominate provisioning in provincial hubs. Reliance Jio Infocomm Limited anchors its expansion through aggressive pricing and bundled mobile-IPTV convergence. KT Corporation differentiates via proprietary set-top integration and UHD content pipelines.
Internet Protocol Television delivers broadcast and on-demand video content over managed IP networks, typically requiring multicast-enabled core routers, MPEG-4/H.265 encoding, and quality-of-service guarantees for sub-200ms latency. Cloud-based deployment is capturing the fastest expansion as operators abandon capex-heavy on-premise headends for elastic CDN orchestration. Subscription services generate the deepest revenue pools, while ad-supported tiers are gaining traction in price-sensitive Indonesian and Philippine metros where freemium trials convert to paid tiers at slower velocity.
TRAI in India enforces tariff disclosure and interconnection rules that compress bundling margins yet expand addressable subscriber bases. China's MIIT mandates GB-standard encryption and content licensing through SAMR-aligned protocols, raising compliance costs for foreign content aggregators. South Korea's MFDS and KCC frameworks govern broadcast-grade reliability standards that shape procurement specifications. Stakeholders must weigh regulatory fragmentation against the scale economics of unified content delivery platforms.
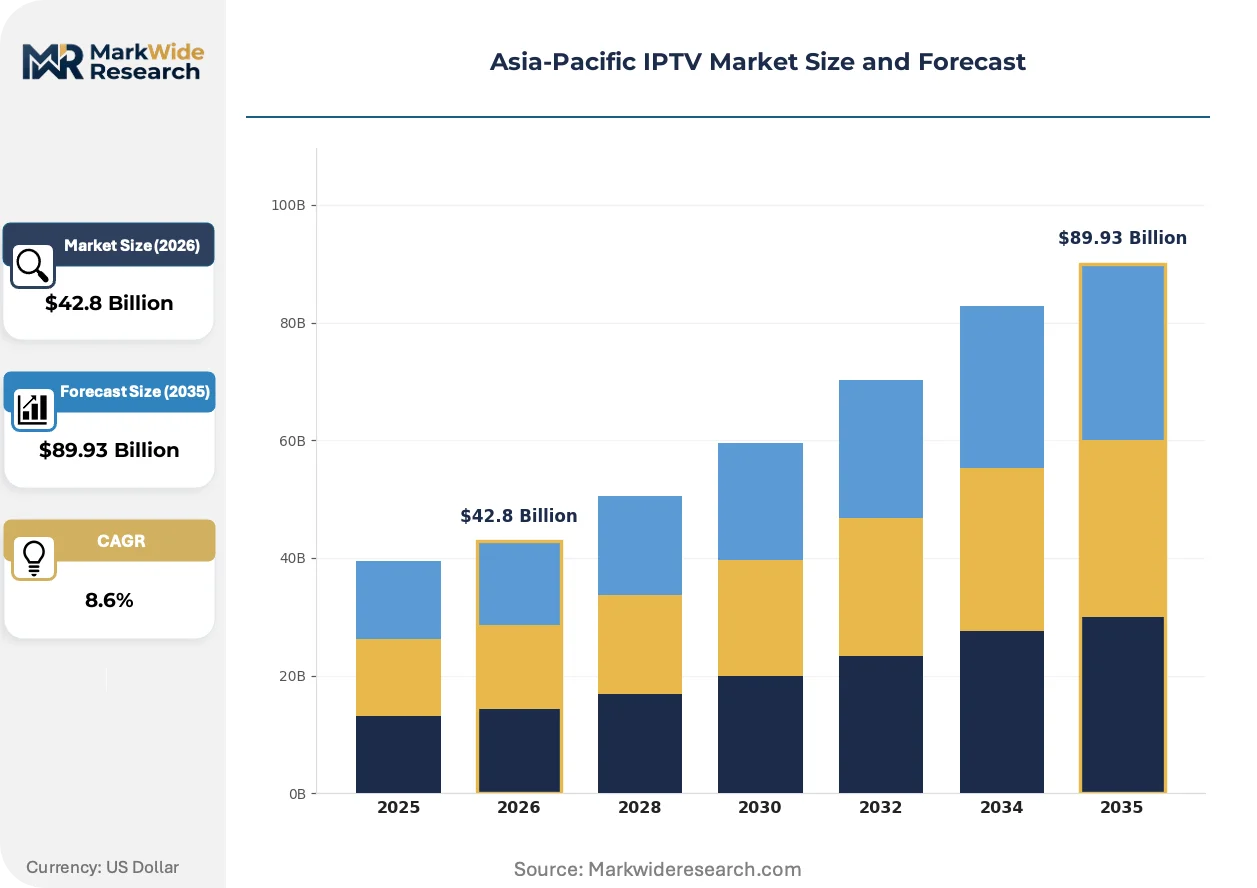
Market Dynamics
Fiber-to-the-home rollouts across tier-one Indian cities are compressing legacy cable infrastructure timelines while TRAI's tariff transparency mandates force carriers to unbundle video from broadband subscriptions.
Growth Catalysts
- Gigabit broadband penetration:South Korea's nationwide fiber backbone enables 4K and 8K IPTV streams that command premium subscriber fees.
- TRAI interconnection rules:India's tariff disclosure mandates expand addressable subscriber bases by prohibiting opaque bundling practices.
- Cloud-native CDN orchestration:Elastic infrastructure is displacing capex-heavy on-premise headends, accelerating deployment velocity for mid-tier operators.
Market Restraints
- Fiber-optic technician scarcity:Southeast Asian markets face collapsed deployment timelines due to insufficient skilled labor pools.
- GB-standard encryption compliance:China's MIIT mandates raise content licensing costs for foreign aggregators through SAMR-aligned protocols.
- Multicast router dependency:Core network upgrades requiring quality-of-service guarantees impose heavy capital burdens on tier-two carriers.
Strategic Opportunities
- Indonesian freemium conversion:Ad-supported tiers in price-sensitive Jakarta and Surabaya metros present subscriber acquisition white space.
- Mobile-IPTV convergence:Bundled smartphone and television subscriptions unlock cross-selling revenue streams in India's prepaid-dominant market.
- UHD content pipelines:KT Corporation's proprietary integration model demonstrates premium differentiation through broadcast-grade reliability standards.
Industry Challenges
- Cloud-native video engineer shortages:Elastic infrastructure deployment stalls where DevOps and streaming architecture expertise concentrates in Seoul and Singapore.
- Legacy set-top integration:Proprietary middleware from incumbent carriers complicates third-party application deployment and subscriber churn.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific IPTV Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $89.93 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, Managed Service Type: Subscription, Pay-per-view, Freemium, Ad-supported End User: Residential, Commercial, Educational, Hospitality Content Type: Live TV, Video on Demand, Catch-up TV, Web Series |
| Companies Covered | Reliance Jio Infocomm Limited, Singtel, China Telecom Corporation Limited, Telstra Corporation Limited, KT Corporation, SK Telecom Co., Ltd., Bharti Airtel Limited, PT Telekomunikasi Indonesia Tbk, NTT Communications Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific IPTV Market Trends and Innovations
H.265 encoding and edge-computing architectures are compressing latency thresholds while reshaping how operators provision live sports and interactive gaming content across the region.
HEVC compression is supplanting legacy MPEG-4 standards in live broadcast workflows. Tier-one carriers in Seoul and Mumbai are mandating H.265 compatibility for all new set-top deployments. This codec migration is supplanting bandwidth-hungry legacy streams, freeing network capacity for 8K trials and multi-view angle services.
TRAI's net neutrality enforcement prohibits zero-rating arrangements that previously subsidized video consumption. Indian carriers must now price broadband and IPTV as distinct line items, compressing bundling margins. Tier-two operators in Bangalore and Hyderabad are responding with skinny bundles that separate sports and movie tiers.
Subscriber self-provisioning through mobile applications is displacing technician-led installations. Younger demographics in Manila and Bangkok activate fiber-IPTV bundles without truck rolls, forcing carriers to simplify remote diagnostics. This channel shift concentrates support costs in digital onboarding rather than field operations.
Asia-Pacific IPTV Market Segmentation
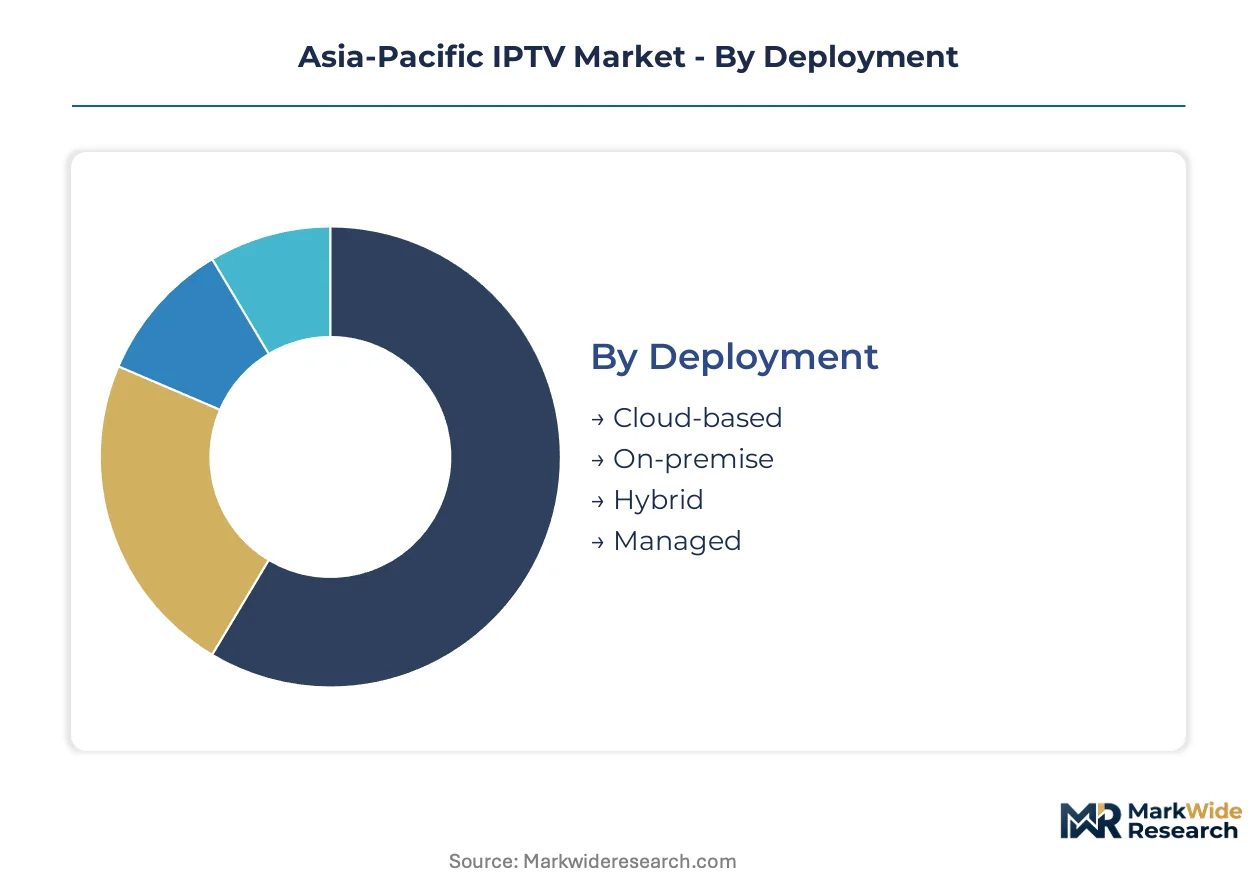
Segmentation across deployment architectures, service tiers, and content formats reveals where capital efficiency and subscriber lifetime value diverge across the Asia-Pacific IPTV landscape. Understanding these fault lines helps operators prioritize infrastructure bets and pricing architecture.
Deployment:
Margin pools concentrate in cloud-native orchestration as operators abandon depreciating on-premise assets for elastic consumption models.
- Cloud-based:Elastic CDN infrastructure enables mid-tier operators to provision multicast streams without core router ownership. Korean and Singaporean carriers are migrating live sports workflows to serverless architectures that scale with concurrent viewership spikes.
- On-premise:Dedicated headend hardware with MPEG-4/H.265 encoding clusters remains entrenched in provincial Chinese markets where MIIT mandates GB-standard encryption compliance. State-backed fiber operators absorb heavy capex burdens to maintain broadcast-grade control.
- Hybrid:Split architectures reserve live broadcast for edge nodes while cloud handles on-demand libraries. Indian tier-two operators in Bangalore deploy hybrid stacks to balance TRAI tariff transparency requirements against latency-sensitive cricket streaming.
- Managed:Outsourced network operations with SLA-backed quality-of-service guarantees appeal to Southeast Asian markets facing fiber-optic technician shortages. Vietnamese and Thai carriers contract managed services to compress deployment timelines.
Cloud-based holds installed capacity. Hybrid is rotating up the share rankings.
Service Type:
Revenue concentration tracks willingness-to-pay gradients across prepaid-dominant versus contract-based subscriber cultures.
- Subscription:Recurring monthly fees generate the deepest revenue pools in South Korea's gigabit-saturated markets. KT Corporation and SK Broadband lock subscribers into 24-month contracts bundled with UHD content pipelines.
- Pay-per-view:Transactional access to live sports and cinema releases captures premium extraction in India's price-fragmented metros. Reliance Jio monetizes IPL cricket and Bollywood premieres through micropayment integrations.
- Freemium:Ad-supported tiers with conversion gates to paid libraries are expanding most quickly in Indonesian and Philippine urban centers. Jakarta and Surabaya subscribers tolerate pre-roll advertising before upgrading to remove commercial breaks.
- Ad-supported:Pure advertising models sustain engagement in Bangladesh and Vietnam where disposable income constraints limit paid conversion. Local carriers optimize fill rates through programmatic insertion in catch-up TV windows.
Subscription holds installed capacity. Freemium is rotating up the share rankings.
End User:
Application intensity varies sharply between bandwidth-hungry residential streaming and commercial multi-screen deployments.
- Residential:Fiber-to-the-home subscribers across tier-one Indian cities and Seoul metropolitan areas drive volume. Gigabit broadband penetration enables 4K and 8K streams that command premium subscriber fees.
- Commercial:Enterprise IPTV for corporate campuses and co-working spaces requires multicast-enabled distribution with centralized content curation. Singaporean fintech clusters deploy commercial tiers for internal communications and market data visualization.
- Educational:University and K-12 deployments prioritize catch-up TV and archived lecture libraries. Philippine distance learning mandates accelerated educational IPTV provisioning during school closures.
- Hospitality:Hotel and hospital networks demand seamless roaming between in-room screens and personal devices. Thai hospitality chains integrate IPTV with property management systems for guest personalization.
Residential holds installed capacity. Commercial is rotating up the share rankings.
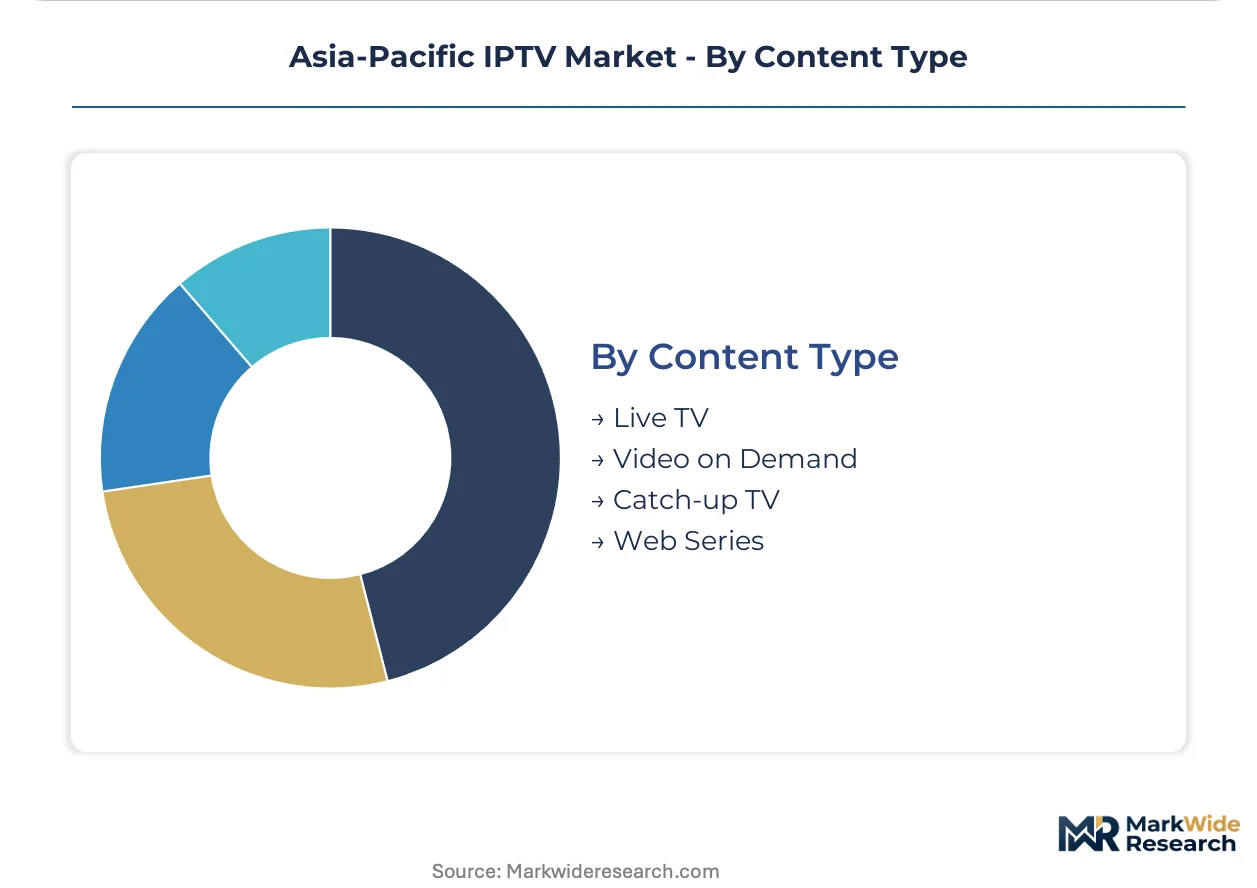
Content Type:
Technical specifications diverge between synchronous live broadcast and asynchronous on-demand delivery.
- Live TV:Real-time multicast streams with sub-200ms latency requirements dominate sports and news consumption. HEVC compression is supplanting legacy MPEG-4 standards in Seoul and Mumbai live broadcast workflows.
- Video on Demand:Unicast delivery of licensed libraries scales efficiently through edge caching. Korean and Japanese operators invest in exclusive drama and anime content to reduce churn.
- Catch-up TV:Time-shifted broadcast archives with 7-30 day retention windows bridge linear and on-demand behaviors. Indian carriers leverage catch-up functionality to comply with TRAI tariff unbundling while maintaining engagement.
- Web Series:Short-form episodic content produced for mobile-first consumption attracts younger demographics in Manila and Bangkok. Local production houses supply vertical video formats optimized for smartphone IPTV apps.
Live TV holds installed capacity. Video on Demand is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TRAI's tariff transparency mandates and interconnection rules are reshaping carrier economics across India while South Korea's MFDS and KCC frameworks enforce broadcast-grade reliability standards that dictate procurement specifications throughout the Asia-Pacific region.
South Korea
Gigabit broadband penetration enables 4K and 8K IPTV streams commanding premium subscriber fees. The MFDS and KCC frameworks govern broadcast-grade reliability standards shaping procurement specifications. Seoul metropolitan carriers migrate live sports workflows to serverless architectures scaling with concurrent viewership spikes.
India
Fiber-to-the-home rollouts across tier-one cities compress legacy cable infrastructure timelines. TRAI's tariff disclosure mandates expand addressable subscriber bases by prohibiting opaque bundling practices. Bangalore and Hyderabad tier-two operators deploy hybrid stacks balancing transparency requirements against latency-sensitive cricket streaming.
China
State-backed fiber operators dominate provisioning in provincial hubs through captive infrastructure. MIIT mandates GB-standard encryption and content licensing through SAMR-aligned protocols, raising compliance costs for foreign content aggregators. Yangtze River Delta carriers absorb heavy capex burdens to maintain broadcast-grade control.
Indonesia
Ad-supported tiers with conversion gates to paid libraries expand quickly in price-sensitive Jakarta and Surabaya metros. The country's national telecommunications regulator enforces infrastructure sharing rules that accelerate fiber deployment. Jakarta subscribers tolerate pre-roll advertising before upgrading to remove commercial breaks.
Australia
Commercial multi-screen deployments for corporate campuses and co-working spaces require multicast-enabled distribution. The national communications regulator oversees quality-of-service guarantees appealing to markets facing technician shortages. Sydney fintech clusters deploy commercial tiers for internal communications and market data visualization.
Asia-Pacific IPTV Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific IPTV landscape. State-backed fiber operators leverage captive backbone infrastructure to dominate provincial provisioning, while mobile-first challengers anchor expansion through aggressive pricing and bundled convergence. Strategic differentiation concentrates in proprietary set-top integration, UHD content pipelines, and cloud-native CDN orchestration. Competitive moves center on M&A for content libraries and strategic partnerships for elastic infrastructure scaling.
Within the state-backed infrastructure tier, China Telecom Corporation Limited exemplifies scale-driven provisioning through captive fiber assets. Reliance Jio Infocomm Limited occupies a position representing mobile-IPTV convergence archetypes through bundled smartphone and television subscriptions. KT Corporation sits within the premium differentiation tier, anchoring broadcast-grade reliability through proprietary integration models.
| Leading Market Players |
|---|
| Reliance Jio Infocomm Limited |
| Singtel |
| China Telecom Corporation Limited |
| Telstra Corporation Limited |
| KT Corporation |
| SK Telecom Co., Ltd. |
| Bharti Airtel Limited |
| PT Telekomunikasi Indonesia Tbk |
| NTT Communications Corporation |
| Others |
Pricing and Supply Chain Analysis
Ninety-day set-top box inventory cycles in tier-one Indian metros compress margin buffers for carriers while amplifying pricing power for semiconductor foundries serving the H.265 encoder market. This lead-time asymmetry concentrates supplier leverage in Seoul and Taipei, forcing tier-two operators into longer procurement commitments that lock in cost structures across the analysis window.
Pricing Analysis
Seoul carriers command subscriber fees triple those in Jakarta, reflecting gigabit broadband penetration gaps and content licensing tier differentials. Three-tier pricing structure across premium UHD, standard HD, and economy ad-supported levels dominates South Korea and India, with TRAI tariff transparency mandates stripping bundling subsidies that previously masked true service costs. Pricing pressure stems from Reliance Jio's aggressive mobile-IPTV convergence bundles, which force incumbent repricing in Mumbai and Delhi. Prepaid-dominant Indian subscribers exhibit acute price sensitivity, while South Korean contract-locked households tolerate sustained premium extraction.
Supply Chain Analysis
South Korea and Taiwan anchor H.265 encoder chipset fabrication and set-top box original design manufacturing for the regional IPTV hardware stack. Cloud-native CDN orchestration draws from Singaporean and Japanese hyperscaler infrastructure, while fiber-optic cable production concentrates in Chinese state-backed facilities. Single-source vulnerability runs through multicast-enabled core router suppliers, where Cisco and Huawei alternatives face MIIT encryption compliance barriers. Distribution runs through carrier-direct procurement with SLA-backed managed service overlays in Southeast Asian markets facing technician shortages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of fiber-optic technicians and cloud-native video engineers concentrates competitive advantage in carriers with captive training pipelines or outsourced managed service relationships. This capability gap rewards early infrastructure bets and penalizes mid-tier operators attempting rapid cloud migration without DevOps depth.
For Market Incumbents: Secure proprietary set-top integration ecosystems to heighten switching costs against mobile-first challengers entering through bundled smartphone-television convergence. Lock fiber-to-the-home deployment partnerships in tier-two Indian cities before Reliance Jio saturates addressable subscriber bases. Vertical integration into edge-computing node ownership preserves broadcast-grade latency guarantees that cloud-native entrants cannot match. For New Entrants and Emerging Players: Lead with freemium ad-supported tiers in Indonesian and Philippine metros where disposable income constraints limit paid conversion velocity. Target Surabaya and Davao subscriber acquisition white spaces ahead of incumbent fiber rollouts. Go-to-market through mobile application self-provisioning eliminates truck-roll dependencies that collapse deployment timelines for legacy carriers. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because recurring subscription revenue pools deepen with gigabit broadband penetration and content exclusivity amortization. Target managed service providers with SLA-backed quality-of-service capabilities in Southeast Asian technician-scarce markets. Watch cloud-native CDN orchestration adoption rates in Seoul and Singapore as inflection indicators for elastic infrastructure displacing on-premise headends.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native CDN Migration | Elastic infrastructure enables KT Corporation to scale live sports workflows without core router ownership burdens. |
| Mobile-IPTV Convergence Bundling | Reliance Jio anchors subscriber lock-in through prepaid-dominant market smartphone-television integration. |
| UHD Content Pipeline Investment | SK Broadband differentiates via exclusive 8K streams commanding premium fees in gigabit-saturated Seoul metros. |
| Fiber-to-the-Home Partnership | Telstra accelerates deployment timelines through infrastructure sharing with Australia's national broadband network. |
| Freemium Tier Conversion Optimization | PT Telekomunikasi Indonesia captures Jakarta price-sensitive subscribers through ad-supported trial-to-paid mechanics. |
Research Methodology
The analysis maps cloud-native CDN orchestration, on-premise headend deployment, hybrid architectures, and managed service overlays, each validated through conversations with carrier network operations executives, fiber infrastructure procurement leads, content licensing directors, and cloud video engineering specialists. Primary intelligence triangulates against secondary sources including TRAI tariff orders, MIIT GB-standard encryption protocols, MFDS broadcast reliability frameworks, carrier capex disclosures, and hyperscaler infrastructure expansion announcements. Bottom-up subscriber forecasts and top-down broadband penetration projections cross-validate volume estimates.
Consistency checks against external benchmarks anchor the analytical framework across the projection horizon. Segmentation models incorporate deployment architecture elasticity, service tier willingness-to-pay gradients, end-user application intensity, and content format latency requirements. CAGRs derive from broadband subscriber growth curves, encoder efficiency improvement trajectories, and content licensing cost inflation patterns. Cloud infrastructure pricing trajectories and fiber technician wage inflation feed cost-side modeling.
Forecasts assume regulatory continuity in India's TRAI tariff transparency regime, South Korea's MFDS broadcast standards, and China's MIIT encryption mandates; material policy shifts would require re-modeling. Technology disruption risks include H.266 codec displacement of H.265 and satellite-to-cell broadcast alternatives. Recalibration cycles align with material shifts in gigabit broadband penetration thresholds and cloud-native CDN adoption inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Broadband Services Market
Telecommunications
5G Equipment Market
Telecommunications
Prepaid Communication Market
Telecommunications
Diameter Signaling Market
Telecommunications
GPON Market
Telecommunications
Nigeria Telecom Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Cambodia Telecom Tower Market
Telecommunications
Promotional Sms Market
Telecommunications
Global IP Phone Market
Telecommunications
5G in Defense Market
Telecommunications
Rich Communication Services (RCS) Market
Telecommunications
5G Technology Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Asia Pacific Telecom Expense Management Market