
 5G Fronthaul and Backhaul Equipment Market | 2026-2036
5G Fronthaul and Backhaul Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
5G Fronthaul and Backhaul Equipment Market Insights
3GPP Release 17 certification is unwinding vendor eligibility for advanced 5G transport deployments, forcing equipment makers to recalibrate roadmaps. Nokia Corporation leverages its optical transport heritage to sustain leadership in wavelength division multiplexing fronthaul solutions. Samsung Electronics anchors its position through vertical integration across baseband and radio units. Huawei Technologies competes on manufacturing scale despite facing access constraints in multiple Western markets.
5G fronthaul and backhaul equipment encompasses routers, switches, optical transport systems, and microwave links that bridge centralized baseband processing with distributed radio units, typically operating at latency thresholds below 100 microseconds to maintain synchronized radio performance. Fiber optics technology dominates high-capacity deployments due to its bandwidth scalability and immunity to electromagnetic interference, while millimeter wave links address last-mile connectivity where fiber trenching proves cost-prohibitive. Optical transport products command premium positioning in dense urban corridors where capacity aggregation drives infrastructure investment. Telecom operators represent the primary demand pool, though data center interconnect requirements are expanding the addressable base for edge computing deployments.
FCC spectrum allocation rulings and the EU AI Act's infrastructure transparency mandates are reshaping equipment compliance requirements across North American and European deployments. China's MIIT enforces domestic GB standards that condition market access for foreign optical transport vendors. India's TRAI and BIS frameworks are tightening electromagnetic compatibility testing for imported microwave equipment. Stakeholders must monitor how open interface specifications evolve from O-RAN Alliance working groups against incumbent proprietary ecosystems.
Market Dynamics
Open RAN interface standardization is forcing equipment vendors to dismantle proprietary architectures and recalibrate R&D roadmaps around interoperability certifications. This structural shift is compressing margins for incumbents while creating entry points for specialized optical and microwave component suppliers.
Growth Catalysts
- Mid-band spectrum deployment mandates:FCC rulings on C-band and 3.5 GHz allocation are compelling US carriers to densify transport infrastructure for nationwide coverage targets.
- EU AI Act infrastructure transparency requirements:European operators must document network equipment provenance, accelerating procurement of certified optical transport systems with auditable supply chains.
- Edge computing node proliferation:Data center interconnect demand from hyperscale cloud providers is expanding addressable capacity requirements for low-latency fronthaul links.
Market Restraints
- Optical component supply concentration:Laser diode and coherent DSP manufacturing clusters in Taiwan and South Korea create single-source vulnerability for wavelength division multiplexing systems.
- Fiber trenching cost escalation:Urban right-of-way fees and labor shortages in dense metropolitan corridors inflate last-mile deployment economics for greenfield 5G sites.
- Millimeter wave atmospheric attenuation:Rain fade and oxygen absorption at E-band frequencies constrain link reliability for backhaul in tropical and coastal climates.
Strategic Opportunities
- India TRAI infrastructure sharing mandates:Regulatory push for tower and fiber co-location is opening multi-tenant transport equipment procurement at scale.
- Passive optical network convergence:Integration of 5G fronthaul with fiber-to-the-home infrastructure allows cable operators to monetize existing fiber assets for mobile transport.
- China MIIT domestic substitution incentives:Foreign equipment vendors face GB standard compliance requirements that favor joint ventures with local optical component manufacturers.
Industry Challenges
- Coherent optics engineering talent scarcity:Specialized skills in digital signal processing and silicon photonics design command premium compensation and constrain vendor scaling.
- 3GPP Release 17 certification timelines:Extended testing protocols for timing and synchronization compliance delay product qualification cycles for advanced fronthaul routers.
- Legacy TDM migration complexity:Circuit-switched backhaul infrastructure in rural networks requires staged overlay deployment strategies that fragment capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Fronthaul and Backhaul Equipment Market |
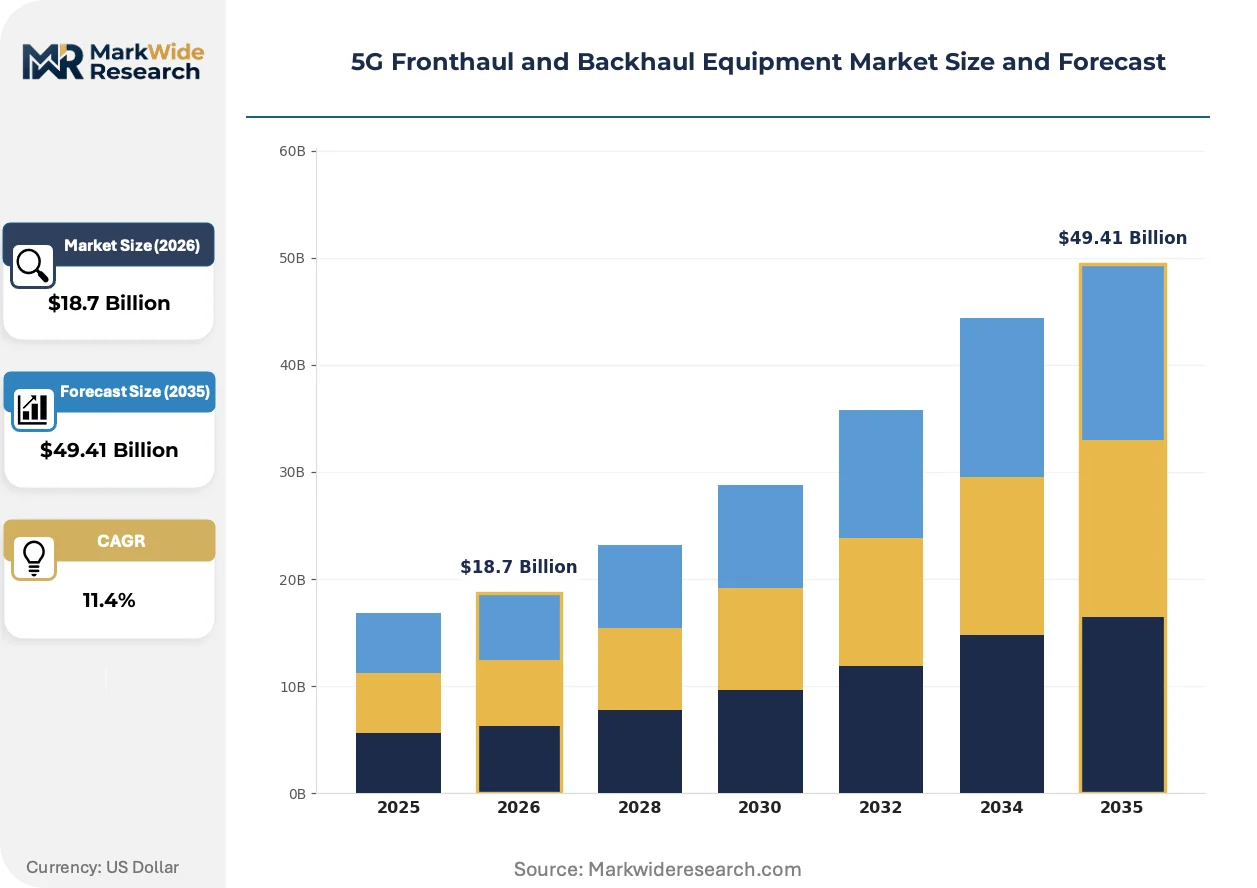
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Router, Switch, Optical Transport, Microwave Link Technology: Wavelength Division Multiplexing, Millimeter Wave, Ethernet, Fiber Optics End User: Telecom Operators, Enterprises, Data Centers, System Integrators Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Huawei Technologies, Nokia Corporation, Samsung Electronics, ZTE Corporation, Telefonaktiebolaget LM Ericsson, Cisco Systems, Fujitsu Limited, NEC Corporation, Infinera Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Fronthaul and Backhaul Equipment Market Trends and Innovations
Packetized fronthaul architectures are displacing circuit-based transport, enabling statistical multiplexing gains while introducing new synchronization engineering requirements. This transition is reshaping vendor competitive positions around software-defined networking capabilities.
Coherent pluggable optics is decomposing traditional chassis-based optical transport into disaggregated edge devices. Hyperscale data center operators are driving 400G ZR and ZR+ module adoption for metro interconnects. This modularity is compressing equipment vendor service revenue streams while democratizing wavelength services for smaller network operators.
FCC spectrum auction rules now embed supply chain security attestation requirements for equipment eligibility in federally funded rural broadband programs. US operators must document component sourcing and manufacturing locations for microwave and optical transport gear. This compliance burden is favoring vendors with transparent North American assembly operations over integrated Asian manufacturing.
Telecom procurement teams are consolidating transport equipment purchasing through framework agreements with systems integrators rather than direct vendor relationships. Tier-1 operators in Germany and France are outsourcing lifecycle management to Ericsson and Nokia service divisions. This channel shift is compressing direct sales headcount at component specialists while elevating solution architecture capabilities as the primary competitive differentiator.
5G Fronthaul and Backhaul Equipment Market Segmentation
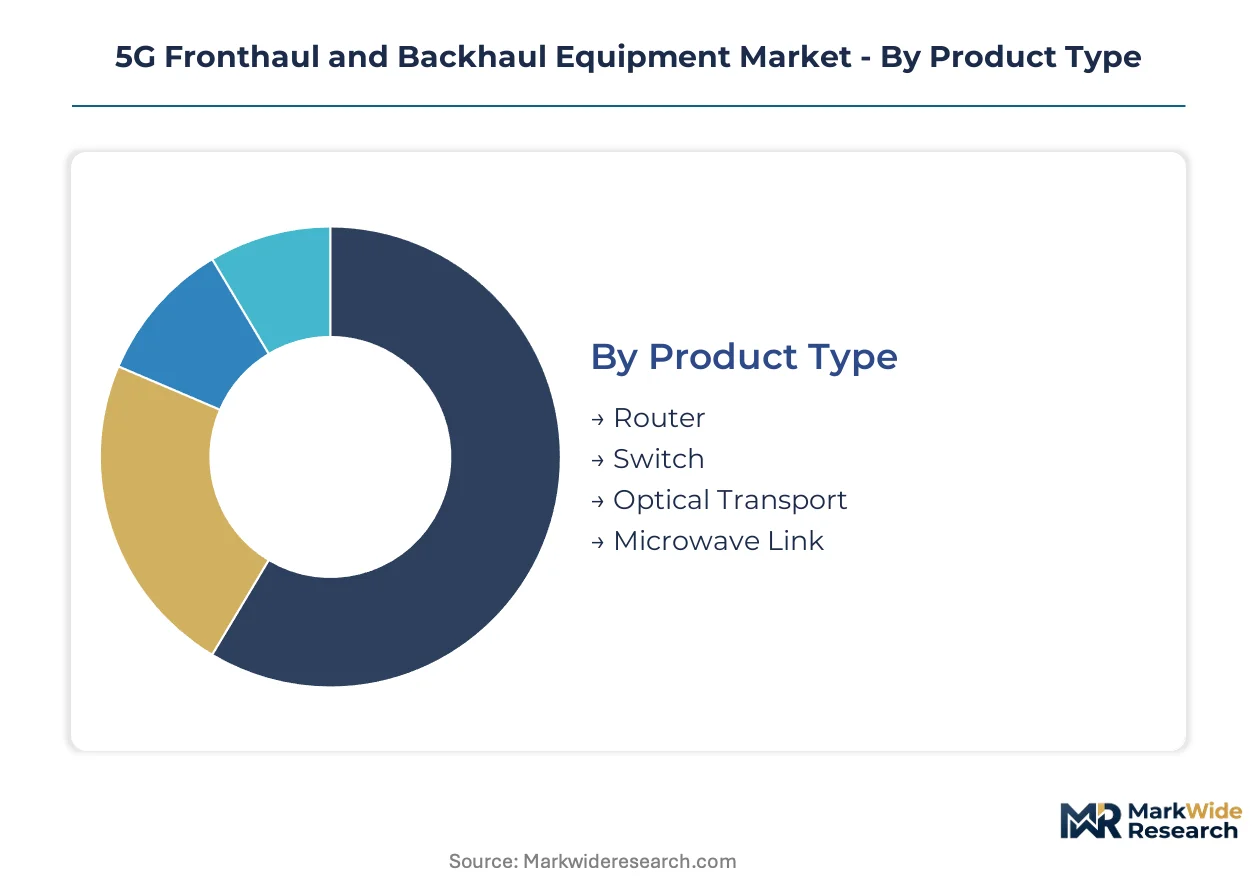
Equipment segmentation in 5G transport networks reveals divergent procurement patterns between carrier-grade infrastructure and enterprise edge deployments. Technology choices cascade through deployment economics, with fiber-based solutions commanding premium positioning in dense urban corridors while microwave alternatives penetrate cost-constrained rural extensions.
Product Type:
Router and optical transport equipment concentrates in domestic carrier procurement cycles, whereas microwave links and switches see stronger export-led demand from emerging market infrastructure programs.
- Optical Transport:Dense wavelength division multiplexing chassis and coherent transponders aggregate multiple 25G fronthaul streams onto single fiber pairs. US carriers in the C-band rollout corridor are procuring these systems to densify metro rings, constrained by Taiwan-sourced laser diode lead times.
- Router:Cell site routers with precise timing and synchronization capabilities bridge distributed unit connectivity to centralized baseband pools. European operators under EU AI Act provenance mandates are prioritizing vendors with auditable supply chains for these deployments.
- Switch:Ethernet switches for mid-haul aggregation scale through merchant silicon architectures.
- Microwave Link:E-band and V-band radio systems address last-mile gaps where fiber trenching economics fail.
Optical transport commands the established base. The steepest expansion runs through router deployments as mid-band densification accelerates.
Technology:
Cost tier stratification separates wavelength division multiplexing and fiber optics as premium infrastructure investments from millimeter wave and Ethernet as economy-tier alternatives for capacity-constrained scenarios.
- Fiber Optics:Single-mode fiber infrastructure with passive optical networking convergence enables cable operators to monetize existing plant for mobile transport. India's TRAI infrastructure sharing mandates are opening multi-tenant fiber deployments at scale, though right-of-way fees in dense metros inflate deployment costs.
- Wavelength Division Multiplexing:Coherent optics with 400G ZR+ pluggables disaggregates traditional chassis into edge-mountable modules. Hyperscale cloud providers in Germany and France are driving adoption for data center interconnect, compressing vendor service revenue streams.
- Millimeter Wave:E-band links at 70-80 GHz face atmospheric attenuation constraints in tropical climates.
- Ethernet:Packetized transport over standard Ethernet PHY dominates enterprise and small-cell backhaul.
Fiber optics commands the established base. Wavelength division multiplexing is climbing the fastest as coherent pluggable optics democratizes wavelength services.
End User:
Application-driven segmentation separates latency-sensitive radio access networks from throughput-optimized data center interconnect and enterprise private 5G deployments.
- Telecom Operators:Tier-1 mobile network operators procure integrated fronthaul-backhaul systems under framework agreements with systems integrators. Procurement consolidation in Germany and France is outsourcing lifecycle management to service divisions, elevating solution architecture capabilities as the primary vendor differentiator.
- Data Centers:Hyperscale facilities demand low-latency edge interconnect for distributed computing nodes. FCC rural broadband funding rules now embed supply chain security attestation requirements, favoring vendors with transparent North American assembly operations.
- Enterprises:Manufacturing and logistics facilities deploy private 5G with integrated transport.
- System Integrators:Channel partners aggregate procurement for mid-market operators and vertical specialists.
Telecom operators command the established base. Data centers are gaining share fastest as edge computing node proliferation expands addressable capacity requirements.
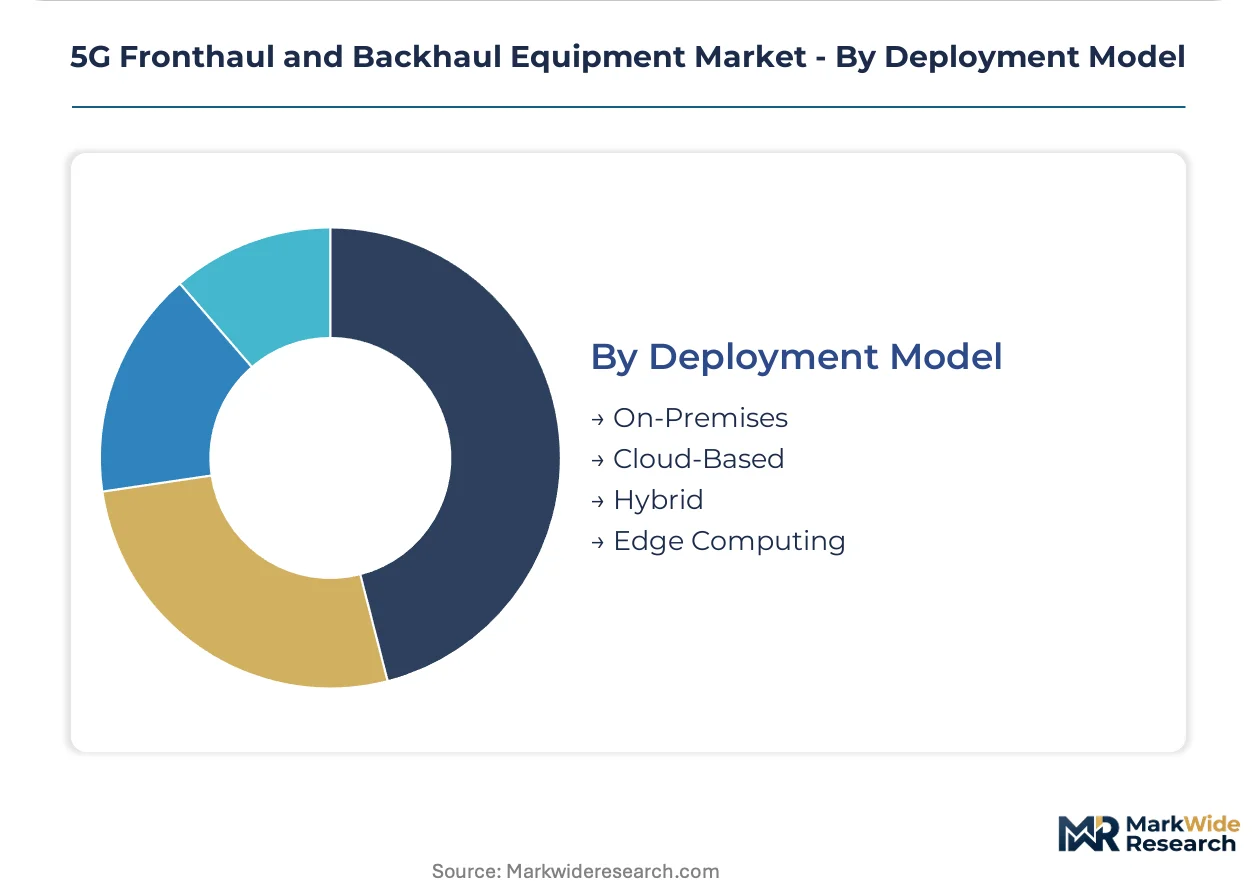
Deployment Model:
Customer-type differentiation separates centralized cloud-based orchestration for multi-tenant operators from on-premises and edge computing deployments for latency-critical applications.
- Edge Computing:Distributed compute nodes collocated with radio access network infrastructure require sub-100 microsecond transport latency. US carriers pursuing nationwide mid-band coverage are deploying these architectures to support network slicing for industrial automation and autonomous systems.
- On-Premises:Traditional centralized baseband hotel deployments persist in legacy network overlays. Rural networks with circuit-switched backhaul infrastructure require staged migration strategies that fragment capital allocation across TDM replacement cycles.
- Cloud-Based:Software-defined transport orchestration from centralized data centers enables multi-tenant resource pooling.
- Hybrid:Mixed architectures balance latency requirements against operational complexity.
On-premises commands the established base. Edge computing is expanding most quickly as radio access network densification drives distributed processing architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC spectrum allocation rulings on C-band and 3.5 GHz are compelling US carriers to densify transport infrastructure for nationwide coverage targets. Telecom operators across multiple geographies are accelerating 5G transport network upgrades to support densified radio access networks.
United States
Mid-band spectrum deployment mandates from the FCC are driving carrier procurement of wavelength division multiplexing systems for metro ring densification. Supply chain security attestation requirements now embed in federally funded rural broadband programs, favoring vendors with transparent North American assembly operations. Dallas and Atlanta corridor deployments concentrate demand for coherent pluggable optics as C-band rollout accelerates.
China
Domestic substitution incentives from MIIT enforce GB standards that condition market access for foreign optical transport vendors. National regulators mandate electromagnetic compatibility testing frameworks that favor joint ventures with local optical component manufacturers. Shenzhen and Shanghai manufacturing clusters anchor captive supply chains for laser diode and coherent DSP production.
Germany
EU AI Act infrastructure transparency requirements are accelerating procurement of certified optical transport systems with auditable supply chains. Tier-1 operators are consolidating transport equipment purchasing through framework agreements with systems integrators, outsourcing lifecycle management to service divisions. Munich and Frankfurt data center interconnect demand drives adoption of 400G ZR+ pluggable modules.
India
TRAI infrastructure sharing mandates for tower and fiber co-location are opening multi-tenant transport equipment procurement at scale. BIS frameworks tighten electromagnetic compatibility testing for imported microwave equipment, conditioning market entry. Bengaluru and Hyderabad industrial corridors concentrate edge computing node deployments requiring sub-100 microsecond transport latency.
South Korea
Coherent optics engineering clusters command premium compensation for specialized skills in digital signal processing and silicon photonics design. National spectrum policy drives millimeter wave backhaul deployment in dense urban corridors where fiber trenching economics fail. Seoul metropolitan area anchors manufacturing scale for optical component supply concentration.
5G Fronthaul and Backhaul Equipment Market Competitive Landscape
Player mix skews toward diversified telecom infrastructure conglomerates with optical transport heritage. Vendor positioning stratifies across integrated system houses, component specialists, and merchant silicon suppliers. Three archetypes dominate: wavelength division multiplexing incumbents with service divisions, coherent optics challengers with pluggable module focus, and microwave specialists with E-band radio portfolios. Competitive moves center on strategic partnerships for open RAN interoperability certification and geographic expansion through joint ventures with local manufacturers.
Within the integrated system house tier, Huawei Technologies and Nokia Corporation exemplify divergent geographic positioning strategies. Huawei Technologies occupies a position shaped by manufacturing scale advantages despite access constraints in multiple Western markets. Nokia Corporation represents the wavelength division multiplexing incumbent archetype with sustained leadership in optical transport solutions. Samsung Electronics anchors the vertical integration model across baseband and radio units. ZTE Corporation sits within the coherent pluggable optics challenger segment alongside Telefonaktiebolaget LM Ericsson.
| Leading Market Players |
|---|
| Huawei Technologies |
| Nokia Corporation |
| Samsung Electronics |
| ZTE Corporation |
| Telefonaktiebolaget LM Ericsson |
| Cisco Systems |
| Fujitsu Limited |
| NEC Corporation |
| Infinera Corporation |
| Others |
Pricing and Supply Chain Analysis
Twenty-six-week lead times for Taiwan-sourced coherent DSP modules and laser diodes compress vendor margins while amplifying pricing power for integrated system houses with captive optical component supply. This inventory constraint cascades through equipment procurement cycles, forcing telecom operators into multi-year framework agreements that lock in volume commitments against supply volatility.
Pricing Analysis
Certification level under 3GPP Release 17 and O-RAN Alliance interoperability standards creates the primary spread between premium-tier coherent transport systems and economy-grade microwave links. Three-tier pricing structure across premium, standard, and economy levels stratifies by synchronization precision, optical reach, and software-defined networking capabilities. Cost compression in the standard tier is intensifying because merchant silicon vendors are disaggregating traditional chassis-based systems into pluggable modules. Data center interconnect buyers exhibit the highest price sensitivity due to hyperscale volume procurement, while rural broadband program administrators under FCC funding rules prioritize supply chain transparency over unit cost.
Supply Chain Analysis
Taiwan Strait transit routes and Kaohsiung port congestion underwrite single-source vulnerability for coherent optics manufacturing clusters. Production gravity centers on Taiwan for laser diodes and coherent DSPs, South Korea for silicon photonics packaging, and China for passive optical component assembly. Raw material dependencies span rare earth elements for optical amplifiers, high-purity germanium for photodetectors, and specialized substrates for indium phosphide lasers. Tariff exposure on Chinese-manufactured passive components conditions procurement strategies for North American operators. Distribution runs through systems integrator channels rather than direct vendor relationships for Tier-1 carrier deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mid-band spectrum deployment mandates across multiple geographies signal early-cycle expansion for transport infrastructure, with edge computing node proliferation extending the addressable base beyond traditional telecom procurement.
For Market Incumbents: Secure O-RAN Alliance interoperability certification ahead of 3GPP Release 17 timelines to defend against coherent pluggable optics challengers eroding chassis-based revenue streams. Deepen backward integration into laser diode and DSP supply through joint ventures with Taiwan and South Korean component manufacturers, mitigating single-source concentration risk that threatens margin stability. For New Entrants and Emerging Players: Differentiate on open interface software stacks and disaggregated hardware architectures to penetrate mid-market operators bypassing incumbent framework agreements. Target India's multi-tenant infrastructure sharing mandates and Germany's EU AI Act provenance requirements as the most penetrable regulatory corridors, leveraging auditable supply chains as the primary go-to-market angle against integrated Asian manufacturing. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure replacement cycle play because transport network lifecycles span 7-10 years with overlay deployment strategies fragmenting capital allocation. Acquisition target archetype: coherent optics specialists with 400G ZR+ module portfolios and established hyperscale data center relationships. Monitor FCC rural broadband funding disbursement velocity as the signal to watch for inflection in North American demand.| Strategic Initiative | Industry Significance |
|---|---|
| O-RAN Alliance Interoperability Certification | 3GPP Release 17 compliance unlocks eligibility for federally funded rural broadband programs. |
| Coherent Pluggable Optics Module Launch | 400G ZR+ adoption by hyperscale cloud providers compresses traditional chassis vendor service revenue. |
| Joint Venture with Taiwan Component Manufacturers | Local optical component partnerships satisfy China's MIIT GB standard compliance for market access. |
| Framework Agreement with Systems Integrators | Ericsson and Nokia service divisions capture lifecycle management outsourcing from Tier-1 operators. |
| Passive Optical Network Convergence | Cable operators monetize existing fiber-to-the-home plant for mobile transport infrastructure. |
Research Methodology
Desk research of 3GPP technical specifications, O-RAN Alliance interface standards, FCC spectrum auction records, and EU AI Act implementation guidance preceded structured interviews with optical transport engineering directors, telecom procurement executives, hyperscale data center network architects, and systems integrator solution specialists. Secondary validation drew from carrier capital expenditure disclosures, equipment vendor SEC filings, and national regulator electromagnetic compatibility testing frameworks. Bottom-up equipment deployment modeling and top-down infrastructure investment forecasts were cross-referenced for triangulation.
Variance in projections decomposes across technology substitution rates, spectrum allocation timelines, and supply chain disruption scenarios. Segmentation dimensions modeled include equipment type, transport technology, end-user category, and deployment architecture across the analysis window. CAGRs were derived from equipment shipment volumes and average selling price trajectories, incorporating edge computing node density assumptions and fiber trenching cost escalation curves as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained mid-band spectrum deployment, stable Taiwan Strait logistics, and coherent optics manufacturing scale would require recalibration. Forecasts reflect documented assumptions on operator densification timelines and hyperscale capex cycles. Practitioners should keep alternative scenarios live as open RAN standardization maturity and geopolitical trade restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Mexico Telecom Market
Telecommunications
Chile Telecom Market
Telecommunications
Telecom API Platform Market
Telecommunications
Russia Telecom Market
Telecommunications
Singapore Telecom Market
Telecommunications
Global Dense Wave Digital Multiplexing (DWDM) System Market
Telecommunications
Angola Telecom Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Austria Telecom Market
Telecommunications
Cloud PBX Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Global LTE Market
Telecommunications
South Africa Telecom Tower Market
Telecommunications
Indonesia ICT Market
Telecommunications
5G RAN Market