
 Indonesia Volte Market | 2026-2036
Indonesia Volte Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Volte Market Insights
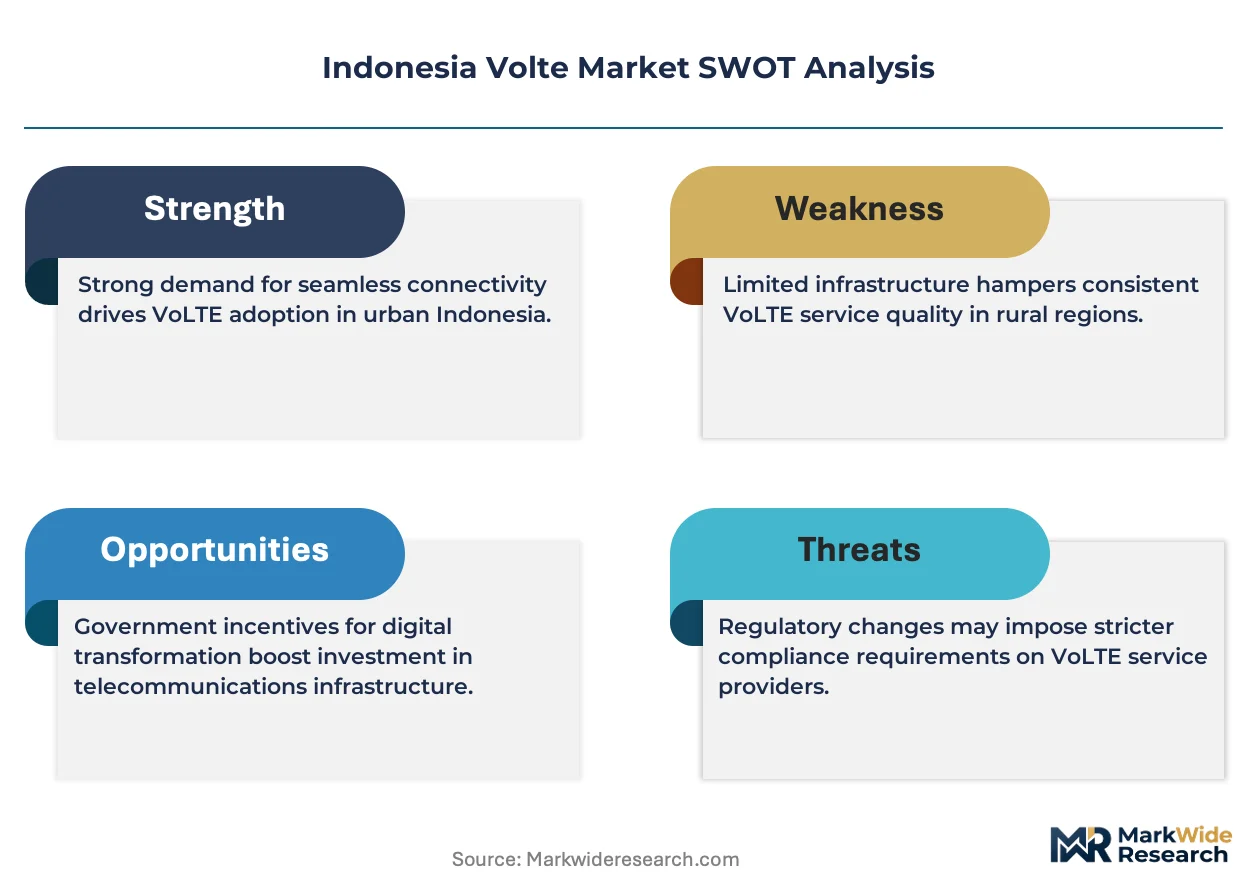
Indonesia's national broadband acceleration program is pivoting carrier investment toward all-IP voice infrastructure. Telkomsel leverages its nationwide LTE footprint to anchor premium VoLTE services in urban corridors. XL Axiata competes through aggressive IMS modernization, while Smartfren specializes in VoWiFi as a coverage extension tool for its FDD-LTE network.
Voice over LTE (VoLTE) refers to packet-switched voice delivery over 4G LTE radio access with an IP Multimedia Subsystem core, enabling high-definition audio with 13 kbps to 64 kbps adaptive codecs and sub-200 millisecond latency. The technology replaces circuit-switched fallback, eliminating dual-radio power drain while supporting simultaneous voice and data sessions. Among deployment modes, public networks dominate subscriber volume due to mass-market mobile operator scale, whereas private networks capture concentrated margin pools from mining and plantation enterprises in remote Kalimantan and Papua. Cloud-based solutions represent the fastest-expanding segment as hyperscaler partnerships reduce core network capital intensity for tier-two carriers.
BIS equipment certification requirements shape device compatibility timelines for Indonesian operators, while the Ministry of Communication and Informatics radio frequency regulations govern spectrum allocation for LTE voice channels. TRAI-inspired quality-of-service benchmarks, adapted through local regulatory consultation, mandate minimum voice call completion rates that carriers must engineer into IMS implementations. Stakeholders should monitor spectrum auction outcomes and enterprise private network licensing frameworks to anticipate capacity expansion cycles and partnership opportunities.
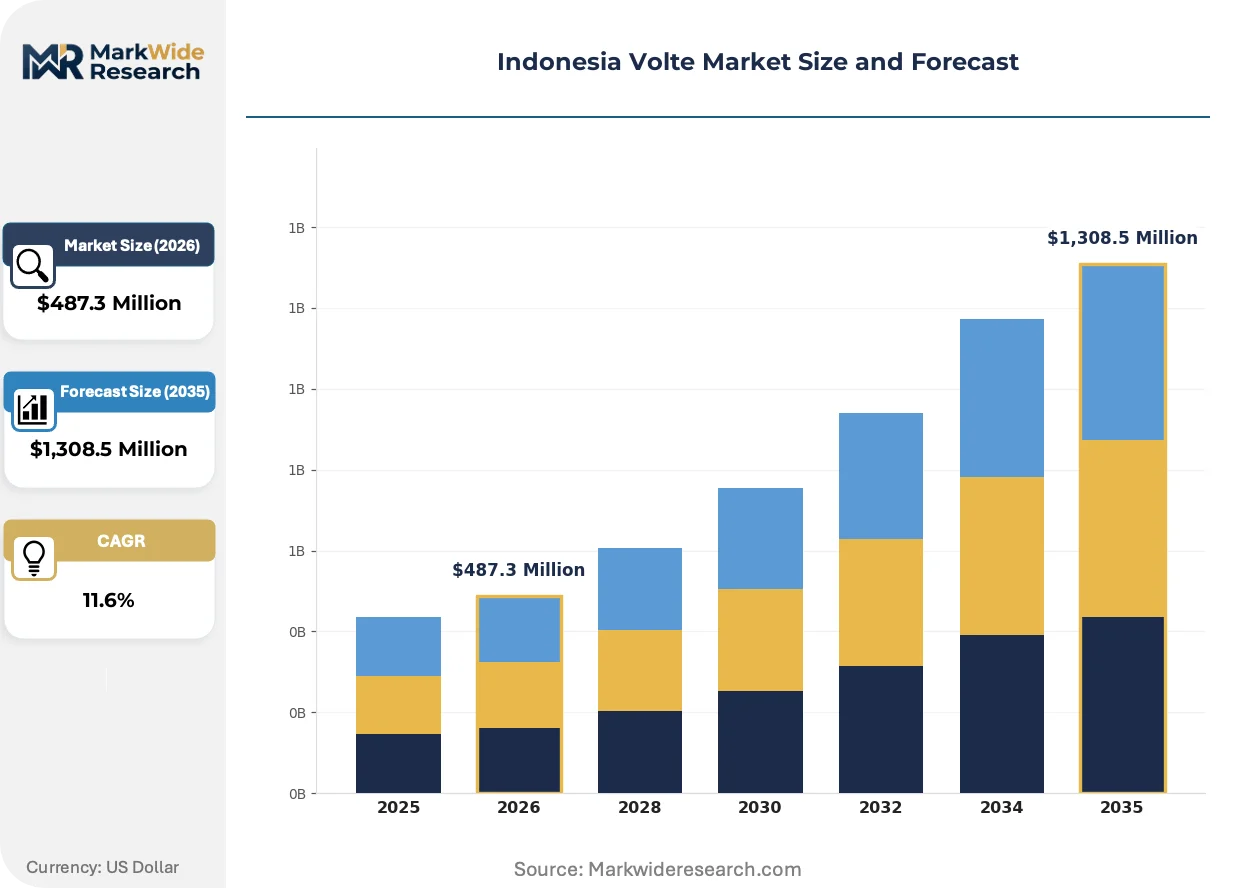
Market Dynamics
Indonesia's spectrum refarming mandates from the Ministry of Communication and Informatics are forcing mobile operators to retire legacy circuit-switched infrastructure ahead of schedule. This regulatory pressure is compressing IMS core deployment timelines and reshaping capital allocation across the archipelago's carrier ecosystem.
Growth Catalysts
- Smartphone penetration in Java:Mass-market device upgrades in Jakarta, Surabaya, and Bandung are creating immediate addressable bases for HD voice services. Urban corridors now exceed threshold densities for VoLTE economics.
- Kominfo spectrum refarming:The ministry's 2G/3G sunset directives are accelerating all-IP migration timelines. Operators must deploy IMS cores to maintain voice service continuity.
- Enterprise video conferencing:Mining and plantation headquarters in Jakarta demand sub-200 millisecond latency for unified communications. VoLTE reliability specifications are displacing OTT alternatives in procurement criteria.
Market Restraints
- IMS core capex concentration:Tier-two carriers face prohibitive upfront investments for packet core modernization. Capital constraints limit competitive response speed.
- Device certification lag:BIS equipment approval timelines stretch six to nine months for new VoLTE-capable handsets. Hardware availability bottlenecks subscriber migration.
- Geographic coverage fragmentation:Outer island provinces in Maluku and Papua lack contiguous LTE footprints. Circuit-switched fallback remains necessary in these corridors.
Strategic Opportunities
- VoWiFi convergence:Unlicensed spectrum voice offload is penetrating indoor coverage gaps. Smartfren's FDD-LTE architecture positions this as a primary extension mechanism.
- Kalimantan private networks:Mining concessions in East Kalimantan require dedicated IMS implementations. Enterprise licensing frameworks are opening for carrier-neutral deployments.
- Cloud-native core migration:Hyperscaler partnerships are reducing capital intensity for tier-two operators. Subscription-based IMS delivery is compressing time-to-market for regional carriers.
Industry Challenges
- Interoperability testing complexity:Multi-vendor IMS environments require extensive protocol validation. Integration friction between radio access and core network elements extends deployment cycles.
- Subscriber education requirements:Feature phone users in Sumatran provinces lack familiarity with HD voice activation. Carrier support infrastructure strains under migration assistance demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Volte Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IMS, LTE, VoWiFi, Circuit-Switched Fallback End User: Smartphone Users, Businesses, Enterprises, Service Providers Deployment: Public Networks, Private Networks, Hybrid Systems, Cloud-Based Solutions Service Type: Voice Services, Data Services, Messaging Services, Multimedia Services |
| Companies Covered | PT Telekomunikasi Selular (Telkomsel), PT Indosat Tbk (Indosat Ooredoo Hutchison), PT XL Axiata Tbk, PT Smartfren Telecom Tbk, Tri Indonesia, Live.On (by XL Axiata), by.U (by Telkomsel), Switch Mobile (by Smartfren), MyRepublic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Volte Market Trends and Innovations
Automation of network operations is redefining how Indonesian carriers deploy and maintain VoLTE infrastructure. Three interconnected developments are compressing implementation timelines while raising service quality benchmarks.
AI-driven radio resource management is automating dynamic codec selection between 13 kbps and 64 kbps based on real-time congestion. Telkomsel's urban corridor deployments are adopting these algorithms fastest. The technology is automating quality-of-service enforcement that previously required manual threshold tuning.
Kominfo's adapted TRAI-inspired quality-of-service benchmarks now mandate minimum voice call completion rates for licensed operators. These technical specifications are hardening into enforceable compliance thresholds. Tier-one carriers in Jakarta and Surabaya are pre-emptively over-engineering IMS redundancy to exceed these floors.
Enterprise procurement teams are unbundling voice quality guarantees from data service contracts. Mining headquarters in Balikpapan and plantation offices in Medan now specify HD voice SLAs separately. This specification fragmentation is creating premium pricing tiers for guaranteed latency performance.
Indonesia Volte Market Segmentation
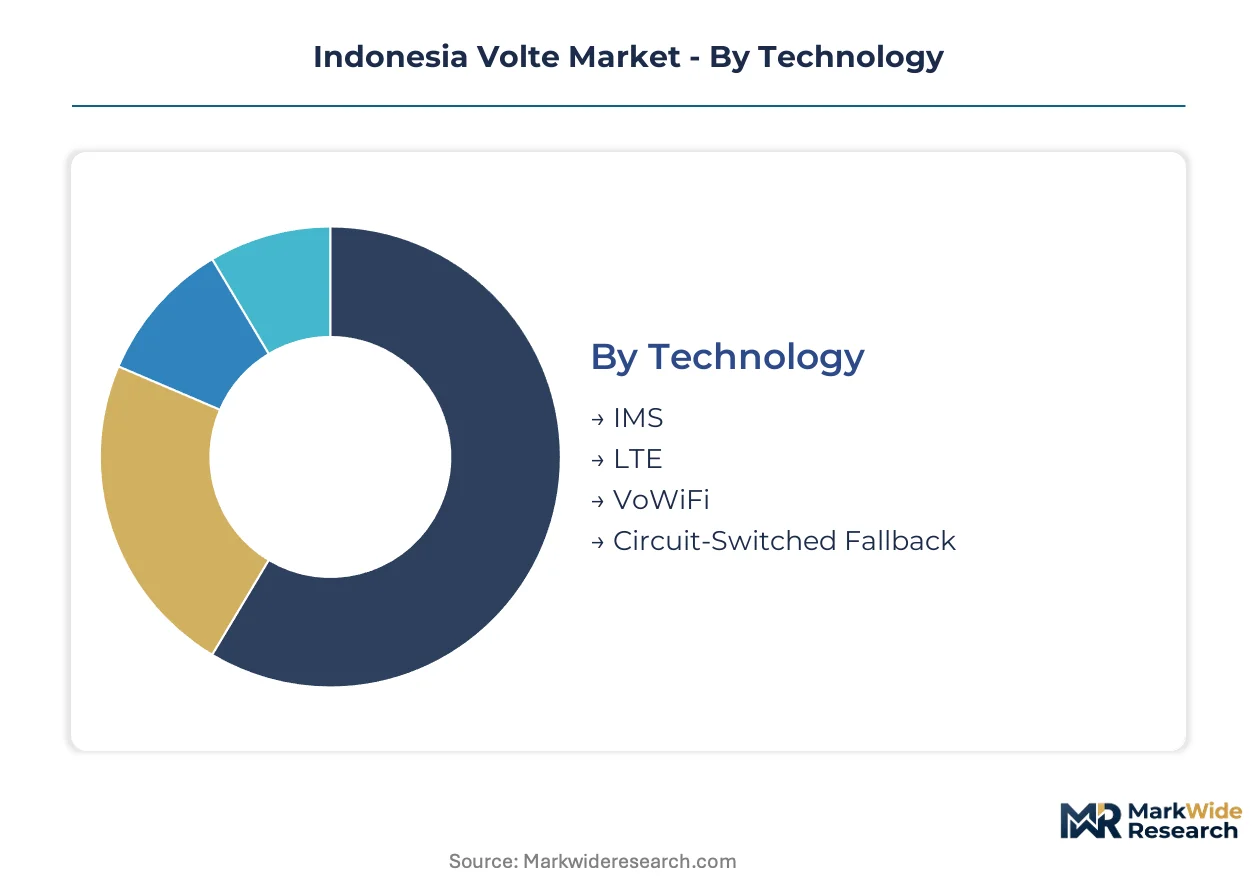
VoLTE market segmentation in Indonesia reveals how capital allocation, regulatory mandates, and subscriber density interact across technology layers. Each category exposes different investment thresholds and margin structures that carriers navigate during IMS migration.
Technology:
IMS core infrastructure demands the heaviest upfront capital commitment, while radio access technologies vary in deployment economics across Indonesia's archipelago geography.
- IMS:IP Multimedia Subsystem cores orchestrate session control, subscriber authentication, and interconnection with legacy PSTN networks. Deployment concentrates in Jakarta and Surabaya where carrier headquarters co-locate network operations centers with submarine cable landing stations. Kominfo's quality-of-service benchmarks mandate redundant IMS implementations that double capital requirements for tier-one operators.
- LTE:Radio access networks carry packetized voice over dedicated bearers with guaranteed bit rates. Java's urban corridors host the densest LTE voice traffic, while Sumatra's eastern provinces require tower-sharing agreements to justify cell site economics.
- VoWiFi:Unlicensed spectrum offload extends coverage into indoor environments without additional licensed spectrum investment. Smartfren deploys this as a primary mechanism for FDD-LTE coverage extension in Bandung's high-rise districts.
- Circuit-Switched Fallback:Legacy interworking maintains voice continuity where LTE footprints remain discontinuous. Maluku and Papua provinces retain this as a necessary fallback mechanism.
Most installed capacity flows through LTE radio access. Expansion is steepest in IMS core modernization as Kominfo's refarming deadlines approach.
End User:
Customer type determines pricing power and service level agreement structures, with enterprise accounts commanding premium tiers unavailable to mass-market subscribers.
- Smartphone Users:Mass-market subscribers in Java's metropolitan areas generate volume scale for HD voice services. Device certification delays from BIS create six-to-nine month migration bottlenecks for this segment.
- Businesses:Small and medium enterprises in Surabaya and Medan demand bundled voice-data packages with basic quality guarantees. Procurement decisions cluster around total cost of ownership rather than latency specifications.
- Enterprises:Mining headquarters in Balikpapan and plantation offices in Medan specify sub-200 millisecond latency SLAs separately from data contracts. These accounts drive private network licensing negotiations with Kominfo.
- Service Providers:MVNOs and wholesale voice carriers purchase bulk IMS capacity from tier-one infrastructure owners. Margin compression in this segment accelerates cloud-native core adoption.
Smartphone users dominate subscription volume. Enterprise accounts deliver the steepest expansion trajectory as procurement teams unbundle voice quality guarantees.
Deployment:
Network architecture choices reflect trade-offs between capital ownership and operational flexibility, with cloud models reducing barriers for regional carriers.
- Public Networks:Mass-market mobile operator infrastructure serves subscriber bases across Indonesia's major islands. Telkomsel's nationwide footprint anchors premium VoLTE services through this deployment mode.
- Private Networks:Dedicated IMS implementations serve mining concessions in East Kalimantan and plantation estates in North Sumatra. Enterprise licensing frameworks from Kominfo are opening for carrier-neutral deployments in these corridors.
- Hybrid Systems:Combinations of owned infrastructure and leased capacity allow tier-two operators to target specific geographic clusters without full-archipelago coverage obligations.
- Cloud-Based Solutions:Hyperscaler partnerships reduce core network capital intensity for regional carriers. Subscription-based IMS delivery is compressing time-to-market for operators outside Java.
Public networks carry most subscriber volume. Cloud-based solutions are gaining share fastest as tier-two carriers seek capital-efficient expansion paths.
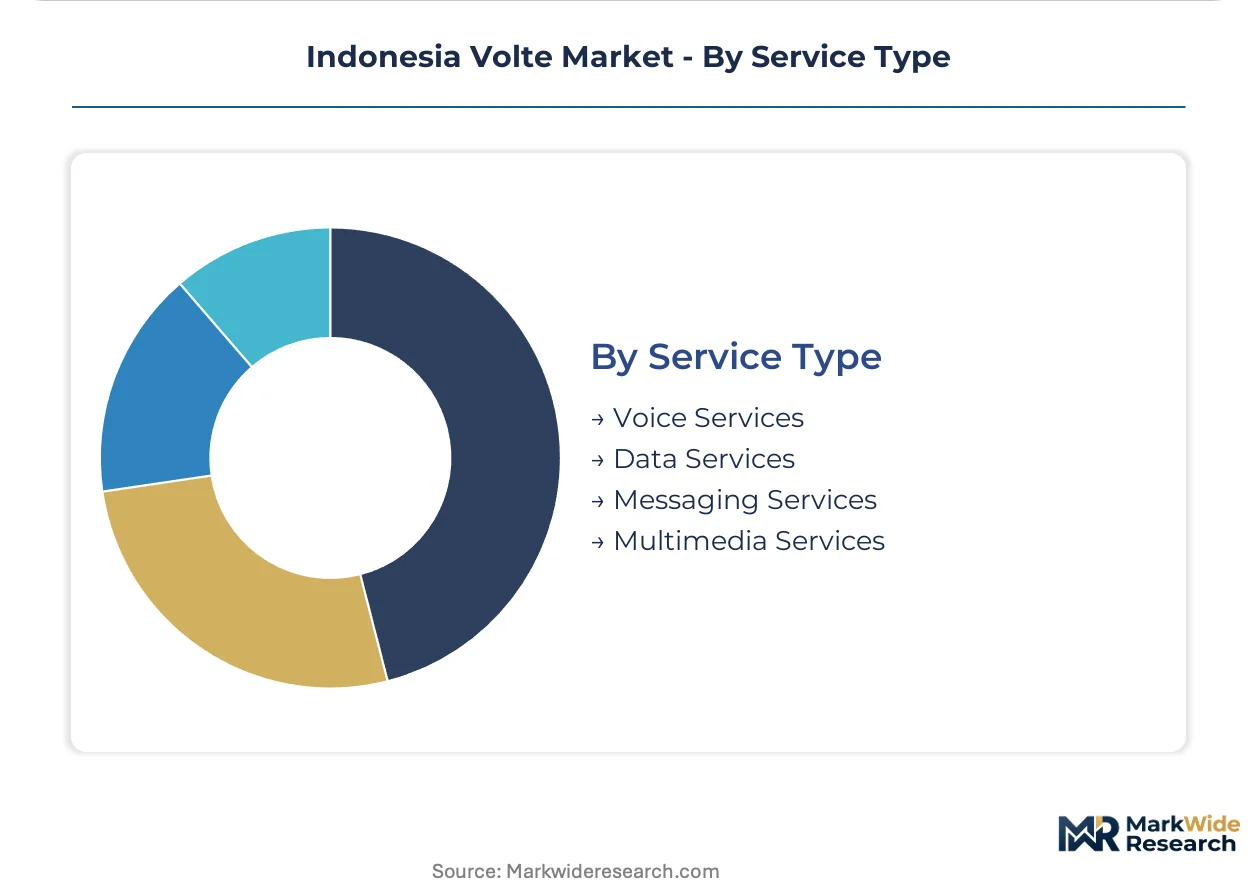
Service Type:
Service unbundling is fragmenting traditional bundled offerings, with quality-guaranteed voice emerging as a standalone procurement category.
- Voice Services:HD audio with adaptive codecs between 13 kbps and 64 kbps replaces circuit-switched telephony. AI-driven radio resource management now automates dynamic codec selection based on real-time congestion in Telkomsel's urban corridors.
- Data Services:Simultaneous voice and data sessions without dual-radio power drain represent a core VoLTE value proposition. Smartphone penetration in Jakarta and Bandung creates immediate addressable bases for this capability.
- Messaging Services:SMS over IMS and Rich Communication Services ride the same packet core infrastructure. Interoperability testing complexity across multi-vendor environments extends deployment cycles for this overlay.
- Multimedia Services:Video calling and content sharing leverage guaranteed quality-of-service bearers. Enterprise video conferencing demand from mining headquarters is displacing OTT alternatives in procurement criteria.
Voice services absorb most network engineering resources. Multimedia services show the steepest expansion trajectory as enterprise SLAs harden around video performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
VoLTE infrastructure in Indonesia originated from Java's metropolitan corridors where Telkomsel first deployed IMS cores alongside submarine cable landing stations. The technology spread outward through spectrum refarming mandates issued by Kominfo, creating distinct regional deployment patterns across the archipelago.
Java
Jakarta, Surabaya, and Bandung generate the densest VoLTE traffic volumes as smartphone penetration exceeds threshold economics for HD voice services. Kominfo's quality-of-service benchmarks mandate redundant IMS implementations that carriers co-locate with network operations centers in the capital. Telkomsel anchors premium services through this corridor while XL Axiata competes via aggressive IMS modernization.
Sumatra
Medan's plantation offices and SME clusters drive enterprise demand for bundled voice-data packages with basic quality guarantees. The Ministry of Communication and Informatics radio frequency regulations govern spectrum allocation for LTE voice channels across the island. Eastern provinces require tower-sharing agreements to justify cell site economics as BIS device certification delays stretch subscriber migration timelines.
Kalimantan
Mining headquarters in Balikpapan and East Kalimantan concessions specify sub-200 millisecond latency SLAs for unified communications procurement. Enterprise licensing frameworks from Kominfo are opening for carrier-neutral private network deployments in these corridors. Cloud-based IMS delivery is compressing time-to-market for regional carriers targeting resource extraction compounds.
Sulawesi
Makassar's emerging metropolitan base creates immediate addressable markets for VoWiFi coverage extension into high-rise districts. Local operators leverage unlicensed spectrum offload as a primary mechanism for FDD-LTE coverage gaps. Subscriber education requirements strain carrier support infrastructure as feature phone users transition to HD voice activation protocols.
Papua and Maluku
Outer island provinces lack contiguous LTE footprints that would support pure packet-switched voice deployment. Circuit-switched fallback remains necessary in these corridors where geographic coverage fragmentation persists. Hybrid systems combining owned infrastructure with leased capacity allow tier-two operators to target specific clusters without full-archipelago coverage obligations.
Indonesia Volte Market Competitive Landscape
Capital-heavy mobile network operators compete with asset-light virtual brands for subscriber relationships across Indonesia's archipelago. The carrier ecosystem consolidates around three tier-one infrastructure owners while MVNOs and sub-brands fragment the service layer. Strategic archetypes include nationwide integrated operators, regional challengers with specialized coverage tools, and digital-native sub-brands targeting youth segments. Dominant competitive moves encompass IMS core modernization races and cloud-native partnerships that reduce capital intensity for expansion.
Among Jakarta-based integrated operators, PT Telekomunikasi Selular anchors the premium tier through nationwide LTE footprint scale while PT XL Axiata exemplifies the modernization-focused challenger archetype. PT Smartfren Telecom Tbk occupies a distinct position specializing in VoWiFi as coverage extension for its FDD-LTE architecture. These three represent the capital-heavy foundation that asset-light brands such as Live.On, by.U, and Switch Mobile leverage for service differentiation without infrastructure ownership.
| Leading Market Players |
|---|
| PT Telekomunikasi Selular (Telkomsel) |
| PT Indosat Tbk (Indosat Ooredoo Hutchison) |
| PT XL Axiata Tbk |
| PT Smartfren Telecom Tbk |
| Tri Indonesia |
| Live.On (by XL Axiata) |
| by.U (by Telkomsel) |
| Switch Mobile (by Smartfren) |
| MyRepublic |
| Others |
Pricing and Supply Chain Analysis
Cloud-native IMS core migration is compressing capital requirements for tier-two carriers while concentrating procurement leverage among hyperscaler partners. This technology shift simultaneously flattens cost curves for regional operators and narrows the supplier base for virtualized network functions.
Pricing Analysis
Subscription-based IMS delivery from hyperscaler partners anchors the dominant pricing structure across Indonesian carriers. Price differentiation rests on network redundancy tiers and Kominfo-mandated quality-of-service certification levels. Cost compression in standard-tier services is intensifying because cloud-native alternatives eliminate proprietary hardware markups. Enterprise mining accounts in Kalimantan show the lowest price sensitivity due to unbundled SLA requirements, while mass-market smartphone subscribers in Sumatran provinces drive volume at thinner margins.
Supply Chain Analysis
BIS equipment certification gates hardware availability with six-to-nine month approval timelines that constrain device vendor participation. Network equipment manufacturing concentrates in China, South Korea, and Finland, with radio access unit production anchored in Shenzhen and Seoul. Raw material dependencies span gallium nitride semiconductors, precision RF filters, and submarine fiber optic cable. Single-source vulnerability persists for IMS core software licensing from European and North American vendors. Distribution runs through carrier-direct procurement with systems integrators managing multi-vendor interoperability testing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's VoLTE market has entered a late-cycle quality phase where enterprise procurement teams unbundle voice SLAs from data contracts. Mining headquarters in Balikpapan now specify sub-200 millisecond latency as a premium requirement.
For Market Incumbents: Deploy AI-driven radio resource management to automate dynamic codec selection and defend margin position against cloud-native challengers. Telkomsel should accelerate IMS redundancy over-engineering to exceed Kominfo's hardening quality-of-service floors. XL Axiata must secure tower-sharing agreements in eastern Sumatra before regional carriers achieve coverage parity through leased capacity. For New Entrants and Emerging Players: Hyperscaler partnerships offer the fastest path to compress time-to-market for tier-two operators outside Java. Private network licensing frameworks in East Kalimantan mining concessions represent the most penetrable white-space. Cloud-based IMS delivery enables carrier-neutral deployments without full-archipelago infrastructure obligations. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated regional carriers because spectrum refarming mandates are forcing accelerated IMS migration timelines. Target operators with existing LTE footprints in underpenetrated outer island provinces. Monitor Kominfo enterprise licensing framework announcements as the primary inflection signal for private network valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| IMS Core Modernization | Telkomsel's redundant Jakarta implementations exceed Kominfo quality-of-service mandates. |
| Cloud-Native Partnership | Hyperscaler alliances reduce capital intensity for tier-two carriers in Sulawesi. |
| VoWiFi Coverage Extension | Smartfren's unlicensed spectrum offload penetrates Bandung high-rise districts. |
| Private Network Licensing | Kominfo frameworks open carrier-neutral deployments in Kalimantan mining corridors. |
| AI-Driven Radio Management | Automated codec selection compresses latency for enterprise video conferencing demand. |
Research Methodology
Direct dialogue with network operations executives, IMS systems integrators, Kominfo regulatory officials, and enterprise procurement managers in Jakarta and Surabaya grounded the qualitative foundation. Secondary validation drew from Ministry of Communication and Informatics spectrum refarming directives, BIS equipment certification databases, submarine cable landing station utilization reports, and carrier capital expenditure disclosures. Bottom-up subscriber modeling and top-down infrastructure investment analysis were triangulated to cross-verify volume estimates.
Market size outputs across the projection horizon reflect segmented modeling by technology layer, deployment architecture, end-user category, and service type. CAGRs were derived from regression analysis of historical IMS investment cycles and smartphone penetration trajectories. Industry-specific inputs included Kominfo quality-of-service benchmark evolution, BIS certification timeline distributions, and hyperscaler partnership announcement patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to spectrum auction timing, enterprise licensing framework finalization, and cloud-native adoption velocity. The model assumes continued 2G/3G sunset adherence without regulatory extension. A model refresh is warranted upon material change in Kominfo refarming deadlines or hyperscaler partnership terms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Italy Telecom Market
Telecommunications
5G Monetization Market
Telecommunications
Austria Telecom Market
Telecommunications
Global SS7 Market
Telecommunications
Mobile Voice Market
Telecommunications
Transport Stream Switching Market
Telecommunications
Russia ICT Market
Telecommunications
Indonesia Telecom Market
Telecommunications
Belgium ICT Market
Telecommunications
Global Virtual PBX Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Digital Mobile Radio (DMR) Market
Telecommunications
Poland Telecom Market
Telecommunications
5G MVNO Market
Telecommunications
Mexico MNVO Market