
 Global Backup Restore Software Market | 2026-2036
Global Backup Restore Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Backup Restore Software Market Foresight
GDPR is hardening the cost-of-entry calculus for backup restore vendors seeking European market access. Veeam Software leverages its channel density to sustain dominance in virtual environment recovery. Acronis anchors its competitive position through integrated cyber protection that spans backup and endpoint security. Commvault differentiates via deep archival governance capabilities that appeal to regulated industries.
Backup restore software encompasses applications, platforms, and services designed to create redundant copies of digital data and enable systematic recovery following loss events, typically supporting recovery time objectives measured in minutes to hours and recovery point objectives ranging from seconds to days depending on the continuity tier. The primary commercial purpose centers on ensuring operational resilience, regulatory compliance, and business continuity across enterprise IT estates. Cloud deployment now leads growth trajectories as organizations abandon tape-centric architectures, while ransomware protection within application segments commands premium pricing due to escalating cyber incident frequency. Full backup solutions retain structural importance for compliance baselines, though continuous data protection is accelerating fastest among solution offerings as synchronous replication matures.
FDA mandates for healthcare data integrity, SEC recordkeeping rules for financial services, and China's GB standards for critical information infrastructure collectively shape product certification requirements and sales cycle complexity across major economies. Japan's METI guidelines on operational technology security further extend compliance scope into industrial backup scenarios. Stakeholders must monitor evolving cross-border data flow restrictions and encryption export controls as these determine architectural choices between sovereign cloud instances and global platform deployments.
Market Dynamics
Ransomware frequency is compressing recovery time objectives from hours to minutes, forcing architecture shifts toward continuous data protection and immutable storage tiers. Cloud repatriation debates are reshaping deployment decisions as egress costs and sovereignty requirements collide.
Growth Catalysts
- Healthcare digitization:FDA mandates for electronic health record integrity require immutable backup architectures across hospital networks. Patient data volume growth outpaces legacy tape retention capacity.
- EU AI Act:Training data lineage requirements create audit-trail obligations that backup systems must satisfy for machine learning pipelines in European operations.
- Edge computing expansion:Distributed manufacturing and retail footprints generate fragmented data estates requiring centralized recovery orchestration.
Market Restraints
- Cloud storage cost volatility:Hyperscaler egress fees and tiered retrieval pricing create unpredictable total cost of ownership for long-term retention workloads.
- Encryption export controls:US Bureau of Industry and Security restrictions limit cross-border deployment of certain cryptographic modules in backup appliances.
- Tape infrastructure stranded assets:Specialized robotics and media libraries face accelerated depreciation as organizations abandon physical offsite rotation.
Strategic Opportunities
- Operational technology convergence:Japan's METI guidelines extend backup scope to industrial control systems in manufacturing and energy infrastructure.
- Sovereign cloud instances:Germany's Gaia-X and France's Bleu initiatives create demand for EU-hosted backup platforms with data residency guarantees.
- Immutable object storage:S3-compatible write-once architectures are displacing traditional deduplication appliances in financial services vaulting.
Industry Challenges
- Legacy system integration:Mainframe and AS/400 environments resist API-native backup methods, requiring specialized gateway appliances that fragment operational workflows.
- Skills bifurcation:Storage administration expertise concentrates in aging workforce cohorts while cloud-native talent lacks deep recovery procedure knowledge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Backup Restore Software Market |
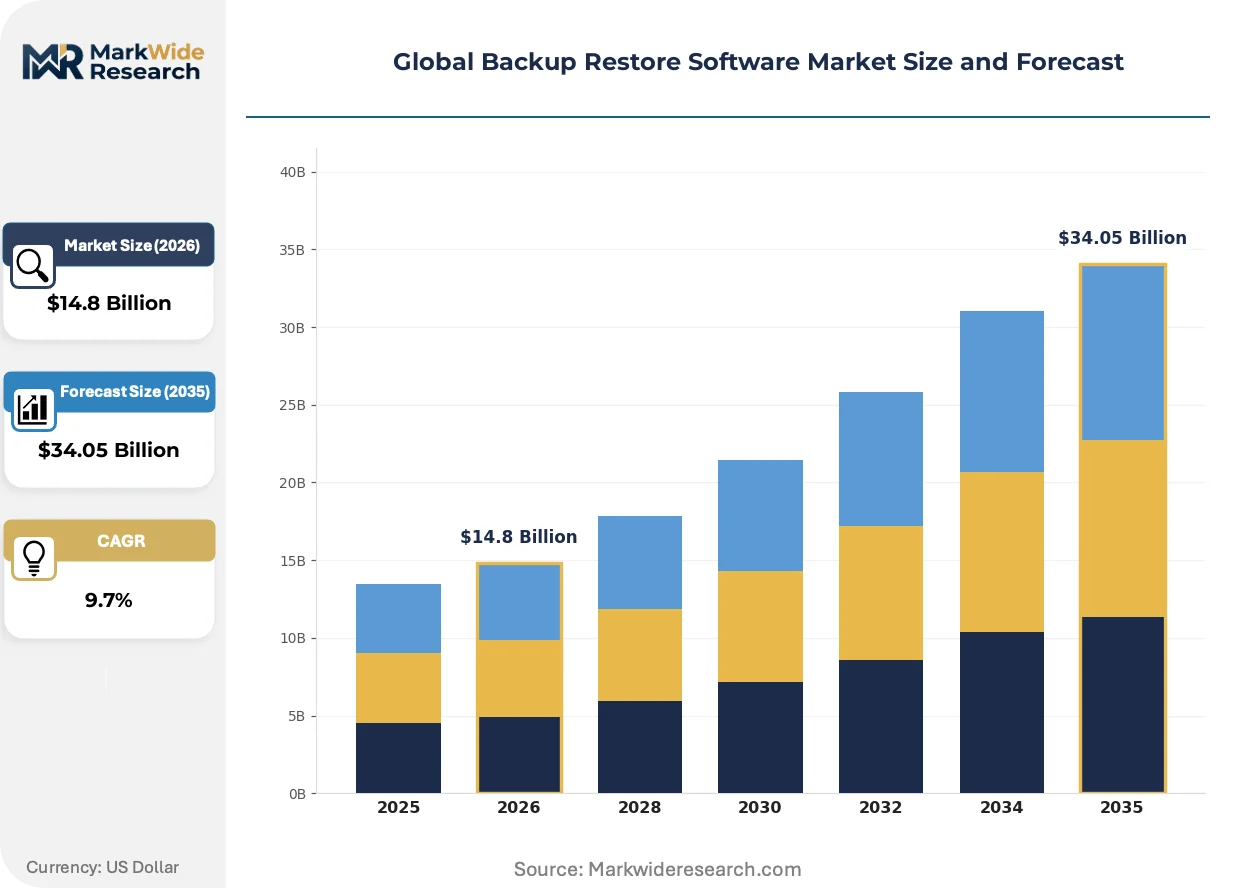
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $34.05 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid Cloud, Virtual Environments, Edge Computing Solution Offering: Full Backup, Incremental Backup, Differential Backup, Continuous Data Protection, Snapshot Backup Application: Data Archiving, Disaster Recovery, Data Migration, Ransomware Protection, Compliance Management End User Industry: BFSI, Government Agencies, Telecommunications, Manufacturing, Education |
| Companies Covered | Veeam Software, Acronis, Commvault, Veritas Technologies, IBM, Dell Technologies, Microsoft, Cohesity, Rubrik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Backup Restore Software Market Shifts & Advancements
Backup architectures are fragmenting into composable microservices that decouple data movement from policy management. This decomposition enables buyers to substitute components without forklift upgrades.
Immutable object storage is modularizing disaster recovery stacks by separating compute orchestration from capacity tiers. Financial services vaulting operations adopt S3-compatible write-once architectures fastest. Vendors now compete on API granularity rather than integrated appliance density.
China's GB standards for critical information infrastructure mandate domestic encryption modules and geographic data residency. Multinational enterprises must architect separate backup instances for PRC operations. Compliance certification timelines extend sales cycles by four to six months for foreign vendors.
Consumption-based licensing is displacing perpetual capacity purchases in mid-market procurement. Managed service providers aggregate demand and resell metered protection services. This shift concentrates buying power among regional hosting specialists in Germany and Australia.
Global Backup Restore Software Market Segmentation
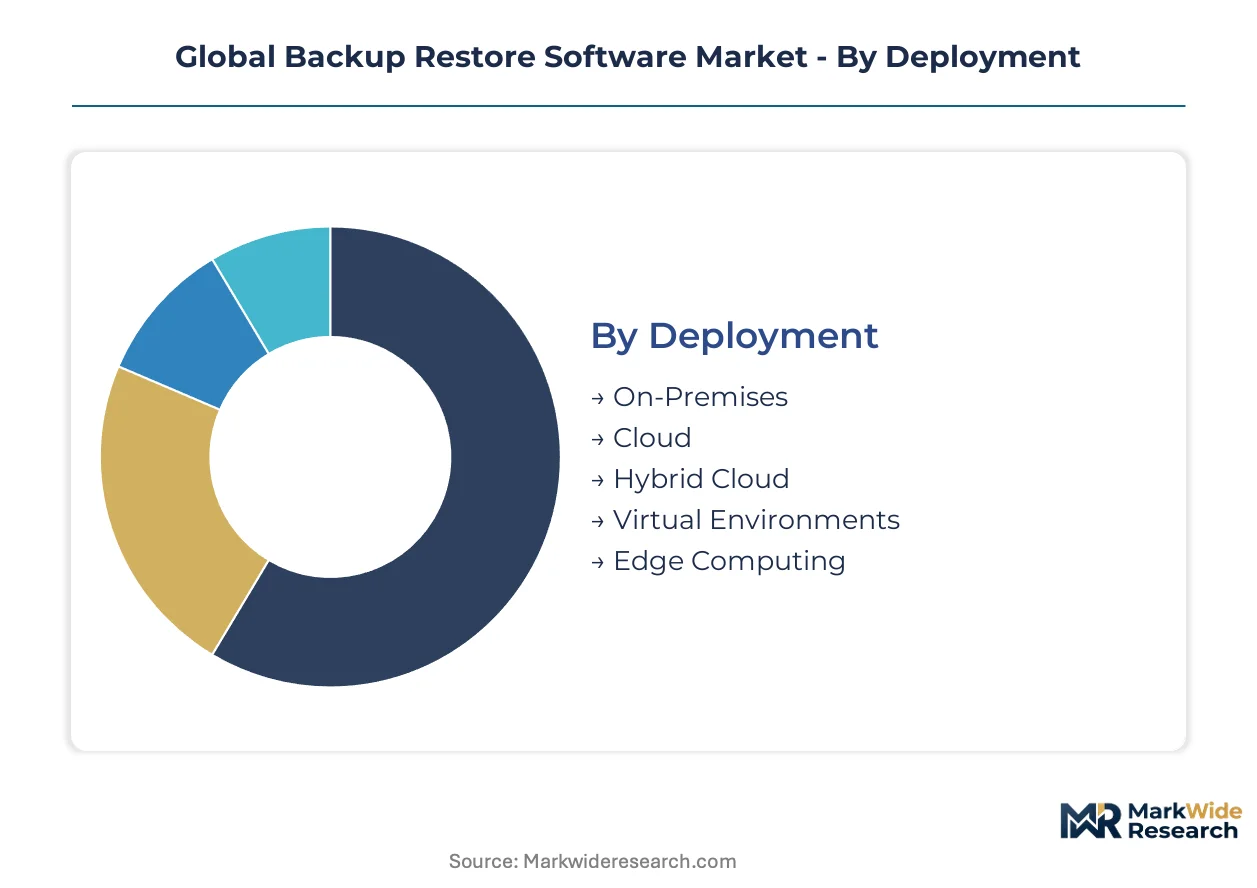
Backup restore software vendors architect product portfolios around four intersecting dimensions: infrastructure location, protection methodology, operational purpose, and sector-specific compliance. Segmentation discipline determines pricing power, implementation complexity, and renewal rates across customer lifecycles.
Deployment:
Customization intensity varies sharply across deployment modes, from fully managed SaaS to engineer-intensive on-premises builds.
- Cloud:Multi-tenant architectures with consumption-based metering dominate new procurement. Healthcare networks in the United States favor this mode for HIPAA-compliant offsite vaulting without capital deployment. Cloud deployment captures the largest revenue share among all deployment modes.
- Hybrid Cloud:Policy-driven tiering between local fast recovery and cloud long-term retention addresses sovereignty requirements. German manufacturers under GDPR pressure adopt this architecture to keep primary copies domestic while archiving to EU sovereign zones. Hybrid Cloud is expanding most quickly as regulatory fragmentation intensifies.
- On-Premises:Dedicated appliances and software licenses for air-gapped environments.
- Virtual Environments:Agentless protection for VMware, Hyper-V, and KVM estates.
- Edge Computing:Lightweight agents for distributed retail and industrial endpoints.
Leading the category by volume: Cloud. Growing fastest: Hybrid Cloud.
Solution Offering:
Technical sophistication correlates with recovery granularity and storage economics.
- Continuous Data Protection:Journal-based capture with point-in-time rollback to any second. Financial exchanges in Japan deploy METI-aligned CDP to meet sub-minute recovery mandates for trading systems. Continuous Data Protection is gaining share fastest as ransomware response requirements harden.
- Full Backup:Complete dataset copies establishing compliance baselines for audit defense. BFSI regulators in India require periodic full backups under RBI operational resilience guidelines. Full Backup retains structural importance for baseline compliance documentation.
- Incremental Backup:Change-only capture reducing network load and storage footprint.
- Differential Backup:Cumulative change sets since last full backup for faster restore assembly.
- Snapshot Backup:Storage-array-native point-in-time copies for virtualized workloads.
Volume leadership: Full Backup. Steepest expansion trajectory: Continuous Data Protection.
Application:
Use case specialization determines integration depth and pricing tier.
- Ransomware Protection:Immutable storage with behavioral detection and isolated recovery environments. Australian critical infrastructure operators under TGA-adjacent security frameworks prioritize this application for operational continuity. Ransomware Protection commands premium pricing due to incident frequency escalation.
- Disaster Recovery:Orchestrated failover with automated runbook execution across geographically separated sites. Telecommunications providers in South Korea leverage this application for MFDS-aligned service continuity in healthcare connectivity. Disaster Recovery represents the largest application segment by committed spend.
- Data Archiving:Long-term retention with legal hold and e-discovery integration.
- Data Migration:Structured movement between storage platforms with integrity verification.
- Compliance Management:Audit trail generation and retention policy enforcement.
Dominant by revenue: Disaster Recovery. Accelerating most rapidly: Ransomware Protection.
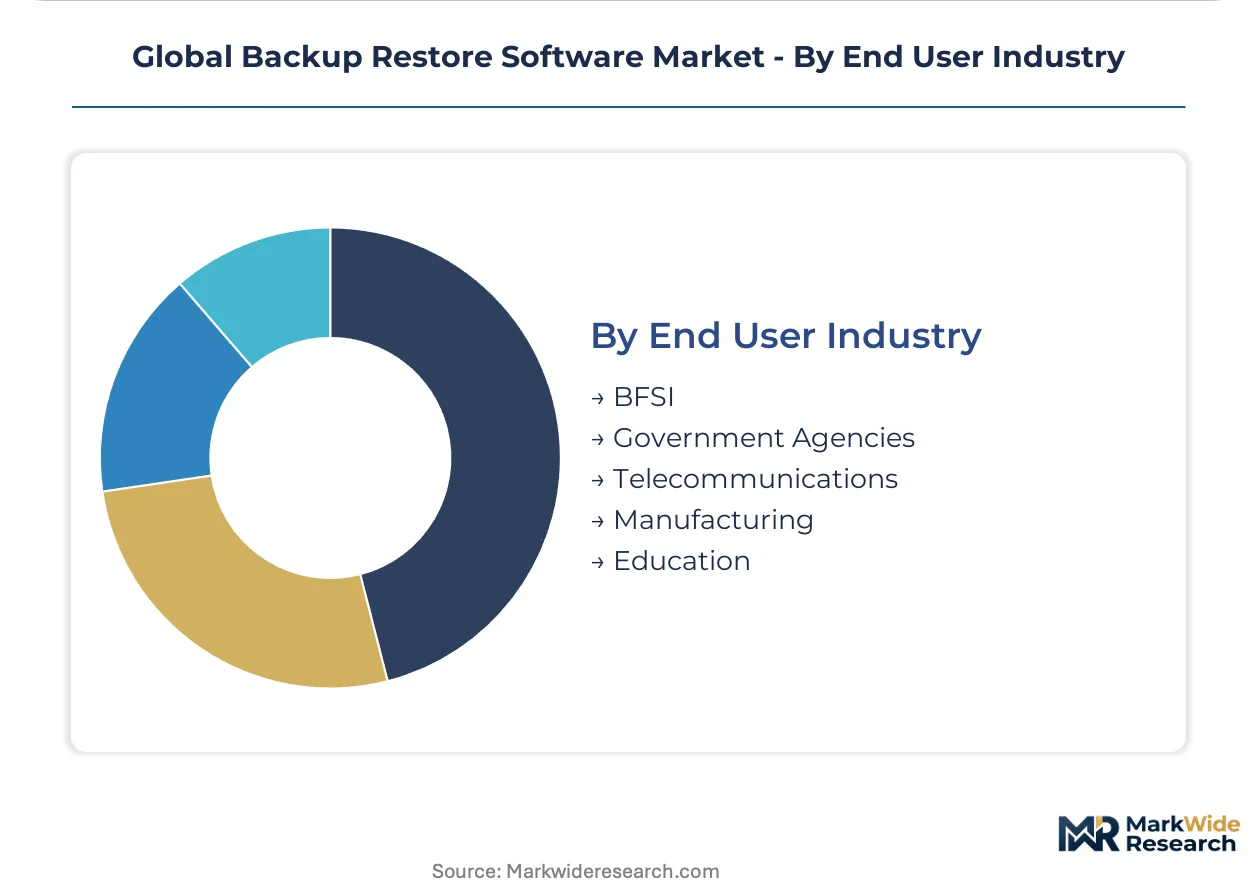
End User Industry:
Sector-specific regulatory density shapes product certification requirements and sales cycle length.
- BFSI:Multi-jurisdictional recordkeeping with SEC, FINRA, and Basel-aligned retention schedules. US broker-dealers under SEC Rule 17a-4 mandate immutable WORM storage for trade records. BFSI generates the highest average contract value across industries.
- Government Agencies:Classified and unclassified tiering with FedRAMP and StateRAMP authorization requirements. Federal civilian agencies in the United States drive demand for sovereign cloud instances with domestic encryption modules. Government Agencies are expanding procurement most aggressively.
- Telecommunications:Subscriber data protection with national security intercept compliance.
- Manufacturing:OT-IT convergence with industrial control system backup under Japan METI guidelines.
- Education:Student information system protection with FERPA-aligned access controls.
Leading by committed annual value: BFSI. Fastest budget growth: Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Jurong Innovation District tax incentives concentrate backup infrastructure investment for Asia-Pacific headquarters operations. Multinational enterprises leverage these zones to deploy sovereign cloud instances serving regional data residency mandates.
United States
Healthcare networks and financial services drive demand concentration across hospital systems and broker-dealers. SEC Rule 17a-4 mandates immutable WORM storage for trade records, compressing procurement cycles. The Dallas-Fort Worth metro anchors disaster recovery colocation capacity serving central US enterprise continuity requirements.
Germany
Automotive manufacturers under GDPR pressure adopt hybrid architectures keeping primary copies domestic. The country's national data protection authority enforces strict cross-border transfer protocols. Bavaria's industrial corridor hosts Gaia-X aligned sovereign cloud deployments for manufacturing backup orchestration.
Japan
Financial exchanges deploy sub-minute recovery systems for trading continuity under METI operational technology guidelines. The central bank's payment system oversight extends backup scope to critical financial infrastructure. Tokyo's financial district concentrates CDP deployment for securities clearing operations.
China
Critical information infrastructure operators must use domestic encryption modules under GB standards. Multinational enterprises architect separate backup instances for PRC operations. Shanghai's Pudong district hosts certified data centers serving compliance-extended sales cycles for foreign vendors.
Australia
Critical infrastructure operators prioritize ransomware protection under the national security framework adjacent to healthcare continuity requirements. The national therapeutic goods administration influences operational resilience standards. Sydney's technology corridor concentrates managed service provider aggregation of metered protection services.
Global Backup Restore Software Market Competitive Landscape
United States producers anchor the scale-driven tier; European specialists hold differentiated positions in compliance-intensive segments. Market structure concentrates around integrated platform vendors and modular component suppliers. Three archetypes dominate: virtual environment recovery specialists, cyber protection integrators, and archival governance providers. Competitive moves center on strategic partnerships for sovereign cloud certification and portfolio diversification into immutable object storage architectures.
Within the virtual environment tier, Veeam Software exemplifies channel-density positioning. Acronis occupies a position bridging backup and endpoint security integration. Commvault anchors the archival governance archetype for regulated industry penetration.
| Leading Market Players |
|---|
| Veeam Software |
| Acronis |
| Commvault |
| Veritas Technologies |
| IBM |
| Dell Technologies |
| Microsoft |
| Cohesity |
| Rubrik |
| Others |
Supply & Pricing Matrix
EU AI Act training data lineage mandates gate qualified supply access for backup restore vendors while compressing premium-tier pricing bandwidth for compliant architectures. Sovereign cloud certification timelines extend procurement cycles, forcing buyers to absorb compliance-premium structures or defer migration roadmaps.
Pricing Analysis
Lead-time-driven pricing stratification rewards immediate deployment capacity with premium positioning while spot inventory of standard SaaS licenses trades at contracted discounts. Subscription tiers anchored in ransomware protection modules and immutable storage guarantees command the widest spreads, with certified EU-resident deployments carrying material premiums over standard multi-tenant alternatives. Pricing pressure stems from hyperscaler egress fee volatility eroding long-term retention economics. Mid-market healthcare networks exhibit acute price sensitivity, whereas BFSI incumbents under SEC Rule 17a-4 mandates prioritize compliance-grade immutability over unit cost.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand for integrated backup platforms, while managed service providers aggregate mid-market procurement through metered consumption models. Engineering talent concentrates in the United States, Germany, and Israel, with cryptographic module development anchored in domestic certification regimes. Software supply chains draw from open-source replication frameworks, proprietary deduplication engines, and sovereign cloud infrastructure partnerships. Single-source vulnerability in EU-certified encryption libraries poses structural risk. Distribution runs through value-added resellers in regulated verticals and direct hyperscaler marketplaces for cloud-native deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where GDPR and EU AI Act audit-trail obligations erect barrier-to-entry moats favoring certified incumbents with established channel density.
For Market Incumbents: Deploy sovereign cloud certification investments to lock out unqualified competitors from European procurement cycles. Veeam Software's channel density model offers a template for defensive positioning. Counter Cohesity and Rubrik's cloud-native architectures by accelerating API granularity roadmaps. Threat substitution from immutable object storage vendors demands rapid portfolio diversification into S3-compatible vaulting tiers. For New Entrants and Emerging Players: Immutable object storage for financial services WORM compliance represents the most penetrable white-space target, with Australian critical infrastructure operators under national security frameworks offering beachhead demand. Edge computing backup orchestration for distributed manufacturing footprints remains undersupplied. Go-to-market execution should anchor in managed service provider aggregation partnerships rather than direct enterprise sales builds. For Investors and Strategic Acquirers: FDA 21 CFR Part 11 healthcare certification attainment is the leading indicator that a target has crossed the compliance moat separating viable acquisition candidates from stranded technology bets. Long-term viability across the analysis window rests on regulatory certification breadth rather than feature velocity. Acquisition target archetype: modular backup component vendors with EU sovereign cloud partnerships and METI-aligned operational technology credentials. Signal to watch: Gaia-X and Bleu initiative certification announcements as sovereign cloud demand inflection markers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified cyber protection spanning backup and endpoint security satisfies Acronis-style buyer consolidation preferences. |
| Strategic Partnership | Gaia-X certification partnerships unlock German automotive and manufacturing procurement under GDPR pressure. |
| Acquisition of Specialist Firm | Immutable object storage technology addresses financial services WORM mandates displacing deduplication appliances. |
| Geographic Expansion | Shanghai Pudong data center certification navigates China's GB standards for critical infrastructure operators. |
| Product Launch | Continuous data protection modules with sub-minute RTOs capture METI-aligned Japanese financial exchange demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews across backup software vendor product managers, enterprise IT procurement officers, channel partner technical leads, and healthcare compliance officers. SEC Rule 17a-4 enforcement patterns, FDA 21 CFR Part 11 audit documentation, and EU AI Act implementation guidance formed regulatory intelligence foundations. Bottom-up deployment mode sizing triangulated against top-down vendor revenue attribution across cloud, hybrid, and on-premises architectures.
Granularity-level modeling segmented the market by deployment mode, solution offering, application use case, and end-user industry vertical, with regional adoption patterns and regulatory cluster alignment as cross-cutting dimensions. CAGRs derived from elasticity-adjusted demand curves incorporating ransomware incident frequency trajectories and sovereign cloud infrastructure buildout timelines. Hyperscaler capex disclosures and healthcare digitization spend patterns informed sector-specific forecast inputs throughout the projection horizon.
Several conditions sit outside the modeled scope, including abrupt encryption export control revisions, hyperscaler pricing regime discontinuities, and unanticipated regulatory mutual recognition agreements. Forecasts reflect assumptions regarding compliance timeline adherence and sovereign cloud certification throughput capacity. Periodic stress-testing of base assumptions against METI guideline evolution and GB standards enforcement intensity is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Address Verification Software Market
Software & Services
Enterprise Application Market
Software & Services
Global App Store Optimization Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Global Customer Experience Software Market
Software & Services
Attendance Management Software Market
Software & Services
Global Content Management Software Market
Software & Services
Augmented Reality Software Development Kit Market
Software & Services
Open Source Bug Tracking Tool Market
Software & Services
Global CMMS Software Market
Software & Services
Saas-Based Expense Management Market
Software & Services
Jobsite Management Software Market
Software & Services
Application Lifecycle Management (ALM) Market
Software & Services
Bankruptcy Software Market
Software & Services
Automotive Hypervisor Market
Software & Services
Global Ipad POS Software Market