
 United States IT Outsourcing Market | 2026-2036
United States IT Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
United States IT Outsourcing Market Insights
Healthcare demand for compliant data infrastructure is decoupling from traditional on-premise outsourcing models. IBM Corporation leverages its federal contracting heritage to anchor security-cleared cloud migration programs for public sector clients. Accenture competes through specialized healthcare payer platforms that integrate HIPAA audit trails with AI-driven claims processing. Cognizant Technology Solutions dominates pharmaceutical IT services by sustaining deep FDA validation expertise in computerized systems.
United States IT Outsourcing encompasses the contractual delegation of information technology functions—including application development, infrastructure operations, and technical support—to external providers, typically governed by service-level agreements specifying uptime thresholds, response times, and data sovereignty requirements. The primary purpose centers on cost optimization, access to specialized talent pools, and operational scalability without fixed capital commitments. Infrastructure management retains the largest revenue share among service types due to persistent enterprise data center footprints, though cloud-based deployment models capture the fastest expansion as organizations exit owned hardware. Small and medium enterprises represent an underpenetrated end-user tier where standardized service bundles can displace fragmented vendor relationships.
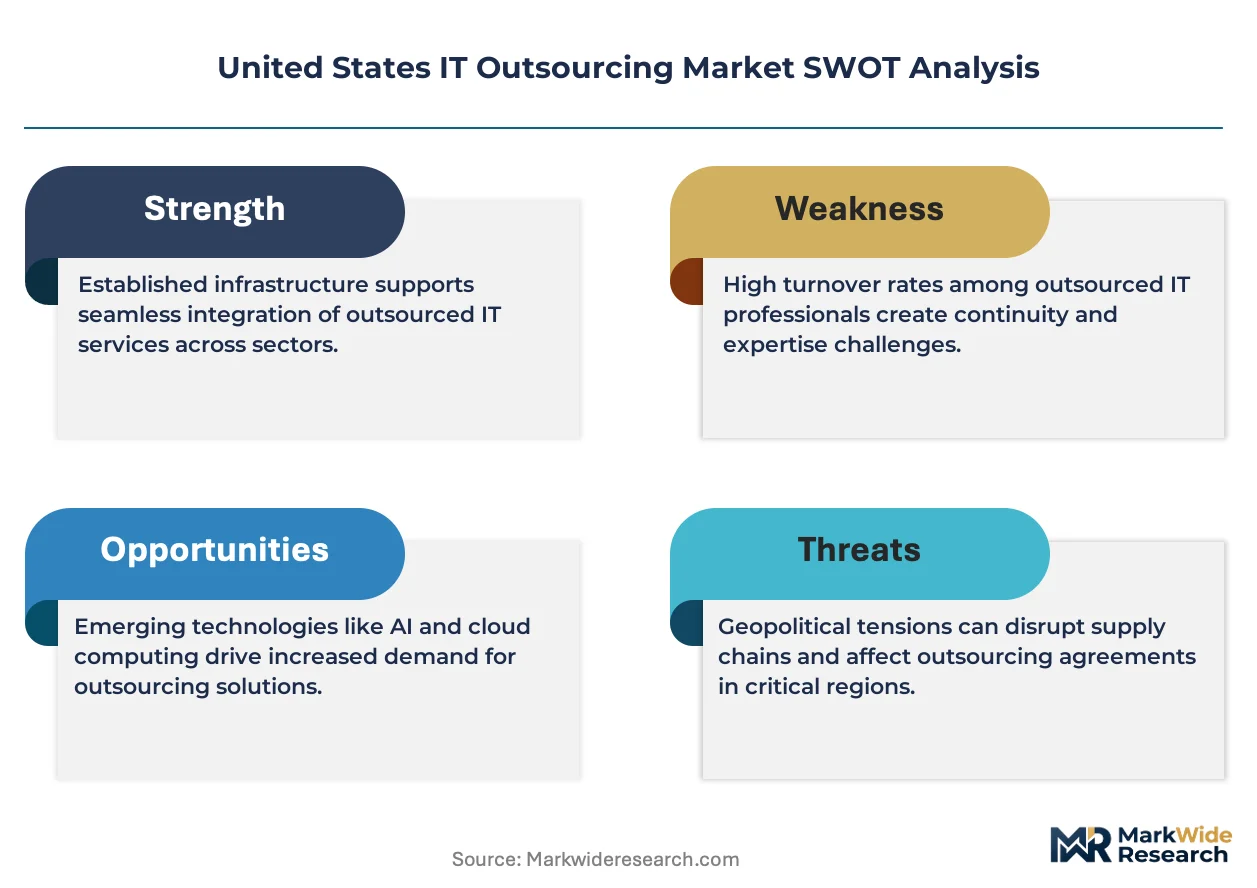
FDA oversight of software-as-medical-device, HIPAA security rule enforcement by HHS, and NIST cybersecurity framework compliance requirements collectively elevate vendor qualification barriers and contract complexity. FERC grid reliability standards and SEC disclosure rules for material cyber incidents further expand the regulated scope of outsourced IT governance. Stakeholders must evaluate whether provider ecosystems can absorb escalating federal compliance obligations without fragmenting service continuity.
Market Dynamics
Federal cloud migration mandates are compressing procurement timelines and forcing hybrid architecture adoption across defense, healthcare, and energy agencies. This structural pressure is reconfiguring vendor qualification criteria and contract structures throughout the ecosystem.
Growth Catalysts
- HIPAA Security Rule Amendments:Healthcare providers are expanding managed services contracts to achieve technical safeguard compliance, creating durable demand for security-cleared infrastructure operators.
- AI-Driven Claims Processing:Healthcare payers require specialized platforms integrating audit trails with machine learning, pulling outsourced development toward regulated verticals.
- Texas Enterprise Clustering:Dallas-Fort Worth metroplex concentration of captive centers and third-party providers generates talent density and contract proximity advantages.
Market Restraints
- Security Clearance Bottlenecks:Federal contracting requirements restrict eligible vendor pools, concentrating procurement among established defense contractors and extending onboarding cycles.
- Hybrid Architecture Complexity:Organizations maintaining on-premise footprints alongside cloud deployments face integration cost escalation and operational fragmentation.
- Domestic Labor Cost Premium:Onshore delivery mandates for sensitive data categories compress margin structures relative to offshore alternatives.
Strategic Opportunities
- Small and Medium Enterprise Standardization:Fragmented vendor relationships among mid-market buyers create openings for bundled service offerings with predictable pricing.
- FDA Software-as-Medical-Device Pathway:Pharmaceutical and device manufacturers require validated computerized systems, elevating demand for specialized compliance engineering.
- NIST Cybersecurity Framework Convergence:Federal contractor requirements are diffusing into private sector procurement, expanding addressable market for certified security operations.
Industry Challenges
- Cleared Talent Scarcity:Security-cleared cloud architects and compliance engineers command premium compensation, constraining delivery scale for public sector programs.
- Multi-Cloud Integration Friction:Federal agencies mandate specific cloud environments while commercial operations run on competing platforms, complicating unified service delivery.
- Continuous Authorization Timelines:FedRAMP and agency-specific security assessments extend sales cycles and delay revenue recognition for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States IT Outsourcing Market |
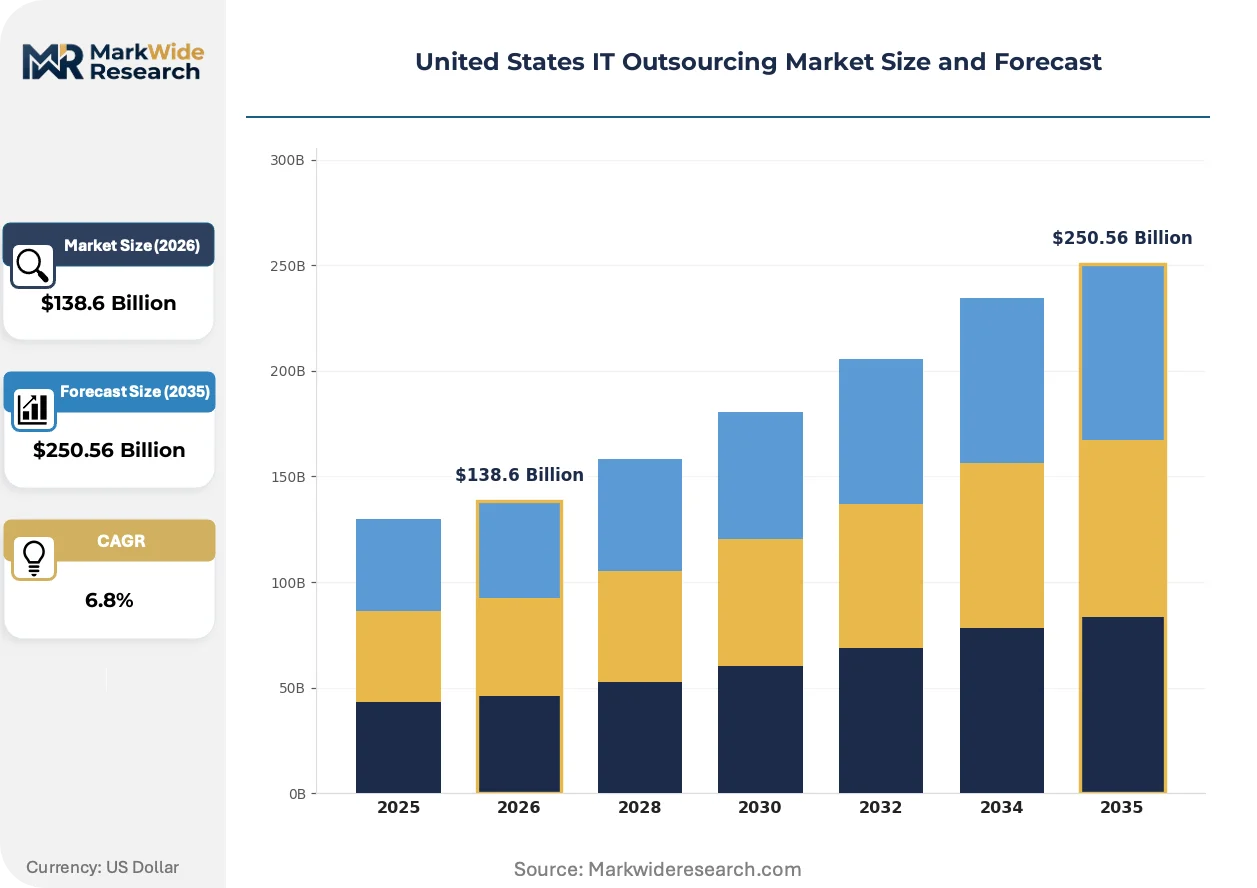
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $250.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Application Development, Infrastructure Management, Business Process Outsourcing, Technical Support End User: Small Enterprises, Medium Enterprises, Large Enterprises, Public Sector Deployment Model: On-Premise, Cloud-Based, Hybrid, Dedicated Hosting Industry Vertical: Healthcare, Finance, Retail, Telecommunications |
| Companies Covered | IBM Corporation, Accenture, Cognizant Technology Solutions, NTT Corporation, Hewlett Packard Enterprise Company, DXC Technology Company, Infosys, Capgemini, CDW Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States IT Outsourcing Market Trends and Innovations
Generative AI capabilities are embedding into service delivery models, while regulatory compliance automation and outcome-based contracting are restructuring buyer-provider relationships across federal and commercial segments.
Agentic AI systems are rewriting operational workflows across infrastructure monitoring and incident response functions. Federal agencies and healthcare payers are piloting autonomous remediation tools that compress mean-time-to-resolution metrics. This capability shift is enabling tier-one providers to displace lower-margin staff augmentation contracts with platform-driven managed services.
HHS enforcement of HIPAA security rule amendments is elevating technical safeguard requirements for business associate agreements. Healthcare providers now mandate encrypted data transmission, access logging, and breach notification automation as contractual table stakes. California's Bay Area health systems are responding by consolidating vendor relationships around specialized healthcare IT operators with dedicated compliance engineering.
Enterprise buyers are compressing contract durations and unbundling transformation programs from steady-state operations. Federal procurement officers now separate cloud migration milestones from ongoing infrastructure management, creating discrete competitive events for each phase. This pattern is most visible in defense and intelligence community contracting, where multi-vendor strategies reduce concentration risk.
United States IT Outsourcing Market Segmentation
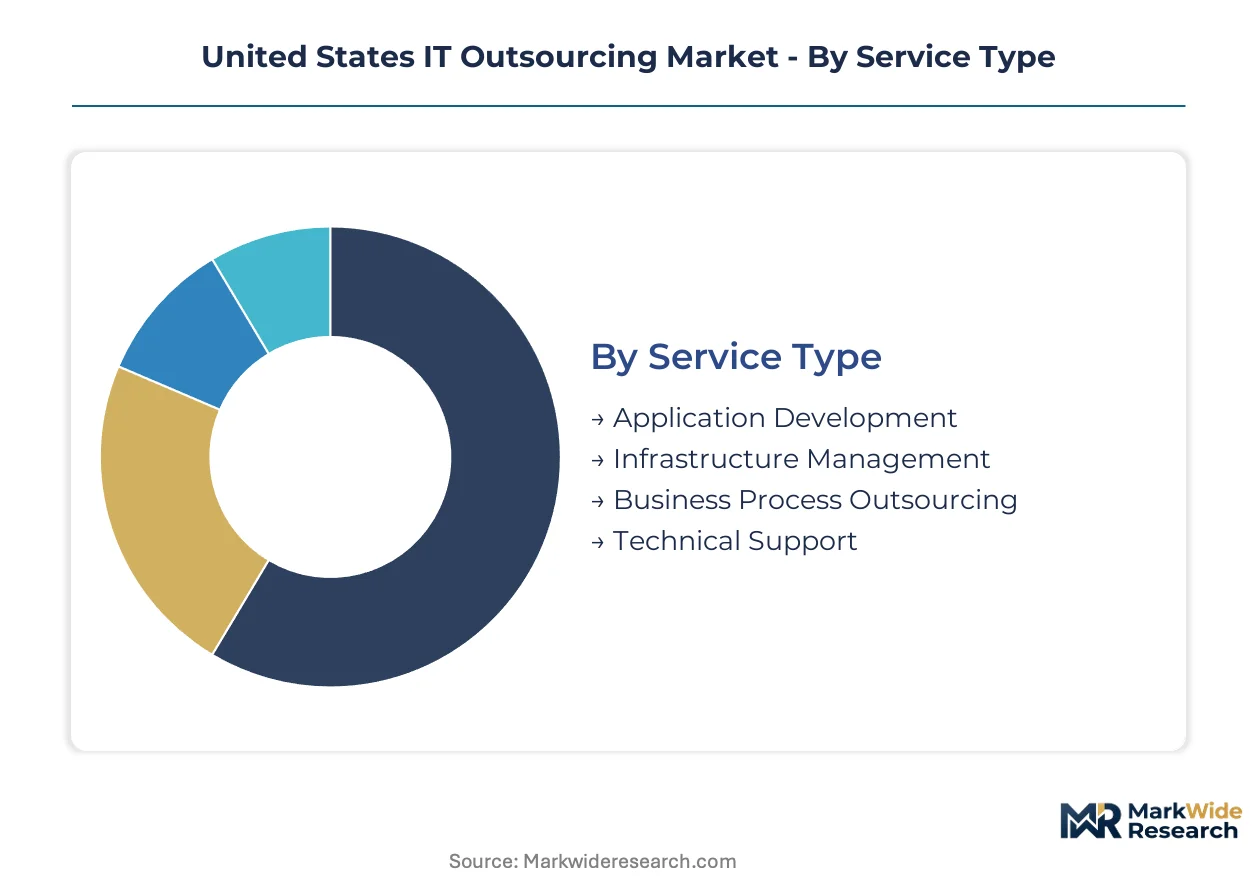
Segmentation in the United States IT Outsourcing Market reveals how procurement priorities diverge across buyer sophistication, compliance exposure, and infrastructure maturity. Understanding these fault lines exposes where standardized offerings displace custom engagements and where specialized capabilities command premium positioning.
Service Type:
Buyers allocate budget based on whether the function controls revenue operations or supports back-office efficiency, creating divergent vendor selection criteria across service categories.
- Infrastructure Management:Encompasses data center operations, network administration, and server maintenance under service-level agreements specifying uptime thresholds. Demand concentrates among large enterprises in Texas's Dallas-Fort Worth metroplex, where captive centers and third-party providers cluster to access security-cleared talent pools for federal-adjacent workloads.
- Application Development:Covers custom software engineering, legacy modernization, and mobile application creation governed by agile delivery frameworks. Healthcare payers in California's Bay Area are pulling outsourced development toward regulated verticals, requiring platforms that integrate HIPAA audit trails with AI-driven claims processing capabilities.
- Business Process Outsourcing:Delegates operational workflows including finance, HR, and customer service functions to external operators. Mid-market buyers seek bundled offerings with predictable pricing to displace fragmented vendor relationships.
- Technical Support:Delivers end-user helpdesk services, incident resolution, and knowledge base maintenance through tiered escalation protocols. Public sector agencies mandate onshore delivery for sensitive data categories, compressing margin structures relative to offshore alternatives.
Volume sits with Infrastructure Management; growth tilts toward Application Development.
End User:
Organizational scale determines whether buyers prioritize compliance engineering depth, cost predictability, or operational flexibility in vendor contracts.
- Large Enterprises:Maintain complex multi-year contracts spanning transformation and steady-state operations with tier-one providers. Procurement officers now separate cloud migration milestones from ongoing infrastructure management, creating discrete competitive events for each phase.
- Public Sector:Federal agencies and state governments impose security clearance requirements, FedRAMP certification, and agency-specific security assessments that extend sales cycles. Defense and intelligence community contracting favors multi-vendor strategies to reduce concentration risk.
- Medium Enterprises:Represent an underpenetrated tier where standardized service bundles can displace fragmented vendor relationships through simplified contracting.
- Small Enterprises:Rely on consumption-based pricing and pre-configured service catalogs with limited customization to minimize fixed commitments.
Contract value concentrates with Large Enterprises; expansion opportunities cluster around Medium Enterprises.
Deployment Model:
Infrastructure ownership preferences are shifting as federal mandates and compliance obligations reconfigure the economics of cloud migration.
- Hybrid:Combines on-premise data center assets with cloud-based workloads orchestrated through unified management platforms. Federal cloud migration mandates are compressing procurement timelines and forcing hybrid architecture adoption across defense, healthcare, and energy agencies.
- Cloud-Based:Delivers compute, storage, and application services through third-party hyperscale providers with consumption-based pricing. HHS enforcement of HIPAA security rule amendments elevates technical safeguard requirements, mandating encrypted data transmission and access logging as contractual table stakes.
- On-Premise:Retains dedicated hardware and software within buyer-controlled facilities for workloads with stringent data sovereignty requirements. Persistent enterprise data center footprints sustain demand despite cloud expansion pressures.
- Dedicated Hosting:Provides single-tenant infrastructure environments managed by external providers without shared resource pooling. Financial services firms favor this model for transaction processing systems requiring isolated security boundaries.
Installed base remains with On-Premise; Hybrid architectures are climbing the fastest as organizations exit owned hardware while maintaining compliance-critical workloads.
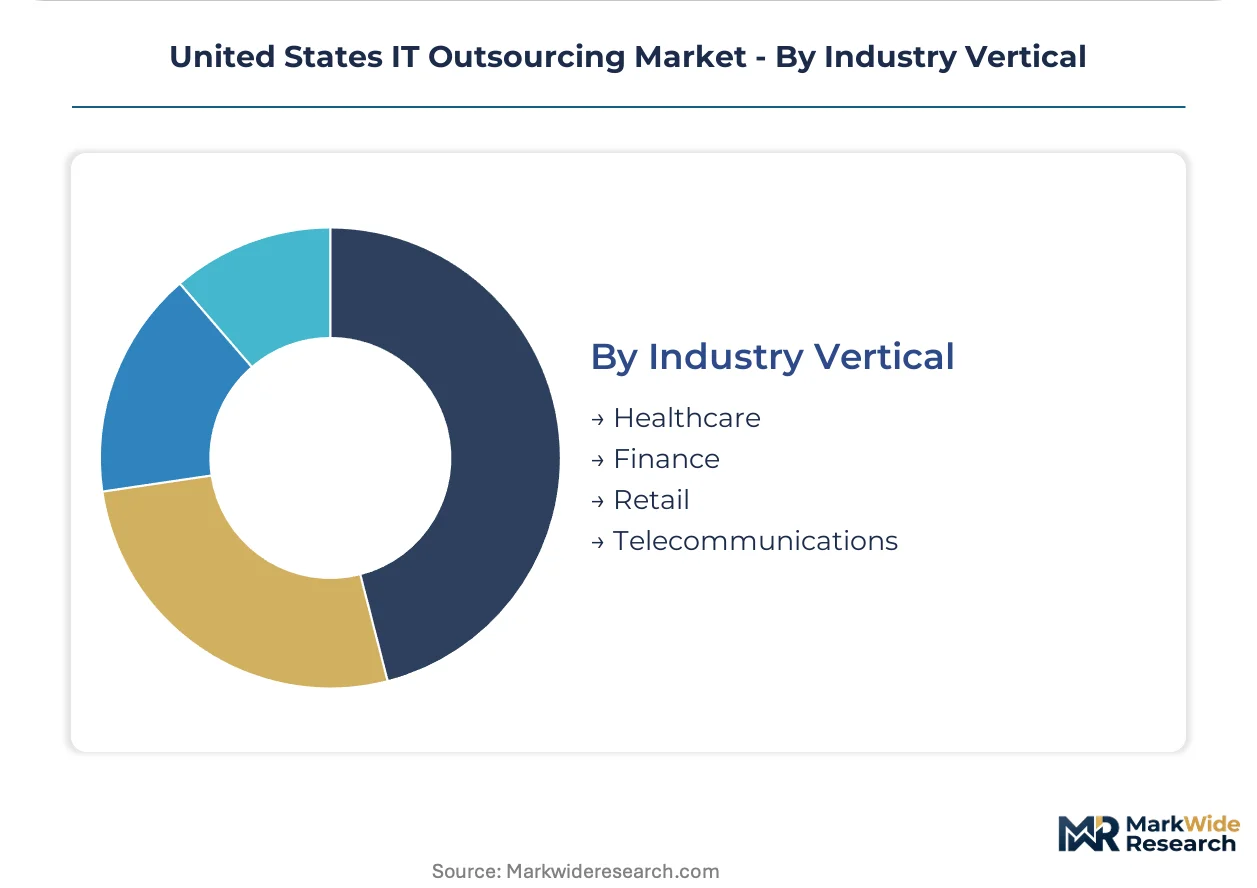
Industry Vertical:
Sector-specific regulatory exposure creates vendor qualification barriers that reshape competitive dynamics within each vertical.
- Healthcare:Providers and payers face HIPAA security rule amendments and FDA oversight of software-as-medical-device, elevating demand for specialized compliance engineering. California's Bay Area health systems are consolidating vendor relationships around operators with dedicated healthcare IT expertise.
- Finance:Banks, insurers, and asset managers navigate SEC disclosure rules for material cyber incidents alongside state-level data protection requirements. NIST Cybersecurity Framework compliance is diffusing from federal contractors into private sector procurement.
- Retail:E-commerce platforms and brick-and-mortar chains prioritize scalable infrastructure for seasonal demand spikes and omnichannel integration. PCI-DSS compliance requirements shape vendor selection for payment processing functions.
- Telecommunications:Carriers and cable operators manage network operations centers and customer billing systems under FCC regulatory oversight. 5G network rollouts are expanding edge computing requirements for low-latency service delivery.
Compliance complexity peaks in Healthcare; Retail presents the most price-sensitive procurement environment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters along the coasts and Texas corridor, while consumption spreads across federal agencies and healthcare systems nationwide. This geographic split shapes vendor location decisions and talent acquisition strategies.
California
Bay Area health systems drive demand for HIPAA-compliant cloud infrastructure and AI-integrated claims platforms. State privacy regulations under CCPA complement federal HIPAA amendments, elevating data governance requirements. San Francisco and San Jose anchor a dense ecosystem of healthcare IT specialists and security-cleared engineering talent.
Texas
Dallas-Fort Worth metroplex concentration of enterprise captive centers and third-party providers generates contract proximity advantages for federal-adjacent workloads. State economic development incentives support data center expansion and workforce training programs. Austin's technology corridor adds software engineering capacity for regulated vertical applications.
Virginia
Northern Virginia's data center alley processes massive federal cloud migration workloads under compressed procurement timelines. Proximity to defense and intelligence agencies creates security clearance bottlenecks that restrict eligible vendor pools. Fairfax and Loudoun counties host hyperscale facilities serving hybrid architecture mandates.
Illinois
Chicago's financial services sector demands NIST Cybersecurity Framework compliance for outsourced infrastructure operations. State procurement rules favor multi-vendor strategies that reduce concentration risk in critical systems. The metro area sustains specialized technical support operations for onshore delivery mandates.
New York
New York City health payers and financial institutions require integrated HIPAA audit trails with AI-driven processing capabilities. State cybersecurity disclosure rules for material incidents expand governance scope for outsourced IT functions. The metro anchors compliance engineering expertise for SEC-regulated entities.
United States IT Outsourcing Market Competitive Landscape
Top-tier vendors anchor federal and healthcare verticals, while mid-tier specialists compete on price and regional proximity. The market structure concentrates around providers with security clearances, FedRAMP certification, and specialized compliance engineering depth. Strategic archetypes include federal contractors with legacy infrastructure expertise, healthcare-focused platforms with AI integration capabilities, and global systems integrators with multi-cloud orchestration skills. Dominant competitive moves center on M&A to acquire cleared talent pools and strategic partnerships to accelerate FedRAMP authorization timelines.
Within the federal contracting tier, IBM Corporation and Accenture exemplify providers leveraging security-cleared heritage for public sector cloud migration programs. Cognizant Technology Solutions occupies a position among healthcare-specialized operators sustaining FDA validation expertise. These three anchors represent distinct competitive vectors: federal heritage, vertical platform integration, and regulatory compliance engineering.
| Leading Market Players |
|---|
| IBM Corporation |
| Accenture |
| Cognizant Technology Solutions |
| NTT Corporation |
| Hewlett Packard Enterprise Company |
| DXC Technology Company |
| Infosys |
| Capgemini |
| CDW Corporation |
| Others |
Pricing and Supply Chain Analysis
Security-cleared cloud architects in Northern Virginia command premium compensation that compresses margin structures and widens spreads between onshore federal contracts and commercial alternatives. Labor-cost differentials between cleared talent pools in Virginia's data center alley and non-cleared engineering centers in Texas and California segment pricing tiers across the market.
Pricing Analysis
Margin tightening in federal-adjacent services reflects security clearance bottlenecks that restrict eligible vendor pools. Three-tier pricing structure across premium cleared-federal, standard healthcare-compliant, and economy commercial segments separates buyers by compliance exposure. Price differentiation hinges on FedRAMP authorization status and HIPAA audit trail integration. Mid-market enterprises exhibit highest price sensitivity, while defense agencies accept cost premiums for cleared delivery.
Supply Chain Analysis
Cleared talent scarcity in Virginia, Texas, and California constrains delivery scale for public sector programs. The supply chain draws from domestic labor markets exclusively due to onshore delivery mandates for sensitive data categories. Hyperscale cloud infrastructure, compliance engineering expertise, and security-cleared personnel constitute critical inputs. Single-source vulnerability concentrates around cleared talent pipelines. Distribution runs through direct federal contracting channels and healthcare system procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into compliance engineering capabilities and cleared talent development programs defines competitive positioning. Players are pursuing backward integration into security-cleared workforce pipelines to secure delivery capacity.
For Market Incumbents: Acquire specialized healthcare IT operators with FDA validation expertise to anchor pharmaceutical verticals. Consolidate cleared talent pools through targeted hiring in Northern Virginia and Texas corridors. Defense agency multi-vendor strategies threaten concentration risk for established federal contractors.
For New Entrants and Emerging Players: Enter via standardized service bundles for underpenetrated medium enterprises seeking predictable pricing. Target California's Bay Area health systems consolidating vendor relationships around specialized compliance engineering. Lead with AI-integrated claims processing platforms that displace fragmented legacy relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with healthcare-specialized platforms given HIPAA security rule amendment enforcement acceleration. Long-term viability favors operators with FedRAMP certification and multi-cloud orchestration capabilities. Watch NIST Cybersecurity Framework diffusion into private sector procurement as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Compresses sales cycles for new entrants seeking federal cloud migration contracts. |
| Healthcare Payer Platform Integration | Consolidates vendor relationships around HIPAA-compliant AI-driven claims processing. |
| Cleared Talent Pipeline Development | Secures delivery capacity for defense and intelligence community cloud programs. |
| Multi-Cloud Orchestration Capability | Addresses federal agency mandates for specific cloud environments alongside commercial platforms. |
| Medium Enterprise Bundle Standardization | Displaces fragmented vendor relationships through simplified contracting and predictable pricing. |
Research Methodology
Independent corroboration across CTOs at healthcare payers, federal procurement officers, cloud platform engineers, and compliance engineering directors underwrites the qualitative findings. Secondary validation draws from SEC filings of tier-one providers, FedRAMP authorization databases, CMS Medicare reimbursement data, and hyperscaler capex disclosures. Bottom-up service-line modeling and top-down macroeconomic triangulation anchor the analytical framework.
Comparable-period anchoring to historical federal contracting cycles and healthcare IT procurement patterns structures the projection methodology. Segmentation dimensions span deployment model, organization size, industry vertical, compliance exposure tier, and regional talent cluster. CAGRs derive from trend extrapolation adjusted for regulatory enforcement intensity and cloud migration mandate timelines. Workforce availability constraints and FedRAMP authorization backlogs constitute key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated HIPAA enforcement or federal budget sequestration scenarios. Projections reflect assumptions regarding clearance pipeline expansion and hybrid architecture adoption curves. A small set of triggers—FedRAMP timeline compression, HHS audit frequency changes, and defense cloud contract awards—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
BPO Business Analytics Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Legal Process Outsourcing (LPO) Market
Business Process Outsourcing (BPO)
South Africa Business Process Outsourcing Market
Business Process Outsourcing (BPO)
Front Office BPO Services Market
Business Process Outsourcing (BPO)
US Managed Print Services Market
Business Process Outsourcing (BPO)
Service Bureau Market
Business Process Outsourcing (BPO)
Labor Outsourcing Service Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market
Business Process Outsourcing (BPO)
Middleoffice BPO Services Market
Business Process Outsourcing (BPO)
Global Knowledge Process Outsourcing Market
Business Process Outsourcing (BPO)
Global Outsourced Sales Service Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market