
 MVNO Market | 2026-2036
MVNO Market Size, Share, and Industry Trends Forecast 2026-2036
MVNO Market Outlook
Subscription billing software is hardening into the core monetization layer for virtual network operators, transforming how connectivity gets packaged and sold. Transatel (NTT) leverages its multi-country SIM provisioning infrastructure to sustain pan-European enterprise contracts. Tata Communications anchors its MVNO stack with submarine cable backhaul integration, while KORE Wireless specializes in IoT-centric network slicing for industrial telemetry.
A mobile virtual network operator leases wholesale wireless capacity from host mobile network operators and resells branded services to end users, operating through software-defined core functions rather than owning physical radio access infrastructure. Full-MVNO architectures command the deepest margin pools because these operators control their own core networks and numbering resources, whereas Light-MVNO and Reseller configurations sacrifice margin for faster market entry. Bundled Plans and Unlimited Offerings attract residential subscribers seeking cost transparency, while Business customer segments generate superior lifetime value through multi-line enterprise contracts.
The FCC governs wholesale access terms and interconnection pricing in the United States, while the EU's Electronic Communications Code mandates national regulators to enforce open wholesale markets across member states. TRAI in India imposes floor tariffs and foreign investment caps that constrain MVNO pricing flexibility and capital structure. Stakeholders must monitor spectrum re-farming schedules and wholesale rate negotiations as host operators balance retail competition against infrastructure monetization.
Market Dynamics
Subscription billing software is hardening into the core monetization layer for virtual network operators, transforming how connectivity gets packaged and sold while compressing time-to-market for service launches.
Growth Catalysts
- Enterprise IoT Deployments:Industrial fleet operators are expanding adoption of connected vehicle telemetry, creating sustained wholesale demand for network slicing capabilities.
- EU Electronic Communications Code:This mandate requires national regulators to enforce open wholesale markets across member states, reducing barriers to MVNO market entry.
- Private Network Buildouts:German industrial manufacturers are deploying captive MVNO infrastructure for connected logistics, generating specialized system integration demand.
Market Restraints
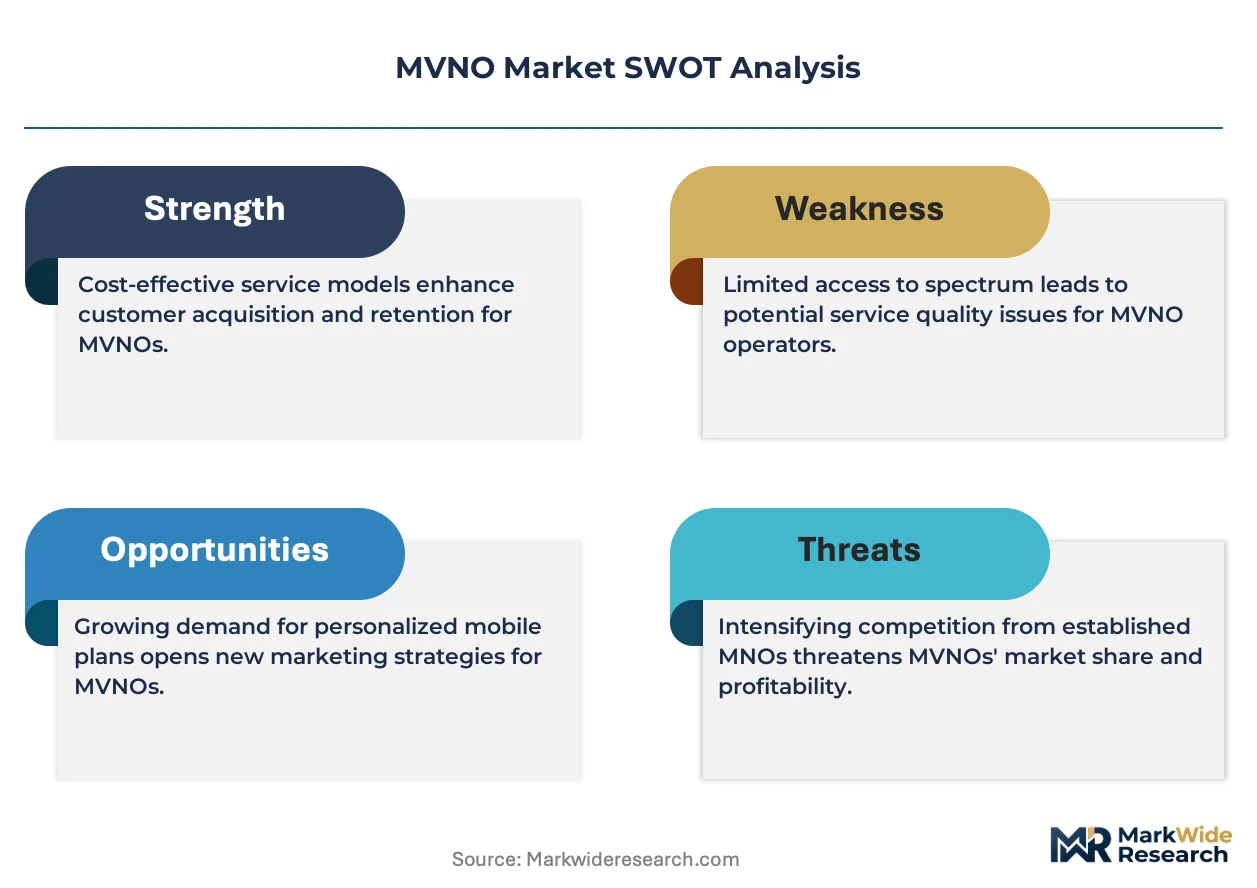
- Host Operator Concentration:Wholesale capacity access depends on three to four national mobile network operators in most markets, creating asymmetric bargaining power.
- Spectrum Re-farming Uncertainty:Host operators balance retail competition against infrastructure monetization, delaying long-term wholesale rate agreements.
- Core Network Capital Requirements:Full-MVNO architectures demand substantial upfront investment in software-defined core functions and numbering resources.
Strategic Opportunities
- Pan-European Enterprise Contracts:Multi-country SIM provisioning infrastructure enables unified connectivity management across fragmented national markets.
- Submarine Cable Backhaul Integration:Operators with captive submarine fiber assets can compress transmission costs for international enterprise traffic.
- Industrial Telemetry Specialization:Network slicing optimized for low-latency sensor data creates defensible positioning in manufacturing and energy verticals.
Industry Challenges
- Regulatory Fragmentation:TRAI floor tariffs and foreign investment caps in India constrain pricing flexibility and capital structure design.
- Interconnection Negotiation Complexity:Protracted wholesale rate disputes with host operators delay service launches and compress operating margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MVNO Market |
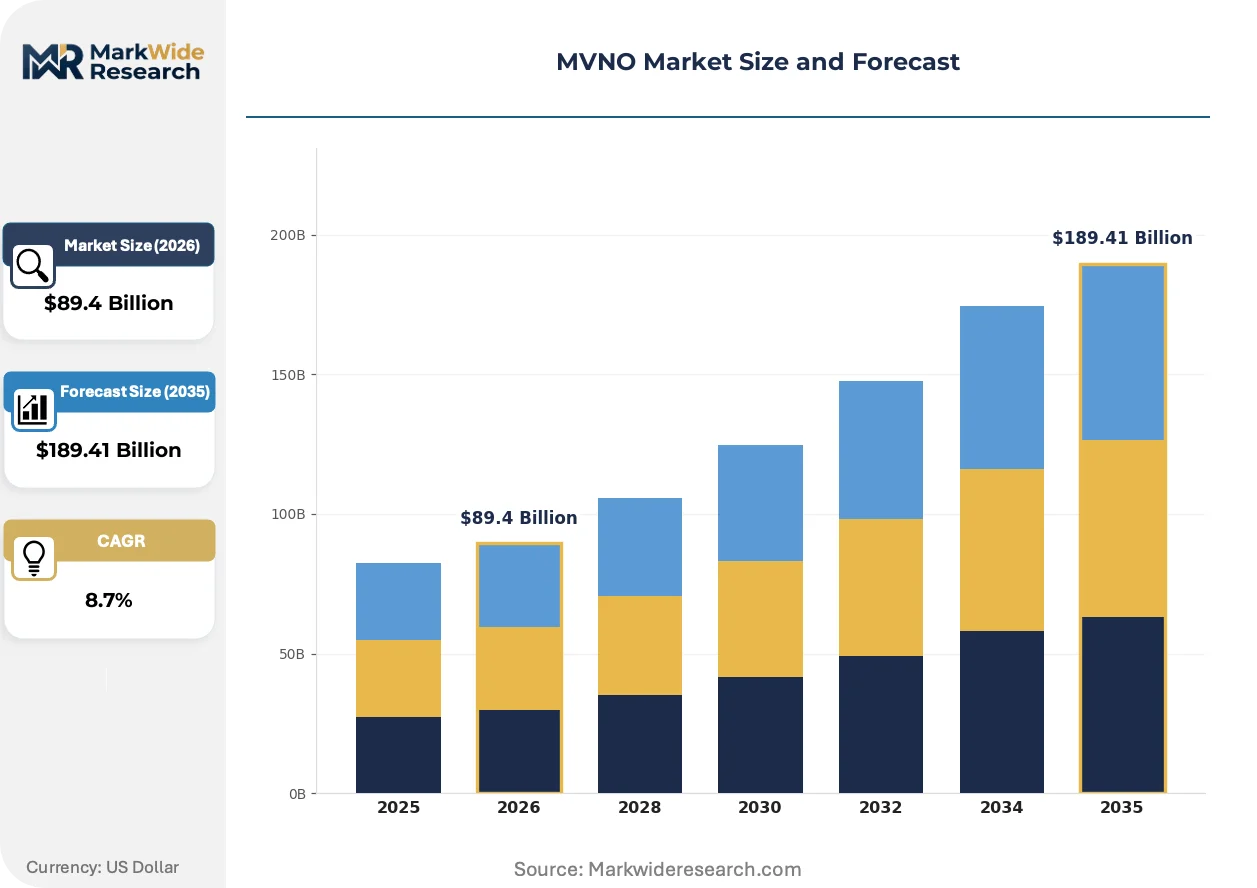
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $189.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-MVNO, Light-MVNO, Reseller, Niche Player Customer Type: Residential, Business, Government, Senior Citizens Pricing Model: Prepaid, Postpaid, Bundled Plans, Unlimited Offerings Technology: GSM, CDMA, LTE, VoLTE |
| Companies Covered | Plintron, Transatel (NTT), Pareteum (Circles), Syniverse, Amdocs, Tata Communications, BICS, Telefonica Tech, KORE Wireless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MVNO Market Strategic Shifts
Software-defined core functions are displacing proprietary hardware stacks, enabling virtual operators to launch services without physical infrastructure ownership while compressing capital deployment timelines.
Network function virtualization is decentralizing radio access network management, allowing MVNOs to deploy localized edge computing nodes without host operator dependency. Industrial manufacturers in Germany and the Netherlands are piloting this architecture for private factory-floor networks. The technology is decentralizing control over quality-of-service guarantees, previously concentrated in host operator core networks.
The FCC's wireless spectrum auction framework is altering network access economics by introducing new wholesale capacity entrants and dynamic spectrum sharing mechanisms. Virtual operators in the United States must now evaluate millimeter-wave and CBRS bands alongside traditional macro network leases. This regulatory architecture most affects regional MVNOs seeking to differentiate through coverage quality rather than price.
Enterprise buyers are consolidating connectivity procurement under single-vendor managed service contracts, displacing multiple carrier relationships. Manufacturing and logistics verticals in Germany and France are leading this consolidation, demanding unified billing and cross-border SLA guarantees. The shift concentrates contract value among operators with multi-country infrastructure and subscription billing platform maturity.
MVNO Market Segmentation
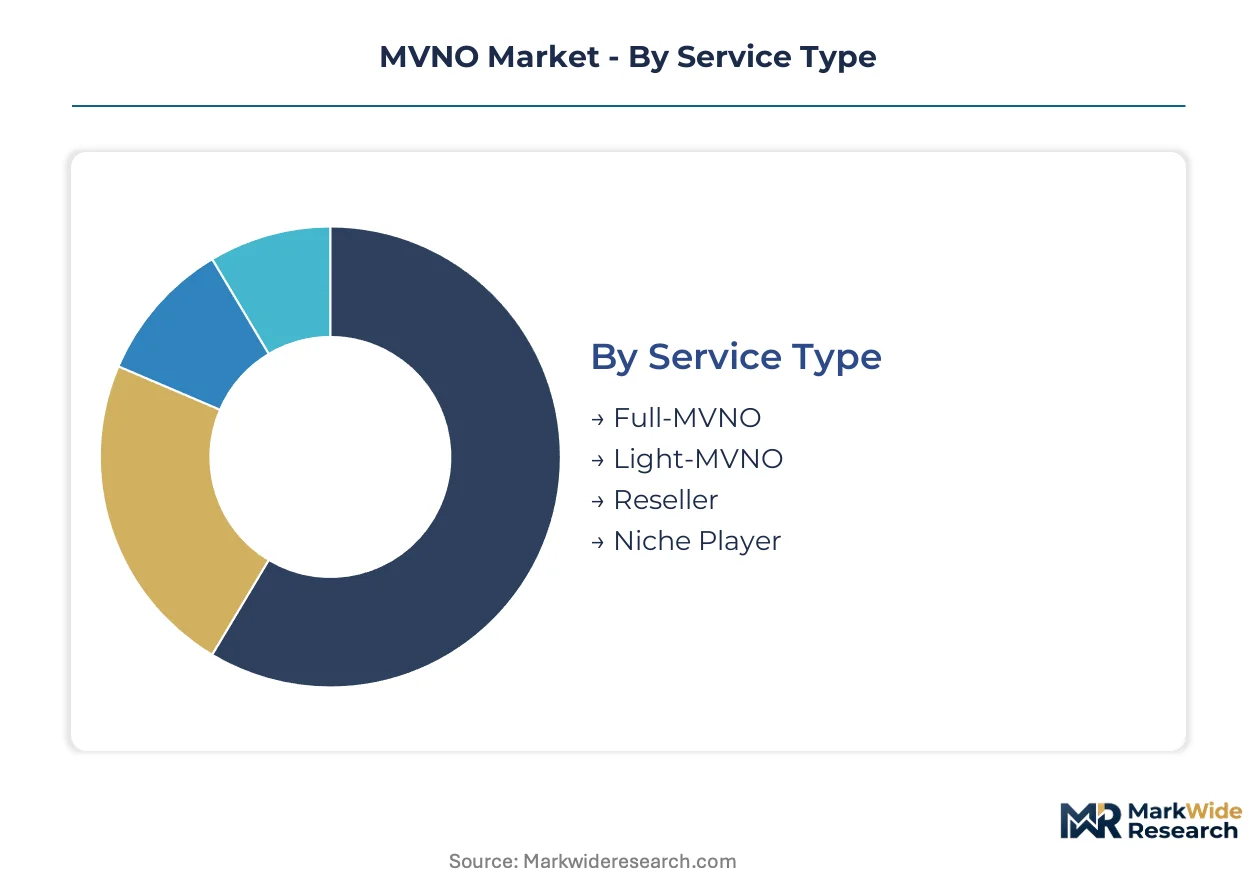
MVNO business models fragment across four structural dimensions that determine capital intensity, margin depth, and regulatory exposure. Service architecture choices lock in core network ownership levels, while customer mix and pricing mechanics shape lifetime value economics. Technology vintage constrains service quality differentiation and wholesale access terms.
Service Type:
Full-MVNO architectures demand numbering resource certification from national telecom regulators including FCC in the United States and TRAI in India. Light-MVNO and Reseller configurations operate under lighter host-operator dependency frameworks with reduced sovereign approval burdens.
- Full-MVNO:Operators deploy proprietary software-defined core networks and control own numbering resources. German industrial manufacturers favor this architecture for captive private networks in connected logistics deployments.
- Light-MVNO:Shares host operator core infrastructure while maintaining independent branding and customer management. Faster market entry in India despite TRAI foreign investment caps constraining capital structure flexibility.
- Reseller:Pure retail brand with zero network infrastructure ownership, relying entirely on host operator platforms for provisioning and billing.
- Niche Player:Targets vertical-specific segments such as IoT telemetry or senior citizen services with customized service wrappers.
Leading the category by volume: Light-MVNO. Growing fastest: Full-MVNO.
Customer Type:
Enterprise contracts concentrate procurement under single-vendor managed service agreements, displacing fragmented multi-carrier relationships. Residential segments drive subscriber scale while government verticals impose stringent security certification requirements.
- Residential:Price-sensitive consumers seeking cost transparency through bundled plans and unlimited offerings. Concentrated in United States and Germany where subscription billing software enables rapid service packaging.
- Business:Multi-line enterprise contracts generate superior lifetime value through unified billing and cross-border SLA guarantees. Manufacturing and logistics verticals in Germany and France lead consolidation trends.
- Government:Requires enhanced security certifications and sovereign data residency compliance, favoring operators with domestic infrastructure presence.
- Senior Citizens:Specialized service tiers with simplified interfaces and priority customer support, expanding in Japan and Western European markets with aging demographics.
Business segments command premium pricing power. Residential provides the scale foundation.
Pricing Model:
Prepaid structures dominate emerging market penetration strategies with lower credit risk exposure. Postpaid and bundled configurations anchor enterprise retention through contractual lock-in mechanisms.
- Prepaid:Subscriber funds account before service consumption, eliminating receivables risk. Preferred entry mechanism in India where TRAI floor tariffs constrain pricing flexibility.
- Postpaid:Monthly billing cycles with credit-based subscription commitments. Standard for Business customer segments requiring unified enterprise invoicing.
- Bundled Plans:Combines voice, data, and messaging into single price points. Attracts Residential subscribers seeking cost predictability in United States and European markets.
- Unlimited Offerings:Flat-rate data consumption without overage charges, compressing margin per gigabyte while driving subscriber acquisition velocity.
Postpaid anchors enterprise value. Prepaid scales emerging market penetration.
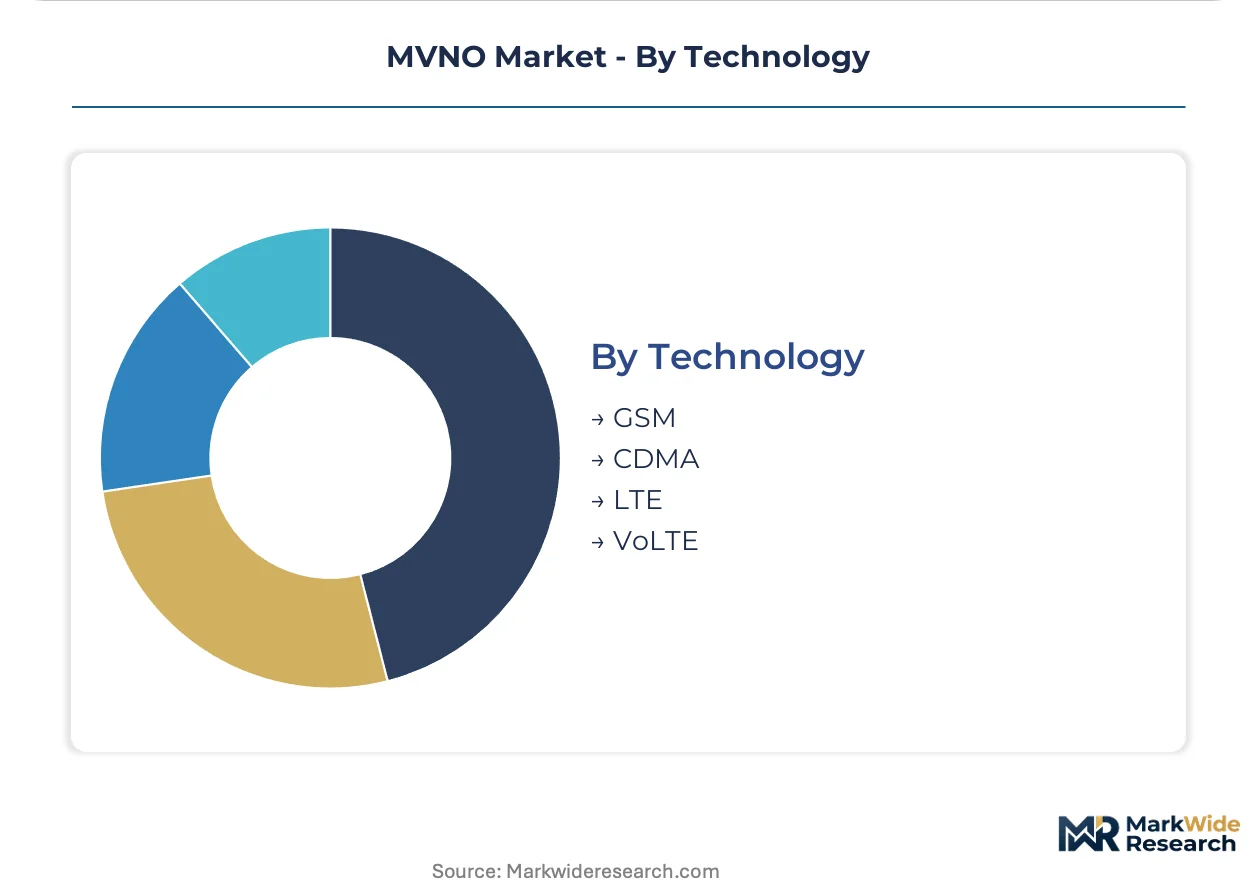
Technology:
Legacy GSM infrastructure constrains service velocity while VoLTE enables high-definition voice quality differentiation. LTE dominance defines current wholesale access negotiations with host operators.
- GSM:Second-generation circuit-switched architecture with limited data capability. Remains relevant for basic voice and SMS services in cost-sensitive segments.
- CDMA:Code-division multiple access technology with declining host operator support, concentrated in legacy United States regional networks.
- LTE:Fourth-generation all-IP standard enabling mobile broadband and network slicing for industrial IoT. Core technology for Enterprise IoT deployments among fleet operators.
- VoLTE:Voice over LTE delivers high-definition audio and faster call setup times. Critical quality differentiator for Business segments demanding reliable communications.
LTE carries current volume. VoLTE climbs fastest as host operators sunset legacy platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors European MVNO infrastructure development through its concentration of industrial manufacturers deploying private network solutions for connected logistics operations.
United States
Enterprise fleet operators and industrial IoT deployers drive wholesale capacity demand across major metropolitan corridors. The FCC's wireless spectrum auction framework introduces dynamic spectrum sharing mechanisms that alter network access economics for virtual operators. Regional MVNOs in the Midwest and Southeast evaluate millimeter-wave and CBRS bands alongside traditional macro network leases.
Germany
Industrial manufacturers in the Ruhr region and Bavaria deploy captive Full-MVNO infrastructure for factory-floor connectivity and supply chain telemetry. The EU Electronic Communications Code mandates national regulators to enforce open wholesale markets, reducing barriers to virtual operator entry. Stuttgart's automotive cluster generates specialized demand for low-latency network slicing in connected vehicle testing.
India
Prepaid subscriber bases in Maharashtra and Gujarat sustain volume growth despite pricing constraints. TRAI imposes floor tariffs and foreign investment caps that constrain MVNO pricing flexibility and capital structure design. Bangalore's technology corridor hosts Light-MVNO operations seeking faster market entry under reduced sovereign approval burdens.
United Kingdom
Business customer segments in London and the Southeast consolidate connectivity procurement under single-vendor managed service contracts. Ofcom regulates wholesale access terms and interconnection pricing alongside EU-derived open market mandates. Manchester's logistics hub demands unified billing and cross-border SLA guarantees from pan-European operators.
Japan
Aging demographics in Tokyo and Osaka expand specialized service tiers for senior citizens with simplified interfaces. METI oversees industrial digitalization programs that incorporate private MVNO networks for manufacturing telemetry. Nagoya's automotive manufacturing belt pilots network function virtualization for localized edge computing nodes.
MVNO Market Competitive Environment
Capital-heavy host network operators compete with asset-light virtual service providers for end-user relationships and enterprise contract value. The market structure concentrates around three to four national mobile network operators per geography that control wholesale capacity access. Strategic archetypes include infrastructure-anchored full operators, platform-specialized enablers, and vertical-focused niche providers. Dominant competitive moves encompass submarine cable backhaul integration and multi-country SIM provisioning infrastructure expansion.
Within the infrastructure-anchored tier, Tata Communications and BICS exemplify operators leveraging captive submarine fiber assets to compress transmission costs for international enterprise traffic. Transatel (NTT) occupies a position representing pan-European platform specialization through multi-country SIM provisioning capabilities. KORE Wireless anchors the vertical-focused archetype with network slicing optimization for industrial telemetry applications.
| Leading Market Players |
|---|
| Plintron |
| Transatel (NTT) |
| Pareteum (Circles) |
| Syniverse |
| Amdocs |
| Tata Communications |
| BICS |
| Telefonica Tech |
| KORE Wireless |
| Others |
Value Chain & Pricing Dynamics
Enterprise fleet operators in the United States and Germany concentrate procurement under multi-year managed service contracts, anchoring subscription-based pricing models that bundle connectivity, device management, and SLA guarantees into unified per-vehicle or per-site fees. This buyer archetype's volume concentration grants negotiating leverage over wholesale access rates, compressing margins for Light-MVNO and Reseller configurations while rewarding Full-MVNO operators with captive core infrastructure.
Pricing Analysis
Outcome-based pricing tied to network uptime and telemetry throughput anchors enterprise contracts, with German automotive manufacturers paying premiums for sub-50 millisecond latency guarantees in connected vehicle testing. Price differentiation separates Full-MVNO operators with sovereign numbering resources from Reseller tiers dependent on host-operator platforms. Cost compression in the residential prepaid segment intensifies because TRAI floor tariffs in India constrain pricing flexibility, while unlimited data offerings in the United States sacrifice margin per gigabyte for subscriber acquisition velocity. Residential segments exhibit highest price sensitivity; government verticals with security certification requirements show least.
Supply Chain Analysis
Domestic-content mandates in India's telecom sector and data-sovereignty requirements in Germany's Industrial Data Space initiative reshape sourcing toward local SIM provisioning and edge computing nodes. Wholesale wireless capacity concentrates in the United States, Germany, and India where three to four host mobile network operators control radio access infrastructure. Software-defined core functions, submarine cable backhaul, and multi-country SIM provisioning platforms constitute critical input dependencies. Single-source vulnerability runs through host-operator concentration for radio spectrum access. Distribution feeds from direct enterprise sales teams and specialized IoT system integrators serving manufacturing verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MVNO market functions as a vertical-integration race where operators pursue upstream control over software-defined core networks and numbering resources to escape host-operator pricing power. Full-MVNO architectures represent the decisive lever separating margin-sustainable operators from commodity resellers.
For Market Incumbents: Deepen submarine cable backhaul integration and multi-country SIM provisioning infrastructure to defend against platform-specialized enablers like Transatel. Secure long-term wholesale rate agreements before spectrum re-farming uncertainty hardens host-operator bargaining positions. Invest in network slicing certification for industrial telemetry to lock in German automotive and logistics verticals.
For New Entrants and Emerging Players: Senior citizen service tiers in Japan's aging metropolitan markets present an underserved buyer archetype with simplified interface requirements and premium support willingness. Private MVNO networks for German industrial manufacturers offer penetrable white-space with captive factory-floor deployments. Pursue Light-MVNO market entry under EU Electronic Communications Code open wholesale mandates, avoiding Full-MVNO capital intensity.
For Investors and Strategic Acquirers: The window for entry favors infrastructure-anchored operators with captive submarine fiber assets and pan-European platform reach over vertical-focused niche providers. Long-term viability hinges on software-defined core ownership enabling margin capture independent of host-operator rate negotiations. Monitor FCC spectrum auction outcomes and CBRS band utilization as inflection indicators for regional MVNO differentiation potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Core Deployment | Full-MVNO operators in Germany bypass host-operator dependency for factory-floor connectivity. |
| Multi-Country SIM Provisioning Expansion | Pan-European enterprise contracts require unified connectivity management across fragmented national markets. |
| Submarine Cable Backhaul Integration | Tata Communications compresses transmission costs for international enterprise traffic through captive fiber assets. |
| Network Slicing Certification | KORE Wireless secures defensible positioning in manufacturing telemetry through low-latency optimization. |
| Private MVNO Infrastructure Buildout | German industrial manufacturers deploy captive networks for connected logistics under EU data sovereignty rules. |
Study Parameters
Independent corroboration across host network operator wholesale pricing disclosures, national regulatory filings with the FCC and TRAI, and enterprise IoT deployment records underwrites the qualitative findings in this study. Primary interviews with MVNO platform engineers, enterprise fleet procurement managers, and telecom regulatory affairs specialists combined with secondary validation from spectrum auction results, submarine cable capacity databases, and EU Electronic Communications Code implementation reports. Bottom-up subscriber and revenue modeling triangulates against top-down wholesale capacity market estimates.
Historical reference periods spanning pre-pandemic wholesale rate structures through post-spectrum-auction pricing regimes anchor the forecast window. The analytical framework models segmentation across service architecture tiers, customer verticals, pricing mechanisms, and technology vintages. CAGRs derive from subscriber growth trajectories, wholesale rate negotiation patterns, and enterprise IoT deployment scaling curves. Network function virtualization adoption rates and private 5G network buildout timelines constitute industry-specific forecast inputs.
Revisions become necessary when host-operator consolidation alters wholesale market structure, spectrum re-farming schedules disrupt long-term rate agreements, or regulatory shifts in India or the European Union modify foreign investment and data sovereignty rules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Algeria Telecom Market
Telecommunications
Thailand ICT Market
Telecommunications
Embedded SIM (Esim) Market
Telecommunications
Global Roaming Tariff Market
Telecommunications
Cloud Radio Access Network (C-RAN) Market
Telecommunications
Diameter Signaling Control Market
Telecommunications
Singapore MVNO Market
Telecommunications
Telecom API Platform Market
Telecommunications
Germany Critical Communication Market
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
Telecommunication Service Market
Telecommunications
Mobile Fronthaul and Backhaul Market
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
Smart Feature Phone Market
Telecommunications
IoT Telecom Services Market