
 Oman Telecom Market | 2026-2036
Oman Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Telecom Market Outlook
Software-defined network features and subscription-based managed services is shifting the core revenue model away from pure connectivity toward value-added platforms. Omantel leverages its nationwide fiber backbone to anchor enterprise contracts across government and energy verticals. Ooredoo Oman competes through aggressive 5G rollout density in urban corridors. Vodafone Oman differentiates by targeting digital-native residential segments with flexible, app-managed plans.
Oman telecom encompasses the infrastructure, services, and regulatory frameworks enabling voice, data, and video transmission across fixed-line, mobile, and internet protocols, with fiber-optic backhaul achieving latency below 10 milliseconds on core routes and 5G New Radio operating in sub-6 GHz and millimeter-wave bands for enhanced mobile broadband and ultra-reliable low-latency communications. Mobile service revenue leads volume contribution given prepaid dominance and rising smartphone penetration, while fiber-to-the-premises deployment accelerates fastest in Muscat and Salalah as the Telecommunications Regulatory Authority pushes universal broadband targets. Enterprise and government customer segments concentrate margin pools due to multi-year managed service contracts and security requirements.
Oman's Telecommunications Regulatory Authority governs licensing, spectrum allocation, and interconnection pricing, while the National Cyber Security Agency enforces data localization and critical infrastructure protection standards that elevate compliance costs for international operators. TRA's 5G spectrum awards and tower-sharing mandates reshape capital intensity by reducing redundant infrastructure spend. Stakeholders must monitor how Oman's digital economy framework and smart city investments in Duqm and Muscat recalibrate procurement criteria for telecom vendors.
Market Dynamics
TRA's 5G spectrum awards and tower-sharing mandates are compressing capital intensity while enterprise cloud connectivity adoption among Omani logistics operators pulls fiber deployment toward industrial zones rather than residential corridors.
Growth Catalysts
- Industrial digitization mandates:Duqm Special Economic Zone authorities require low-latency fiber and private wireless for port automation, creating anchor demand that justifies infrastructure buildout ahead of residential saturation.
- TRA spectrum reforms:Oman Telecommunications Regulatory Authority's alignment with TRAI frameworks accelerates 5G New Radio deployment in sub-6 GHz bands, reducing time-to-market for enhanced mobile broadband services.
- Fiber-to-the-premises acceleration:Universal broadband targets push deployment fastest in Muscat and Salalah, where smartphone penetration and prepaid mobile dominance create upgrade pathways to fixed-wireless convergence.
Market Restraints
- Data localization compliance:National Cyber Security Agency enforcement elevates operational costs for international operators through mandatory critical infrastructure protection standards and sovereign data storage requirements.
- Prepaid revenue volatility:Mobile service revenue concentration in prepaid segments exposes cash flow to subscriber churn and price sensitivity, compressing average revenue per user predictability.
- Tower infrastructure redundancy:Prior uncoordinated buildout created overlapping macro sites, and mandated sharing now strands legacy assets while amortization schedules extend payback periods.
Strategic Opportunities
- Managed security services:Government and energy verticals seek multi-year contracts bundling connectivity with sovereign-grade cybersecurity, opening margin pools beyond pure transmission.
- Smart city integration:Muscat metropolitan investments recalibrate procurement criteria toward platform vendors capable of IoT aggregation, analytics, and vertical application delivery.
- Private wireless convergence:5G millimeter-wave bands paired with edge computing architectures enable ultra-reliable low-latency communications for industrial automation in remote extraction sites.
Industry Challenges
- Legacy system integration:Enterprise customers operate hybrid environments requiring seamless handoff between circuit-switched voice infrastructure and packet-based IP services, complicating service assurance.
- Specialized workforce scarcity:Network function virtualization and software-defined WAN deployment outpaces local supply of engineers certified in cloud-native orchestration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Telecom Market |
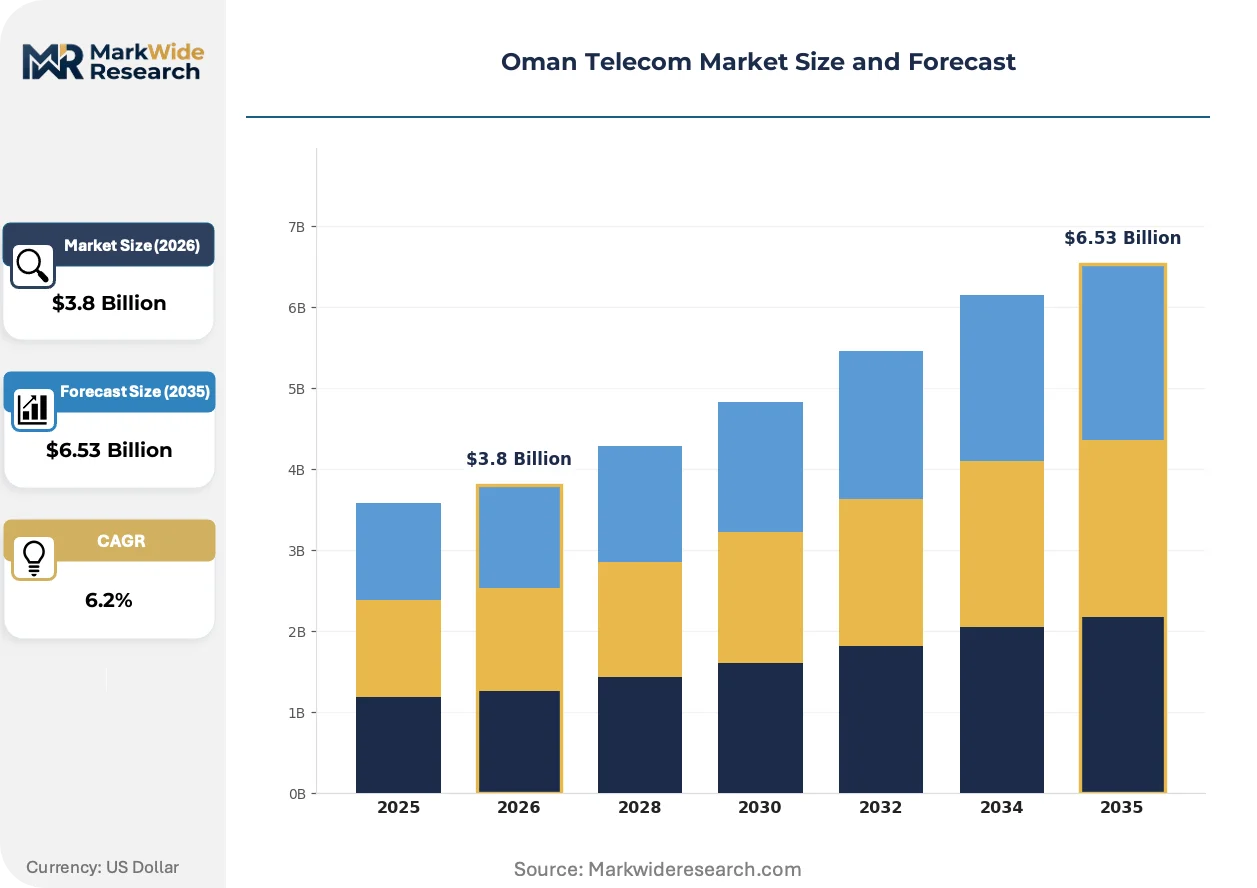
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Fixed-Line, Internet, Data Deployment Model: On-Premises, Cloud, Hybrid, Managed Customer Type: Residential, Small Business, Enterprise, Government Technology: 5G, LTE, Fiber Optic, Satellite |
| Companies Covered | Awasr, Equinix, Omantel, Al Izdihar Technology Solutions, Bayanat, Ooredoo Oman, Oman Data Park, Omantel Digital Solutions, Vodafone Oman, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Telecom Market Strategic Shifts
Software-defined architectures and subscription monetization are displacing hardware-centric business models, with fiber latency compression and open RAN interoperability emerging as technical battlegrounds for vendor selection.
Open RAN disaggregation is modularizing baseband processing and radio unit procurement, enabling Omani mobile operators to mix vendors across the stack. Large logistics enterprises in Duqm now pilot multi-vendor 5G private networks, breaking historical single-supplier lock-in. This architecture is modularizing capital deployment by separating hardware refresh cycles from software feature releases.
TRA's tower-sharing mandates and infrastructure unbundling regulations force operational separation between passive assets and active network equipment. The policy compresses redundant site construction while creating regulated lease-rate frameworks for independent tower companies. Rural coverage obligations attached to spectrum licenses now drive co-location density in secondary corridors rather than greenfield builds.
Enterprise buyers now unbundle connectivity from managed services, procuring raw bandwidth through wholesale arrangements while contracting systems integrators for security overlay and application management. Energy sector procurement teams in Muscat lead this bifurcation, splitting transport layer decisions from IT transformation budgets. The pattern concentrates pricing pressure on pure-play connectivity providers while elevating platform vendors with vertical expertise.
Oman Telecom Market Segmentation
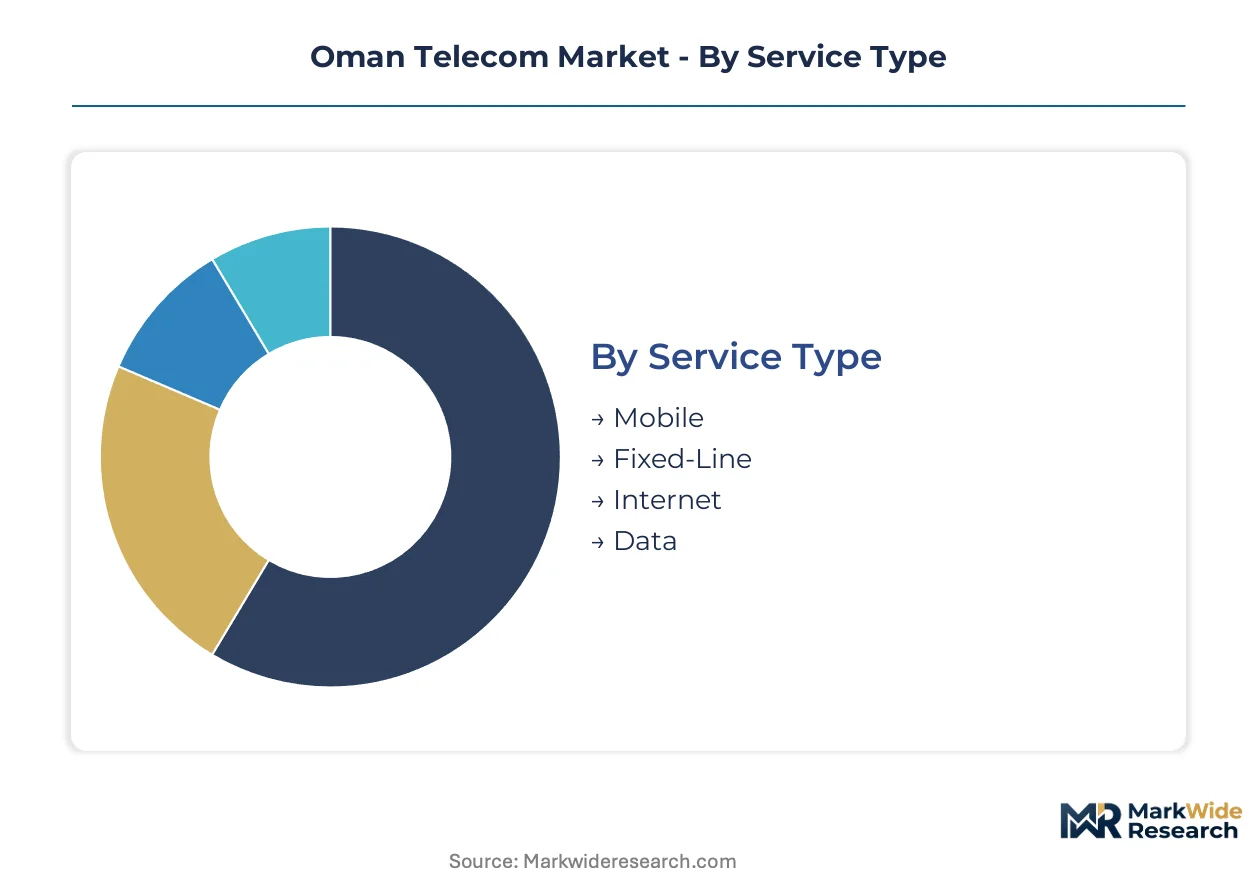
Telecom segmentation in Oman reveals how TRA spectrum mandates and enterprise procurement patterns reshape revenue concentration across service tiers. Each dimension carries distinct compliance burdens and infrastructure requirements that determine margin capture.
Service Type:
Certification intensity varies sharply across service categories, with government-facing data services requiring National Cyber Security Agency sovereign-grade accreditation while residential mobile operates under lighter TRA consumer protection frameworks.
- Mobile:Prepaid dominance drives volume through smartphone penetration corridors in Muscat and Salalah. TRA's 5G spectrum awards compress capital intensity while subscriber churn volatility compresses average revenue per user predictability in this segment.
- Fixed-Line:Circuit-switched voice infrastructure persists in enterprise hybrid environments, complicating seamless handoff to packet-based IP services. Government and energy verticals anchor demand through multi-year managed service contracts with security overlays.
- Internet:Fiber-to-the-premises deployment accelerates fastest in metropolitan zones under universal broadband targets.
- Data:Enterprise cloud connectivity adoption among Duqm logistics operators pulls fiber deployment toward industrial zones.
Leading the category by volume: Mobile. Growing fastest: Data.
Deployment Model:
Cost tier stratification separates capex-heavy on-premises installations from opex-based subscription models, with hybrid architectures capturing mid-market buyers seeking staged cloud migration.
- On-Premises:Legacy PBX and dedicated switching equipment persist in financial services and defense-adjacent installations requiring air-gapped sovereignty.
- Cloud:Software-defined WAN and network function virtualization enable rapid feature deployment without hardware refresh cycles.
- Hybrid:Enterprise buyers in Muscat unbundle connectivity from managed services, splitting transport layer decisions from IT transformation budgets.
- Managed:Multi-year contracts bundling connectivity with sovereign-grade cybersecurity open margin pools beyond pure transmission for government and energy verticals.
Expanding most quickly: Cloud. Dominating contract value: Managed.
Customer Type:
Application intensity maps directly to procurement sophistication, with government and enterprise segments demanding integrated platforms while residential buyers prioritize price-per-gigabyte simplicity.
- Residential:Digital-native segments drive demand for flexible, app-managed plans with prepaid dominance creating upgrade pathways to fixed-wireless convergence.
- Small Business:SaaS-dependent operations require symmetric broadband and basic managed security without dedicated network operations centers.
- Enterprise:Logistics and port operators in Duqm Special Economic Zone require low-latency fiber and private wireless for port automation, justifying infrastructure buildout ahead of residential saturation.
- Government:Smart city investments in Muscat recalibrate procurement criteria toward platform vendors capable of IoT aggregation and vertical application delivery.
Highest margin concentration: Government. Steepest expansion trajectory: Enterprise.
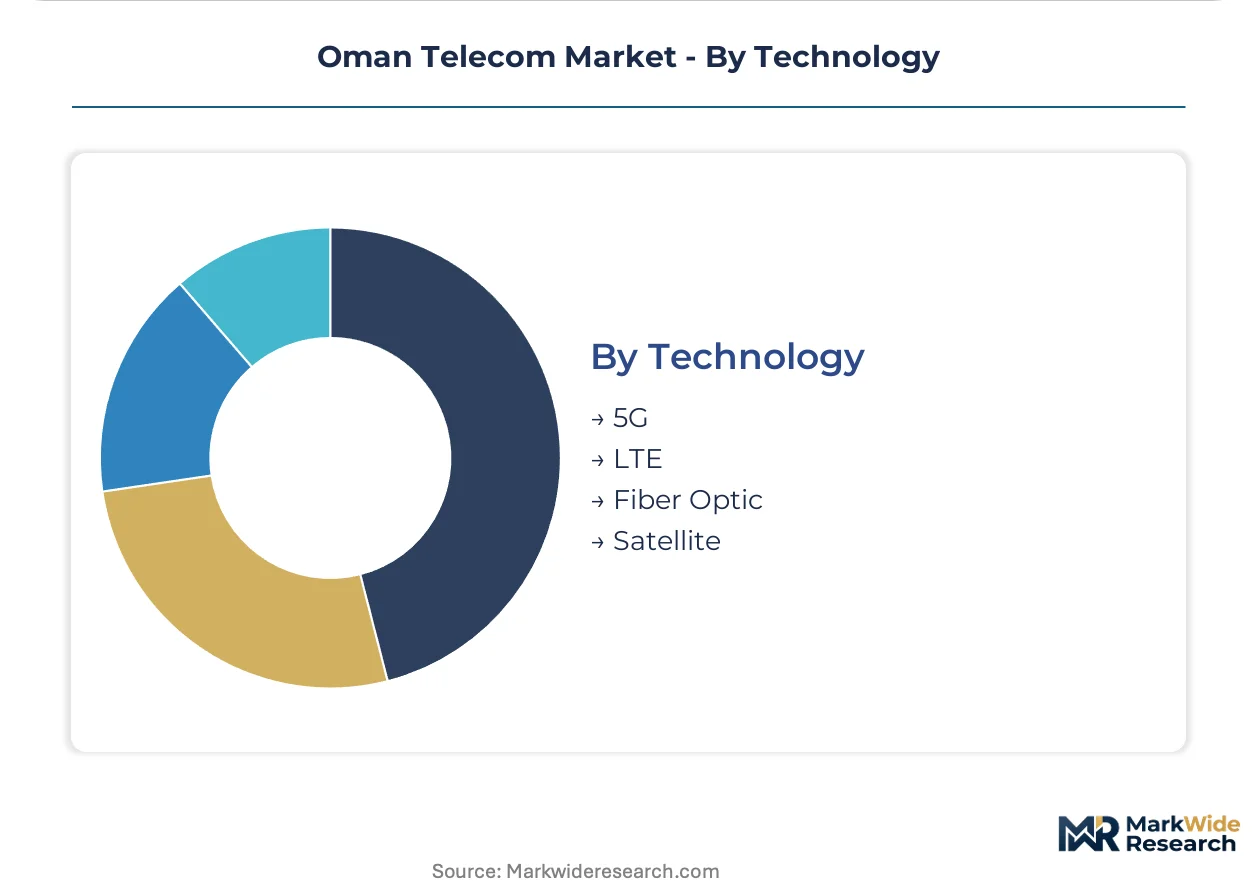
Technology:
Supply concentration clusters around fiber backbone assets and 5G radio access networks, with satellite filling coverage gaps in remote extraction sites.
- 5G:New Radio deployment in sub-6 GHz and millimeter-wave bands enables enhanced mobile broadband and ultra-reliable low-latency communications for industrial automation.
- LTE:Macro site redundancy from prior uncoordinated buildout now faces mandated tower sharing that strands legacy assets while extending amortization schedules.
- Fiber Optic:Latency compression below 10 milliseconds on core routes anchors Omantel's nationwide backbone for enterprise and government contracts.
- Satellite:Remote coverage obligations attached to spectrum licenses drive adoption in secondary corridors beyond fiber economics.
Capturing infrastructure investment: Fiber Optic. Gaining share fastest: 5G.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oman produces telecom infrastructure for domestic consumption while importing specialized network equipment and cloud software stacks. Muscat and the Duqm Special Economic Zone concentrate demand for low-latency fiber and private wireless deployments. The Telecommunications Regulatory Authority governs spectrum allocation and tower-sharing mandates that reshape capital deployment across the Sultanate.
Muscat Governorate
Smart city investments and government digitization programs drive fiber-to-the-premises deployment across the capital region. The Telecommunications Regulatory Authority enforces universal broadband targets that accelerate infrastructure buildout in metropolitan corridors. Omantel leverages its nationwide backbone to anchor enterprise contracts with ministries and energy headquarters clustered in Ruwi and Al Khuwair.
Al Batinah North and South
Industrial zones along the coastal corridor generate demand for private wireless and managed security services from logistics operators. Tower-sharing mandates from the Telecommunications Regulatory Authority reduce redundant macro site construction in densely populated coastal settlements. Sohar Port and surrounding free zones require ultra-reliable low-latency communications for port automation and container tracking systems.
Dhofar Governorate
Salalah's transhipment hub status pulls submarine cable landing stations and data center investments toward the southern coast. The National Cyber Security Agency enforces data localization requirements that elevate compliance costs for international operators serving regional maritime trade. Salalah Free Zone enterprises procure multi-year managed service contracts bundling connectivity with sovereign-grade cybersecurity overlays.
Al Wusta Governorate
Duqm Special Economic Zone authorities mandate low-latency fiber and private 5G networks for port automation and industrial digitization projects. The Telecommunications Regulatory Authority's 5G spectrum awards in sub-6 GHz bands enable enhanced mobile broadband services for remote extraction sites. Duqm's special economic zone status creates anchor demand that justifies infrastructure investment ahead of residential market saturation.
Ad Dakhiliyah Governorate
Nizwa and interior cities exhibit prepaid mobile dominance with rising smartphone penetration creating upgrade pathways to fixed-wireless convergence. Rural coverage obligations attached to spectrum licenses drive co-location density through mandated tower sharing rather than greenfield builds. Traditional commerce and emerging tourism clusters generate mid-market demand for symmetric broadband and basic managed security without dedicated network operations centers.
Oman Telecom Market Competitive Environment
Capital-heavy infrastructure owners compete with asset-light service integrators for margin pools across Oman's telecom value chain. The market structure concentrates around three licensed mobile operators with nationwide spectrum holdings, supplemented by specialized data center and managed services providers. Strategic archetypes separate fiber backbone owners, tower infrastructure specialists, and cloud-native digital service platforms. Dominant competitive moves include operational separation of passive assets from active equipment and vertical integration into cybersecurity and IoT application layers.
Within the infrastructure-owner tier, Omantel and Ooredoo Oman anchor the competitive landscape as established licensees with nationwide fiber and mobile radio access networks. Vodafone Oman occupies a position as the challenger mobile operator targeting digital-native residential segments with flexible, app-managed service plans. Among specialized service providers, Equinix represents the global data center interconnection archetype, while Oman Data Park exemplifies sovereign-cloud positioning for government and enterprise workloads requiring National Cyber Security Agency compliance.
| Leading Market Players |
|---|
| Awasr |
| Equinix |
| Omantel |
| Al Izdihar Technology Solutions |
| Bayanat |
| Ooredoo Oman |
| Oman Data Park |
| Omantel Digital Solutions |
| Vodafone Oman |
| Others |
Value Chain & Pricing Dynamics
Captive fiber backbone ownership anchors Omantel's supply position and pricing power across government and energy verticals in Oman. This vertical integration into passive infrastructure insulates the incumbent from tower-sharing lease-rate compression while enabling premium positioning on latency-guaranteed enterprise contracts.
Pricing Analysis
Price erosion across residential prepaid segments traces to Vodafone Oman's app-managed plan aggression and smartphone penetration saturation in Muscat. Three-tier pricing structure across premium, standard, and economy levels stratifies by latency guarantee and cybersecurity certification grade. Government and energy buyers show least price sensitivity due to sovereign-grade compliance mandates. Enterprise cloud connectivity contracts face cost-down pressure as buyers unbundle transport from managed services.
Supply Chain Analysis
Domestic-content mandates from Oman's Telecommunications Regulatory Authority reshape sourcing toward local tower companies and regional system integrators. Equipment supply concentrates in China, South Korea, and Finland for radio access networks and core switching infrastructure. Fiber optic cable draws from Chinese and Indian manufacturers, while cloud software stacks feed from US hyperscalers. Single-source vulnerability sits with millimeter-wave radio unit suppliers facing export control restrictions. Distribution runs through TRA-licensed operators with operational separation between passive assets and active equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman telecom functions as a consolidation play where TRA tower-sharing mandates and spectrum auction costs force sub-scale infrastructure owners toward asset divestment or operational partnerships.
For Market Incumbents: Acquire independent tower portfolios to consolidate passive asset density ahead of mandated lease-rate frameworks. Secure fiber-to-the-premises footprint in Salalah before submarine cable landing station investments mature. Defend against Vodafone Oman's digital-native segmentation by embedding network function virtualization capabilities that accelerate feature velocity without hardware refresh cycles. For New Entrants and Emerging Players: Launch via wholesale bandwidth arrangements targeting enterprise buyers who have unbundled connectivity from managed services. White-space concentrates in Duqm Special Economic Zone private wireless deployments where industrial digitization mandates outpace incumbent response capacity. Penetrate through sovereign-grade cybersecurity overlays for National Cyber Security Agency compliance requirements that strain international operator cost structures. For Investors and Strategic Acquirers: Exit pathways concentrate in infrastructure carve-outs to independent tower companies and fiber backbone sales to pension funds seeking yield-bearing utility assets. Long-term viability favors operators with captive fiber routes and government contract anchoring. Watch TRA spectrum renewal timelines as inflection indicators for capital intensity resets.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Deployment | Modularizes vendor procurement for Duqm logistics operators piloting multi-vendor 5G private networks. |
| Tower Asset Carve-Out | Creates regulated lease-rate frameworks compliant with TRA infrastructure unbundling mandates. |
| Managed Security Service Launch | Captures margin pools beyond pure transmission through National Cyber Security Agency accreditation. |
| Edge Computing Partnership | Enables ultra-reliable low-latency communications for remote extraction site automation. |
| Smart City Platform Integration | Recalibrates Muscat metropolitan procurement toward IoT aggregation and vertical application delivery. |
Study Parameters
Regulatory filings from Oman's Telecommunications Regulatory Authority, National Cyber Security Agency compliance documentation, and operator spectrum auction records formed the secondary backbone for market sizing. Primary interviews with network planning executives at mobile operators, enterprise procurement leads in Duqm logistics, and infrastructure asset managers informed demand elasticity assumptions. SEC filings of listed telecom equipment vendors and hyperscaler capex disclosures supplied capital intensity benchmarks. Bottom-up and top-down triangulation validated subscriber forecasts against infrastructure deployment trajectories.
Bottom-up modeling anchored on fiber route kilometers and 5G base station counts across governorates, while top-down cross-checks applied regional telecom penetration benchmarks. Segmentation dimensions spanned service type, deployment model, customer archetype, and technology generation across the projection horizon. CAGRs derived from infrastructure investment cycles, spectrum license tenures, and enterprise contract renewal patterns. Duqm Special Economic Zone industrial digitization timelines and Muscat smart city procurement schedules served as demand-pull validation inputs.
TRA spectrum policy reversals, National Cyber Security Agency data localization enforcement escalations, and global radio equipment export restrictions are the dominant revision risks to infrastructure deployment assumptions. Forecasts reflect documented stakeholder guidance and disclosed regulatory frameworks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Europe Managed SD-WAN Services Market
Telecommunications
DECT System Market
Telecommunications
5G Equipment Market
Telecommunications
Singapore MVNO Market
Telecommunications
Voip Phone Market
Telecommunications
Digital Mobile Radio (DMR) Market
Telecommunications
GPON Equipment Market
Telecommunications
Rich Communication Services (RCS) Messaging Market
Telecommunications
Ghana Telecom Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
Argentina Telecom Market
Telecommunications
Oman Telecommunication Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Machine to Machine (M2M) Services Market