
 Call Control (PBX-IP PBX) Market | 2026-2036
Call Control (PBX-IP PBX) Market Size, Share, and Industry Trends Forecast 2026-2036
Call Control (PBX-IP PBX) Market Analysis
Software-defined voice architectures are rebalancing capital expenditure models across enterprise communications. Vonage leverages its API-first platform to anchor developer-centric embedding strategies. RingCentral sustains multi-tenant cloud density through proprietary microservices infrastructure. Dialpad competes on native AI voice analytics integrated at the transport layer rather than bolted atop legacy stacks.
Call Control (PBX-IP PBX) systems encompass private branch exchange equipment and session management software that routes, switches, and terminates voice calls across enterprise networks using packet-switched protocols with sub-150ms latency thresholds for real-time conversational quality. These systems serve commercial organizations by consolidating internal and external voice traffic while enabling unified communications overlays. Cloud-Based deployment configurations now capture the fastest expansion trajectory as SMEs abandon depreciating on-premise chassis for consumption-priced alternatives. SIP Trunking technology segments hold mature margin pools where carrier interconnection fees and wholesale minute arbitrage still defend profitability against commoditizing WebRTC endpoints.
FCC Part 68 regulations govern terminal equipment connection to public networks, while HIPAA security rules constrain healthcare deployments and GDPR cross-border data transfer protocols shape European cloud voice architectures. These compliance frameworks elevate barriers for uncertified entrants and compel incumbent vendors to maintain dedicated regulatory engineering functions. Stakeholders must weigh sovereign data residency requirements against the operational elasticity of hyperscale cloud delivery models as jurisdictional fragmentation intensifies.
Market Dynamics
The migration from circuit-switched TDM infrastructure to packet-based SIP architectures is compressing enterprise hardware refresh cycles while forcing incumbent vendors to recalibrate recurring revenue models around cloud-native delivery.
Growth Catalysts
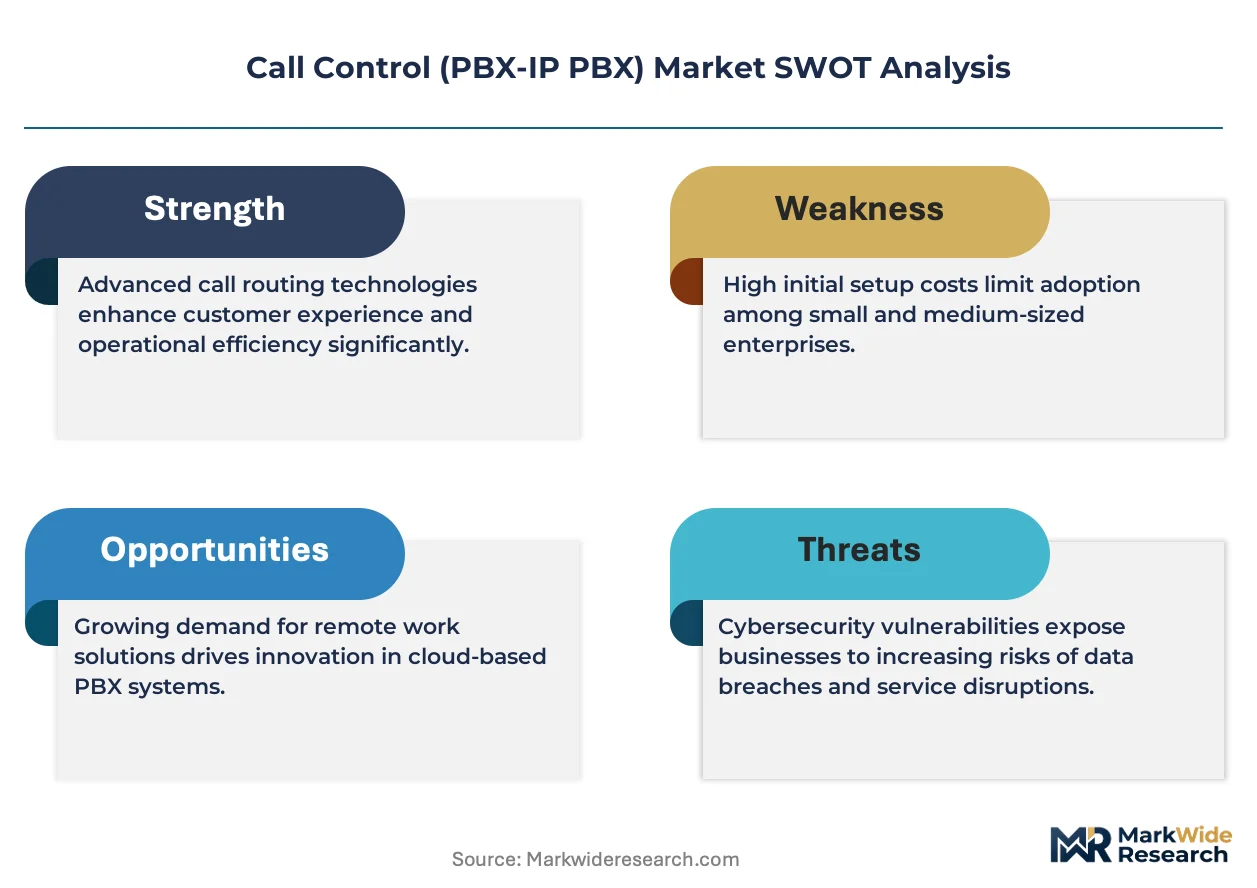
- FCC Part 68 modernization:Federal mandates for network interoperability accelerate enterprise VoIP adoption across United States healthcare and financial services sectors.
- HIPAA-compliant cloud voice:Healthcare providers deploy encrypted session border controllers to satisfy federal security rules while enabling remote clinical workflows.
- Hybrid workforce permanence:Distributed enterprise demand for unified communications overlays sustains replacement demand for legacy PBX chassis.
Market Restraints
- Carrier interconnection concentration:Wholesale SIP trunking margins compress as tier-one carriers consolidate peering arrangements in North America.
- Legacy TDM sunk costs:Enterprises defer migration where existing circuit-switched investments carry unamortized depreciation.
- GDPR data residency friction:European cloud deployments face architectural constraints from cross-border transfer protocols that limit hyperscale elasticity.
Strategic Opportunities
- API-first embedding:Developer-centric voice platforms enable white-label integration into vertical SaaS applications.
- AI-native transport layer:Real-time speech analytics at the session level creates differentiation beyond bolt-on transcription services.
- India SME cloud migration:TRAI-licensed service providers capture underpenetrated mid-market demand for consumption-priced alternatives to depreciating on-premise systems.
Industry Challenges
- Session border controller certification timelines:Hardware vendors face extended validation cycles for common criteria and FIPS 140-2 compliance.
- Legacy PRI integration complexity:Enterprises struggle to bridge ISDN-based fax, alarm, and elevator systems during staged SIP migrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Call Control (PBX-IP PBX) Market |
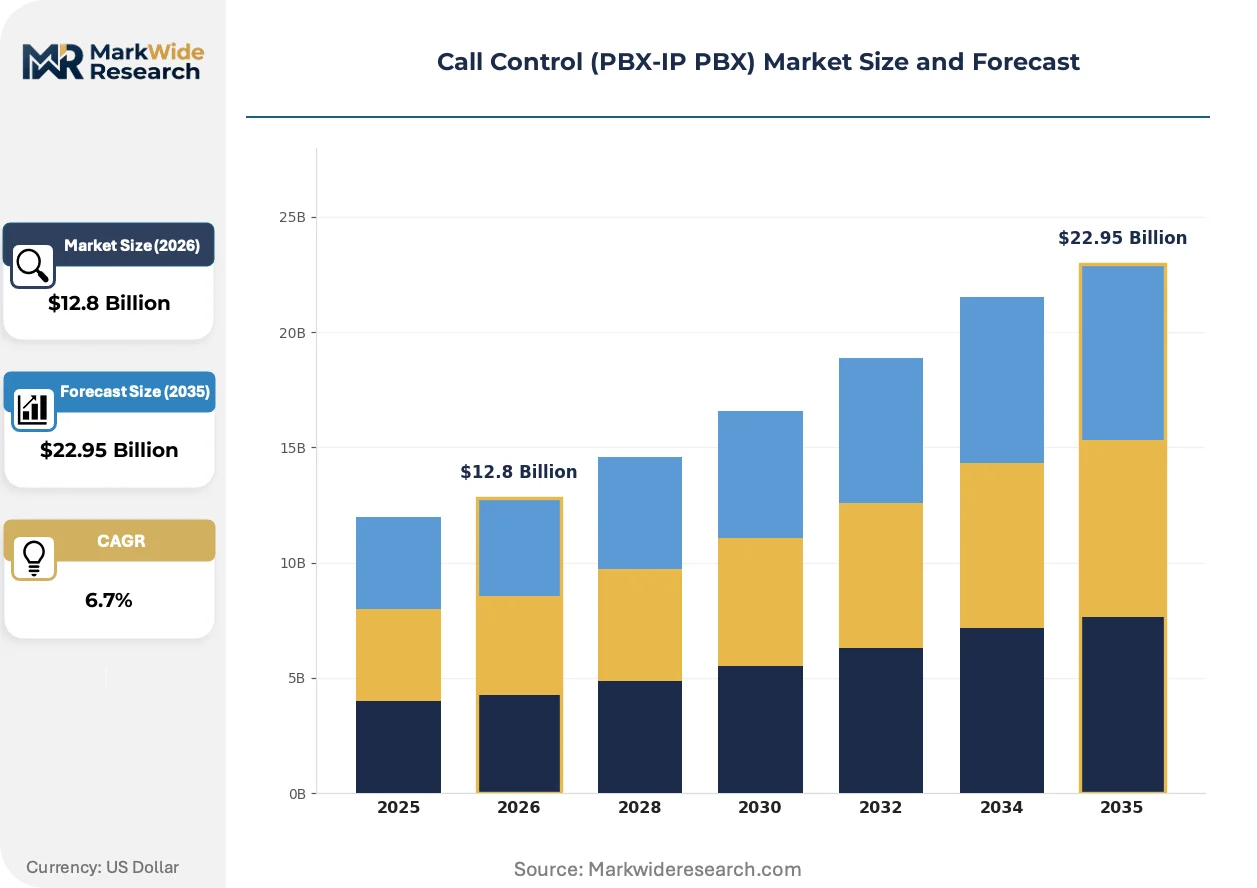
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Feature: Call Routing, Voicemail, Call Recording, Conference Calling Technology: VoIP, SIP Trunking, PBX System, WebRTC |
| Companies Covered | AVOXI, Vonage, RingCentral, Dialpad, GoTo Connect, Nextiva, Zoom Phone, VirtualPBX, 8x8, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Call Control (PBX-IP PBX) Market Emerging Trajectories
Voice infrastructure is shedding its hardware-defined boundaries as software abstraction layers rewrite procurement patterns and competitive moats across enterprise communications.
WebRTC is converging with traditional SIP signaling to collapse the distinction between browser-based endpoints and registered desk phones. Mid-market enterprises adopt this hybrid architecture fastest, eliminating client-side installation friction. The technology is converging with carrier-grade session management to commoditize proprietary endpoint margins.
GDPR cross-border data transfer protocols are forcing European cloud voice providers to architect region-locked instances with sovereign data residency. This fragmentation elevates operational costs for multi-tenant platforms while creating compliance arbitrage for regional specialists. Healthcare and public sector deployments in Germany and France face the strictest localization requirements.
Enterprise buyers now unbundle voice infrastructure from managed services contracts, treating session capacity as a commodity input rather than a strategic partnership. Systems integrators lose annuity attach rates as direct cloud provisioning displaces traditional resale channels. This pattern is most visible in United States financial services, where procurement teams negotiate API-based consumption models separate from professional services.
Call Control (PBX-IP PBX) Market Segmentation
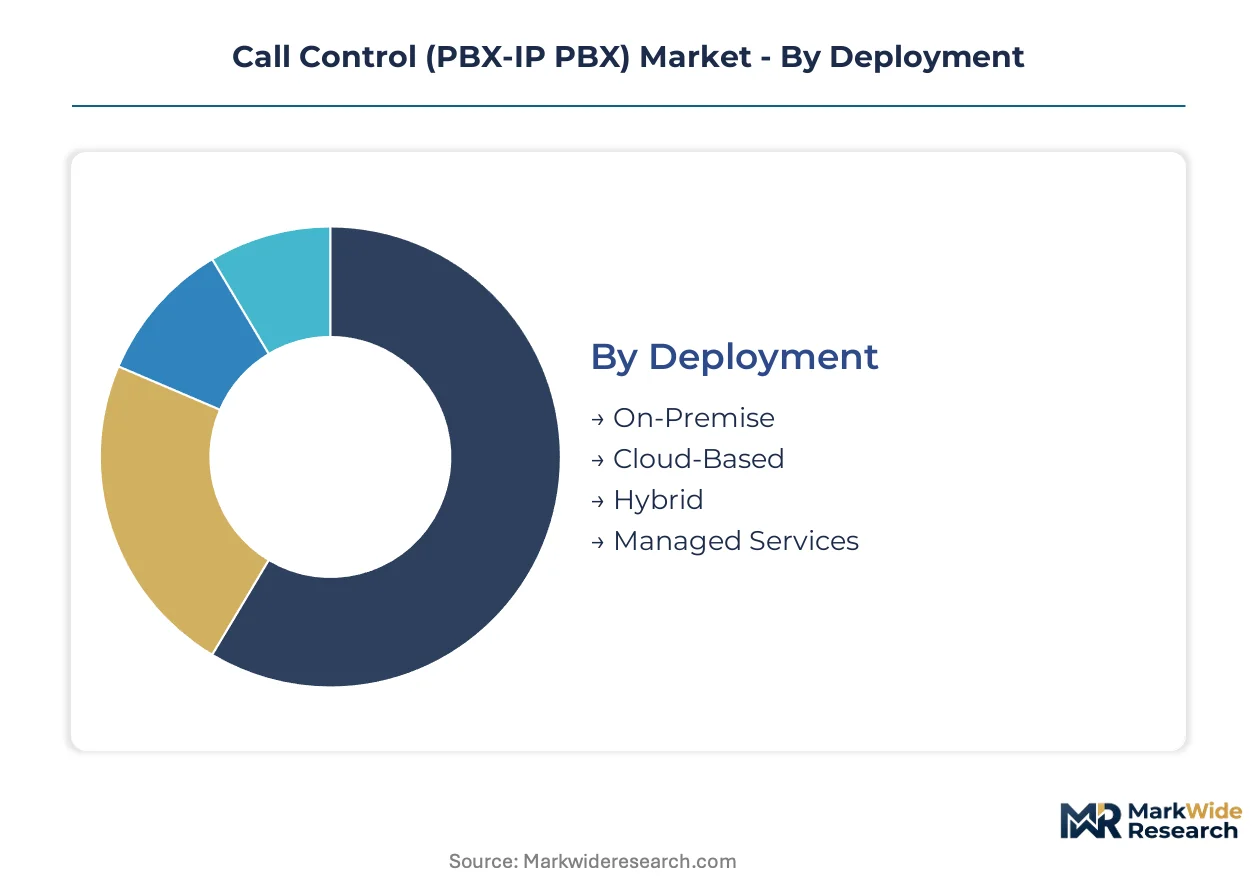
Call Control (PBX-IP PBX) procurement patterns diverge sharply across deployment models, organizational scale, and underlying transport protocols. Segment boundaries determine integration complexity, recurring revenue potential, and regulatory exposure for vendors competing across enterprise communications.
Deployment:
Standalone chassis installations persist where data sovereignty or legacy interoperability demands physical infrastructure control, while embedded cloud-native stacks dominate greenfield deployments seeking API extensibility.
- On-Premise:Hardware chassis with dedicated session border controllers and PRI/T1 interface cards serve financial services and defense contractors requiring air-gapped voice infrastructure. Demand concentrates in United States federal contracting corridors where FIPS 140-2 certification gates cloud alternatives.
- Cloud-Based:Multi-tenant microservices architectures deliver consumption-priced session capacity with automatic failover across availability zones. Healthcare providers in United States metropolitan clusters deploy these most aggressively to satisfy HIPAA encryption mandates without capital depreciation.
- Hybrid:Split-traffic models route internal extensions through on-premise switches while external PSTN termination leverages cloud SIP trunks. Manufacturing facilities with mixed legacy equipment adopt this bridging approach during staged migration timelines.
- Managed Services:Third-party operations of customer-owned infrastructure, including patch management, capacity planning, and carrier interconnection negotiation. State and local government entities in budget-constrained jurisdictions favor this opex treatment.
Volume placements concentrate in Cloud-Based configurations; the faster expansion belongs to Hybrid architectures bridging legacy sunk costs with cloud elasticity.
End User:
Procurement sophistication varies across organizational maturity, with compliance exposure and integration complexity scaling with entity size and regulatory oversight intensity.
- SMEs:Cloud-native consumption models with per-seat pricing and self-service administration portals. United States professional services firms with under 500 employees represent the densest adoption cluster.
- Large Enterprises:Custom session routing policies, global number provisioning, and ERP/CRM integration requirements. Multi-national manufacturers demand geographic redundancy across three or more carrier interconnects.
- Government Agencies:FedRAMP-authorized or equivalent sovereign-certified platforms with mandatory encryption key escrow. United States civilian agencies face congressional mandates accelerating legacy TDM replacement.
- Educational Institutions:Semester-variable capacity scaling and emergency notification system integration. State university systems in United States public higher education negotiate enterprise-wide master service agreements.
Revenue concentration sits with Large Enterprises; steepest expansion trajectory belongs to SMEs abandoning depreciating on-premise hardware.
Feature:
Capability unbundling allows procurement teams to match license tiers against actual workflow requirements rather than accepting monolithic platform bundles.
- Call Routing:Intelligent distribution algorithms including time-of-day rules, skills-based queues, and geographic load balancing. Contact center operations in United States healthcare and retail deploy these most extensively.
- Voicemail:Unified messaging with speech-to-text transcription and mobile app access. Field service organizations prioritize this capability for asynchronous coordination.
- Call Recording:Compliance-grade capture with immutable storage, legal hold tagging, and PCI-DSS redaction. Financial services broker-dealers face SEC and FINRA retention mandates.
- Conference Calling:Multi-party bridging with host controls, dial-out escalation, and webinar-scale broadcasting. Distributed professional services firms consume this as a primary collaboration modality.
Attachment rates are highest for Call Routing; gaining share fastest is Call Recording driven by regulatory enforcement intensity.
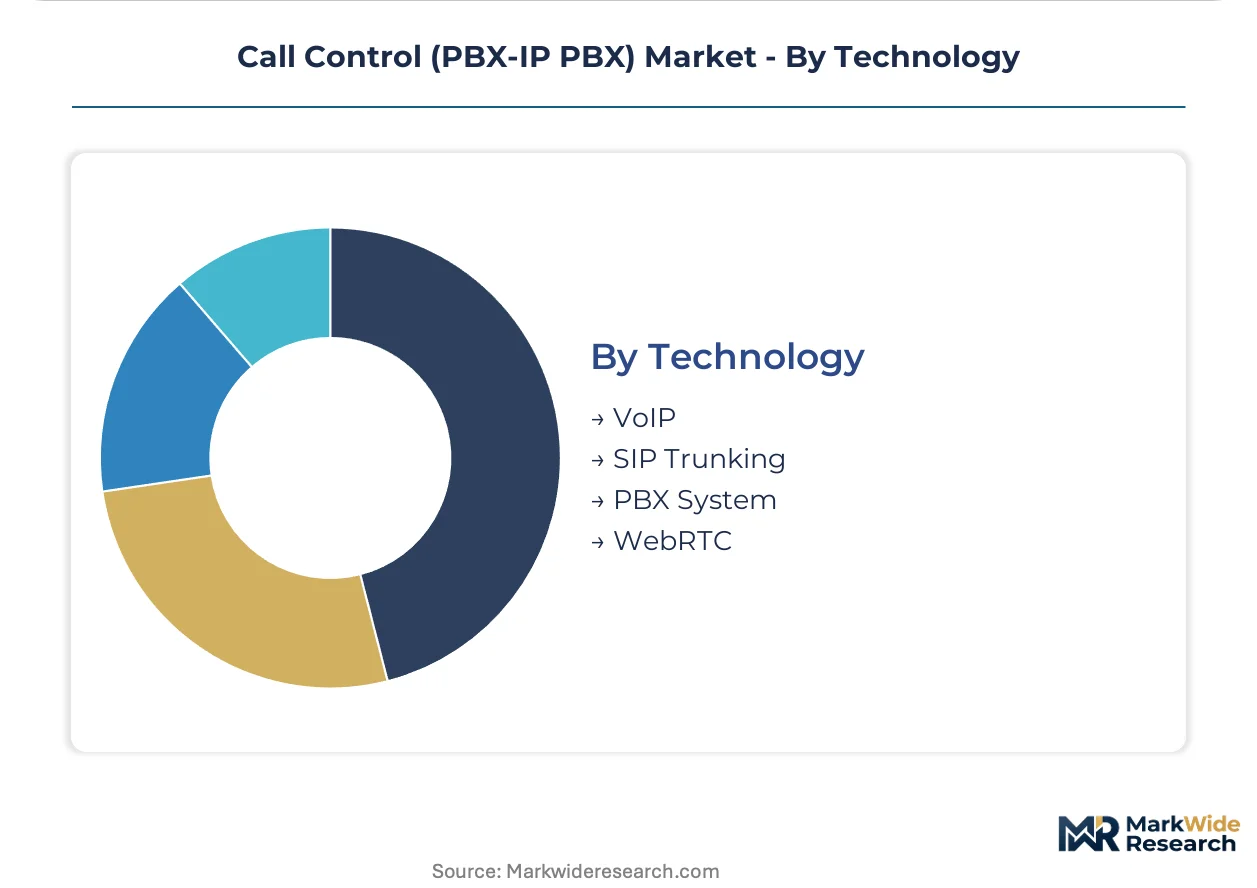
Technology:
Transport layer selection determines latency budgets, interoperability scope, and endpoint commoditization exposure for enterprise communications architects.
- VoIP:Packet-switched voice over dedicated MPLS or SD-WAN transport with guaranteed QoS markings. Legacy enterprise networks with established carrier relationships maintain this protocol preference.
- SIP Trunking:Session initiation protocol carrier interconnection replacing ISDN PRI circuits with IP-based wholesale minute termination. United States tier-one carrier consolidation is compressing margins in this mature segment.
- PBX System:Traditional private branch exchange architectures including both legacy TDM and IP-enabled chassis with gateway functionality. Industrial facilities with elevator, alarm, and fax integration requirements defer full migration.
- WebRTC:Browser-native real-time communication eliminating client software installation through encrypted peer-to-peer channels. Mid-market software companies embed this for in-app voice without telephony infrastructure.
Deployment scale favors SIP Trunking; climbing the fastest is WebRTC as browser-based endpoints displace proprietary desk phones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise VoIP procurement concentrates in the United States, where federal modernization mandates and hybrid workforce policies accelerate SIP trunking adoption. Healthcare providers and financial services firms drive replacement demand for legacy TDM infrastructure across metropolitan clusters.
United States
FCC Part 68 regulations govern terminal equipment interconnection while HIPAA security rules constrain healthcare cloud deployments. Federal civilian agencies face congressional mandates accelerating legacy circuit-switched replacement timelines. Densest adoption clusters appear in United States healthcare metropolitan areas where encrypted session border controllers satisfy compliance requirements.
Germany
GDPR cross-border data transfer protocols force region-locked cloud voice architectures with sovereign data residency requirements. The country's national telecommunications regulator enforces strict localization standards for public sector deployments. Industrial manufacturers in Baden-Württemberg adopt hybrid configurations bridging legacy ISDN systems with cloud SIP trunks.
United Kingdom
BT's 2025 ISDN switch-off deadline compels enterprise migration to packet-based alternatives. The country's national communications regulator oversees wholesale market competition in SIP trunking interconnection. London financial services firms deploy compliance-grade call recording with immutable storage to satisfy FCA retention mandates.
India
TRAI-licensed service providers capture underpenetrated mid-market demand for consumption-priced cloud alternatives. The national telecommunications regulator governs interconnection frameworks for IP-based voice services. Software companies in Bangalore embed WebRTC capabilities for in-app voice without traditional telephony infrastructure investment.
Japan
METI industrial digitization programs subsidize SME migration from legacy PBX systems to cloud-native platforms. The country's national telecommunications standards body certifies equipment for network interoperability. Manufacturing facilities in the Nagoya industrial corridor deploy hybrid architectures during staged migration from circuit-switched infrastructure.
Call Control (PBX-IP PBX) Market Vendor Landscape
API-first platform strategies dominate the current landscape as vendors compete for developer-centric embedding opportunities. The vendor base fragments across three distinct tiers: hyperscale cloud providers with multi-tenant microservices infrastructure, mid-market specialists competing on vertical SaaS integration, and legacy hardware vendors defending installed base maintenance revenue. Two archetypes anchor competitive positioning: API-first embedders seeking white-label distribution through software platforms, and AI-native transport layer specialists differentiating on real-time analytics. Geographic expansion into underpenetrated SME markets and strategic partnerships with carrier interconnect providers represent the dominant competitive moves.
Among United States-based cloud communications providers, Vonage, RingCentral, and Dialpad exemplify contrasting platform strategies. Vonage occupies a position representing API-first embedders anchoring developer-centric distribution models. RingCentral exemplifies the multi-tenant infrastructure archetype sustaining cloud density through proprietary microservices. Dialpad represents AI-native transport layer positioning where voice analytics integrate at the session level rather than as bolt-on services. These three anchors illustrate how competitive differentiation increasingly concentrates on architectural decisions around embedding depth, infrastructure ownership, and analytics integration rather than traditional feature parity.
| Leading Market Players |
|---|
| AVOXI |
| Vonage |
| RingCentral |
| Dialpad |
| GoTo Connect |
| Nextiva |
| Zoom Phone |
| VirtualPBX |
| 8x8 |
| Others |
Supply Flow & Price Mechanics
United States healthcare procurement teams concentrate purchasing power through enterprise-wide master service agreements, compressing margins for cloud voice providers while elevating consumption-based SaaS tiers as the dominant pricing architecture across the Call Control (PBX-IP PBX) market.
Pricing Analysis
Volume placements cluster in per-seat subscription tiers while margin pools concentrate in API-embedded licensing and compliance-grade call recording add-ons. Price differentiation hinges on HIPAA certification level and geographic redundancy architecture. Cost compression in mid-market SIP trunking intensifies as tier-one carriers consolidate peering arrangements. Government agencies exhibit lowest price sensitivity due to FedRAMP authorization requirements, while SMEs abandoned on-premise depreciation show highest elasticity to per-seat rates.
Supply Chain Analysis
Workforce availability constraints in Taiwan and South Korea semiconductor fabrication centers ripple through session border controller chipset supply, while Mexico and Vietnam final assembly facilities absorb overflow from China-based hardware chassis production. Component sourcing draws from specialized DSP foundries, carrier-grade Ethernet switch silicon, and FIPS 140-2 certified cryptographic modules. Single-source vulnerability concentrates in Taiwan-based semiconductor packaging for enterprise voice processors. Distribution runs through carrier-direct provisioning, systems integrator resale, and hyperscale cloud marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Call Control (PBX-IP PBX) market functions as a vertical-integration race where proprietary microservices infrastructure and captive session border controller supply chains determine competitive durability against API-first disrupters.
For Market Incumbents: Acquire session border controller hardware certification assets to defend maintenance revenue against cloud-native substitution. Consolidate carrier interconnection relationships in United States metropolitan clusters where wholesale SIP trunking margins still defend profitability. Prioritize FIPS 140-2 and FedRAMP authorization investments to maintain air-gapped infrastructure positioning against hyperscale entrants. For New Entrants and Emerging Players: Launch via white-label API embedding into vertical SaaS platforms serving United States healthcare and professional services workflows. Target Indian SME mid-market demand where TRAI-licensed service providers capture underpenetrated consumption-priced migration from depreciating on-premise chassis. Lead with WebRTC-native transport to eliminate client-side installation friction against legacy PBX incumbents. For Investors and Strategic Acquirers: The window for entry favors AI-native transport layer specialists with real-time speech analytics integrated below application level rather than bolt-on transcription services. Long-term viability rests on architectural control over session-level data pipelines enabling vertical SaaS distribution partnerships. Monitor FCC Part 68 modernization timelines and HIPAA enforcement intensity as inflection signals for compliance-grade infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables white-label embedding into healthcare EHR systems and legal practice management software. |
| Carrier Interconnection Consolidation | Secures wholesale SIP trunking margin pools against tier-one peering arrangement compression. |
| FedRAMP Authorization Investment | Unlocks United States federal civilian agency procurement mandates accelerating TDM replacement. |
| AI-Native Transport Layer Development | Differentiates real-time analytics at session level from bolt-on transcription commodity services. |
| Regional Cloud Sovereignty Expansion | Addresses GDPR data residency constraints forcing German and French public sector localization. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with enterprise IT procurement officers, cloud communications platform engineers, healthcare compliance directors, carrier interconnection managers, and session border controller hardware vendors. FCC Part 68 equipment authorization databases, HIPAA security rule guidance documents, and TRAI licensing records provided regulatory validation. Bottom-up deployment model estimates triangulated against top-down carrier revenue disclosures.
Data-stream reconciliation across cloud provisioning metrics, on-premise chassis shipment volumes, and SIP trunking minute termination reports informed the analytical framework. Segmentation dimensions modeled include deployment architecture, organizational scale, end-use vertical, transport protocol preference, and regional regulatory cluster. CAGRs derived from slope-log regression of annualized revenue trajectories, with sensitivity testing against hybrid workforce permanence assumptions and federal modernization mandate timelines.
The model assumes a particular technology adoption path; alternative pathways for WebRTC browser-native endpoints displacing registered desk phones would alter the outlook. Forecasts reflect documented assumptions around carrier consolidation intensity and compliance certification validation cycles. Material deviation in FCC enforcement posture or GDPR cross-border transfer protocol rulings warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
SIP Trunking Services Market
Telecommunications
Medical 5G Market
Telecommunications
GSM Mobile Phone Market
Telecommunications
Portable Base Station (PBS) Market
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Luxembourg Telecom Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Global Telecom Order Management Market
Telecommunications
Europe Managed SD-WAN Services Market
Telecommunications
LTE and 5G NR-Based CBRS Networks Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Russia ICT Market
Telecommunications
Embedded SIM (Esim) Market
Telecommunications
Satcom Terminal Market
Telecommunications
Software Defined Radio Market
Telecommunications
Canada Hosted PBX Market