
 Private LTE in Mining Industry Market | 2026-2036
Private LTE in Mining Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Private LTE in Mining Industry Market Analytics
3GPP Release 13 MCPTT certification is bifurcating the vendor landscape between qualified mission-critical suppliers and generalist telecom equipment makers. Nokia Corporation leverages its Bell Labs heritage to sustain dominance in underground spectrum optimization. Ericsson anchors its position through deep partnerships with Australian and Canadian mine operators. Huawei Technologies Co., Ltd. competes aggressively on integrated baseband-to-core offerings despite geopolitical headwinds in North American markets.
Private LTE in mining denotes a localized cellular network operating in licensed, shared, or unlicensed spectrum bands, typically between 400 MHz and 3.5 GHz, to deliver sub-50 millisecond latency for connected heavy machinery and wearable safety devices. Its primary industrial purpose replaces unreliable Wi-Fi and leaky feeder systems in geologically complex extraction environments. The deployment dimension shows managed services capturing disproportionate margin pools as miners outsource radio planning, core network maintenance, and spectrum licensing to specialized integrators. Application-level demand clusters around safety management systems, where gas detection alerts and lone-worker emergency signaling command premium pricing over conventional voice and data packages.
FCC Part 90 rules governing industrial/business pool frequencies in the United States shape hardware certification requirements and spectrum auction access for private network builders. Australia's ACMA mining-specific spectrum allocations and Canada's ISED 3.5 GHz priority licensing frameworks create divergent compliance pathways that vendors must navigate simultaneously. Stakeholders should monitor evolving 5G NR-RedCap device ecosystems to determine whether simplified radio complexity opens private network deployment to mid-tier quarry operators previously priced out of full LTE infrastructure.
Market Dynamics
3GPP Release 16 industrial IoT specifications are compressing equipment refresh cycles as miners demand URLLC-grade latency for autonomous haulage coordination. This standardization push is fragmenting the installed base between legacy TETRA deployments and next-generation private cellular infrastructure.
Growth Catalysts
- ACMA mining spectrum allocations:Australia's dedicated 400 MHz and 2.6 GHz bands for resource extraction eliminate interference from public networks. Rio Tinto and BHP have leveraged these licenses to deploy underground tracking systems.
- Autonomous vehicle coordination:Private LTE enables sub-50 millisecond handoffs between base stations for driverless truck fleets. This capability is supplanting Wi-Fi and leaky feeder systems in Pilbara iron ore operations.
- Worker safety mandates:Gas detection alerts and lone-worker emergency signaling now require guaranteed quality-of-service levels. Mission-critical push-to-talk over cellular commands premium infrastructure investment.
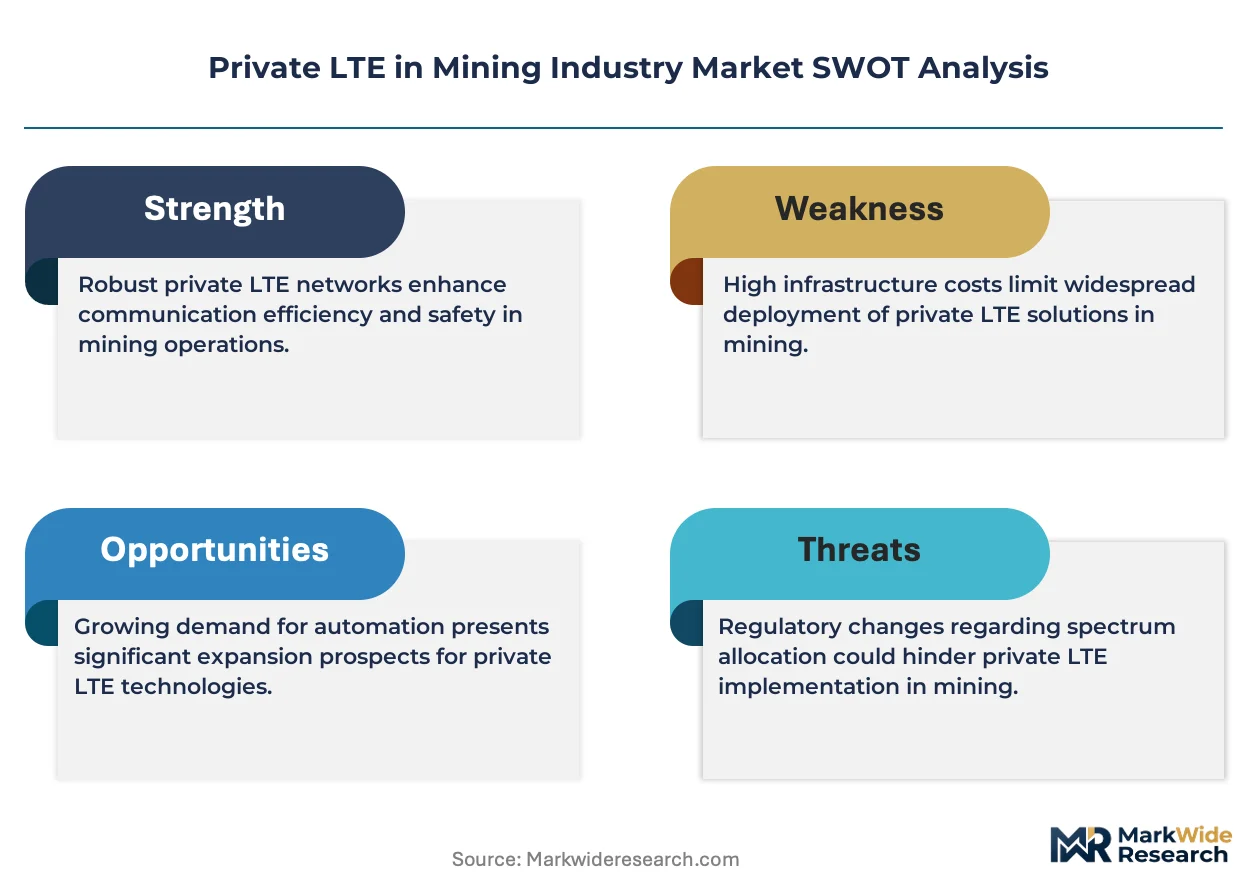
Market Restraints
- Radio frequency component concentration:Gallium nitride power amplifiers and high-performance filters source predominantly from East Asian foundries. Supply disruptions propagate directly to base station lead times.
- 3GPP certification complexity:MCPTT and MCVideo testing timelines extend 18-24 months for underground-hardened devices. This friction delays vendor entry and concentrates qualified supplier pools.
- Leaky feeder substitution economics:Existing coaxial cable infrastructure in mature underground mines carries sunk capital. Partial LTE overlay deployments compete against full rip-and-replace business cases.
Strategic Opportunities
- 5G NR-RedCap device ecosystems:Reduced capability radios will enable private network deployment for mid-tier quarry operators previously priced out of full LTE infrastructure. This opens volume markets below tier-one mining.
- Managed services margin pools:Radio planning, core network maintenance, and spectrum licensing outsourcing concentrates recurring revenue. Specialist integrators capture disproportionate value versus hardware vendors.
- ISED 3.5 GHz priority licensing:Canada's framework for industrial priority access licenses creates first-mover advantages in oil sands and potash extraction regions. Early deployers lock in interference-protected spectrum.
Industry Challenges
- Underground RF propagation modeling:Geologically complex ore bodies create multipath and shadowing effects that defy standard prediction tools. Site-specific measurement campaigns extend deployment timelines.
- Integration with legacy dispatch systems:TETRA and P25 voice infrastructure persists in surface operations. Hybrid network management platforms require custom development for seamless interoperability.
- Skilled radio planning workforce scarcity:Underground spectrum optimization demands expertise in both cellular engineering and mining ventilation topology. Training pipelines lag deployment demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private LTE in Mining Industry Market |
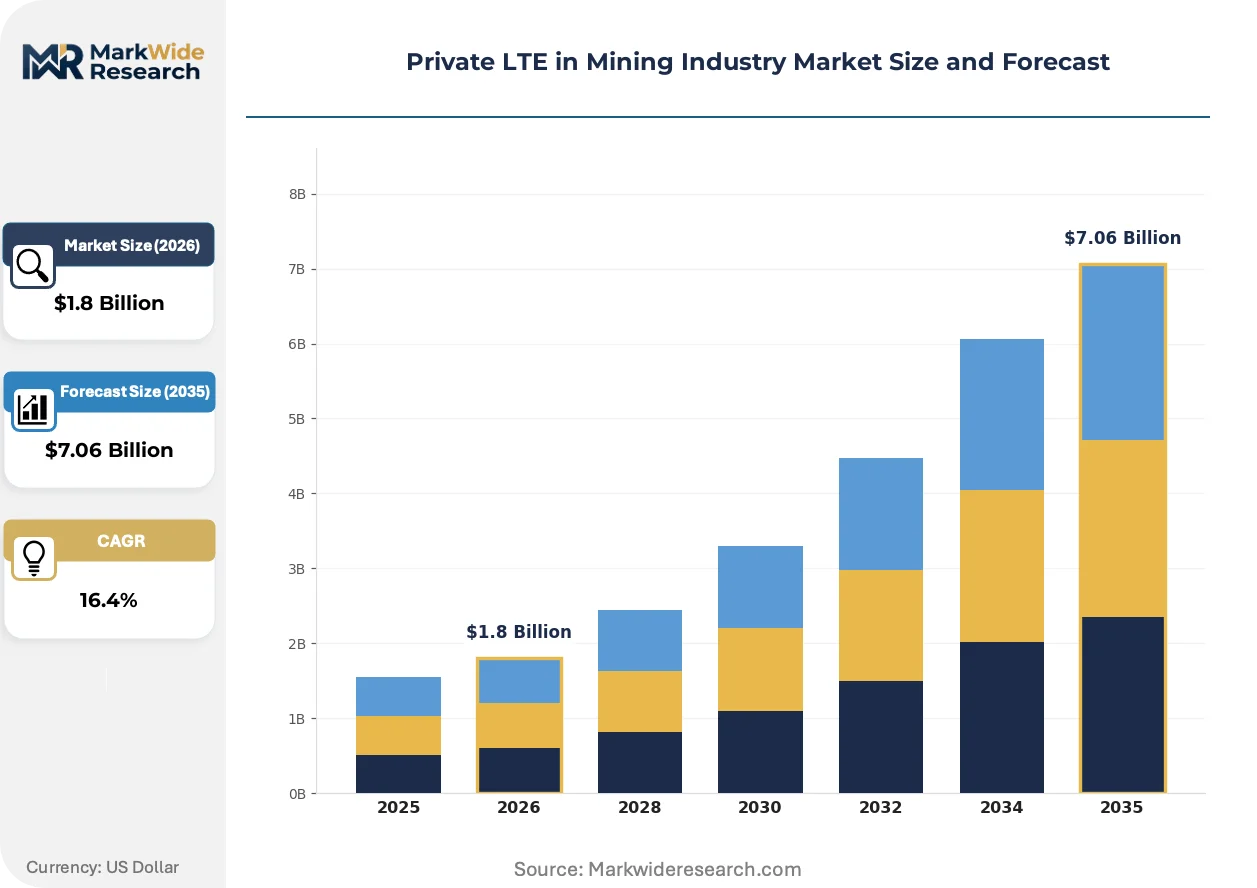
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LTE, 5G, VoLTE, Small Cells End User: Quarries, Underground Mines, Surface Mines, Processing Plants Deployment: Hybrid, On-Premises, Managed Services, Private Network Application: Asset Tracking, Real-Time Monitoring, Safety Management, Communication Systems |
| Companies Covered | ZTE Corporation, Cisco Systems, Inc., Nokia Corporation, Ericsson, Samsung Electronics Co. Ltd., Huawei Technologies Co., Ltd., Verizon, Qualcomm, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private LTE in Mining Industry Market Evolving Landscape
Private LTE architectures are fragmenting into modular, cloud-native core deployments that separate control plane functions from radio access layers. This disaggregation is enabling new vendor entry and compressing traditional integrated equipment margins.
Time-Sensitive Networking over LTE is supplanting proprietary industrial Ethernet backbones in underground automation networks. Hard-rock mining operators in Canada and Sweden are piloting TSN-capable base stations for conveyor synchronization and crusher coordination. The technology is compressing integration timelines with existing SCADA infrastructure while eliminating redundant cabling layers.
REACH substance restrictions and the EU Green Deal's embodied carbon reporting requirements are reshaping base station hardware specifications. European mining equipment procurement now mandates conflict-free mineral certification and full lifecycle carbon disclosure. Vendors with modular, upgradeable radio units capture preference over sealed, disposable designs in Nordic and German brownfield projects.
Equipment procurement is consolidating through long-term managed service contracts that bundle spectrum licensing, radio maintenance, and core network operations. Australian iron ore operators pioneered this shift, and the model is now displacing capital-heavy ownership structures in Chilean copper and South African platinum operations. Procurement committees now weight total cost of ownership over upfront equipment expenditure in vendor selection criteria.
Private LTE in Mining Industry Market Segmentation
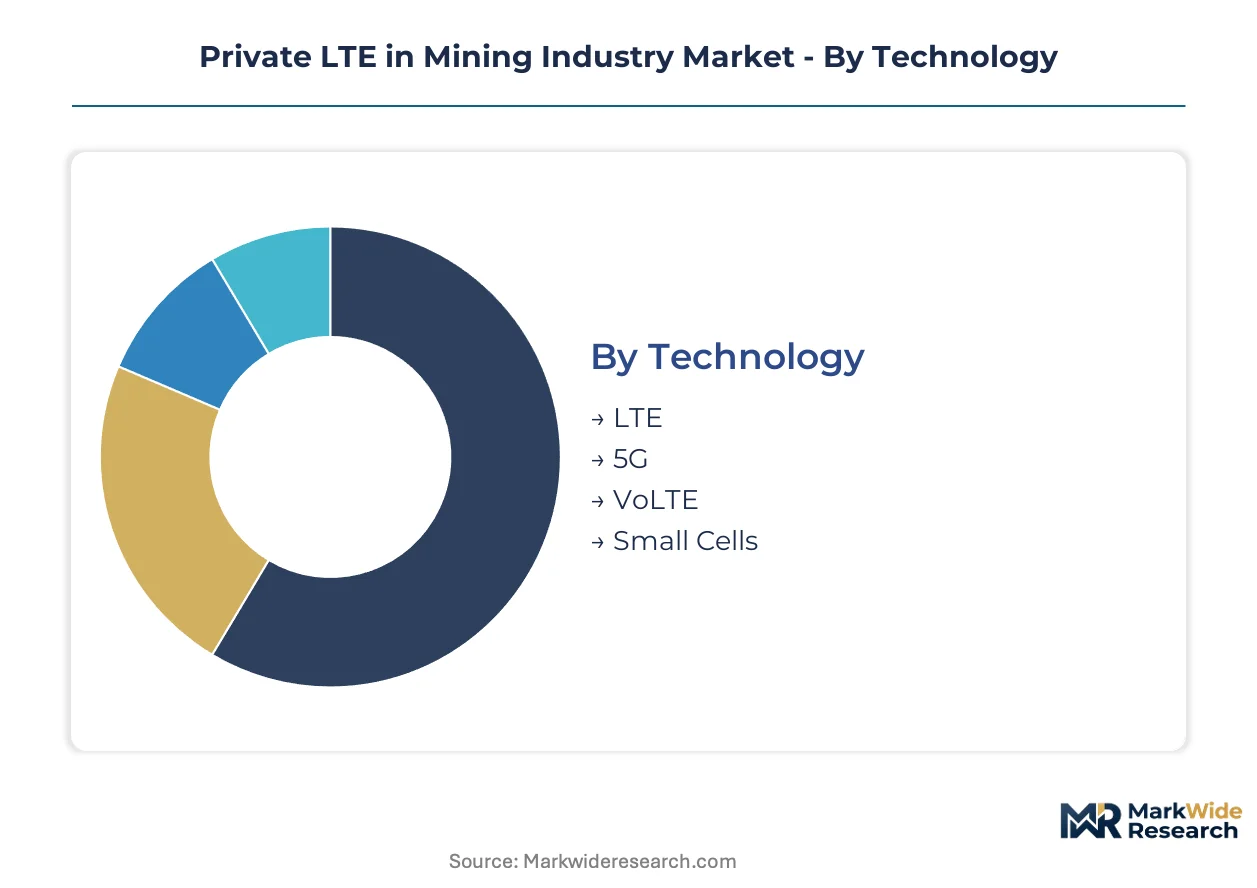
Private LTE deployments in mining fragment across four structural dimensions that determine equipment specifications, spectrum licensing pathways, and vendor selection criteria. Technology choices govern interoperability with legacy TETRA infrastructure. Deployment models reshape capital allocation between miners and specialized integrators.
Technology:
LTE-based systems face substitution pressure from 5G NR-RedCap rollouts targeting mid-tier quarry operators, while VoLTE and small cell architectures compete for underground coverage supremacy.
- LTE:Mature 3GPP Release 13/14 equipment dominates current installations with proven underground propagation characteristics. Pilbara iron ore operators in Australia and Saskatchewan potash miners in Canada standardize on this stack for autonomous haulage coordination.
- 5G:Release 16 URLLC specifications enable sub-10 millisecond latency for real-time crusher control and conveyor synchronization. Swedish hard-rock operators pilot 5G standalone cores for Time-Sensitive Networking integration.
- VoLTE:Voice-over-LTE modules replace legacy circuit-switched infrastructure in surface operations. South African platinum belt miners deploy VoLTE for mission-critical push-to-talk interoperability with existing dispatch consoles.
- Small Cells:Compact base stations address coverage gaps in geologically complex ore bodies. Chilean copper underground operations deploy small cell overlays to supplement macro network dead zones.
LTE retains volume leadership; 5G holds the steepest expansion curve.
End User:
Underground operations command premium infrastructure investment due to RF propagation challenges, while surface mines balance coverage economics against fleet autonomy requirements.
- Quarries:Mid-scale limestone and aggregate extraction sites drive demand for simplified, reduced-capability radio deployments. North American quarry operators prioritize cost-optimized small cell architectures over full macro network builds.
- Underground Mines:Deep metal and coal extraction environments require hardened equipment with explosion-proof certifications. Australian gold and base metal underground operations lead private LTE adoption for worker tracking and gas monitoring systems.
- Surface Mines:Open-pit copper, iron ore, and oil sands operations leverage favorable propagation conditions for wide-area coverage. Canadian oil sands operators in Alberta deploy hybrid networks combining private LTE with satellite backhaul.
- Processing Plants:Crushing, grinding, and refining facilities demand industrial-grade reliability for SCADA integration. Brazilian iron ore pelletizing plants adopt private LTE to replace aging industrial Ethernet backbones.
Surface mines dominate current installed base; underground operations are expanding most quickly.
Deployment:
Managed services models concentrate recurring revenue with specialist integrators, while on-premises deployments preserve operational control for technically sophisticated miners.
- Hybrid:Split architectures combine private radio access networks with public core roaming for remote site connectivity. Nordic mining operators pilot hybrid models to bridge isolated extraction sites with centralized operations centers.
- On-Premises:Fully captive infrastructure places spectrum licensing, core network operations, and radio maintenance under direct miner control. Large diversified miners in Australia and Canada favor this model for data sovereignty compliance.
- Managed Services:Outsourced arrangements bundle radio planning, equipment procurement, and lifecycle maintenance. Chilean copper and South African platinum operations increasingly adopt managed services to shift capital expenditure to operational budgets.
- Private Network:Standalone cellular deployments with dedicated spectrum allocations eliminate public network dependency. Pilbara iron ore operators leverage ACMA mining-specific spectrum licenses for interference-protected operations.
Managed services capture margin concentration; private network deployments gain share fastest.
Application:
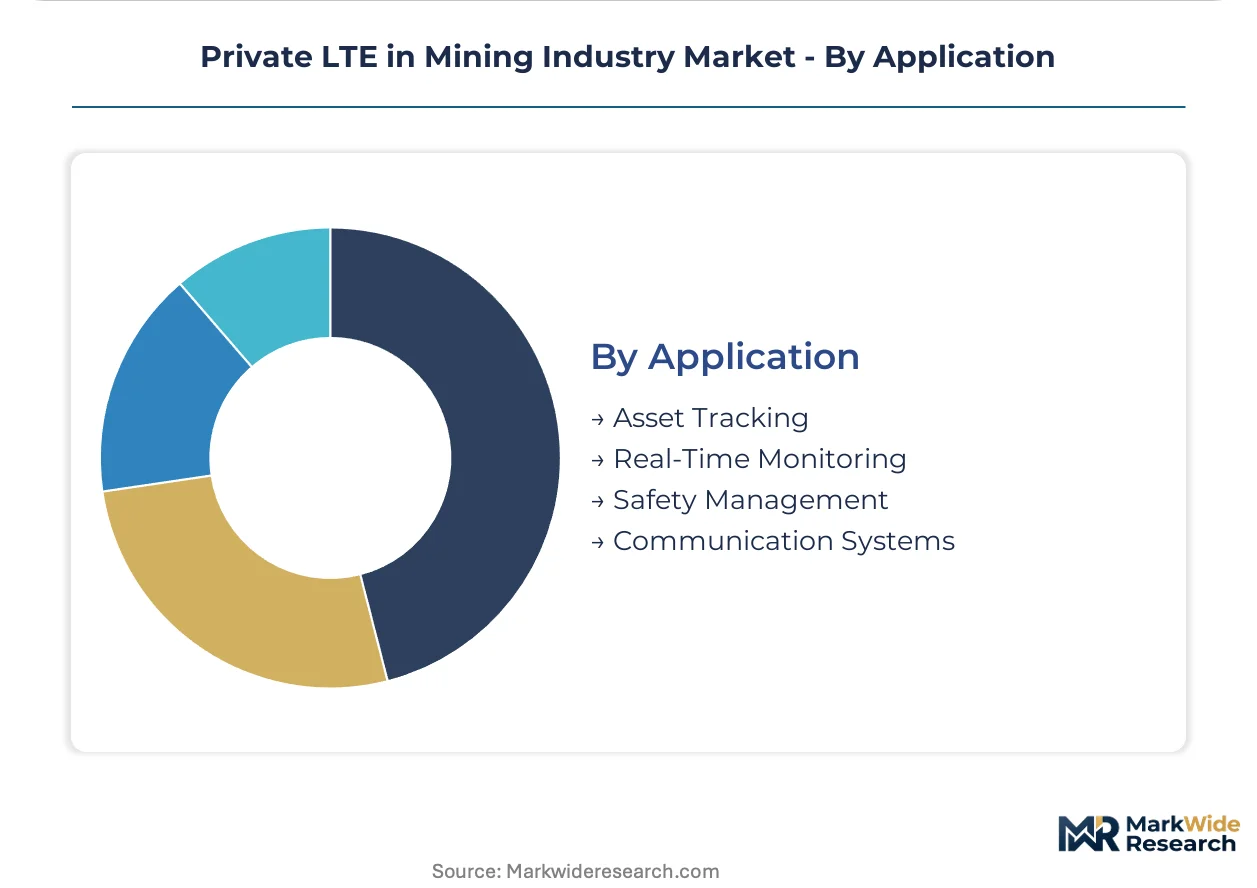
Safety management systems command premium pricing due to regulatory mandates and liability exposure, while asset tracking applications scale across fleet sizes with linear economics.
- Asset Tracking:Real-time location systems monitor heavy machinery, vehicles, and mobile equipment across extraction and processing zones. Canadian potash and Australian coal operators deploy asset tracking for fleet optimization and theft prevention.
- Real-Time Monitoring:Continuous sensor streams from crushers, conveyors, and ventilation systems enable predictive maintenance. Swedish underground iron ore mines integrate real-time monitoring with existing SCADA infrastructure.
- Safety Management:Lone-worker emergency signaling, gas detection alerts, and evacuation coordination require guaranteed quality-of-service levels. Underground operations in South Africa and Australia mandate safety management system deployment under national mining regulations.
- Communication Systems:Mission-critical voice, video, and data services replace legacy leaky feeder and Wi-Fi infrastructure. Surface mines in Brazil and Chile standardize on private LTE communication systems for pit-wide workforce coordination.
Safety management holds pricing power; asset tracking scales most efficiently.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara heavy haul rail network underwrites Australia's dominance in autonomous mining communications infrastructure. This dedicated freight corridor connects remote extraction sites to coastal export terminals across Western Australia.
Australia
Rio Tinto and BHP deploy private LTE across Pilbara iron ore operations for driverless truck coordination. ACMA mining-specific spectrum allocations in 400 MHz and 2.6 GHz bands eliminate public network interference. Perth-based systems integrators manage radio planning and core network operations for underground gold and base metal mines in Kalgoorlie.
Canada
Alberta oil sands operators combine private LTE with satellite backhaul for pit-wide workforce coordination. ISED 3.5 GHz priority licensing frameworks create first-mover advantages in industrial spectrum access. Saskatchewan potash miners around Saskatoon standardize on LTE-based autonomous haulage systems for continuous extraction operations.
United States
Arizona copper porphyry deposits and Nevada gold operations drive demand for hardened underground communications equipment. FCC Part 90 rules governing industrial/business pool frequencies shape hardware certification requirements and spectrum auction access. Equipment vendors target the Mountain West mining corridor spanning Utah, Colorado, and Idaho for small cell overlay deployments.
Sweden
Kiruna underground iron ore mines pilot 5G standalone cores for Time-Sensitive Networking integration with existing SCADA infrastructure. REACH substance restrictions and EU Green Deal embodied carbon reporting requirements reshape base station hardware specifications. Luleå technical universities supply radio planning expertise for geologically complex ore body propagation modeling.
Chile
Atacama Desert copper operations adopt managed service contracts to shift capital expenditure toward operational budgets. Subsecretaría de Telecomunicaciones frameworks govern industrial spectrum licensing for remote extraction sites. Antofagasta and Calama mining clusters deploy small cell overlays to supplement macro network dead zones in underground galleries.
Private LTE in Mining Industry Market Competitive Landscape
Listed leaders compete with private specialists across spectrum optimization and managed service delivery. The vendor landscape bifurcates between qualified mission-critical suppliers and generalist telecom equipment makers. Three archetypes dominate: integrated infrastructure providers, modular radio specialists, and managed service integrators. Competitive moves concentrate on strategic partnerships with mine operators and geographic expansion into resource-rich jurisdictions.
Within the integrated infrastructure tier, Nokia Corporation and Ericsson exemplify divergent geographic positioning strategies. Nokia leverages its Bell Labs heritage to sustain dominance in underground spectrum optimization. Ericsson anchors its market presence through deep partnerships with Australian and Canadian mine operators. Huawei Technologies Co., Ltd. occupies a distinct competitive position through integrated baseband-to-core offerings, though geopolitical headwinds constrain North American market access. These three entities collectively represent the spectrum of vendor approaches to mining-specific private LTE deployment.
| Leading Market Players |
|---|
| ZTE Corporation |
| Cisco Systems, Inc. |
| Nokia Corporation |
| Ericsson |
| Samsung Electronics Co. Ltd. |
| Huawei Technologies Co., Ltd. |
| Verizon |
| Qualcomm |
| NEC Corporation |
| Others |
Value Network & Pricing Analysis
FCC Part 90 certification requirements for industrial radio equipment gate both vendor qualification and price stratification in private LTE mining deployments. Hardware vendors must navigate divergent national spectrum frameworks simultaneously, concentrating supply leverage with integrators who hold multi-jurisdiction licensing expertise.
Pricing Analysis
Volume-discount tiering separates mission-critical hardened equipment from standard commercial-grade alternatives. Pricing stratifies across premium, standard, and economy tiers based on 3GPP Release 16 URLLC certification status and managed service bundling depth. Cost compression in the economy tier is intensifying as RedCap radios enable mid-tier quarry participation. Tier-one mining operators in Australia and Canada show lowest price sensitivity due to safety mandate compliance requirements, while aggregate quarries in North America drive aggressive procurement negotiation.
Supply Chain Analysis
Base station lead times extending 18-24 months reflect gallium nitride power amplifier inventory constraints concentrated in Taiwanese and South Korean foundries. Radio frequency component sourcing draws from East Asian semiconductor fabrication, with high-performance filter supply anchored in Japanese specialty ceramic manufacturers. Single-source vulnerability in GaN substrate supply creates propagation risk to deployment timelines. Distribution runs through specialist mining communications integrators who bundle spectrum licensing with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Private LTE mining infrastructure represents a service-attach opportunity where managed services revenue expands faster than base station hardware sales. Recurring network operations contracts now capture disproportionate margin pools relative to one-time equipment procurement.
For Market Incumbents: Shield market position by deepening 3GPP Release 16 certification portfolios before RedCap commoditization accelerates. Prioritize vertical integration into underground-hardened radio manufacturing to offset East Asian component concentration risk. Lock in long-term spectrum licensing partnerships with Australian ACMA and Canadian ISED to create regulatory switching costs for mine operators. For New Entrants and Emerging Players: 3GPP MCPTT fast-track certification programs open entry pathways into South African platinum belt safety management systems. Target mid-tier North American limestone quarries previously priced out of full LTE builds through RedCap-enabled small cell architectures. Lead with managed service offerings that shift customer capital expenditure to operational budgets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across 5G NR-RedCap device ecosystems as simplified radio complexity reduces infrastructure deployment costs. Long-term viability favors specialist integrators with multi-mine managed service contracts over pure-play hardware vendors. Watch 3GPP Release 17 timeline acceleration as the signal indicating RedCap volume market opening.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Service Contract Consolidation | Chilean copper operators shift capital expenditure to operational budgets through bundled network operations. |
| 3GPP Release 16 Certification Investment | Swedish hard-rock mines gain URLLC latency guarantees for Time-Sensitive Networking crusher control. |
| RedCap Radio Portfolio Development | Mid-tier quarry operators in North America access private cellular previously priced out of full LTE builds. |
| Spectrum Licensing Partnership | Australian ACMA mining-specific allocations lock in interference-protected operations for Pilbara iron ore sites. |
| Underground Propagation Modeling Capability | Canadian potash mines reduce deployment timelines through site-specific RF measurement campaigns. |
Research Methodology
Desk research of 3GPP standardization documents, national spectrum regulator filings, and mining operator procurement disclosures preceded structured interviews with mine communications engineers, radio planning specialists, and managed services procurement leads. Primary fieldwork across Australian Pilbara operations, Canadian oil sands sites, and Chilean copper underground galleries triangulated against equipment vendor technical specifications and systems integrator contract structures. Bottom-up deployment counts and top-down spectrum licensing revenue estimates were cross-validated.
Variance-decomposition across technology generation, deployment model, and end-use application segments shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include LTE versus 5G NR technology stacks, managed services versus on-premises deployment architectures, and underground versus surface mine end-use environments. CAGRs were derived from equipment shipment trajectories and recurring service contract value expansion. Forecast inputs incorporated ACMA spectrum allocation timelines and ISED priority licensing framework adoption rates.
Underlying assumptions cover sustained 3GPP standardization momentum and stable industrial spectrum policy across Australia, Canada, and the United States, with deviation risk concentrated in East Asian semiconductor supply disruptions and geopolitical equipment vendor restrictions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Mexico Telecom Market
Telecommunications
Global Small Cell 5G Network Market
Telecommunications
Kenya Telecom Market
Telecommunications
Standalone 5G Network Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
Carrier Aggregation Solutions Market
Telecommunications
Telecom Managed Services Market
Telecommunications
Chile Telecom Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Global Radio Access Network Market
Telecommunications
Embedded SIM (Esim) Market
Telecommunications
Austria ICT Market
Telecommunications
Global Broadband Services Market
Telecommunications
Norway Telecom Market
Telecommunications
Argentina Telecom Market
Telecommunications
Spain ICT Market