
 Denmark POS Terminals Market | 2026-2036
Denmark POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark POS Terminals Market Outlook
Market Context
Sweden's Nordic fintech corridor is fragmenting as cross-border payment infrastructure spreads. Ingenico Group (Worldline) anchors European terminal certification pathways for Danish merchants. Shopify leverages cloud-based commerce tools to compete with legacy hardware providers. Adyen sustains direct-acquiring relationships that bypass traditional banking intermediaries.
Technical Definition and Segment Structure
Denmark POS terminals encompass electronic payment acceptance devices combining secure chip readers, near-field communication modules, and encrypted data transmission protocols for commercial transaction processing. Mobile POS units process transactions through tablet or smartphone peripherals, while fixed POS terminals integrate with permanent retail checkout infrastructure. Cloud-based deployment captures structural momentum as Danish merchants abandon on-premises server maintenance. Contactless terminals lead transaction volume growth, though integrated systems command premium pricing through unified inventory and payment management.
Regulatory Environment and Outlook
Denmark's national payment systems regulator enforces PSD2 compliance and Strong Customer Authentication mandates across terminal deployments. The Danish Financial Supervisory Authority monitors acquiring bank relationships and interchange fee structures affecting merchant terminal economics. Stakeholders must track evolving EU digital wallet interoperability standards and domestic open-banking API requirements.
Market Dynamics
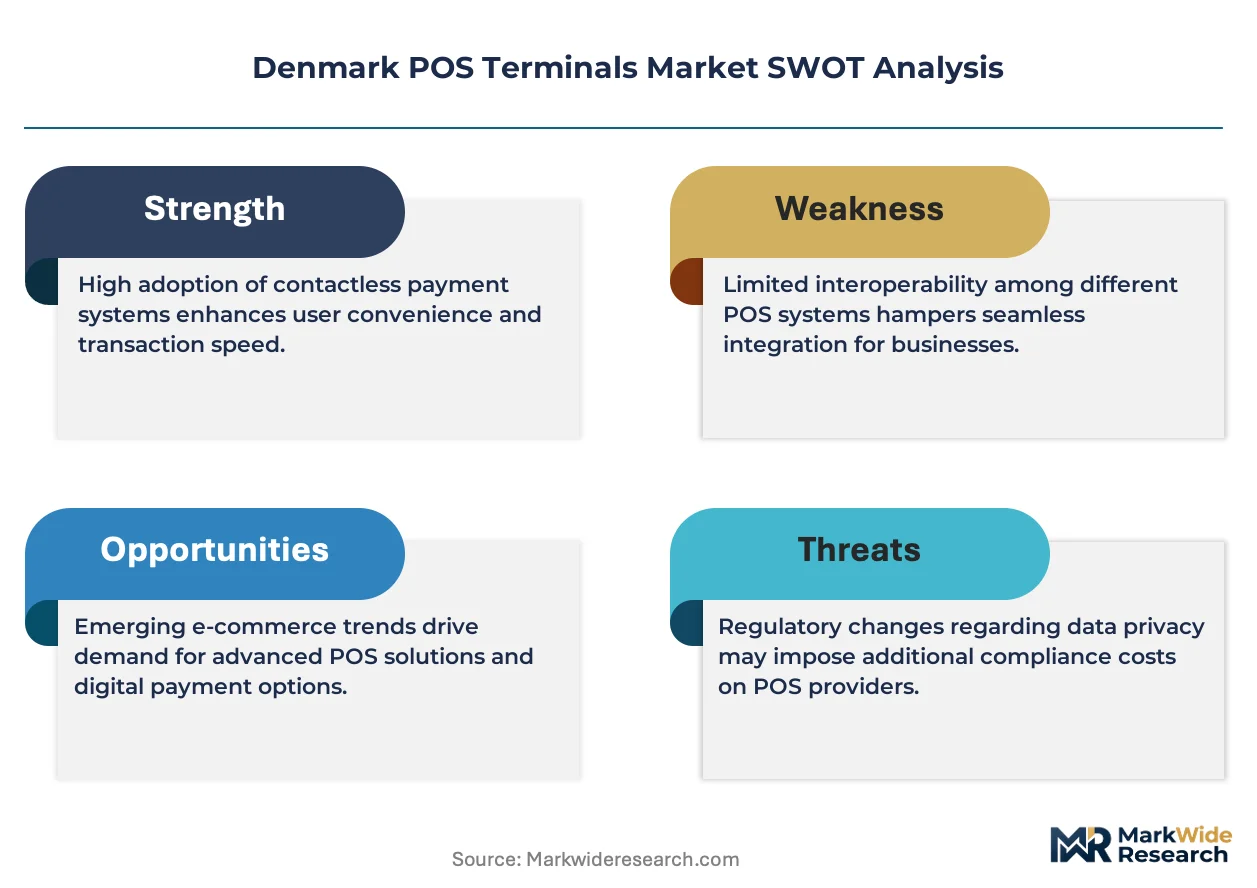
Cloud-based deployment architectures are displacing on-premises server infrastructure across Danish retail and hospitality sectors, compressing hardware refresh cycles and redirecting merchant capital toward subscription-based software layers.
Growth Catalysts
- PSD2 Strong Customer Authentication:Danish Financial Supervisory Authority mandates drive terminal hardware upgrades toward biometric-capable devices and dual-factor authentication modules.
- Hospitality contactless adoption:Copenhagen's restaurant and hotel corridor accelerates NFC-enabled terminal deployment to reduce transaction friction during peak service hours.
- API-first open banking:Domestic payment service providers integrate terminal data streams directly with merchant accounting systems, eliminating reconciliation delays.
Market Restraints
- Terminal certification bottlenecks:National payment systems regulator enforces extended testing protocols for EMV contactless compliance, stretching hardware approval timelines.
- Silicon supply concentration:Secure element chip fabrication concentrates in East Asian foundries, exposing Danish terminal assemblers to input volatility.
- Smartphone-based payment substitution:SoftPOS applications on consumer devices reduce merchant willingness to invest in dedicated hardware terminals.
Strategic Opportunities
- Odense-Aarhus retail corridor:Secondary urban centers outside Copenhagen maintain legacy cash-register infrastructure ripe for integrated POS replacement.
- EU digital wallet interoperability:Pending European Commission standards for cross-border wallet acceptance create certification advantages for early-compliant terminal vendors.
- Inventory-payment convergence:Cloud ERP systems merging with payment terminals enable real-time stock deduction, attracting mid-market Danish grocers.
Industry Challenges
- Cybersecurity talent scarcity:Terminal firmware development requires specialized encryption expertise that Danish labor markets supply inadequately.
- Legacy ERP integration complexity:Established Danish retailers operate decades-old inventory systems that resist API connectivity with modern cloud terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark POS Terminals Market |
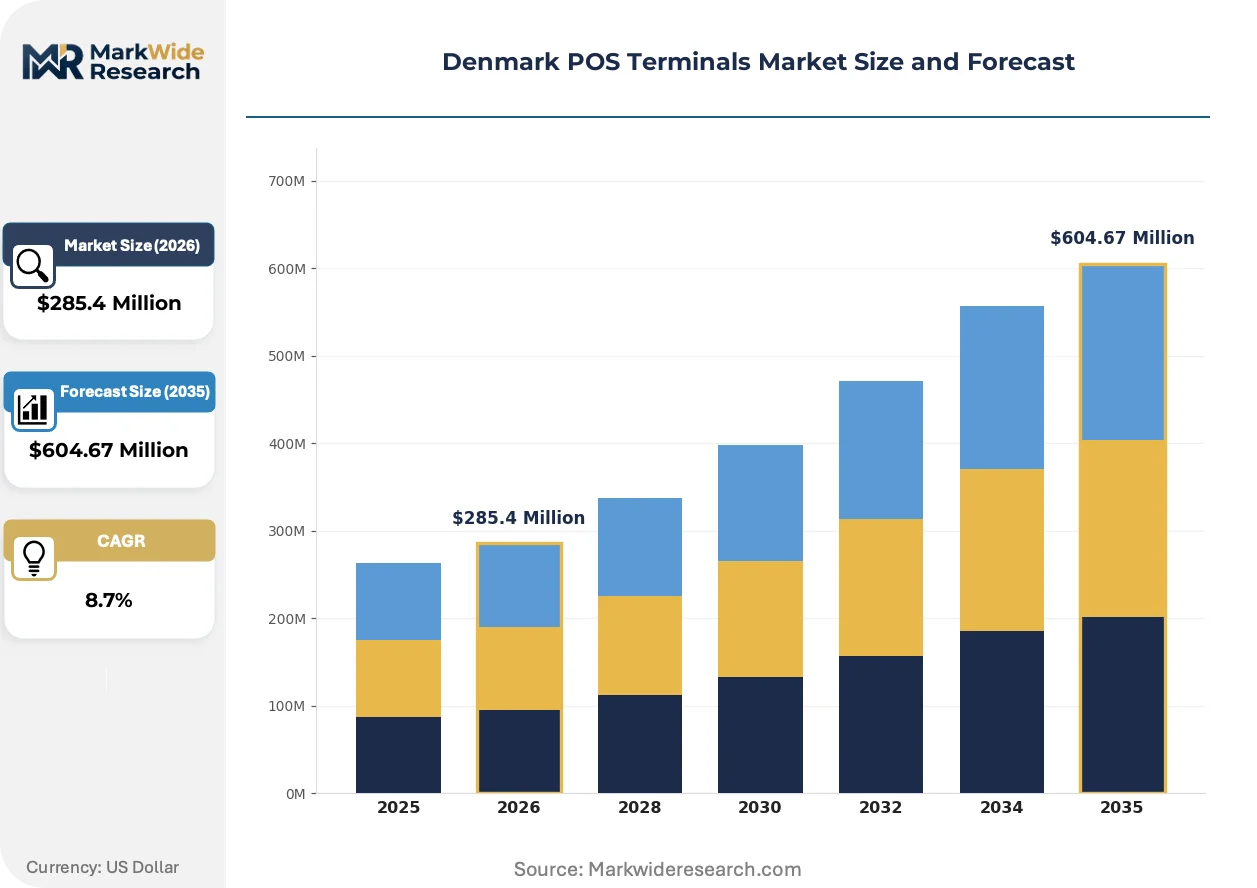
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Fixed POS, Contactless Terminals, Integrated Systems Deployment: Cloud-based, On-premises, Hybrid, Legacy Systems Customer Type: Small Businesses, Large Enterprises, Retail Chains, Hospitality Services Payment Method: Credit Cards, Debit Cards, Mobile Payments, Digital Wallets |
| Companies Covered | Shopify, OnlinePOS A/S, Ingenico Group (Worldline), Erply, DATECS Ltd, VeriFone Inc, myPOS World Ltd, Bizsys, Adyen, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark POS Terminals Market Strategic Shifts
Merchant acquisition strategies are pivoting from hardware margins toward software monetization, embedding payment terminals within broader commerce operating systems that capture transaction data value.
SoftPOS technology is digitizing smartphone and tablet devices into payment acceptance endpoints without dedicated hardware peripherals. Danish food trucks and pop-up retailers adopt these solutions fastest, eliminating upfront terminal procurement costs. This shift is digitizing the low-end of the merchant acquiring market, compressing entry-level hardware demand.
PSD2 Strong Customer Authentication rules enforced by the Danish Financial Supervisory Authority mandate biometric readers or PIN-on-glass interfaces for transactions exceeding contactless limits. Terminal manufacturers redesign form factors to accommodate fingerprint sensors. Small-format retail in Copenhagen's pedestrian zones faces the steepest compliance-driven replacement pressure.
Subscription-based terminal provisioning displaces outright purchase models across Danish merchant segments. Payment service providers bundle hardware, software, and acquiring services into per-transaction fees. Hospitality chains in Aarhus and Odense demonstrate the strongest uptake, preferring operational expenditure classification over capital deployment.
Denmark POS Terminals Market Segmentation
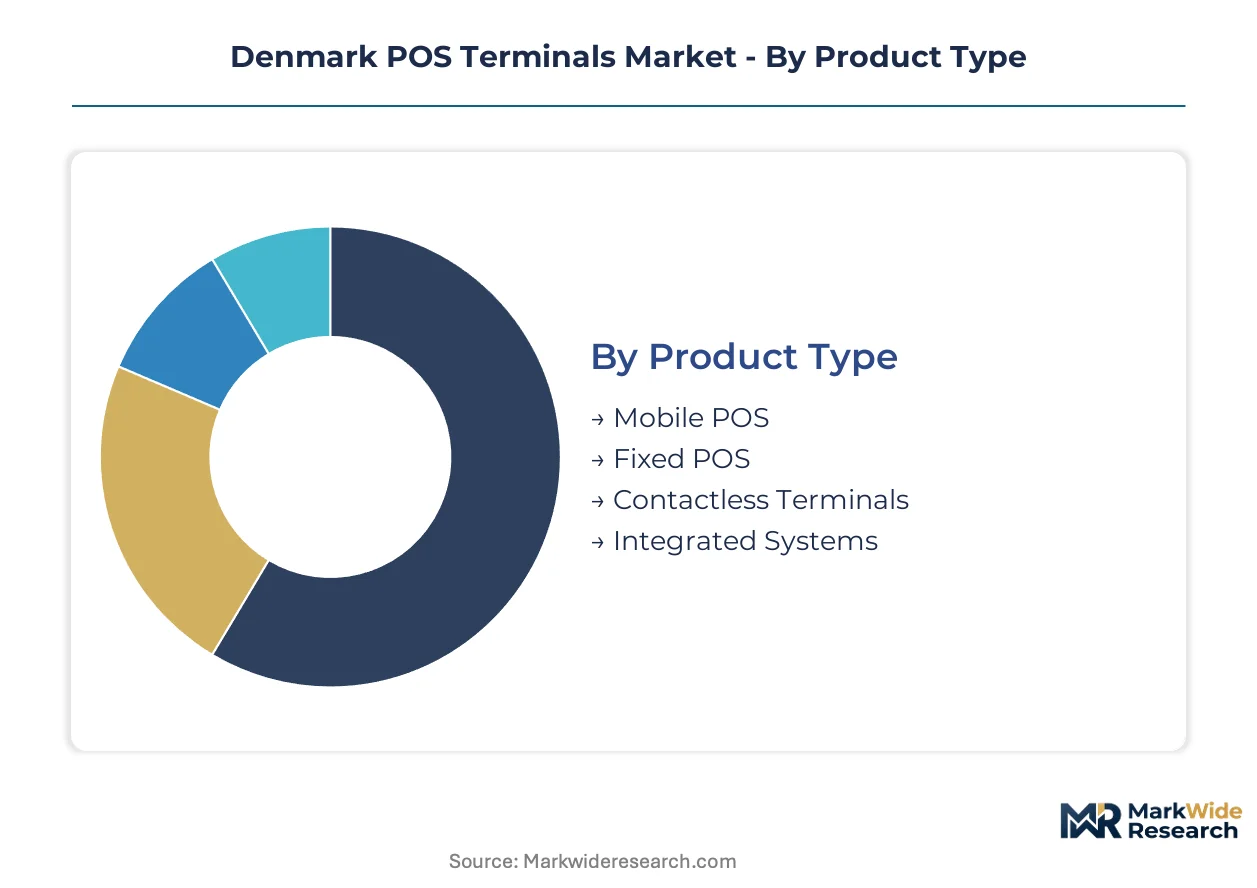
Denmark's POS terminal market fragments across hardware form factors, software deployment models, and merchant scale tiers. Each segmentation dimension carries distinct regulatory compliance requirements and capital expenditure profiles that reshape vendor go-to-market strategies.
Product Type:
Hardware configuration determines terminal mobility, connectivity architecture, and integration depth with merchant back-office systems.
- Mobile POS:Tablet and smartphone peripherals process transactions through Bluetooth-connected card readers. Copenhagen's food trucks and pop-up retailers drive demand for these lightweight units that eliminate countertop footprint constraints.
- Fixed POS:Permanent countertop terminals integrate with receipt printers and cash drawers through Ethernet or Wi-Fi backbones. Danish supermarkets and department stores in Aarhus maintain this infrastructure for high-volume checkout lanes.
- Contactless Terminals:NFC-enabled devices accept tap-to-pay cards and wearable payment tokens.
- Integrated Systems:Unified hardware combining payment acceptance, inventory scanning, and customer display modules.
Fixed POS holds installed capacity. Contactless Terminals is rotating up the share rankings.
Deployment:
Software architecture choices separate merchants by IT staffing levels and data sovereignty preferences.
- Cloud-based:Terminal data routes to remote servers managed by payment service providers, eliminating on-site server maintenance. Danish hospitality chains in Odense adopt this model to standardize multi-location operations without dedicated IT personnel.
- On-premises:Transaction data remains within merchant-controlled server infrastructure. Legacy Danish retailers with established data center investments retain this deployment for compliance audit trails.
- Hybrid:Sensitive payment data processes locally while analytics and reporting sync to cloud dashboards.
- Legacy Systems:Proprietary software stacks running on end-of-life operating systems.
Cloud-based deployment is expanding most quickly. On-premises retains share in regulated merchant segments.
Customer Type:
Merchant scale dictates terminal procurement economics and support service expectations.
- Small Businesses:Independent merchants with single-location operations and limited transaction volumes. Copenhagen's specialty boutiques negotiate per-transaction pricing rather than capital expenditure for hardware ownership.
- Large Enterprises:National retail and hospitality groups with centralized procurement functions. These merchants demand API connectivity between terminals and enterprise resource planning systems.
- Retail Chains:Multi-location merchants with standardized checkout formats across stores.
- Hospitality Services:Restaurants, hotels, and event venues requiring tableside or mobile payment acceptance.
Hospitality Services demonstrates steepest replacement cycles. Small Businesses concentrate new customer acquisition for terminal vendors.
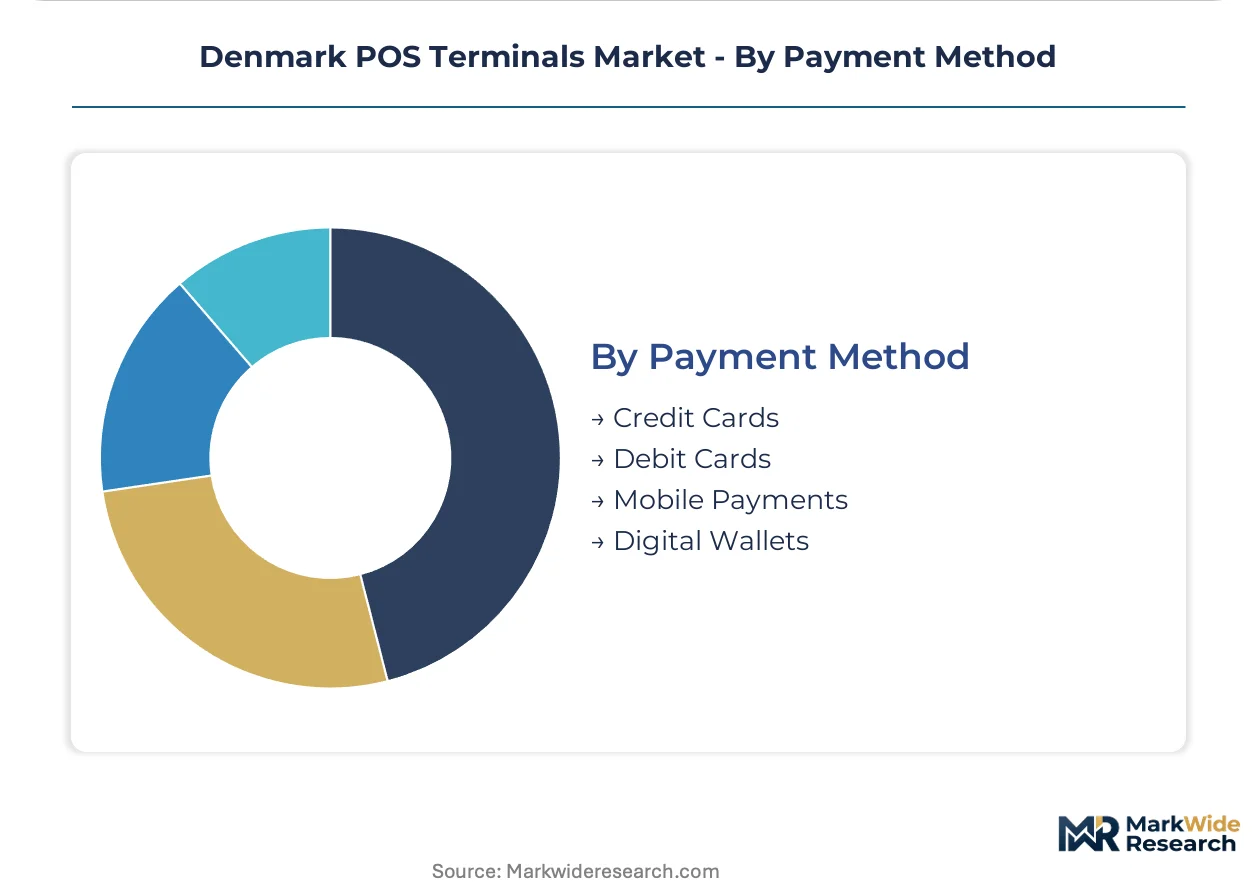
Payment Method:
Accepted transaction types determine terminal certification requirements and hardware module specifications.
- Credit Cards:International scheme cards (Visa, Mastercard) requiring EMV chip compliance and dynamic data authentication. Danish Financial Supervisory Authority mandates govern these transactions.
- Debit Cards:Domestic Dankort network cards carrying lower interchange fees and faster settlement timelines. Terminal certification for Dankort acceptance follows separate national protocols.
- Mobile Payments:Smartphone-based transactions through Apple Pay, Google Pay, and Samsung Pay.
- Digital Wallets:Merchant-branded stored-value applications and emerging European wallet standards.
Credit Cards maintains transaction volume leadership. Mobile Payments is climbing the fastest in terminal configuration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Terminal manufacturing concentrates in East Asian foundries, while Nordic software development and payment service provision anchors European merchant adoption patterns. Danish regulatory standards propagate across Scandinavian markets through shared certification frameworks.
Sweden
Stockholm's fintech corridor drives contactless terminal demand among hospitality merchants and boutique retailers. The Swedish Financial Supervisory Authority enforces PSD2 compliance timelines that accelerate hardware refresh cycles. Malmö's cross-border commerce with Copenhagen creates integrated POS requirements for dual-currency acceptance.
Norway
Oslo's oil-services hospitality sector demands ruggedized mobile POS units for seasonal tourism fluctuations. Finanstilsynet mandates Strong Customer Authentication for transactions above contactless thresholds, forcing biometric-capable terminal upgrades. Bergen's seafood export merchants require terminals with multi-language interfaces for international tourist payments.
Finland
Helsinki's design-focused retail sector prioritizes aesthetically integrated countertop terminals over purely functional hardware. The Finnish Financial Supervisory Authority monitors open-banking API standards affecting terminal data routing. Tampere's manufacturing supply chain supports Nordic terminal assembly with specialized secure-element sourcing.
Germany
Berlin's cashless retail acceleration creates demand for high-throughput fixed POS installations in department stores. BaFin enforces strict EMV certification protocols that Danish terminal vendors must navigate for cross-border market access. Munich's automotive supplier canteens and corporate campuses drive enterprise-scale terminal deployment with ERP integration requirements.
Denmark POS Terminals Market Competitive Environment
Payment hardware specialists and cloud-native software platforms split the market along legacy-versus-digital fault lines. Consolidation pressure intensifies as acquiring banks bundle terminal provisioning with merchant services. Two strategic archetypes dominate: integrated commerce platforms embedding payments within broader retail operating systems, and dedicated terminal manufacturers competing on certification speed and hardware reliability. Competitive moves center on subscription-based hardware provisioning and API-first ecosystem partnerships that lock merchants into recurring revenue relationships.
Among Nordic payment service providers, OnlinePOS A/S and Erply occupy positions emphasizing localized merchant support and inventory-payment convergence. Shopify exemplifies the cloud-platform archetype, leveraging software distribution to displace traditional hardware procurement models. Ingenico Group (Worldline) anchors the established terminal manufacturing tier, representing certification pathway dominance that newer entrants must circumvent through software differentiation.
| Leading Market Players |
|---|
| Shopify |
| OnlinePOS A/S |
| Ingenico Group (Worldline) |
| Erply |
| DATECS Ltd |
| VeriFone Inc |
| myPOS World Ltd |
| Bizsys |
| Adyen |
| Others |
Value Chain & Pricing Dynamics
Secure element chip fabrication concentration in East Asian foundries exposes Danish terminal assemblers to input volatility that compresses hardware margins and forces pricing stratification across premium, standard, and economy tiers. This single-source dependency for cryptographic processors dictates both the cost floor for certified devices and the geographic distribution of final assembly capacity.
Pricing Analysis
PSD2 Strong Customer Authentication dictates the pricing tier structure across Danish POS terminal deployments, with biometric-capable devices commanding premium positioning over basic NFC readers. Three-tier pricing structure across premium, standard, and economy levels separates integrated cloud-ERP systems from standalone contactless terminals and entry-level mobile peripherals. Cost compression in the standard tier is intensifying because SoftPOS applications reduce merchant willingness to pay for dedicated hardware. Small businesses in Copenhagen's specialty retail corridor demonstrate highest price sensitivity, while national hospitality chains absorb premium pricing for unified inventory-payment management.
Supply Chain Analysis
Export control restrictions on advanced semiconductor manufacturing equipment limit secure element chip flows from Taiwan and South Korea to Danish terminal assemblers, creating supply bottlenecks for EMV-certified components. Terminal production draws from Chinese final assembly facilities, Malaysian PCB fabrication, and German precision component suppliers. Single-source vulnerability concentrates in NFC controller chip sourcing from Taiwanese foundries. Distribution runs through Nordic payment service providers that bundle hardware with acquiring services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark's POS terminal market sits in early-cycle expansion as hospitality contactless adoption accelerates terminal replacement waves across Copenhagen, Aarhus, and Odense. Cloud-based deployment architectures are reshaping procurement patterns toward subscription models that extend vendor relationships beyond hardware transactions.
For Market Incumbents: Pre-empt SoftPOS substitution by embedding payment terminals within broader commerce operating systems that capture transaction data value. Incumbents should deepen API-first ecosystem partnerships with Danish ERP providers to lock merchants into recurring revenue relationships. Certification speed investments neutralize emerging entrants competing on software differentiation. For New Entrants and Emerging Players: Build out white-space positions in Odense-Aarhus retail corridors where legacy cash-register infrastructure resists integrated POS replacement. Secondary urban centers outside Copenhagen maintain the most penetrable merchant base for cloud-native terminal vendors. Food trucks and pop-up retailers offer fastest adoption velocity for mobile POS solutions. For Investors and Strategic Acquirers: EU digital wallet interoperability standards reshape the acquisition landscape toward early-compliant terminal vendors with certification advantages. Long-term viability centers on software monetization capabilities rather than hardware manufacturing scale. Watch pending European Commission standards for cross-border wallet acceptance as the signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cloud ERP merging with payment terminals attracts mid-market Danish grocers seeking real-time inventory deduction. |
| Certification Investment | Early EMV contactless compliance with Danish Financial Supervisory Authority protocols accelerates hardware approval timelines. |
| Geographic Expansion | Secondary urban corridor penetration in Odense and Aarhus captures legacy infrastructure replacement cycles. |
| Strategic Partnership | API-first collaborations with domestic payment service providers eliminate merchant reconciliation delays. |
| Product Launch | Biometric-capable terminal form factors address PSD2 Strong Customer Authentication mandates for Copenhagen retailers. |
Study Parameters
Initial hypotheses were tested against primary input from payment service provider executives, terminal firmware engineers, Danish hospitality procurement managers, and merchant acquiring specialists and refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of Danish Financial Supervisory Authority regulatory filings, EMV certification databases, Nordic payment network interchange data, and customs records for terminal component imports. Bottom-up merchant demand modeling triangulated against top-down payment volume projections.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning hardware form factor, deployment architecture, merchant scale tier, and payment method configuration. CAGRs derived from terminal shipment trajectories, merchant adoption curves, and replacement cycle dynamics. Cloud migration velocity and SoftPOS penetration rates served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native software platforms would shift outcomes toward subscription-dominated procurement. Material shifts in EU digital wallet interoperability standards or Danish open-banking API requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Latin America Retail Cash Management Market
Payments
Retail Cash Management Market
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Europe Digital Transaction Management (DTM) Market
Payments
Japan Virtual Cards Market
Payments
Germany Real Time Payments Market
Payments
Contactless Payment Ring Market
Payments
Global Telecom Billing and Revenue Management Market
Payments
Europe Clearing Houses and Settlements Market
Payments
Germany POS Terminal Market
Payments
NFC Payments Market
Payments
Asia-Pacific Payment Gateway Market
Payments
Cash Management System Market
Payments
In-Vehicle Payment System Market
Payments
Estonia POS Terminal Market
Payments
South Korea POS Terminals Market