
 Japan Mobile Payments Market | 2026-2036
Japan Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Mobile Payments Market Foresight
Asset-light acquiring models and revenue-sharing arrangements between fintech platforms and regional banks are tilting competitive dynamics toward scaled technology operators. PayPay Corporation leverages its merchant subsidy programs to dominate small-business onboarding. Rakuten Payment anchors its ecosystem strategy within the broader loyalty and e-commerce infrastructure. GMO Payment Gateway competes through specialized gateway services for mid-tier enterprises seeking modular integration.
Japan mobile payments encompass digital fund transfers executed through smartphones, tablets, or wearable devices, typically employing near-field communication protocols, encrypted token exchanges, or scannable matrix barcodes to authenticate and settle transactions between consumers and merchants. The primary commercial purpose centers on reducing cash-handling costs, accelerating checkout velocity, and capturing transaction data for loyalty program optimization and behavioral analytics. QR code-based settlement occupies the largest volume share among payment types, reflecting Japan's dense network of convenience stores and small-format retailers with low terminal investment thresholds. NFC infrastructure sustains premium positioning in transit and high-frequency urban corridors where tap speed determines throughput. Cloud-based deployment leads among technology configurations, though hybrid architectures gain traction among financial institutions balancing latency requirements with legacy core system constraints.
The Financial Services Agency enforces the Payment Services Act, which mandates registration for prepaid payment instrument issuers and imposes fund segregation requirements that shape capital allocation across wallet operators. METI promotes cashless conversion targets through merchant fee subsidies and consumer rebate programs, directly influencing adoption curves in prefectures with lower digital penetration. The Personal Information Protection Commission and JIS standards for biometric authentication constrain how tokenization and facial-recognition systems deploy at scale. Stakeholders must monitor whether FSA clarifications on stablecoin and crypto-asset interoperability expand or constrict the perimeter of permissible mobile payment functionalities.
Market Dynamics
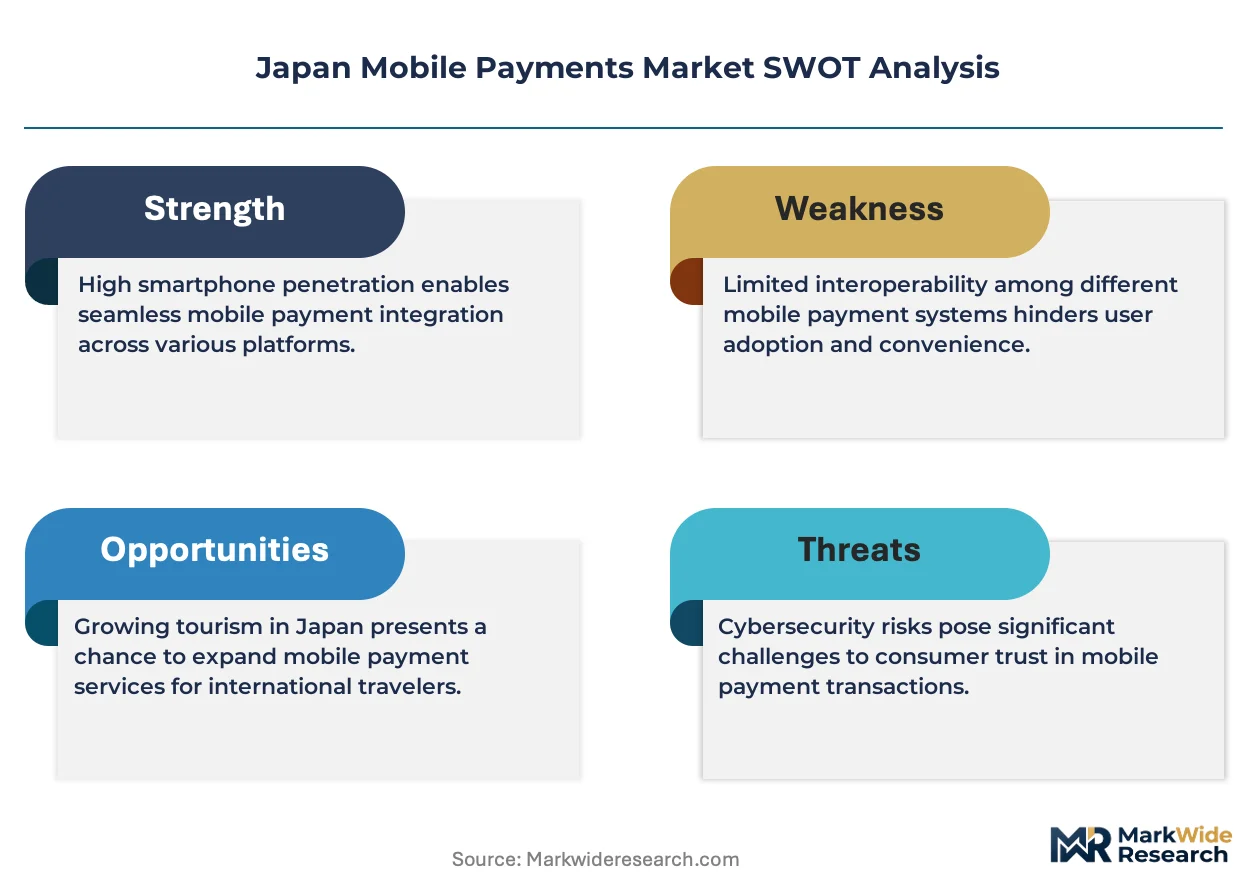
Japan's mobile payments sector is undergoing a fundamental reconfiguration as the Financial Services Agency tightens fund segregation rules under the Payment Services Act, forcing wallet operators to restructure capital reserves while transit authorities and convenience store chains accelerate interoperable QR code deployment across the Greater Tokyo metropolitan area.
Growth Catalysts
- METI Cashless Conversion Subsidies:Merchant fee rebates and consumer point-back programs in prefectures with lower digital penetration are accelerating small-business onboarding onto QR code platforms.
- Transit Authority NFC Modernization:Suica and PASMO system upgrades across JR East and private railway operators are embedding mobile wallet compatibility into high-frequency commuter corridors.
- Convenience Store Density:Seven-Eleven Japan, Lawson, and FamilyMart's combined 50,000-plus locations provide low-threshold QR terminal deployment that generates network effects for wallet providers.
Market Restraints
- FSA Fund Segregation Compliance:Prepaid payment instrument issuers must maintain segregated reserves equivalent to outstanding balances, constraining capital deployment for user acquisition subsidies.
- Regional Bank Infrastructure Fragmentation:Legacy core banking systems in Hokkaido and Kyushu institutions create integration friction for cloud-based wallet architectures.
- Cash Transaction Persistence:Japan's cultural attachment to physical currency, particularly among elderly demographics in rural prefectures, limits digital wallet penetration outside metropolitan centers.
Strategic Opportunities
- Osaka-Kobe-Kyoto Corridor Expansion:Merchant density in Kansi's urban core remains underpenetrated relative to Tokyo, offering whitespace for QR code network buildout.
- Biometric Authentication Convergence:Integration of facial recognition with JIS-compliant tokenization standards enables frictionless checkout in high-throughput retail environments.
- Regional Bank Partnership Channels:Asset-light acquiring models through revenue-sharing arrangements with Shizuoka Bank and Fukuoka Financial Group unlock small-business segments outside megabank dominance.
Industry Challenges
- Interoperability Standardization Delays:Competing QR code formats between PayPay, LINE Pay, and Rakuten Pay create merchant confusion and duplicate terminal investments.
- Legacy Core System Integration:Regional financial institutions' decades-old mainframe architectures require expensive middleware development for real-time wallet settlement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Mobile Payments Market |
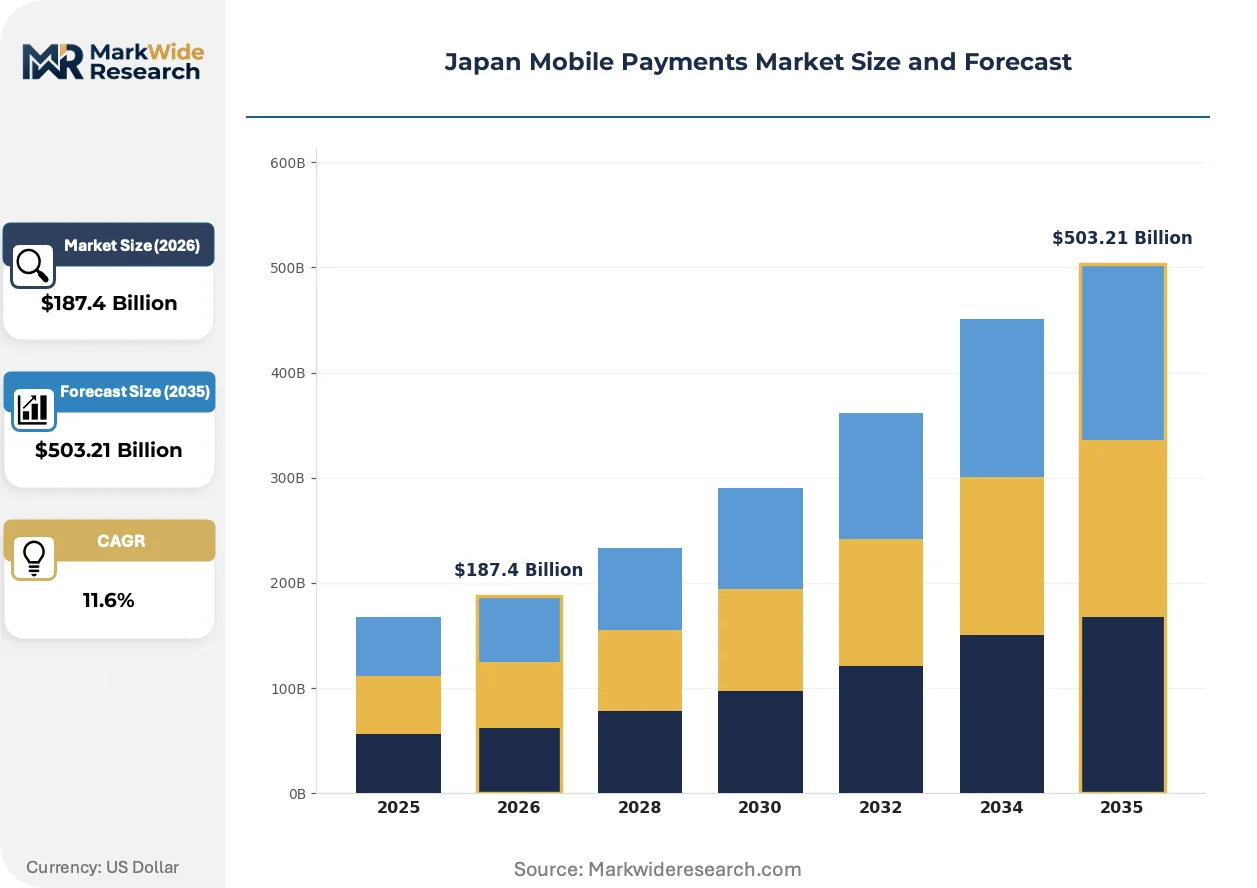
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $503.21 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: QR Code, NFC, Mobile Wallets, In-App Payments End User: Retail Customers, Businesses, E-commerce Platforms, Financial Institutions Deployment: Cloud-Based, On-Premises, Hybrid, Point of Sale Technology: Blockchain, Tokenization, Biometric Authentication, Machine Learning |
| Companies Covered | GMO Payment Gateway, Line Pay, PayPay Corporation, JCB, Credit Saison, Rakuten Payment, SB Payment Service, Mitsubishi UFJ Financial Group, LY Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Mobile Payments Market Shifts & Advancements
Tokenized biometric authentication is compressing transaction latency requirements while regulatory clarity on stablecoin interoperability is expanding the functional perimeter of permissible mobile payment instruments beyond traditional prepaid wallets.
Cloud-native token vaults with edge-computing deployment are rendering obsolete on-premise hardware security modules that previously dominated payment processor infrastructure. Mid-tier enterprises in Osaka and Nagoya are adopting these architectures to reduce PCI-DSS compliance overhead. The shift is compressing capital expenditure cycles for merchant acquirers while accelerating settlement velocity.
METI's revised guidelines on open banking APIs, issued under the Banking Act amendments, mandate standardized data portability between financial institutions and fintech platforms. This regulatory pressure is forcing regional banks to expose core transaction feeds to licensed wallet operators. The Fukuoka and Sapporo metropolitan areas are experiencing the fastest API integration timelines as local institutions race to meet compliance deadlines.
Consumer preference is rotating toward consolidated super-app wallets that unify transit, retail, and loyalty functions within single interfaces. Convenience store chains in Aichi and Hyogo prefectures are responding by consolidating previously separate payment terminals into unified QR-NFC hybrid devices. This behavioral shift is most visible among commuters aged 25-40 who prioritize checkout speed over brand-specific loyalty programs.
Japan Mobile Payments Market Segmentation
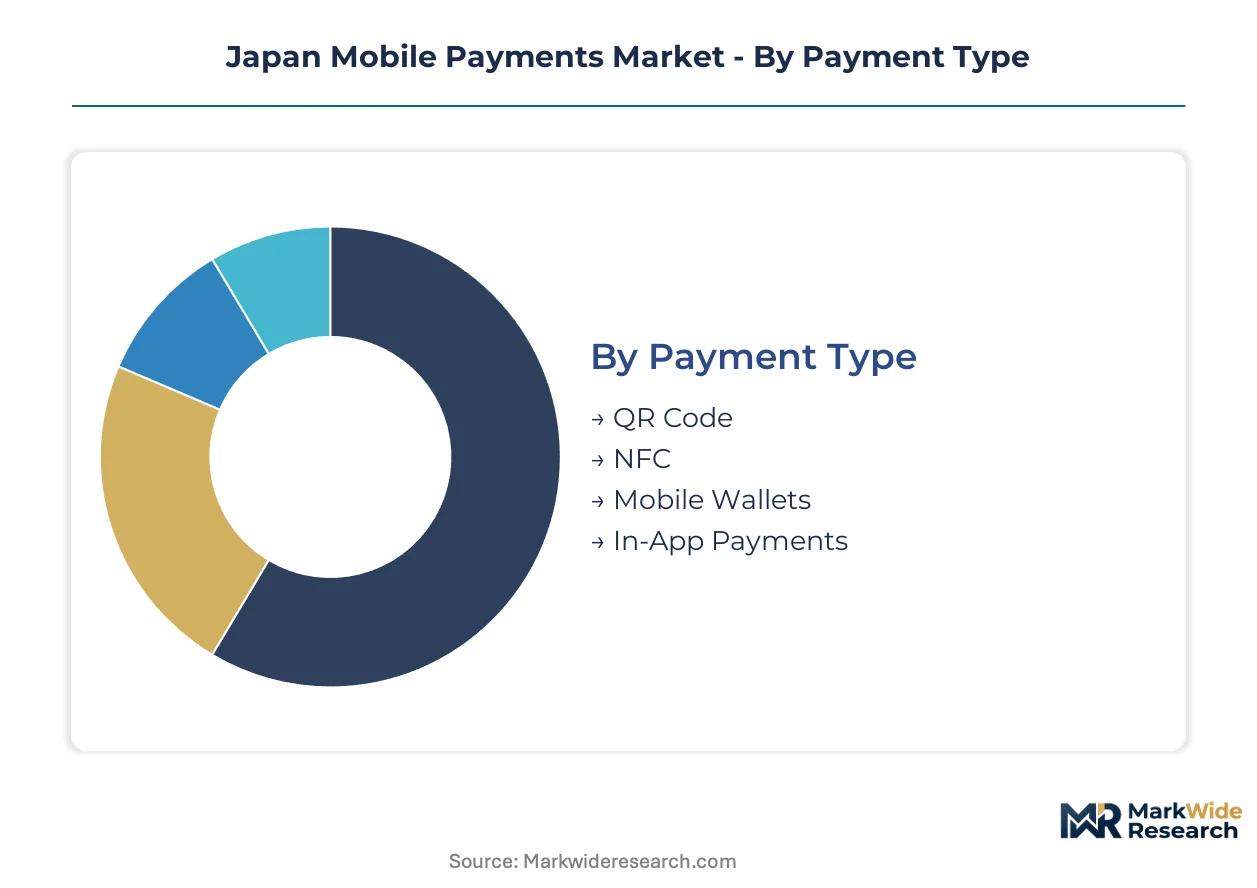
Japan's mobile payments landscape fragments across payment protocols, user archetypes, infrastructure models, and authentication technologies. Each dimension carries distinct regulatory footprints and capital intensity profiles that shape competitive positioning for wallet operators and merchant acquirers.
Payment Type:
Japan's payment type spectrum spans from low-infrastructure QR codes to embedded NFC transit systems, with each format commanding different merchant onboarding economics and consumer habit formation patterns.
- QR Code:Scannable matrix barcodes dominate small-format retail due to minimal terminal investment requirements. Demand concentrates in Greater Tokyo's convenience store corridors where merchant density generates network effects for wallet providers.
- NFC:Near-field communication protocols enable sub-second authentication for transit and premium retail environments. Suica and PASMO system integration across JR East commuter lines sustains volume concentration in high-frequency urban corridors.
- Mobile Wallets:Consolidated super-app interfaces unifying transit, retail, and loyalty functions. Adoption accelerates among demographics aged 25-40 prioritizing checkout velocity over brand-specific programs.
- In-App Payments:Embedded settlement within merchant-owned applications bypassing third-party wallet interfaces. E-commerce platforms in Osaka-Kobe-Kyoto corridor deploy these to capture first-party transaction data.
Established volume favors QR Code; emerging adoption favors Mobile Wallets.
End User:
End user segmentation reveals divergent procurement patterns between transaction-intensive retail networks and compliance-heavy financial infrastructure.
- Retail Customers:Individual consumers executing person-to-merchant transactions through smartphone interfaces. Point-back programs from METI concentrate demand in prefectures with historically lower digital penetration.
- Businesses:Small and mid-sized enterprises seeking reduced cash-handling overhead and accelerated reconciliation. Regional bank partnerships in Fukuoka and Sapporo unlock merchant segments outside megabank dominance.
- E-commerce Platforms:Online marketplaces requiring tokenized payment flows with PCI-DSS compliance. Cloud-native architectures gain traction among mid-tier enterprises in Nagoya seeking reduced compliance overhead.
- Financial Institutions:Banks and payment service providers issuing prepaid instruments under FSA registration requirements. Fund segregation mandates constrain capital deployment for user acquisition subsidies.
Transaction density peaks with Retail Customers; integration complexity concentrates with Financial Institutions.
Deployment:
Deployment models reflect latency requirements against legacy system constraints across Japan's heterogeneous banking infrastructure.
- Cloud-Based:Distributed token vaults with edge-computing deployment rendering on-premise hardware security modules obsolete. Settlement velocity advantages attract merchant acquirers in Aichi and Hyogo prefectures.
- On-Premises:Localized infrastructure maintaining data sovereignty for institutions with legacy core system dependencies. Regional banks in Hokkaido and Kyushu retain these architectures due to integration friction.
- Hybrid:Architectures balancing real-time wallet settlement with batch-processed legacy core feeds. Fukuoka metropolitan institutions adopt these configurations to meet open banking API compliance deadlines.
- Point of Sale:Terminal-integrated deployments at physical merchant locations. Convenience store chains consolidate previously separate payment terminals into unified QR-NFC hybrid devices.
Capital efficiency favors Cloud-Based; regulatory latency sustains Hybrid.
Technology:
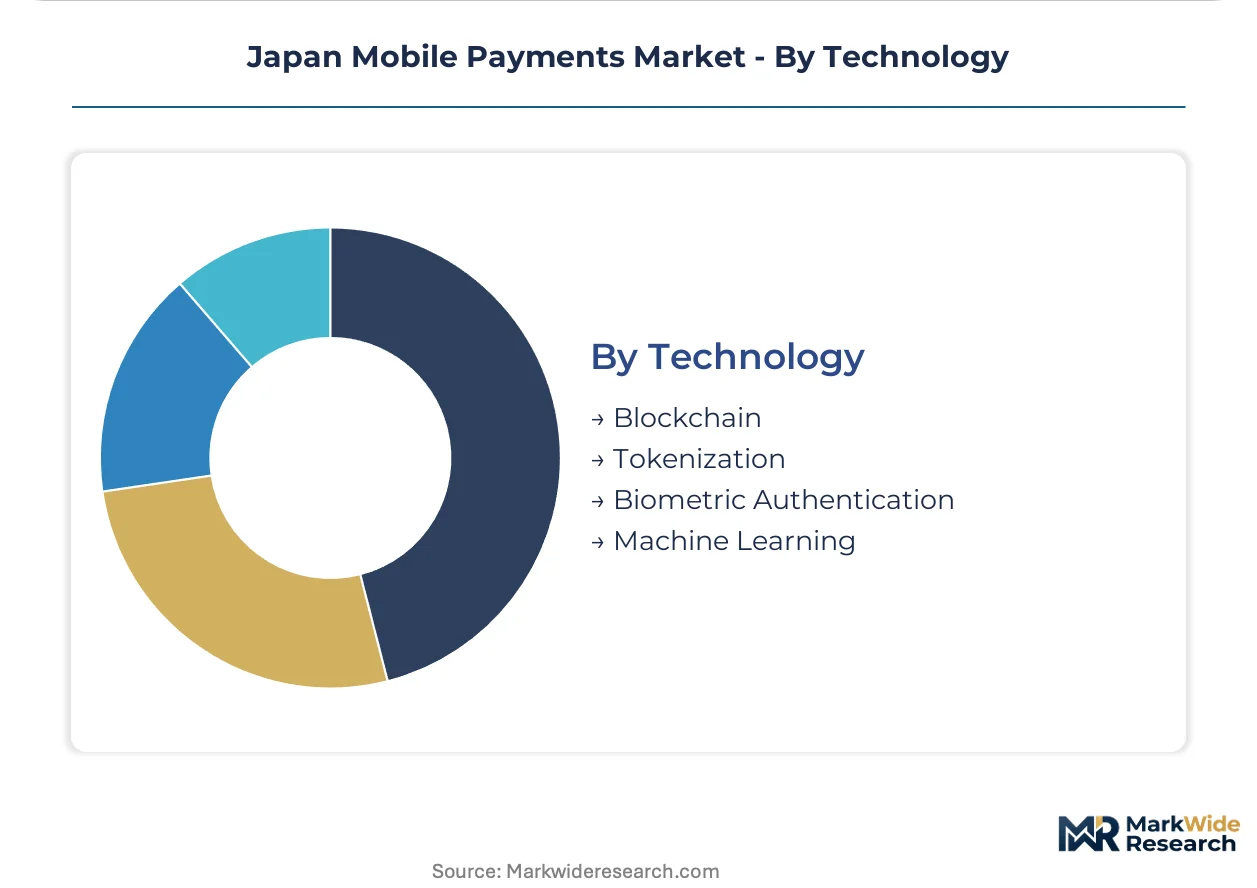
Technology segmentation tracks authentication and ledger innovations reshaping permissible payment instrument boundaries under evolving FSA guidance.
- Blockchain:Distributed ledger infrastructure for settlement finality and cross-border remittance corridors. Regulatory clarity on stablecoin interoperability from FSA is expanding functional perimeters.
- Tokenization:Replacement of sensitive card data with non-sensitive equivalents reducing breach exposure. JIS standards for biometric authentication constrain how facial-recognition systems deploy at scale.
- Biometric Authentication:Facial recognition and fingerprint verification compressing transaction latency. High-throughput retail environments in Tokyo metropolitan area pilot frictionless checkout implementations.
- Machine Learning:Behavioral analytics for fraud detection and loyalty program optimization. Transaction data capture enables personalized point-back calculations under METI subsidy frameworks.
Regulatory maturation favors Tokenization; experimental adoption clusters around Blockchain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's cashless conversion subsidies and FSA regulatory frameworks are redistributing mobile payment infrastructure investment across Japan's major metropolitan corridors, with merchant density and transit integration determining wallet provider penetration rates.
Kanto/Tokyo
Greater Tokyo's convenience store density and JR East commuter volumes generate unmatched network effects for QR code and NFC wallet providers. The Financial Services Agency's fund segregation requirements under the Payment Services Act concentrate compliance investment among prepaid instrument issuers headquartered in the metropolitan core. Shinjuku and Shibuya commercial districts host the highest terminal deployment rates for unified QR-NFC hybrid devices.
Kansai/Osaka
Osaka-Kobe-Kyoto corridor merchants exhibit lower digital wallet penetration relative to Tokyo, creating whitespace for QR code network buildout. METI merchant fee rebate programs target this region specifically to accelerate cashless conversion. Dotonbori retail clusters and Osaka Station transit hubs are piloting biometric authentication integration with JIS-compliant tokenization standards.
Chubu/Nagoya
Mid-tier enterprises in Aichi and Gifu prefectures are adopting cloud-native token vaults to reduce PCI-DSS compliance overhead. Open banking API mandates under revised Banking Act amendments are forcing regional institutions to expose core transaction feeds to licensed wallet operators. Nagoya Station and Sakae commercial districts concentrate merchant acquirer deployment activity.
Kyushu
Fukuoka metropolitan institutions are adopting hybrid cloud-on-premise architectures to meet open banking compliance deadlines while managing legacy core system constraints. Revenue-sharing arrangements between fintech platforms and Fukuoka Financial Group unlock small-business segments outside megabank dominance. Hakata Station transit corridors sustain NFC infrastructure investment from regional railway operators.
Hokkaido
Sapporo metropolitan banks are racing to meet API integration timelines under METI's open banking guidelines, though legacy mainframe architectures create settlement friction for real-time wallet architectures. Cash transaction persistence among elderly demographics in rural prefectures limits digital penetration outside Sapporo's urban core. Regional convenience store chains are consolidating separate payment terminals into unified devices.
Japan Mobile Payments Market Competitive Landscape
On the supply side, the industry is consolidating around technology platforms with scaled merchant acquisition capabilities and ecosystem integration depth. The competitive structure tilts toward operators combining subsidy-funded user acquisition with transit authority partnerships. Three archetypes dominate: ecosystem-anchored super-app wallets, specialized payment gateway providers, and financial institution-backed instrument issuers. M&A activity concentrates on acquiring regional bank partnership channels, while technology licensing agreements proliferate for biometric authentication modules.
Among Japan-based operators, PayPay Corporation and Rakuten Payment exemplify the ecosystem-anchored archetype, leveraging merchant subsidy programs and loyalty infrastructure respectively to secure network density. GMO Payment Gateway occupies a specialist position serving mid-tier enterprises with modular gateway integration. These three entities represent distinct competitive vectors: mass-market penetration through subsidized onboarding, vertical integration within retail and e-commerce ecosystems, and technical specialization for enterprise middleware requirements.
| Leading Market Players |
|---|
| GMO Payment Gateway |
| Line Pay |
| PayPay Corporation |
| JCB |
| Credit Saison |
| Rakuten Payment |
| SB Payment Service |
| Mitsubishi UFJ Financial Group |
| LY Corporation |
| Others |
Supply & Pricing Matrix
The Port of Yokohama container corridor's freight cost dynamics compress margins for hardware terminal manufacturers while amplifying price differentiation between FSA-certified wallet operators and uncertified fintech entrants across Japan's payment ecosystem.
Pricing Analysis
Certification level under FSA Payment Services Act registration creates the primary spread between prepaid instrument issuers and unlicensed payment facilitators. Pricing stratifies across premium FSA-registered wallets, standard regional bank partnerships, and economy-tier white-label acquirers. Cost compression in economy tiers is intensifying because METI merchant subsidy programs cap per-transaction revenue shares. Small-format retailers in rural prefectures exhibit highest price sensitivity; transit-integrated super-app wallets command lowest sensitivity among Tokyo commuters.
Supply Chain Analysis
Foxconn and Pegatron concentration in Taiwan and China dominates NFC terminal hardware assembly for Japanese wallet operators. Semiconductor fabrication draws from TSMC's Taiwanese foundries, Samsung's South Korean memory facilities, and domestic Renesas microcontroller production. Single-source vulnerability concentrates in advanced biometric sensor modules from limited qualified suppliers. Distribution runs through regional bank partnership channels and convenience store chain procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of real-time settlement engineering talent constrains wallet operator expansion, privileging incumbents with captive technical infrastructure over capital-rich challengers.
For Market Incumbents: Harden token vault security architectures against biometric authentication spoofing attacks while consolidating regional bank partnership channels in Kyushu and Hokkaido. Vertical integration into edge-computing infrastructure reduces latency-dependent merchant churn. FSA fund segregation rule tightening threatens smaller issuers; acquire their prepaid instrument licenses before compliance deadlines force exits. For New Entrants and Emerging Players: The Osaka-Kobe-Kyoto corridor's underpenetrated merchant density offers whitespace for QR code network buildout without Tokyo's subsidy-saturated acquisition costs. Target Fukuoka Financial Group's SME lending book for embedded wallet distribution. White-label gateway licensing to mid-tier Nagoya enterprises bypasses direct consumer acquisition burn rates. For Investors and Strategic Acquirers: Carve-out targets emerge from regional bank payment subsidiaries lacking cloud-native architecture capabilities. Five-to-ten-year viability hinges on open banking API compliance rather than transaction volume scale. Watch FSA stablecoin guidance clarifications as regulatory inflection signal for blockchain-integrated wallet valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FSA Prepaid Instrument License Acquisition | Captures regulatory moat as fund segregation rules tighten compliance thresholds. |
| Regional Bank Partnership Expansion | Unlocks SME merchant segments outside PayPay's subsidy-dominated Tokyo stronghold. |
| Biometric Authentication Module Integration | Compresses checkout latency for JR East commuter corridor wallet adoption. |
| Cloud-Native Token Vault Migration | Reduces PCI-DSS compliance overhead for mid-tier Osaka-Kobe-Kyoto enterprises. |
| Transit Authority System Interoperability | Embeds wallet functionality into Suica-PASMO infrastructure for habitual usage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across wallet operators, regional bank payment divisions, and convenience store chain procurement heads. Secondary validation drew from FSA regulatory filings, METI cashless conversion reports, JR East transit data disclosures, and JIS standards documentation. Bottom-up merchant terminal deployment counts triangulated against top-down transaction volume estimates from prepaid instrument issuer registrations.
Calibration anchored projections to observed API integration timelines and open banking compliance deadlines across the analysis window. Segmentation modeled payment protocol type, deployment architecture, end-user archetype, and authentication technology tier. CAGRs derived from merchant onboarding velocity curves and commuter corridor wallet adoption saturation patterns. FSA fund segregation reserve requirements and METI subsidy program budgets fed regulatory scenario inputs.
The forecast holds incumbent behavior within observed patterns; aggressive subsidy escalation by ecosystem-anchored super-apps or accelerated regional bank consolidation would shift outcomes. Quarterly review of FSA enforcement actions, METI rebate program renewals, and transit authority NFC procurement awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Biometric Payment Cards Market
Payments
Biometric Payment Market
Payments
Global Payments Market
Payments
Cross-Border Payment Platform Market
Payments
Dual Interface Payment Card Market
Payments
Singapore Payments Market
Payments
Spain POS Terminals Market
Payments
Estonia POS Terminal Market
Payments
Buy Now Pay Later Platform Market
Payments
Bitcoin Payments Market
Payments
Smart POS System Market
Payments
United States Clearing Houses and Settlements Market
Payments
India Mobile Payments Market
Payments
Cyprus POS Terminals Market
Payments
Medical Payment Fraud Detection Market
Payments
Italy Gift Cards Market