
 United States Payment Gateways Market | 2026-2036
United States Payment Gateways Market Size, Share, and Industry Trends Forecast 2026-2036
United States Payment Gateways Market Intelligence
Merchant buyer fragmentation across small businesses and marketplace sellers is repositioning how payment infrastructure providers allocate engineering resources. Stripe, Inc. leverages developer-centric API tools to capture high-growth software platforms. PayPal Holdings, Inc. sustains consumer trust through its dual-sided network of buyers and merchants. Square dominates in-person commerce through integrated hardware-software systems for Main Street retailers.
A payment gateway is a technology layer that encrypts, routes, and authorizes transaction data between merchants, acquiring banks, and card networks using TLS protocols and tokenization standards. Its commercial purpose is to reduce fraud exposure while enabling real-time settlement across digital and physical channels. Hosted payment pages now anchor margin pools because they shift compliance liability away from merchants. API integration represents the fastest-expanding technology segment as platforms embed financial services directly into software workflows. E-commerce end users continue to outpace retail in transaction volume growth.
The Federal Reserve's FedNow Service, NACHA operating rules for ACH transfers, and PCI DSS certification requirements collectively shape provider architecture and market access thresholds. The Consumer Financial Protection Bureau scrutinizes fee transparency and dispute resolution standards. Stakeholders must monitor how real-time settlement mandates and open banking rulemaking alter competitive dynamics between bank-owned and independent gateway platforms.
Market Dynamics
The FedNow real-time payment infrastructure is forcing gateway providers to rebuild settlement architectures from batch-based to instant-clearing systems. Small merchants now expect sub-second fund availability as a baseline feature.
Growth Catalysts
- PCI DSS compliance mandates:The Payment Card Industry Data Security Standard requires tokenization and encryption upgrades, compelling merchants to abandon legacy terminals for certified cloud gateways.
- California's technology corridor:Software platforms in San Francisco and San Jose embed financial services directly into SaaS workflows, expanding API-first gateway adoption.
- Embedded finance convergence:Marketplace sellers and vertical software vendors integrate checkout, lending, and treasury functions through unified gateway stacks.
Market Restraints
- Interchange cost volatility:Card network fee schedules and assessment charges compress margins for independent gateways serving price-sensitive Main Street retailers.
- Bank-owned platform concentration:JPMorgan Chase, Bank of America, and Wells Fargo operate captive gateway infrastructure, limiting addressable market for third-party providers.
- Technical debt in legacy ISO integrations:Reseller networks built on 1990s protocol stacks resist API migration, slowing feature parity with modern platforms.
Strategic Opportunities
- Underpenetrated rural merchant segments:Agricultural cooperatives and independent gas stations across the Great Plains lack integrated POS-gateway solutions.
- Healthcare payment modernization:HIPAA-compliant patient portals and HSA-linked checkout flows create specialized infrastructure demand.
- Buy Now Pay Later convergence:Installment lending embedded at checkout is rewriting consumer payment preferences and gateway fee structures.
Industry Challenges
- Cybersecurity talent scarcity:Cryptographic engineering and fraud modeling expertise concentrates in New York and San Francisco, leaving regional providers understaffed.
- Certification timeline compression:Annual PCI DSS audits and FedNow operational readiness assessments demand continuous compliance investment.
- ISO partner churn:Independent sales organizations switch gateway providers based on residual splits, eroding channel stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Payment Gateways Market |
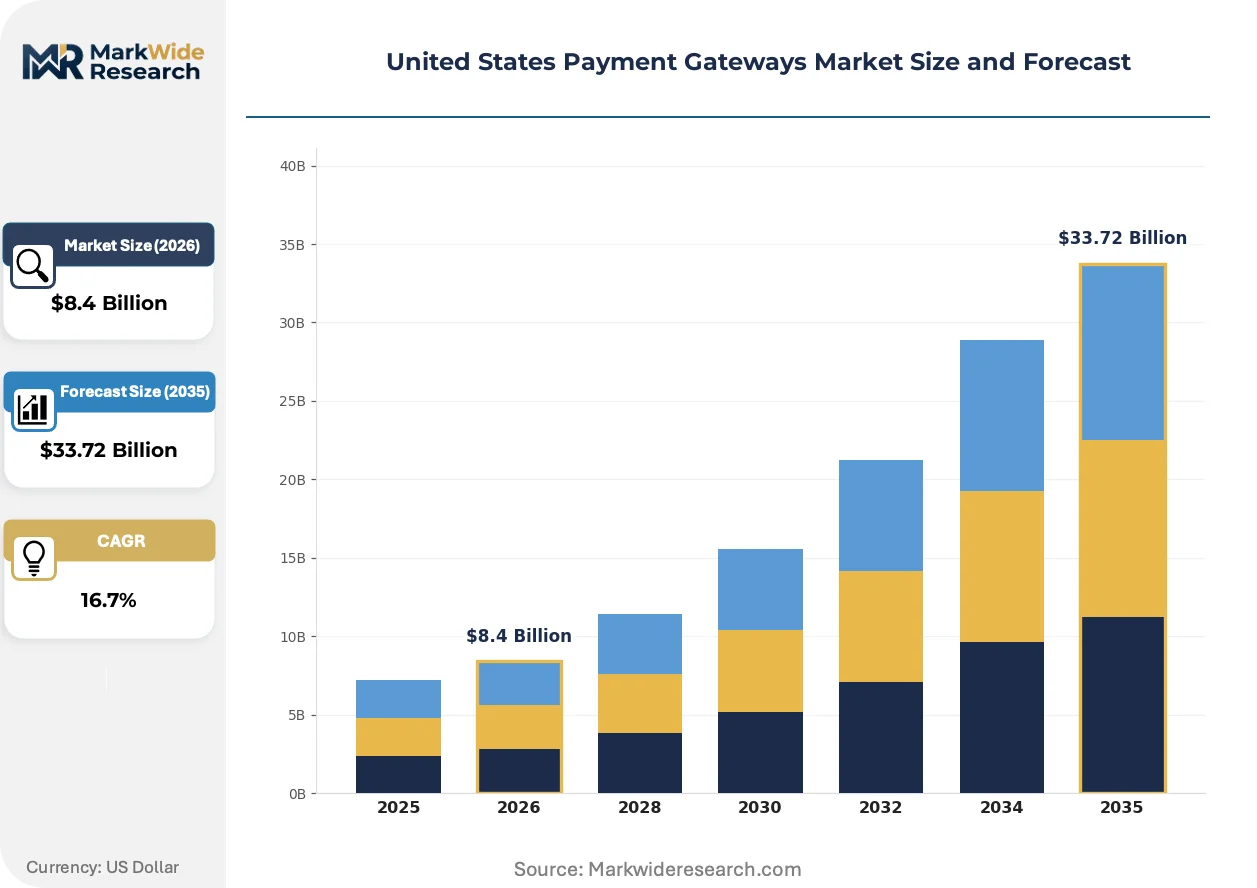
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Credit Card Processing, Digital Wallets, ACH Transfers, Payment Security Technology: API Integration, Hosted Payment Pages, Point of Sale, Mobile Payments End User: E-commerce, Retail, Non-Profit, Subscription Services Customer Type: Small Businesses, Enterprises, Individual Consumers, Marketplaces |
| Companies Covered | Stripe, Inc., PayPal Holdings, Inc., Adyen, Amazon Pay, Braintree, WePay, Inc., Shopify Payments, Authorize.net, Square, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Payment Gateways Market Strategic Shifts & Innovations
Payment infrastructure is fragmenting across specialized stacks for embedded finance, real-time settlement, and merchant-facing software platforms. Providers must now engineer for three distinct buyer psychologies simultaneously.
Tokenization vaults with network-agnostic credential storage are rewriting fraud liability allocation between merchants and gateways. Large retailers in Texas and Florida are adopting these systems to reduce breach exposure. The technology is compressing PCI scope and enabling checkout customization without compliance burden.
The Consumer Financial Protection Bureau's scrutiny of junk fees and dispute resolution standards is reshaping gateway pricing transparency requirements. Providers must now itemize interchange pass-through and platform fees separately. Small business merchants in Illinois and Ohio are switching to gateways with simplified fee structures.
Merchant procurement of payment infrastructure is fragmenting from single-gateway relationships to multi-provider orchestration stacks. Enterprise retailers now route transactions dynamically across gateways based on cost, approval rates, and redundancy needs. This pattern is most visible among marketplace sellers operating across California, New York, and Texas fulfillment networks.
United States Payment Gateways Market Segmentation
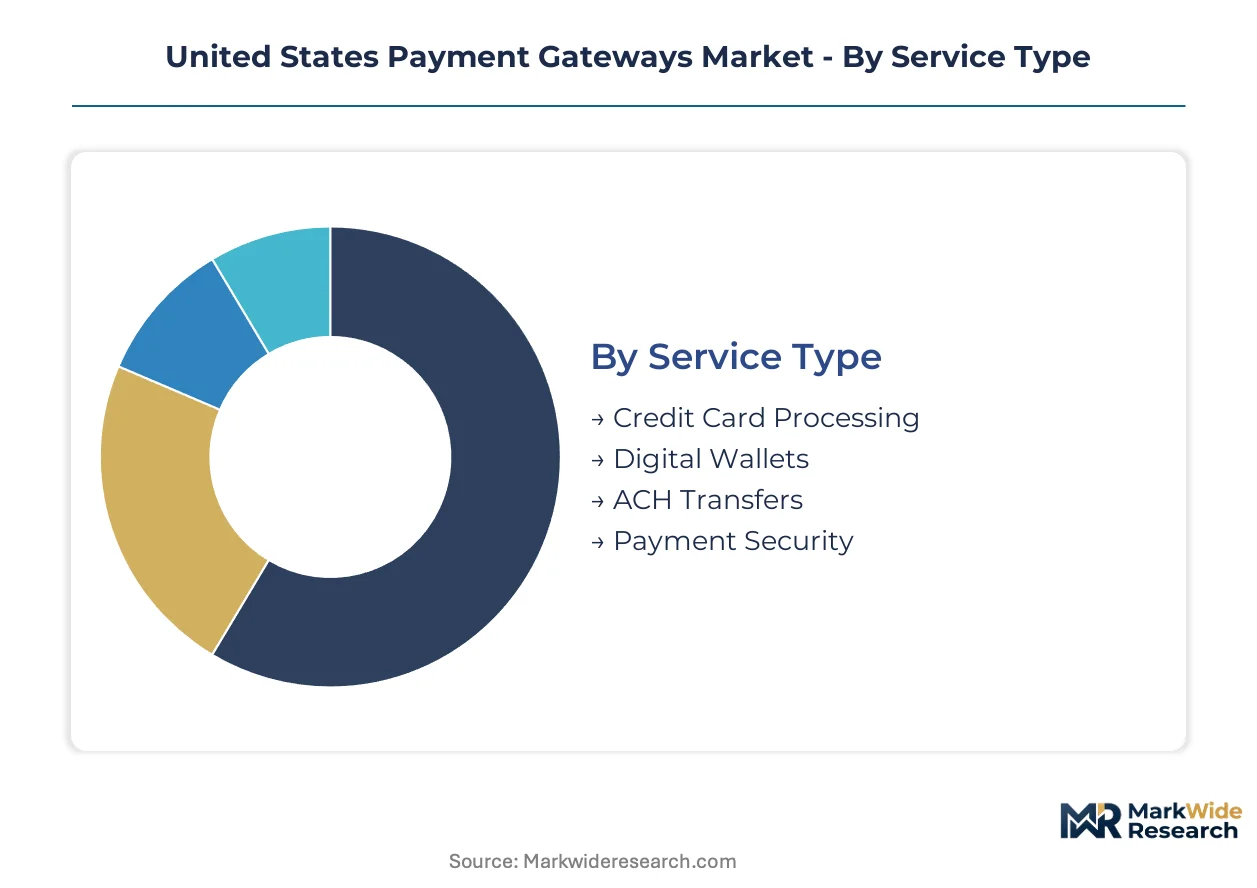
Payment gateway procurement patterns diverge sharply across merchant scale, transaction modality, and technical integration depth. Understanding these fault lines reveals where infrastructure investments concentrate and which provider architectures capture margin.
Service Type:
Merchant risk tolerance and settlement speed requirements determine service selection, with compliance liability shifting dramatically between options.
- Credit Card Processing:Dominant transaction rails for US commerce, routing encrypted card data through Visa, Mastercard, and American Express networks. Demand concentrates among omnichannel retailers in Texas and Florida seeking unified authorization across physical and digital storefronts. Interchange pass-through pricing compresses margins for high-volume merchants.
- Digital Wallets:Tokenized credential storage enabling one-click checkout through Apple Pay, Google Pay, and PayPal vaults. California software platforms embed these APIs to reduce cart abandonment in mobile commerce workflows. Consumer preference for biometric authentication accelerates merchant adoption.
- ACH Transfers:Bank-to-bank settlement through NACHA-operated networks, favored by B2B marketplaces and subscription billers for lower per-transaction costs than card rails.
- Payment Security:Tokenization, fraud scoring, and PCI DSS compliance-as-a-service layers that shift breach liability away from merchants.
Volume sits with Credit Card Processing; growth tilts toward Digital Wallets.
Technology:
Integration architecture separates merchants with in-house engineering capacity from those requiring managed solutions.
- API Integration:Direct code-level embedding of payment functions into merchant software stacks, demanding developer resources but enabling checkout customization. San Francisco SaaS platforms and New York fintechs leverage these tools to embed financial services natively. FedNow real-time settlement APIs are accelerating migration from batch-based integrations.
- Hosted Payment Pages:Provider-managed checkout interfaces that redirect customers away from merchant domains, eliminating PCI scope for small businesses. Agricultural cooperatives across the Great Plains and independent gas stations adopt these to avoid compliance infrastructure investment. Simplified fee structures from Illinois and Ohio providers drive switching behavior.
- Point of Sale:Terminal-integrated gateway stacks for in-person commerce, dominant among Main Street retailers seeking unified inventory and payment management.
- Mobile Payments:NFC-enabled and QR-code systems for smartphone-initiated transactions, expanding fastest among food service and delivery platforms.
Hosted Payment Pages capture the broadest merchant base; API Integration commands the steepest expansion trajectory.
End User:
Transaction velocity and customer acquisition economics reshape gateway requirements across verticals.
- E-commerce:Pure-play digital merchants requiring global currency support, fraud scoring, and subscription billing logic. Marketplace sellers operating across California, New York, and Texas fulfillment networks drive demand for multi-provider orchestration stacks. Dynamic transaction routing based on approval rates and cost optimizes authorization success.
- Retail:Brick-and-mortar and omnichannel merchants needing unified inventory, loyalty, and payment systems. Hardware-software integration from Square and similar providers dominates in-person commerce.
- Non-Profit:Donation processing with recurring giving capabilities and tax receipt automation, sensitive to interchange cost structures.
- Subscription Services:Recurring billing platforms requiring dunning management, card updater services, and churn reduction tools.
E-commerce anchors transaction volume growth; Subscription Services show the fastest platform specialization.
Customer Type:
Scale determines pricing leverage, technical sophistication, and willingness to manage compliance complexity.
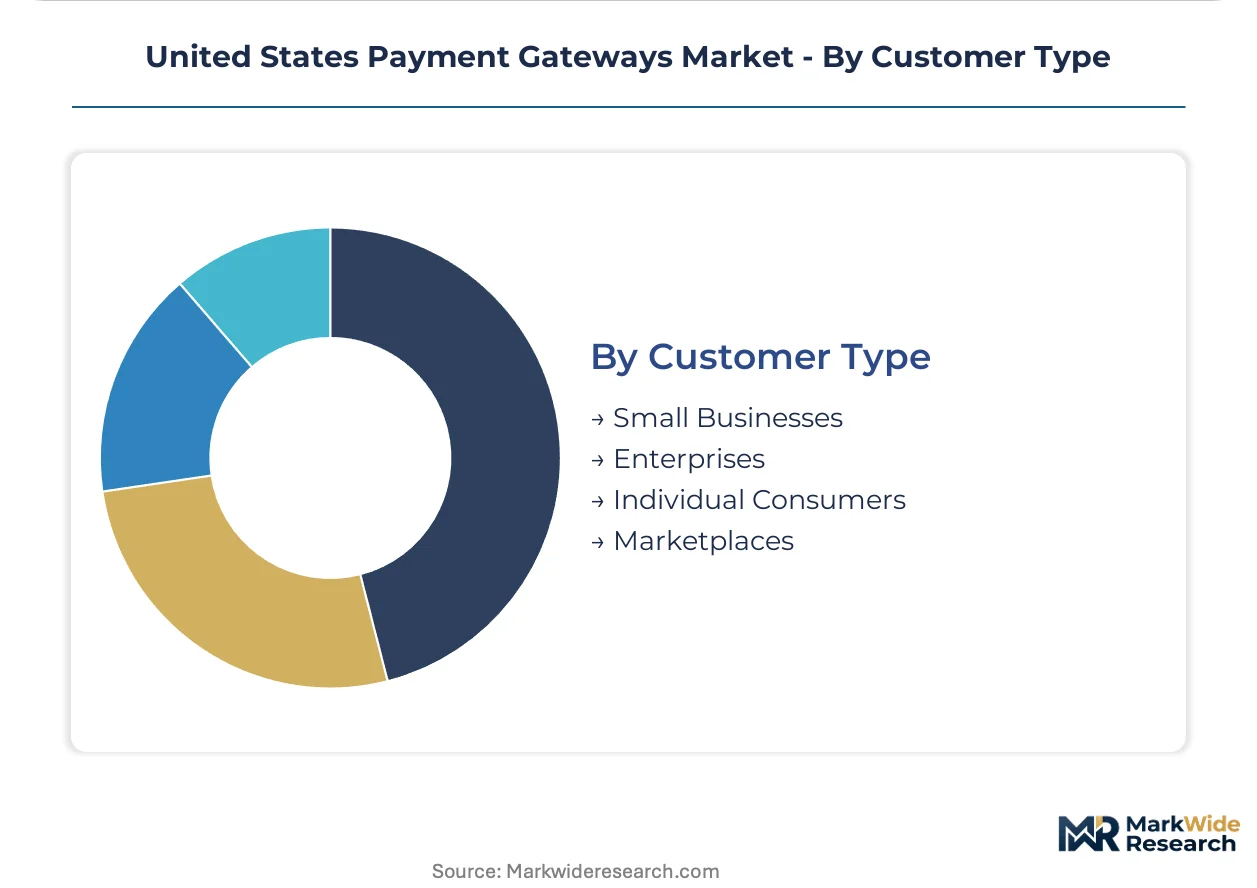
- Small Businesses:Price-sensitive merchants prioritizing simplicity and bundled hardware-software solutions over feature depth. Main Street retailers across the Midwest abandon legacy terminals for cloud gateways as PCI DSS mandates tighten. Residual split competition among ISOs creates provider churn.
- Enterprises:Large merchants with dedicated payments engineering teams negotiating custom interchange rates and demanding SLA guarantees. Multi-gateway orchestration for redundancy and cost optimization is standard practice.
- Individual Consumers:Peer-to-peer and sole proprietor payment acceptance, often through simplified mobile-first platforms.
- Marketplaces:Multi-party platforms requiring split payments, seller onboarding automation, and escrow functionality.
Enterprises drive per-merchant revenue; Small Businesses expand the addressable base most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for payment gateway infrastructure concentrates in coastal technology and financial services corridors, with regulatory mandates and merchant density driving procurement patterns across distinct sub-regional economies.
California
San Francisco and San Jose software platforms embed financial services natively into SaaS workflows, expanding API-first gateway adoption. The California Consumer Privacy Act shapes data handling requirements for payment processors serving technology clients. Los Angeles entertainment and gaming companies drive high-velocity transaction processing demand.
New York
Manhattan financial services firms and Brooklyn fintech startups require real-time settlement and institutional-grade compliance infrastructure. The New York Department of Financial Services enforces cybersecurity standards for payment service providers. The Hudson Valley corridor hosts expanding back-office operations for gateway providers.
Texas
Dallas-Fort Worth and Houston energy sector B2B marketplaces favor ACH transfers for large invoice settlements. The Texas Department of Banking regulates money transmission licenses for gateway operators. Austin's technology corridor attracts payment infrastructure engineering talent from coastal markets.
Florida
Miami's Latin American trade finance hub demands multi-currency gateway capabilities for cross-border commerce. The Florida Office of Financial Regulation oversees payment instrument seller licensing. Orlando tourism and hospitality merchants drive mobile payment terminal deployment.
Illinois
Chicago's commodity trading and agricultural cooperative sectors require specialized B2B payment orchestration. The Illinois Department of Financial and Professional Regulation enforces consumer protection standards for payment services. Peoria and Springfield agricultural processors adopt hosted payment pages to minimize compliance infrastructure costs.
United States Payment Gateways Market Key Industry Players
California-based technology platforms anchor one tier; New York and European financial specialists hold institutional and cross-border segments. The market structures around three distinct capability layers: developer-centric API infrastructure, integrated hardware-software systems, and bank-owned captive platforms. Strategic moves concentrate on embedded finance partnerships and real-time settlement architecture upgrades.
Within the developer-platform tier, Stripe, Inc. and Braintree exemplify API-first infrastructure providers serving software-embedded payments. Square occupies a position bridging in-person hardware and digital commerce for Main Street merchants. These companies represent archetypes of technical integration depth versus physical presence breadth.
| Leading Market Players |
|---|
| Stripe, Inc. |
| PayPal Holdings, Inc. |
| Adyen |
| Amazon Pay |
| Braintree |
| WePay, Inc. |
| Shopify Payments |
| Authorize.net |
| Square |
| Others |
Cost & Logistics Intelligence
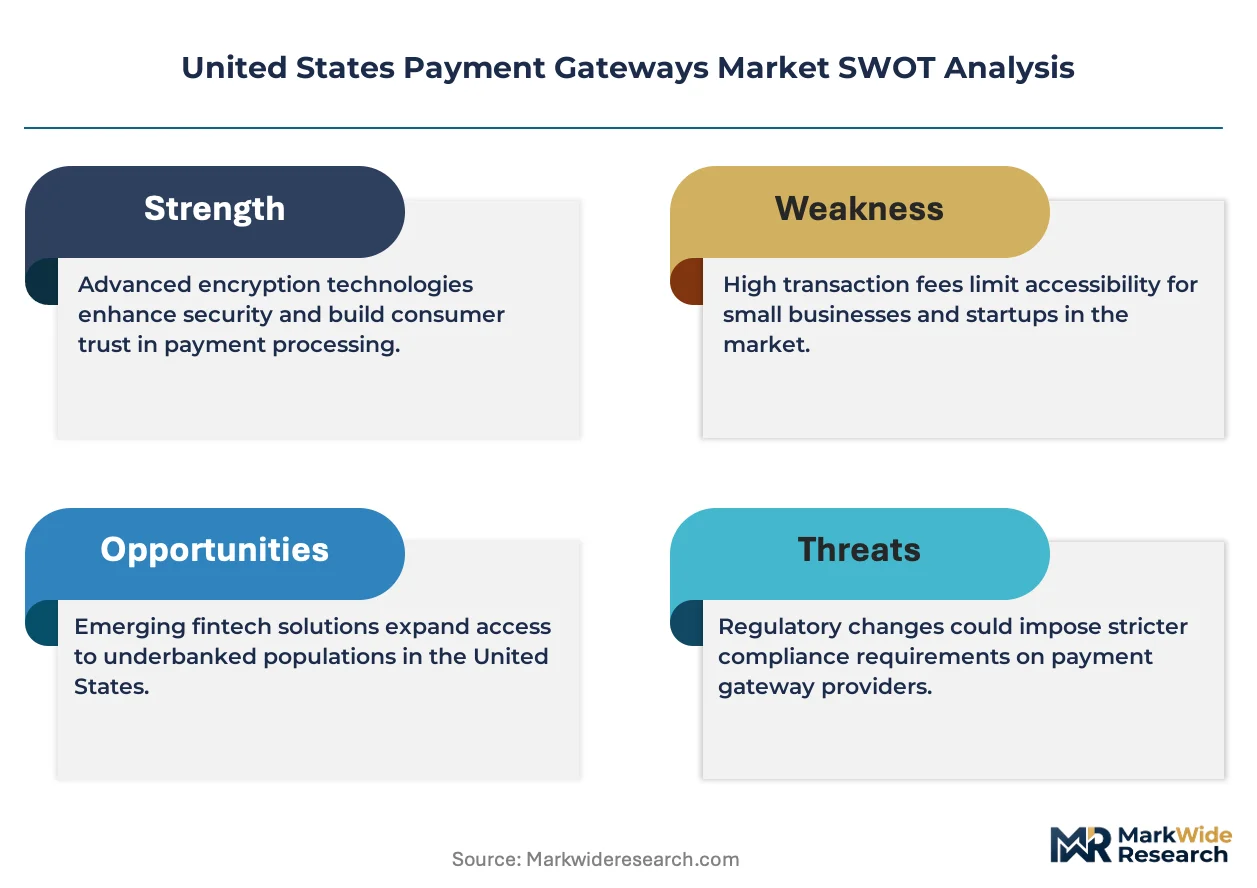
PCI DSS compliance certification gates both qualified supply and premium-tier pricing access, as merchants without tokenization infrastructure face liability premiums that cloud-native providers avoid. FedNow real-time settlement requirements further stratify the market, with instant-clearing capabilities commanding margin premiums over batch-based competitors.
Pricing Analysis
Volume sits with interchange pass-through models while margin concentrates in value-added services. Three-tier pricing structure across enterprise, mid-market, and small business levels differentiates by settlement speed and compliance bundling. Cost compression in the small business tier intensifies because ISO residual competition drives provider switching. Main Street retailers exhibit highest price sensitivity; enterprise merchants with dedicated payments engineering teams negotiate custom rates and demand SLA guarantees.
Supply Chain Analysis
Direct-to-merchant API channels handle hyperscale software platform demand, while ISO reseller networks serve price-sensitive rural segments. Engineering talent concentrates in California's technology corridor and New York's financial services cluster, with cryptographic expertise scarce in regional markets. Raw material dependencies include TLS certificate infrastructure, fraud scoring data feeds, and FedNow node connectivity. Single-source vulnerability in real-time settlement architecture poses structural risk as providers rebuild from batch systems. Distribution runs through cloud-hosted infrastructure with edge nodes in Texas and Illinois data centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Payment Gateways Market occupies a technology-transition phase, with FedNow real-time settlement APIs displacing legacy batch-based architectures that dominated the past decade.
For Market Incumbents: Acquire fraud-scoring data assets to defend against API-first entrants targeting enterprise orchestration stacks. Deepen FedNow node deployment in underpenetrated Midwest corridors to preempt regional bank-owned platform expansion. Certification investment in HIPAA-compliant healthcare infrastructure opens specialized verticals where compliance liability shifts favor incumbent scale. For New Entrants and Emerging Players: Capture agricultural cooperative payment modernization across the Great Plains, where hosted payment page simplicity outweighs feature depth for compliance-averse buyers. Target healthcare patient portal integration in Illinois and Ohio, where simplified fee structures drive switching from legacy ISO relationships. Partner with vertical SaaS platforms in Austin's technology corridor to embed checkout natively before incumbents consolidate embedded finance partnerships. For Investors and Strategic Acquirers: FedNow operational readiness certification delays among regional ISOs is the leading indicator that consolidation pressure will intensify for undercapitalized gateway providers. Target acquisition profiles center on API-first infrastructure with existing FedNow node connectivity and healthcare compliance certifications. Watch for ISO partner churn spikes as residual split competition erodes channel stability for legacy protocol-dependent platforms.| Strategic Initiative | Industry Significance |
|---|---|
| FedNow Node Deployment | Real-time settlement infrastructure captures merchant demand for sub-second fund availability in Texas and California corridors. |
| Healthcare Compliance Certification | HIPAA-aligned patient portal integration opens specialized B2B payment flows in Illinois commodity trading and agricultural sectors. |
| ISO Channel Consolidation | Acquiring reseller networks with legacy merchant relationships accelerates geographic footprint expansion in underpenetrated rural segments. |
| Embedded Finance Partnership | Vertical SaaS platform integration embeds lending and treasury functions through unified gateway stacks in San Francisco software ecosystems. |
| Tokenization Vault Expansion | Network-agnostic credential storage reduces PCI scope for large retailers in Florida and Texas seeking checkout customization. |
Research Approach
Multi-period observation of FedNow adoption timelines, PCI DSS certification rates, and ISO partner churn anchored the trend analysis, supplemented by interviews with payment engineering directors, gateway product managers, merchant acquiring executives, and healthcare IT procurement leads. Secondary validation drew from SEC filings of publicly traded payment processors, Federal Reserve operational readiness disclosures, NACHA rule change documentation, and Consumer Financial Protection Bureau enforcement actions. Bottom-up merchant adoption modeling triangulated against top-down infrastructure investment flows from cloud service providers.
Input-output matrix framing connected transaction volume projections to gateway infrastructure capacity requirements across the analysis window. Segmentation dimensions modeled include service type, integration technology, end-user vertical, and customer scale tier. CAGRs derived from trend extrapolation of merchant abandonment rates for legacy terminals and real-time settlement API adoption curves. Forecast inputs incorporated FedNow node deployment schedules and PCI DSS 4.0 compliance transition timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to interchange fee regulatory action, bank-owned platform competitive response, and cybersecurity talent concentration shifts. Forecasts reflect assumptions about merchant technology refresh cycles and real-time payment infrastructure buildout pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Bulgaria POS Terminals Market
Payments
UAE Card Payments Market
Payments
Argentina Mobile Wallet Market
Payments
Cryptocurrency Payment Apps Market
Payments
United Kingdom Real Time Payments Market
Payments
Remote Deposit Capture Market
Payments
Saudi Arabia Cash Management Services Market
Payments
United Kingdom Payment Gateway Market
Payments
Global Digital Wallets Market
Payments
Transaction Monitoring Market
Payments
Poland Payments Market
Payments
Recurring Payments Market
Payments
Israel Credit Cards Market
Payments
Finland Payments Market
Payments
North America Payments Market
Payments
Spain Payment Gateway Market