
 Italy Payments Market | 2026-2036
Italy Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Payments Market Foresight
Italian merchant acquirers is rebalancing around contactless infrastructure and real-time rails. Nexi S.p.A. leverages its domestic processing network to anchor merchant relationships across retail chains. Intesa Sanpaolo S.p.A. sustains dual strength in corporate banking and consumer payment apps. Satispay differentiates through social payment features and zero-fee positioning for small merchants.
Payments encompass the transfer of monetary value between parties through instruments including cards, mobile devices, digital wallets, and bank transfers, governed by protocols such as EMV chip authentication, tokenization standards, and ISO 20022 messaging for interoperability. The system enables commercial exchange, treasury management, and consumer purchasing across physical and digital environments. Card payments occupy the largest transaction volume pool, reflecting entrenched POS infrastructure and consumer habit. Mobile payments represent the fastest-expanding segment, driven by smartphone penetration and QR code integration at merchant terminals. Blockchain-based settlement services remain nascent, constrained by regulatory uncertainty and throughput limitations relative to conventional rails.
Bank of Italy supervises payment system stability and enforces anti-money laundering compliance across financial institutions. PSD2 and the EU Digital Operational Resilience Act shape technical standards for authentication interfaces and operational continuity. Italy's national cybersecurity agency coordinates incident response protocols for critical payment infrastructure. Stakeholders must weigh interoperability investments against the fragmentation risk from diverging national instant payment implementations across Europe.
Market Dynamics
SEPA Instant Credit Transfer infrastructure is compressing settlement windows across Italian retail banking, forcing merchant acquirers to rebuild core processing stacks around real-time rails rather than batch-based legacy systems.
Growth Catalysts
- PSD2 Strong Customer Authentication:The European mandate for two-factor verification is expanding qualified digital wallet usage among Italian e-commerce merchants, creating compliant transaction volumes for licensed payment service providers.
- Contactless POS terminalization:Retail chains in Milan and Rome are replacing magnetic stripe hardware with NFC-enabled devices, accelerating tap-to-pay adoption rates among habitual card users.
- Smartphone penetration saturation:Italy's mobile device density is enabling QR code payment integration at small merchant terminals, particularly in food service and urban transit corridors.
Market Restraints
- Interchange fee compression:EU regulatory caps on card transaction fees are squeezing acquirer margins, forcing revenue model shifts toward value-added merchant services.
- Core banking system fragility:Many Italian regional banks operate on decades-old COBOL-based payment engines, creating technical debt that obstructs API-first open banking integration.
- Cash transaction persistence:Italy's cultural attachment to physical currency, particularly among aging demographics in southern regions, limits digital payment penetration in high-frequency low-value retail.
Strategic Opportunities
- Sicily and Calabria merchant digitization:Underpenetrated southern Italian provinces present whitespace for mobile-first acquirers to capture small business relationships before incumbent branch networks consolidate.
- Request-to-Pay messaging convergence:The integration of ISO 20022 messaging with instant payment rails is enabling invoice-linked payment initiation for B2B treasury workflows.
- EU Digital Operational Resilience Act compliance services:Third-party risk management mandates are creating advisory and technical implementation revenue streams for payment infrastructure consultancies.
Industry Challenges
- ISO 20022 migration complexity:Italian banks face multi-year core system overhauls to replace MT messaging formats, requiring scarce specialized integration talent and parallel operational continuity.
- Anti-money laundering surveillance costs:Bank of Italy enforcement of enhanced due diligence protocols is elevating compliance operational expenditure for transaction monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Payments Market |
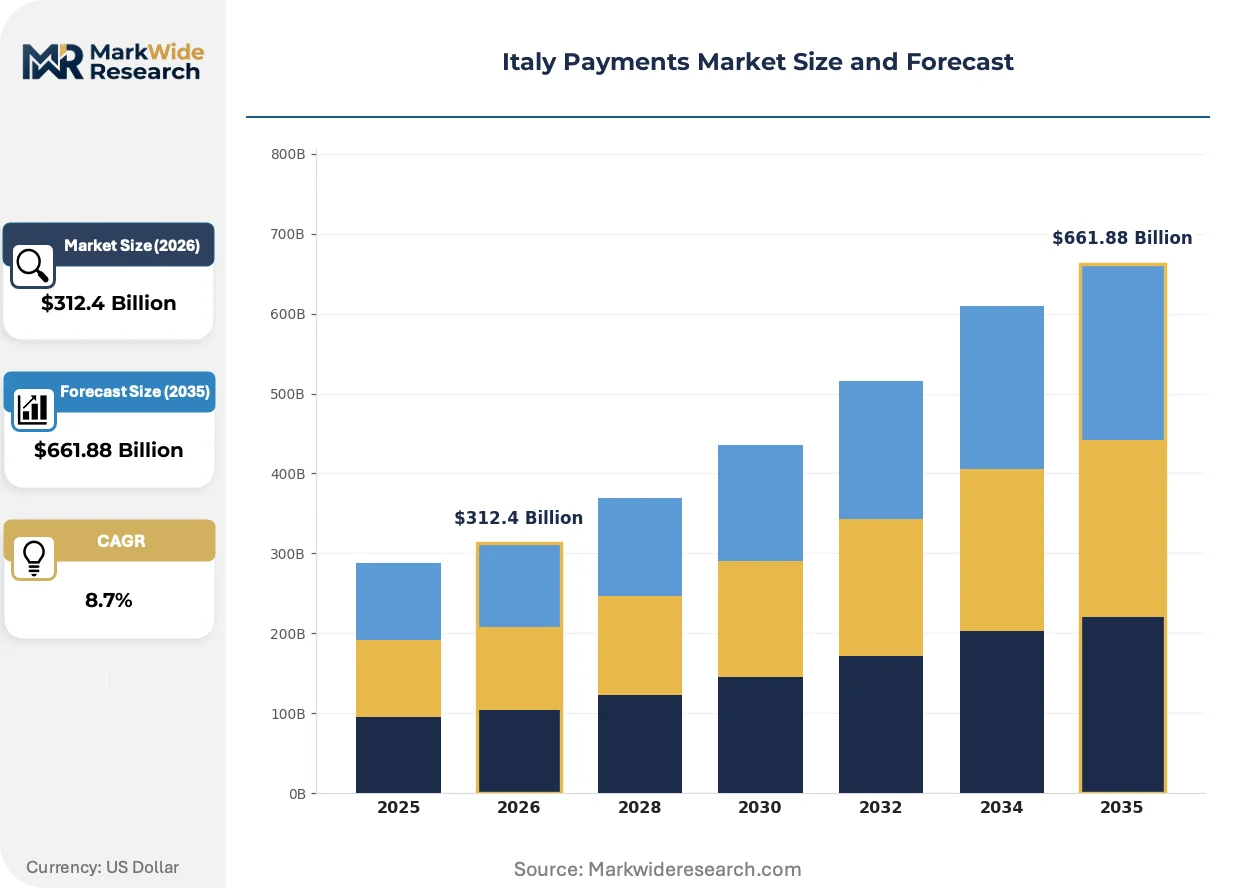
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $661.88 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transaction Type: Card Payments, Mobile Payments, E-Wallets, Bank Transfers Service Type: Payment Processing, Fraud Detection, Gateway Services, Settlement Services End User: Retailers, E-commerce Platforms, Financial Institutions, Payment Service Providers Technology: Contactless Payment, NFC, QR Code, Blockchain |
| Companies Covered | Nexi S.p.A., Intesa Sanpaolo S.p.A., UniCredit S.p.A., Worldline S.A., PayPal Holdings, Inc., Visa Inc., Mastercard Incorporated, Satispay, Bancomat S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Payments Market Shifts & Advancements
Distributed ledger experimentation is intersecting with instant payment infrastructure, creating hybrid settlement architectures that challenge conventional correspondent banking relationships across Italian wholesale markets.
Blockchain-based settlement protocols are decentralizing correspondent banking dependencies for cross-border remittance corridors. Italian money transfer operators serving Albanian and Moroccan diaspora communities are piloting stablecoin bridges to bypass SWIFT latency. The structural consequence is compressing intermediary fee stacks while introducing new custody and regulatory reporting obligations for non-bank payment institutions.
PSD3 negotiations within the European Commission are tightening open banking access rules and liability frameworks for account information service providers. Italian retail banks must expand API gateway investment to maintain compliant data sharing with third-party fintech aggregators. The merchant acquiring segment faces heightened authentication cost pass-through as strong customer authentication exemptions narrow.
Subscription billing models are displacing traditional invoice-based B2B payment cycles among Italian SaaS and logistics software providers. Finance teams at mid-market manufacturing firms are adopting virtual card programs for recurring vendor spend, compressing accounts payable processing overhead. The shift is most visible in Emilia-Romagna's industrial automation cluster, where treasury digitization lags northern European peers.
Italy Payments Market Segmentation
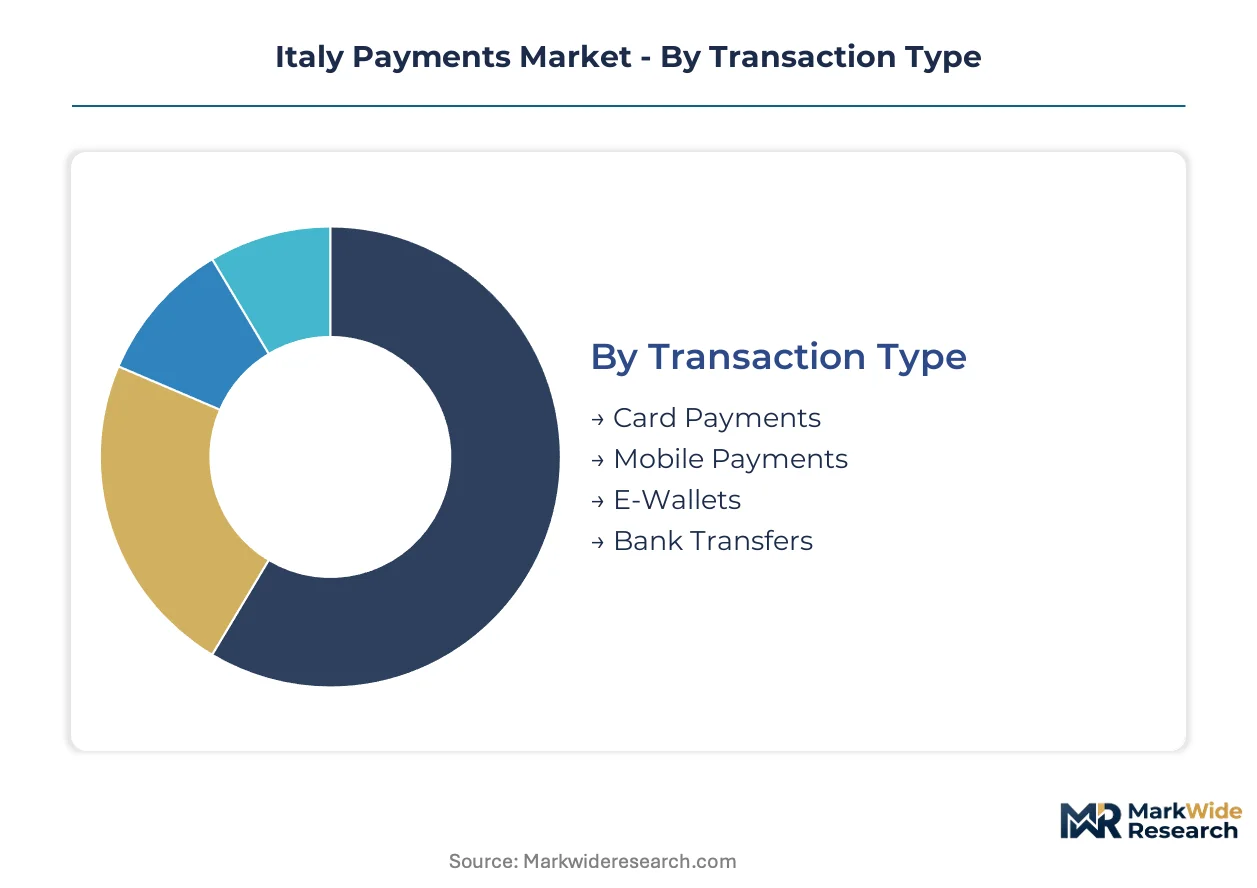
Italian payment flows fragment across four distinct classification axes, each revealing divergent margin structures and infrastructure requirements. Transaction type and service type splits expose where acquirers capture value versus where commoditization pressures concentrate.
Transaction Type:
Card payments dominate transaction volume while mobile and wallet solutions command premium per-transaction economics through lower interchange exposure.
- Card Payments:EMV chip and contactless card rails process the majority of Italian retail transaction value. Demand concentrates among supermarket chains and fuel stations in Milan and Turin, where NFC terminalization has displaced magnetic stripe infrastructure.
- Mobile Payments:Smartphone-native transaction initiation through banking apps and device wallets. Growth concentrates in Rome's food service corridor and urban transit networks, driven by QR code integration at small merchant terminals.
- E-Wallets:Stored-value accounts enabling closed-loop merchant and transit payments. Italian transit authorities in Naples and Florence have deployed proprietary wallet systems for fare collection.
- Bank Transfers:Direct account-to-account settlement through SEPA Instant Credit Transfer rails. Corporate treasury teams at Emilia-Romagna manufacturing firms are adopting request-to-pay messaging for supplier payments.
Mature deployment sits with card payments. Newer deployment is concentrated in mobile payments.
Service Type:
Revenue pools separate between high-volume processing commoditization and value-added services capturing fraud and treasury workflow premiums.
- Payment Processing:Authorization, clearing, and settlement orchestration across card networks and instant payment rails. Italian merchant acquirers compete on transaction throughput guarantees for retail chains.
- Fraud Detection:Real-time transaction scoring and behavioral analytics. Demand from e-commerce platforms in Lombardy has accelerated following PSD2 strong authentication mandates.
- Gateway Services:API middleware connecting merchant platforms to multiple acquiring endpoints. SaaS providers in Rome's logistics software cluster require multi-rail gateway redundancy.
- Settlement Services:End-of-day net position reconciliation and liquidity management. Regional banks across Sicily and Calabria rely on third-party settlement utilities due to core system limitations.
Processing volume concentrates with established retail acquirers. Fraud detection is climbing the fastest among service categories.
End User:
Customer scale and technical sophistication determine service bundling depth and pricing power distribution across the value chain.
- Retailers:Physical merchant locations requiring POS integration and reconciliation reporting. Fashion retail chains in Milan demand omnichannel payment orchestration across storefront and digital channels.
- E-commerce Platforms:Digital-native merchants prioritizing checkout conversion and international card acceptance. Marketplace operators in Rome compete on payment method breadth for cross-border sales.
- Financial Institutions:Banks and payment service providers requiring white-label processing infrastructure. Regional Italian banks seek hosted card issuing platforms to avoid core system replacement costs.
- Payment Service Providers:Licensed fintechs aggregating merchant relationships under AISP/PISP licenses. Satispay and similar entrants target small merchant segments with simplified onboarding.
Established relationships sit with retailers. E-commerce platforms are gaining share fastest as merchant digitization accelerates.
Technology:
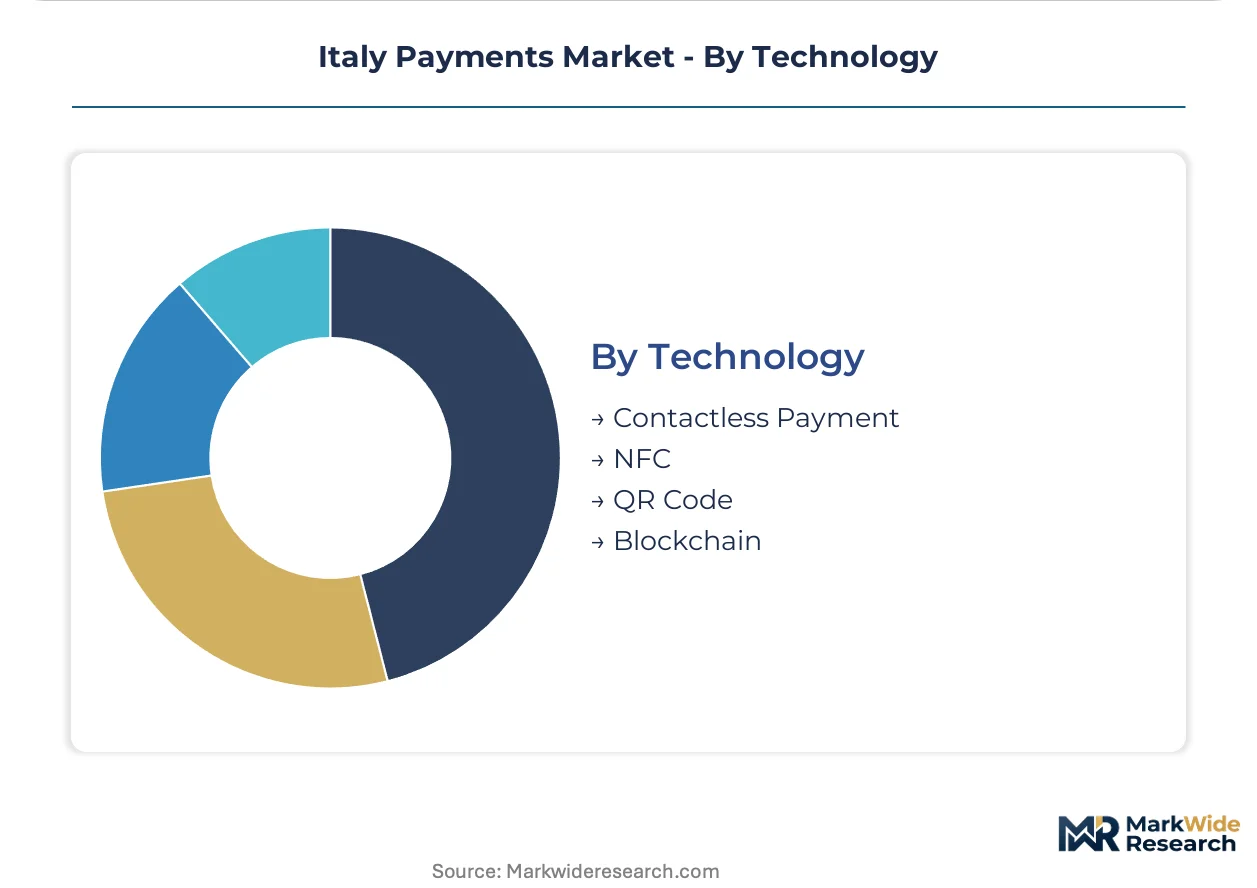
Hardware deployment cycles and software integration complexity create divergent capital intensity requirements across technology categories.
- Contactless Payment:NFC-enabled card and device tap-to-pay protocols. Italian fuel retailers and quick-service restaurants have completed terminal upgrades to support contactless limits.
- NFC:Near-field communication hardware enabling proximity data exchange. Transit operators in Turin and Bologna have deployed NFC validators for fare gate entry.
- QR Code:Optical scanning for payment initiation and merchant identification. Small merchants in southern Italian provinces adopt QR solutions to avoid terminal hardware costs.
- Blockchain:Distributed ledger protocols for settlement and remittance corridors. Money transfer operators serving Albanian diaspora communities pilot stablecoin bridges for cross-border value movement.
Contactless deployment is mature across northern retail corridors. QR code adoption is expanding most quickly among underbanked merchant segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lombardy's financial infrastructure anchors Italian payment processing capacity. The region's dense merchant ecosystem and proximity to European clearing hubs concentrate transaction volume and technical talent.
Lombardy
Milan's fashion retail chains and corporate headquarters drive omnichannel payment orchestration demand. Bank of Italy supervises real-time settlement stability across the region's banking concentration. The Porta Nuova business district hosts merchant acquirer technology centers processing northern Italy's card transaction volume.
Lazio
Rome's e-commerce platforms and government procurement systems require compliant digital payment rails. PSD2 strong customer authentication mandates shape technical investment priorities for local payment service providers. The EUR district clusters fintech development labs serving public sector payment modernization.
Emilia-Romagna
Industrial automation firms and logistics software providers in Bologna and Modena adopt virtual card programs for supplier payments. SEPA Instant Credit Transfer infrastructure enables treasury digitization for manufacturing supply chains. The Motor Valley automotive cluster pilots request-to-pay messaging for B2B parts procurement.
Veneto
Tourism-dependent merchants in Venice and Verona prioritize contactless terminal deployment for international visitor transactions. EU interchange fee caps compress acquirer margins across the region's hospitality sector. The Treviso footwear manufacturing belt experiments with blockchain-based cross-border settlement for export receivables.
Sicily
Small merchants in Palermo and Catania adopt QR code solutions to avoid hardware acquisition costs. Underpenetrated southern provinces present whitespace for mobile-first acquirers before incumbent branch networks consolidate. Regional banks rely on third-party settlement utilities due to core system technical debt.
Italy Payments Market Competitive Landscape
Global majors compete with regional champions across merchant acquiring and processing infrastructure. The market structure concentrates around domestic banking networks with international card scheme partnerships, creating tiered competition between scale-driven processors and specialized fintech entrants. Three archetypes dominate: incumbent banking conglomerates with captive merchant bases, independent payment processors leveraging domestic infrastructure, and mobile-first challengers targeting underserved small merchant segments. Competitive moves center on contactless terminal deployment acceleration and real-time payment rail integration.
Among Italy-based financial institutions, Nexi S.p.A., Intesa Sanpaolo S.p.A., and Satispay exemplify divergent strategic positioning within this structure. Nexi S.p.A. occupies a position as a domestic processing specialist with merchant relationship depth across retail chains. Intesa Sanpaolo S.p.A. represents the integrated banking conglomerate archetype combining corporate banking strength with consumer payment application distribution. Satispay anchors the challenger tier through social payment feature differentiation and zero-fee positioning for small merchant acquisition.
| Leading Market Players |
|---|
| Nexi S.p.A. |
| Intesa Sanpaolo S.p.A. |
| UniCredit S.p.A. |
| Worldline S.A. |
| PayPal Holdings, Inc. |
| Visa Inc. |
| Mastercard Incorporated |
| Satispay |
| Bancomat S.p.A. |
| Others |
Supply & Pricing Matrix
SEPA Instant Credit Transfer infrastructure pricing benchmarks cascade through Italian payment networks, compressing settlement service margins for regional banks while concentrating premium pricing power among real-time rail operators serving Milan's merchant acquirers.
Pricing Analysis
Service-bundling configurations separate hardware-inclusive terminal leases from unbundled software-only gateway contracts. Three-tier pricing structure across premium, standard, and economy levels reflects authentication complexity, fraud guarantee coverage, and settlement speed guarantees. Pricing pressure stems from EU interchange fee caps squeezing acquirer margins and forcing unbundling of value-added services. Small merchants in southern provinces exhibit highest price sensitivity, while corporate treasury clients in Emilia-Romagna prioritize workflow integration over unit cost.
Supply Chain Analysis
Warehouse-distribution layer concentration across Milan and Rome hubs feeds into hub-and-spoke patterns serving regional banking nodes. Hardware manufacturing draws from China, Taiwan, and Vietnam for POS terminal components. Software development centers on Ireland, Poland, and domestic Italian engineering clusters. Supply chain risk centers on single-source vulnerability for EMV chip modules from constrained semiconductor foundries. Distribution runs through licensed payment service providers maintaining direct merchant relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian payment infrastructure sits in a technology-transition phase as SEPA Instant Credit Transfer rails displace batch-based legacy settlement systems. Real-time processing stacks are replacing decades-old COBOL engines.
For Market Incumbents: Anticipate core banking system replacement cycles accelerating as Bank of Italy enforces Digital Operational Resilience Act compliance deadlines. Defensive consolidation through API gateway acquisition preserves merchant relationships against fintech disintermediation. Threat from Satispay and mobile-first challengers demands authentication cost pass-through capabilities. Leverage vertical integration into settlement utilities for regional bank outsourcing contracts.
For New Entrants and Emerging Players: Capture whitespace in Sicily and Calabria merchant digitization before incumbent branch networks consolidate relationships. Most penetrable segment: small food service operators in Palermo and Catania seeking zero-fee QR code acceptance. Go-to-market angle: social payment feature differentiation mirroring Satispay's community transfer capabilities.
For Investors and Strategic Acquirers: Distressed-cycle entries favor payment infrastructure consultancies in Lombardy with EU Digital Operational Resilience Act compliance expertise. Long-term viability favors processors with real-time rail integration depth over batch-legacy dependent regional acquirers. Signal to watch: ISO 20022 migration completion rates as inflection indicator for technical debt resolution.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Rail Integration | SEPA Instant Credit Transfer adoption locks in merchant treasury relationships against fintech disruption. |
| API Gateway Expansion | Open banking connectivity preserves data-sharing revenue under tightening PSD3 liability frameworks. |
| Contactless Terminal Deployment | NFC hardware saturation in Milan retail corridors defends market share against mobile-wallet substitution. |
| ISO 20022 Migration Completion | Messaging standardization enables request-to-pay B2B workflows for Emilia-Romagna manufacturing clients. |
| Fraud Detection Service Unbundling | PSD2 strong authentication mandates create standalone revenue streams from e-commerce platform demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Italy Payments Market analysis. Primary interviews with merchant acquirer technology officers, Bank of Italy supervisory staff, payment service provider product managers, and regional bank operations directors combined with secondary validation from SEPA implementation reports, EU Commission PSD2 compliance databases, and Italian banking association statistics. Bottom-up transaction volume modeling and top-down macroeconomic triangulation ensured cross-verification.
Data-stream reconciliation across authorization volume, settlement value, and terminal deployment metrics shaped the analytical framework. Segmentation dimensions modeled include transaction type, service type, end user category, and technology protocol across the projection horizon. CAGRs were derived from trend extrapolation of real-time rail adoption curves and contactless terminal replacement cycles. Forecast inputs incorporated SEPA Instant Credit Transfer infrastructure rollout timelines and PSD3 negotiation progress indicators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory implementation delays and core banking system replacement pace. Forecasts reflect documented assumptions on interchange fee stability and instant payment adoption elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Singapore Gift Card and Incentive Card Market
Payments
Payment Security Market
Payments
Bitcoin Payments Market
Payments
Middle East and Africa Real Time Payments Market
Payments
North America Mobile Payments Market
Payments
Latin America Subscription and Billing Management Market
Payments
Mobile Payment Data Protection Market
Payments
Europe Gift Card and Incentive Card Market
Payments
Global Payments Market
Payments
Saudi Arabia Payment Gateway Market
Payments
Global Prepaid Cards Market
Payments
Japan POS Terminals Market
Payments
Japan Credit Cards Market
Payments
United Kingdom Payment Gateway Market
Payments
Australia Mobile Payment Market
Payments
Greece POS Terminals Market