
 Italy Gift Cards Market | 2026-2036
Italy Gift Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Gift Cards Market Insights
Market Context
PSD2 is rebalancing the cost-of-entry calculus for new digital gift card entrants in Italy by mandating strong customer authentication for electronic payment instruments. Amazon.com leverages its pan-European fulfillment backbone to sustain low-friction digital card delivery across the peninsula. Esselunga anchors premium physical card placement through controlled supermarket distribution in affluent northern provinces.
Technical Definition and Segment Structure
Italy gift cards are prepaid stored-value instruments, typically encoded with magnetic stripes, chip interfaces, or tokenized digital credentials, that transfer purchasing power from giver to recipient within closed-loop retailer networks or open-loop payment schemes. Their primary commercial purpose is to lock in future consumer spending, capture float revenue, and generate zero-liability customer acquisition for issuing merchants. Digital cards and e-gift cards now lead product type expansion as PSD2-compliant instant issuance displaces physical inventory costs, while mobile gift cards represent the fastest-growing activation channel as NFC-enabled smartphones penetrate Italian youth demographics. Physical cards retain margin concentration in seasonal holiday use cases where tactile presentation sustains premium pricing.
Regulatory Framework
Banca d'Italia and the European Banking Authority jointly govern e-money issuance thresholds and anti-money laundering reporting for open-loop gift instruments circulating above defined value limits. Italy's data protection regulator applies GDPR strictures to loyalty-linked card programs, forcing issuers to segment customer databases by consent status. Stakeholders must monitor whether forthcoming EU digital euro pilots absorb gift card float into central bank liabilities.
Market Dynamics
PSD2 mandates on strong customer authentication are compressing the operational runway for new digital gift card entrants while advantaging incumbent issuers with established compliance infrastructure. Banca d'Italia's e-money thresholds and the European Banking Authority's anti-money laundering protocols now function as gatekeepers to market participation.
Growth Catalysts
- Corporate incentive programs:Northern Italian industrial zones are driving bulk procurement volumes as manufacturers deploy gift cards for employee recognition and channel partner rewards.
- PSD2 compliance framework:Tighter authentication protocols for e-gift card issuers are accelerating consolidation around established digital payment platforms with pre-built regulatory infrastructure.
- NFC-enabled smartphone penetration:Italian youth demographics are activating mobile gift cards at accelerating velocity, displacing physical card circulation in urban centers.
Market Restraints
- Float revenue compression risk:Forthcoming EU digital euro pilots threaten to absorb gift card float into central bank liabilities, eroding a core profit mechanism for open-loop issuers.
- GDPR database segmentation costs:Italy's data protection regulator forces loyalty-linked card programs to maintain parallel customer databases by consent status, inflating operational overhead.
- Physical inventory carry costs:Seasonal holiday demand for tactile gift card presentation requires premium stockpiling in Q4, locking working capital in depreciating plastic inventory.
Strategic Opportunities
- Lombardy density exploitation:Milan's concentrated retail and banking infrastructure supports high-frequency card circulation models that can replicate across Turin and Bologna corridors.
- Instant issuance technology:PSD2-compliant digital credential delivery is eliminating physical distribution bottlenecks while capturing margin from last-minute gift purchases.
- Supermarket channel premium placement:Controlled distribution through affluent northern province retail networks enables closed-loop issuer margin defense against open-loop payment schemes.
Industry Challenges
- Authentication engineering talent scarcity:PSD2 strong customer authentication requirements demand specialized fintech engineering capabilities that outpace Italian technical education pipeline output.
- Legacy magnetic stripe infrastructure:Retail POS terminal upgrade cycles lag behind chip and tokenized credential standards, fragmenting acceptance networks and complicating issuer technical roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Gift Cards Market |
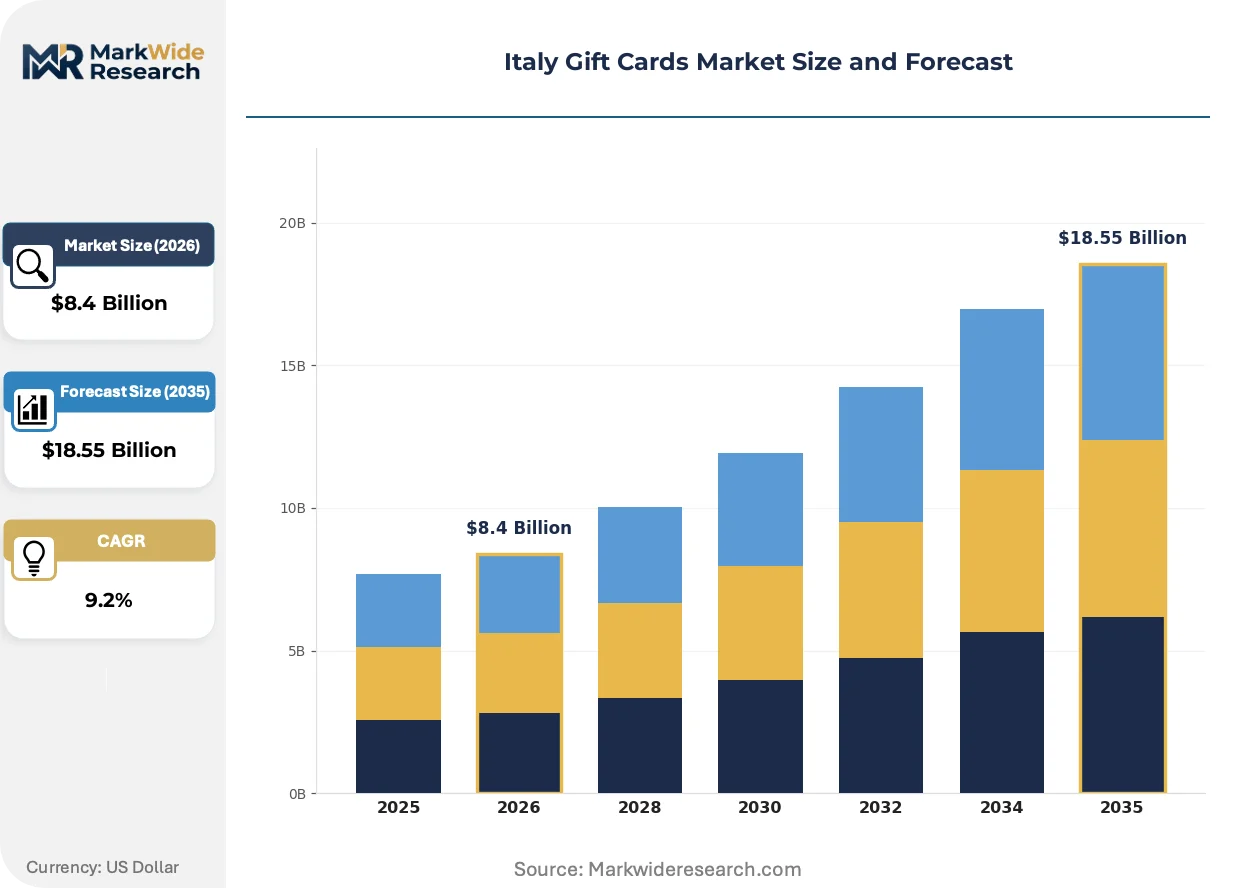
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Cards, Digital Cards, e-Gift Cards, Mobile Gift Cards End User: Retail Customers, Corporate Clients, Students, Online Shoppers Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Restaurants Use Case: Birthday Gifts, Holiday Gifts, Promotional Offers, Employee Rewards |
| Companies Covered | Amazon.com, Apple Inc., Conad, Esselunga, Carrefour Group, Coop Italia, Epipoli Group, Nexi Payments, PostePay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Gift Cards Market Trends and Innovations
Tokenized digital credential architectures are compressing issuance-to-redemption latency while NFC activation protocols are shifting consumer preference toward mobile-first gift card experiences. These converging technical trajectories are restructuring competitive advantage around real-time payment infrastructure ownership.
Tokenized digital gift cards encode prepaid value as cryptographically secured credentials rather than static magnetic stripe data. Major Italian retail chains are migrating issuance to these formats to eliminate physical production and distribution costs. This migration is electrifying closed-loop issuer margins by collapsing working capital cycles from weeks to seconds.
GDPR strictures on loyalty-linked card programs are forcing database architecture rewrites across Italian issuers. Banca d'Italia coordinates with the European Banking Authority to enforce anti-money laundering reporting thresholds that capture high-value open-loop circulation. Premium physical card programs in seasonal use cases face the steepest compliance cost inflation as they straddle both regulatory regimes.
Corporate procurement departments are consolidating vendor relationships around single-platform gift card solutions that integrate expense management and tax reporting. Traditional retail distribution through supermarket end-caps is ceding volume to direct API integration with enterprise HR systems. This behavioral pivot concentrates most visibly in Lombardy's manufacturing belt where multinational employers standardize incentive programs across Italian operations.
Italy Gift Cards Market Segmentation
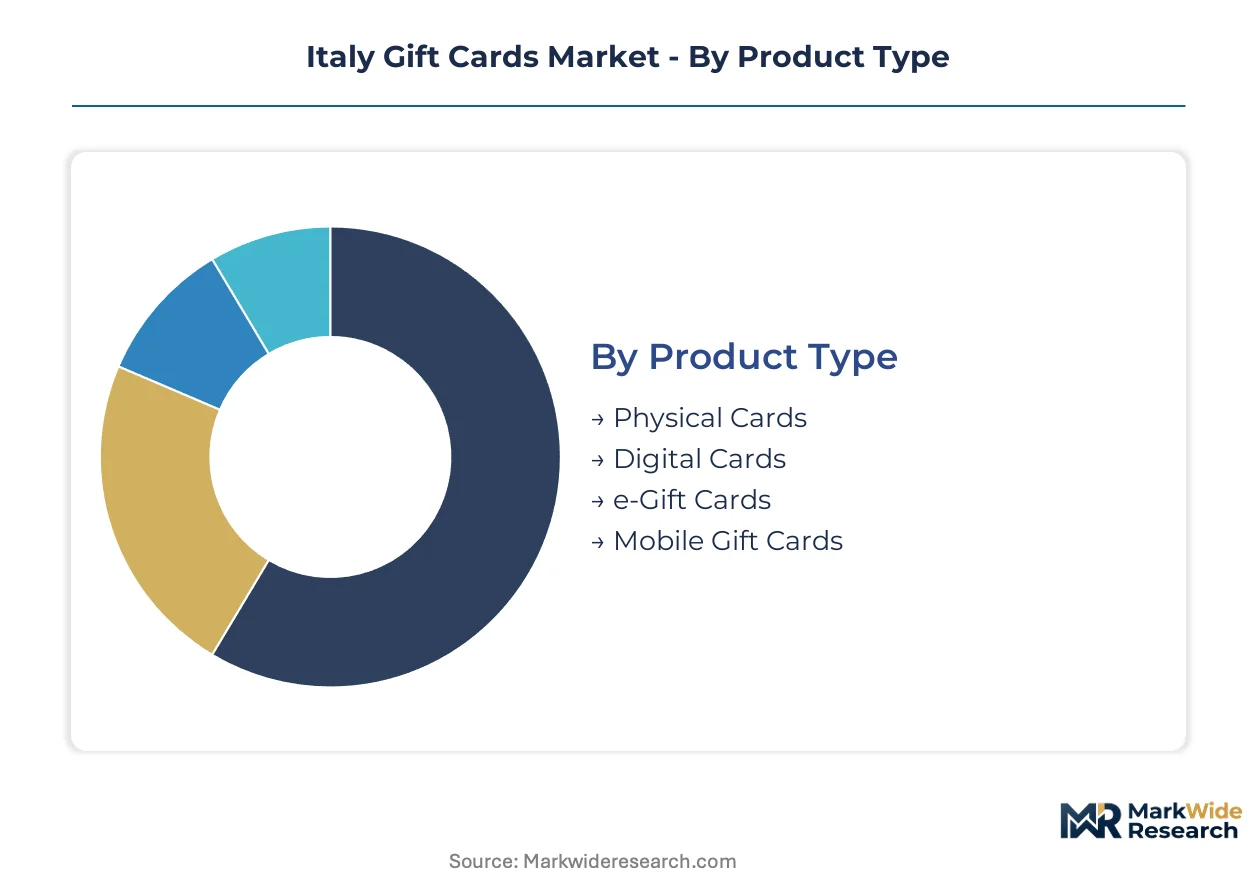
Gift card segmentation in Italy reflects divergent buyer priorities across consumer gifting, corporate procurement, and loyalty program deployment. Technical format choices, distribution channel access, and regulatory compliance requirements reshape competitive positioning within each category.
Product Type:
Buyer-decision drivers center on issuance speed, authentication burden, and presentation context for the intended recipient.
- Physical Cards:Magnetic stripe or chip-encoded plastic instruments dominate seasonal holiday exchanges where tactile unboxing sustains premium pricing. Lombardy's dense retail infrastructure supports high-frequency supermarket and specialty store placement, though Q4 inventory carry costs compress margins for issuers.
- Digital Cards:Tokenized credentials delivered via email or web portals eliminate physical production and distribution overhead. Corporate procurement departments in northern industrial zones favor instant issuance for employee recognition programs, bypassing postal latency and enabling precise delivery timing.
- e-Gift Cards:Browser-based redemption links with PSD2-compliant strong authentication protocols. Italian youth demographics in Milan and Turin urban centers activate these for last-minute purchases.
- Mobile Gift Cards:NFC-enabled smartphone credentials represent the steepest expansion trajectory as contactless POS penetration accelerates across Italian retail.
Physical cards lead on scale; mobile gift cards lead on momentum.
End User:
Procurement volume and margin structure diverge sharply between individual discretionary purchases and institutional bulk contracts.
- Retail Customers:Individual purchasers selecting cards for personal gifting occasions. Demand concentrates in affluent northern provinces during December holiday windows.
- Corporate Clients:Manufacturers and service firms deploying cards for channel partner incentives and employee rewards. Bulk procurement volumes from Lombardy and Emilia-Romagna industrial belts sustain issuer float revenue.
- Students:University-aged recipients activating digital credentials for campus-adjacent retail and food service. Budget constraints favor lower-denomination closed-loop instruments.
- Online Shoppers:E-commerce platform users redeeming cards for home delivery purchases. Amazon.com's pan-European fulfillment backbone captures disproportionate volume.
Corporate clients anchor revenue concentration; online shoppers are climbing the fastest.
Distribution Channel:
Channel selection determines authentication infrastructure requirements and working capital intensity for issuers.
- Online Retailers:Direct-to-consumer digital delivery platforms with API-integrated issuance systems. Esselunga and similar retail chains leverage proprietary e-commerce portals to bypass third-party commission structures.
- Supermarkets:Controlled end-cap placement in affluent northern province locations enables premium physical card positioning. Seasonal stockpiling demands compress issuer liquidity during Q3.
- Specialty Stores:Narrow-assortment retailers focusing on experiential or luxury gift card categories. Higher per-transaction values offset lower foot traffic.
- Restaurants:Hospitality-sector closed-loop instruments for dining experiences. Recovery of Italian food service post-pandemic is expanding redemption velocity.
Supermarkets dominate transaction frequency; online retailers are gaining share fastest.
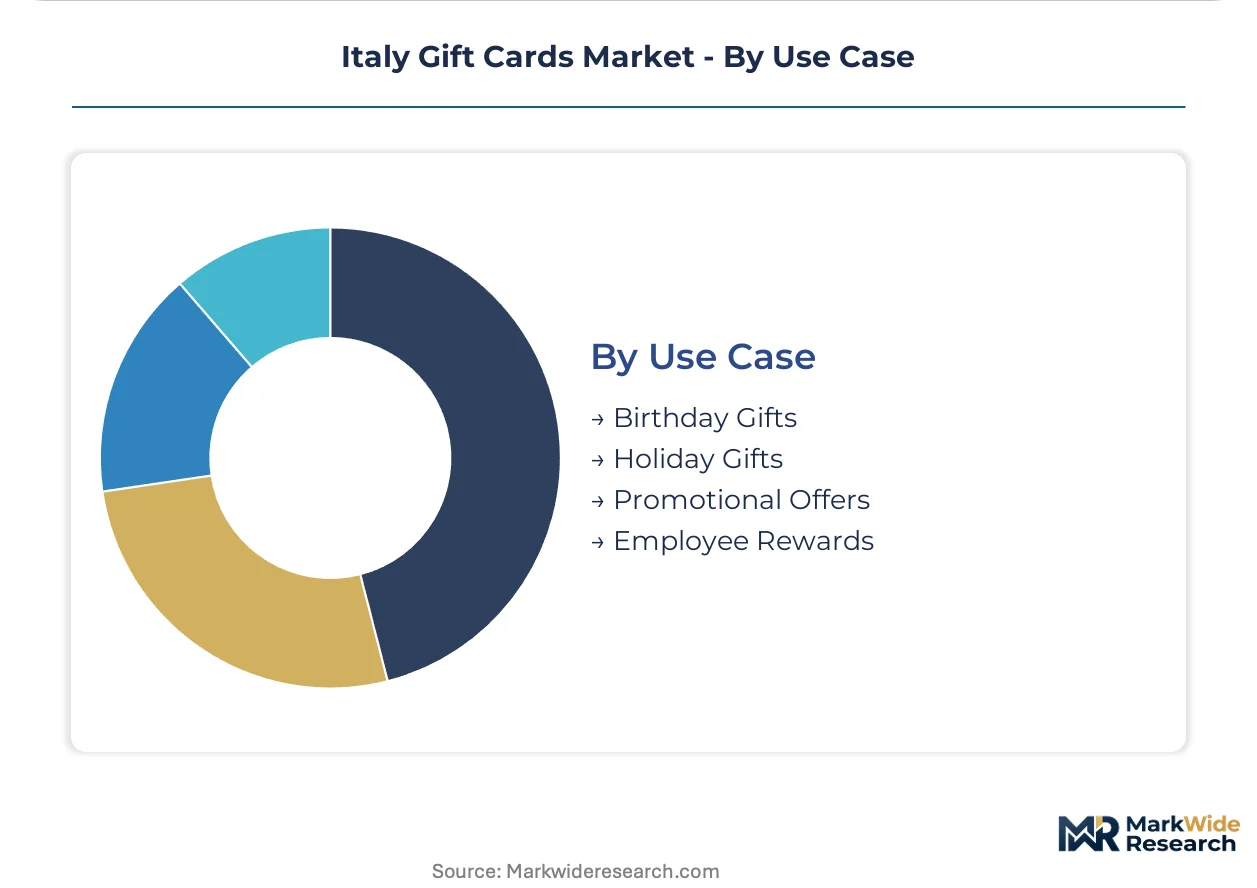
Use Case:
Occasion-based segmentation shapes denomination patterns, design premium tolerance, and redemption urgency.
- Birthday Gifts:Year-round demand with moderate denomination concentration and personalized messaging features. Digital delivery is displacing physical cards among younger donor demographics.
- Holiday Gifts:December volume spikes drive 40%+ of annual physical card sales. Tactile presentation requirements sustain premium pricing despite higher production costs.
- Promotional Offers:Retailer-issued incentives for customer acquisition and basket-size expansion. GDPR consent segmentation inflates database architecture costs for loyalty-linked programs.
- Employee Rewards:Corporate recognition programs with standardized denomination tiers and tax reporting integration. Northern manufacturing belt multinationals consolidate vendor relationships around single-platform solutions.
Holiday gifts anchor absolute volume; employee rewards show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan's dense fintech engineering workforce anchors Italy's gift card infrastructure development, concentrating authentication expertise and instant issuance platform architecture in Lombardy's metropolitan core.
Lombardy
Corporate procurement departments in Milan's manufacturing belt drive bulk digital card volumes for employee recognition programs. Banca d'Italia's e-money thresholds regulate open-loop instruments circulating above defined value limits. The city's retail banking density supports high-frequency card circulation models replicating across Turin and Bologna corridors.
Piedmont
Turin's automotive supply chain employers standardize incentive programs across Italian operations using single-platform gift card solutions. The European Banking Authority's anti-money laundering protocols capture high-value corporate circulation. Industrial procurement consolidation concentrates volume through API-integrated HR systems rather than retail distribution.
Emilia-Romagna
Food processing and packaging machinery manufacturers in Bologna deploy channel partner reward programs sustaining issuer float revenue. Italy's data protection regulator applies GDPR strictures forcing parallel customer database maintenance by consent status. Premium physical card placement persists in affluent provincial supermarket networks.
Veneto
Verona and Padua retail chains migrate issuance to tokenized digital formats eliminating physical production overhead. PSD2 strong customer authentication mandates compress operational runway for new entrants lacking pre-built compliance infrastructure. NFC-enabled smartphone penetration accelerates mobile gift card activation among urban youth demographics.
Lazio
Rome's public sector and hospitality employers generate seasonal demand spikes for closed-loop dining and experiential cards. The central bank coordinates with EU authorities on forthcoming digital euro pilots threatening gift card float absorption. Tourism recovery post-pandemic expands redemption velocity at restaurant and hotel partners.
Italy Gift Cards Market Competitive Landscape
The competitive structure tilts toward diversified retail conglomerates with proprietary distribution networks and established compliance infrastructure. Incumbent supermarket chains leverage controlled physical placement in affluent northern provinces while technology platforms capture digital issuance volume through pan-European fulfillment backbones. Three archetypes dominate: retail-anchored closed-loop issuers, technology-enabled open-loop platforms, and payment infrastructure specialists. Consolidation pressures intensify as PSD2 authentication requirements favor scale, while strategic partnerships between retailers and fintech providers accelerate API-integrated corporate procurement solutions.
Among technology-enabled platforms, Amazon.com exemplifies the open-loop archetype through its fulfillment backbone spanning the peninsula. Retail-anchored competition centers on Esselunga and Carrefour Group, each occupying positions within controlled supermarket distribution networks where premium physical card placement defends margin against payment scheme displacement. These three entities represent the dominant competitive anchors structuring Italy's gift card landscape.
| Leading Market Players |
|---|
| Amazon.com |
| Apple Inc. |
| Conad |
| Esselunga |
| Carrefour Group |
| Coop Italia |
| Epipoli Group |
| Nexi Payments |
| PostePay |
| Others |
Pricing and Supply Chain Analysis
Corporate procurement departments in northern Italian industrial zones are consolidating vendor relationships around single-platform gift card solutions, forcing issuers to absorb authentication infrastructure costs while defending margin through controlled distribution networks. This buyer consolidation compresses pricing power for fragmented digital entrants while supermarket chains leverage premium physical placement to sustain premium tiers.
Pricing Analysis
Bundled authentication services versus unbundled credential issuance splits the competitive landscape. Three-tier pricing structure across premium, standard, and economy levels reflects authentication burden, with PSD2-compliant instant issuance commanding premium positioning. Price differentiation hinges on delivery latency and compliance infrastructure ownership. Pricing pressure stems from corporate procurement standardization, which favors volume discounts over per-unit margin. Small retail customers exhibit highest price sensitivity, while multinational employers in Lombardy demonstrate lowest sensitivity due to tax reporting integration requirements.
Supply Chain Analysis
Reverse-logistics flows for unspent physical card inventory create working capital drag, with Q4 seasonal stockpiling requiring depreciation reserves against obsolescence. Manufacturing concentrates in China, Germany, and domestic Italian converters for plastic substrate and chip encoding. Raw material dependencies span PVC resin, magnetic oxide coatings, and NFC antenna substrates. Single-source vulnerability sits with specialized fintech engineering talent for PSD2 authentication protocols. Distribution runs through controlled supermarket end-caps in affluent northern provinces and direct API integration with enterprise HR systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's gift card market reads as a late-cycle quality story, with corporate procurement departments prioritizing compliance-integrated platforms over commodity credential issuance. Premium specifications now center on real-time tax reporting and GDPR-consent architecture rather than denomination range alone.
For Market Incumbents: Extend authentication infrastructure ownership to capture corporate procurement consolidation. Esselunga and similar retail-anchored issuers should deepen proprietary e-commerce portal development to bypass third-party commission erosion. Defend against open-loop payment scheme displacement by tightening controlled distribution in Lombardy and Emilia-Romagna supermarket networks. Prioritize API integration capabilities with enterprise HR systems over retail end-cap expansion. For New Entrants and Emerging Players: Fintech engineering consultancies represent the most accessible channel partner type for market entry. White-space targets concentrate in instant issuance technology for last-minute gift purchases and tokenized credential architectures eliminating physical production overhead. The most penetrable segment comprises university-adjacent retail serving student demographics with lower-denomination closed-loop instruments. A go-to-market angle anchored in GDPR-compliant database architecture for loyalty-linked programs bypasses incumbent technical debt advantages. For Investors and Strategic Acquirers: Asymmetric upside sits with payment infrastructure specialists possessing pre-built PSD2 compliance frameworks. Long-term viability favors platforms integrating expense management, tax reporting, and authentication protocols within unified architectures. Acquisition target archetype: mid-scale digital issuers with corporate procurement relationships but lacking authentication engineering depth. Monitor Banca d'Italia e-money threshold adjustments and EU digital euro pilot announcements as inflection indicators for float revenue compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| PSD2 Compliance Infrastructure Investment | Pre-built strong customer authentication capabilities gatekeep corporate procurement consolidation in Lombardy. |
| API Integration with Enterprise HR Systems | Direct platform connectivity captures northern Italian manufacturing belt incentive program standardization. |
| Tokenized Digital Credential Migration | Cryptographic issuance architectures collapse working capital cycles from weeks to seconds for closed-loop issuers. |
| Controlled Supermarket Distribution Expansion | Premium physical card placement in affluent northern provinces defends margin against open-loop displacement. |
| GDPR-Compliant Database Architecture | Consent-status segmentation capabilities unlock loyalty-linked program participation without regulatory penalty exposure. |
Research Methodology
Coverage spans Lombardy, Piedmont, Emilia-Romagna, Veneto, and Lazio, with primary inputs from each region informing demand-side calibration. The analysis combines structured interviews with gift card program directors at major retail chains, authentication engineering leads at fintech infrastructure providers, corporate procurement managers at northern Italian manufacturers, and regulatory affairs specialists at Banca d'Italia-coordinated institutions. Secondary validation draws from PSD2 implementation guidance documents, GDPR enforcement precedents from Italy's data protection regulator, European Banking Authority anti-money laundering protocols, and e-money issuance threshold determinations. Bottom-up segment sizing triangulates against top-down macroeconomic consumption indicators.
Rate-of-change decomposition separates volume expansion from value capture across product type, end user, distribution channel, and use case dimensions. The analytical framework models growth trajectories across the analysis window through elasticity-adjusted demand curves and regulatory compliance cost pass-through assumptions. Segmentation dimensions span physical versus digital credential formats, corporate versus retail procurement patterns, supermarket versus online channel flows, and seasonal versus year-round redemption velocity. CAGRs derive from trend-line extrapolation of corporate incentive program penetration, NFC-enabled smartphone adoption curves, and instant issuance technology diffusion rates.
Revisions become necessary when EU digital euro pilot specifications materialize with float absorption mechanisms, when Banca d'Italia adjusts e-money thresholds, or when GDPR enforcement creates step-change compliance cost inflation. Practitioners should monitor corporate procurement vendor consolidation announcements, authentication engineering salary inflation indices, and central bank digital currency development timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Telecom Billing and Revenue Management Market
Payments
Master Recharge API Market
Payments
Global Accounts Payable (AP) Automation Software Market
Payments
India Payments Market
Payments
South Korea Mobile Payment Market
Payments
Mobile Payment Transaction Market
Payments
Asia Pacific Mobile Wallet Market
Payments
Japan Payments Market
Payments
Germany Gift Card and Incentive Card Market
Payments
Slovakia POS Terminal Market
Payments
Digital Payment in Healthcare Market
Payments
Global Virtual Cards Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
Point-Of-Sale [POS] Terminal Market
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Gift Card and Incentive Card Market