
 Latin America Mobile Payment Market | 2026-2036
Latin America Mobile Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Mobile Payment Market Intelligence
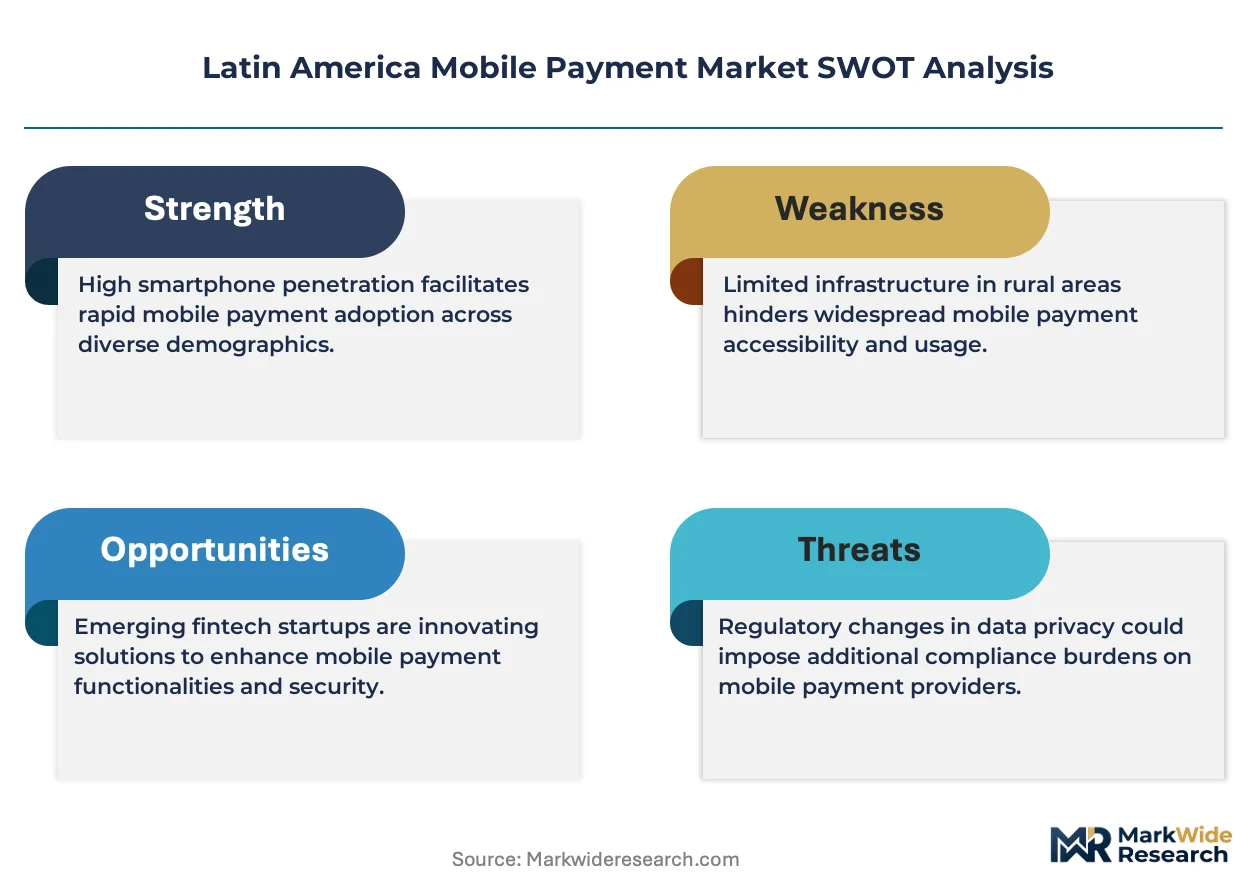
QR code infrastructure is broadening access for unbanked populations across Latin America. Mercado Pago leverages its e-commerce origin to anchor merchant acquisition in Argentina and Brazil. Nubank sustains user engagement through digital banking integration that blurs wallet and account boundaries. Stone competes on hardware-plus-software bundles that lock in small-business payment flows.
Latin America mobile payment systems transmit value through encrypted digital channels using NFC, SMS, blockchain, and biometric authentication protocols, with transaction routing optimized for low-bandwidth environments prevalent outside major metropolitan zones. The primary commercial purpose is reducing cash-handling costs while expanding financial inclusion for underbanked populations. Wallet and QR code payment segments lead transaction volume across the region, reflecting merchant preference for low-friction onboarding and minimal hardware investment. P2P transfer and e-commerce payment service types capture the fastest growth as PIX and SPEI real-time rails normalize instant settlement expectations among consumers.
Brazil's Central Bank PIX mandate, Mexico's CNBV fintech licensing framework, and Colombia's SFC open-banking regulations collectively shape product standards and market access thresholds across the region. Compliance with these divergent national frameworks demands localized infrastructure investments that favor established regional operators over global entrants. Stakeholders must monitor regulatory divergence on consumer-data portability and interchange-fee caps as these variables determine unit economics and competitive moat durability.
Market Dynamics
Brazil's PIX instant-payment rails have compressed settlement timelines from T+2 to real-time, forcing wallet providers to rebuild infrastructure around zero-latency expectations rather than batch-processing economics.
Growth Catalysts
- PIX instant-payment mandate:Brazil's central bank requirement for universal real-time settlement eliminates friction for micro-merchants previously dependent on cash handling.
- Smartphone penetration corridors:Urban density in São Paulo and Mexico City creates contiguous addressable markets where QR code acceptance networks achieve critical mass faster than hardware-dependent alternatives.
- Open-banking interoperability:Colombia's SFC and Mexico's CNBV frameworks mandate data portability that reduces customer acquisition costs for fintech wallets.
Market Restraints
- Interconnect fee volatility:Uncapped interchange disputes between acquirers and issuers in Brazil compress unit economics for low-ticket transactions.
- Last-mile connectivity gaps:Rural zones outside metropolitan corridors lack reliable 4G coverage, degrading QR code scan reliability and forcing fallback to USSD protocols.
- Regulatory fragmentation:Divergent licensing requirements across Mexico's CNBV, Brazil's Central Bank, and Colombia's SFC force redundant compliance infrastructure.
Strategic Opportunities
- Colombia's unbanked corridor:Pacific and Amazonian regions with sub-40% banking penetration offer greenfield wallet adoption without incumbent displacement costs.
- Biometric authentication convergence:Facial recognition layered atop PIX rails enables passwordless onboarding for populations with limited documentation.
- Municipal transit integration:City-level transport authorities in Buenos Aires and Santiago seek unified payment credentials, creating captive daily-use cases.
Industry Challenges
- Legacy core banking integration:Incumbent banks in Mexico and Chile operate on COBOL-based systems that resist API-native wallet connectivity without expensive middleware layers.
- Fraud-model recalibration:Real-time settlement eliminates chargeback buffers, requiring machine-learning transaction scoring deployed at sub-100-millisecond latency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Mobile Payment Market |
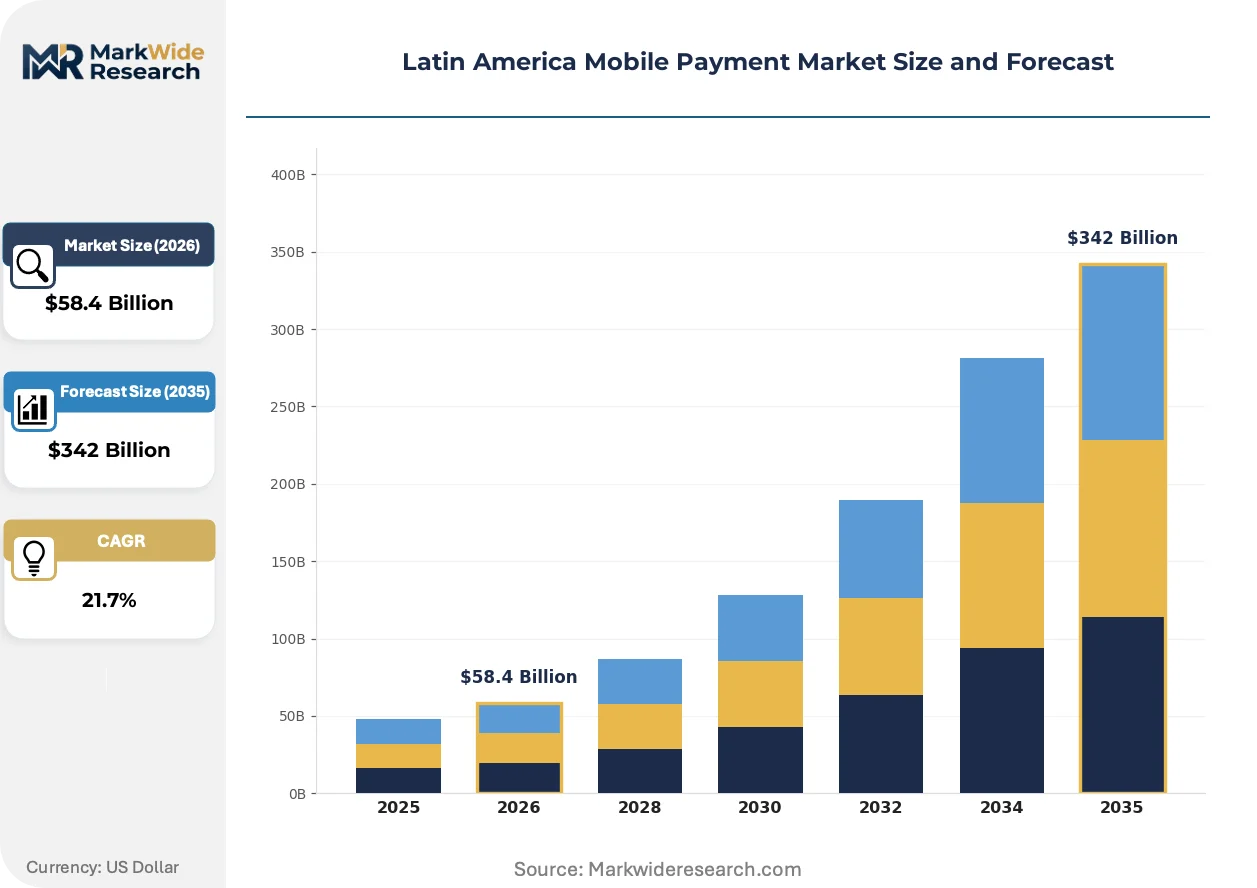
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $342 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wallets, Contactless Cards, QR Code Payments, Digital Banking Customer Type: Consumers, Merchants, Banks, Payment Processors Technology: NFC, SMS, Blockchain, Biometric Authentication Service Type: P2P Transfers, Bill Payments, In-store Payments, E-commerce Payments |
| Companies Covered | EBANX, Stone, Nubank, Rede, Cielo, Mercado Pago, Uala, Bitso, Clip, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Mobile Payment Market Strategic Shifts & Innovations
Payment infrastructure across Latin America is consolidating around instant rails that collapse the distinction between account-based and wallet-based value storage. This convergence demands new architectural approaches to identity verification and merchant onboarding.
Biometric facial recognition is unifying identity proofing with transaction authorization in Brazil and Mexico. Fintechs serving informal merchants are deploying liveness detection at onboarding to bypass document-heavy KYC. This compression is collapsing the traditional separation between identity verification and payment credential issuance, enabling same-minute wallet activation.
Brazil's Central Bank has tightened PIX participant liability rules, shifting fraud losses toward originating institutions rather than receiving banks. The industrial consequence is accelerated investment in behavioral analytics and device fingerprinting by wallet operators. Small and mid-size fintechs are responding through vendor partnerships rather than in-house model development.
Merchant acquisition is fragmenting away from dedicated sales forces toward embedded distribution within accounting and inventory software. Argentine and Chilean micro-businesses now encounter payment acceptance as a feature within vertical SaaS rather than through standalone wallet pitches. This pattern is most visible in retail and food service verticals where software penetration preceded financial service adoption.
Latin America Mobile Payment Market Segmentation
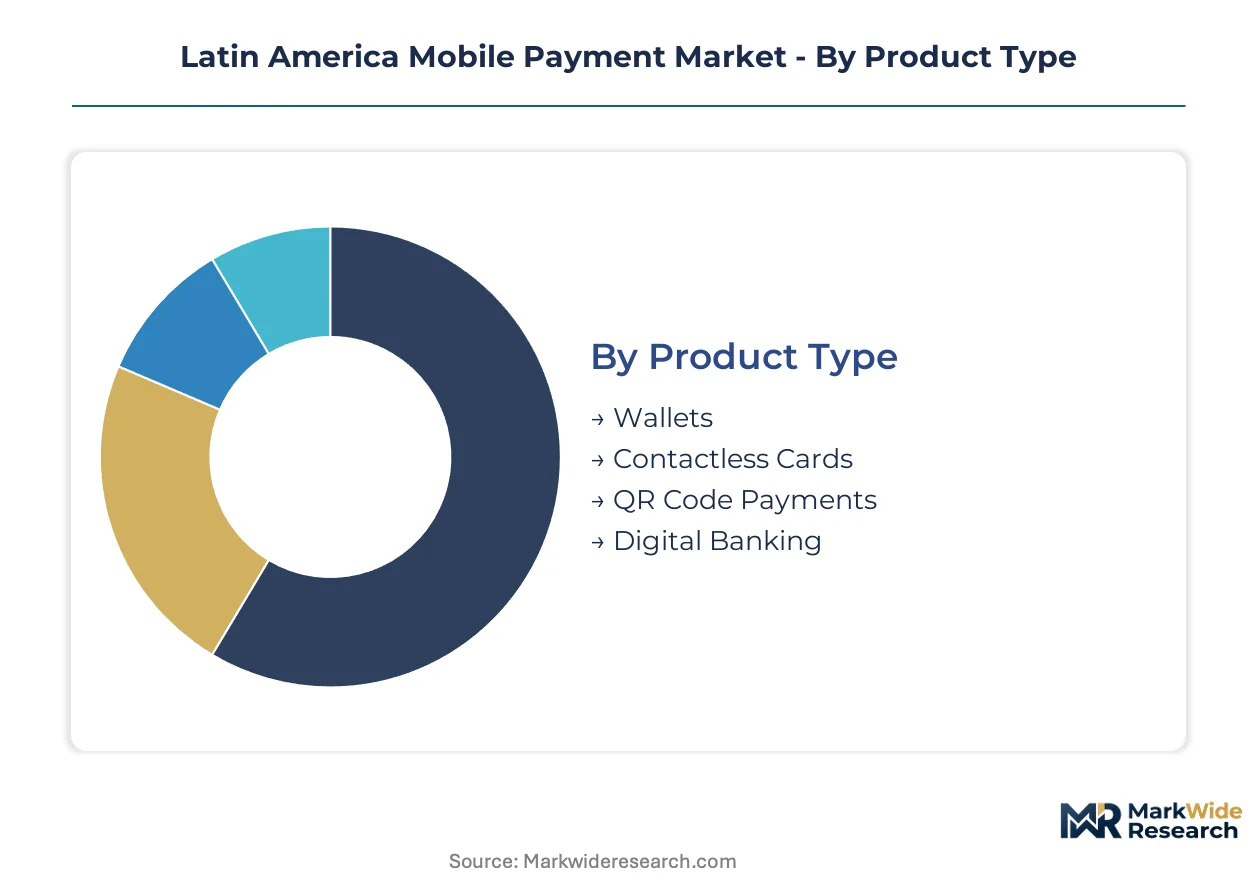
Segmentation in Latin America mobile payments reveals how infrastructure choices and user contexts fragment go-to-market economics. Product architecture, customer workflow, and technical protocol each impose distinct margin structures and capital requirements on operators competing across Brazil, Mexico, and Colombia.
Product Type:
Customization intensity varies sharply across this category, from standardized interoperable rails to vertically integrated proprietary stacks.
- Wallets:Software-based value storage applications integrate with PIX, SPEI, and other instant-payment rails. Brazilian fintechs embed wallets within super-app ecosystems to capture daily transaction frequency in São Paulo and Rio de Janeiro corridors. Leading the category by volume: Wallets. Growing fastest: QR Code Payments.
- QR Code Payments:Optical scan protocols enable merchant acceptance without dedicated hardware, slashing onboarding costs for micro-merchants in Colombia's Pacific region and Mexico's informal commerce zones. Regulatory mandates for interoperable QR standards across Brazil's Central Bank and Mexico's CNBV accelerate network density.
- Contactless Cards:NFC-enabled plastic credentials bridge legacy point-of-sale infrastructure with digital settlement, concentrating demand among underbanked populations with limited smartphone access in Chile and Peru urban peripheries.
- Digital Banking:Full-service neobank platforms blur payment and deposit functions, with Nubank and similar operators capturing primary financial relationships in Brazil's metropolitan corridors.
Volume leadership sits with wallet architectures; steepest expansion trajectory belongs to QR code protocols as merchant acquisition costs compress.
Customer Type:
Margin profiles diverge by customer sophistication, from mass-market consumers to infrastructure-dependent payment processors.
- Consumers:Individual users drive transaction velocity through P2P and merchant payments, with adoption concentrated in Brazilian urban centers where PIX penetration exceeds regional benchmarks. Leading the category by volume: Consumers. Expanding most quickly: Merchants.
- Merchants:Micro-businesses and retail operators constitute the fastest-growing acquisition target, particularly in Colombia's Amazonian regions where sub-40% banking penetration enables greenfield wallet adoption without incumbent displacement costs.
- Banks:Traditional financial institutions participate as infrastructure providers and wallet sponsors, with compliance investments in Brazil's Central Bank liability rules reshaping fraud-model economics.
- Payment Processors:Acquirer-issuer intermediaries manage settlement complexity across divergent national regulatory frameworks, facing margin pressure from uncapped interchange disputes in Brazil.
Consumer transaction volume dominates current flows; merchant segment gains share fastest as micro-business onboarding accelerates.
Technology:
Protocol maturity spans from ubiquitous SMS to emerging biometric layers, each imposing distinct latency and security constraints.
- NFC:Near-field communication enables tap-to-pay functionality at physical terminals, with deployment concentrated in Buenos Aires and Santiago municipal transit integrations that create captive daily-use cases. Leading the category by volume: NFC. Gaining share fastest: Biometric Authentication.
- Biometric Authentication:Facial recognition and liveness detection protocols collapse identity verification with transaction authorization, enabling passwordless onboarding for documentation-limited populations in Brazil and Mexico.
- SMS:Text-based transaction initiation persists in rural zones outside metropolitan corridors where 4G coverage degrades QR reliability, forcing fallback to USSD protocols.
- Blockchain:Distributed ledger settlement remains experimental, with limited commercial deployment constrained by regulatory uncertainty across Mexico's CNBV and Colombia's SFC frameworks.
NFC protocols carry current transaction volume; biometric layers climb fastest as KYC friction compresses.
Service Type:
Use-case granularity separates high-frequency low-ticket flows from episodic high-value transactions.
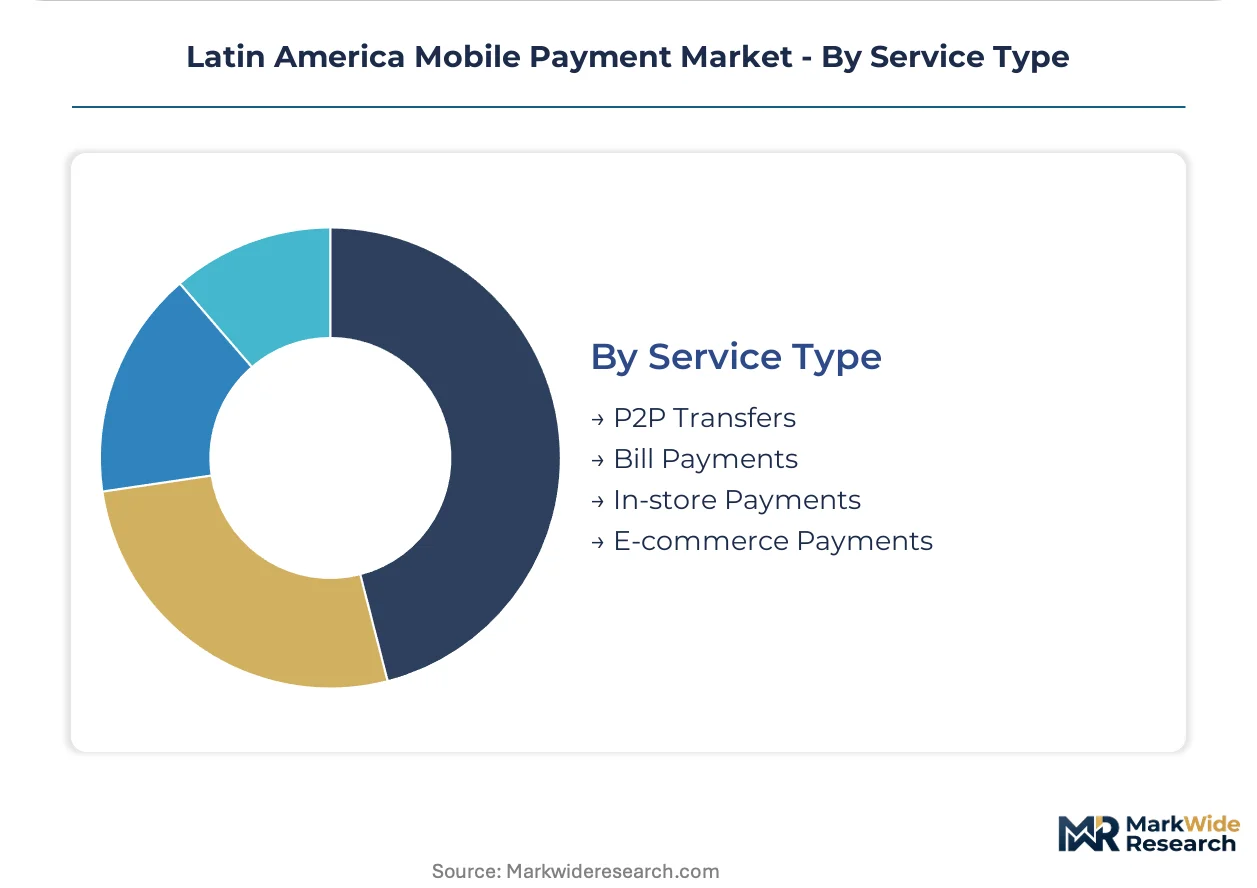
- P2P Transfers:Person-to-person value movement normalizes real-time settlement expectations through PIX and SPEI rails, with Brazilian consumers replacing cash for informal economy transactions. Leading the category by volume: In-store Payments. Climbing fastest: E-commerce Payments.
- E-commerce Payments:Online checkout integration captures growth as Mercado Pago and similar platforms leverage e-commerce origin to anchor merchant acquisition in Argentina and Brazil.
- In-store Payments:Physical retail checkout constitutes the volume anchor, with QR code networks achieving critical mass faster than hardware-dependent alternatives in São Paulo and Mexico City density corridors.
- Bill Payments:Recurring utility and service settlements represent stable but slower-growing volume, concentrated among banked populations with established digital habits.
In-store payments dominate current flows; e-commerce checkout layers expand most quickly as online retail penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban payment density concentrates in Brazilian metropolitan corridors where PIX instant rails and smartphone penetration exceed regional benchmarks. Mexico and Colombia follow with regulatory-mandated open-banking frameworks accelerating interoperability. Argentina and Chile round out the five-country landscape with distinct merchant-acquisition patterns shaped by inflation volatility and transit integration opportunities.
Brazil
PIX real-time settlement and micro-merchant onboarding drive transaction volume in São Paulo and Rio de Janeiro density corridors. Brazil's Central Bank mandates universal instant-payment participation, eliminating batch-processing economics for wallet operators. São Paulo anchors merchant acquisition networks where QR code acceptance achieves critical mass faster than hardware-dependent alternatives.
Mexico
SPEI instant rails and CNBV fintech licensing normalize real-time expectations among consumers in Mexico City Metro. The central bank's open-banking framework mandates data portability that reduces customer acquisition costs for digital wallets. Nuevo León and Jalisco industrial clusters see embedded payment distribution through accounting software verticals.
Colombia
Sub-40% banking penetration in Pacific and Amazonian regions enables greenfield wallet adoption without incumbent displacement costs. The SFC open-banking regulations accelerate interoperability standards across financial institutions. Bogotá and Medellín urban corridors concentrate fintech density while rural zones force fallback to USSD protocols.
Argentina
Hyperinflation dynamics push consumers toward dollar-denominated digital wallets and P2P transfer velocity. The central bank's regulatory stance on fintech licensing shapes market access thresholds for new entrants. Buenos Aires anchors merchant acquisition where vertical SaaS embeds payment acceptance for retail and food service micro-businesses.
Chile
Municipal transit integration in Santiago creates captive daily-use cases for unified payment credentials. The central bank's instant-payment infrastructure investments compress settlement timelines toward real-time expectations. Legacy COBOL-based core banking systems in incumbent financial institutions resist API-native wallet connectivity without expensive middleware layers.
Latin America Mobile Payment Market Key Industry Players
Merchant acquisition through embedded software distribution dominates the current landscape as standalone wallet pitches lose traction against vertical SaaS integration. The market structure fragments across three tiers: e-commerce-origin super-apps with merchant networks, neobank platforms blurring wallet and account boundaries, and hardware-plus-software bundlers locking in small-business payment flows. Two strategic archetypes anchor competitive positioning: infrastructure-light QR code networks achieving rapid rural penetration, and vertically integrated stacks controlling hardware, software, and settlement rails. Portfolio diversification into adjacent financial services and geographic expansion across Andean and Southern Cone corridors represent the dominant competitive moves.
Among Brazil-based operators, Nubank and Stone occupy positions at opposite ends of the integration spectrum. Nubank exemplifies the neobank archetype where payment functions dissolve into primary banking relationships. Stone represents hardware-dependent merchant acquisition with software bundles that capture small-business cash flows. Mercado Pago anchors the e-commerce-origin tier, leveraging marketplace merchant relationships to build acceptance network density across Argentina and Brazil. These three operators illustrate how origin context—banking license, point-of-sale hardware, or marketplace commerce—determines sustainable competitive positioning.
| Leading Market Players |
|---|
| EBANX |
| Stone |
| Nubank |
| Rede |
| Cielo |
| Mercado Pago |
| Uala |
| Bitso |
| Clip |
| Others |
Cost & Logistics Intelligence
Software engineering talent concentration in São Paulo and Mexico City drives labor-cost differentials that widen pricing-tier spreads between premium full-stack wallets and economy QR-code solutions.
Pricing Analysis
Volume leadership sits with low-margin QR-code transactions while margin capture concentrates in vertically integrated wallet-banking hybrids. Three-tier pricing structure across premium, standard, and economy levels reflects customization depth and settlement speed guarantees. Pricing pressure stems from uncapped interchange disputes in Brazil compressing unit economics on sub-five-dollar tickets. Micro-merchants in Colombia's Pacific corridor exhibit highest price sensitivity; enterprise acquirers in São Paulo demonstrate lowest.
Supply Chain Analysis
Workforce availability for cloud infrastructure engineering concentrates in Brazil, Mexico, and Colombia metropolitan zones, constraining regional expansion timelines. Hardware component sourcing draws from China for point-of-sale terminals, Taiwan for NFC chips, and domestic assembly in São Paulo for last-mile distribution. Single-source vulnerability sits with PIX rail dependency controlled by Brazil's Central Bank. Distribution runs through embedded software partnerships with vertical SaaS providers rather than direct sales forces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over merchant onboarding software determines pricing power and retention economics.
For Market Incumbents: Acquire merchant SaaS platforms to lock in small-business payment flows before accounting-software distributors consolidate distribution. PIX liability rule tightening by Brazil's Central Bank threatens fraud-model economics; invest in behavioral analytics partnerships rather than in-house development. Defend position through exclusive transit credential contracts in Buenos Aires and Santiago municipal systems. For New Entrants and Emerging Players: Colombia's SFC open-banking regulations in Pacific and Amazonian regions open a window for greenfield wallet deployment without incumbent displacement costs. Target biometric-authentication layers for documentation-limited populations in rural Mexico. Pursue municipal transit integration as the primary go-to-market anchor for daily-use habit formation. For Investors and Strategic Acquirers: Re-rating potential sits with hardware-plus-software bundlers given merchant acquisition cost compression through embedded distribution. Five-to-ten-year viability favors operators controlling both acceptance infrastructure and settlement rail access. Monitor interchange-fee regulatory caps as the critical inflection signal for unit economics durability.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Layer Deployment | Facial recognition integration with PIX rails enables passwordless onboarding for underbanked Colombian populations. |
| Vertical SaaS Embedded Distribution | Payment acceptance features within Argentine retail software reduce merchant acquisition costs versus standalone wallet pitches. |
| Municipal Transit Credential Consolidation | Unified payment systems in Santiago and Buenos Aires create captive daily-use cases with high switching costs. |
| Open-Banking API Infrastructure Investment | Data portability compliance across Mexico's CNBV framework lowers customer acquisition friction for digital wallets. |
| Real-Time Fraud Model Development | Sub-100-millisecond transaction scoring addresses PIX chargeback elimination and liability shift to originating institutions. |
Research Approach
Central bank regulatory filings, fintech licensing databases, and instant-payment rail transaction disclosures formed the secondary backbone for market sizing and regulatory mapping. Primary interviews with digital wallet product managers, merchant acquisition executives, central bank payment system officers, and vertical SaaS platform engineers validated infrastructure investment trajectories and adoption assumptions. Bottom-up merchant density estimates triangulated against top-down payment volume projections from national clearing systems.
Bottom-up modeling segmented addressable merchants by urban corridor density, banking penetration rates, and smartphone ownership thresholds. Top-down validation cross-checked against PIX, SPEI, and other instant-rail disclosed transaction volumes. Segmentation dimensions included product architecture, customer workflow, technical protocol, and service type. CAGRs derived from trend extrapolation of rail adoption curves and merchant onboarding velocity. Industry-specific inputs incorporated open-banking regulatory phase-in schedules and biometric authentication deployment timelines.
The model assumes a particular technology adoption path; alternative pathways for blockchain-based settlement would alter the outlook if regulatory clarity emerges across Mexico's CNBV or Colombia's SFC frameworks. Forecasts reflect assumptions on interchange-fee stability and rural connectivity infrastructure investment. Material deviation in PIX liability rule enforcement or open-banking data portability implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Estonia POS Terminal Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
Middle East and Africa Payments Market
Payments
Europe Fuel Cards Market
Payments
Smart Home Payments Market
Payments
China Mobile Payments Market
Payments
Poland POS Terminal Market
Payments
Hong Kong Credit Cards Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Bill Splitting Apps Market
Payments
United Kingdom Mobile Payments Market
Payments
Japan Payments Market
Payments
Fuel and Convenience Store POS Market
Payments
Middle East and Africa Prepaid Card Market
Payments
Tanzania Mobile Money Market
Payments
Germany Real Time Payments Market