
 China POS Terminals Market | 2026-2036
China POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
China POS Terminals Market Outlook
The divergence between premium and commodity tiers is hardening across the China POS Terminals Market. Shenzhen Xinguodu Technology Co., Ltd. leverages its Android-based platform architecture to dominate mid-market merchant segments, while PAX Global Technology Limited anchors its position through in-house secure-element manufacturing and overseas certification breadth. Fujian Newland Payment Technology Co., Ltd. differentiates via deep vertical integration into barcode-scanning modules, a capability that sustains margin pools unavailable to pure assembler competitors.
China POS terminals are electronic payment acceptance devices combining secure cryptographic processors, touchscreen interfaces, and connectivity modules (4G, Wi-Fi, Bluetooth) to authenticate and settle card-present and card-not-present transactions. These systems encode transaction data through PCI-certified hardware security modules and transmit encrypted payloads to acquiring banks or payment aggregators for settlement authorization. Mobile POS and self-service kiosk deployments are expanding fastest, driven by SMB merchant mobility requirements and labor-cost sensitivity in quick-service restaurants; fixed POS remains the largest revenue pool but faces margin compression from state-backed procurement standardization. Cloud-based deployment architectures are displacing on-premises legacy stacks as acquiring banks push software-as-a-service terminal management to reduce field-service costs.
SAMR enforces mandatory CCC certification and payment-device security testing that filters out uncertified hardware imports, while MIIT's radio-frequency regulations govern 4G and NFC module approval timelines that directly impact product launch cycles. The People's Bank of China's technical specifications for digital yuan acceptance are forcing terminal OEMs to retrofit or redesign hardware to support dual-offline transaction protocols. Stakeholders must monitor whether SAMR tightens data-localization requirements for terminal transaction logs, a shift that would trigger costly firmware architecture decisions for cloud-dependent vendors.
Market Dynamics
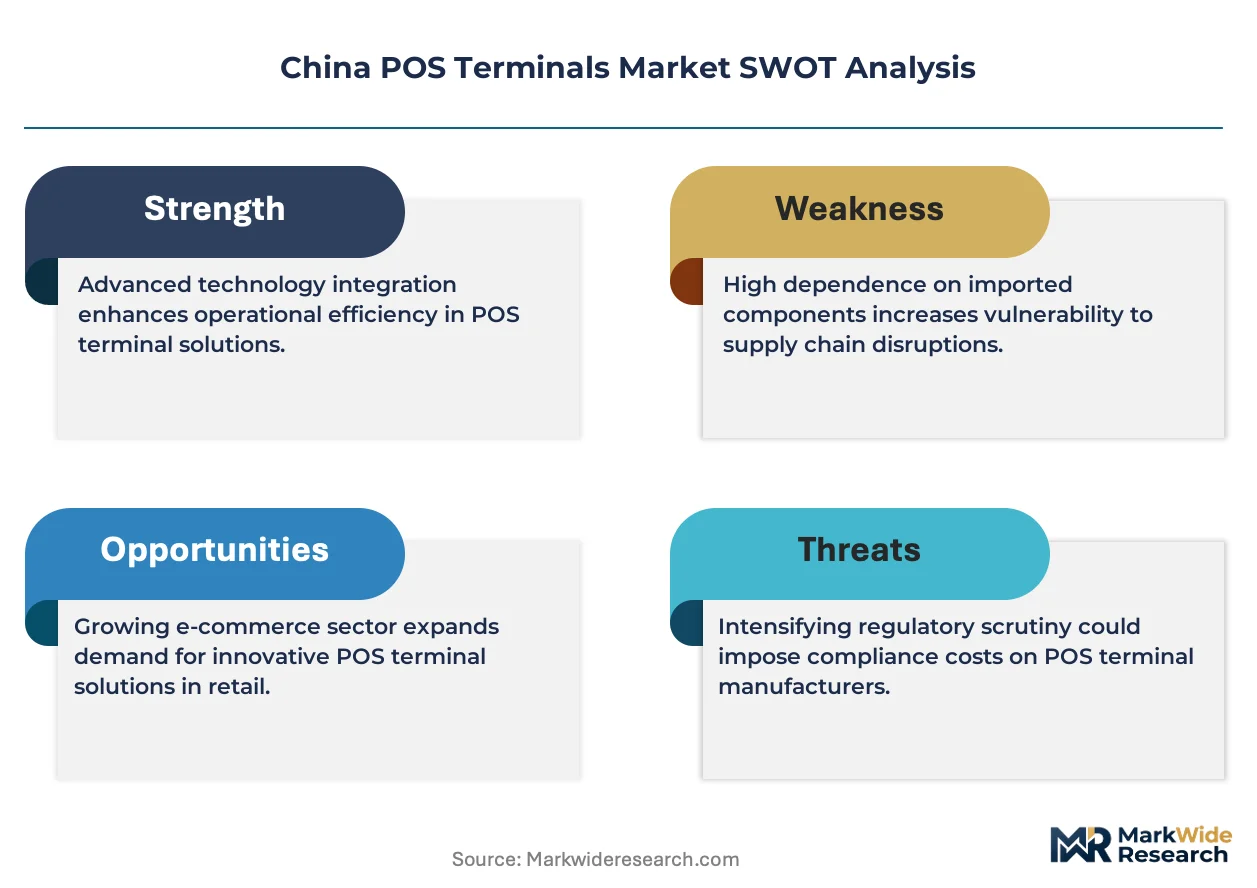
The People's Bank of China's digital yuan mandate is forcing terminal OEMs to redesign hardware architectures around dual-offline transaction protocols, compressing development cycles and redrawing competitive boundaries between certified and uncertified suppliers.
Growth Catalysts
- MIIT radio-frequency fast-tracking:Accelerated 4G and NFC module approvals are shortening product launch windows for domestic manufacturers seeking first-mover advantage in merchant acquiring channels.
- Quick-service restaurant automation:Labor-cost sensitivity across tier-two cities is driving self-service kiosk deployments that bundle payment acceptance with order management functionality.
- GB national standards harmonization:Unified financial data security specifications are reducing compliance fragmentation and enabling scale economies for terminal firmware development.
Market Restraints
- SAMR certification bottlenecks:Mandatory CCC certification and payment-device security testing create 4-6 month approval delays that filter out uncertified hardware imports and protect domestic incumbents.
- Secure element supply concentration:In-house manufacturing of cryptographic processors remains concentrated among vertically integrated OEMs, limiting assembler access to margin-critical components.
- Cloud dependency risks:SAMR's potential tightening of data-localization requirements for transaction logs threatens firmware architectures optimized for centralized terminal management platforms.
Strategic Opportunities
- Yangtze River Delta merchant density:Shanghai's fintech ecosystem and Hangzhou's service provider clusters offer concentrated deployment channels for next-generation Android-based terminals.
- Mobile POS penetration gaps:SMB mobility requirements in tier-three cities remain underserved by current hardware refresh cycles focused on tier-one and tier-two urban centers.
- Software-as-a-service terminal management:Acquiring banks are pushing cloud-based deployment architectures to reduce field-service costs, opening subscription revenue streams for firmware-integrated vendors.
Industry Challenges
- Dual-offline protocol engineering:Digital yuan hardware retrofits demand scarce embedded systems expertise combining cryptographic security with intermittent connectivity design.
- Legacy stack integration friction:Cloud-native terminal management platforms face compatibility barriers with on-premises acquiring bank infrastructure still prevalent in provincial branches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China POS Terminals Market |
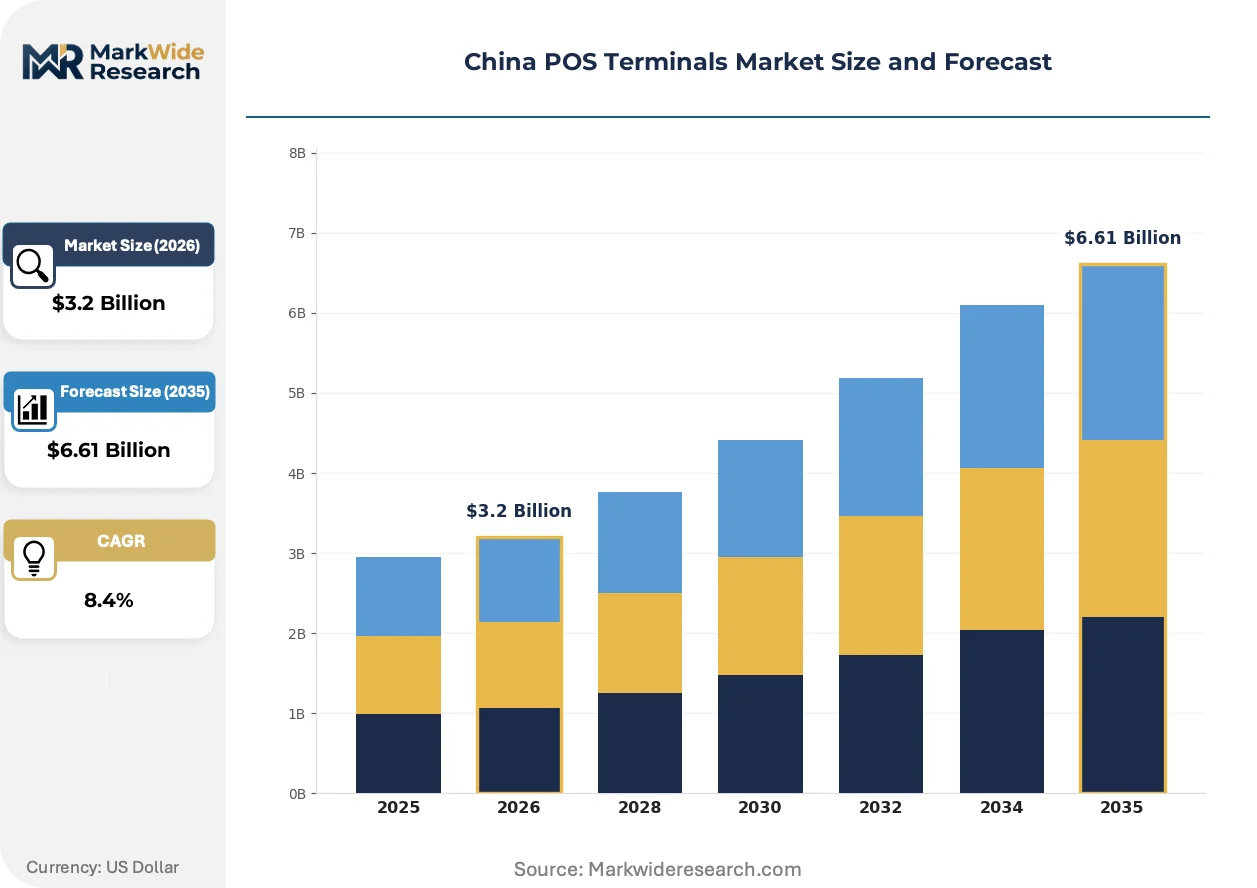
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.61 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Fixed POS, Self-Service Kiosk, Virtual Terminal Technology: Magnetic Stripe, NFC, EMV, Biometric Authentication End User: Retail, Hospitality, Transportation, Healthcare Deployment: Cloud-Based, On-Premises, Hybrid, Managed Services |
| Companies Covered | Verifone Systems LLC, Shenzhen Xinguodu Technology Co., Ltd., Fujian Newland Payment Technology Co., Ltd., New POS Technology Limited, Centerm Information Co., Ltd., PAX Global Technology Limited, Sunmi Technology Co., Ltd., Hisense Intelligent Commercial Equipment Co., Ltd., Ingenico Group SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China POS Terminals Market Strategic Shifts
Hardware-software bundling is collapsing traditional procurement boundaries as acquiring banks and merchant service providers seek unified platforms that compress total cost of ownership across deployment and operational phases.
Android-based POS operating systems are converging with payment application ecosystems to enable third-party software marketplaces on terminal hardware. Quick-service restaurant chains in the Yangtze River Delta are adopting these open-platform devices fastest, replacing proprietary closed-stack terminals. This convergence is compressing margins for pure hardware assemblers while expanding recurring software revenue pools for platform-integrated OEMs.
SAMR's enforcement of GB standards for financial data security is tightening certification requirements for cryptographic module integration. Terminal OEMs must now demonstrate end-to-end encryption compliance through designated testing laboratories before market entry. Fixed POS manufacturers face the steepest compliance burden as their legacy architectures require firmware restructuring to meet localized key-management mandates.
Merchant acquiring banks are unbundling terminal procurement from payment processing contracts, shifting toward hardware-as-a-service subscription models. This restructuring displaces upfront capital expenditure with per-transaction leasing fees across supermarket chains and franchise networks. The shift is most visible in Shanghai and Hangzhou, where fintech-enabled acquiring platforms have captured merchant segments previously locked into long-term equipment financing arrangements.
China POS Terminals Market Segmentation
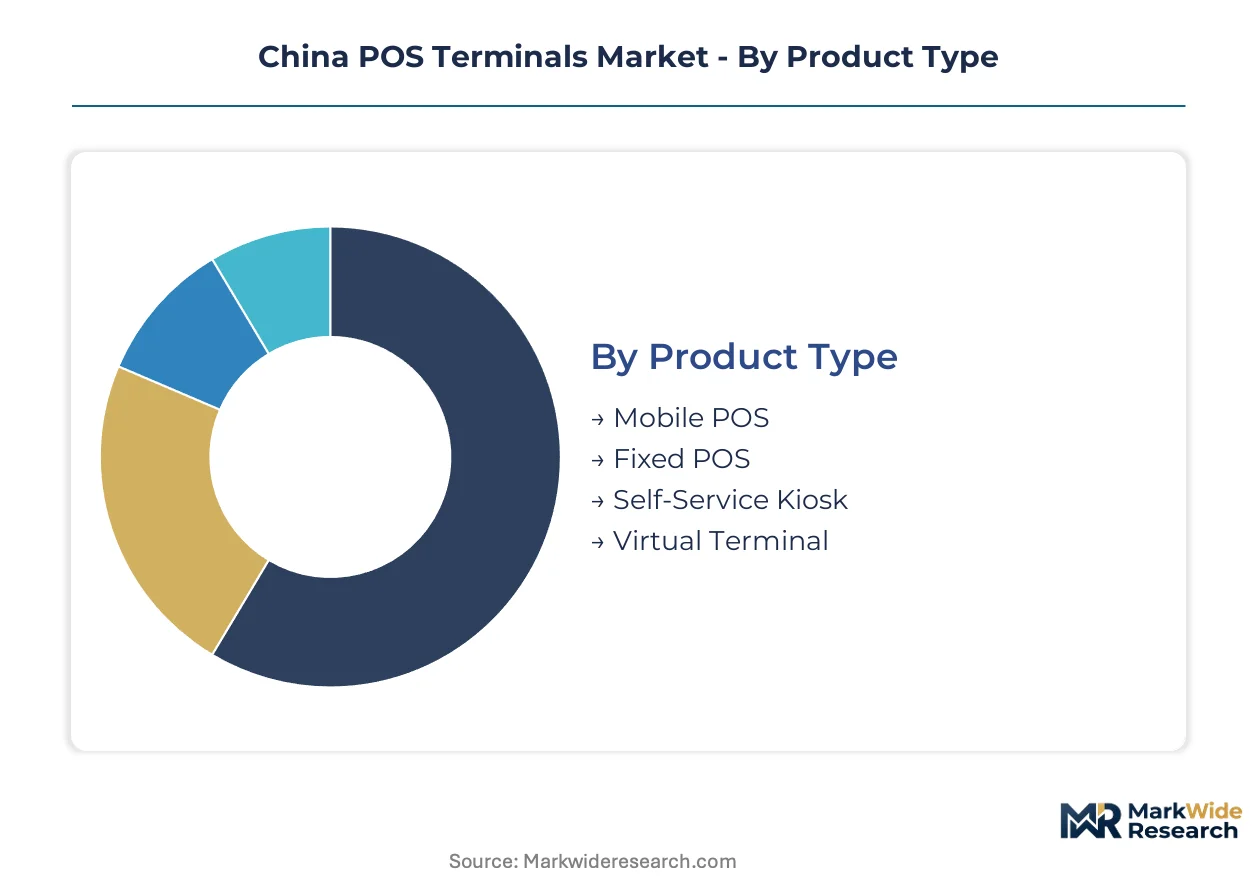
POS terminal segmentation in China reflects divergent supply chain capabilities across hardware architectures and deployment models. OEM procurement strategies and SAMR certification pathways vary sharply by product format and technology stack, creating tiered competitive moats.
Product Type:
Supply concentration for cryptographic modules and secure-element manufacturing favors vertically integrated OEMs in specific hardware categories.
- Mobile POS:Battery-powered Android terminals with integrated 4G modems and PCI-certified PIN pads. Tier-three city SMBs in Sichuan and Henan provinces drive procurement as merchant mobility requirements outpace fixed infrastructure rollout.
- Fixed POS:Countertop devices with Ethernet connectivity and hardware security modules dominate supermarket chains in Shanghai and Hangzhou. State-backed procurement standardization compresses margins for pure assemblers lacking in-house secure-element production.
- Self-Service Kiosk:Bundles payment acceptance with touchscreen ordering interfaces. Quick-service restaurants in tier-two cities deploy these for labor-cost reduction.
- Virtual Terminal:Software-only solutions running on merchant smartphones or tablets. Micro-merchants in rural counties adopt these for zero hardware acquisition cost.
Fixed POS absorbs the bulk of installed capacity; self-service kiosk is expanding most quickly.
Technology:
Certification requirements from the People's Bank of China and MIIT radio-frequency approvals segment suppliers by technical capability depth.
- NFC:Contactless protocols enabling tap-to-pay transactions through dual-interface cards and mobile wallets. Yangtze River Delta transit authorities and convenience store chains mandate NFC acceptance, forcing terminal retrofits.
- EMV:Chip-card authentication with dynamic cryptogram generation. Tier-one city acquiring banks require EMV compliance for fraud liability shift protection.
- Magnetic Stripe:Legacy swipe-card reading via magnetic heads. Provincial rural credit cooperatives maintain limited deployments for aging cardholder bases.
- Biometric Authentication:Fingerprint and facial recognition modules for cardholder verification. Digital yuan pilot programs in Shenzhen and Suzhou test biometric-linked wallets.
EMV holds the largest transaction volume base; biometric authentication is climbing the fastest as central bank pilots expand.
End User:
Merchant acquiring channel structures and hardware refresh cycles diverge sharply across sectoral labor-cost sensitivity and transaction velocity.
- Retail:Supermarket chains and franchise networks with high-throughput checkout requirements. State-owned commercial banks dominate terminal leasing relationships in this segment.
- Hospitality:Hotels and restaurants prioritizing tableside payment and tipping functionality. Hangzhou merchant service providers cluster around hospitality-specific software integrations.
- Transportation:Transit authorities and ride-hailing platforms demanding sub-second transaction authorization. Beijing and Shanghai metro systems drive contactless terminal specifications.
- Healthcare:Hospitals and clinics requiring insurance card integration and installment payment plans. Provincial health bureau procurement favors fixed POS with embedded social security readers.
Retail commands the deepest terminal installed base; transportation is gaining share fastest through transit authority modernization.
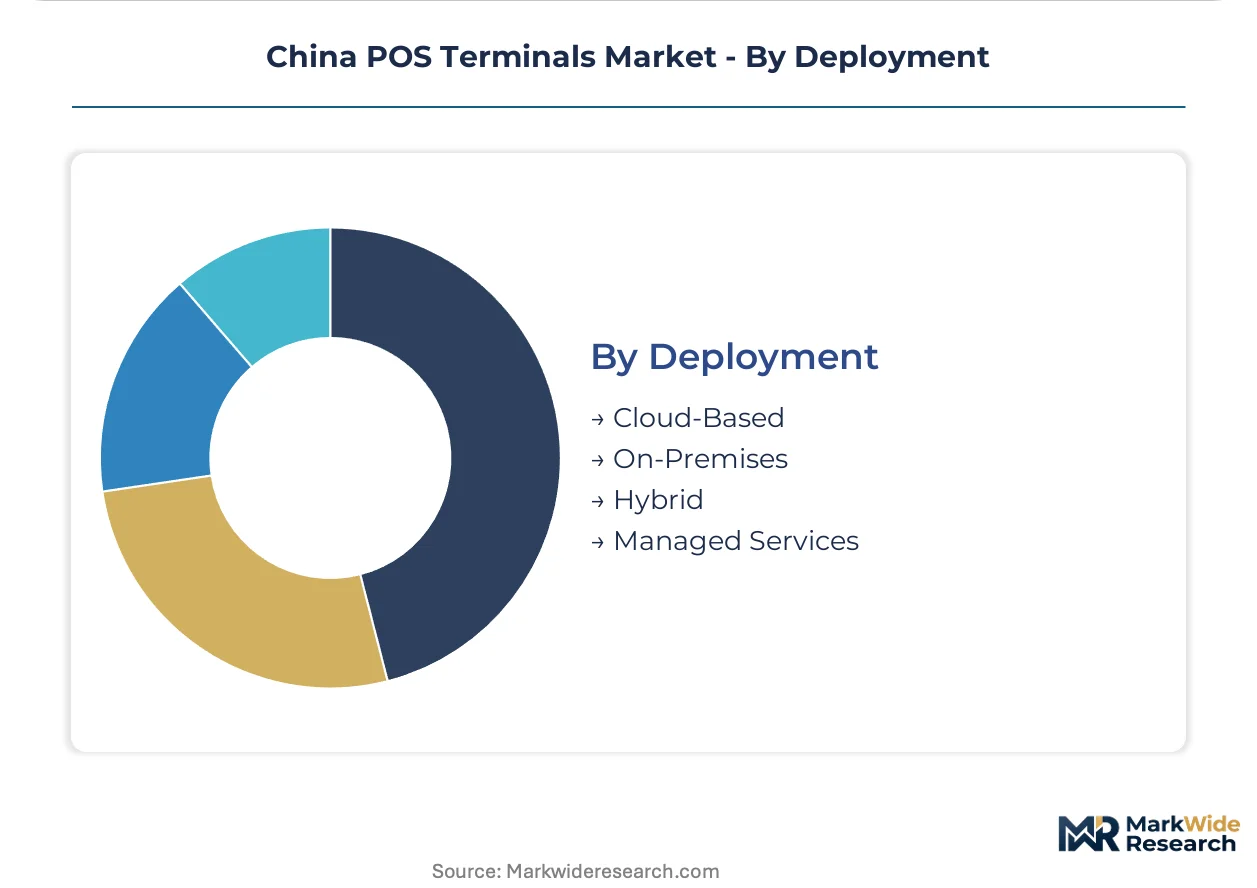
Deployment:
Acquiring bank infrastructure maturity and field-service cost structures determine cloud migration velocity across merchant tiers.
- Cloud-Based:Centralized terminal management with over-the-air firmware updates and real-time transaction monitoring. Fintech-enabled acquiring platforms in Shanghai push this model to reduce provincial branch service calls.
- On-Premises:Legacy server stacks within acquiring bank data centers. Provincial branch infrastructure in central and western provinces maintains this architecture for control retention.
- Hybrid:Edge transaction processing with cloud reconciliation. Large franchise networks balance latency requirements against centralized analytics.
- Managed Services:Third-party terminal lifecycle outsourcing including deployment, maintenance, and compliance updates. Quick-service restaurant chains favor per-device subscription economics.
On-premises retains the largest legacy footprint; cloud-based deployment shows the steepest expansion trajectory as acquiring banks consolidate infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors terminal demand through its fintech ecosystem and merchant acquiring infrastructure. The Yangtze River Delta concentrates hardware deployment channels and certification expertise. Sub-regional variation reflects divergent regulatory enforcement and bank infrastructure maturity.
Yangtze River Delta
Supermarket chains and quick-service restaurants drive hardware refresh cycles across Shanghai and Hangzhou. SAMR enforces GB national standards for financial data security that compress product launch timelines. Hangzhou's merchant service providers cluster around cloud-based terminal management platforms.
Pearl River Delta
Shenzhen's electronics manufacturing base supplies cryptographic modules and secure elements to domestic OEMs. MIIT radio-frequency regulations govern 4G and NFC module approvals that shape competitive positioning. Guangzhou's acquiring banks push software-as-a-service deployment models to reduce field-service costs.
Beijing-Tianjin-Hebei
Transit authorities mandate NFC-enabled terminals for sub-second transaction authorization across metro systems. The People's Bank of China's digital yuan pilots force hardware retrofits for dual-offline protocols. Beijing's state-owned commercial banks dominate procurement standardization for fixed POS deployments.
Sichuan-Chongqing
Tier-three city SMBs adopt mobile POS for merchant mobility requirements underserved by fixed infrastructure. Provincial rural credit cooperatives maintain legacy magnetic stripe deployments for aging cardholder bases. Chengdu's fintech-enabled acquiring platforms capture merchant segments through hardware-as-a-service subscriptions.
Shandong Peninsula
Franchise networks and retail chains drive self-service kiosk deployments for labor-cost reduction. SAMR certification bottlenecks create approval delays that filter out uncertified hardware imports. Qingdao's port logistics facilitate component sourcing for terminal assembly operations.
China POS Terminals Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the China POS Terminals Market. Vertically integrated OEMs with in-house secure-element manufacturing anchor premium-tier positioning, while pure assemblers face margin compression from state-backed procurement standardization. Three archetypes dominate: platform-integrated specialists with Android-based operating systems, component-captive manufacturers controlling cryptographic supply chains, and software-native entrants bundling terminal management with acquiring services. Competitive moves concentrate on certification breadth expansion and cloud-native firmware architecture shifts.
Among China-based platform specialists, Shenzhen Xinguodu Technology Co., Ltd. and Sunmi Technology Co., Ltd. exemplify the Android-native archetype that captures recurring software revenue through third-party application ecosystems. Fujian Newland Payment Technology Co., Ltd. occupies a position within the component-integrated tier, representing manufacturers with captive supply of barcode-scanning modules. PAX Global Technology Limited anchors the certification-heavy segment, reflecting players with overseas regulatory breadth and in-house cryptographic processor production.
| Leading Market Players |
|---|
| Verifone Systems LLC |
| Shenzhen Xinguodu Technology Co., Ltd. |
| Fujian Newland Payment Technology Co., Ltd. |
| New POS Technology Limited |
| Centerm Information Co., Ltd. |
| PAX Global Technology Limited |
| Sunmi Technology Co., Ltd. |
| Hisense Intelligent Commercial Equipment Co., Ltd. |
| Ingenico Group SA |
| Others |
Value Chain & Pricing Dynamics
Cryptographic processor costs cascade from Taiwan Semiconductor Manufacturing Company wafer fabrication through Shenzhen assembly floors into tiered terminal pricing. SAMR certification timelines extend working capital cycles for OEMs lacking in-house secure-element production, compressing margins at the standard tier while premium vendors capture value through integrated supply control.
Pricing Analysis
Transaction throughput guarantees anchor value-based pricing for acquiring banks subscribing to hardware-as-a-service models. Three-tier pricing structure across premium, standard, and economy levels separates PAX Global Technology Limited's certification-heavy positioning from pure assembler competitors. Price differentiation hinges on GB standards compliance depth and after-sales firmware update bundling. Cost compression in the economy tier is intensifying because state-backed procurement standardization eliminates brand premiums for undifferentiated hardware. Tier-three city SMBs exhibit highest price sensitivity; Shanghai fintech-enabled acquiring platforms show lowest.
Supply Chain Analysis
Embedded systems engineering talent scarcity in Shenzhen and Dongguan manufacturing corridors constrains dual-offline protocol development capacity. Secure-element fabrication concentrates in Taiwan, South Korea, and mainland China foundries. Raw material dependencies span cryptographic chip wafers, NFC antenna substrates, and PCI-certified PIN pad assemblies. Single-source vulnerability in EMV kernel licensing from international payment schemes threatens domestic OEM expansion timelines. Distribution runs through acquiring bank procurement departments and Hangzhou merchant service provider clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secure-element manufacturing capacity represents the binding constraint propping premium-tier pricing power. Foundry slot allocation favoring vertically integrated OEMs sustains margin pools unavailable to assembler competitors.
For Market Incumbents: Lock in certification breadth expansion through MIIT radio-frequency pre-approval investments and GB standards testing laboratory partnerships. Cloud-native firmware architectures defend against SAMR data-localization tightening. In-house cryptographic processor production anchors margin defense against pure-assembler price erosion. For New Entrants and Emerging Players: MIIT accelerated 4G and NFC module fast-tracking in China opens a window for tier-three city mobile POS penetration gaps. Target Sichuan and Henan province SMBs underserved by fixed infrastructure rollout. Software-as-a-service terminal management integration offers lowest customer acquisition friction against hardware-as-a-service incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor component-captive manufacturers in the Pearl River Delta with dormant certification pipelines. Long-term viability hinges on digital yuan hardware retrofit capability and cloud-native architecture migration. Watch SAMR data-localization rulemaking as inflection trigger for firmware-dependent vendor repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Offline Protocol Certification | People's Bank of China digital yuan mandates force hardware redesign for qualified suppliers. |
| Cloud-Native Firmware Migration | Shanghai acquiring banks push SaaS terminal management to reduce provincial service costs. |
| GB Standards Testing Investment | SAMR enforcement tightens cryptographic module compliance before market entry. |
| Secure-Element Capacity Expansion | Taiwan foundry partnerships anchor premium-tier positioning against assembler competitors. |
| Android Platform Ecosystem Buildout | Hangzhou merchant service providers capture recurring software revenue through third-party marketplaces. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with terminal OEM procurement directors, acquiring bank technology officers, merchant service provider sales heads, and SAMR certification consultants combined with MIIT radio-frequency approval databases, People's Bank of China technical specification releases, and PCI Security Standards Council device listings. Bottom-up shipment estimates triangulated against top-down acquiring bank terminal leasing disclosures.
Data-stream reconciliation across product type, technology protocol, end-user vertical, and deployment architecture dimensions shaped the analytical framework. CAGRs derived from installed base replacement cycles, digital yuan pilot expansion trajectories, and cloud migration velocity across provincial bank infrastructure. Forecast inputs incorporated MIIT module approval timelines and SAMR certification backlog assumptions.
Caveats apply where SAMR data-localization rulemaking or People's Bank of China digital yuan protocol revisions could materially shift the outlook. Forecasts reflect assumptions on certification timeline stability and foundry capacity allocation continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Czech Republic POS Terminals Market
Payments
Third Party Payment Market
Payments
Subscription Billing Management Market
Payments
Vietnam Payments Market
Payments
Japan Payment Gateway Market
Payments
Enterprise Payment Software Market
Payments
MENA Digital Payments Market
Payments
Clearing Houses and Settlements Market
Payments
Europe Payment Gateways Market
Payments
US Gift Card and Incentive Card Market
Payments
New Zealand Payments Market
Payments
Italy Gift Cards Market
Payments
Mpos Terminals Market
Payments
China Mobile Payments Market
Payments
Russia Payments Market
Payments
Asia-Pacific Crypto Payment Gateway Market