
 Latin America Payment Gateway Market | 2026-2036
Latin America Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Payment Gateway Market Insights
Brazilian fintech infrastructure is broadening as merchant acquirers scale API-native platforms across the region. Mercado Pago leverages its marketplace origin to sustain dominance in cross-border settlement corridors. DLocal Limited anchors its position through localized payment method aggregation in high-friction markets. EBANX competes by specializing in installment-friendly checkout flows tailored to Brazilian consumer credit behavior.
A payment gateway functions as a technical intermediary that encrypts transaction data, routes authorization requests between merchants and card networks, and manages settlement protocols across multiple acquiring banks. The system processes card-not-present transactions through tokenized credentials, real-time fraud scoring, and dynamic currency conversion to complete digital commerce purchases. Mobile payment methods are expanding fastest among payment method segments as smartphone penetration and instant payment rails proliferate across Colombia and Argentina. API integration technology leads the technology dimension because large e-commerce merchants demand direct embedded checkout control rather than redirected hosted pages. Subscription services within client type segments command durable margin pools due to recurring billing complexity and lower churn-related chargeback exposure.
Brazil's Banco Central enforces stringent PIX interoperability mandates and open banking data-sharing standards that reshape processor technical compliance burdens. Mexico's CNBV and Colombia's SFC impose tiered capital reserve requirements on payment aggregators based on monthly transactional volume thresholds. Argentina's BCRA maintains foreign exchange settlement restrictions that force gateway providers to architect dual-currency clearing architectures. Stakeholders must monitor how evolving central bank digital currency pilots across the region will recalibrate incumbent gateway value propositions.
Market Dynamics
Brazil's Banco Central PIX interoperability mandates are compressing legacy card network margins while forcing processors to rebuild core infrastructure around instant payment rails. This regulatory pivot is redistributing value from traditional acquirers to API-native platforms that can embed real-time settlement into merchant workflows.
Growth Catalysts
- PIX Open Banking Mandates:Brazil's central bank requires payment aggregators to support instant payment rails and share transactional data across institutions, lowering merchant onboarding friction.
- Smartphone Penetration Clusters:Colombia and Argentina exhibit dense urban smartphone adoption that enables mobile wallet checkout flows without dedicated POS hardware.
- Subscription Commerce Expansion:Recurring billing models in SaaS and streaming verticals generate predictable transaction volumes that attract processor investment.
Market Restraints
- Foreign Exchange Settlement Restrictions:Argentina's BCRA maintains dual-currency clearing requirements that force gateways to maintain parallel USD and peso settlement infrastructure.
- Tiered Capital Reserve Requirements:Mexico's CNBV imposes escalating liquidity buffers on aggregators processing above monthly volume thresholds, squeezing working capital.
- Technical Legacy Dependencies:Many merchants remain tethered to hosted checkout pages that cannot support embedded API integrations without complete replatforming.
Strategic Opportunities
- Underpenetrated Colombian Corridor:Bogotá and Medellín merchant digitization lags São Paulo and Mexico City, creating whitespace for localized payment method aggregation.
- Installment Checkout Innovation:Brazilian consumer credit behavior favors buy-now-pay-later flows that processors can monetize through interest-sharing arrangements.
- Central Bank Digital Currency Pilots:Regional monetary authorities are testing wholesale CBDC architectures that could recalibrate settlement velocity for early-integrating gateways.
Industry Challenges
- API Integration Talent Scarcity:Merchant technical teams lack embedded checkout engineering expertise, extending implementation timelines and inflating professional services costs.
- Anti-Money Laundering Compliance Velocity:Central banks across the region are tightening transaction monitoring protocols faster than processors can deploy automated screening systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Payment Gateway Market |
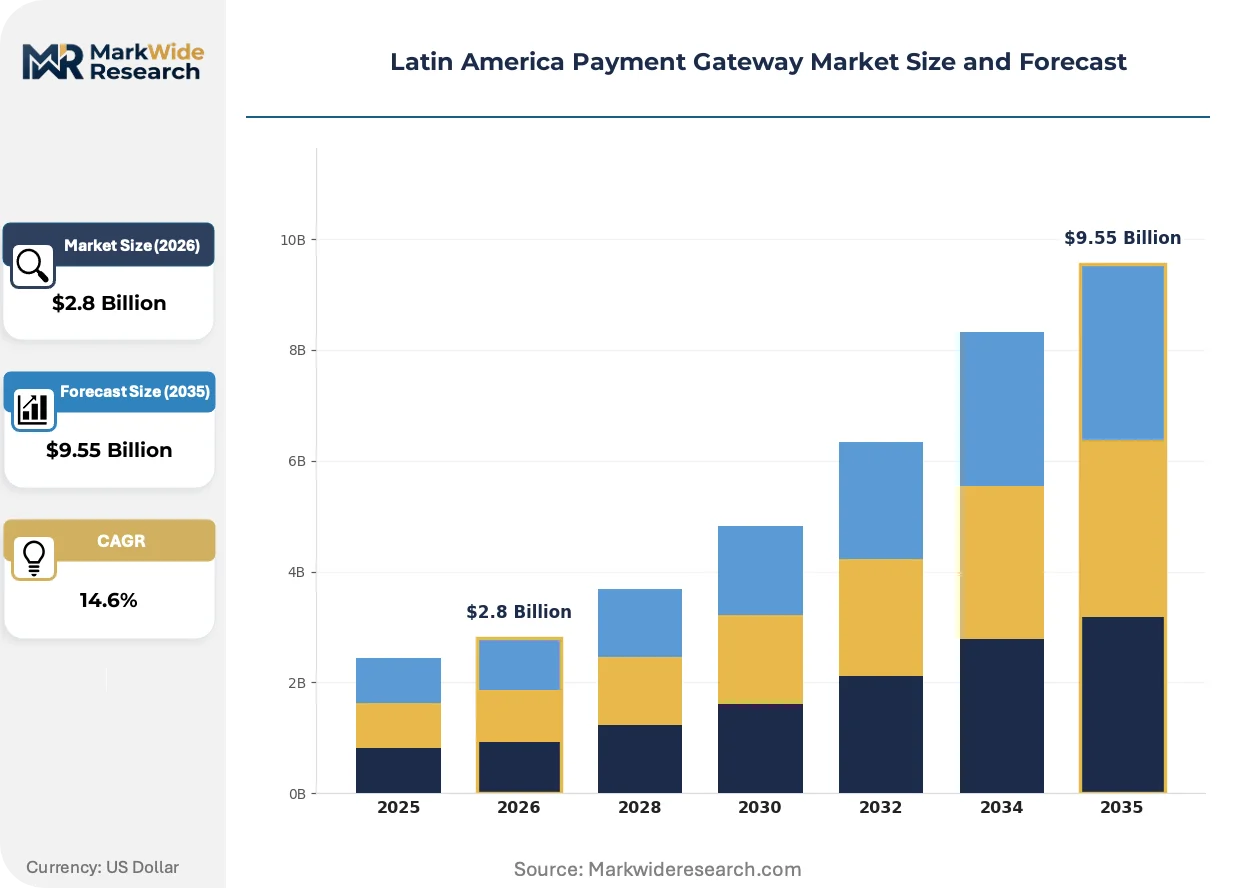
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Payment, Bank Transfer Client Type: E-Commerce, Retail, Subscription Services, Charitable Organizations Technology: API Integration, Hosted Solutions, Direct Payment, White Label Transaction Type: One-Time Payment, Recurring Payment, Invoicing, Split Payment |
| Companies Covered | Mercado Pago, DLocal Limited, EBANX, PagSeguro, StoneCo Ltd., PayU Payments Private Limited, Cielo S.A, PayPal Holdings, Inc., Stripe, Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Payment Gateway Market Trends and Innovations
Payment infrastructure across Latin America is fragmenting into specialized layers as merchants demand granular control over checkout experiences. This decomposition is creating distinct competitive arenas for tokenization providers, fraud scoring engines, and local payment method aggregators.
API-native checkout architectures are overtaking traditional hosted page redirects as large e-commerce merchants seek direct embedded control over transaction flows. Retailers operating cross-border storefronts are adopting these interfaces to reduce cart abandonment and capture richer customer data. The shift is compressing margins for legacy processors that cannot expose granular configuration endpoints.
Brazil's open banking data-sharing standards are forcing payment aggregators to reengineer customer onboarding and risk scoring workflows. The regulation mandates standardized API access to transactional histories, enabling alternative credit models but requiring substantial compliance investment. Mid-tier processors in São Paulo are responding by partnering with specialized KYC technology vendors rather than building proprietary stacks.
Merchant procurement of payment services is compressing toward unified platforms that combine gateway, risk, and settlement functions under single contracts. This bundling displaces point-solution vendors that previously dominated specific workflow segments. The pattern is most visible among Brazilian marketplace operators seeking to minimize vendor management overhead across Latin American expansion.
Latin America Payment Gateway Market Segmentation
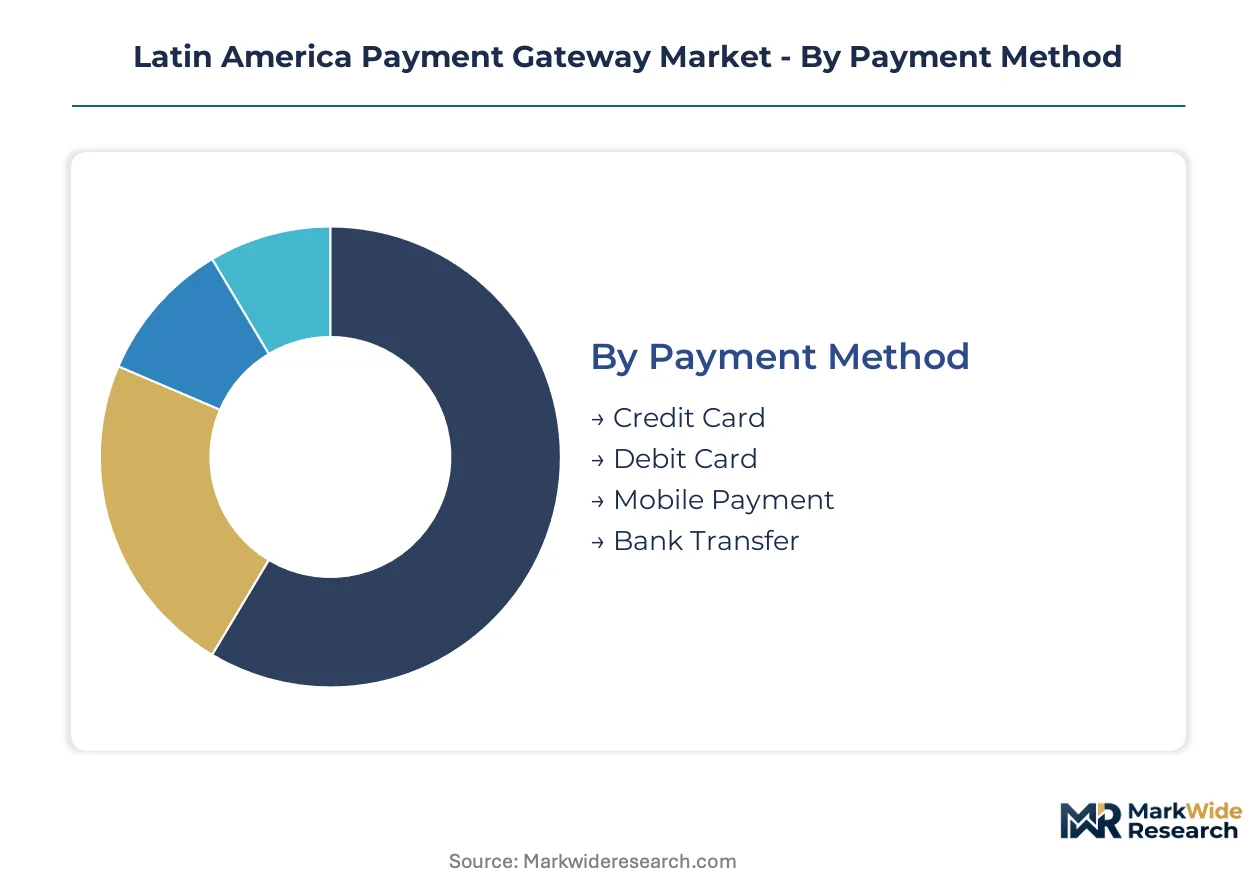
Payment gateway segmentation across Latin America reveals how regulatory frameworks and technical architectures shape processor specialization. Merchants select configurations based on settlement velocity requirements, fraud exposure tolerance, and central bank compliance mandates in their primary operating jurisdictions.
Payment Method:
Brazil's Banco Central mandates PIX interoperability certification for all payment aggregators, while Mexico's CNBV requires tiered capital reserves based on transactional volume across each method type.
- Credit Card:Tokenized credential routing through card networks dominates merchant checkout flows in São Paulo and Mexico City corridors. Brazilian installment-friendly processing requirements sustain acquirer investment in interest-sharing arrangements despite PIX compression.
- Mobile Payment:Smartphone penetration clusters in Bogotá and Medellín enable instant payment rail integration without dedicated POS hardware. Colombia's dense urban adoption accelerates wallet-based checkout flows as merchants bypass legacy terminal infrastructure.
- Debit Card:Real-time authorization networks process PIN-verified transactions through domestic switching systems.
- Bank Transfer:Account-to-account settlement protocols leverage open banking APIs for direct merchant funding.
Credit card processing sits at the top of the volume ranking, with mobile payment climbing the fastest.
Client Type:
Subscription services command premium processor margins due to recurring billing complexity and lower chargeback exposure, while retail merchants prioritize settlement speed over feature depth.
- Subscription Services:SaaS and streaming verticals generate predictable transaction volumes that attract specialized fraud scoring investment. Brazilian regulators mandate enhanced customer consent protocols for recurring debits under open banking standards.
- E-Commerce:Cross-border storefronts demand embedded API control to reduce cart abandonment and capture richer customer data. Argentina's foreign exchange restrictions force dual-currency clearing architectures for international merchants.
- Retail:Brick-and-mortar digitization concentrates in metropolitan São Paulo corridors.
- Charitable Organizations:Donation processors face simplified KYC thresholds under regional financial inclusion mandates.
Subscription services capture the highest margin tier, with e-commerce expanding most quickly.
Technology:
API-native architectures require substantial engineering investment but enable embedded checkout control that hosted solutions cannot match.
- API Integration:Direct embedded control over transaction flows reduces cart abandonment for large marketplace operators. Technical talent scarcity in São Paulo extends implementation timelines and inflates professional services costs.
- Hosted Solutions:Redirected checkout pages persist among legacy merchants lacking replatforming resources. Mexico City small businesses remain tethered to these configurations due to limited technical staff.
- Direct Payment:Merchant-branded settlement interfaces bypass third-party processor visibility.
- White Label:Reseller-configured platforms enable rapid market entry for regional fintech startups.
API integration leads the revenue concentration, with white label gaining share fastest among mid-tier entrants.
Transaction Type:
Recurring payment protocols demand sophisticated dunning management and failure recovery systems that one-time flows do not require.
- Recurring Payment:Automated billing engines with retry logic and expiration date tracking sustain predictable revenue streams. Colombian subscription commerce verticals drive processor investment in specialized dunning technology.
- One-Time Payment:Single authorization events dominate marketplace checkout volumes with minimal post-transaction infrastructure. Brazilian e-commerce platforms optimize these flows for PIX instant settlement conversion.
- Invoicing:B2B trade credit workflows require extended settlement windows and buyer verification.
- Split Payment:Marketplace fund distribution mandates escrow-like holding arrangements across multiple beneficiaries.
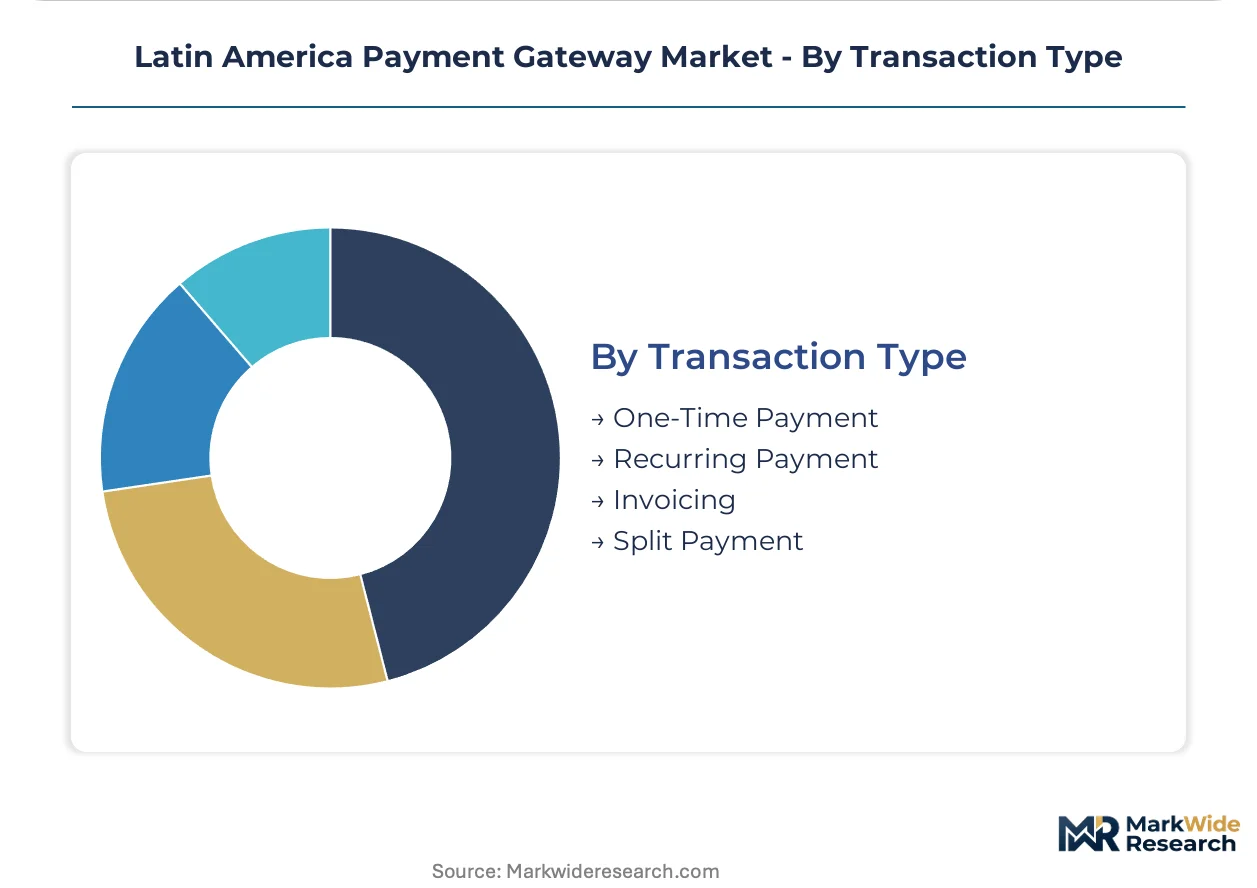
One-time payment holds the volume crown, with split payment showing the steepest expansion trajectory among marketplace operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment gateway operators are migrating technical infrastructure across Latin American jurisdictions to exploit gaps in compliance cost structures. Brazil's stringent PIX mandates impose heavier engineering burdens than Mexican or Colombian requirements, shifting development center gravity toward São Paulo and Mexico City corridors.
Brazil
Banco Central's PIX interoperability certification and open banking data-sharing standards drive merchant acquirer investment in real-time settlement rails. The central bank mandates standardized API access to transactional histories, forcing processors to reengineer onboarding workflows. São Paulo anchors the deepest merchant digitization cluster, with API-native platforms dominating checkout infrastructure deployment across the metropolitan corridor.
Mexico
E-commerce platform expansion in Mexico City accelerates demand for embedded checkout control and cross-border settlement capabilities. CNBV imposes tiered capital reserve requirements on payment aggregators processing above monthly volume thresholds, squeezing working capital for mid-tier operators. The metropolitan corridor concentrates merchant procurement of unified gateway-risk-settlement platforms under single vendor contracts.
Colombia
Smartphone penetration clusters in Bogotá and Medellín enable mobile wallet checkout flows without dedicated POS hardware. The country's financial regulator maintains simplified KYC thresholds for charitable donation processors under financial inclusion mandates. Urban merchant digitization lags Brazilian and Mexican corridors, creating whitespace for localized payment method aggregation specialists.
Argentina
BCRA foreign exchange settlement restrictions force gateway providers to architect dual-currency clearing architectures for international merchants. Dual-currency infrastructure requirements inflate operational complexity for processors serving cross-border e-commerce storefronts. Buenos Aires concentrates subscription commerce verticals that drive specialized dunning technology investment from regional processors.
Chile
Santiago's merchant base demands instant payment rail integration as smartphone penetration enables wallet-based checkout adoption. The central bank's instant payment infrastructure reduces terminal hardware dependency for urban retailers. The metropolitan corridor exhibits procurement patterns favoring unified platforms that combine gateway, risk, and settlement functions.
Latin America Payment Gateway Market Competitive Landscape
Brazilian operators anchor one competitive tier; Mexico-based specialists hold differentiated positions in cross-border settlement corridors. The vendor structure fragments across API-native platforms, legacy acquirers with hosted solutions, and localized payment method aggregators. Three archetypes dominate: marketplace-origin processors leveraging merchant ecosystem data, pure-play aggregators specializing in high-friction emerging markets, and global fintechs embedding checkout infrastructure. M&A activity concentrates on acquiring API engineering talent; strategic partnerships proliferate between processors and specialized KYC technology vendors.
Within the marketplace-origin tier, Mercado Pago exemplifies ecosystem leverage into payment infrastructure. DLocal Limited and EBANX occupy positions as specialized aggregators focused on localized payment method coverage across high-friction Latin American markets. These three anchors represent distinct strategic postures: ecosystem extension versus emerging market specialization versus installment-optimized checkout flows.
| Leading Market Players |
|---|
| Mercado Pago |
| DLocal Limited |
| EBANX |
| PagSeguro |
| StoneCo Ltd. |
| PayU Payments Private Limited |
| Cielo S.A |
| PayPal Holdings, Inc. |
| Stripe, Inc. |
| Others |
Pricing and Supply Chain Analysis
Large e-commerce marketplace operators in São Paulo and Mexico City corridors command volume-based transactional discounts that compress per-unit gateway fees toward commoditized levels. This buyer concentration forces mid-tier processors toward SaaS-tiered subscription models with embedded risk and settlement bundling.
Pricing Analysis
Direct-to-merchant API integration fees carry thinner margins than hosted-page redirect markups due to reduced technical support overhead. Pricing stratifies across enterprise API tiers, mid-market bundled suites, and small-merchant hosted solutions based on transaction volume thresholds and compliance certification levels. Cost compression in the mid-market tier is intensifying because PIX instant settlement rails disintermediate traditional card-network fee stacks. Small retailers in Mexico City exhibit highest price sensitivity, while subscription commerce operators in Buenos Aires tolerate premium pricing for specialized dunning technology.
Supply Chain Analysis
Engineering talent scarcity in São Paulo and Bogotá extends API implementation timelines and inflates professional services costs for gateway deployments. Technical infrastructure concentrates in Brazil, Mexico, and Colombia, with data center capacity clustering around São Paulo and Mexico City metropolitan corridors. Platform development draws from specialized KYC technology vendors, cloud compute providers, and card-network tokenization services. Single-source vulnerability runs through PIX rail certification dependencies controlled by Brazil's Banco Central. Distribution runs through direct enterprise sales teams and regional fintech reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's PIX interoperability mandates function as a regulatory compounder, forcing infrastructure rebuilds that redistribute value toward API-native platforms capable of embedding real-time settlement.
For Market Incumbents: Anchor defensive positioning through backward integration into specialized fraud scoring engines and KYC technology stacks. Prioritize certification investment for open banking data-sharing standards before regulatory deadlines tighten. Consolidate channel control by acquiring API engineering talent in São Paulo to offset implementation timeline inflation from technical staff scarcity. For New Entrants and Emerging Players: Enter via underpenetrated merchant digitization corridors in Bogotá and Medellín where localized payment method aggregation remains fragmented. Target subscription commerce verticals in Buenos Aires for specialized recurring billing infrastructure with lower competitive density. Pursue white-label platform partnerships with regional fintech startups lacking proprietary gateway development resources. For Investors and Strategic Acquirers: Marketplace-origin processors with embedded merchant ecosystem data are the most active acquirer in this space, seeking API engineering capabilities and cross-border settlement licenses. Long-term viability favors platforms with dual-currency clearing architecture and PIX certification already deployed. Monitor central bank digital currency pilot announcements as inflection indicators for early-integrating gateway valuations.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Platform Migration | São Paulo processors rebuild core infrastructure around PIX instant rails to capture merchant workflow embedding. |
| Specialized KYC Technology Partnership | Mid-tier aggregators outsource compliance stacks to vendors rather than building proprietary onboarding systems. |
| Dual-Currency Clearing Architecture | Argentina-focused gateways architect parallel USD and peso settlement to navigate BCRA foreign exchange restrictions. |
| Installment Checkout Flow Optimization | Brazilian processors monetize interest-sharing arrangements tailored to local consumer credit behavior patterns. |
| Subscription Commerce Vertical Expansion | Regional processors invest in dunning technology for SaaS and streaming billing with lower chargeback exposure. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with payment gateway CTOs, merchant platform engineers, central bank regulatory leads, and fintech reseller channel heads with secondary validation. Sources included Banco Central PIX certification filings, CNBV capital reserve disclosures, SEC 10-K submissions from listed processors, and open banking API documentation. Bottom-up transaction volume modeling and top-down market sizing triangulated segment-level estimates.
Segment-weighting approaches applied differential growth assumptions across payment method types, client verticals, and technology deployment models throughout the forecast period. Analytical frameworks modeled API integration versus hosted solution adoption curves, recurring versus one-time payment protocol expansion, and mobile wallet penetration against legacy terminal infrastructure. CAGRs derived from volume trajectory analysis and pricing elasticity estimates, with inputs from smartphone penetration clusters and central bank instant payment rail deployment schedules.
The model holds under stable regulatory enforcement timelines; deviation in PIX mandate acceleration or CBDC pilot expansion would shift infrastructure investment calendars. Forecasts reflect assumptions about merchant digitization continuity and open banking compliance cost trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Southeast Asia POS Terminal Market
Payments
Biometric Payment Cards Market
Payments
Tanzania Mobile Money Market
Payments
Germany Gift Card and Incentive Card Market
Payments
Netherlands POS Terminal Market
Payments
Taiwan Mobile Payments Market
Payments
Face-Swiping Payment Market
Payments
Smart Payment Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Poland POS Terminal Market
Payments
Saudi Arabia Mobile Payments Market
Payments
China Mobile Payments Market
Payments
North America Real Time Payment Market
Payments
Saudi Arabia Gift Card and Incentive Card Market
Payments
Spain Payment Gateway Market
Payments
Mexico Real Time Payments Market