
 Bus Card Reader Market | 2026-2036
Bus Card Reader Market Size, Share, and Industry Trends Forecast 2026-2036
Bus Card Reader Market Intelligence
The strategic middle ground between large-scale, full-system transit integrators and niche component suppliers is collapsing. Cubic Corporation leverages its deep integration with major municipal transit authorities to secure long-term, comprehensive contracts. In contrast, Masabi specializes in mobile-first, software-as-a-service ticketing platforms, often partnering with multiple hardware vendors. Thales Group competes by offering secure payment and identity solutions across transport and other sectors, positioning itself as a technology provider.
A bus card reader is an electronic data capture device designed to validate and process fare payments on public transport vehicles. These devices typically operate using radio-frequency identification and must comply with standards like ISO/IEC 14443 to ensure interoperability with various contactless cards. Contactless readers utilizing Near Field Communication (NFC) technology represent the fastest-growing product segment, displacing older magnetic stripe systems. While public transit remains the dominant end user, adoption is increasing within corporate transport for employee shuttle services.
Payment security standards, such as the PCI DSS framework enforced in the United States, mandate stringent data protection for cardholder information processed by readers. In Europe, GDPR compliance governs the handling of passenger data, while in China, devices must adhere to specific GB standards for electronic equipment. The critical decision for transit operators now centers on balancing the proprietary control of closed-loop systems against the rider convenience and lower infrastructure costs of open-loop payment acceptance.
Market Dynamics
The central dynamic shaping the bus card reader market is the architectural tug-of-war between closed-loop systems, which offer transit agencies tight control, and open-loop systems, which prioritize rider convenience by accepting standard contactless bank cards and mobile wallets.
Growth Catalysts
- National Mobility Initiatives:Government-led programs, such as India's National Common Mobility Card (NCMC) initiative, create large-scale, standardized demand for interoperable readers, accelerating public transit modernization across entire nations and simplifying procurement for transit authorities.
- NFC Technology Adoption:The proliferation of Near Field Communication (NFC) in consumer smartphones and bank cards provides a powerful tailwind, driving passenger expectations for tap-to-pay convenience and pushing operators to upgrade from legacy magnetic stripe or proprietary card systems.
- Corporate Transport Modernization:Expansion into adjacent verticals like corporate shuttles and university bus networks provides a new growth avenue, as these organizations seek to professionalize their transport services with automated fare collection and ridership tracking.
Market Restraints
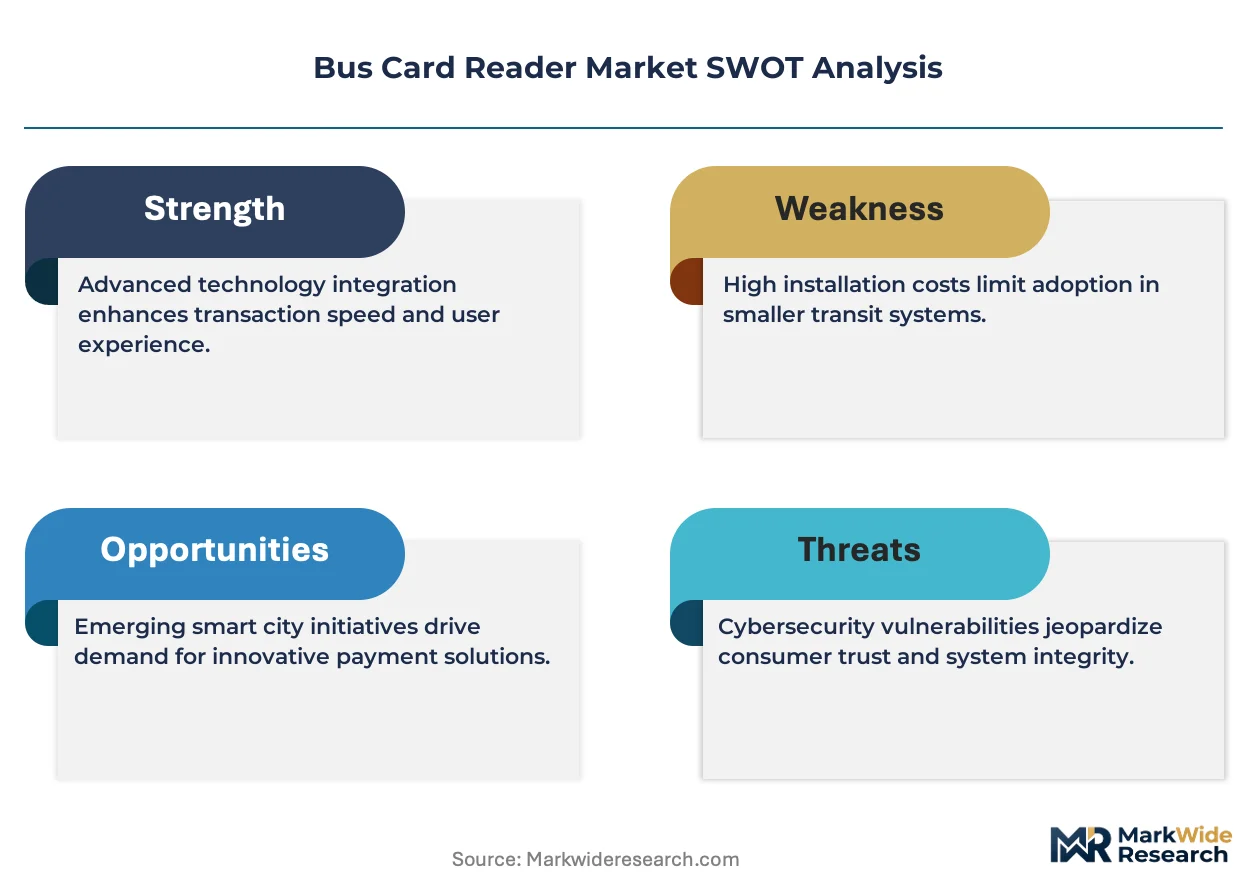
- High Capital Expenditure:The significant upfront investment required for a full-fleet replacement of readers and associated back-office software can be prohibitive for smaller or budget-constrained municipal transit agencies, delaying modernization cycles.
- System Interoperability:A lack of universal standards for back-office integration creates friction, making it difficult for transit operators to mix and match reader hardware from different vendors without incurring substantial custom integration costs and risks.
- Complex Security Compliance:Reader hardware and software must simultaneously adhere to multiple, often overlapping, regulatory frameworks, such as the PCI DSS for payment data in the US and GDPR for passenger privacy in Europe, increasing design complexity.
Strategic Opportunities
- Emerging Market Transit Upgrades:Major metropolitan areas in Latin America and Southeast Asia are actively investing in formalizing their public transport networks, presenting a significant opportunity for first-time deployments of modern card reader systems.
- Integration with Mobility-as-a-Service:Readers can evolve into data collection points for broader Mobility-as-a-Service (MaaS) platforms, integrating with bike-share, scooter, and ride-hailing services to provide a seamless multi-modal journey payment experience.
- Value-Added Data Analytics:Offering cloud-based analytics services that process anonymized ridership data from readers allows providers to create recurring revenue streams by helping transit agencies optimize routes, schedules, and vehicle allocation.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the complex and costly process of integrating new open-loop payment readers with decades-old, proprietary closed-loop fare collection and financial reconciliation systems without disrupting daily operations.
- Cybersecurity Vulnerability:As readers become more connected and process sensitive financial data, they become more attractive targets for cyberattacks, requiring constant firmware updates and sophisticated security protocols to prevent data breaches and service fraud.
- Skilled Workforce Scarcity:A shortage of technicians and software engineers with expertise in both transport-specific protocols and modern payment security standards creates bottlenecks in deploying and maintaining advanced reader systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bus Card Reader Market |
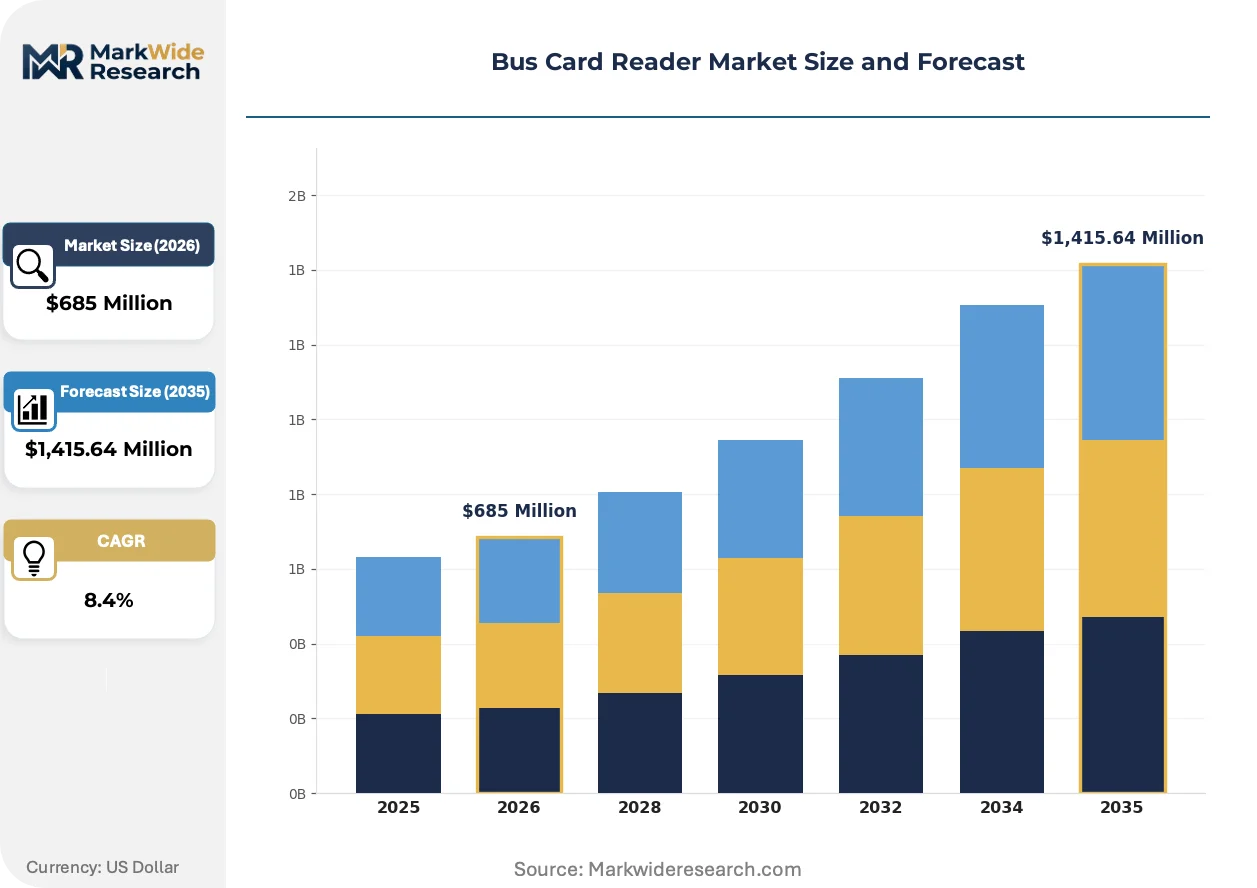
| Market Size in 2026 | $685 Million |
| Market Size in 2035 | $1,415.64 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contactless Reader, Magnetic Stripe Reader, Hybrid Reader, Mobile Reader Technology: RFID, NFC, Bluetooth, Infrared End User: Public Transit, Corporate Transport, Educational Institutions, Retail Installation Type: Fixed, Portable, Integrated, Standalone |
| Companies Covered | Cubic Corporation, VeriFone Holdings, Inc, Conduent Inc, Scheidt & Bachmann, Ingenico Group, Thales Group, MagTek Inc, Advanced Card Systems Ltd, Masabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bus Card Reader Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental shift from hardware-centric transactions to software-defined, data-rich fare collection ecosystems. This transition prioritizes system flexibility and rider-centric data over the physical validation device itself, changing the value proposition for manufacturers and operators.
Account-Based Ticketing (ABT) systems represent a significant product evolution, shifting fare calculation logic from the physical card to a centralized back-office account. Major transit authorities are adopting ABT to offer more flexible fare capping and multi-modal passes. This change is decomposing the traditional role of the reader; it no longer needs to store complex fare rules, instead becoming a simpler, more robust device for validating a rider's identity token against the central system.
Europe's General Data Protection Regulation (GDPR) imposes strict rules on how passenger data is collected, stored, and processed. This regulation directly impacts reader and system design, forcing manufacturers to build in privacy-by-design principles, such as data minimization and robust anonymization for travel pattern analysis. The public transit sector across the European Union is most affected, leading to a preference for systems that can prove compliance and give passengers greater control over their data.
A notable demand-side shift is the move away from one-time capital equipment purchases toward "Fare Collection as a Service" (FCaaS) subscription models. This disrupts the business of traditional system integrators who rely on large, upfront contracts, opening the door for software-focused vendors offering lower initial costs and continuous updates. This trend is most pronounced in small to mid-sized cities in North America and Europe, which can modernize their transit payment systems without a massive capital bond issuance.
Bus Card Reader Market Segmentation
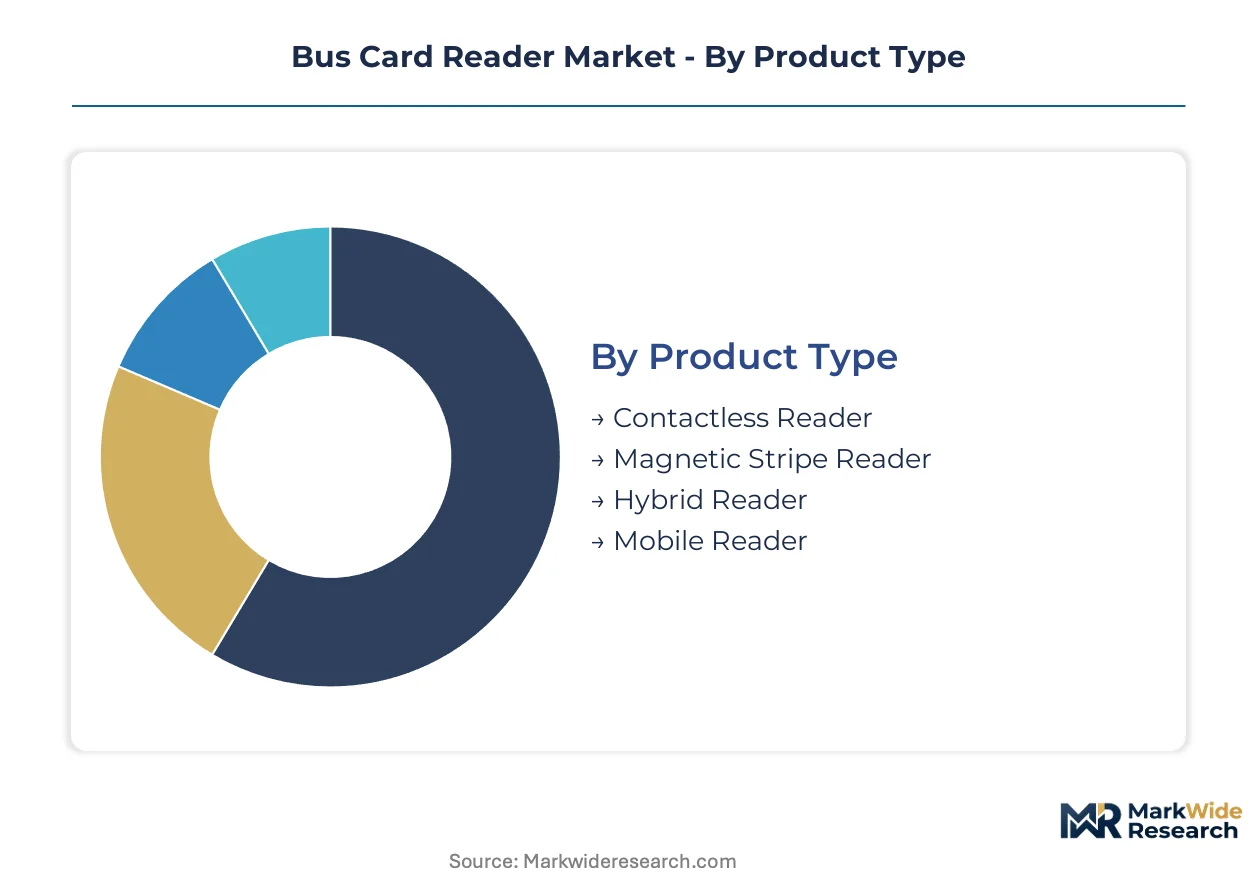
Understanding the bus card reader market through segmentation reveals distinct pathways for product development and market penetration. Different end-user requirements drive varied technological adoptions and installation preferences, directly influencing procurement cycles and investment priorities for transit authorities and private operators alike. This granular view helps identify where innovation delivers the most significant operational efficiency or rider convenience.
Product Type:
The channel mix for bus card readers is shifting, with modern contactless solutions gaining prominence over traditional physical card formats. This transition impacts both hardware manufacturing and software integration for fare collection systems.
- Contactless Reader:These devices utilize Near Field Communication (NFC) or radio-frequency identification (RFID) technology to process payments from contactless bank cards, mobile wallets, or transit-specific smart cards, adhering to standards like ISO/IEC 14443. Demand concentrates in regions like India, where the National Common Mobility Card (NCMC) initiative mandates interoperable contactless payment infrastructure.
- Mobile Reader:Often smartphone-based or purpose-built handheld devices, mobile readers offer flexibility for on-demand services, smaller routes, or fare enforcement, processing digital tickets or EMV contactless payments. Their adoption is expanding most quickly in smaller to mid-sized cities in North America and Europe, which are leveraging "Fare Collection as a Service" (FCaaS) models for lower capital outlay.
- Magnetic Stripe Reader:This legacy technology reads data from a magnetic stripe on a card, typically used for older transit cards or occasional paper tickets.
- Hybrid Reader:These versatile units combine multiple reading capabilities, often supporting magnetic stripe, contact smart card, and contactless payment technologies within a single device.
Magnetic Stripe Readers still dominate the installed base in many older systems. Contactless Readers are where expansion concentrates as agencies modernize their fare collection infrastructure.
Technology:
The maturity of various technologies dictates their current deployment and future potential within bus card reader systems. Established radio-frequency identification (RFID) systems still hold significant market share, but newer Near Field Communication (NFC) solutions are rapidly gaining ground due to widespread consumer adoption.
- NFC:This short-range wireless technology enables secure, two-way communication between devices, supporting tap-to-pay functionality for bank cards, mobile phones, and wearables at speeds suitable for high-volume transit. The proliferation of NFC-enabled consumer devices drives its rapid integration into new public transit systems globally.
- RFID:Operating at various frequencies, RFID technology is foundational for many closed-loop transit card systems, allowing readers to identify and validate proprietary smart cards. Public transit agencies in emerging markets frequently deploy RFID-based systems for initial automation of fare collection.
- Bluetooth:Bluetooth Low Energy (BLE) can facilitate hands-free ticketing or communication with mobile applications, offering alternative validation methods.
- Infrared:This technology is less common for primary fare validation but can be used in specific applications like data transfer or object detection in some reader designs.
NFC technology currently commands the largest share of new deployments. RFID systems continue to see consistent demand for upgrading existing closed-loop networks.
End User:
Customer type significantly influences the scale, complexity, and specific features required from bus card reader systems. Public transit operators demand robust, high-throughput solutions, while corporate clients seek integration with existing employee management systems.
- Public Transit:This segment includes municipal, regional, and national transport authorities operating bus networks, requiring readers capable of handling high transaction volumes, diverse fare structures, and robust back-office integration. National mobility initiatives, such as India's NCMC, create substantial demand for standardized reader deployments within this sector.
- Corporate Transport:Enterprises providing shuttle services for employees utilize bus card readers for access control, automated fare collection, and ridership tracking, often integrating with human resources systems. Modernization efforts in large corporations are driving demand for professionalized transport solutions.
- Educational Institutions:Universities and schools deploy readers for campus shuttle services, student identification, and internal payment systems, often linked to student ID cards.
- Retail:While less common for dedicated bus card readers, some retail environments might integrate payment terminals that could accept transit cards or mobile payments for combined services.
Public Transit represents the largest end-user segment by deployment volume. Corporate Transport is gaining share through professionalization efforts.
Installation Type:
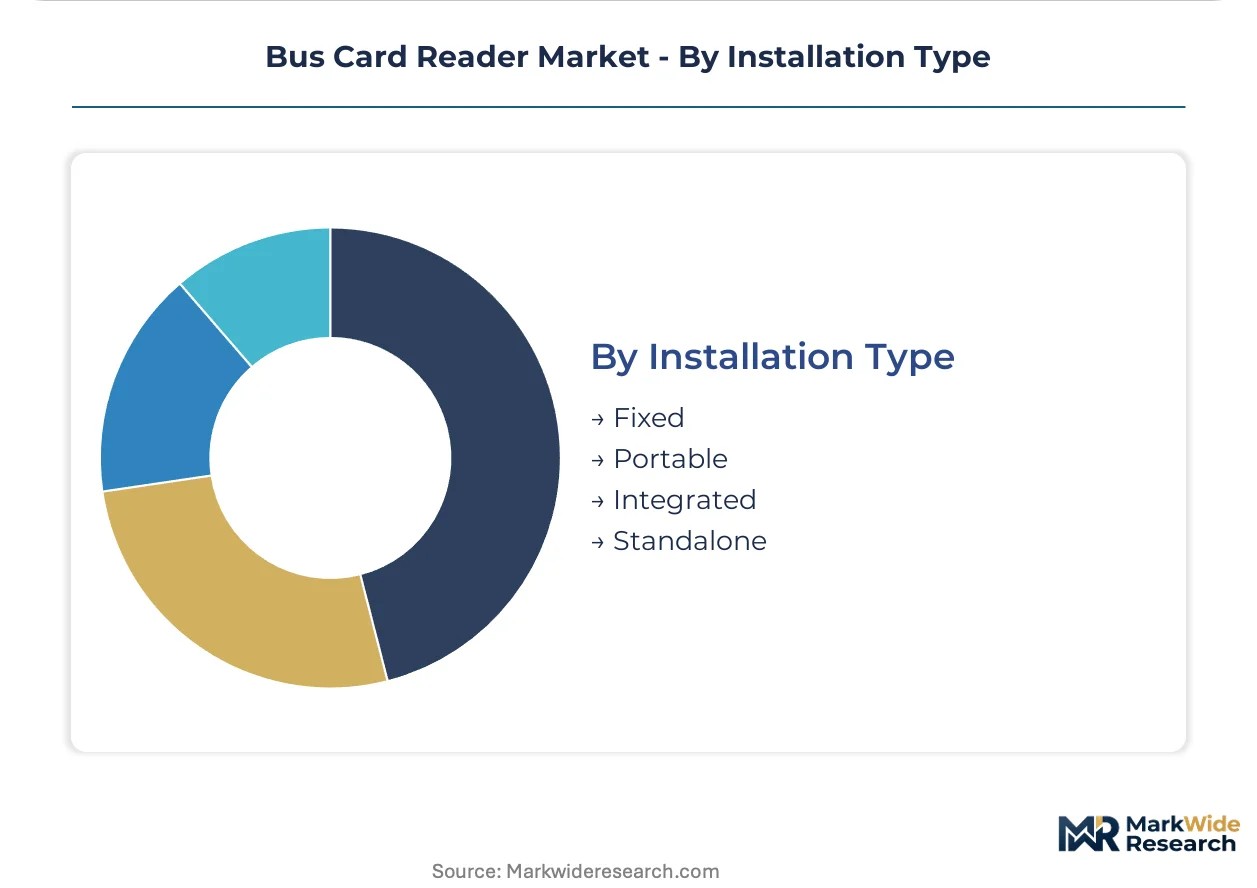
The cost tier associated with different installation types impacts initial capital expenditure and long-term maintenance budgets for transit operators. Fixed installations generally represent higher upfront costs but offer greater durability and integration, while portable options provide flexibility at a lower entry point.
- Fixed:These readers are permanently mounted within a bus, typically at entry and exit points, designed for continuous operation and high durability in demanding transit environments. Major metropolitan areas investing in new bus fleets or comprehensive system overhauls prioritize fixed installations for reliability.
- Portable:Handheld or mobile devices offer flexibility for fare enforcement, temporary routes, or smaller transport operations, allowing staff to move throughout the vehicle or operate off-bus. Smaller transit agencies and on-demand shuttle services often opt for portable solutions due to their lower initial investment and operational versatility.
- Integrated:These systems are seamlessly built into the bus's existing infrastructure, such as ticket machines or driver consoles, providing a unified user interface.
- Standalone:Standalone readers operate independently, often with their own power source and communication capabilities, suitable for specific validation points or as backup systems.
Fixed installations remain the standard for high-volume public transit routes. Portable options are seeing increased adoption in flexible and smaller-scale transport operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand for bus card readers exhibits varied elasticity across regions, with mature markets prioritizing advanced open-loop systems and emerging economies focusing on foundational modernization. Transit agencies in developed nations seek rider convenience and data analytics, while those in developing countries prioritize large-scale, standardized deployments for initial fare collection automation.
India
India demonstrates high demand for bus card readers driven by extensive public transit modernization and dense urban populations. The National Common Mobility Card (NCMC) initiative standardizes interoperable payment infrastructure across the country. Major metropolitan areas like Mumbai and Delhi are actively implementing NCMC-compliant systems, simplifying procurement for transit authorities.
United States
The United States market is expanding due to a significant shift toward open-loop payments and the modernization of corporate transport services. The PCI DSS framework mandates stringent data protection for cardholder information processed by readers. Cities such as New York and Chicago are upgrading their fare collection systems to accept contactless bank cards, enhancing rider experience.
Germany
Germany focuses on integrated mobility solutions and strict data privacy, influencing reader and system design. GDPR compliance governs the handling of passenger data, leading to a preference for privacy-by-design systems. Urban centers like Berlin and Munich are piloting Mobility-as-a-Service platforms that integrate bus card readers as key data collection points for seamless travel.
China
China presents substantial demand for bus card readers, fueled by rapid urbanization and extensive public transport network expansion. Devices must adhere to specific GB standards for electronic equipment and payment security protocols. Megacities like Shanghai and Guangzhou are deploying advanced contactless systems, often integrating with local digital payment ecosystems.
Brazil
Brazil's market is characterized by the formalization of public transport networks and initial automation of fare collection systems. Local municipal transport authorities often set specific procurement guidelines for new fare collection technologies. Major cities such as São Paulo and Rio de Janeiro are investing in modern card reader systems for their expanding and professionalizing bus networks.
Bus Card Reader Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the bus card reader market's competitive structure. Large transit integrators provide comprehensive, end-to-end solutions, while niche component suppliers focus on specific hardware or software elements. Mobile-first platform providers represent a distinct archetype, often partnering with hardware vendors. Strategic partnerships and technology licensing are dominant competitive moves, enabling broader market reach and specialized offerings.
Within the integrated solutions tier, Cubic Corporation exemplifies deep engagement with major municipal transit authorities, securing long-term, comprehensive contracts that span hardware and software. Thales Group, a global technology provider, occupies a position offering secure payment and identity solutions across transport and other critical sectors, leveraging its expertise in secure transactions. Masabi represents the mobile-first, software-as-a-service archetype, specializing in cloud-based ticketing platforms that often integrate with multiple hardware vendors to deliver flexible and scalable solutions for transit operators.
| Leading Market Players |
|---|
| Cubic Corporation |
| VeriFone Holdings, Inc |
| Conduent Inc |
| Scheidt & Bachmann |
| Ingenico Group |
| Thales Group |
| MagTek Inc |
| Advanced Card Systems Ltd |
| Masabi |
| Others |
Cost & Logistics Intelligence
High-volume manufacturing of contactless reader components drives scale economies, shaping both supply concentration in key regions and establishing competitive price floors for standardized units.
Pricing Analysis
Recurring software licensing and integration services drive lifetime value for bus card reader vendors. The dominant pricing structure involves a hybrid of project-based contracts for large system deployments and subscription models for "Fare Collection as a Service" (FCaaS) platforms. Price differentiation stems from the level of customization required for specific transit agency needs and the robustness of ongoing after-sales support. Pricing pressure stems from the increasing availability of FCaaS models offering lower upfront capital expenditure for operators. Smaller to mid-sized cities represent the most price-sensitive buyers, while major metropolitan areas prioritize feature sets and system reliability.
Supply Chain Analysis
Extended lead times for specialized microcontrollers and secure element chips impact bus card reader manufacturing schedules. Geographic supply concentration for critical electronic components primarily centers on China and South Korea, with specialized system integration capabilities in Germany. The market draws from a global pool of raw materials including rare earth elements for internal electronics and various plastics for housing. Single-source vulnerability for specific secure payment chips represents a structural supply chain risk. Distribution runs through a combination of direct sales to large municipal transit authorities and specialized system integrators for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bus card reader market is experiencing a cyclical recovery, driven by renewed government investment in public transit infrastructure post-pandemic.
For Market Incumbents: Consolidate existing long-term contracts with major municipal transit authorities to defend market share against mobile-first entrants. Deepen integration with back-office systems and expand service offerings for open-loop payment acceptance. Invest in R&D for advanced cybersecurity protocols and obtain certification for PCI DSS and GDPR compliance. This strategy mitigates the threat from agile software-centric competitors like Masabi.
For New Entrants and Emerging Players: Lead with flexible, cloud-native Fare Collection as a Service (FCaaS) models to penetrate underserved small and mid-sized cities. Target adjacent white-space opportunities such as corporate transport for employee shuttles and university bus networks. Partnering with multiple hardware vendors for system flexibility provides a compelling go-to-market angle for these segments. The most penetrable segment comprises smaller transit agencies in North America and Europe seeking lower initial investment.
For Investors and Strategic Acquirers: Specialized software providers offering Account-Based Ticketing (ABT) platforms represent attractive acquisition targets for larger integrators seeking to enhance their digital capabilities. The market exhibits strong long-term viability over the next 5-10 years, driven by urbanization and digital transformation in public transit. A signal to watch is increased M&A activity among traditional integrators acquiring mobile-first SaaS providers to expand their offerings.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Open-Loop Payment Integration | This initiative broadens revenue streams by accepting standard contactless bank cards and mobile wallets. |
| Develop Mobility-as-a-Service (MaaS) Partnerships | Integrating with MaaS platforms positions readers as data collection points for seamless multi-modal journeys. |
| Invest in Cybersecurity Enhancements | Strengthening security protocols protects sensitive payment data and builds trust with transit operators and riders. |
| Offer Fare Collection as a Service (FCaaS) | This model lowers capital expenditure for transit agencies, accelerating modernization efforts in smaller markets. |
| Target Emerging Market Deployments | Focusing on regions like Latin America and Southeast Asia captures first-time deployment opportunities for modern systems. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings. This involved discussions with transit authority procurement managers, payment solution architects, hardware engineers, and public transport policy advisors. Secondary sources included government transport agency reports, payment network whitepapers, technology standards bodies (ISO/IEC), and financial filings of public companies. The analysis employed both bottom-up market sizing and top-down validation to ensure data integrity.
Sensitivity analysis explores market responses to varying modernization investment levels and technological adoption rates across the modeling period. The analytical framework models market dynamics across product type, technology, end-user, installation type, and regional regulatory compliance. Compound annual growth rates were derived from historical trends, projected market dynamics, and anticipated shifts in public transit ridership growth and contactless payment penetration rates. This approach provides a robust quantitative foundation for the market forecast.
Underlying assumptions cover sustained public transit funding and stable regulatory environments, with deviation risk concentrated in geopolitical shifts affecting component supply. Forecasts reflect these assumptions, acknowledging that rapid shifts in payment technology standards could also alter projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Europe Virtual Cards Market
Payments
Biometric Payment Market
Payments
Poland POS Terminal Market
Payments
Europe Payment Gateways Market
Payments
United Arab Emirates Real Time Payments Market
Payments
Tanzania Mobile Money Market
Payments
Transaction Monitoring Market
Payments
Netherlands Mobile Payments Market
Payments
Electronic Payment System for Transportation Market
Payments
Remote Mobile Payment Market
Payments
Mpos Terminals Market
Payments
Mobile Wallet Market
Payments
Global Telecom Billing and Revenue Management Market
Payments
Europe Credit Cards Market
Payments
Point-To-Point Encryption (P2PE) Payment Market